
 Conductive Coatings Market | 2026-2036
Conductive Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Conductive Coatings Market Analysis
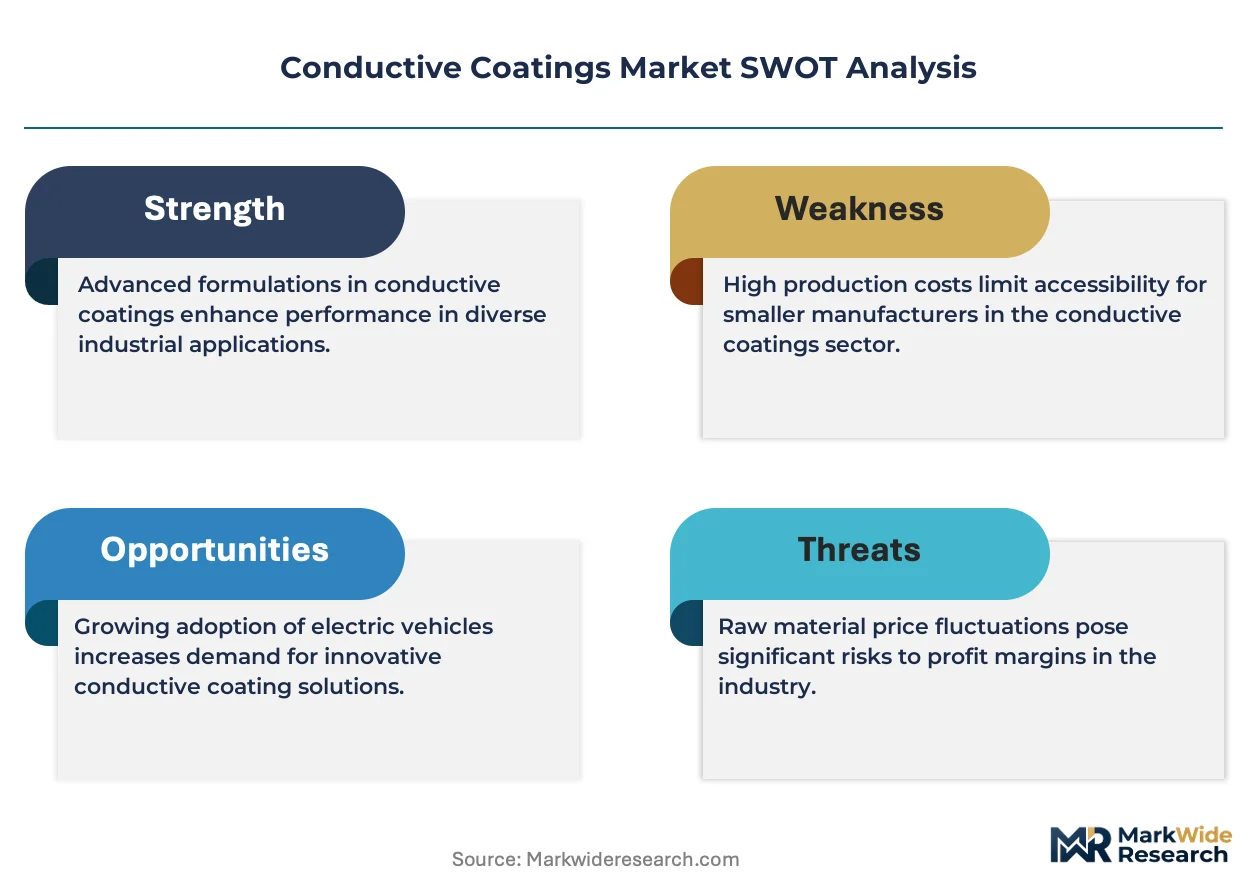
Buyer concentration among automotive electronics suppliers is restructuring procurement patterns across the conductive coatings value chain. PPG Industries leverages its automotive OEM relationships to sustain volume commitments for silver-based EMI formulations. Henkel AG & Co. KGaA anchors the European industrial segment with epoxy-conductive adhesives that compete directly with traditional coating systems. 3M differentiates through fluoropolymer-conductive hybrids that occupy the aerospace specification tier.
Conductive coatings are thin-film formulations incorporating metallic or carbon-based fillers that provide electrical conductivity while maintaining substrate adhesion and environmental protection, typically achieving surface resistances from 10^-3 to 10^6 ohms per square depending on filler loading and binder chemistry. These materials serve primarily to dissipate static charge, provide electromagnetic interference shielding, and create functional circuit pathways on non-conductive substrates. Silver coatings dominate current value generation due to their unmatched conductivity and established supply chains, though graphene coatings represent the fastest-expanding technology segment as manufacturers seek to reduce precious metal dependence. Carbon-based coatings sustain cost-sensitive volume applications in consumer electronics packaging, while vacuum deposition technology commands premium positioning for medical device electrodes where film uniformity directly impacts signal fidelity.
EPA hazardous air pollutant standards for coating operations and REACH substance restrictions on chromium and certain nanoparticles are elevating compliance costs and redirecting R&D investment toward waterborne and UV-curable conductive systems. China's MEE enforcement of VOC emission limits at provincial level is forcing domestic reformulation of solvent-based silver pastes used in electronics manufacturing. Stakeholders must monitor how evolving ECHA nanomaterial registration requirements and FDA biocompatibility standards for implantable device coatings reshape material qualification timelines and supplier certification barriers.
Market Dynamics
Waterborne conductive formulations are displacing solvent-based systems across electronics manufacturing as REACH VOC limits and China's MEE enforcement tighten emission controls, compressing reformulation timelines and elevating waterborne R&D allocation.
Growth Catalysts
- EMI Shielding Mandates:FCC emission standards for 5G infrastructure and automotive radar systems are expanding specification-grade silver coating volumes for base station enclosures and vehicle sensor housings.
- Dual Carbon Goals:China's provincial MEE enforcement is accelerating domestic electronics manufacturers' transition from solvent-based silver pastes to waterborne alternatives with equivalent conductivity profiles.
- Flexible Circuit Demand:South Korea's display manufacturing belt is scaling graphene-polymer hybrid procurement for foldable device interconnects, reducing precious metal loading while maintaining bend-cycle durability.
Market Restraints
- Silver Price Volatility:Precious metal cost swings compress margin stability for EMI shielding suppliers serving automotive electronics tier-1s with annual price-lock contracts.
- Single-Source Graphene Feedstock:High-purity graphene flake supply concentrates among limited Chinese and Canadian producers, creating qualification bottlenecks for aerospace specification tiers.
- Film Uniformity Limits:Vacuum deposition throughput constraints restrict medical electrode coating economics against screen-printed alternatives for high-volume diagnostic applications.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and mobile device assembly are creating first-mover positioning for conductive adhesive suppliers establishing local formulation capacity.
- UV-Curable Convergence:Instant-cure conductive inks paired with roll-to-roll processing are enabling on-demand circuit patterning for IoT sensor substrates without thermal damage to polymer bases.
- Biocompatibility Certification:FDA streamlined pathways for implantable device coatings are shortening qualification timelines for silver-silver chloride electrode formulations in neurostimulation applications.
Industry Challenges
- Formulation Chemistry Expertise Gap:Cross-functional talent combining polymer science, filler dispersion, and electronics packaging knowledge commands premium compensation and extended recruitment cycles.
- MEE Compliance Timeline Compression:China's provincial environmental inspectors are granting 90-day reformulation windows for solvent-based coating lines, forcing parallel validation of waterborne alternatives without production interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Conductive Coatings Market |
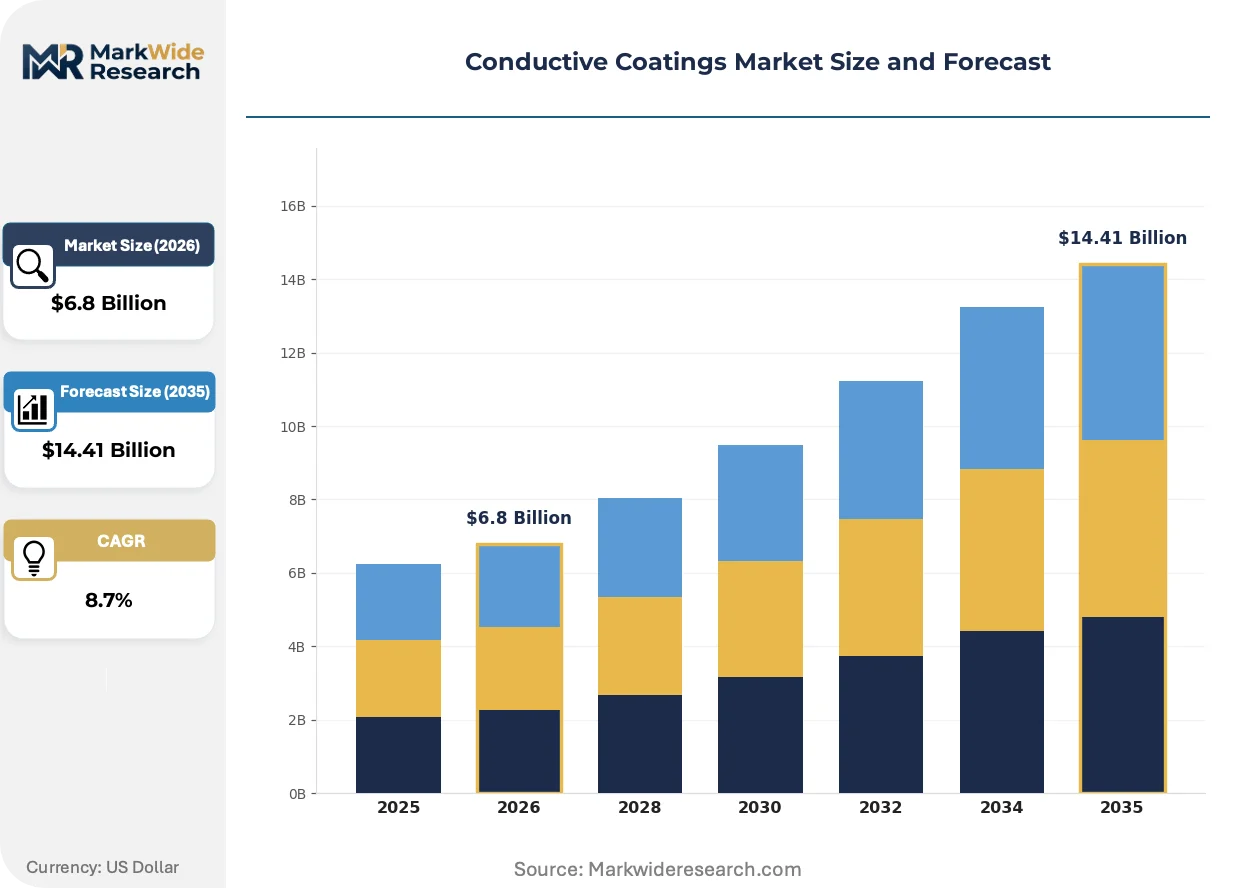
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Coatings, Copper Coatings, Graphene Coatings, Carbon-Based Coatings Technology: Electrostatic Spray Coating, Screen Printing, Dip Coating, Vacuum Deposition Application: Electronics, Automotive, Aerospace, Medical Devices End Use Industry: Consumer Electronics, Industrial Equipment, Telecommunications, Energy |
| Companies Covered | PPG Industries Inc., Akzo Nobel NV, Henkel AG & Co. KGaA, Parker Hannifin Corp., Axalta Coating Systems Ltd., The Sherwin-Williams Company, 3M, Altana AG, Creative Materials Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conductive Coatings Market Emerging Trajectories
Modular deposition architectures and regulatory emission frameworks are converging to reshape how conductive coatings transition from laboratory qualification to production-scale deployment across defense, medical, and consumer electronics verticals.
Hybrid silver-graphene composite inks are modularizing functional circuit fabrication by enabling screen-printed antenna patterns with tunable conductivity gradients. Automotive radar module suppliers in Germany's electronics corridor are adopting these formulations to replace etched copper traces on curved bumper substrates. This modularizing trend compresses capital requirements for antenna production while expanding design freedom for vehicle exterior integration.
REACH Annex XVII restrictions on chromium compounds and evolving ECHA nanomaterial registration requirements are elevating documentation burdens for conductive coating importers serving European medical device manufacturers. Industrial consequence includes extended safety data sheet preparation and downstream user notification protocols. Medical electrode suppliers are responding by consolidating supplier bases to partners with established nano-registry dossiers, favoring incumbents over emerging graphene specialists.
Specification-driven procurement is consolidating buyer power among automotive OEMs and defense primes, compressing vendor counts for EMI shielding qualifications. Tier-1 electronics suppliers are unbundling coating specification authority from substrate sourcing, creating direct relationships with PPG, Henkel, and 3M for silver-based formulations. This concentration is most visible in Texas and California defense-aerospace clusters, where primes now mandate supplier-specific material approval lists for satellite and avionics applications.
Conductive Coatings Market Segmentation
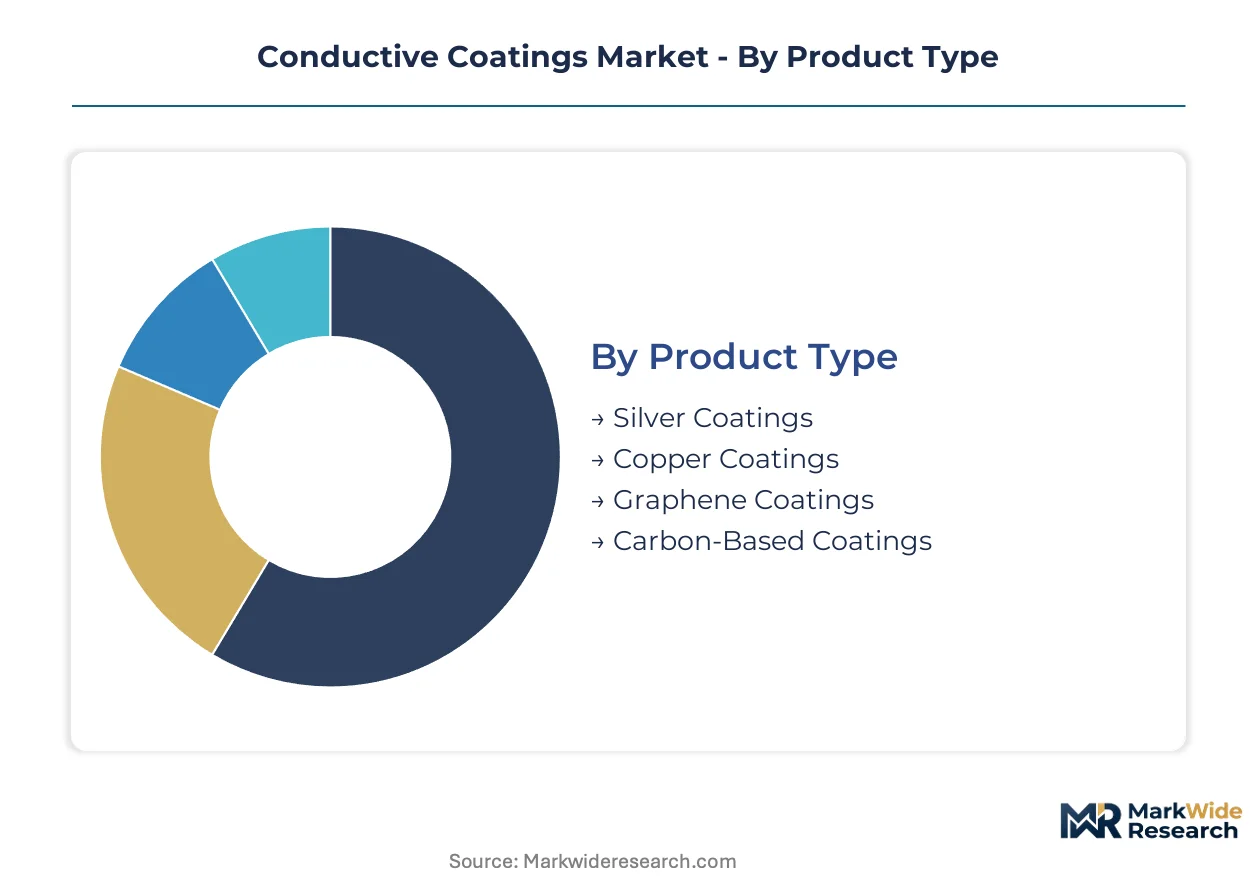
Conductive coatings fragment across four intersecting dimensions that determine formulation chemistry, deposition method, and qualification barriers. Product type governs raw material cost exposure and conductivity hierarchy. Technology selection locks in capital intensity and throughput economics. Application verticals impose distinct regulatory and performance specifications.
Product Type:
Silver flake supply concentrates among German and Japanese refiners, creating procurement leverage for EMI shielding formulators serving automotive tier-1s.
- Silver Coatings:Flake and nanoparticle suspensions in epoxy or acrylic binders achieve surface resistances below 0.01 ohms per square. Demand clusters in Germany's automotive electronics corridor for radar module housings, though silver price volatility compresses margin stability under annual price-lock contracts.
- Graphene Coatings:Exfoliated graphite dispersions in polymer matrices enable tunable conductivity with reduced precious metal loading. South Korea's display manufacturing belt scales procurement for foldable device interconnects, yet single-source feedstock from Chinese and Canadian producers creates qualification bottlenecks for aerospace tiers.
- Copper Coatings:Oxidation-stabilized particle systems compete on cost for industrial grounding applications where conductivity requirements are moderate.
- Carbon-Based Coatings:Carbon black and graphite formulations sustain cost-sensitive volume in consumer electronics packaging and anti-static flooring.
Today's leader: Silver Coatings. Tomorrow's challenger: Graphene Coatings.
Technology:
Deposition method selection separates specification-grade medical and aerospace applications from high-volume electronics manufacturing.
- Vacuum Deposition:Physical vapor deposition of metals onto polymer substrates achieves atomic-scale film uniformity critical for signal fidelity. Medical electrode manufacturers in the US cluster around this technology despite throughput constraints that limit economics against screen-printed alternatives for high-volume diagnostic applications.
- Screen Printing:Thick-film conductive pastes enable roll-to-roll patterning of antenna traces and circuit pathways. Automotive radar suppliers in Germany adopt silver-graphene hybrid inks to replace etched copper on curved bumper substrates, compressing capital requirements while expanding design freedom.
- Electrostatic Spray Coating:Charged particle application delivers uniform coverage on complex geometries for EMI shielding of base station enclosures and industrial equipment housings.
- Dip Coating:Submersion methods serve high-volume consumer electronics packaging where film thickness tolerance is relaxed and processing speed dominates.
Vacuum Deposition commands premium positioning. Screen Printing scales fastest across automotive and flexible electronics.
Application:
End-use performance requirements fragment the vendor landscape between commodity suppliers and specification-locked specialists.
- Electronics:EMI shielding and interconnect applications span consumer devices through 5G infrastructure. FCC emission standards for base stations and automotive radar expand specification-grade silver coating volumes.
- Automotive:Sensor housings and battery management systems drive waterborne formulation transitions as China's MEE enforces VOC emission limits at provincial level.
- Aerospace:Satellite and avionics applications mandate supplier-specific material approval lists in Texas and California defense clusters, consolidating procurement authority with PPG, Henkel, and 3M.
- Medical Devices:Implantable electrodes and diagnostic sensors require FDA biocompatibility certification, favoring incumbents with established safety dossiers over emerging graphene specialists.
Electronics generates current volume concentration. Medical Devices represents the steepest expansion trajectory as neurostimulation applications multiply.
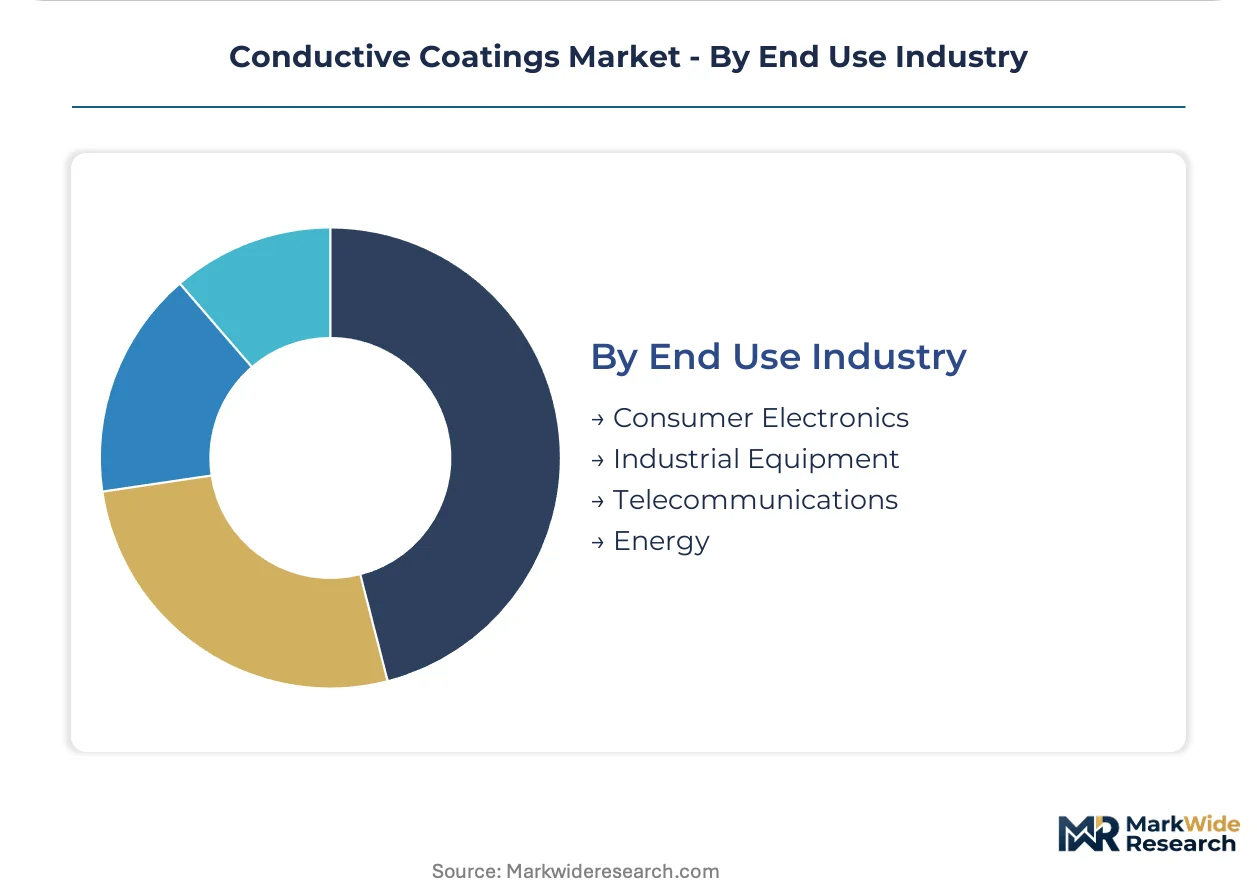
End Use Industry:
Customer procurement sophistication separates price-driven volume buyers from specification-locked technology adopters.
- Consumer Electronics:Mobile device and wearable manufacturers drive cost-down pressure on carbon-based and copper formulations for packaging and shielding applications.
- Telecommunications:5G infrastructure deployment sustains silver coating demand for base station enclosures and antenna arrays.
- Industrial Equipment:Grounding and static dissipation applications favor mature carbon and copper systems with established supply chains.
- Energy:Battery and fuel cell interconnects represent emerging demand for corrosion-resistant conductive coatings in grid storage applications.
Telecommunications anchors near-term procurement. Energy storage applications are climbing fastest as grid-scale battery deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and filler dispersion engineers cluster around Germany's automotive electronics corridor, South Korea's display belt, and the US defense-aerospace nexus. These talent concentrations anchor regional competitive positioning in formulation development and qualification expertise.
United States
Defense primes in Texas and California mandate supplier-specific material approval lists for satellite and avionics EMI shielding applications. FCC emission standards for 5G infrastructure expand specification-grade silver coating procurement for base station enclosures. Houston and Los Angeles aerospace clusters consolidate direct relationships with formulators for radar-absorbent and conductive hybrid systems.
Germany
Automotive tier-1 electronics suppliers drive procurement of silver-graphene hybrid inks for curved bumper-integrated radar modules. REACH Annex XVII restrictions on chromium compounds elevate documentation burdens for medical device coating importers. Bavaria's automotive electronics corridor hosts concentrated formulation R&D for waterborne conductive systems replacing solvent-based alternatives.
China
Provincial MEE enforcement grants 90-day reformulation windows for solvent-based silver paste lines in electronics manufacturing. Dual carbon goals accelerate domestic transition to waterborne conductive coatings with equivalent conductivity profiles. Yangtze River Delta electronics assemblers scale procurement of carbon-based formulations for cost-sensitive consumer device packaging.
South Korea
Display manufacturers scale graphene-polymer hybrid procurement for foldable device interconnects requiring bend-cycle durability. MFDS biocompatibility standards shape electrode coating qualification timelines for emerging neurostimulation applications. Seoul metropolitan area concentrates vacuum deposition expertise for medical signal fidelity applications.
India
PLI scheme incentives for semiconductor packaging and mobile device assembly attract first-mover conductive adhesive suppliers. BIS certification requirements extend material qualification timelines for imported formulations. Maharashtra and Karnataka electronics manufacturing zones concentrate domestic formulation capacity investment for anti-static and EMI shielding applications.
Conductive Coatings Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across specification tiers, creating a bifurcated structure where scale-driven coating majors anchor automotive and aerospace procurement while niche formulators capture medical and flexible electronics segments. The vendor base separates into three archetypes: diversified chemical majors with automotive OEM relationships, specialty adhesive and sealant houses with industrial electronics expertise, and emerging graphene-focused technology developers. Competitive dynamics center on M&A activity consolidating formulation capabilities and strategic partnerships securing single-source graphene feedstock for aerospace qualification tiers.
Among diversified coating majors, PPG Industries and Axalta Coating Systems occupy positions anchored by automotive specification authority, while Henkel AG & Co. KGaA exemplifies the specialty adhesive house archetype competing directly with traditional coating systems through epoxy-conductive platforms. These three entities represent distinct strategic postures: PPG leverages volume commitments through OEM channel relationships, Axalta maintains industrial coating infrastructure adaptable to conductive formulations, and Henkel anchors European industrial segments with materials science expertise spanning adhesion and conductivity optimization.
| Leading Market Players |
|---|
| PPG Industries Inc. |
| Akzo Nobel NV |
| Henkel AG & Co. KGaA |
| Parker Hannifin Corp. |
| Axalta Coating Systems Ltd. |
| The Sherwin-Williams Company |
| 3M |
| Altana AG |
| Creative Materials Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized polymer chemists and filler dispersion engineers clustering around Germany's automotive electronics corridor, South Korea's display belt, and the US defense-aerospace nexus create labor-cost differentials that widen pricing-tier spreads between specification-grade formulators and commodity suppliers.
Pricing Analysis
Bundled formulation-plus-qualification services command premiums against unbundled material-only supply in medical and aerospace tiers. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-deposited medical electrodes from screen-printed automotive radar coatings and dip-coated consumer electronics packaging. Cost compression in silver flake formulations is intensifying because automotive tier-1s negotiate annual price-lock contracts. Consumer electronics manufacturers exhibit highest price sensitivity, while defense primes show lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Silver flake supply rests on German and Japanese specialty metal refiners, while high-purity graphene feedstock draws from Chinese and Canadian producers. Epoxy binders, acrylic carriers, and exfoliated graphite constitute critical input dependencies alongside precious metal powders. Single-source vulnerability concentrates in aerospace-grade graphene qualification tiers where limited producers create approval bottlenecks. Distribution runs through direct specification relationships with automotive OEMs and defense primes, bypassing traditional coating distributors for EMI shielding and radar-absorbent formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in waterborne formulation transitions and graphene-polymer hybrid platforms as silver price volatility and dual carbon compliance create premium-tier shifts away from precious metal dependence.
For Market Incumbents: Extend waterborne R&D pipelines to capture MEE-driven solvent reformulation mandates in China's electronics manufacturing zones. Deepen backward integration into graphene feedstock partnerships to secure aerospace qualification tiers against emerging Canadian and Chinese specialists. Lock in automotive OEM specification authority through joint validation of silver-graphene hybrid inks for curved bumper radar modules.
For New Entrants and Emerging Players: UV-curable conductive ink platforms offer technology-first wedge into IoT sensor substrate markets where instant-cure roll-to-roll processing eliminates thermal damage risks. Target India's PLI-incentivized semiconductor packaging corridors for first-mover conductive adhesive positioning. Pursue FDA streamlined biocompatibility pathways for implantable neurostimulation electrodes as qualification barriers favor nimble specialists over diversified incumbents.
For Investors and Strategic Acquirers: Specialty adhesive houses with established automotive electronics relationships are the most active acquirer in this space, consolidating formulation capabilities and nano-registry dossiers. Long-term viability hinges on waterborne technology transitions and graphene scale-up economics rather than silver price cyclicality. Watch ECHA nanomaterial registration enforcement timelines as inflection indicator for supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Transition | MEE enforcement in China accelerates domestic electronics manufacturers' solvent-to-waterborne conversion timelines. |
| Graphene Feedstock Partnership | Single-source aerospace qualification bottlenecks favor early movers securing Canadian or Chinese flake supply. |
| UV-Curable Ink Platform Launch | Instant-cure roll-to-roll processing enables on-demand IoT sensor circuit patterning without thermal substrate damage. |
| Biocompatibility Certification Investment | FDA streamlined pathways for implantable electrodes shorten neurostimulation application qualification cycles. |
| Automotive Specification Authority Lock | Direct OEM relationships for silver-graphene hybrid inks replace etched copper in curved bumper radar modules. |
Methodological Framework
Multiple input streams — technical R&D directors at coating formulators, procurement leads at automotive tier-1 electronics suppliers, biomedical engineers at medical device manufacturers, and channel partners in industrial distribution — were reconciled against customs and trade data, SEC 10-K filings, ECHA nano-registry dossiers, and REACH Annex XVII restriction notices. Bottom-up volume modeling across product type, technology, application, and end-use industry segments was cross-validated through top-down macroeconomic triangulation.
Data-stream reconciliation anchored volume and value outputs across the projection horizon through segmented demand modeling by deposition method, filler chemistry, and regional regulatory cluster. CAGRs were derived from fitted growth curves incorporating silver price volatility indices, MEE enforcement intensity metrics, and graphene production scale-up trajectories. Industry-specific forecast inputs included automotive radar module penetration rates and foldable display manufacturing capacity expansion.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA nanomaterial registration timelines, silver market price cycles, and MEE provincial enforcement variability. Forecasts reflect documented assumptions about waterborne conductivity equivalence and graphene flake supply diversification. A small set of named triggers — REACH restriction scope expansion, FDA biocompatibility pathway revisions, and defense prime supplier list consolidation — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electron Beam Curable Coating Market
Coatings
Asia-Pacific Protective Coatings Market
Coatings
Anti Soiling Coating Market
Coatings
Germany Industrial Coatings Market
Coatings
United States Floor Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Global Performance Coating Market
Coatings
Global Smart Coating Market
Coatings
Technical Coil Coatings Market
Coatings
Automotive Refinish Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Corrosion Protective Coatings and Acid Proof Lining Market
Coatings
Global Powder Coating Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
North America Polyimide Coating Market
Coatings
Hull Coatings Market