
 Global Therapeutic Respiratory Devices Market | 2026-2036
Global Therapeutic Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Therapeutic Respiratory Devices Market Intelligence
Home care providers is rebalancing the end-user mix as post-acute respiratory management shifts outside hospital walls. ResMed Inc. anchors sleep apnea therapy through connected device ecosystems that sustain recurring revenue streams. Koninklijke Philips N.V. dominates oxygen concentrator manufacturing scale across multiple continents. Fisher & Paykel Healthcare Ltd specializes in humidification systems that extend its presence in critical care ventilation circuits.
Therapeutic respiratory devices encompass mechanical apparatus engineered to deliver aerosolized medication, positive airway pressure, or supplemental oxygen to patients with impaired pulmonary function, typically operating at flow rates between 2–15 liters per minute depending on clinical indication. These systems serve the primary commercial purpose of reducing acute exacerbation frequency, stabilizing chronic respiratory disease progression, and enabling ambulatory treatment outside institutional settings. CPAP devices and oxygen concentrators command the largest installed base, while portable ventilators represent the fastest-expanding margin pool as manufacturers miniaturize turbine technology and extend battery endurance. Nebulizers retain mature demand in pediatric and geriatric populations where hand-breath coordination limits inhaler efficacy.
The FDA enforces 510(k) clearance and premarket approval pathways that shape product development timelines for software-integrated respiratory systems, while the EU MDR imposes strengthened clinical evidence requirements for Class IIa and IIb devices entering European markets. Japan's PMDA maintains distinct pharmaceutical affairs standards that condition market access for combination drug-device products such as metered-dose inhalers. Stakeholders must monitor how converging cybersecurity guidance from FDA and EU regulators reshapes connected device architectures and post-market surveillance obligations.
Market Dynamics
Home care providers are consolidating procurement around connected respiratory platforms that transmit adherence data to payers, compressing hospital readmission revenue and forcing manufacturers to embed cellular modules as standard configuration rather than premium tier.
Growth Catalysts
- Remote Patient Monitoring Protocols:CMS reimbursement codes in the United States now cover respiratory therapy delivered outside acute settings, accelerating device deployment into patient homes.
- Aging Demographics:Japan's super-aged population drives concentrator demand as chronic obstructive pulmonary disease prevalence climbs among cohorts over 75.
- Software-Enabled Diagnostics:Turbine miniaturization and algorithm-driven pressure adjustment are extending CPAP efficacy into milder apnea classifications previously untreated.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries control microcontroller supply for turbine motor controllers, exposing manufacturers to allocation volatility.
- EU MDR Clinical Evidence Burden:Class IIb respiratory devices now require prospective clinical studies for CE marking renewal, extending regulatory timelines by 18-24 months.
- Reimbursement Compression:German statutory health insurers have reduced oxygen therapy tariff rates, squeezing concentrator margins across Central European markets.
Strategic Opportunities
- India's Underserved Tier-2 Cities:Pulmonologist density remains below 0.5 per 100,000 population in states like Uttar Pradesh and Bihar, creating whitespace for portable nebulizer distribution.
- Subscription Revenue Models:ResMed and Philips are piloting hardware-as-a-service contracts that bundle device, consumables, and cloud analytics into per-patient monthly fees.
- FDA Breakthrough Device Designation:Expedited review pathways for AI-integrated ventilation systems are compressing time-to-market for adaptive algorithms that personalize pressure support.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time pressure control requires specialized expertise in control theory and medical-grade software validation that pools narrowly in Boston, Tel Aviv, and Munich clusters.
- Legacy Hospital IT Integration:HL7 FHIR interoperability remains incomplete across health systems, forcing device manufacturers to maintain multiple data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Therapeutic Respiratory Devices Market |
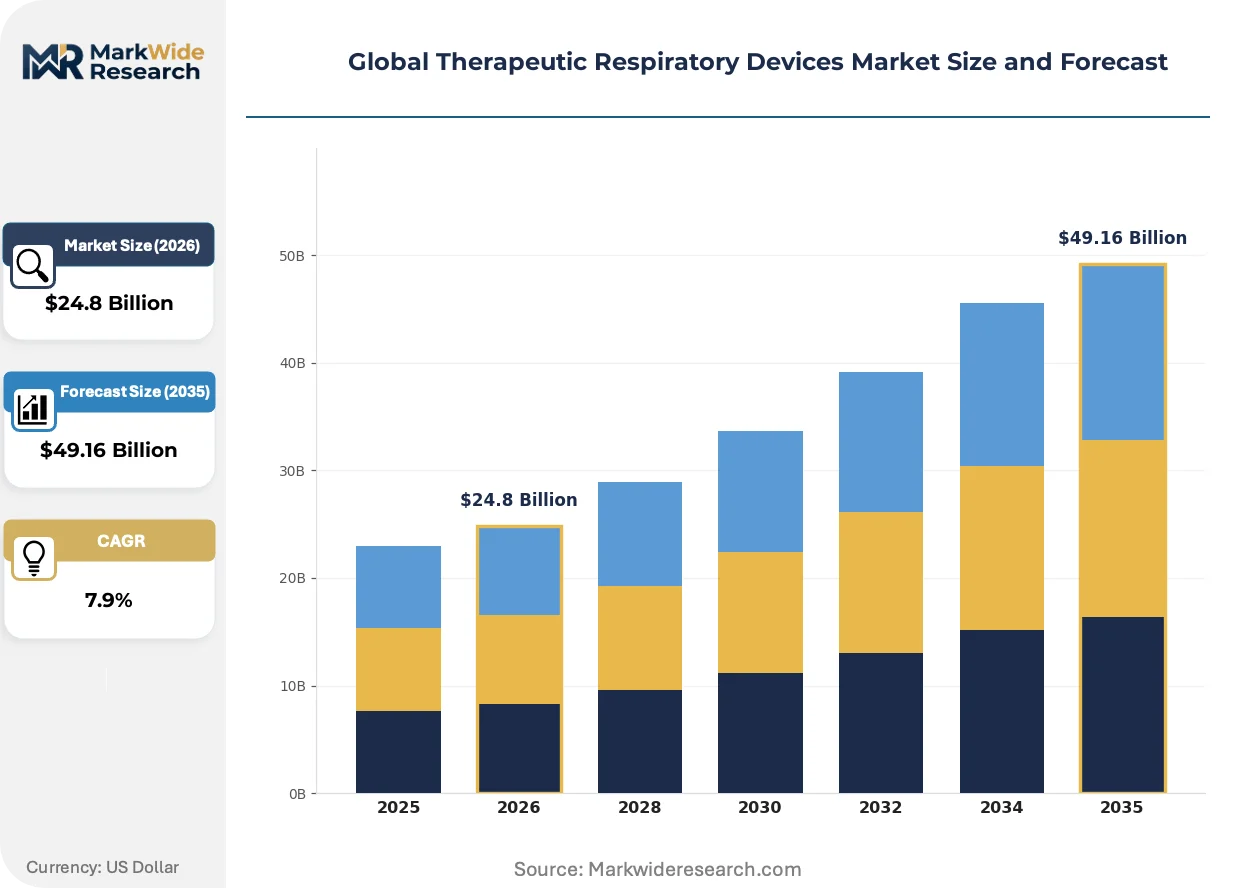
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $49.16 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nebulizers, CPAP Devices, Oxygen Concentrators, Inhalers, Ventilators Application: Chronic Obstructive Pulmonary Disorder, Asthma Management, Sleep Apnea Therapy, Cystic Fibrosis Treatment, Pneumonia Support End User: Home Care Providers, Specialty Clinics, Rehabilitation Centers, Long-Term Care Facilities, Emergency Medical Services Delivery Mode: Manual Operation, Electric Operation, Portable Devices, Stationary Units, Battery-Operated |
| Companies Covered | ResMed Inc., Koninklijke Philips N.V., Fisher & Paykel Healthcare Ltd, Drägerwerk AG & Co. KGaA, GE HealthCare, Becton, Dickinson and Company, Getinge AB, Medtronic, Invacare Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Therapeutic Respiratory Devices Market Strategic Shifts & Innovations
Turbine electrification and solid-state oxygen separation are converging with cloud-native software architectures to redefine how respiratory therapy is delivered, monitored, and reimbursed across ambulatory settings.
Solid-state oxygen concentrators are electrifying the stationary device category by replacing pneumatic compression cycles with electrochemical oxygen separation membranes. Home care providers in Germany and Japan are piloting these units for nocturnal oxygen patients who require silent operation. The technology is electrifying margin structures by eliminating compressor maintenance intervals and enabling decade-long service life projections that reshape capital deployment models.
The EU MDR's strengthened post-market surveillance requirements are forcing manufacturers to restructure quality management systems around proactive vigilance rather than reactive complaint handling. Respiratory device firms must now submit periodic safety update reports that integrate real-world performance data from connected devices. Class IIb ventilation systems face the steepest compliance burden, with notified bodies demanding expanded clinical follow-up periods that delay portfolio renewal cycles.
Hospital purchasing consortia are consolidating procurement authority for respiratory capital equipment into centralized value analysis committees that evaluate total cost of ownership across warranty, training, and disposable bundling. Independent durable medical equipment suppliers in the United States are losing direct hospital access as IDN-owned distribution networks internalize device provisioning. The shift is most visible in the Southeast and Midwest regions where health system consolidation has advanced fastest, compressing vendor counts from twelve to three preferred suppliers per category.
Global Therapeutic Respiratory Devices Market Segmentation
Therapeutic respiratory devices fragment across multiple technical and clinical dimensions that determine reimbursement pathways, regulatory classification, and procurement authority. Manufacturers must align product architectures with specific end-user workflows rather than pursuing universal platform designs.
Product Type:
Turbine engineering specifications and pressure generation mechanisms define competitive differentiation across hardware categories.
- CPAP Devices:Continuous positive airway pressure systems deploy blower motors generating 4–20 cm H₂O pressure ranges with heated humidification circuits. Philips and ResMed dominate procurement contracts with United States sleep centers as CMS reimbursement codes expand coverage into milder apnea classifications.
- Oxygen Concentrators:Pressure swing adsorption systems separate ambient air into 90–95% oxygen concentrations at flow rates of 1–10 liters per minute. German home care providers are consolidating procurement around portable units weighing under five kilograms as statutory insurers push ambulatory therapy.
- Nebulizers:Jet compressor and mesh vibration technologies aerosolize bronchodilator suspensions for patients with limited hand-breath coordination.
- Inhalers:Metered-dose and dry-powder mechanisms deliver corticosteroid formulations through breath-actuated or press-and-breathe designs.
- Ventilators:Turbine-based or pneumatic drive systems provide invasive and non-invasive respiratory support across acute and sub-acute settings.
Oxygen concentrators lead on scale; CPAP devices lead on momentum.
Application:
Clinical indication severity determines device specification requirements and therapy duration economics.
- Sleep Apnea Therapy:Diagnostic polysomnography thresholds have broadened to include respiratory event indices above five events per hour, expanding addressable populations in Japan and the United States where obesity prevalence drives undiagnosed caseloads.
- Chronic Obstructive Pulmonary Disorder:Long-acting bronchodilator delivery through nebulizers or inhalers dominates maintenance therapy for emphysema and chronic bronchitis phenotypes.
- Asthma Management:Controller and rescue medication delivery systems emphasize rapid onset and portable form factors for pediatric and young adult demographics.
- Cystic Fibrosis Treatment:High-frequency chest wall oscillation and mucolytic nebulization address thickened secretions in specialized pulmonary centers.
- Pneumonia Support:Acute oxygenation and secretion clearance devices deploy in emergency departments and step-down units.
Sleep apnea therapy commands the largest installed base; COPD management shows the steepest expansion trajectory.
End User:
Procurement authority concentration varies sharply across care settings, reshaping sales force deployment and service model design.
- Home Care Providers:Durable medical equipment suppliers in the United States are consolidating into regional networks that negotiate volume-based contracts with manufacturers. CMS remote patient monitoring reimbursement codes are accelerating device deployment with cellular connectivity modules as standard configuration.
- Specialty Clinics:Pulmonology and sleep medicine practices in Germany and Japan maintain direct purchasing authority for diagnostic and titration equipment.
- Rehabilitation Centers:Post-acute respiratory therapy programs require ventilator weaning and muscle training devices.
- Long-Term Care Facilities:Skilled nursing facilities in the United States manage stable oxygen therapy and secretion clearance for elderly residents.
- Emergency Medical Services:Portable ventilators and oxygen delivery systems must withstand field conditions and rapid deployment protocols.
Home care providers concentrate procurement volume; specialty clinics retain pricing power on high-acuity configurations.
Delivery Mode:
Power source and mobility specifications determine use-case boundaries and reimbursement categorization.
- Portable Devices:Battery-powered concentrators and ventilators under three kilograms enable ambulatory oxygen therapy and travel mobility. Japanese super-aged populations and United States rural demographics drive replacement of stationary units with transportable alternatives.
- Electric Operation:Mains-powered devices dominate nocturnal therapy and continuous oxygen delivery where weight constraints are secondary to flow rate stability.
- Manual Operation:Hand-powered resuscitation bags and simple nebulizers serve resource-constrained settings and backup scenarios.
- Stationary Units:High-flow concentrators and ICU-grade ventilators occupy fixed infrastructure in institutional settings.
- Battery-Operated:Lithium-ion and solid-state power systems extend runtime for travel ventilators and emergency backup configurations.
Electric operation maintains installed base dominance; portable devices gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as the cost-of-compliance gap between FDA premarket approval and EU MDR clinical evidence requirements widens. Production migration toward jurisdictions with streamlined software-enabled device pathways is accelerating as manufacturers seek to compress 18-24 month regulatory timelines.
United States
CMS reimbursement codes for remote patient monitoring are accelerating home care device deployment with cellular connectivity as standard configuration. The FDA's 510(k) clearance and Breakthrough Device Designation pathways compress time-to-market for AI-integrated ventilation systems. Boston anchors embedded systems talent pools where firmware engineering for real-time pressure control concentrates.
Germany
Statutory health insurers have reduced oxygen therapy tariff rates, squeezing concentrator margins across Central European markets while pushing ambulatory therapy adoption. The EU MDR imposes strengthened clinical evidence requirements for Class IIa and IIb devices entering European markets. Munich clusters specialized expertise in medical-grade software validation for control theory applications.
Japan
Super-aged populations drive concentrator demand as chronic obstructive pulmonary disease prevalence climbs among cohorts over 75. The PMDA maintains distinct pharmaceutical affairs standards that condition market access for combination drug-device products. Tokyo and Osaka metropolitan areas concentrate sleep medicine practices with direct purchasing authority for diagnostic equipment.
India
Pulmonologist density remains below 0.5 per 100,000 population in states like Uttar Pradesh and Bihar, creating whitespace for portable nebulizer distribution. The CDSCO regulates medical device imports while domestic manufacturing incentives expand. Karnataka and Maharashtra host emerging device assembly operations serving tier-2 city penetration strategies.
China
Domestic turbine motor controller production is expanding as manufacturers seek to reduce Taiwan-based foundry allocation exposure. The NMPA regulates software-enabled respiratory systems with evolving cybersecurity guidance. Yangtze River Delta industrial corridors concentrate electrochemical oxygen separation membrane development for solid-state concentrator manufacturing.
Global Therapeutic Respiratory Devices Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers embed cellular modules and cloud analytics to satisfy home care provider procurement consolidation. The vendor base organizes around three tiers: diversified health technology conglomerates with multi-continent oxygen concentrator scale, sleep therapy specialists sustaining recurring revenue through connected device ecosystems, and critical care ventilation firms with humidification circuit expertise. Competitive positioning crystallizes through M&A activity targeting software-enabled diagnostics capabilities and geographic expansion into India's underserved tier-2 markets.
Within the connected platform tier, ResMed Inc. and Koninklijke Philips N.V. exemplify hardware-as-a-service contract pilots that bundle device, consumables, and cloud analytics into per-patient monthly fees. Fisher & Paykel Healthcare Ltd occupies a position among humidification system specialists extending presence in critical care ventilation circuits. These three anchors represent divergent strategic archetypes: therapy-focused recurring revenue models, diversified health technology scale, and sub-system specialization within integrated circuits.
| Leading Market Players |
|---|
| ResMed Inc. |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare Ltd |
| Drägerwerk AG & Co. KGaA |
| GE HealthCare |
| Becton, Dickinson and Company |
| Getinge AB |
| Medtronic |
| Invacare Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up home care equipment distributors in the United States and Germany are consolidating procurement authority into regional networks that extract volume-based rebates from manufacturers, compressing channel margins while forcing suppliers to absorb cellular connectivity module costs as standard configuration rather than premium upsell.
Pricing Analysis
Distributor margin layers in therapeutic respiratory devices typically absorb 18-25 points before reaching end-user facilities, with direct-to-hospital contracts commanding steeper discounts for IDN-owned networks. Three-tier pricing structure across premium, standard, and economy levels separates cloud-integrated platforms with FDA Breakthrough designation from basic pneumatic concentrators and manual nebulizers. Cost compression in portable oxygen concentrators is intensifying because German statutory insurers have reduced ambulatory oxygen tariff rates, squeezing mid-tier manufacturers most severely. Price-sensitive buyers cluster among independent durable medical equipment suppliers in rural United States markets, while academic medical centers in Japan exhibit lowest sensitivity due to bundled reimbursement for critical care configurations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for turbine motor controllers and pressure sensors, bypassing distribution markups for ResMed and Philips volume commitments. Manufacturing concentration rests on Taiwan for microcontroller fabrication, China for lithium-ion battery cell production, and Germany for precision blower motor assembly. Critical dependencies include rare-earth magnets for turbine efficiency, medical-grade silicone for mask interfaces, and specialized pressure transducers. Single-source vulnerability concentrates in Taiwan-based foundries controlling microcontroller supply for real-time pressure control firmware. Distribution runs through hospital purchasing consortia in the United States, statutory health insurer-approved networks in Germany, and sleep medicine clinic direct procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where manufacturers can compress 18-24 month regulatory timelines by routing software-enabled devices through FDA Breakthrough pathways rather than EU MDR Class IIb clinical evidence requirements.
For Market Incumbents: Cement control over connected device data streams by acquiring cloud analytics specialists in Boston and Tel Aviv talent clusters, insulating against white-label hardware entrants from Shenzhen. Defend margin position by backward integration into turbine motor controller firmware development, reducing allocation exposure to Taiwan foundries. Prioritize CE marking renewal investments for Class IIb ventilation portfolios before EU MDR transition deadlines harden.
For New Entrants and Emerging Players: Regional home care networks in India's Uttar Pradesh and Bihar states offer lowest competitive density for portable nebulizer penetration, with pulmonologist scarcity creating whitespace for patient-direct distribution models. Target subscription revenue pilots bundling hardware, consumables, and adherence monitoring into per-patient monthly fees, mirroring ResMed and Philips contract structures. Partner with telemedicine platforms serving tier-2 cities to bypass specialist channel gatekeepers entirely.
For Investors and Strategic Acquirers: Valuations sit cheapest among humidification subsystem specialists with critical care ventilation circuit presence but limited sleep therapy platform scale, offering tuck-in acquisition targets for platform consolidators. Five-to-ten year viability hinges on regulatory pathway efficiency rather than manufacturing scale alone. Watch FDA Breakthrough Device Designation grant velocity as inflection indicator for AI-integrated ventilation system time-to-market compression.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pursuit | Expedited review pathways compress time-to-market for adaptive algorithm ventilation systems against standard 510(k) timelines. |
| CE Marking Pathway Investment | EU MDR Class IIb clinical evidence requirements demand prospective studies that delay portfolio renewal cycles without early preparation. |
| Hospital System Partnership | IDN-owned distribution networks in United States Southeast and Midwest regions consolidate vendor counts from twelve to three preferred suppliers per category. |
| Software Companion Development | Cloud-native adherence analytics satisfy home care provider procurement consolidation around connected respiratory platforms transmitting data to payers. |
| Reimbursement Strategy Alignment | CMS remote patient monitoring codes in United States and German statutory insurer ambulatory oxygen tariffs determine addressable market expansion. |
Research Approach
Multiple input streams — regulatory filing databases, hospital procurement contract registries, and semiconductor supply chain manifests — were reconciled against primary interviews with biomedical engineers, GPO contracts managers, sleep medicine clinicians, and home care network procurement directors. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified body documentation, Japan PMDA pharmaceutical affairs standards, CMS Medicare reimbursement code updates, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up unit economics modeling triangulated against top-down market sizing across product type, application, end user, and delivery mode segmentation dimensions.
Historical shipment data cross-referenced against expert panel inputs from pulmonology practice administrators and durable medical equipment supplier executives shaped analytical framework construction across the analysis window. Segmentation dimensions modeled include device pressure generation mechanism, clinical indication severity, procurement authority concentration, and power source mobility specifications. CAGRs derived from curve-fitting approaches applied to installed base replacement cycles and therapy expansion into milder diagnostic thresholds. Forecast inputs incorporated turbine miniaturization trajectories, solid-state oxygen separation membrane commercialization timelines, and cellular module cost degradation curves.
Revisions become necessary when semiconductor allocation volatility, EU MDR notified body capacity constraints, or CMS reimbursement code modifications materialize outside base-case assumptions. Forecasts reflect documented assumptions regarding regulatory pathway efficiency, home care provider consolidation velocity, and aging demographic chronic disease prevalence trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Incubator Devices Market
Medical Devices
Australia Ultrasound Devices Market
Medical Devices
Global Extracorporeal Shock Wave Lithotripsy Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Contact Cast Systems Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Ventricle Assist Device Market
Medical Devices
Global Dry Powder Inhaler (DPI) Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Intrauterine Insemination Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Colposcopes Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Oral Appliance Market
Medical Devices
Cyclotron Market