
 Veterinary Arthroscopy Device Market | 2026-2036
Veterinary Arthroscopy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Arthroscopy Device Market Insights
ISO 13485 certification for veterinary medical device quality management is redrawing competitive access in this space. Karl Storz SE & Co. KG leverages its endoscopic manufacturing heritage to dominate rigid arthroscope supply for equine and small animal surgeons. Arthrex, Inc. sustains technology leadership through specialized suture anchor and disposable instrument portfolios tailored to veterinary joint anatomy. Biovision Veterinary Endoscopy, LLC. competes on compact, portable system designs that suit mobile veterinary orthopedic services.
Veterinary arthroscopy devices encompass rigid endoscopes, motorized shavers, fluid management pumps, and high-intensity illumination systems engineered for joint examination and minimally invasive surgery in animals. These instruments typically operate with 2.7 mm to 4.0 mm diameter scopes and saline irrigation pressures between 50-150 mmHg to maintain joint distension during stifle, shoulder, and tarsal procedures. Arthroscopes and shaver systems command the deepest installed base among device types, though integrated systems combining HD imaging with robotic assistance are gaining fastest in specialty practices. Orthopedic surgery applications generate the dominant procedure volume, while diagnostic arthroscopy represents a mature, price-sensitive segment where margin pools have compressed.
FDA 510(k) premarket notification requirements govern veterinary surgical devices in the United States, while the EU Medical Device Regulation (MDR) and CE marking framework apply to products sold in Europe, with both regimes pushing manufacturers toward enhanced biocompatibility documentation and clinical performance data. The EU Green Deal's restrictions on hazardous substances in electronics are influencing light source and camera component sourcing decisions across the supply chain. Stakeholders must monitor how regulatory divergence between FDA streamlined pathways and MDR conformity assessment timelines reshapes geographic launch sequencing and capital allocation priorities.
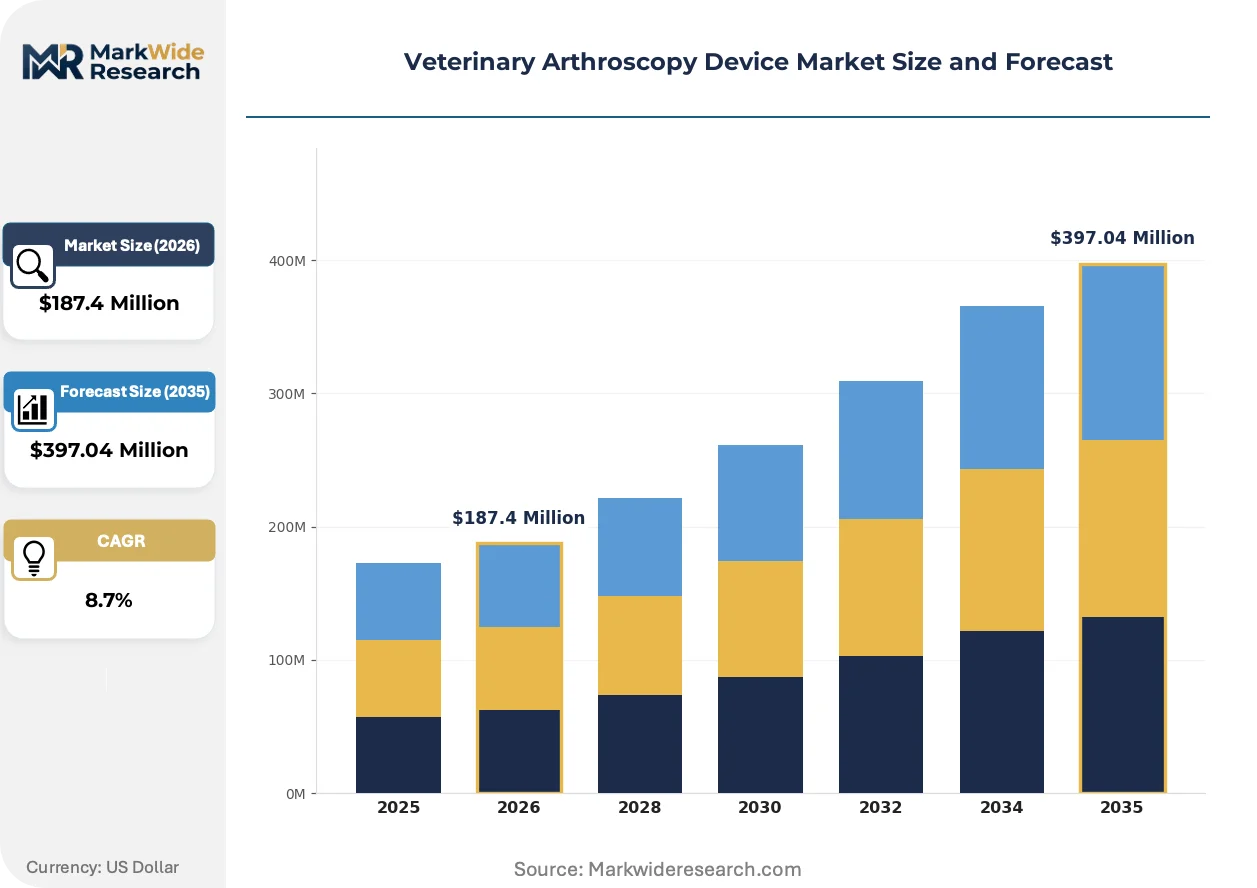
Market Dynamics
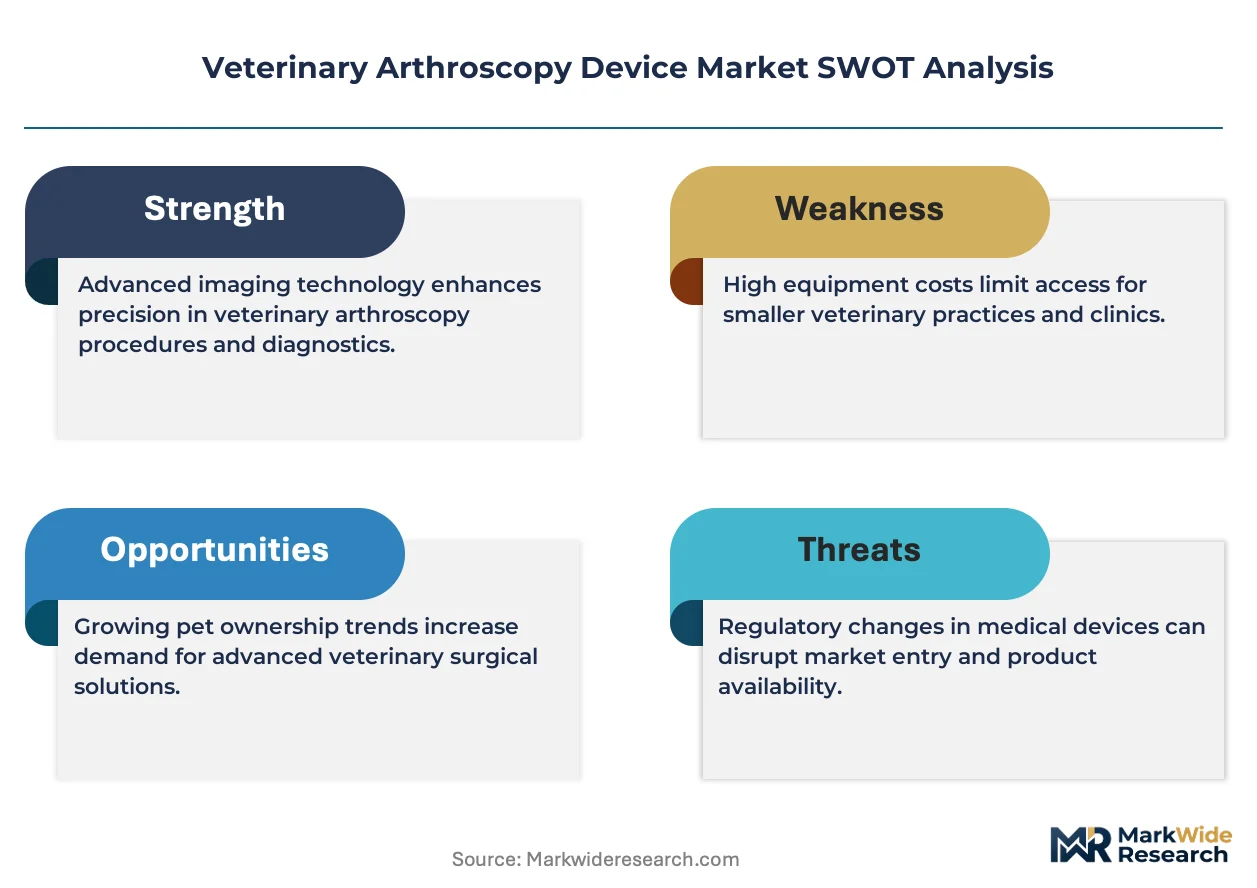
Specialty veterinary referral hospitals are consolidating purchasing power around integrated arthroscopy systems, compressing margins for standalone instrument suppliers while elevating vendors with full-stack visualization and fluid management platforms.
Growth Catalysts
- Companion animal orthopedic specialization:Small animal practices in the United States are building dedicated sports medicine units that standardize on arthroscopy for cruciate ligament and shoulder procedures.
- FDA 510(k) streamlined pathways:The premarket notification framework for veterinary surgical devices accelerates product entry timelines relative to human medical device approvals.
- Equine athletic performance medicine:Thoroughbred racing and sport horse disciplines in Kentucky and Florida are driving demand for stifle and fetlock arthroscopy.
Market Restraints
- Optical component supply concentration:German and Japanese precision glass manufacturers control rod-lens supply for rigid arthroscopes, creating single-source vulnerability.
- Veterinary specialist training pipeline:Residency programs in veterinary surgery produce fewer than 150 board-certified surgeons annually in the United States, constraining procedure volume expansion.
- Capital equipment replacement cycles:High-definition camera heads and light sources operate on 7-10 year depreciation schedules, slowing upgrade velocity.
Strategic Opportunities
- Mobile veterinary surgical services:Equine practitioners in Texas and California are adopting portable arthroscopy systems for on-farm procedures.
- Biodegradable suture anchor materials:Convergence of polymer science and veterinary orthopedics is opening premium pricing for absorbable fixation devices.
- Telemedicine-integrated diagnostic arthroscopy:Real-time video streaming to university teaching hospitals enables remote case consultation and resident training.
Industry Challenges
- Cross-species instrument compatibility:Manufacturers must engineer scope diameters and working channel geometries that accommodate anatomical variation from 3-kg terriers to 500-kg horses.
- ISO 13485 certification timelines:Quality management system audits for veterinary device manufacturers average 18-24 months from initial documentation to certificate issuance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Arthroscopy Device Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Arthroscopes, Fluid Pumps, Light Sources, Shaver Systems Application: Orthopedic Surgery, Soft Tissue Surgery, Diagnostic Procedures, Joint Repair End User: Veterinary Clinics, Research Laboratories, Animal Hospitals, Specialty Practices Technology: High-Definition Imaging, Minimally Invasive Techniques, Robotic Assistance, Integrated Systems |
| Companies Covered | Arthrex, Inc., Karl Storz SE & Co. KG, Biovision Veterinary Endoscopy, LLC., Eickemeyer, vetOvation, Dr. Fritz Endoscopes, DePuy Synthes, Integra LifeSciences Corporation, ConMed Linvatec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Arthroscopy Device Market Trends and Innovations
Digital imaging pipelines and disposable instrument economics are reconfiguring how veterinary arthroscopy systems are specified, purchased, and maintained across practice types.
4K camera sensor technology is miniaturizing arthroscope distal tips while preserving optical resolution, enabling 2.7 mm diameter scopes to deliver surgical-grade visualization previously requiring 4.0 mm instruments. Specialty companion animal practices in Germany are adopting these platforms for feline and toy-breed canine joint procedures. The shift is compressing demand for traditional 4.0 mm rigid scopes in small animal applications.
The EU Medical Device Regulation's enhanced biocompatibility documentation requirements are extending conformity assessment timelines for arthroscopy shaver handpieces and cannulae sold in Europe. Manufacturers are reallocating regulatory affairs resources from new product development to technical file remediation. German and Swiss veterinary device suppliers are most exposed given their historical European market concentration.
Leasing and subscription-based equipment access models are displacing outright capital purchases among independent veterinary orthopedic practices. Equipment finance firms are bundling maintenance, consumables, and software updates into per-procedure fee structures. This transition is most visible in the United States, where practice ownership consolidation has tightened credit access for standalone equipment acquisition.
Veterinary Arthroscopy Device Market Segmentation
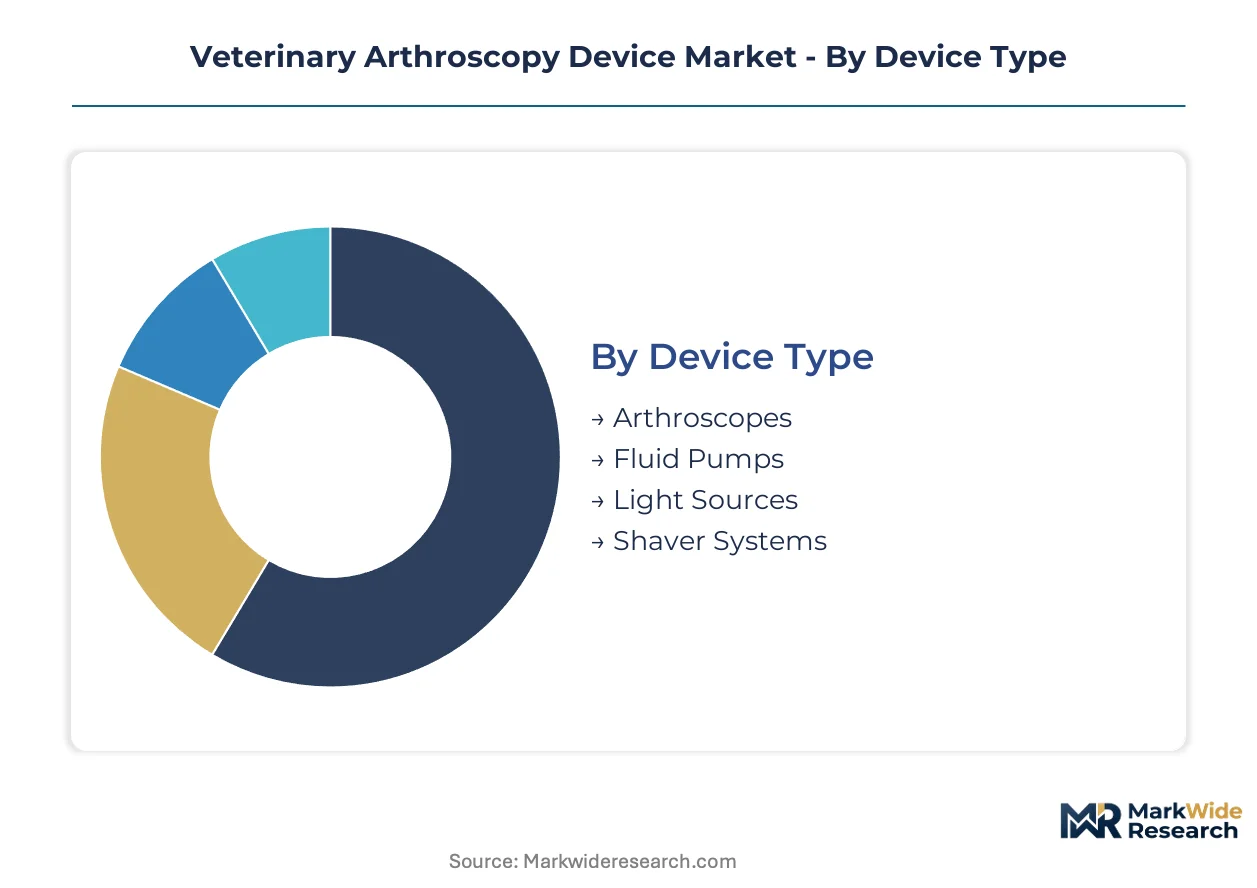
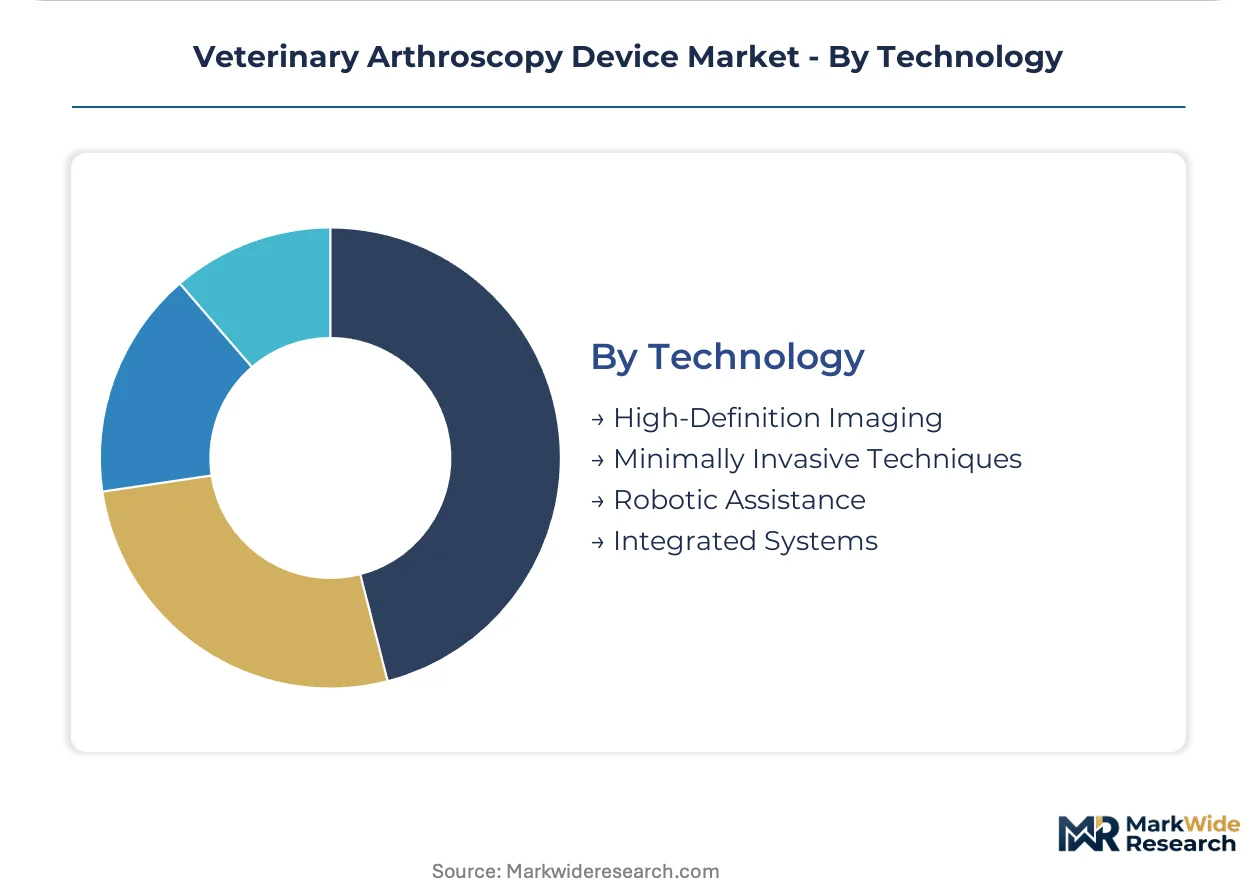
Segmentation in veterinary arthroscopy reveals how capital allocation, procedure complexity, and practice scale reshape purchasing patterns. Device specifications, application settings, and technology tiers fragment demand across distinct customer economics and regulatory exposure.
Device Type:
Substitution pressure from integrated visualization platforms threatens standalone instrument margins most acutely in mature categories.
- Arthroscopes:Rigid endoscopes with 2.7 mm to 4.0 mm diameters deliver optical visualization through rod-lens systems. German and Japanese precision glass manufacturers supply critical lens components to veterinary device assemblers in the United States and Europe. Demand concentrates in specialty companion animal practices performing stifle and shoulder procedures.
- Shaver Systems:Motorized handpieces with disposable blades enable synovial tissue resection and joint debridement. Kentucky and Florida equine referral hospitals drive replacement cycle velocity for high-torque shaver motors. Battery-powered portable variants are displacing console-based systems in mobile veterinary services.
- Fluid Pumps:Saline irrigation systems maintain 50-150 mmHg joint distension pressure during procedures.
- Light Sources:High-intensity LED and xenon illumination systems power arthroscope distal tip visualization.
Arthroscopes anchor the volume base while shaver systems gain share at the steepest rate.
Application:
Cost tier stratification separates high-margin therapeutic interventions from commoditized diagnostic screening.
- Orthopedic Surgery:Cruciate ligament repair, shoulder osteochondritis dissection, and tarsal arthrodesis command premium device utilization. United States specialty practices in sports medicine units standardize on arthroscopy for TPLO and TTA adjunct procedures. Procedure volume scales with board-certified veterinary surgeon availability.
- Diagnostic Procedures:Exploratory joint examination without therapeutic intervention faces pricing compression from alternative imaging modalities. German and Japanese university teaching hospitals maintain steady demand for resident training applications. Reimbursement limitations constrain expansion in general practice settings.
- Joint Repair:Meniscal treatment and subchondral bone microfracture utilize specialized instrument sets.
- Soft Tissue Surgery:Synovectomy and capsular release procedures apply arthroscopic access techniques.
Orthopedic surgery commands the revenue concentration while joint repair climbs the fastest.
End User:
Customer type determines capital intensity, with consolidated hospital networks extracting volume discounts unavailable to independent operators.
- Specialty Practices:Dedicated orthopedic and sports medicine clinics generate the deepest per-procedure device utilization. United States referral networks in metropolitan corridors concentrate purchasing power around integrated system vendors. Leasing and subscription models displace outright capital acquisition.
- Veterinary Clinics:General practice settings with occasional arthroscopy capability prioritize portable, multi-species compatible systems. Mobile equine practitioners in Texas and California adopt compact platforms for on-farm procedures. Capital constraints limit upgrade frequency.
- Animal Hospitals:Multi-specialty tertiary institutions coordinate arthroscopy with imaging and rehabilitation services.
- Research Laboratories:Academic and pharmaceutical research facilities utilize arthroscopy for preclinical orthopedic studies.
Specialty practices dominate absolute spending while veterinary clinics expand most quickly.
Technology:
Maturity gradients separate established visualization platforms from emerging integration architectures.
- High-Definition Imaging:4K camera sensors miniaturized to 2.7 mm scope diameters preserve surgical-grade resolution. German specialty practices adopt these platforms for feline and toy-breed canine applications. The shift compresses demand for legacy 4.0 mm optical systems.
- Integrated Systems:Combined visualization, fluid management, and instrument control platforms consolidate vendor relationships. United States specialty hospital networks standardize purchasing around full-stack suppliers. FDA 510(k) streamlined pathways accelerate product entry timelines relative to human device approvals.
- Minimally Invasive Techniques:Single-portal and reduced-approach methods demand specialized cannulae and angled optics.
- Robotic Assistance:Haptic guidance and automated instrument positioning remain early-stage in veterinary applications.
High-definition imaging holds the installed base while integrated systems capture the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty veterinary referral hospitals in the United States, Germany, and Japan concentrate purchasing power for arthroscopy systems. These markets build advanced networks that standardize on minimally invasive joint procedures for companion animals and equines.
United States
Kentucky and Florida equine referral hospitals drive stifle and fetlock arthroscopy volume for thoroughbred racing and sport horse disciplines. FDA 510(k) premarket notification pathways accelerate veterinary surgical device approvals relative to human medical frameworks. Metropolitan corridor specialty practices in New York, California, and Texas consolidate purchasing around integrated visualization platforms.
Germany
German precision glass manufacturers supply critical rod-lens components for rigid arthroscope assembly to veterinary device makers worldwide. EU Medical Device Regulation biocompatibility documentation requirements extend conformity assessment timelines for shaver handpieces and cannulae. Bavarian and Baden-Württemberg surgical instrument clusters anchor European veterinary endoscope production capacity.
Japan
Japanese university teaching hospitals maintain steady demand for diagnostic arthroscopy in resident training programs. METI industrial standards and PMDA quality frameworks govern veterinary medical device market entry. Tokyo and Osaka metropolitan veterinary referral networks concentrate sports medicine specialization for small animal orthopedics.
United Kingdom
UK specialty companion animal practices in the Southeast and Midlands build dedicated arthroscopy units for cruciate ligament procedures. CE marking and UKCA conformity requirements apply to veterinary surgical devices post-Brexit regulatory divergence. London corridor referral hospitals coordinate purchasing with European mainland supplier networks.
Australia
Australian equine practitioners in New South Wales and Victoria adopt portable arthroscopy systems for on-farm procedures in thoroughbred and sport horse sectors. TGA regulatory frameworks align with international standards for veterinary device quality management. Sydney and Melbourne specialty veterinary hospitals drive adoption of 4K imaging platforms for small animal joint surgery.
Veterinary Arthroscopy Device Market Competitive Landscape
Player mix skews toward diversified surgical instrument conglomerates with endoscopic manufacturing heritage alongside specialized veterinary device boutiques. Market structure concentrates around three to four full-stack system vendors controlling integrated platform supply, while standalone instrument suppliers face margin compression. Strategic archetypes span heritage endoscope manufacturers, veterinary-focused specialists, and diversified orthopedic conglomerates. Competitive moves center on regulatory certification acceleration and leasing model expansion to capture independent practice demand.
Within the heritage endoscope tier, Karl Storz SE & Co. KG anchors German-engineered rigid arthroscope supply through its manufacturing base in Baden-Württemberg. Arthrex, Inc. and Biovision Veterinary Endoscopy, LLC. occupy distinct positioning vectors—Arthrex exemplifying diversified orthopedic technology portfolios, Biovision representing compact portable system design for mobile service applications. These three entities collectively illustrate how geographic manufacturing heritage, species-specific specialization, and form-factor innovation define competitive differentiation in veterinary arthroscopy supply.
| Leading Market Players |
|---|
| Arthrex, Inc. |
| Karl Storz SE & Co. KG |
| Biovision Veterinary Endoscopy, LLC. |
| Eickemeyer |
| vetOvation |
| Dr. Fritz Endoscopes |
| DePuy Synthes |
| Integra LifeSciences Corporation |
| ConMed Linvatec |
| Others |
Pricing and Supply Chain Analysis
4K camera sensor miniaturization replacing legacy 4.0 mm optical systems simultaneously shifts procurement toward Japanese precision glass suppliers and compresses margin pools for standalone arthroscope manufacturers unable to bundle visualization platforms. German and Japanese rod-lens producers now capture disproportionate pricing power as veterinary device assemblers compete for limited high-resolution optical component capacity.
Pricing Analysis
Cost-plus contracts with German and Japanese optical component suppliers index to precision glass spot markets and yen-euro exchange rate fluctuations. Three-tier pricing structure across premium 4K-integrated systems, standard HD platforms, and economy refurbished equipment separates university teaching hospitals from metropolitan specialty practices and mobile equine services. Cost compression in the economy tier intensifies as leasing firms bundle maintenance and consumables into per-procedure fee structures. Mobile veterinary clinics exhibit highest price sensitivity, while consolidated United States specialty hospital networks extract volume discounts through multi-year integrated system commitments.
Supply Chain Analysis
Just-in-time inventory strategies dominate among United States veterinary device assemblers, though German manufacturers maintain strategic stockpiles of precision rod-lens assemblies against optical component supply disruption. Supply concentrates in Germany, Japan, and the United States for critical inputs: Schott AG and Hoya Corporation control precision glass rod-lens supply, while Sony and OmniVision anchor 4K CMOS sensor production. Single-source vulnerability in German-Japanese optical component supply creates structural risk from trade restriction or logistics chokepoint. Distribution runs through specialized veterinary surgical instrument distributors and direct hospital system contracts, with equipment finance firms increasingly intermediating capital acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: FDA 510(k) clearance timelines and ISO 13485 certification barriers protect incumbents from rapid competitive displacement while locking in customer switching costs.
For Market Incumbents: Consolidate backward integration into precision optical component supply through captive manufacturing partnerships with Baden-Württemberg or Tottori Prefecture glass specialists. Lock in multi-year exclusive supply agreements with Kentucky and Florida equine referral hospitals before portable system competitors erode installed base loyalty. Priority lever rests on preemptive certification investment for EU MDR technical file remediation. For New Entrants and Emerging Players: Mobile veterinary surgical service gaps in Texas, California, and Australian New South Wales present white-space penetration targets where incumbents under-serve on-farm equine practitioners. Compact battery-powered shaver systems with disposable blade economics offer the most penetrable product entry point. Go-to-market angle centers on subscription-based equipment access with embedded maintenance and telemedicine integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed veterinary device boutiques holding ISO 13485 certification but lacking integrated platform breadth. Five-to-ten year viability hinges on regulatory certification entrenchment and specialty practice consolidation tailwinds. Signal to watch: FDA 510(k) clearance velocity for robotic-assisted arthroscopy platforms as inflection indicator for technology substitution risk.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Quality management certification from TÜV SÜD or BSI unlocks EU MDR market access before technical file remediation deadlines. |
| Leasing Model Expansion | Per-procedure fee structures with embedded maintenance displace capital purchase barriers for independent orthopedic practices. |
| Precision Glass Supply Partnership | Captive rod-lens agreements with Schott AG or Hoya Corporation secure optical component allocation against supply concentration risk. |
| Telemedicine Platform Integration | Real-time video streaming to university teaching hospitals enables remote case consultation and resident training revenue streams. |
| Biodegradable Anchor Development | Absorbable polymer suture anchors command premium pricing in cruciate ligament repair procedures across companion animal specialties. |
Research Methodology
Desk research of FDA 510(k) premarket notification databases, EU MDR technical file registries, and veterinary surgical instrument trade publications preceded structured interviews with board-certified veterinary surgeons, specialty practice purchasing managers, biomedical engineers at referral hospitals, and equipment finance firm underwriters. Secondary validation drew from ISO certification body audit reports, German precision glass industry associations, and Japanese METI industrial statistics. Bottom-up procedure volume estimates triangulated against top-down capital equipment replacement cycle analysis.
Variance decomposition across device type, application setting, end-user scale, and technology tier anchored the analytical framework over the projection horizon. Segmentation dimensions modeled include scope diameter specifications, species-specific instrument compatibility, and regional regulatory cluster. CAGRs derived from installed base growth rates multiplied by per-procedure device utilization intensity. Forecast inputs incorporated veterinary surgeon residency pipeline constraints and 4K imaging platform substitution elasticity.
Underlying assumptions cover stable FDA 510(k) clearance timelines and sustained specialty practice consolidation, with deviation risk concentrated in EU MDR conformity assessment delays or optical component trade restrictions. Revision becomes warranted when integrated system vendor concentration crosses monopoly thresholds or when biodegradable anchor material failure rates trigger regulatory intervention.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Veterinary Stereotactic Radiosurgery System Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Elbow Fixators Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Japan Ultrasound Devices Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Personal-Use Facial and Skin Therapy Devices Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Single-Use Centrifuge System Market
Medical Devices
Cranial Orthoses Market
Medical Devices
Neurotech Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Global Urethral Dilator Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Submucosal Injections Market