
 Veterinary Respiratory Disease Treatment Market | 2026-2036
Veterinary Respiratory Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Respiratory Disease Treatment Market Analytics
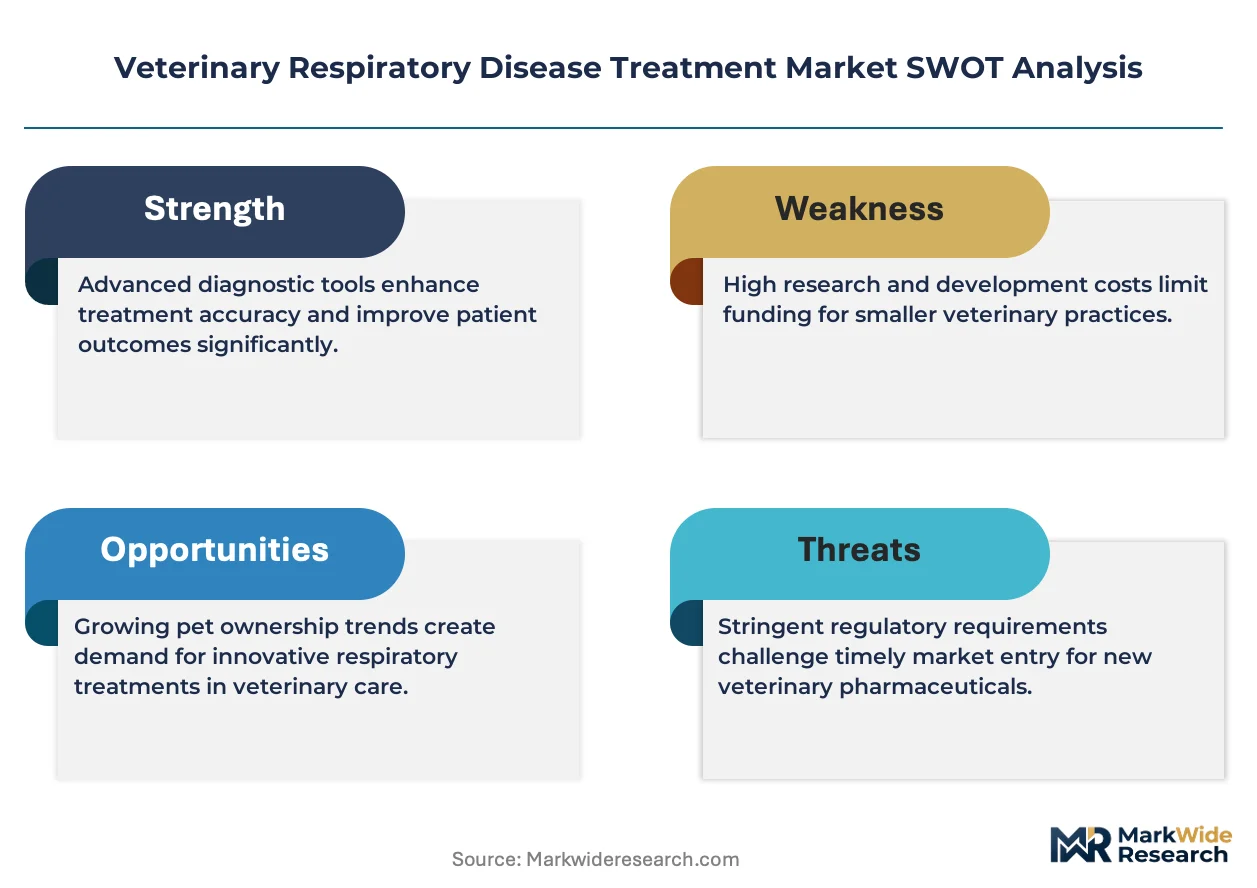
Veterinary pharmacology expertise is collapsing across rural practice networks, constraining proper diagnosis and targeted therapy deployment for complex respiratory conditions. Zoetis Inc. leverages its integrated diagnostics-to-pharmaceuticals platform to sustain clinical pull-through in companion animal respiratory care. Boehringer Ingelheim Animal Health anchors its position through vaccine-respiratory therapeutic bundling across livestock channels. Merck Animal Health differentiates via molecular diagnostic integration that positions antimicrobial selection upstream of treatment decisions.
Veterinary respiratory disease treatment encompasses pharmaceutical and biological interventions designed to manage infectious and inflammatory conditions affecting the upper and lower respiratory tracts of animals, with formulations typically requiring species-specific pharmacokinetic profiling and tissue penetration thresholds for lung parenchyma efficacy. Antibiotics dominate current product type revenue streams though corticosteroid demand accelerates in equine chronic obstructive pulmonary disease management where airway inflammation control determines performance outcomes. Injectable treatment modes command premium positioning in livestock operations due to mass administration efficiency, while intranasal delivery gains traction in feline upper respiratory protocols where patient compliance limits oral alternatives.
FDA Center for Veterinary Medicine oversight shapes antimicrobial approval pathways and residue monitoring requirements, directly influencing product development timelines and label claim scope for respiratory indications. EU REACH and EMA veterinary pharmacovigilance frameworks constrain excipient selection and environmental discharge parameters across European manufacturing and distribution networks. Stakeholders must monitor evolving regulatory divergence between FDA veterinary feed directive enforcement and EU antibiotic resistance reduction targets to align portfolio allocation with compliance-bound market access conditions.
Market Dynamics
Antimicrobial stewardship mandates from FDA veterinary feed directive guidelines are forcing livestock operations to reduce prophylactic antibiotic use, redirecting investment toward targeted diagnostics and vaccine-first protocols across companion animal and production animal channels.
Growth Catalysts
- Companion animal clinic consolidation:Corporate veterinary groups are standardizing respiratory diagnostic protocols across multi-site networks, creating pull-through demand for integrated testing platforms. This concentration accelerates adoption of molecular screening before therapeutic selection.
- EMA veterinary pharmacovigilance frameworks:Stricter environmental discharge monitoring in European manufacturing is pushing formulation innovation toward biodegradable excipients and reduced-residue actives, opening premium positioning for compliant suppliers.
- Intensive farming scaling in Brazil:Beef and poultry operation densification in Mato Grosso and Paraná is elevating respiratory disease incidence rates, driving therapeutic volume growth through mass administration protocols.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for veterinary macrolides and tetracyclines concentrates in Chinese chemical clusters, exposing formulators to export license volatility and geopolitical friction.
- Veterinary pharmacology expertise collapse:Rural practice networks face acute shortages of clinicians trained in species-specific pharmacokinetic profiling, constraining proper diagnosis and targeted therapy deployment for complex respiratory conditions.
- Regulatory divergence friction:Misalignment between FDA antimicrobial approval timelines and EU antibiotic resistance reduction targets forces parallel development tracks, extending product launch windows and inflating compliance costs.
Strategic Opportunities
- Intranasal delivery innovation:Feline upper respiratory protocols are shifting away from oral compliance-challenged administration toward intranasal formulations, creating white space for device-drug combination products.
- India livestock channel expansion:Dairy cooperative consolidation in Gujarat and Maharashtra is concentrating animal health procurement decisions, enabling direct therapeutic bundling with artificial insemination and nutrition services.
- Carbon credit alignment:EU Green Deal agricultural sustainability incentives are rewarding reduced-antibiotic production systems, positioning vaccine-respiratory therapeutic bundles for premium pricing in Dutch and Danish pork operations.
Industry Challenges
- Diagnostic-therapeutic integration complexity:Point-of-care molecular platforms require retraining of field veterinarians in nucleic acid test interpretation, slowing clinical adoption despite laboratory accuracy advantages.
- Residue monitoring compliance timelines:FDA Center for Veterinary Medicine withdrawal period validation studies demand extended field trials across multiple species, compressing effective patent life for new respiratory actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Respiratory Disease Treatment Market |
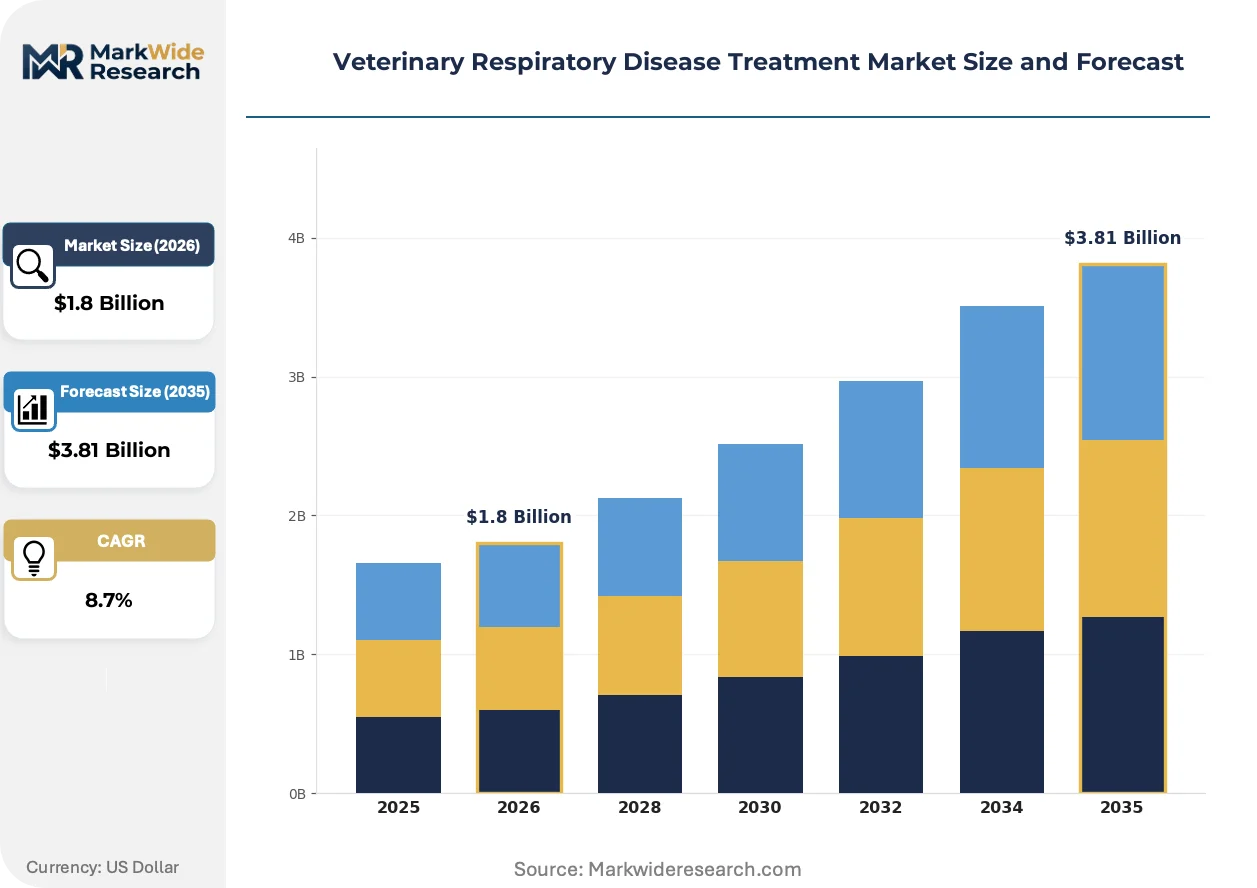
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Anti-inflammatories, Bronchodilators, Corticosteroids Treatment Mode: Topical, Injectable, Oral, Intranasal Animal Type: Dogs, Cats, Horses, Livestock Distribution Channel: Veterinary Clinics, Pharmacies, Online Retailers, Hospitals |
| Companies Covered | Zoetis Inc., Boehringer Ingelheim Animal Health, Merck Animal Health, Elanco Animal Health, Virbac S.A., Ceva Santé Animale, Vetoquinol S.A., Dechra Pharmaceuticals PLC, Phibro Animal Health Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Respiratory Disease Treatment Market Evolving Landscape
Respiratory disease management is pivoting from empirical antibiotic therapy toward precision-guided intervention, enabled by rapid diagnostics, alternative immunomodulators, and reconfigured procurement relationships between producers and animal health providers.
Polymerase chain reaction-based point-of-care platforms are displacing culture-based susceptibility testing in companion animal emergency settings. Urban specialty clinics are adopting these systems within eighteen-month procurement cycles. This acceleration is compressing the window between clinical presentation and pathogen-specific therapeutic selection, reducing empirical broad-spectrum antibiotic exposure.
EU REACH substance restriction amendments are tightening excipient approval pathways for inhalation formulations used in equine chronic obstructive pulmonary disease. Manufacturers must now submit extended environmental fate data for propellant alternatives. This regulatory pressure is most acute in German and French equine pharmaceutical markets, where reformulation investments are prioritizing dry powder inhaler technologies over metered-dose alternatives.
Consolidated livestock procurement groups are unbundling after-sales veterinary services from pharmaceutical supply contracts. Brazilian beef feedlot operators now source respiratory therapeutics through independent distributors while contracting diagnostic and treatment protocol design separately. This separation is most visible in São Paulo state cattle finishing operations, where direct manufacturer relationships are fragmenting into multi-vendor purchasing arrangements.
Veterinary Respiratory Disease Treatment Market Segmentation
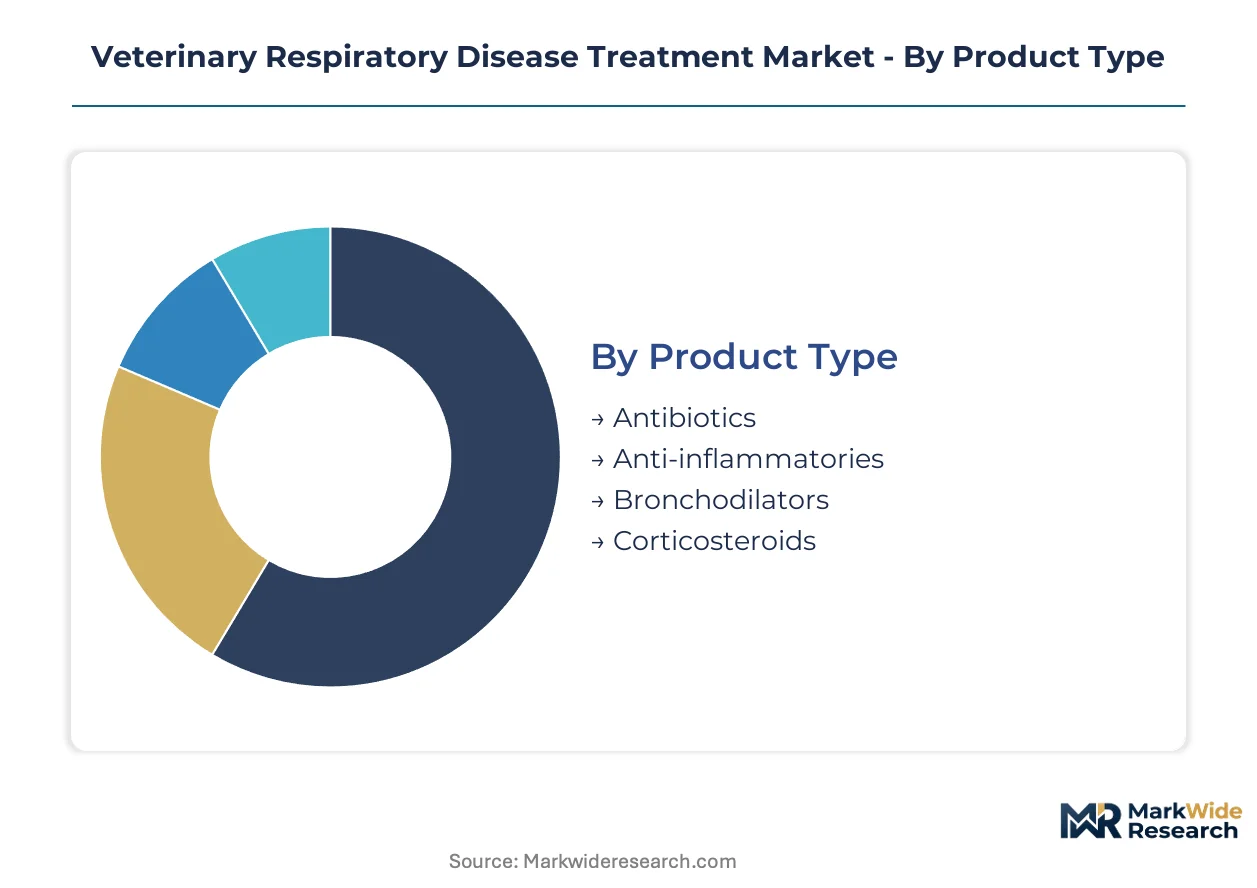
Respiratory therapeutics demand fragments across pharmacological classes, administration routes, species physiology, and procurement channels. Each segmentation axis carries distinct regulatory constraints and margin profiles that reshape portfolio allocation decisions for animal health suppliers.
Product Type:
FDA Center for Veterinary Medicine approval pathways and EU antibiotic resistance reduction targets create divergent commercial timelines for antimicrobial versus non-antimicrobial respiratory actives.
- Antibiotics:Macrolides and tetracyclines dominate livestock respiratory protocols where bacterial pneumonia drives therapeutic volume. FDA veterinary feed directive enforcement in US cattle feedlots is compressing prophylactic use, redirecting demand toward metaphylactic protocols with tighter diagnostic triggers.
- Corticosteroids:Dexamethasone and prednisolone formulations target equine chronic obstructive pulmonary disease where airway inflammation control determines racing and performance outcomes. German and French equine pharmaceutical markets prioritize dry powder inhaler delivery to satisfy EU REACH propellant restrictions.
- Anti-inflammatories:NSAID respiratory applications concentrate in companion animal emergency settings for fever reduction and comfort management during infectious episodes.
- Bronchodilators:Beta-agonist and methylxanthine formulations serve feline asthma and canine chronic bronchitis protocols where reversible airway obstruction requires maintenance therapy.
Antibiotics handle the majority of throughput; corticosteroids are expanding most quickly as precision diagnostics enable targeted anti-inflammatory protocols.
Treatment Mode:
Cost tier differentiation separates mass administration efficiency in livestock from compliance-driven innovation in companion animals.
- Injectable:Long-acting formulations command premium positioning in Brazilian beef feedlots and US dairy operations where labor constraints favor single-dose metaphylaxis. Mato Grosso cattle finishing operations source ceftiofur and tulathromycin injectables through independent distributors unbundled from veterinary service contracts.
- Intranasal:Feline upper respiratory protocols are shifting toward nasal delivery where patient compliance limits oral alternatives. Device-drug combination products for herpesvirus and calicivirus vaccination are creating white space for formulation specialists.
- Oral:Tablet and liquid formulations serve maintenance therapy in canine chronic bronchitis and feline asthma where owner-administered home care extends treatment duration.
- Topical:Transdermal and ophthalmic respiratory applications remain niche, concentrated in exotic species and avian medicine where systemic administration risks toxicity.
Injectable modes capture the highest value per dose; intranasal delivery is climbing the fastest as feline specialty clinics expand.
Animal Type:
Customer type concentration separates corporate veterinary group procurement from fragmented livestock producer decision-making.
- Livestock:Cattle, swine, and poultry respiratory disease drives therapeutic volume through mass administration protocols. Intensive farming scaling in Brazil, China, and India elevates incidence rates in confined feeding operations.
- Dogs:Corporate clinic networks standardize molecular diagnostic protocols before therapeutic selection, accelerating adoption of pathogen-specific antibiotics and reducing empirical broad-spectrum exposure.
- Cats:Upper respiratory complex from herpesvirus and calicivirus dominates feline therapeutic demand, with intranasal vaccine and antiviral protocols gaining traction in urban specialty practices.
- Horses:Equine chronic obstructive pulmonary disease management prioritizes corticosteroid and bronchodilator maintenance, with performance outcomes dictating premium formulation acceptance.
Livestock generates the highest absolute volume; dogs are gaining share fastest through diagnostic-therapeutic integration in consolidated clinic networks.
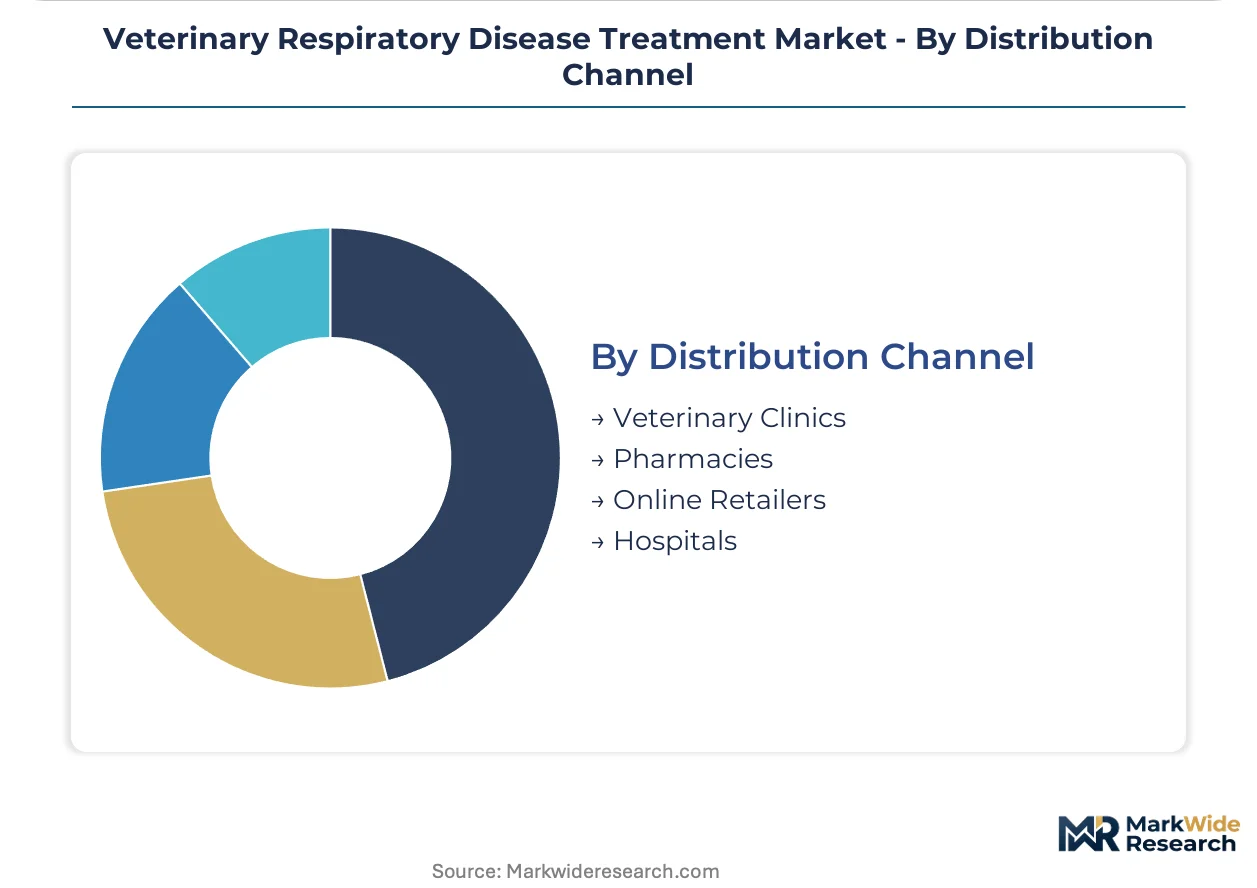
Distribution Channel:
Supply concentration in API manufacturing clusters shapes procurement risk profiles across channel types.
- Veterinary Clinics:Corporate group consolidation in the US and Western Europe standardizes formularies and diagnostic protocols, creating pull-through demand for integrated testing platforms and preferred therapeutic brands.
- Online Retailers:E-commerce penetration accelerates in companion animal maintenance therapies where prescription renewal and home delivery convenience override clinic visit requirements.
- Pharmacies:Human pharmacy chains with veterinary divisions capture overflow demand in markets with veterinary workforce shortages, though regulatory constraints limit controlled substance dispensing.
- Hospitals:Emergency and referral institutions concentrate advanced respiratory case management, driving demand for rapid diagnostics and intensive care therapeutics.
Veterinary clinics handle the majority of throughput; online retailers are expanding most quickly in chronic maintenance categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Center for Veterinary Medicine oversight shapes antimicrobial approval pathways in the United States, while EU REACH and EMA veterinary pharmacovigilance frameworks constrain manufacturing parameters across European networks. Stakeholders must navigate divergent regulatory timelines between these dominant geographies.
United States
Corporate veterinary group consolidation standardizes respiratory diagnostic protocols across multi-site networks. FDA veterinary feed directive enforcement compresses prophylactic antibiotic use in cattle feedlots, redirecting demand toward metaphylactic protocols. Urban specialty clinics in California and Texas accelerate adoption of molecular screening platforms before therapeutic selection.
Germany
EMA veterinary pharmacovigilance frameworks push formulation innovation toward biodegradable excipients and reduced-residue actives. EU REACH substance restriction amendments tighten excipient approval pathways for equine inhalation formulations. Pharmaceutical manufacturing clusters in Baden-Württemberg prioritize dry powder inhaler technologies over metered-dose alternatives to satisfy propellant restrictions.
Brazil
Beef and poultry operation densification in Mato Grosso and Paraná elevates respiratory disease incidence rates. ANVISA regulatory alignment with international antimicrobial stewardship standards shapes import licensing for veterinary macrolides. Feedlot operators in São Paulo state now source respiratory therapeutics through independent distributors unbundled from veterinary service contracts.
China
Intensive livestock farming scaling in Shandong and Henan provinces concentrates therapeutic demand for mass administration protocols. NMPA veterinary drug registration requirements extend approval timelines for new respiratory actives. Chemical manufacturing clusters in Jiangsu and Zhejiang supply active pharmaceutical ingredients for veterinary macrolides and tetracyclines, exposing formulators to export license volatility.
India
Dairy cooperative consolidation in Gujarat and Maharashtra concentrates animal health procurement decisions. CDSCO veterinary drug regulatory harmonization with international standards shapes import substitution strategies for respiratory therapeutics. Pharmaceutical manufacturing corridors in Telangana and Andhra Pradesh expand generic formulation capacity for export markets.
Veterinary Respiratory Disease Treatment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated diagnostics-to-pharmaceuticals platforms commanding premium positioning in companion animal channels. The specialist tier concentrates in species-specific formulation expertise and regional distribution networks. Three archetypes dominate: integrated animal health conglomerates with diagnostic arms, pure-play pharmaceutical specialists with veterinary divisions, and regional generic manufacturers with cost-optimized portfolios. Competitive moves center on vaccine-therapeutic bundling across livestock channels and molecular diagnostic integration upstream of treatment decisions.
Within the integrated conglomerate tier, Zoetis Inc. and Boehringer Ingelheim Animal Health exemplify platform consolidation, while Merck Animal Health anchors the diagnostic-therapeutic integration archetype. These entities occupy positions where clinical pull-through and upstream testing capabilities reinforce procurement relationships with corporate veterinary groups and consolidated livestock operations.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Boehringer Ingelheim Animal Health |
| Merck Animal Health |
| Elanco Animal Health |
| Virbac S.A. |
| Ceva Santé Animale |
| Vetoquinol S.A. |
| Dechra Pharmaceuticals PLC |
| Phibro Animal Health Corporation |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Jiangsu and Zhejiang chemical manufacturing clusters shapes both API availability and price floors for veterinary macrolides and tetracyclines, concentrating cost leverage among integrated formulators while fragmenting margin capture across downstream distributors.
Pricing Analysis
Brazil-to-Germany price spreads for long-acting ceftiofur injectables exceed threefold, reflecting divergent regulatory compliance costs and veterinary service bundling traditions. Three-tier pricing structure across premium, standard, and economy levels separates branded formulations with molecular diagnostic integration from generic alternatives and unlicensed imports. Pricing pressure stems from Brazilian feedlot operators unbundling pharmaceutical procurement from veterinary services. Corporate veterinary groups in the United States exhibit lowest price sensitivity due to standardized formularies and diagnostic platform lock-in.
Supply Chain Analysis
Strategic stockpiling of veterinary macrolide APIs dominates procurement behavior among European formulators anticipating REACH substance restriction amendments, while Brazilian distributors favor just-in-time replenishment from independent Chinese suppliers. Active pharmaceutical ingredient manufacturing concentrates in China, India, and Italy, with tetracycline fermentation capacity anchored in Shandong province and synthetic chemistry clusters distributed across Telangana and Lombardy. Formulation draws from gelatin capsule supplies, propellant alternatives for inhalation devices, and sterile injection packaging. Single-source vulnerability concentrates in Jiangsu province export license volatility. Distribution runs through veterinary clinics, independent distributors, and online retailers with diverging service bundling expectations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vaccine-first protocols and rapid point-of-care diagnostics threaten to displace empirical antibiotic therapy volumes, forcing incumbents to defend substitution-driven margin compression across livestock and companion animal channels.
For Market Incumbents: Fortify diagnostic-therapeutic integration through molecular platform lock-in with corporate veterinary groups and backward integration into API manufacturing to offset Chinese supply volatility. Boehringer Ingelheim's vaccine-respiratory therapeutic bundling model offers a template for margin defense against unbundled procurement trends in Brazilian feedlots. For New Entrants and Emerging Players: Device-drug combination gaps in feline intranasal delivery present white-space targets where patient compliance limitations and specialty clinic procurement concentration enable premium positioning. Target urban companion animal emergency settings in California and Texas where molecular screening adoption accelerates pathogen-specific therapeutic selection and displaces empirical protocols. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated diagnostics-to-pharmaceuticals platforms with corporate clinic network contracts, positioning these archetypes for sustained cash flow quality across veterinary workforce shortage environments. Acquisition priority rests on molecular diagnostic capabilities with regulatory clearance pathways and established pull-through relationships. Watch FDA veterinary feed directive enforcement intensity as inflection indicator for livestock therapeutic volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Platform Integration | Molecular screening lock-in with Zoetis and Merck corporate clinic networks accelerates pathogen-specific antibiotic selection. |
| API Manufacturing Backward Integration | In-house tetracycline fermentation capacity insulates formulators from Jiangsu export license volatility and geopolitical friction. |
| Intranasal Delivery Device Development | Feline herpesvirus-calicivirus combination products capture compliance-driven premium positioning in urban specialty practices. |
| Vaccine-Therapeutic Bundling Expansion | EU Green Deal carbon credit alignment enables premium pricing for reduced-antibiotic pork production systems in Dutch operations. |
| Regional Distribution Channel Diversification | Independent distributor relationships in São Paulo state feedlots fragment legacy manufacturer-veterinary service integration. |
Research Methodology
Cross-validation between veterinary pharmacology specialists and regulatory affairs executives anchors the qualitative findings, with secondary triangulation against FDA Center for Veterinary Medicine approval databases, EMA veterinary pharmacovigilance reports, and ANVISA import licensing records. Primary interviews encompassed companion animal clinic medical directors, livestock feedlot procurement managers, pharmaceutical formulation scientists, and molecular diagnostic platform engineers. Bottom-up therapeutic volume estimates from country-level species population data and top-down market sizing from manufacturer revenue disclosures were reconciled through iterative calibration.
Sensitivity analysis across antimicrobial stewardship enforcement scenarios and API supply disruption probabilities informs the projection framework. Segmentation dimensions modeled include pharmacological class, administration route, animal species, and procurement channel concentration across the analysis window. CAGRs derive from regression against historical therapeutic volume trajectories, adjusted for regulatory inflection points and diagnostic adoption curves. Forecast inputs incorporate veterinary workforce density projections and intensive farming scaling rates in Brazil, China, and India.
Underlying assumptions cover sustained FDA veterinary feed directive enforcement and EU REACH substance restriction progression, with deviation risk concentrated in Chinese API export policy shifts and veterinary pharmacology training pipeline recovery. Forecasts reflect these conditions without explicit probability weighting. Revision becomes warranted when diagnostic-therapeutic integration adoption crosses threshold penetration in corporate clinic networks or when livestock therapeutic procurement unbundling accelerates beyond Brazilian feedlot precedent.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary
US Companion Animal Diagnostics Market
Veterinary
Companion Animal Arthritis Market
Veterinary
Global Cattle Vaccines Market
Veterinary
Companion Animal Drugs Market
Veterinary
Foot and Mouth Disease (FMD) Vaccine Market
Veterinary
Global Companion Animal Specialty Drugs Market
Veterinary
Wearable Sensors for Animal Health Management Market
Veterinary
North America Veterinary Healthcare Market
Veterinary
Animal Antibiotics Market
Veterinary
Pet DNA Testing Market
Veterinary
Veterinary Anesthesia Drugs Market
Veterinary
Global Animal Model Market
Veterinary
Veterinary Ophthalmic Equipment Market
Veterinary
Asia-Pacific Veterinary Healthcare Market
Veterinary
Global Veterinary Infusion Pumps Market
Veterinary
Veterinary Intravenous (IV) Solutions Market