
 Emergency Telemedicine Services Market | 2026-2036
Emergency Telemedicine Services Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Telemedicine Services Market Analysis
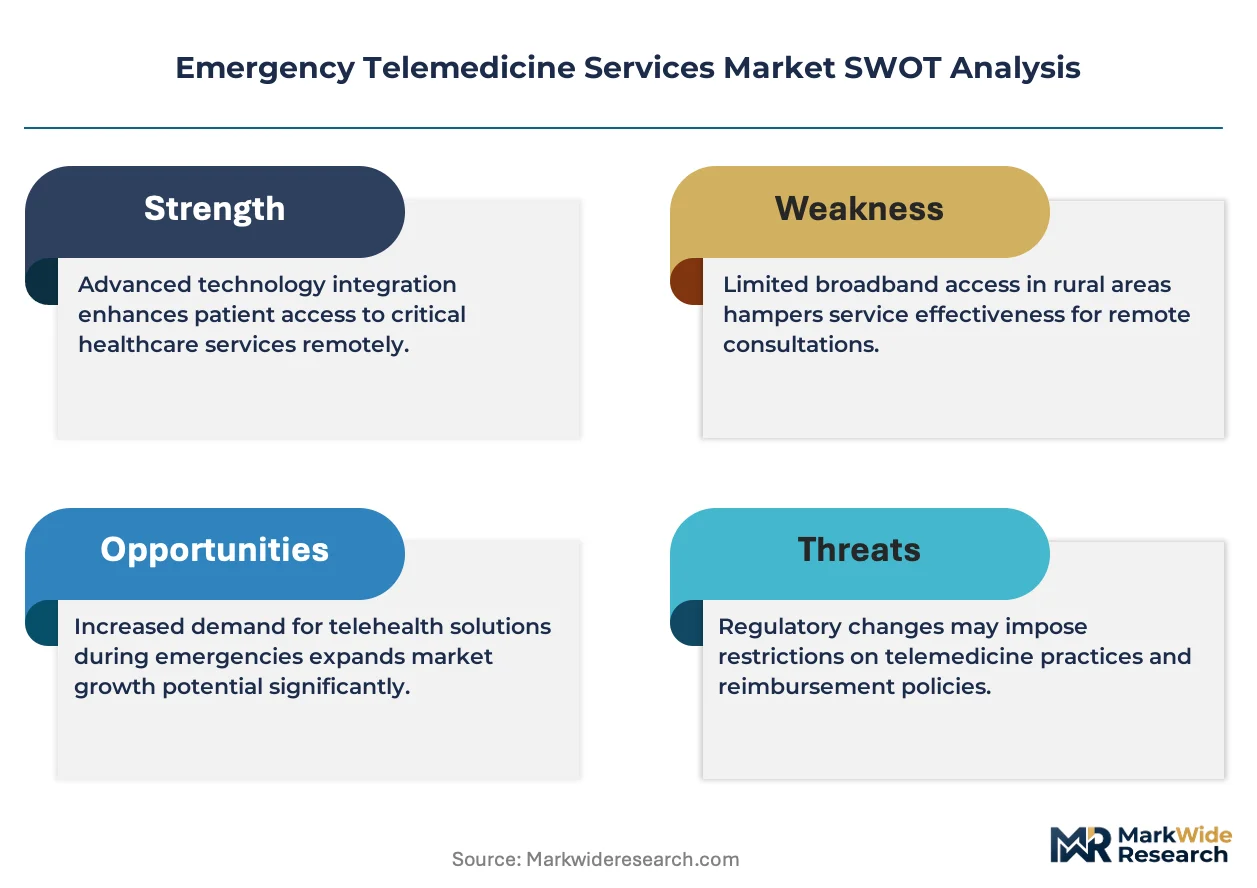
A capital-intensity divergence between full-stack platform operators and point-solution vendors is reorganizing competitive tiers in emergency telemedicine. Teladoc Health, Inc. sustains broad infrastructure investments across acute care triage and specialist networks. American Well Corporation leverages hospital system partnerships to anchor enterprise-scale deployments. SOC Telemed, Inc. dominates the dedicated emergency medicine niche with physician staffing models purpose-built for stroke and critical care consultations.
Emergency telemedicine services encompass real-time remote clinical assessment, diagnostic support, and treatment coordination for acute conditions delivered through synchronous audiovisual platforms with HIPAA-compliant encryption and sub-200-millisecond latency requirements. These systems enable emergency departments to access board-certified specialists during capacity surges or staffing gaps, reducing time-critical intervention delays. Mobile applications and video conferencing anchor current revenue pools, while wearable devices and remote sensors represent the fastest-expanding technology segment as biosignal integration enables pre-arrival vital streaming. Subscription services capture predictable enterprise budgets, though on-demand services retain margin advantages in disaster response and seasonal surge scenarios.
The FDA regulates diagnostic software outputs as medical devices under 21 CFR 820 quality system requirements, while CMS reimbursement policies determine commercial viability for hospital-based tele-emergency programs. State-level medical board licensing compacts such as the Interstate Medical Licensure Compact reduce physician deployment friction across jurisdictions. Stakeholders must monitor evolving DEA prescribing authority for controlled substances via telemedicine and the alignment of malpractice liability frameworks with remote care standards.
Market Dynamics
CMS reimbursement parity for telehealth emergency services has created sustainable payment infrastructure that restructures hospital procurement priorities and platform vendor business models across the United States.
Growth Catalysts
- Interstate Medical Licensure Compact:State-level medical board licensing compacts reduce physician deployment friction across jurisdictions, enabling rapid specialist mobilization during surge events.
- Rural hospital networks:These institutions seek 24/7 specialist coverage without maintaining full-time staff, creating predictable subscription demand for emergency telemedicine platforms.
- Wearable biosignal integration:Remote sensors and pre-arrival vital streaming compress intervention timelines and expand the addressable acute care continuum.
Market Restraints
- FDA software-as-medical-device enforcement:Diagnostic algorithm certification under 21 CFR 820 quality system requirements imposes capital-intensive compliance burdens on platform developers.
- Sub-200-millisecond latency infrastructure:HIPAA-compliant encryption with real-time audiovisual performance demands fiber-optic backbone investments that concentrate viable deployment geography.
- Malpractice liability framework misalignment:Remote care standards vary across state jurisdictions, creating coverage uncertainty that restrains physician participation rates.
Strategic Opportunities
- DEA prescribing authority expansion:Controlled substance telemedicine prescribing rule evolution presents regulatory tailwind for integrated emergency-to-discharge medication management.
- Disaster response on-demand services:Seasonal surge and catastrophe response scenarios retain margin advantages over subscription models through premium pricing structures.
- Stroke and critical care specialist networks:Purpose-built physician staffing models for time-critical conditions command premium positioning in enterprise hospital contracts.
Industry Challenges
- Board-certified emergency medicine specialist recruitment:Physician supply constraints in emergency medicine create talent acquisition bottlenecks for platform scaling.
- Legacy EHR integration complexity:Synchronous platform deployment requires API development and data architecture reconfiguration that extends implementation timelines.
- Cross-state licensing operational overhead:Maintaining current credentials across multiple compact and non-compact states consumes administrative bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Telemedicine Services Market |
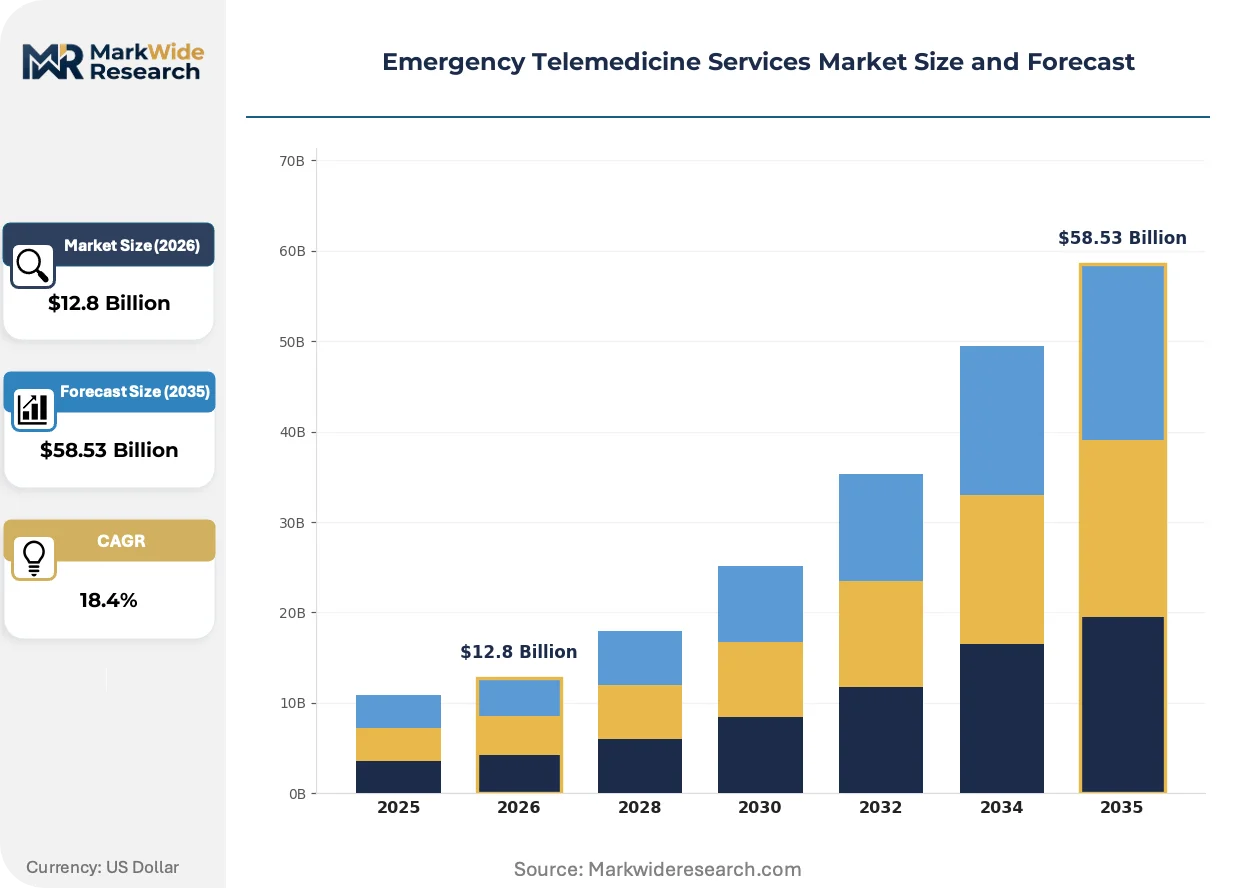
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $58.53 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Diagnosis, Monitoring, Emergency Response User Type: Patients, Healthcare Providers, Emergency Services, Health Insurance Companies Technology: Mobile Applications, Video Conferencing, Wearable Devices, Remote Sensors Delivery Model: On-Demand Services, Subscription Services, Pay-Per-Use, Bundled Packages |
| Companies Covered | Teladoc Health, Inc., American Well Corporation, MDLIVE Inc., Doctor On Demand, Inc., GlobalMed, Avel eCare, RelyMD, Tele911, SOC Telemed, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Telemedicine Services Market Emerging Trajectories
Platform architecture is splitting between full-stack infrastructure operators and modular point-solution vendors, with technology choices increasingly determining competitive tier access rather than clinical capability alone.
Artificial intelligence diagnostic support tools are bifurcating emergency telemedicine platform development. Machine learning algorithms triage chest pain and stroke presentations with radiology-grade confidence. Academic medical centers and integrated delivery networks adopt these tools at accelerated procurement cycles. The technology is bifurcating vendor tiers between FDA-cleared algorithm operators and legacy video-conferencing providers.
CMS telehealth reimbursement policy evolution continues reshaping commercial viability thresholds for hospital-based programs. The agency's site-neutral payment adjustments and originating site requirement modifications alter service line economics. Rural critical access hospitals and urban safety-net institutions face divergent incentive structures under these rules.
Enterprise procurement teams now unbundle emergency telemedicine contracts from broader telehealth master service agreements. Hospital systems negotiate standalone specialist network access with discrete service-level specifications for response time and physician credentialing. This pattern concentrates in multi-hospital systems across Texas, Florida, and Arizona where emergency department volume volatility exceeds staffing flexibility.
Emergency Telemedicine Services Market Segmentation
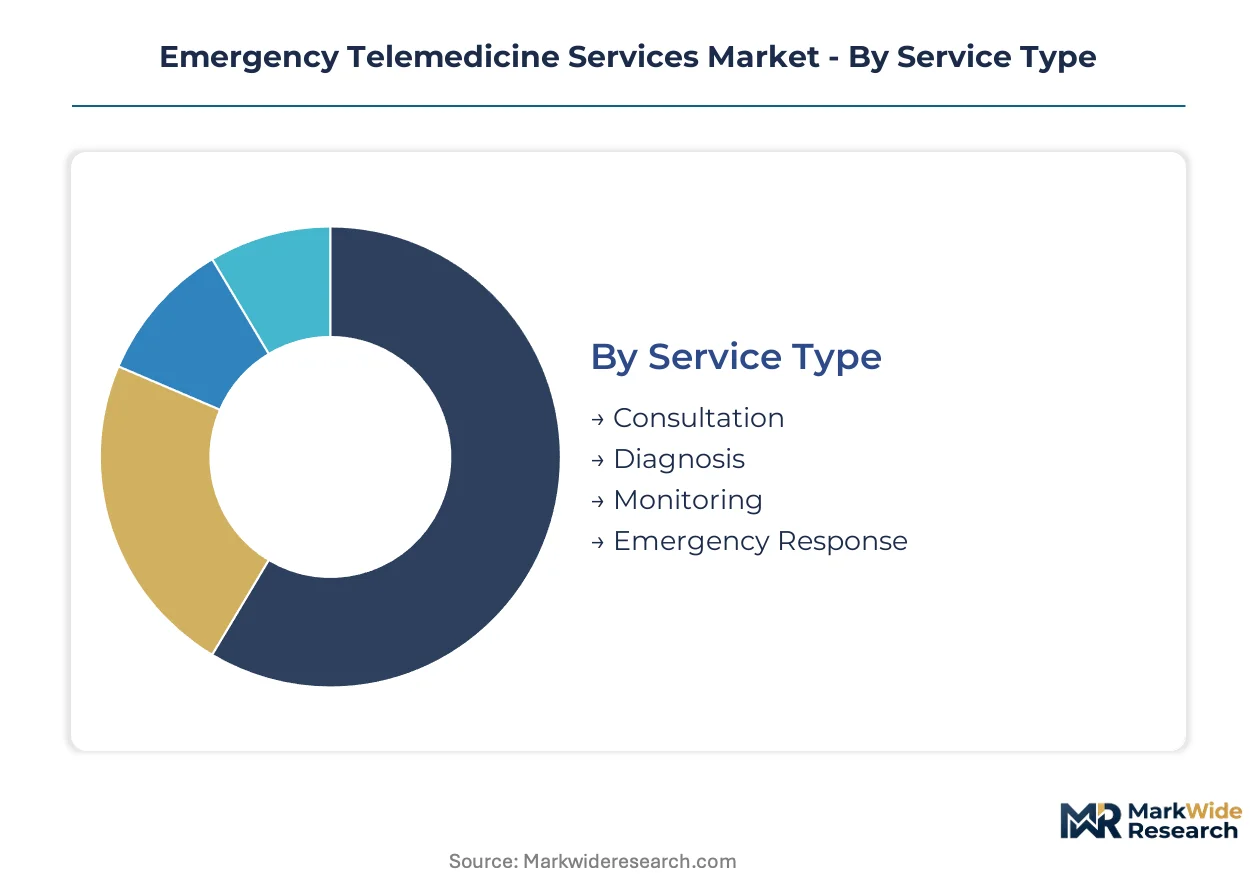
Emergency telemedicine platforms route distinct service types through divergent commercial channels. Subscription models anchor enterprise hospital procurement while on-demand activation captures disaster response premiums. Understanding segment-channel alignment reveals where platform vendors concentrate development resources versus where margin extraction peaks.
Service Type:
Consultation and diagnosis services flow predominantly through subscription contracts with hospital networks, while emergency response activation leverages on-demand pricing during surge events.
- Consultation:Real-time audiovisual connection between emergency department staff and remote specialists for clinical guidance during capacity constraints. Rural critical access hospitals in Texas and Florida concentrate procurement here as 24/7 specialist coverage without full-time employment becomes economically viable.
- Diagnosis:Remote clinical assessment incorporating patient history review, visual examination, and diagnostic algorithm support for acute presentations. Academic medical centers drive adoption as FDA-cleared AI triage tools for chest pain and stroke integrate into synchronous workflows.
- Monitoring:Continuous vital sign surveillance through connected devices with alert escalation protocols for deteriorating patients.
- Emergency Response:Pre-arrival clinical coordination and treatment initiation before physical patient presentation.
Consultation dominates installed base. Diagnosis is where expansion concentrates.
User Type:
Healthcare providers generate predictable recurring revenue through enterprise contracts while emergency services procurement spikes during seasonal demand cycles.
- Healthcare Providers:Hospital systems and physician groups purchasing specialist network access for emergency department coverage. Multi-hospital systems across Arizona negotiate standalone contracts with discrete service-level specifications for response time and physician credentialing.
- Emergency Services:Fire departments, EMS agencies, and disaster response teams activating telemedicine for field triage and transport coordination. Hurricane corridor states generate concentrated seasonal demand with premium pricing structures during catastrophe response.
- Patients:Individual consumers accessing emergency telemedicine through direct-to-consumer platforms or payer-sponsored programs.
- Health Insurance Companies:Payers integrating tele-emergency services into benefit design to reduce unnecessary emergency department utilization.
Healthcare providers anchor contract value. Emergency services represent the steepest expansion trajectory.
Technology:
Video conferencing infrastructure underpins current revenue pools while biosignal hardware integration commands premium positioning in next-generation procurement.
- Video Conferencing:HIPAA-compliant synchronous audiovisual platforms with sub-200-millisecond latency requirements and end-to-end encryption. Fiber-optic backbone investments constrain viable deployment geography to metropolitan corridors and hospital-dense regions.
- Wearable Devices:Continuous biosignal capture through consumer and clinical-grade sensors enabling pre-arrival vital streaming. Pre-hospital stroke networks and critical care transport programs drive fastest adoption as intervention timelines compress.
- Mobile Applications:Smartphone-based patient and provider interfaces for consultation initiation and clinical documentation.
- Remote Sensors:Fixed-location monitoring equipment deployed in ambulances, aircraft, and temporary medical facilities.
Video conferencing saturates current deployment. Wearable devices concentrate R&D investment.
Delivery Model:
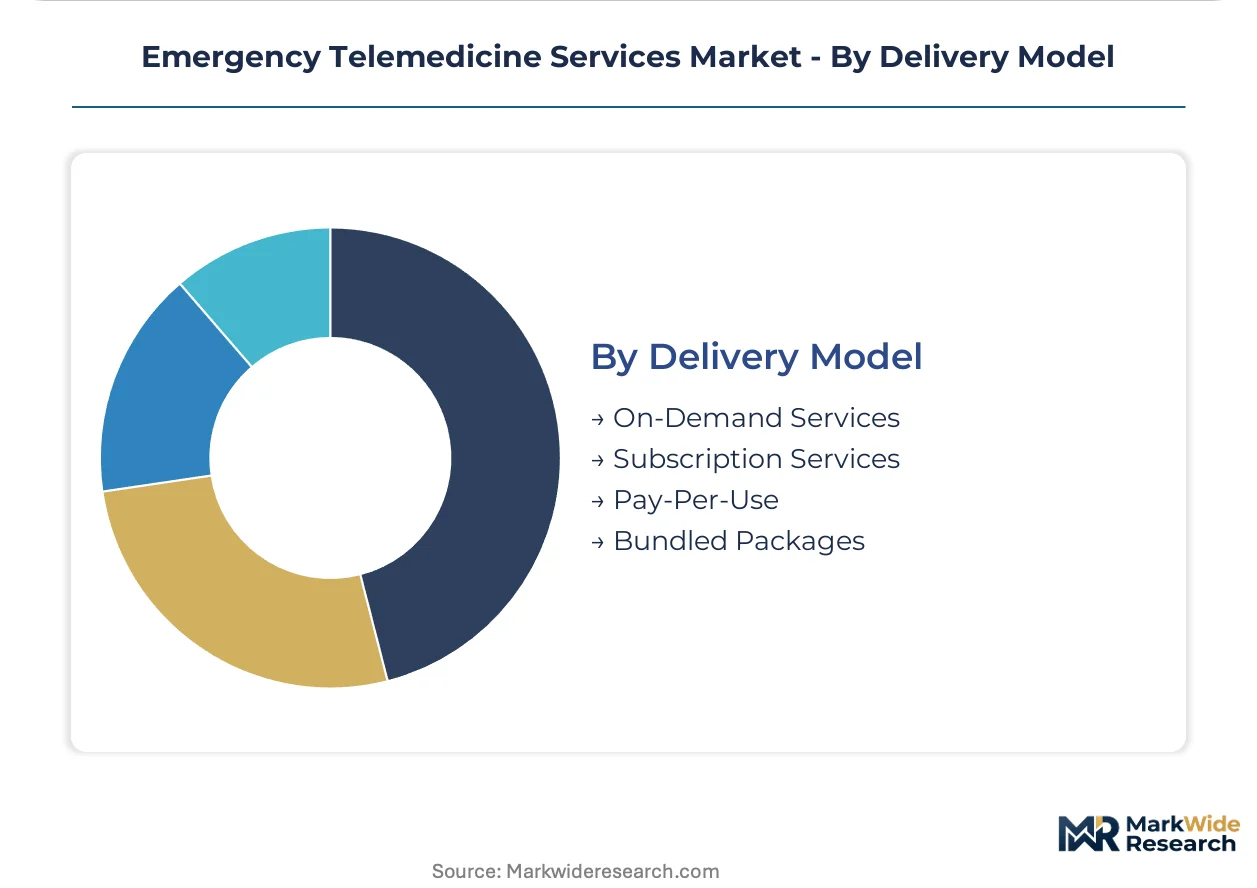
Subscription services capture predictable enterprise capital budgets while on-demand activation extracts margin premiums during capacity-constrained scenarios.
- Subscription Services:Fixed-fee contracts providing unlimited specialist access within defined service tiers and response time guarantees. Rural hospital networks generate concentrated demand as 24/7 coverage requirements meet staffing cost constraints.
- On-Demand Services:Per-activation pricing for emergency telemedicine access without ongoing commitment. Disaster response agencies and seasonal surge planning drive procurement with willingness-to-pay premiums exceeding 40% above subscription-equivalent rates.
- Pay-Per-Use:Transactional billing based on consultation duration or diagnostic complexity.
- Bundled Packages:Integrated offerings combining emergency telemedicine with adjacent virtual care services.
Subscription services dominate enterprise procurement. On-demand services capture highest per-transaction margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in emergency telemedicine concentrates in the United States, where CMS reimbursement parity sustains premium contract structures, while European markets operate under tighter cost-containment frameworks that compress vendor margins.
United States
CMS reimbursement parity for telehealth emergency services has created sustainable payment infrastructure that restructures hospital procurement priorities across Texas, Florida, and Arizona. The FDA enforces software-as-medical-device guidelines under 21 CFR 820 quality system requirements, reshaping platform certification demands. Rural critical access hospitals in the Southeast generate concentrated demand as 24/7 specialist coverage without full-time staffing becomes economically viable.
Germany
The EMA's Medical Device Regulation framework governs diagnostic algorithm certification, creating compliance thresholds that favor established platform operators over point-solution vendors. Germany's hospital digitization funding programs accelerate enterprise telemedicine procurement. Academic medical centers in Bavaria and North Rhine-Westphalia drive adoption of AI-integrated emergency consultation workflows.
United Kingdom
NHS England's integrated care system reforms consolidate emergency telemedicine purchasing across regional hospital networks. The MHRA regulates software-as-medical-device outputs under UKCA marking requirements post-Brexit. London's tertiary hospital clusters anchor specialist network development, while rural NHS trusts in Scotland and Wales expand remote consultation coverage.
Canada
Health Canada's regulatory alignment with FDA software-as-medical-device precedents streamlines cross-border platform certification for US vendors. Provincial health authority procurement varies, with Ontario and British Columbia leading enterprise tele-emergency deployments. Remote northern communities drive demand for pre-arrival vital streaming and critical care transport coordination.
Australia
The TGA's software-based medical device framework imposes quality system requirements on diagnostic algorithm platforms. Medicare reimbursement for telehealth emergency services expanded during recent health system stress periods. Metropolitan hospital networks in New South Wales and Victoria anchor specialist network contracts, while rural and remote health services drive wearable biosignal integration.
Emergency Telemedicine Services Market Vendor Landscape
Concentration sits with full-stack platform operators that sustain broad infrastructure investments across acute care triage and specialist networks. The vendor base splits between enterprise-scale hospital system partners and dedicated emergency medicine specialists with purpose-built physician staffing models. Three archetypes dominate: diversified telehealth conglomerates, emergency-focused niche operators, and technology-integrated service platforms. M&A activity concentrates on specialist network acquisitions, while strategic partnerships anchor enterprise-scale deployment capacity.
Within the emergency-focused tier, SOC Telemed, Inc. exemplifies purpose-built physician staffing models for stroke and critical care consultations. Teladoc Health, Inc. and American Well Corporation occupy positions as diversified platform operators with hospital system anchoring capabilities. These three companies represent the competitive spectrum from dedicated emergency medicine specialization to broad telehealth infrastructure.
| Leading Market Players |
|---|
| Teladoc Health, Inc. |
| American Well Corporation |
| MDLIVE Inc. |
| Doctor On Demand, Inc. |
| GlobalMed |
| Avel eCare |
| RelyMD |
| Tele911 |
| SOC Telemed, Inc. |
| Others |
Supply Flow & Price Mechanics
Subscription-based capacity reservation contracts lock rural hospital networks into multi-year specialist access agreements while simultaneously fixing cost visibility against CMS reimbursement parity benchmarks. This structure concentrates pricing power with platform operators that maintain interstate physician licensure compacts and FDA-cleared diagnostic algorithms.
Pricing Analysis
The customization-premium spread separates standard subscription tiers from configured enterprise deployments with dedicated response-time guarantees and bespoke EHR integration. Pricing stratifies across premium, standard, and economy tiers based on specialist credentialing depth and AI diagnostic tool inclusion. Cost compression in the standard tier is intensifying as point-solution vendors compete on video-conferencing infrastructure alone. Rural critical access hospitals exhibit highest price sensitivity, while academic medical centers prioritize certification grade over unit cost.
Supply Chain Analysis
The United States anchors physician specialist network provisioning, while India and the Philippines concentrate clinical support staffing for documentation and care coordination. Platform development draws from cloud infrastructure providers, HIPAA-compliant encryption vendors, and wearable biosignal hardware manufacturers. Single-source vulnerability concentrates in fiber-optic backbone providers serving sub-200-millisecond latency requirements. Distribution runs through direct enterprise sales teams targeting hospital procurement committees and GPO contract vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency telemedicine operates as a defensive-moat market where regulatory entrenchment through FDA software-as-medical-device certification creates substantial switching costs for hospital customers.
For Market Incumbents: Consolidate specialist network density across stroke and critical care verticals to outflank point-solution vendors lacking physician staffing depth. Pursue backward integration into wearable biosignal hardware to capture pre-arrival vital streaming revenue streams. Defend against emerging AI-native diagnostic entrants by accelerating FDA 510(k) clearances for machine learning triage tools. For New Entrants and Emerging Players: Anchor in emergency services procurement channels serving hurricane corridor states and disaster response agencies where on-demand premium pricing exceeds standard subscription rates. Target fire departments and EMS agencies with field-triage mobile applications as the most penetrable white-space segment. Deploy through state-level emergency management authority contracts rather than hospital procurement committees. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors purpose-built emergency medicine specialists over diversified telehealth conglomerates. Long-term viability rests on physician network scale and regulatory certification depth rather than technology platform differentiation. Monitor DEA prescribing authority rulemaking as the critical inflection signal for integrated medication management revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clears diagnostic algorithm deployment for chest pain and stroke triage workflows. |
| Hospital System Partnership | Anchors enterprise-scale deployment through multi-year specialist network access contracts. |
| Interstate Licensure Expansion | Reduces physician deployment friction across Texas, Florida, and Arizona surge corridors. |
| Software Companion Development | Integrates pre-arrival vital streaming from wearable biosignal devices into synchronous platforms. |
| Reimbursement Strategy | Aligns platform pricing with CMS site-neutral payment adjustments and originating site requirements. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with emergency department directors, telemedicine platform executives, hospital procurement managers, and CMS policy specialists. Secondary validation incorporated FDA 510(k) device filings, CMS Medicare claims data, Interstate Medical Licensure Compact participation records, and GPO contract databases. Bottom-up sizing of hospital system deployments was triangulated against top-down analysis of CMS reimbursement expenditure patterns.
Across the analysis window, the forecasting framework modeled service type segmentation, delivery model bifurcation, technology adoption curves, and user-type procurement behavior. CAGRs were derived from trend extrapolation of rural hospital network subscription growth and wearable biosignal integration velocity. Inputs included physician supply constraints, fiber-optic infrastructure expansion maps, and state-level medical board licensing compact adoption trajectories.
Material uncertainties — regulatory reversals in DEA prescribing authority, CMS reimbursement parity adjustments, and FDA diagnostic algorithm enforcement intensity — sit outside the modeled envelope. Forecasts reflect assumptions about sustained rural hospital network consolidation and uninterrupted interstate licensure compact expansion. Recalibration cycles align with material shifts in CMS rulemaking and FDA quality system guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telehealth and Telemedicine Market
Telemedicine
Telemedicine Technologies Market
Telemedicine
United States Telehealth Postpartum Services Market
Telemedicine
North America and Europe Ehealth Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
Europe Telehealth Service Market
Telemedicine
US Telehealth Market
Telemedicine
Tele-Care Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
In-Flight Telemedicine System Market
Telemedicine
Tele-ICU Services Market
Telemedicine
Global Virtual Care Market