
 Colposcopes Market | 2026-2036
Colposcopes Market Size, Share, and Industry Trends Forecast 2026-2036
Colposcopes Market Intelligence
The gap between premium digital colposcopes and basic optical units is expanding in measurable ways. Carl Zeiss AG leverages its optical heritage to sustain pricing power in high-resolution imaging systems. CooperSurgical, Inc. competes through integrated biopsy guidance platforms that anchor its position in hospital gynecology suites. Olympus Corporation differentiates via endoscopy-adjacent channel control, extending its reach into diagnostic centers that already stock its visualization stack.
A colposcope is a magnified optical instrument designed for direct examination of the cervix, vagina, and vulva, typically employing binocular optics with 4x to 40x magnification and integrated LED or halogen illumination to detect precancerous lesions. Digital colposcopes now dominate capital procurement budgets as hospitals replace aging optical fleets, while portable and handheld delivery modes capture fastest growth in point-of-care and mobile screening outreach where infrastructure constraints favor lighter equipment. Video colposcopes occupy a narrowing mid-tier niche as customers either upgrade to full digital pathology integration or downgrade to cost-optimized portable units.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines and market access costs for manufacturers serving regulated jurisdictions. Japan's PMDA and Germany's BfArM impose additional clinical evidence requirements that filter out smaller entrants and concentrate approvals among established players with dedicated regulatory affairs capacity. Stakeholders must monitor reimbursement code consolidation for office-based cervical screening, as payment policy shifts will determine whether digital upgrade cycles accelerate or stall across outpatient settings.
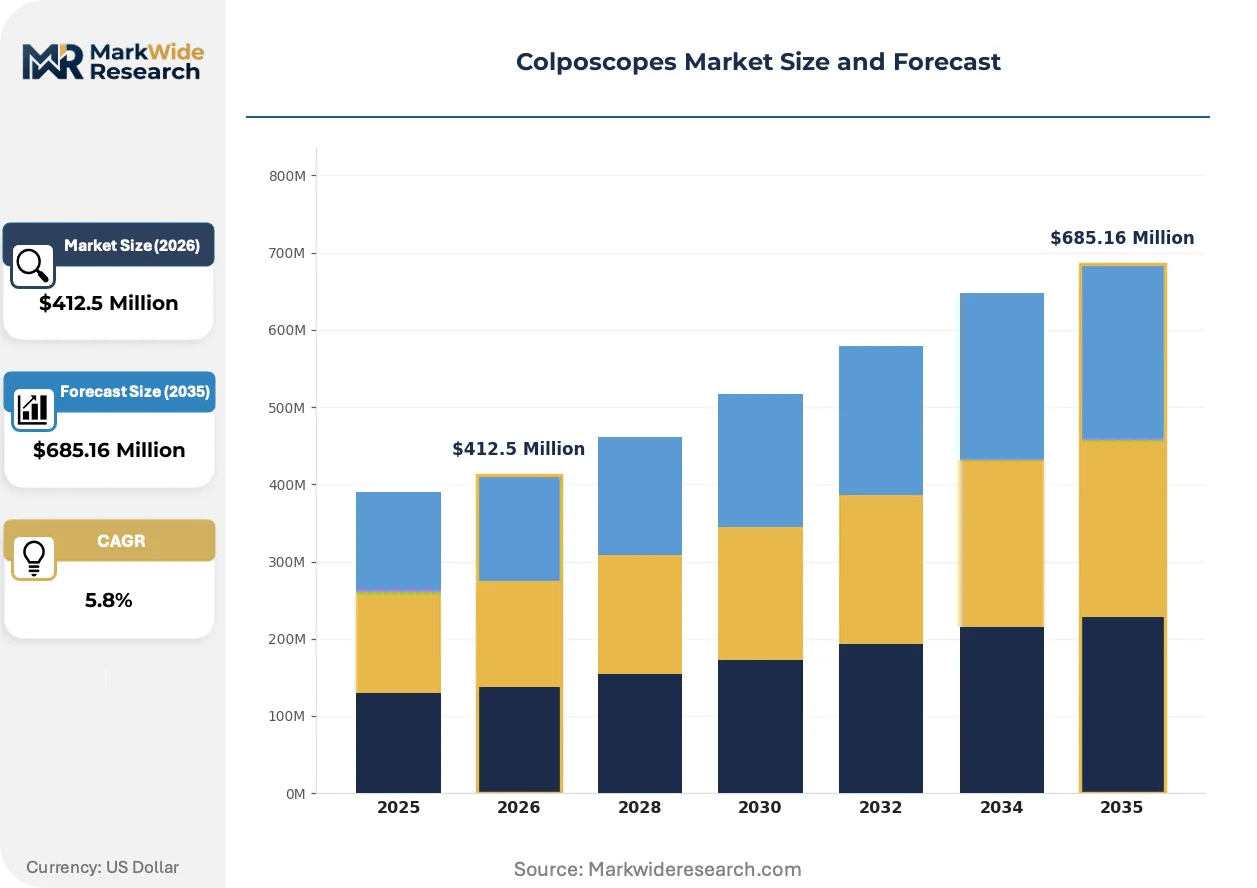
Market Dynamics
Digital pathology integration is compressing replacement cycles for optical colposcope fleets as hospital outpatient departments face simultaneous pressure from FDA 510(k) clearance timelines and EU MDR recertification deadlines. Procurement committees now weight interoperability with PACS networks above standalone imaging performance.
Growth Catalysts
- Cervical cancer screening mandates:Statutory reimbursement programs in Germany, the United States, and Japan lock in predictable demand for diagnostic equipment upgrades. National health service contracts specify digital imaging compatibility.
- EU MDR Article 120 transition:Legacy device recertification deadlines accelerate capital refresh decisions among European hospital systems. Manufacturers with notified body relationships capture displaced volumes.
- Point-of-care delivery models:Mobile screening outreach programs in rural India and sub-Saharan Africa generate pull for handheld battery-powered units. Infrastructure constraints favor lightweight optical designs over tethered systems.
Market Restraints
- Optical component supply concentration:High-resolution sensor fabrication concentrates in South Korean and Japanese foundries. Geopolitical friction disrupts lead times for 4K imaging modules.
- EU MDR clinical evidence requirements:Expanded post-market surveillance obligations inflate regulatory affairs overhead. Smaller manufacturers lack dedicated compliance teams to navigate notified body backlogs.
- Optical colposcope residual utility:Basic binocular systems satisfy screening protocols in price-sensitive public health programs. Digital upgrade ROI remains unproven in low-volume settings.
Strategic Opportunities
- AI-assisted lesion detection:Machine learning algorithms trained on annotated cervical image libraries are expanding into biopsy guidance workflows. Regulatory sandbox programs in Singapore and the United Kingdom accelerate validation timelines.
- Telemedicine integration:Cloud-connected colposcopes enable remote specialist consultation for community health centers. Brazil's SUS program pilots store-and-forward screening in Amazon basin municipalities.
- US Preventive Services Task Force grade revisions:Updated cervical cancer screening recommendations expand eligible patient populations. Federally qualified health centers access HRSA equipment grants for digital upgrade programs.
Industry Challenges
- Biomedical engineer scarcity:Specialized expertise in optical-mechanical integration for gynecologic instruments concentrates in German and Japanese industrial clusters. Recruitment pipelines fail to match product development timelines.
- PACS interoperability certification:DICOM conformance testing for hospital IT networks extends product launch schedules. Vendor-neutral archive compatibility requires iterative firmware revisions.
- Legacy fleet maintenance obligations:End-of-life support commitments for halogen-illuminated systems strain service organization capacity. Spare part inventory management consumes working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colposcopes Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Colposcopes, Optical Colposcopes, Video Colposcopes, Portable Colposcopes Technology: LED, Halogen, Fluorescent, Infrared End User: Hospitals, Clinics, Research Labs, Diagnostic Centers Delivery Mode: Handheld, Tabletop, Mobile Units, Integrated Systems |
| Companies Covered | Carl Zeiss AG, CooperSurgical, Inc., Olympus Corporation, Karl Kaps GmbH & Co. KG, Danaher Corporation, McKesson Corporation, DYSIS Medical Inc., MedGyn Products Inc., ATMOS MedizinTechnik GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colposcopes Market Strategic Shifts & Innovations
Workflow digitization is redefining competitive advantage around software integration rather than optical performance alone. Three developments are compressing product lifecycles and reshaping vendor-customer relationships.
Confocal microendoscopy is expanding into cervical margin assessment applications. Gynecologic oncology departments at tertiary centers in the United States and Germany pilot intraoperative use for excision boundary verification. The technology is expanding into reimbursement negotiations as pathologists demand cellular-level resolution for high-grade lesion management.
Japan's PMDA revised its medical device software guidance in 2023, imposing standalone validation requirements for AI-enabled diagnostic functions. Manufacturers must submit algorithm training datasets and performance benchmarks separate from hardware submissions. Digital colposcope vendors with SaMD components face extended review timelines that favor established players with Tokyo-based regulatory subsidiaries.
Hospital procurement committees now unbundle service contracts from capital equipment purchases, driving 30% shorter replacement cycles. Third-party ISO 13485-certified service providers in Texas and Bavaria capture maintenance revenue previously captive to original manufacturers. The shift is most visible in United States IDN consolidations where centralized biomed departments standardize across multiple acute care sites.
Colposcopes Market Segmentation
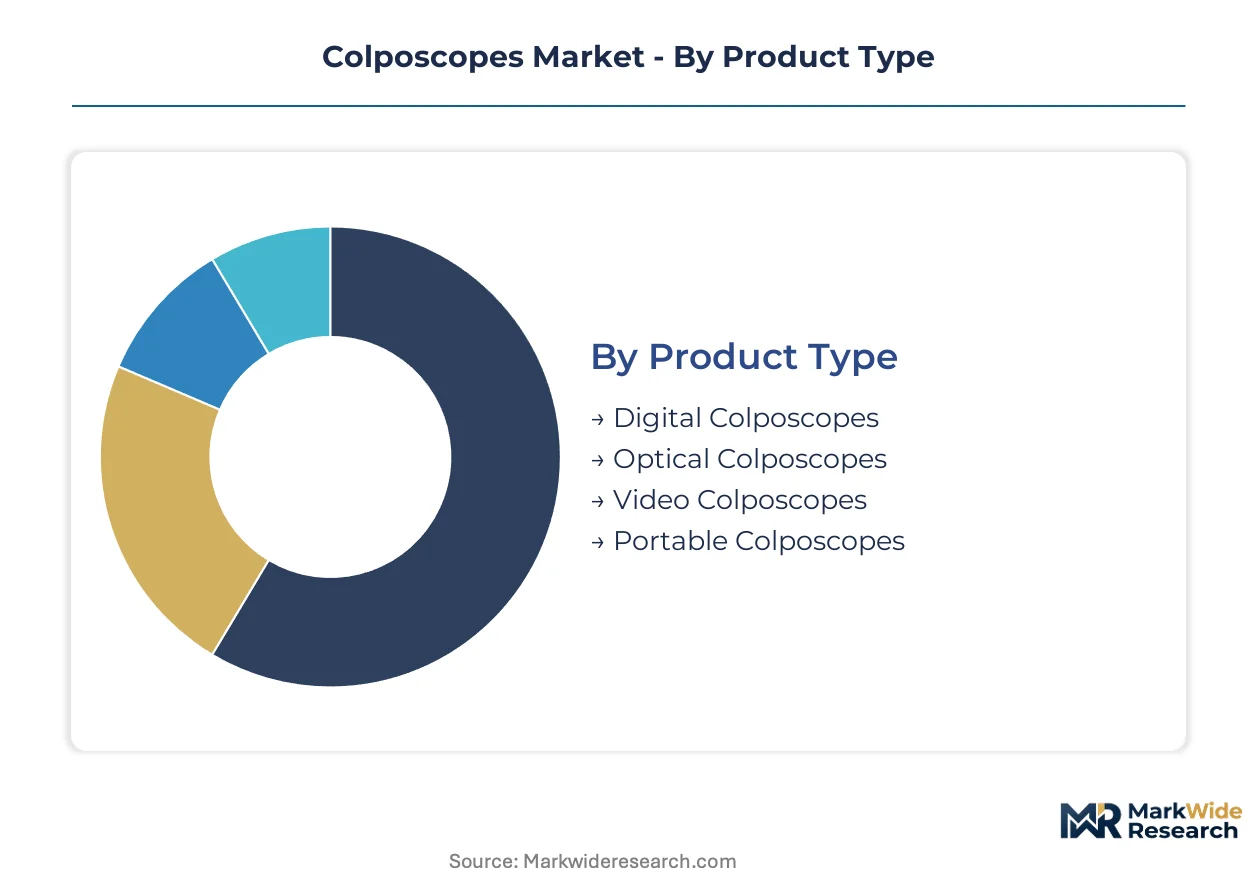
Colposcope procurement patterns diverge sharply between capital-intensive hospital systems and resource-constrained outreach programs. Segmentation reveals where optical heritage commands premium pricing versus where portability unlocks access expansion.
Product Type:
Volume concentrates in cost-optimized optical units for public health screening, while premium flows to digital systems with PACS integration.
- Digital Colposcopes:Full-image capture systems with CMOS or CCD sensors enabling direct electronic storage, annotation, and telemedicine transmission. Hospital outpatient departments in Germany and the United States prioritize these for cervical cancer screening program compliance and electronic health record integration.
- Optical Colposcopes:Binocular microscope-based instruments with 4x to 40x magnification ranges and halogen or LED illumination. Basic units satisfy statutory screening protocols in price-sensitive markets where reimbursement rates favor equipment amortization over diagnostic precision.
- Video Colposcopes:Hybrid systems combining optical magnification with analog or early digital video output for documentation. These occupy narrowing procurement niches as customers either upgrade to full digital pathology integration or downgrade to portable alternatives.
- Portable Colposcopes:Battery-powered, lightweight designs optimized for mobile screening units and point-of-care deployment. Infrastructure constraints in rural India and sub-Saharan Africa drive fastest expansion for handheld battery-powered configurations.
Mature deployment sits with optical colposcopes in established screening programs. Newer deployment is concentrated in portable colposcopes for outreach expansion.
Technology:
Illumination source selection tracks directly to image quality requirements and maintenance cost tolerance across end-use settings.
- LED:Solid-state illumination with 50,000-hour operational lifespans, minimal heat generation, and adjustable color temperature for tissue contrast optimization. Hospital procurement committees specify LED for reduced service contract costs and improved clinician comfort during extended examinations.
- Halogen:Traditional tungsten-halogen bulb technology delivering continuous spectrum illumination familiar to experienced colposcopists. Residual demand persists in training institutions and budget-constrained public health systems where bulb replacement costs are acceptable trade-offs.
- Fluorescent:Mercury vapor-based excitation sources for photodynamic diagnosis applications. Specialized gynecologic oncology departments employ these for acetic acid or iodine contrast enhancement protocols.
- Infrared:Near-infrared illumination systems for subsurface vascular pattern visualization. Research institutions in Japan and Germany pilot these for early neovascularization detection beyond visible spectrum capabilities.
LED technology dominates new capital procurement. Infrared remains confined to research validation.
End User:
Customer type determines equipment specification, service contract structure, and upgrade cycle frequency.
- Hospitals:Acute care systems with dedicated gynecology departments and outpatient surgical suites. These facilities demand digital pathology integration, PACS interoperability, and comprehensive service agreements covering multiple sites.
- Clinics:Community-based and private practice settings with lower patient volumes and capital budgets. Cost-optimized optical or entry-level digital units predominate where screening volume does not justify premium imaging investment.
- Research Labs:Academic medical centers and contract research organizations conducting cervical cancer screening trials or device validation studies. These users prioritize image capture fidelity, measurement calibration, and regulatory documentation support.
- Diagnostic Centers:Independent imaging facilities and women's health specialty centers performing high-throughput screening. Workflow efficiency and rapid patient turnaround drive preference for streamlined digital systems with automated image management.
Diagnostic centers are expanding most quickly with centralized screening models. Research labs maintain stable replacement cycles tied to grant funding.
Delivery Mode:
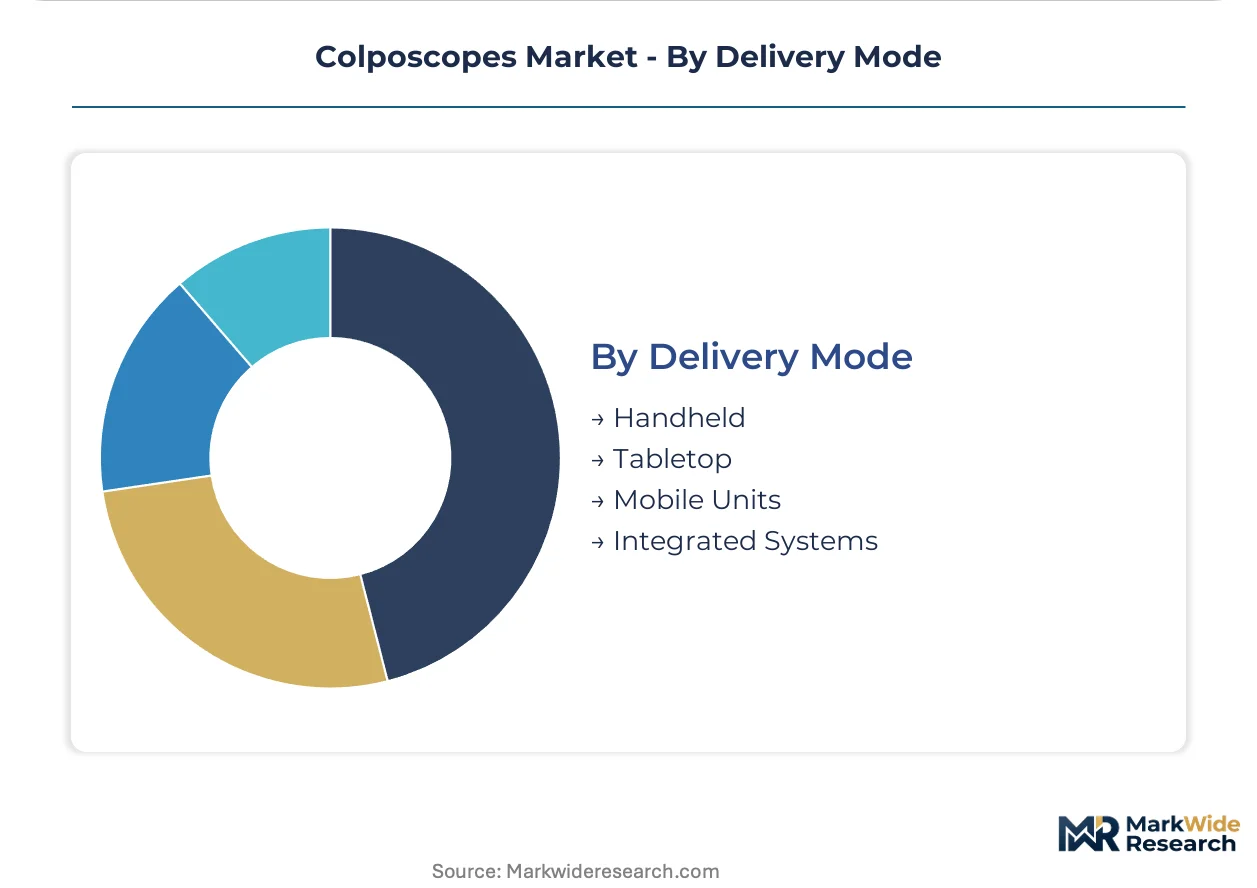
Physical configuration determines deployment flexibility, sterilization protocols, and total cost of ownership calculations.
- Handheld:Compact, pistol-grip or smartphone-integrated designs for examination table-side use. Mobile screening programs in Brazil's Amazon basin municipalities and rural India deploy these for physician-extender examinations with remote specialist consultation.
- Tabletop:Fixed-position instruments with articulating arms and stable bases for dedicated examination rooms. Standard configuration for hospital gynecology suites where procedure volume justifies permanent installation.
- Mobile Units:Vehicle-mounted or transportable screening systems with self-contained power and climate control. National health service contracts in Germany specify these for rural population coverage requirements.
- Integrated Systems:Colposcope-biopsy guidance combinations with co-registered imaging and instrument tracking. Tertiary oncology centers in the United States adopt these for complex lesion management and resident training.
Tabletop systems anchor hospital infrastructure. Handheld configurations are climbing the fastest with telemedicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tübingen anchors optical instrument manufacturing heritage that radiates across German cervical cancer screening infrastructure. Hospital procurement committees in Stuttgart and Munich specify digital colposcope compatibility with national health service contracts.
United States
Federally qualified health centers drive equipment upgrade demand through HRSA capital grants. FDA 510(k) clearance timelines compress product refresh cycles for manufacturers serving hospital outpatient departments. Boston's academic medical corridor pilots AI-assisted biopsy guidance integration with tertiary gynecologic oncology workflows.
Germany
BfArM clinical evidence requirements filter market access toward established regulatory affairs capacity. EU MDR Article 120 recertification deadlines accelerate replacement decisions across hospital systems. The Stuttgart industrial cluster concentrates precision optical fabrication for high-resolution imaging modules.
Japan
PMDA medical device software guidance imposes standalone validation requirements for AI-enabled diagnostic functions. National health insurance reimbursement codes lock in predictable demand for screening equipment upgrades. Nagoya's precision manufacturing base supplies LED illumination components with 50,000-hour operational lifespans.
India
Mobile screening outreach programs in rural Maharashtra and Karnataka generate pull for handheld battery-powered configurations. CDSCO medical device rules classify colposcopes based on intended use and risk classification. Tamil Nadu's medical device manufacturing corridor scales production of cost-optimized portable units for public health procurement.
Brazil
SUS program pilots store-and-forward telemedicine screening in Amazon basin municipalities where specialist access remains constrained. ANVISA medical device registration requirements shape import timelines for digital systems. São Paulo's diagnostic center concentration anchors private-sector demand for workflow-integrated imaging platforms.
Colposcopes Market Key Industry Players
Premium-margin players sit above commodity-margin players across optical heritage and software integration capabilities. The vendor base stratifies into three tiers: established optical instrument houses with century-scale precision manufacturing expertise, integrated women's health platforms with biopsy guidance ecosystems, and regional fabricators serving price-sensitive public health tenders. Dominant competitive moves include portfolio diversification into AI-assisted diagnostic software and strategic partnerships with telemedicine infrastructure providers.
Within the precision optics tier, Carl Zeiss AG and Karl Kaps GmbH & Co. KG anchor German engineering heritage that commands pricing power in high-resolution imaging systems. Olympus Corporation exemplifies endoscopy-adjacent channel control, extending reach into diagnostic centers that already stock visualization stacks. CooperSurgical, Inc. occupies a position among integrated platform specialists, anchoring hospital gynecology suite relationships through bundled instrument ecosystems.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| CooperSurgical, Inc. |
| Olympus Corporation |
| Karl Kaps GmbH & Co. KG |
| Danaher Corporation |
| McKesson Corporation |
| DYSIS Medical Inc. |
| MedGyn Products Inc. |
| ATMOS MedizinTechnik GmbH & Co. KG |
| Others |
Cost & Logistics Intelligence
CMOS sensor pricing indices in South Korean and Japanese foundries cascade through colposcope manufacturing tiers, compressing margins on entry-level digital units while preserving premium pricing for optical heritage brands with in-house illumination component production.
Pricing Analysis
Throughput-linked value pricing anchors hospital procurement decisions, with digital colposcope vendors bundling PACS interoperability and service contracts to justify premium positioning. Price differentiation separates FDA 510(k)-cleared systems from CE-marked alternatives, with brand heritage from German and Japanese optical houses commanding additional margin. Cost compression in portable configurations is intensifying as Tamil Nadu fabricators scale battery-powered units for public health tenders. Price sensitivity concentrates among community clinics in India and Brazil, while German hospital systems prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Single-source vulnerability sits with high-resolution imaging module fabrication concentrated in South Korea, Japan, and Taiwan. LED illumination components draw from Nagoya precision manufacturing clusters, while optical glass and mechanical assemblies rest on German and Japanese industrial bases. Tariff exposure runs through import-dependent markets where ANVISA and CDSCO registration timelines delay market access. Distribution runs through hospital GPO contracts in the United States, national health service tenders in Germany, and regional medical device distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines and PMDA software validation requirements are forcing weaker manufacturers without dedicated regulatory affairs capacity to exit, consolidating procurement influence among established optical instrument houses.
For Market Incumbents: Lock in hospital gynecology suite relationships through integrated biopsy guidance ecosystems that raise switching costs for procurement committees. Capture displaced volumes from manufacturers losing notified body relationships by accelerating EU MDR Article 120 transition support. Invest in Tokyo-based regulatory subsidiaries to navigate PMDA standalone software guidance timelines that filter out smaller competitors. For New Entrants and Emerging Players: Federally qualified health centers in the United States present the most penetrable buyer archetype, with HRSA equipment grants funding digital upgrade cycles outside established vendor relationships. Mobile screening programs in rural India and Brazil's Amazon basin municipalities offer white-space expansion for handheld battery-powered configurations with telemedicine integration. Pursue ISO 13485 certification early to qualify for third-party service contract capture as IDNs unbundle maintenance from capital purchases. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier digital colposcope manufacturers with notified body relationships but strained working capital from EU MDR compliance overhead in Germany and Japan. Long-term viability hinges on AI-assisted diagnostic software validation capabilities and telemedicine infrastructure partnerships rather than hardware margins alone. Monitor reimbursement code consolidation for office-based cervical screening as the inflection signal determining whether digital upgrade cycles accelerate or stall.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Clearance timelines compress product refresh cycles for hospital outpatient departments. |
| CE Marking Pathway | EU MDR Article 120 recertification accelerates capital replacement decisions across European systems. |
| Hospital System Partnership | GPO contract capture locks in multi-site service revenue and raises competitor switching costs. |
| Software Companion Development | AI-assisted lesion detection algorithms expand into biopsy guidance workflows with regulatory sandbox acceleration. |
| Reimbursement Strategy | US Preventive Services Task Force grade revisions expand eligible populations for HRSA equipment grants. |
Research Approach
FDA 510(k) filings, EU MDR notified body documentation, and national health service procurement databases formed the secondary backbone, cross-referenced against primary interviews with hospital purchasing committee members, biomedical engineers specializing in optical-mechanical integration, GPO contracts managers, and regulatory affairs leads at established manufacturers. Bottom-up and top-down triangulation validated unit shipment estimates against capital equipment budget disclosures from German hospital systems and United States federally qualified health centers.
Bottom-up modeling anchored volume projections to installed base replacement cycles and point-of-care expansion trajectories, while top-down validation checked aggregate figures against national cervical cancer screening program equipment specifications across the analysis window. Segmentation dimensions included product type, illumination technology, end-user setting, and delivery mode configuration. CAGRs were derived from weighted average replacement timelines and reimbursement policy elasticity assumptions, with optical component lead times and regulatory approval backlogs incorporated as scenario variables.
Revisions become necessary when FDA guidance shifts on AI-enabled diagnostic functions, EU MDR notified body capacity constraints extend recertification timelines, or reimbursement code consolidation stalls digital upgrade commitments in outpatient settings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Nerve Stimulators Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Peak Flow Meters Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
North America Electrophysiology Market
Medical Devices
Expandable Interbody Fusion System Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Transient Elastography Device Market
Medical Devices
Inhaled Nitric Oxide (NO) Delivery Systems Market
Medical Devices
Meniscus Repair Systems Market
Medical Devices
Ultra High Definition (UHD) Surgical Display Market