
 Spinal Trauma Devices Market | 2026-2036
Spinal Trauma Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Trauma Devices Market Outlook
The EU Medical Device Regulation (MDR) is broadening compliance requirements for implantable spinal devices across European trauma networks. Medtronic Plc leverages its integrated biologics portfolio to sustain premium positioning in stabilization systems. Stryker Corp. anchors its European presence through specialized trauma sales channels. Johnson & Johnson competes via DePuy Synthes with concentrated R&D investment in robotic-assisted fixation platforms.
Spinal trauma devices encompass implantable hardware and biologics designed to stabilize, fuse, or decompress the vertebral column following acute injury, typically manufactured from titanium alloys, polyetheretherketone (PEEK), or resorbable polymers with thread pitches calibrated to cancellous bone density. These devices restore mechanical integrity and neural protection after fractures, dislocations, or burst injuries compromise spinal stability. Spinal fusion devices occupy the largest revenue pool due to established reimbursement and repeat intervention rates, while robotic surgery technology represents the fastest-expanding segment as hospitals justify capital expenditure through reduced revision frequency. Minimally invasive surgery systems concentrate margin capture among vendors with proprietary access and visualization platforms.
FDA 510(k) and PMA pathways govern US commercial entry, with the agency intensifying scrutiny of biologics-containing fusion constructs; EMA MDR compliance now mandates clinical follow-up data for Class III implantables in Europe. Japan's PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor evolving evidence requirements for biologics combinations and position manufacturing capacity to serve divergent regulatory timelines without portfolio fragmentation.
Market Dynamics
Regulatory divergence between FDA PMA pathways and EMA MDR clinical follow-up mandates is fragmenting product launch timelines and forcing manufacturers to maintain parallel evidence-generation infrastructures.
Growth Catalysts
- Level-one trauma center expansion:United States hospitals are upgrading stabilization system procurement budgets to meet ACS-verified trauma center standards.
- Biologics-enhanced fusion constructs:FDA 510(k) clearance streamlining for titanium-alloy implants with osteobiologic coatings is accelerating commercial access.
- Robotic-assisted fixation adoption:German university hospitals are prioritizing capital expenditure on navigation-integrated platforms to reduce revision frequency.
Market Restraints
- Titanium alloy price volatility:Aerospace and defense demand is compressing spot availability for medical-grade Ti-6Al-4V feedstock.
- EMA MDR compliance burden:Post-market clinical follow-up requirements for Class III implantables are extending European registration timelines by 18-24 months.
- Non-fusion motion preservation:Artificial disc replacement systems are capturing select trauma cases previously routed to fusion hardware.
Strategic Opportunities
- Japan PMDA biocompatibility testing:Domestic manufacturers with established JIS-compliant protocols can capture share from foreign entrants facing extended approval cycles.
- Resorbable polymer stabilization:Polylactic-co-glycolic acid screws for pediatric trauma are opening procedural categories titanium cannot address.
- Outpatient ambulatory surgery centers:Minimally invasive access platforms are creating channel access beyond traditional hospital purchasing.
Industry Challenges
- Robotic surgery technician scarcity:Trauma departments lack trained operators for navigation-integrated fixation systems, limiting utilization rates.
- Legacy ERP integration:Hospital supply chains struggle to incorporate implant tracking systems required by EMA MDR Unique Device Identification mandates.
- Biologics cold-chain logistics:Osteobiologic adjuncts require temperature-controlled distribution infrastructure most distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Trauma Devices Market |
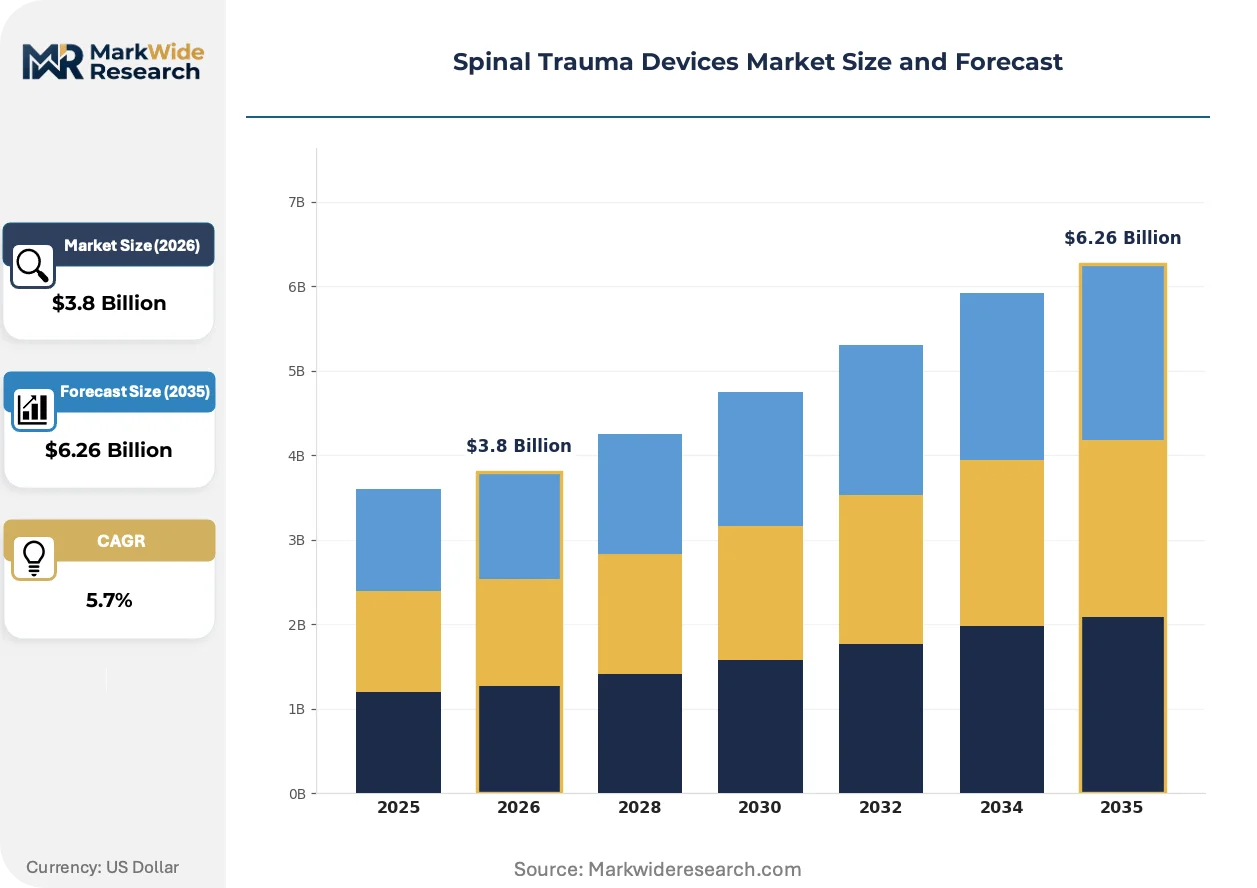
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Spinal Stabilization Systems, Vertebral Compression Fracture Devices, Interbody Devices Technology: Minimally Invasive Surgery, Robotic Surgery, Biologics, Traditional Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Rehabilitation Centers Application: Traumatic Injuries, Degenerative Conditions, Spine Reconstruction, Pain Management |
| Companies Covered | Medtronic Plc, Stryker Corp., Johnson & Johnson, Globus Medical Inc., DePuy Synthes, Orthofix Medical Inc., NuVasive Inc., Alphatec Holdings Inc., Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Trauma Devices Market Strategic Shifts
Three intersecting forces are compressing the competitive landscape: robotic navigation platforms are consolidating procedural control, regulatory evidence requirements are stratifying vendor capabilities, and procurement centralization is concentrating purchasing authority among integrated delivery networks.
Patient-specific 3D-printed titanium cages with topology-optimized lattice structures are consolidating fracture fixation workflows by eliminating intraoperative bending and reducing operative time. Level-one trauma centers in the United States are adopting these constructs for complex burst fractures. The technology is consolidating margin capture among vendors with captive additive manufacturing capacity and FDA-validated quality systems.
EMA MDR Article 10 clinical evaluation requirements now mandate systematic literature review and post-market surveillance for all Class III spinal implantables. Manufacturers must maintain post-market clinical follow-up registries or risk Notified Body suspension. European trauma networks are responding by consolidating supplier relationships toward vendors with established clinical evidence platforms.
Hospital value analysis committees are unbundling implant pricing from instrumentation and biologics, forcing vendors to defend each line item separately. Integrated delivery networks in Germany are centralizing spinal trauma procurement through specialized orthopedic purchasing cooperatives. This behavioral shift is most visible among German university hospitals, where standardization committees now mandate single-source contracts for stabilization platforms.
Spinal Trauma Devices Market Segmentation
Device specification dictates procurement patterns across trauma networks. Surgeons select implant systems based on fracture morphology, bone quality, and revision risk rather than price alone.
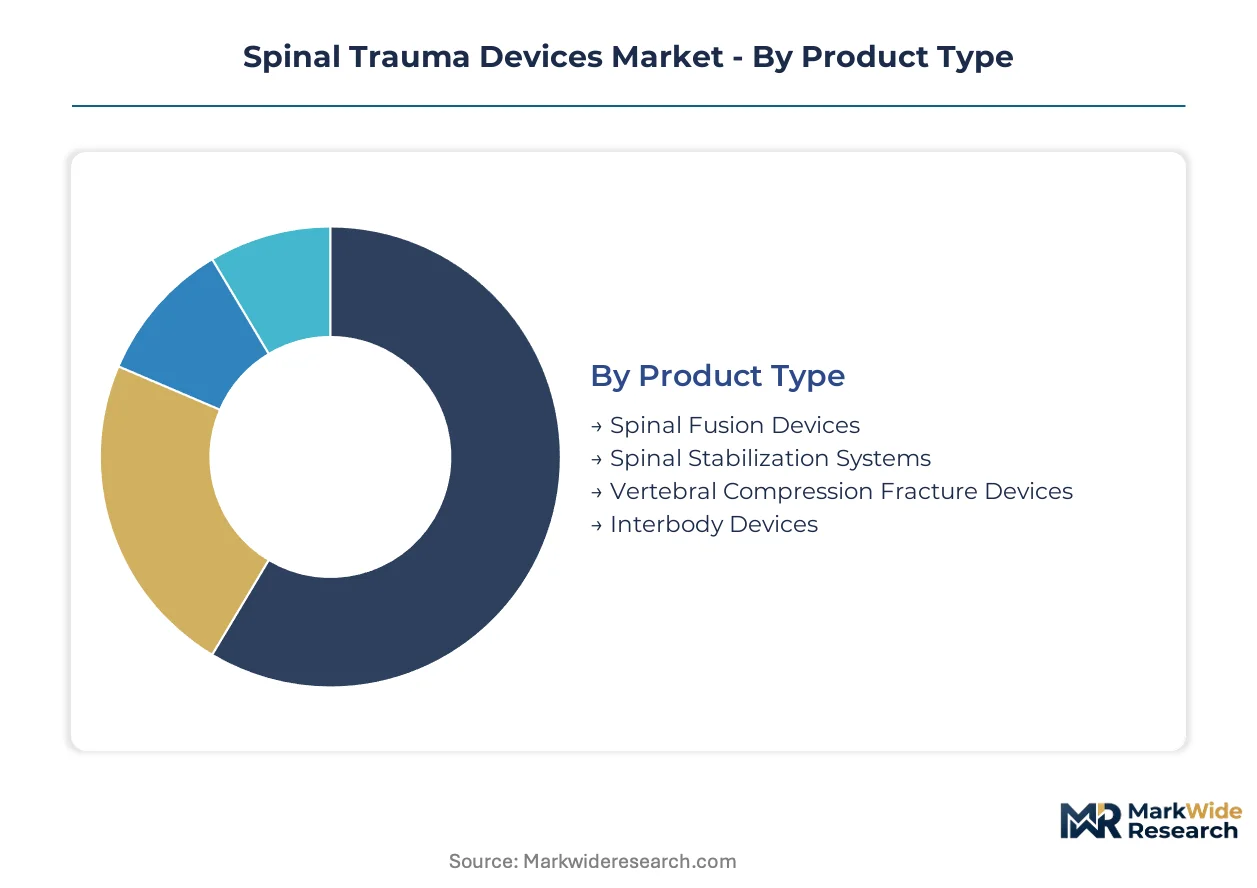
Product Type:
Titanium alloy specifications and PEEK modulus matching determine clinical selection criteria.
- Spinal Fusion Devices:These systems incorporate pedicle screws, rods, and interbody cages manufactured from Ti-6Al-4V or PEEK to achieve arthrodesis across damaged motion segments. United States level-one trauma centers command the largest procurement volumes as ACS verification standards mandate 24-hour spine coverage.
- Spinal Stabilization Systems:External fixation and percutaneous screw constructs provide provisional stability without fusion in polytrauma patients. German university hospitals are expanding inventory for damage-control orthopedics protocols.
- Vertebral Compression Fracture Devices:Balloon kyphoplasty and vertebroplasty systems address osteoporotic burst patterns. Kyphon (Medtronic) and Stryker instruments dominate hospital purchasing.
- Interbody Devices:Threaded titanium or PEEK spacers restore disc height and sagittal alignment. Cervical and lumbar profiles require separate instrumentation sets.
Mature deployment sits with Spinal Fusion Devices. Newer deployment is concentrated in Spinal Stabilization Systems.
Technology:
Capital intensity and training requirements stratify adoption across facility tiers.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous access reduce soft-tissue disruption and blood loss. Ambulatory surgical centers in the United States are adding these platforms to capture outpatient spinal trauma cases.
- Robotic Surgery:Navigation-integrated fixation platforms enable submillimeter screw placement accuracy. Stryker's Mako and Medtronic's Stealth Autoguide systems anchor German hospital capital budgets.
- Biologics:Demineralized bone matrix and bone morphogenetic protein-2 accelerate fusion in compromised bone. FDA PMA scrutiny for BMP-2 dosing regimens complicates formulary placement.
- Traditional Surgery:Open posterior approaches with direct visualization retain dominance in resource-constrained settings and complex deformity reconstruction.
Traditional Surgery captures the highest procedure volume. Robotic Surgery is climbing the fastest as hospitals amortize capital expenditure through reduced revision rates.
End User:
Reimbursement differentials and case complexity filter device selection across care settings.
- Hospitals:Level-one trauma centers maintain comprehensive implant inventories spanning fusion, stabilization, and biologics. These facilities handle polytrauma with spinal column involvement requiring multidisciplinary coordination.
- Ambulatory Surgical Centers:Minimally invasive platforms enable same-day discharge for stable burst fractures and select decompression procedures. United States Medicare reimbursement expansion for ASC spinal procedures is accelerating site-of-service migration.
- Specialty Clinics:Orthopedic spine practices concentrate non-operative management and pre-operative planning. These settings rarely stock implant inventory.
- Rehabilitation Centers:Post-acute facilities manage bracing and mobility restoration without surgical intervention.
Hospitals retain the deepest implant penetration. Ambulatory Surgical Centers are gaining share fastest as minimally invasive techniques mature.
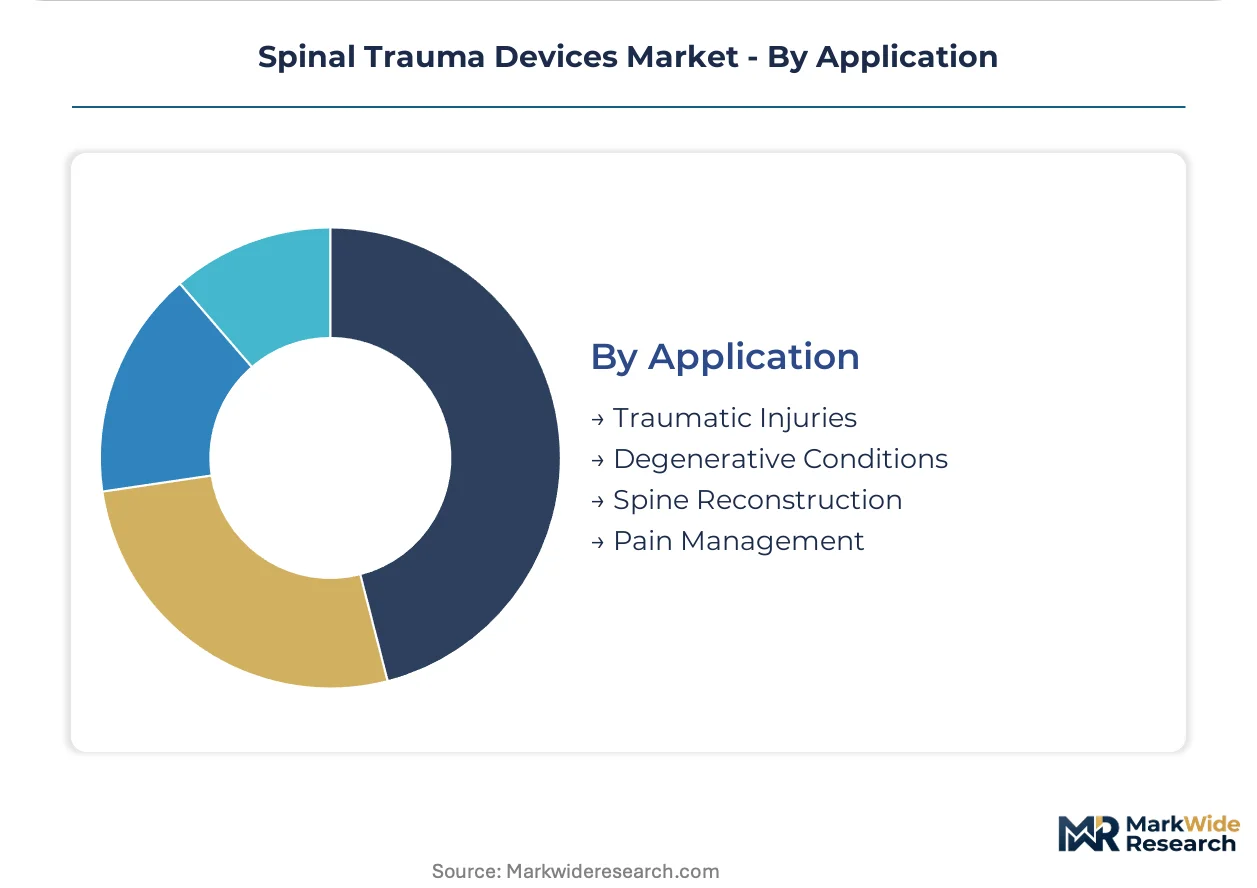
Application:
Acuity level and degenerative burden reshape device demand across patient populations.
- Traumatic Injuries:Fractures, dislocations, and burst injuries from high-energy mechanisms require urgent stabilization. United States trauma centers see concentration of motor vehicle and fall-related spinal column damage.
- Degenerative Conditions:Spondylolisthesis and stenosis in aging populations drive elective fusion volume. Japan's demographic profile sustains procedural demand for degenerative indications.
- Spine Reconstruction:Tumor resection and infection debridement demand expandable cages and long-segment constructs. These cases concentrate at academic medical centers.
- Pain Management:Neurostimulation and intrathecal drug delivery systems address chronic post-traumatic pain syndromes.
Degenerative Conditions command the largest installed base. Traumatic Injuries represent the steepest expansion trajectory as trauma center infrastructure deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for spinal trauma devices clusters in the United States and Germany, while demand expansion concentrates in trauma center networks across Japan and emerging procurement corridors in the Middle East. This production-consumption divide shapes regional competitive positioning.
United States
ACS-verified level-one trauma centers in Houston, Baltimore, and Los Angeles are expanding 24-hour spinal coverage mandates. FDA 510(k) clearance streamlining for titanium-alloy implants with osteobiologic coatings accelerates commercial access for domestic manufacturers. The Texas Medical Center cluster anchors stabilization system procurement volume.
Germany
University hospitals in Munich, Heidelberg, and Berlin are prioritizing capital expenditure on navigation-integrated robotic platforms. EMA MDR Article 10 clinical evaluation requirements mandate systematic literature review for Class III implantables. The Baden-Württemberg medical technology corridor concentrates additive manufacturing capacity for patient-specific titanium cages.
Japan
Aging demographics sustain procedural demand for degenerative spinal indications alongside traumatic injury volume. PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. The Kanto region around Tokyo concentrates trauma center infrastructure and implant distribution networks.
Switzerland
Swissmedic oversees a compact but high-value market where premium pricing supports robotic-assisted fixation adoption. Cantonal hospital networks in Zurich and Geneva standardize on single-source contracts for stabilization platforms. The Basel pharmaceutical-industrial cluster feeds adjacent medical device research corridors.
Saudi Arabia
SFDA registration pathways are streamlining as the kingdom expands trauma care infrastructure under Vision 2030 health sector transformation. Riyadh and Jeddah medical cities are consolidating procurement authority through centralized purchasing cooperatives. The Eastern Province industrial zones are attracting contract manufacturing for titanium alloy feedstock processing.
Spinal Trauma Devices Market Competitive Environment
The competitive structure tilts toward diversified medical technology conglomerates with integrated biologics portfolios. Vendor concentration remains moderate, with tier-one players commanding trauma center purchasing through comprehensive stabilization system offerings and tier-two specialists capturing ambulatory surgery center volume through minimally invasive platforms. Two strategic archetypes dominate: full-line suppliers with robotic navigation integration and focused trauma specialists with damage-control orthopedic expertise. M&A activity targets biologics-enhanced implant capabilities, while capacity expansion concentrates on additive manufacturing for patient-specific constructs.
Among diversified conglomerates, Medtronic Plc and Stryker Corp. exemplify the integrated-platform archetype, anchoring premium positioning through biologics-stabilization combinations. Johnson & Johnson occupies a position within the robotic-assisted fixation tier via DePuy Synthes. These three entities represent the structural concentration shaping procurement negotiations with integrated delivery networks and university hospital systems.
| Leading Market Players |
|---|
| Medtronic Plc |
| Stryker Corp. |
| Johnson & Johnson |
| Globus Medical Inc. |
| DePuy Synthes |
| Orthofix Medical Inc. |
| NuVasive Inc. |
| Alphatec Holdings Inc. |
| Zimmer Biomet |
| Others |
Value Chain & Pricing Dynamics
Additive manufacturing adoption for patient-specific titanium cages is simultaneously compressing per-unit production costs and consolidating supply authority among vendors with captive 3D printing facilities and FDA-validated quality systems.
Pricing Analysis
Margin tightening in standard implant tiers reflects hospital value analysis committees unbundling device pricing from instrumentation and biologics. Three-tier pricing structure across premium robotic-integrated, standard minimally invasive, and economy traditional open systems stratifies procurement negotiations. Cost compression accelerates as German university hospitals mandate single-source stabilization contracts. Ambulatory surgical centers exhibit highest price sensitivity; level-one trauma centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-controlled biologics distribution is forcing manufacturers toward regional cold-chain hub strategies. Medical-grade titanium feedstock concentrates in United States, Germany, and China; PEEK polymer resin sources primarily from United Kingdom and Germany. Supply chain risk centers on aerospace and defense demand compressing Ti-6Al-4V spot availability. Distribution runs through specialized orthopedic distributors and direct hospital contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spinal trauma devices market reads as a cost-of-compliance story where EMA MDR Article 10 clinical evaluation requirements erect barrier-to-entry moats favoring manufacturers with established post-market surveillance registries.
For Market Incumbents: Deepen captive additive manufacturing capacity for patient-specific constructs to defend margin position against commoditization of standard pedicle screw systems. Anchor procurement relationships through biologics-stabilization bundled contracts that complicate hospital switching costs. Prioritize M&A targeting resorbable polymer stabilization platforms for pediatric trauma white space. For New Entrants and Emerging Players: The premium-to-economy pricing gap in robotic navigation platforms creates entry opportunity for focused trauma specialists with damage-control orthopedic expertise. Target ambulatory surgical center channels with percutaneous access systems that bypass capital-intensive hospital purchasing committees. Pursue FDA 510(k) clearance streamlining for titanium-alloy implants with osteobiologic coatings as fastest regulatory pathway. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medtech conglomerates seeking biologics-enhanced implant capabilities. Long-term viability favors vendors with integrated robotic navigation platforms and established clinical evidence registries. Watch Japanese PMDA biocompatibility testing protocol harmonization as signal for foreign manufacturer entry cost reduction.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Streamlining | Accelerates commercial access for domestic titanium-alloy implant manufacturers with osteobiologic coatings. |
| CE Marking Pathway Investment | EMA MDR compliance mandates systematic literature review for Class III spinal implantables in European trauma networks. |
| Hospital System Partnership | Integrated delivery networks in Germany centralize procurement through specialized orthopedic purchasing cooperatives. |
| Software Companion Development | Navigation-integrated fixation platforms require proprietary visualization systems for submillimeter screw placement accuracy. |
| Reimbursement Strategy | United States Medicare expansion for ambulatory surgical center spinal procedures accelerates site-of-service migration. |
Study Parameters
FDA 510(k) and PMA filings, EMA MDR submission databases, and hospital procurement records formed the secondary backbone, cross-referenced against primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Bottom-up and top-down triangulation validated segment-level estimates against manufacturer revenue disclosures and trauma center inventory audits.
Historical trendline analysis across implant shipment volumes, procedural counts, and capital expenditure patterns informed the projection framework. Segmentation dimensions modeled include product type, technology platform, end-user facility tier, and application acuity level across the analysis window. CAGRs derived from regression analysis of regulatory approval velocity, reimbursement expansion trajectories, and trauma center infrastructure investment cycles.
Inputs from EMA Notified Bodies and United States trauma center accreditation databases were available through the study window; gaps in real-time robotic surgery utilization rates introduce uncertainty bands around capital expenditure forecasts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Collateral Ligament Stabilizer System Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Global Surgical Visualization Systems Market
Medical Devices
Global Radial Artery Compression Devices Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Electric Massage Equipment Market
Medical Devices
Radiofrequency-Based Aesthetic Devices Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Walking Aids Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Global Thrombectomy Devices Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Neurovascular Access Catheters Market