

Controlled-Release Drug Delivery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Controlled-Release Drug Delivery Technology Market Insights
European contract manufacturing organizations is decoupling from traditional batch processing capacity as specialized facilities for sustained-release platforms expand across Germany and Switzerland. Pfizer leverages integrated R&D pipelines to anchor its position in long-acting injectable development. Novartis sustains technology leadership through advanced polymer matrix capabilities. Merck & Co. differentiates via geographic dominance in oncology-focused controlled-release applications across North American and European markets.
Controlled-release drug delivery technology encompasses pharmaceutical systems engineered to liberate active pharmaceutical ingredients at predetermined rates, typically employing biodegradable polymers such as PLGA or polylactic acid matrices manufactured through solvent evaporation or microfluidic processing to achieve therapeutic plasma concentrations over hours to months. Its primary commercial purpose centers on improving patient adherence, reducing dosing frequency, and minimizing peak-trough toxicity profiles for chronic disease management. Transdermal patches and liposomes represent mature segments with established reimbursement pathways, while microspheres and nanoparticles capture expanding margin pools as oncology and neurology therapy areas drive demand for targeted, sustained-release platforms. Oral delivery mode retains volume leadership, though injectable systems command premium positioning in hospital and specialty pharmacy channels.
The FDA enforces stringent bioequivalence and in-vitro dissolution testing standards that directly shape product development timelines and market access pathways for novel controlled-release formulations. EMA's Medical Device Regulation and REACH compliance requirements for polymer excipients add layered certification burdens, particularly for implantable and transdermal systems entering European markets. Stakeholders must monitor evolving pharmacopeial standards for novel excipient characterization while calibrating manufacturing investments against shifting regulatory expectations for real-world release-profile verification.
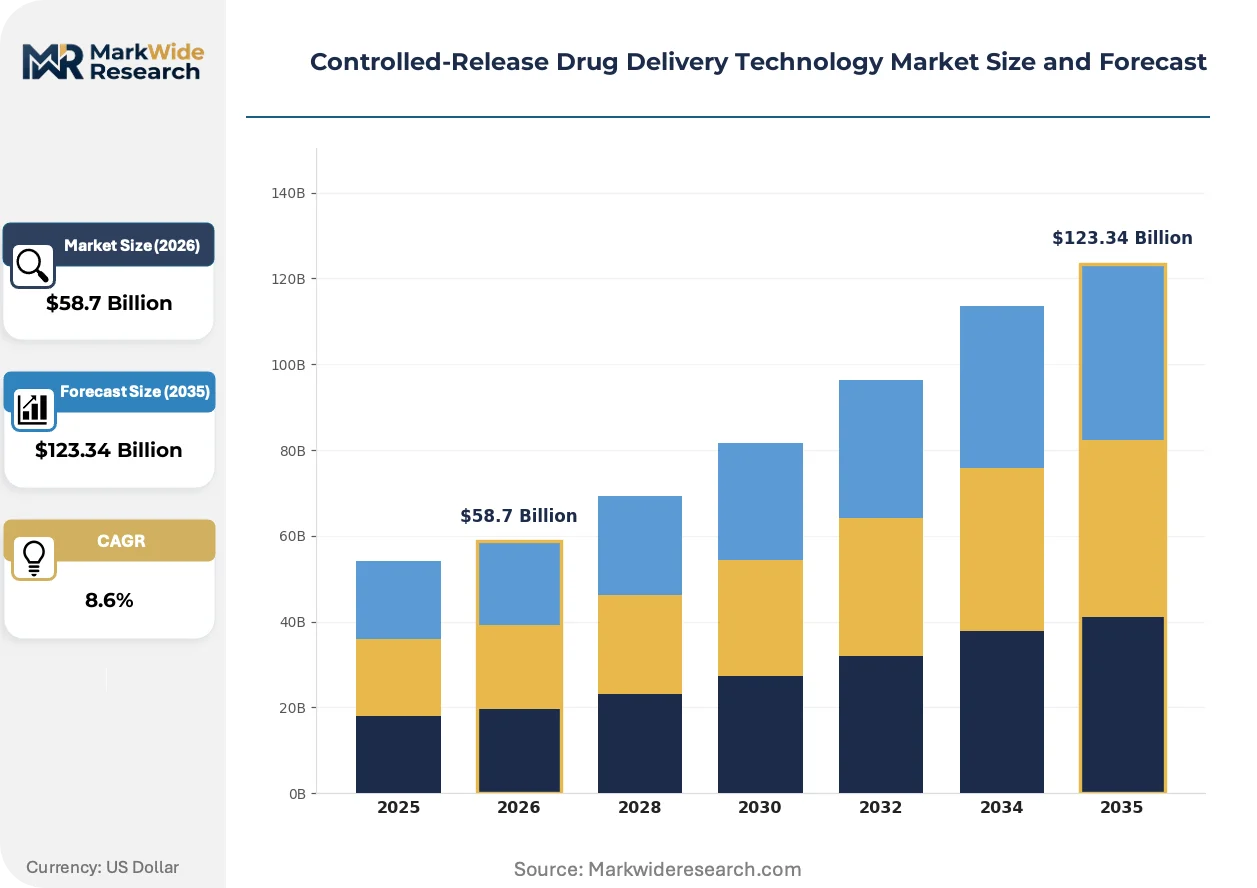
Market Dynamics
Oncology departments at major hospital networks are expanding adoption of long-acting injectable formulations, creating a structural pull toward sustained-release platforms that reduce dosing frequency and minimize peak-trough toxicity profiles for chronic disease management.
Growth Catalysts
- FDA Quality by Design Framework:The FDA's QbD validation requirements for sustained-release platforms are accelerating standardization of polymer matrix characterization, reducing batch-to-batch variability and compressing regulatory review timelines for novel formulations.
- Biodegradable Polymer Matrices:PLGA and polylactic acid matrices manufactured through microfluidic processing are enabling therapeutic plasma concentrations over months, improving patient adherence in neurology and oncology therapy areas.
- German Hospital Network Expansion:Oncology departments across Berlin, Munich, and Hamburg are prioritizing precision dosing infrastructure, driving procurement of long-acting injectable systems for chronic disease protocols.
Market Restraints
- Specialized Manufacturing Concentration:Solvent evaporation and microfluidic processing capacity concentrates in German and Swiss contract manufacturing organizations, creating supply bottlenecks for sustained-release platform scale-up.
- EMA MDR Certification Burden:The European Medical Device Regulation's layered requirements for implantable and transdermal systems add 18-24 month certification timelines, compressing margin pools for mid-scale entrants.
- Transdermal Patch Substitution:Mature transdermal patch segments with established reimbursement pathways limit pricing power for novel microsphere and nanoparticle entrants in pain management applications.
Strategic Opportunities
- Japanese Precision Dosing Demand:Japan's aging demographic and chronic disease management priorities create underpenetrated demand for long-acting injectable formulations in Tokyo, Osaka, and Nagoya hospital networks.
- Real-World Release-Profile Verification:Evolving pharmacopeial standards for novel excipient characterization are creating first-mover advantages for manufacturers with integrated analytical capabilities.
- Microsphere-Nanoparticle Convergence:The intersection of advanced polymer matrix capabilities with targeted oncology applications is opening premium positioning in specialty pharmacy channels.
Industry Challenges
- Microfluidic Processing Skill Gap:Solvent evaporation expertise and microfluidic processing talent scarcity constrains manufacturing scale-up for sustained-release platforms across European and North American facilities.
- Polymer Excipient REACH Compliance:ECHA registration requirements for novel biodegradable polymers create documentation burdens that extend development timelines for implantable system entrants.
- Legacy Oral Delivery Integration:Hospital formulary committees face workflow friction integrating injectable controlled-release protocols alongside established oral delivery regimens.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Controlled-Release Drug Delivery Technology Market Trends and Innovations
Microfluidic processing is consolidating manufacturing control for sustained-release platforms, while regulatory frameworks on both sides of the Atlantic tighten verification standards and hospital procurement models evolve toward outcome-driven selection criteria.
Microfluidic processing is consolidating precision control over polymer matrix formation for sustained-release platforms. Solvent evaporation techniques are yielding to microfluidic systems that enable tighter particle size distribution and more predictable release kinetics. Hospital pharmacy directors in the United States, Germany, and Japan are prioritizing suppliers with demonstrated microfluidic capabilities, compressing demand toward integrated manufacturing operations.
EMA's revised Medical Device Regulation is tightening validation requirements for implantable and transdermal controlled-release systems. The MDR's expanded clinical evidence requirements and post-market surveillance obligations are extending certification timelines for European market entry. German and Swiss contract manufacturing organizations are absorbing compliance costs through dedicated regulatory affairs functions, while smaller entrants face capital constraints.
Hospital procurement committees are consolidating supplier relationships around demonstrated release-profile consistency rather than unit cost. Specialty pharmacy channels are displacing traditional wholesale distribution for long-acting injectable oncology formulations. This concentration is most visible in United States hospital networks, where integrated delivery networks negotiate multi-year supply agreements with polymer matrix manufacturers.
Controlled-Release Drug Delivery Technology Market Segmentation
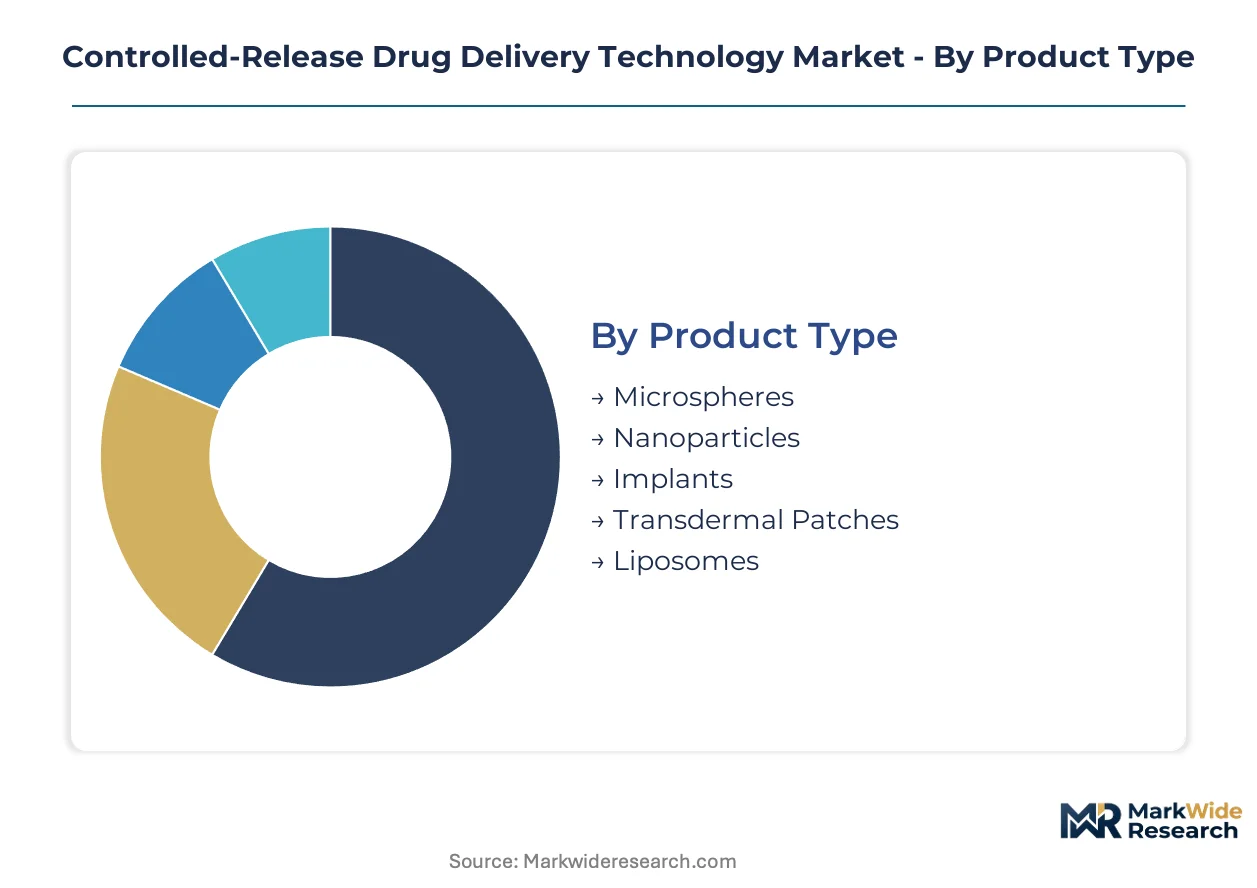
Controlled-release drug delivery technology fragments across multiple technical and commercial dimensions. Each segment carries distinct regulatory pathways, manufacturing requirements, and end-user procurement patterns that shape competitive positioning.
Product Type:
FDA's QbD framework and EMA's MDR impose tiered certification burdens: implantable systems face 18-24 month clinical evidence requirements, while transdermal platforms leverage established pharmacopeial standards.
- Microspheres:Biodegradable polymer matrices manufactured through microfluidic processing enable therapeutic plasma concentrations over months. Hospital oncology departments in the United States and Germany prioritize microsphere formulations for reducing peak-trough toxicity in chronic disease protocols.
- Nanoparticles:Sub-micron carriers engineered for targeted cellular uptake command premium positioning in specialty pharmacy channels. Tokyo and Osaka hospital networks are expanding procurement of nanoparticle systems for precision oncology applications.
- Implants:Long-acting depot formulations require EMA MDR compliance for European market entry.
- Transdermal Patches:Mature segment with established reimbursement pathways and streamlined FDA bioequivalence testing.
- Liposomes:Phospholipid bilayer systems face REACH compliance documentation for polymer excipient characterization.
Transdermal patches sit at the top of the volume ranking, with nanoparticles climbing the fastest.
Therapy Area:
Cost tiering separates chronic disease management protocols from acute intervention applications, with oncology and neurology commanding premium pricing for sustained-release platforms.
- Oncology:Long-acting injectable formulations reduce dosing frequency for chemotherapy regimens. Major hospital networks across Berlin, Munich, and Hamburg are prioritizing precision dosing infrastructure for oncology-controlled-release protocols.
- Neurology:Polymer matrix systems enable month-long therapeutic windows for neurodegenerative conditions. Japanese hospital networks in Tokyo and Nagoya represent underpenetrated demand for neurology-focused sustained-release applications.
- Cardiovascular:Oral controlled-release dominates volume for hypertension management protocols.
- Endocrinology:Insulin and hormone delivery systems require specialized microfluidic manufacturing capabilities.
- Infectious Diseases:Antibiotic depots face formulary integration friction alongside established oral delivery regimens.
Oncology leads revenue concentration, with neurology expanding most quickly as aging demographics drive chronic disease management priorities.
Delivery Mode:
Application-specific requirements dictate manufacturing investment: injectable systems demand microfluidic processing capacity, while oral platforms leverage conventional batch processing infrastructure.
- Injectable:Long-acting formulations command premium positioning in hospital and specialty pharmacy channels. German and Swiss contract manufacturing organizations are decoupling from traditional batch processing to expand microfluidic capacity for sustained-release platform scale-up.
- Oral:Retains volume leadership through established manufacturing infrastructure and streamlined regulatory pathways. United States hospital formulary committees face workflow friction integrating injectable protocols alongside entrenched oral delivery regimens.
- Transdermal:Patch systems require EMA MDR certification for implantable classification in European markets.
- Pulmonary:Dry powder inhaler formulations face pharmacopeial standards evolution for novel excipient characterization.
- Nasal:Mucosal delivery systems concentrate in biotechnology firm R&D pipelines.
Oral delivery sits at the top of the volume ranking, with injectable systems gaining share fastest through oncology and neurology adoption.
End User:
Customer type determines procurement authority and technical specification requirements, with pharmaceutical companies and contract manufacturing organizations driving polymer matrix standardization.
- Pharmaceutical Companies:Integrated R&D pipelines anchor long-acting injectable development through captive manufacturing or strategic supplier relationships. Pfizer leverages internal capabilities to compress regulatory review timelines for novel formulations.
- Contract Manufacturing Organizations:Specialized facilities for sustained-release platforms are expanding across Germany and Switzerland. EMA MDR compliance costs are absorbing through dedicated regulatory affairs functions, while smaller entrants face capital constraints.
- Biotechnology Firms:Early-stage developers rely on external microfluidic processing expertise for scale-up.
- Research Institutes:Academic partnerships drive polymer matrix innovation through government-funded programs.
Pharmaceutical companies sit at the top of the volume ranking, with contract manufacturing organizations climbing the fastest as outsourcing concentrates specialized manufacturing capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as EMA certification burdens push development toward Swiss and German contract manufacturing organizations while FDA pathways retain appeal for United States commercialization. Production capacity migrates toward jurisdictions with established polymer matrix expertise and streamlined quality-by-design frameworks.
United States
Oncology departments at Memorial Sloan Kettering, MD Anderson, and Mayo Clinic networks are expanding precision dosing infrastructure for long-acting injectable protocols. FDA's Quality by Design framework accelerates standardization of polymer matrix characterization, compressing regulatory review timelines for novel sustained-release formulations. Boston-Cambridge and San Diego biotech clusters concentrate microfluidic processing R&D through integrated delivery network partnerships.
Germany
Hospital networks across Berlin, Munich, and Hamburg are prioritizing procurement of sustained-release platforms for chronic disease management protocols. EMA's Medical Device Regulation imposes 18-24 month certification timelines for implantable systems, absorbing compliance costs through dedicated regulatory affairs functions at major contract manufacturing organizations. Baden-Württemberg and North Rhine-Westphalia host specialized solvent evaporation and microfluidic processing facilities decoupling from traditional batch capacity.
Switzerland
Swissmedic's streamlined certification pathways for polymer-based drug delivery systems attract development-stage biotechnology firms seeking European market entry. Basel and Zurich industrial clusters concentrate advanced polymer matrix manufacturing capabilities with integrated analytical verification infrastructure. Contract manufacturing organizations leverage geographic proximity to German hospital networks while maintaining regulatory separation from EMA MDR direct jurisdiction.
Japan
Tokyo, Osaka, and Nagoya hospital networks represent underpenetrated demand for neurology-focused sustained-release applications amid aging demographic pressures. PMDA's evolving pharmacopeial standards for novel excipient characterization create first-mover advantages for manufacturers with integrated microfluidic capabilities. Kanto and Kansai regions concentrate polymer matrix R&D through government-funded chronic disease management initiatives.
India
CDSCO's streamlined bioequivalence pathways for generic controlled-release formulations attract contract development investments from multinational pharmaceutical companies. Hyderabad and Ahmedabad manufacturing clusters expand microsphere and nanoparticle capacity for export-oriented sustained-release platform production. Domestic hospital networks in Mumbai and Delhi-NCR are integrating long-acting injectable protocols for oncology and endocrinology applications.
Controlled-Release Drug Delivery Technology Market Competitive Landscape
United States-based integrated pharmaceutical companies anchor one tier; Swiss and German contract manufacturing specialists hold differentiated positioning through polymer matrix expertise and regulatory proximity. Market structure concentrates around three to five dominant players with captive manufacturing or strategic supplier relationships, while mid-scale entrants face capital constraints from EMA compliance burdens. Strategic archetypes span integrated R&D-to-commercial pipelines, specialized polymer technology licensors, and geographic-focused contract manufacturing organizations. Competitive moves center on capacity expansion in microfluidic processing and strategic partnerships for real-world release-profile verification capabilities.
Within the integrated pharmaceutical tier, Pfizer and Novartis exemplify divergent strategic positioning—Pfizer leveraging internal R&D pipelines to compress regulatory timelines, Novartis sustaining technology leadership through advanced polymer matrix capabilities. Merck & Co. occupies a distinct position through geographic concentration in North American and European oncology-focused applications. These three companies represent the competitive archetypes shaping procurement patterns among United States, German, and Japanese hospital networks.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer |
| Merck & Co. |
| Novartis |
| Roche |
| AbbVie |
| GSK |
| Eli Lilly and Company |
| Amgen |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees in the United States and Germany are consolidating supplier relationships around demonstrated release-profile consistency rather than unit cost, forcing contract manufacturing organizations to absorb EMA MDR compliance costs through dedicated regulatory affairs functions while compressing margin pools for mid-scale entrants.
Pricing Analysis
Specialty pharmacy channel margins for long-acting injectable oncology formulations command premium positioning above traditional wholesale distribution. Three-tier pricing structure across premium, standard, and economy levels separates microfluidic-processed microspheres from solvent-evaporation batches from legacy oral controlled-release platforms. Cost compression in standard-tier injectable systems is intensifying because German and Swiss contract manufacturing organizations are decoupling from traditional batch processing capacity. Biotechnology firms with early-stage pipelines exhibit highest price sensitivity, while integrated pharmaceutical companies with captive manufacturing capabilities demonstrate lowest sensitivity due to backward integration into polymer matrix production.
Supply Chain Analysis
Microfluidic processing talent scarcity in Baden-Württemberg and North Rhine-Westphalia constrains manufacturing scale-up for sustained-release platforms across European facilities. Supply concentrates in Germany, Switzerland, and the United States for specialized solvent evaporation and microfluidic processing infrastructure. Raw material dependencies center on PLGA and polylactic acid polymer matrices, phospholipid excipients for liposome systems, and analytical verification equipment. Single-source vulnerability from concentrated contract manufacturing organization capacity in German-speaking Europe creates structural risk for sustained-release platform scale-up. Distribution runs through integrated delivery networks negotiating multi-year supply agreements with polymer matrix manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The controlled-release drug delivery technology market functions as a stable compounder, with chronic disease management priorities across aging demographics in Japan, Germany, and the United States providing durable demand tailwinds for long-acting injectable formulations.
For Market Incumbents: Lock in hospital network procurement relationships through multi-year supply agreements with integrated delivery networks in the United States, while expanding microfluidic processing capacity in Baden-Württemberg to preempt supply bottlenecks. The threat of mid-scale biotechnology firms developing proprietary polymer matrix capabilities demands accelerated certification investment under FDA Quality by Design frameworks. Priority lever rests with backward integration into analytical verification infrastructure for real-world release-profile verification. For New Entrants and Emerging Players: CDSCO's streamlined bioequivalence pathways for generic controlled-release formulations in India opens a window for export-oriented microsphere and nanoparticle capacity expansion serving multinational pharmaceutical company outsourcing demand. White-space targets include neurology-focused sustained-release applications in Tokyo and Nagoya hospital networks, and antibiotic depot formulations facing formulary integration friction alongside established oral delivery regimens. Go-to-market angle centers on strategic partnerships with German contract manufacturing organizations for EMA MDR compliance navigation. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized polymer technology licensors with demonstrated microfluidic capabilities and integrated analytical verification infrastructure. Long-term viability over the projection horizon favors acquisition targets with captive supply of biodegradable polymer matrices and established hospital procurement relationships. Signal to watch is PMDA pharmacopeial standards evolution for novel excipient characterization in Japan, which would indicate inflection toward premium positioning for manufacturers with integrated capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Processing Scale-Up | Baden-Württemberg facility expansion tightens particle size distribution control for oncology microspheres. |
| EMA MDR Certification Pathway | Dedicated regulatory affairs functions at Swiss contract manufacturing organizations compress 18-24 month timelines. |
| Hospital System Partnership | Memorial Sloan Kettering and MD Anderson procurement consolidation anchors long-acting injectable volume. |
| Polymer Matrix Backward Integration | Captive PLGA production insulates Pfizer and Novartis from ECHA REACH documentation burdens. |
| Japanese Regulatory Early Engagement | PMDA pre-submission meetings for novel excipient characterization secure first-mover advantages in Tokyo hospital networks. |
Research Methodology
Coverage spans the United States, Germany, Switzerland, Japan, and India, with primary inputs from each market combining structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up and top-down triangulation cross-checks polymer matrix manufacturer capacity announcements against hospital network adoption data.
Rate-of-change decomposition separates volume expansion from value-per-unit evolution across the projection horizon. Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster. CAGRs were derived through iterative convergence of historical adoption curves with procurement pipeline visibility. Industry-specific forecast inputs incorporate PMDA pharmacopeial standards evolution timelines and EMA MDR certification completion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in FDA bioequivalence testing requirements or ECHA REACH polymer excipient reclassification. Material deviation in Japanese reimbursement policy for long-acting injectable neurology applications or German hospital network consolidation pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.