
 Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market | 2026-2036
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market Analytics
The FDA's premarket approval requirements for high-risk cardiovascular devices is broadening the cost-of-entry calculus for new VV ECLS entrants. Medtronic leverages its integrated ECMO platform and deep hospital relationships to sustain market presence across major tertiary centers. Getinge AB anchors its competitive stance through proprietary membrane oxygenation technology and specialized cannulae design. Terumo Corporation differentiates via precision manufacturing scale and established regulatory pathways in multiple geographies.
Veno-venous extracorporeal life support devices comprise integrated systems that oxygenate blood and remove carbon dioxide through membrane oxygenators while blood pumps maintain extracorporeal flow at rates typically ranging from 2 to 7 liters per minute, primarily serving patients with reversible but life-threatening respiratory failure. Membrane oxygenation technology leads the technology segment due to its direct impact on gas exchange efficiency and patient survival metrics. Cannulae products capture concentrated margin pools because vascular access precision determines procedural success and complication rates. Intensive care units represent the fastest-growing end-user category as bedside ECMO deployment expands beyond traditional cardiac surgery centers.
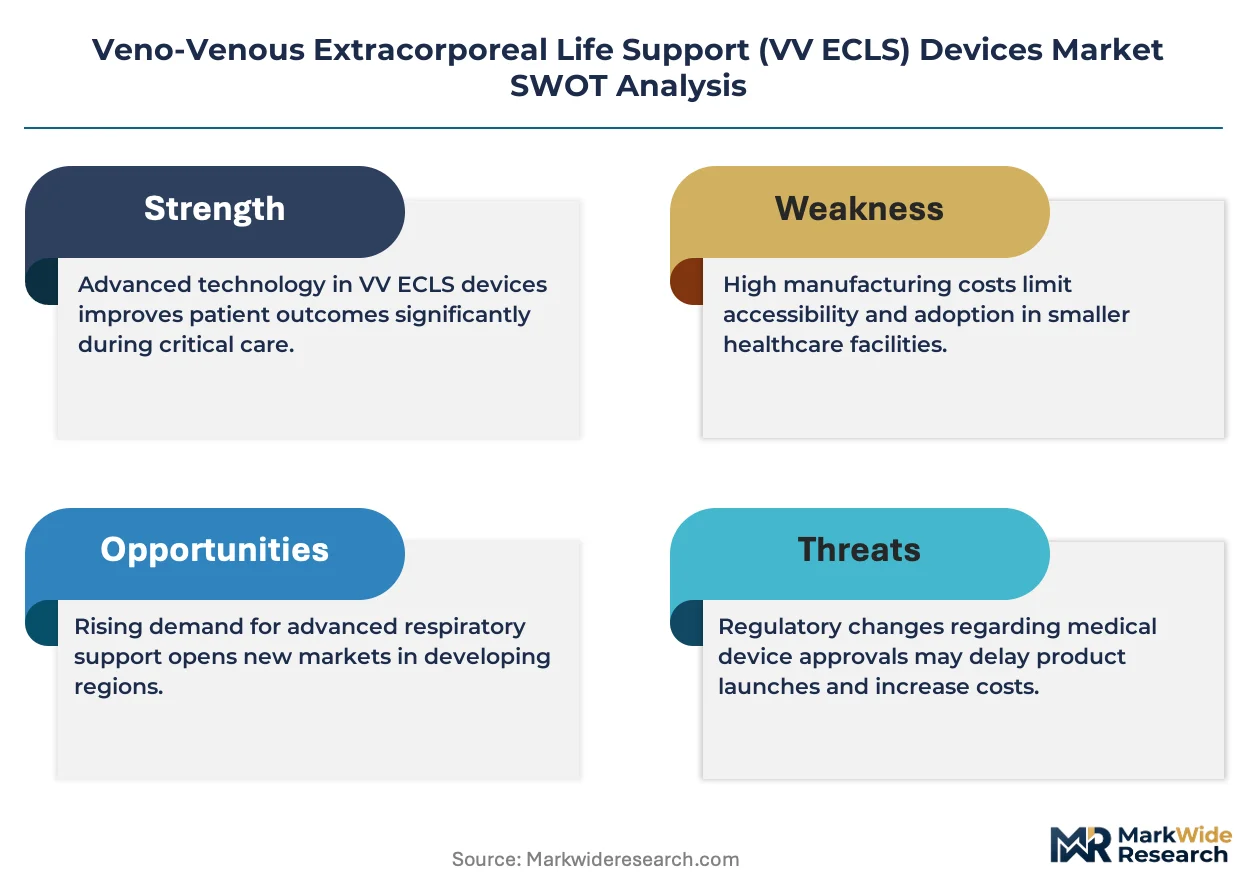
FDA premarket approval processes, EU MDR conformity assessment requirements, and Japan's PMDA orphan device pathways collectively shape product development timelines, clinical evidence standards, and market access conditions for VV ECLS manufacturers. The EU AI Act's emerging implications for automated monitoring algorithms in critical care devices will require manufacturers to revalidate software components within integrated systems. Stakeholders must monitor how regulatory convergence on real-world evidence requirements affects post-market surveillance obligations and competitive positioning across major markets.
Market Dynamics
FDA premarket approval timelines for high-risk cardiovascular devices are compressing commercialization windows for VV ECLS manufacturers, forcing accelerated clinical evidence generation and restructuring of regulatory affairs functions across the industry.
Growth Catalysts
- EU MDR conformity assessment:Streamlined pathways for life-sustaining devices in Germany and France are accelerating market access for qualified manufacturers with established quality management systems.
- Bedside ECMO deployment:Intensive care units in tertiary centers are expanding extracorporeal support capabilities beyond traditional cardiac surgery suites, creating new installation demand.
- Membrane oxygenation advances:Hollow-fiber biocompatibility improvements are extending circuit longevity and reducing transfusion requirements during prolonged respiratory support.
Market Restraints
- Silicone membrane supply concentration:Production of high-performance oxygenator membranes concentrates among specialized polymer suppliers in Germany and Japan, creating input vulnerability.
- PMDA orphan device pathway complexity:Japan's stringent evidentiary requirements for novel life-support technologies extend registration timelines beyond comparable FDA processes.
- Peripheral cannulation technical limitations:Vascular access complications in femoral and jugular configurations constrain candidacy for patients with severe peripheral arterial disease.
Strategic Opportunities
- India's tertiary hospital expansion:Corporate hospital chains in Mumbai, Delhi, and Bangalore are establishing ECMO programs with government-backed critical care infrastructure investments.
- Transportable ECLS systems:Compact pump-oxygenator units for inter-hospital patient transfer address unmet need in regional hub-and-spoke networks.
- EU AI Act algorithm validation:Automated circuit monitoring and predictive clot detection software creates differentiation pathway for integrated system vendors.
Industry Challenges
- Perfusionist workforce scarcity:Specialized extracorporeal membrane oxygenation operation requires certified clinical perfusionists, with training program capacity lagging deployment expansion in the United States and Germany.
- ISO 13485 certification timeline compression:Accelerated EU MDR implementation demands simultaneous quality system recertification and technical documentation updates, straining regulatory affairs bandwidth.
- Legacy EMR integration complexity:Proprietary data protocols from established pump manufacturers complicate connectivity with hospital electronic medical record systems, requiring custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market |
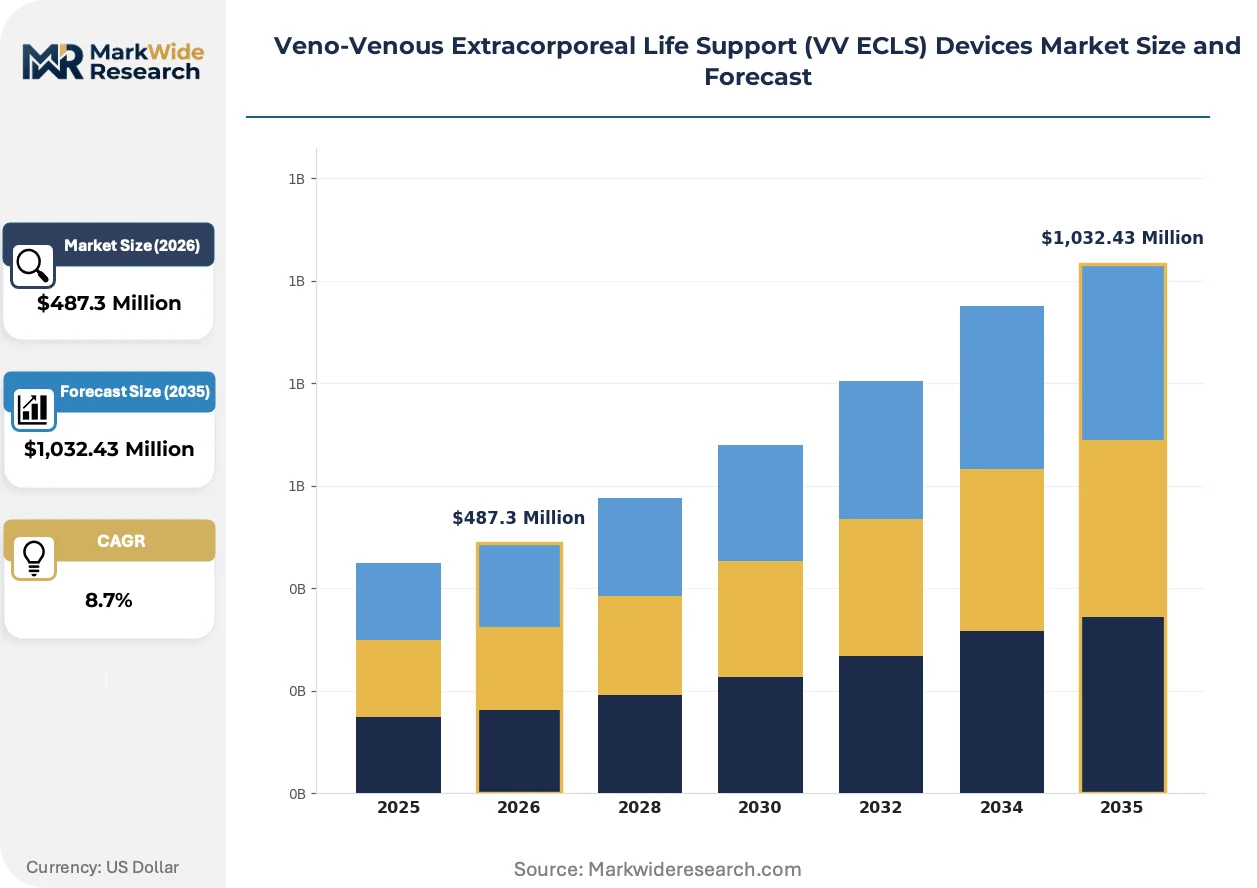
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VV ECLS Systems, Cannulae, Patient Monitors, Accessories End User: Hospitals, Intensive Care Units, Cardiac Centers, Research Institutions Technology: Membrane Oxygenation, Blood Pumps, Heat Exchangers, Monitoring Devices Application: Acute Respiratory Distress Syndrome, Cardiac Surgery, Trauma Care, Pulmonary Support |
| Companies Covered | Medtronic, Getinge AB, Terumo Corporation, LivaNova PLC, Fresenius Medical Care (XENIOS), Abbott Laboratories, MAQUET Holding, Microport Scientific, Nipro Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market Evolving Landscape
Active innovation in VV ECLS systems centers on circuit miniaturization, biocompatible surface coatings, and intelligent monitoring algorithms that reduce anticoagulation burden while maintaining gas exchange efficiency.
Magnetically levitated centrifugal pump technology is integrating active magnetic bearing systems that eliminate mechanical wear surfaces and reduce hemolysis during prolonged support. Pediatric and neonatal intensive care units in the United States and Germany are adopting these platforms for smaller patients requiring extended respiratory support. This integration is compressing the performance gap between compact transportable systems and traditional roller-pump configurations, enabling deployment outside specialized surgical centers.
The EU AI Act's risk classification framework for medical device software is mandating revalidation of automated monitoring algorithms embedded in integrated ECLS platforms. Manufacturers must document algorithmic decision pathways and establish human oversight protocols for predictive clot detection systems. Intensive care device vendors with established quality management systems are responding by segregating software development functions and expanding clinical validation cohorts across German and French tertiary centers.
Hospital procurement committees are consolidating vendor relationships through single-source agreements for disposable circuit components, displacing fragmented purchasing across multiple suppliers. This concentration is restructuring distributor margins and favoring integrated system manufacturers with captive consumables portfolios. The pattern is most visible in the United States, where hospital network consolidation has centralized capital equipment decisions at the corporate level rather than individual facility procurement.
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market Segmentation
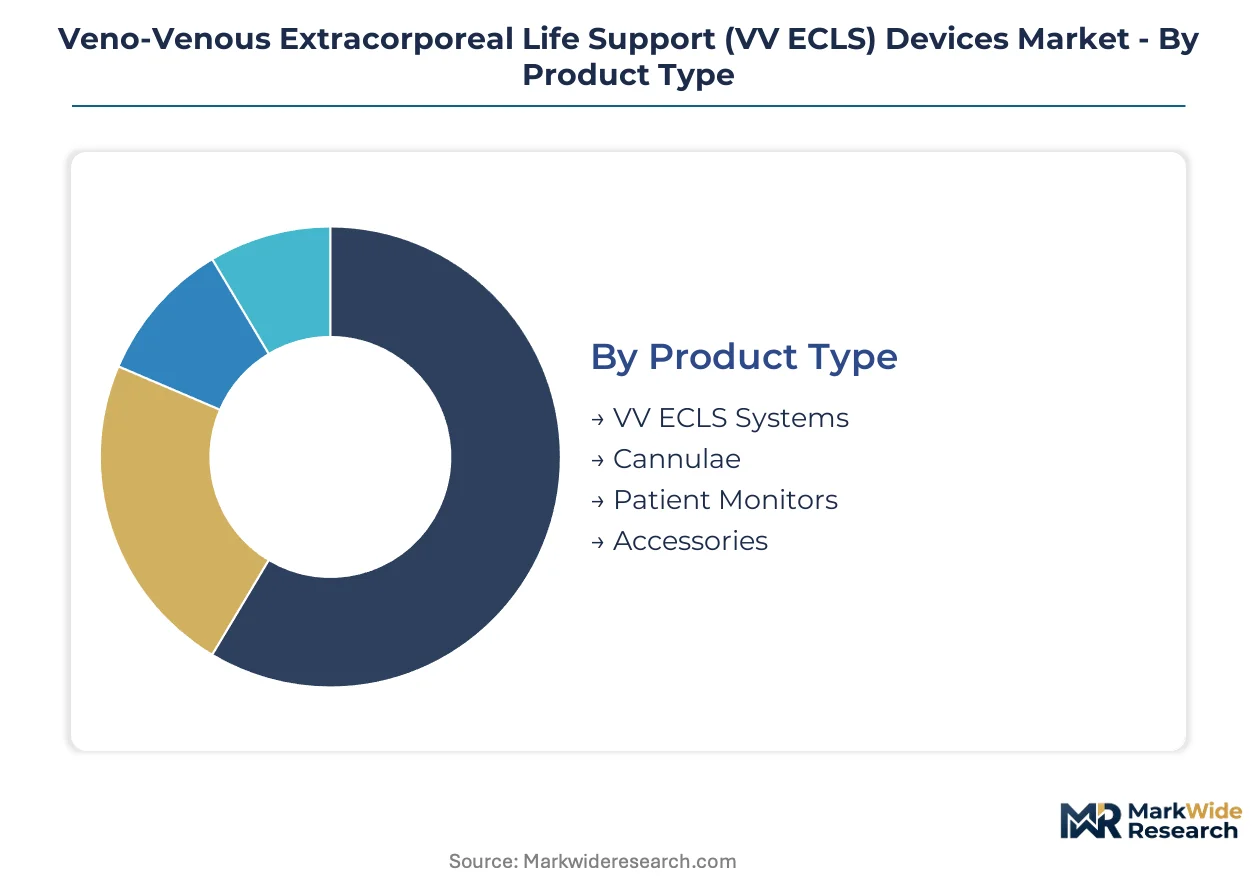
VV ECLS device segmentation reveals how regulatory pathways, clinical workflows, and technology maturity create divergent commercial dynamics across product categories. Manufacturers must align certification strategies with the specific approval burdens governing each segment's market entry.
Product Type:
FDA premarket approval requirements for high-risk cardiovascular devices impose tiered certification burdens across product categories, with integrated systems facing the most extensive clinical evidence demands.
- VV ECLS Systems:Integrated pump-oxygenator platforms incorporate centrifugal pumps, membrane oxygenators, and control modules in unified configurations. Tertiary centers in the United States and Germany concentrate procurement of these capital-intensive systems as ECMO program density expands.
- Cannulae:Vascular access devices range from femoral and jugular configurations to specialized dual-lumen designs for single-site cannulation. Precision manufacturing requirements concentrate production among specialized suppliers in Japan and Germany, with vascular access complication rates directly influencing hospital vendor selection.
- Patient Monitors:Integrated sensors track circuit pressures, blood gases, and flow parameters in real-time configurations.
- Accessories:Circuit tubing, connectors, and sterile drapes complete disposable component portfolios.
VV ECLS Systems sit at the top of the volume ranking, with Cannulae climbing the fastest.
End User:
Capital investment thresholds and staffing requirements create distinct customer tiers, with procurement authority concentrating at different organizational levels across facility types.
- Hospitals:Academic medical centers and large community hospitals maintain centralized ECMO programs with dedicated perfusion teams. Corporate procurement committees in United States hospital networks increasingly consolidate vendor agreements at the system level rather than individual facility discretion.
- Intensive Care Units:Bedside ECMO deployment expands beyond traditional cardiac surgery suites as intensivist training programs proliferate. United States and German tertiary centers lead this operational shift, compressing response times for acute respiratory failure cases.
- Cardiac Centers:Specialized surgical facilities concentrate high-volume ECMO support for postcardiotomy respiratory failure.
- Research Institutions:Translational medicine centers investigate next-generation oxygenation surfaces and miniaturized circuit designs.
Hospitals command the largest installed base, though Intensive Care Units are gaining share fastest as deployment decentralizes.
Technology:
Component-level innovation cycles vary dramatically, with membrane oxygenation advancing rapidly while heat exchanger designs remain relatively mature.
- Membrane Oxygenation:Hollow-fiber and silicone membrane configurations determine gas exchange efficiency and biocompatibility performance. Hollow-fiber biocompatibility improvements in German and Japanese manufacturing facilities are extending circuit longevity and reducing transfusion requirements during prolonged respiratory support.
- Blood Pumps:Centrifugal and roller pump architectures compete on hemolysis profiles and anticoagulation requirements. Magnetically levitated centrifugal platforms from United States and German suppliers are eliminating mechanical wear surfaces and enabling extended deployment in pediatric populations.
- Heat Exchangers:Temperature management components maintain normothermia during extracorporeal circulation.
- Monitoring Devices:Pressure, flow, and gas analysis sensors enable closed-loop control algorithms.
Membrane Oxygenation leads technology investment, with Blood Pumps showing the steepest expansion trajectory as magnetic levitation penetrates pediatric segments.
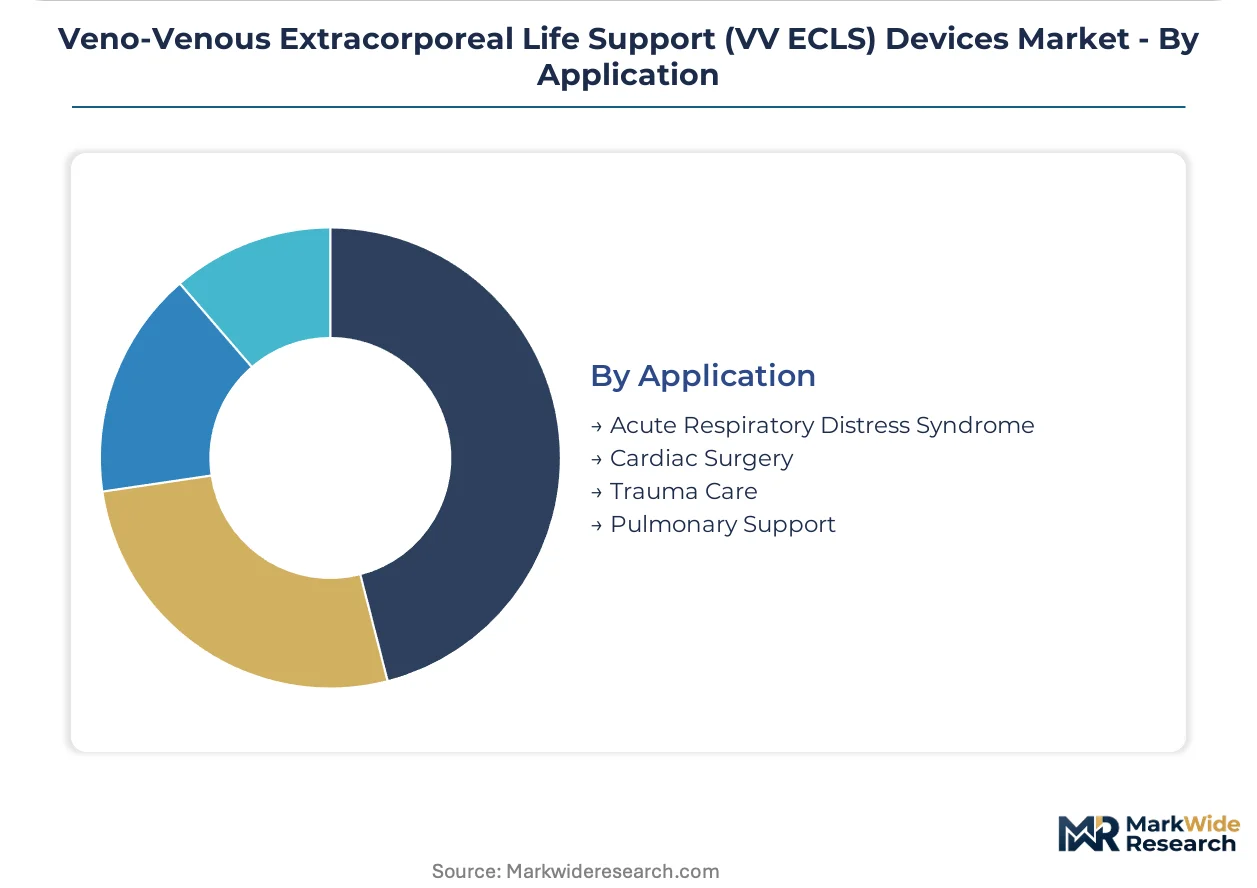
Application:
Clinical indication severity and reimbursement coding create divergent market access conditions across therapeutic areas.
- Acute Respiratory Distress Syndrome:Severe hypoxemic respiratory failure represents the primary VV ECLS indication with established mortality benefit evidence. United States and German intensive care units are expanding ARDS protocol deployment as randomized trial data supports extracorporeal support candidacy.
- Cardiac Surgery:Postcardiotomy respiratory failure and bridge-to-transplant applications drive surgical center utilization. Japanese cardiac centers concentrate volume for these indications within Asia-Pacific regional practice patterns.
- Trauma Care:Severe lung injury from blunt and penetrating mechanisms creates emergent cannulation scenarios.
- Pulmonary Support:Bridge-to-recovery and bridge-to-transplant indications for irreversible lung disease.
Acute Respiratory Distress Syndrome dominates procedure volume, with Trauma Care expanding most quickly as regional trauma networks integrate mobile ECMO capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified perfusionist concentrations in the United States, Germany, and Japan anchor ECMO program density and shape regional adoption trajectories for VV ECLS systems.
United States
Tertiary academic medical centers in Boston, Houston, and Cleveland drive ECMO volume through established respiratory failure protocols. FDA premarket approval requirements for high-risk cardiovascular devices compress commercialization timelines while concentrating procurement decisions within consolidated hospital networks. Corporate procurement committees at systems like HCA Healthcare and CommonSpirit Health now centralize vendor agreements at the enterprise level.
Germany
Intensive care units in Berlin, Munich, and Hamburg expand bedside ECMO deployment beyond traditional cardiac surgery suites. EU MDR conformity assessment pathways for life-sustaining devices accelerate market access for manufacturers with established quality management systems. The country's specialized polymer suppliers in Baden-Württemberg concentrate production of high-performance oxygenator membranes.
Japan
Cardiac centers in Tokyo, Osaka, and Nagoya concentrate postcardiotomy respiratory failure volume within Asia-Pacific regional practice patterns. PMDA orphan device pathway complexity extends registration timelines beyond comparable FDA processes, favoring established entrants with regulatory affairs bandwidth. METI-backed critical care infrastructure investments support ECMO program establishment in corporate hospital chains.
India
Corporate hospital chains in Mumbai, Delhi, and Bangalore establish ECMO programs with government-backed critical care infrastructure investments. CDSCO medical device registration requirements for life-support technologies create compliance thresholds that filter market participation. The country's tertiary hospital expansion targets 50,000 ICU beds by 2025, embedding extracorporeal support capabilities in hub-and-spoke networks.
United Kingdom
NHS England's specialized respiratory failure centers in London, Manchester, and Birmingham coordinate regional ECMO retrieval services. MHRA post-Brexit regulatory alignment with EU MDR technical standards maintains conformity assessment continuity for device manufacturers. Academic medical centers in the Southeast cluster lead protocol development for acute respiratory distress syndrome management.
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven platform vendors and precision component manufacturers occupy distinct competitive positions. The market consolidates around integrated system providers with captive consumables portfolios and specialized suppliers of membrane oxygenation technology. Three archetypes dominate: diversified medical technology conglomerates with deep hospital relationships, focused cardiovascular device specialists with regulatory pathway expertise, and precision manufacturing scale players with multi-geography certification. Competitive dynamics center on M&A activity targeting consumables portfolios and strategic partnerships for algorithm validation under emerging software regulations.
Within the diversified conglomerate tier, Medtronic and Abbott Laboratories occupy positions anchored by integrated ECMO platforms and broad cardiovascular device portfolios. Getinge AB and MAQUET Holding exemplify the focused cardiovascular specialist archetype through proprietary oxygenation technology and specialized cannulae design. Terumo Corporation and LivaNova PLC represent precision manufacturing scale players with established regulatory pathways across multiple geographies. Fresenius Medical Care, operating through its XENIOS subsidiary, and Microport Scientific sit within the emerging market access tier, leveraging regional hospital network relationships and government-backed infrastructure investments.
| Leading Market Players |
|---|
| Medtronic |
| Getinge AB |
| Terumo Corporation |
| LivaNova PLC |
| Fresenius Medical Care (XENIOS) |
| Abbott Laboratories |
| MAQUET Holding |
| Microport Scientific |
| Nipro Medical |
| Others |
Value Network & Pricing Analysis
Magnetically levitated centrifugal pump adoption is compressing the cost-performance gap between transportable and traditional configurations while concentrating procurement leverage among integrated system vendors with captive consumables portfolios. This technology transition simultaneously elevates capital equipment pricing tiers for premium platforms and intensifies margin pressure on standalone component suppliers lacking bundled service offerings.
Pricing Analysis
Bundled disposable circuit contracts dominate hospital procurement, while unbundled capital equipment purchases persist in smaller cardiac centers lacking integrated vendor relationships. Three-tier pricing structure across premium magnetic-levitation platforms, standard centrifugal systems, and economy roller-pump configurations tracks certification grade and after-sales service bundling. Cost compression in standard-tier equipment is intensifying because corporate procurement committees centralize purchasing decisions at the enterprise level. Community hospitals and emerging market facilities exhibit highest price sensitivity, whereas academic medical centers prioritize performance specifications and training support over unit economics.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns serving tertiary hospital networks with 24-hour replenishment capabilities for disposable circuit components. Silicone membrane production concentrates in Baden-Württemberg and Osaka prefecture facilities, while precision cannulae manufacturing anchors in Japanese and German specialized suppliers. Single-source vulnerability in hollow-fiber oxygenator membrane supply creates exposure to polymer feedstock disruptions and specialized tooling capacity constraints. Distribution runs through manufacturer-direct field service organizations for capital equipment, with group purchasing organizations consolidating disposable volume across hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The VV ECLS market represents a late-cycle quality story where survival metrics and circuit longevity specifications increasingly determine procurement decisions over upfront capital cost. Intensivist training program expansion and bedside ECMO deployment are shifting demand toward premium integrated platforms with predictive monitoring capabilities.
For Market Incumbents: Lock in perfusionist training partnerships and service contract renewals before emerging transportable system vendors establish alternative staffing models. Defensive consolidation moves should prioritize captive consumables portfolio expansion and ISO 13485 certification investments that filter smaller competitors from EU MDR conformity assessments. Magnetic levitation technology licensing from German precision manufacturing specialists offers vertical integration leverage against roller-pump commoditization. For New Entrants and Emerging Players: Begin with algorithm validation partnerships for predictive clot detection software under EU AI Act requirements, where regulatory burden parity with incumbents is achievable. White-space targets include India's corporate hospital chains in Mumbai and Bangalore establishing ECMO programs with government-backed infrastructure investments, and regional trauma networks in the United States integrating mobile inter-hospital transfer capabilities. Go-to-market positioning should emphasize compact pump-oxygenator units with simplified cannulation protocols that reduce perfusionist dependency. For Investors and Strategic Acquirers: Valuations sit cheapest among precision component manufacturers with multi-geography regulatory certifications but limited consumables recurring revenue. Long-term viability over the five-to-ten year window hinges on software-enabled differentiation and service contract attachment rates rather than hardware shipment volumes. Acquisition target archetype: specialized membrane oxygenation technology holders with proprietary surface coating intellectual property. The signal to watch is FDA premarket approval timeline compression for high-risk cardiovascular devices, which will accelerate consolidation pressure on regulatory affairs-constrained mid-tier players.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Investment | Accelerated quality system recertification opens German and French tertiary center procurement to qualified manufacturers. |
| Hospital System Partnership | Single-source agreements with HCA Healthcare and CommonSpirit Health consolidate vendor relationships and displace fragmented purchasing. |
| Software Companion Development | Automated circuit monitoring algorithms under EU AI Act validation create differentiation for integrated system vendors. |
| Reimbursement Strategy | CMS Medicare coding alignment for acute respiratory distress syndrome protocols expands addressable patient populations. |
| CE Marking Pathway | Streamlined life-sustaining device assessments in Germany and France compress market access timelines for established quality systems. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and the United Kingdom, with primary inputs from each market's tertiary hospital networks and regulatory affairs specialists. Primary interviews with ECMO program directors, biomedical engineers, hospital purchasing committee members, and group purchasing organization contract managers combined with secondary validation from FDA 510(k) and PMA filings, EUDAMED device registrations, and hospital procurement databases. Bottom-up demand modeling triangulated against top-down manufacturer shipment estimates.
Rate-of-change decomposition across technology adoption curves, regulatory pathway timelines, and hospital capital expenditure cycles informed the analytical framework. Segmentation dimensions modeled include product type, end-user facility tier, membrane oxygenation versus blood pump technology, and acute respiratory distress syndrome versus cardiac surgery application. CAGRs derived from logistic diffusion curves for magnetic levitation penetration and intensity of use metrics for ICU bed expansion. Industry-specific inputs incorporated perfusionist workforce training capacity and EU AI Act algorithm validation requirements.
Several conditions sit outside the modeled scope, including pandemic-related demand surges, raw material supply disruptions, and geopolitical trade restrictions. Forecasts reflect documented assumptions regarding regulatory pathway stability and reimbursement code maintenance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Human Enhancement Market
Medical Devices
Global Wearable Injector Devices Market
Medical Devices
Global Peripheral IV Catheters Market
Medical Devices
Biliary Catheters Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Global Medical Device Contract Manufacturing Market
Medical Devices
Neurothrombectomy Devices Market
Medical Devices
Global Bone Cement Market
Medical Devices
France Spinal Surgery Devices Market
Medical Devices
Actigraphy Sensors & PSG Devices Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Surgical Display Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Asia-Pacific Digital Dentistry Market
Medical Devices
China Intrauterine Devices Market