
 Europe Specialty Generics Market | 2026-2036
Europe Specialty Generics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Specialty Generics Market Intelligence
The EU Green Deal is restructuring pharmaceutical procurement criteria across European hospital networks, favoring suppliers with verified carbon-reduced manufacturing. Teva Pharmaceutical Industries Ltd leverages its broad injectable portfolio to sustain contracts with centralized purchasing bodies in Germany and France. Fresenius Kabi AG anchors its position through captive parenteral production capacity, while STADA Arzneimittel AG differentiates via specialized hormone and CNS therapy formats.
Europe specialty generics comprise complex pharmaceutical products that replicate branded specialty medicines after patent expiry, typically requiring bioequivalence demonstration through advanced analytical methods such as Q1/Q2 sameness for parenteral formulations or in-vitro dissolution profiles for modified-release oral dosage forms. Their primary purpose is to expand patient access to high-cost therapies in oncology, neurology, and endocrinology while reducing reimbursement burdens on national health systems. Injectable products command premium positioning due to sterility assurance requirements and limited manufacturing capacity, whereas oral solid dosage forms compete on scale economics across retail pharmacy channels. Parenteral delivery modes attract concentrated investment from hospital buyers seeking secure supply of chemotherapy supportive care agents.
EMA's centralized marketing authorization procedure governs pan-European access, while national regulators such as Germany's BfArM and France's ANSM enforce supplementary pharmacovigilance and pricing negotiations that directly shape commercial viability. REACH and the EU F-Gas Regulation impose escalating compliance costs on active pharmaceutical ingredient synthesis and cold-chain distribution infrastructure. Stakeholders must monitor evolving EMA guidelines on complex generics and anticipate reimbursement recalibration as biosimilar competition intersects with specialty generic portfolios.
Market Dynamics
Hospital procurement centralization across Germany, France, and Italy is concentrating purchasing power into fewer buying entities, forcing specialty generic manufacturers to restructure pricing and supply assurance models around multi-year framework agreements rather than spot transactions.
Growth Catalysts
- EU Green Deal procurement mandates:Carbon-reduced manufacturing credentials are becoming mandatory selection criteria in French and German hospital tenders, advantaging suppliers with verified sustainable production.
- Injectable oncology demand:Parenteral chemotherapy supportive care agents are experiencing concentrated demand pull from oncology centers expanding across Spain and Poland.
- F-Gas Regulation compliance infrastructure:Cold-chain distributors investing in low-global-warming-potential refrigeration are securing preferred supplier status with national health systems prioritizing environmental performance.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient synthesis for complex parenterals remains concentrated among a limited set of European and Asian contract manufacturers, creating single-source vulnerability.
- REACH compliance cost escalation:Chemical registration and hazard assessment requirements under ECHA frameworks are elevating fixed costs for hormone and CNS therapy production.
- Biosimilar substitution pressure:EMA-approved biosimilars in oncology and immunology are capturing reimbursement preference over traditional specialty generics in several national formularies.
Strategic Opportunities
- Central and Eastern Europe hospital networks:Underpenetrated oncology centers in Romania, Bulgaria, and Hungary present expansion targets for injectable generic suppliers with EMA centralized authorizations.
- Continuous manufacturing adoption:Shift from batch to continuous processing for oral solid dosage forms offers quality assurance differentiation and regulatory pathway advantages.
- CSRD disclosure requirements:Early alignment with corporate sustainability reporting standards enables preferred positioning with procurement bodies integrating ESG metrics into supplier scorecards.
Industry Challenges
- Q1/Q2 sameness demonstration:Proving qualitative and quantitative equivalence for parenteral formulations requires specialized analytical capabilities and extended development timelines that compress margin realization.
- Sterility assurance validation:Aseptic processing capacity expansion demands capital-intensive isolator technology and cleanroom infrastructure with multi-year commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Specialty Generics Market |
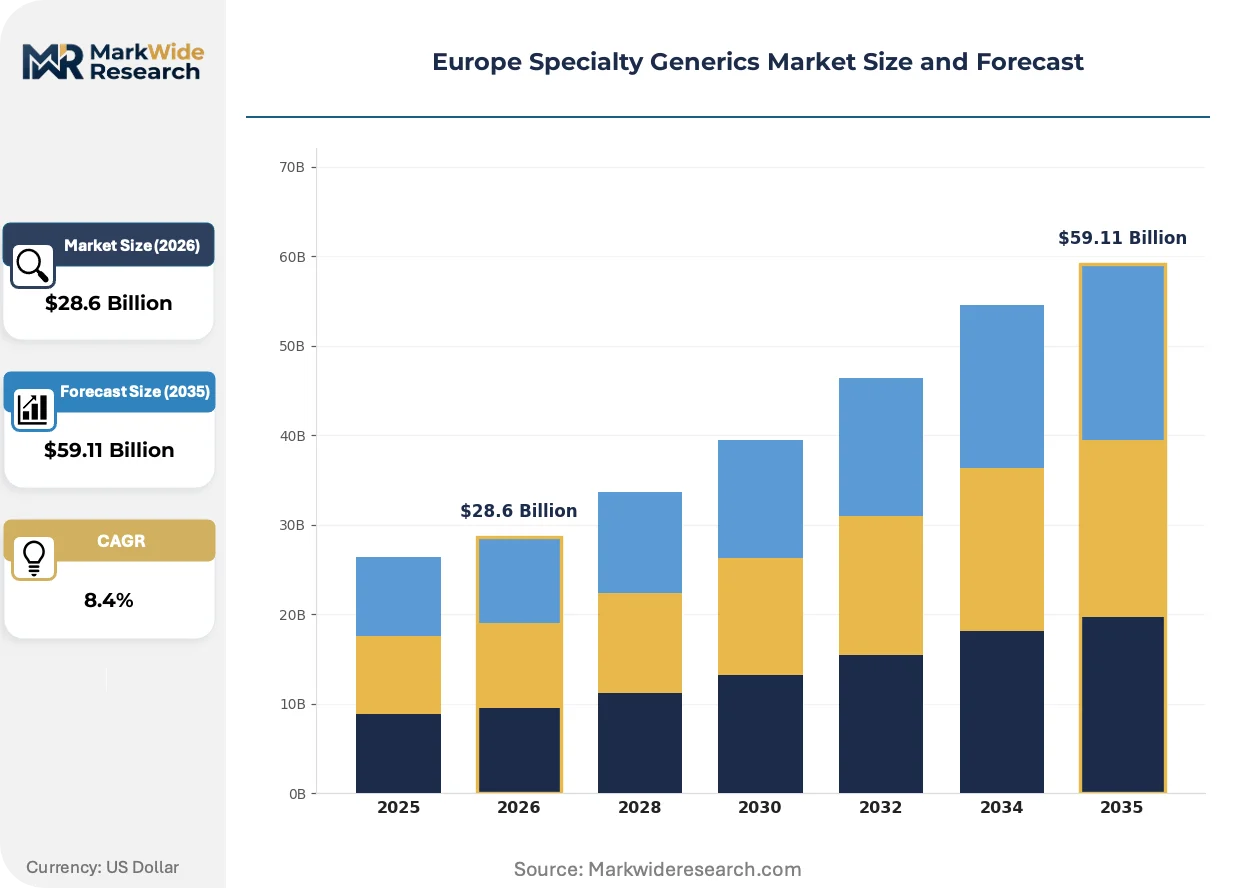
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectables, Tablets, Capsules, Creams Delivery Mode: Oral, Parenteral, Topical, Transdermal End User: Hospitals, Clinics, Homecare, Retail Pharmacies Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology |
| Companies Covered | Teva Pharmaceutical Industries Ltd, Viatris Inc, Fresenius Kabi AG, STADA Arzneimittel AG, Hikma Pharmaceuticals PLC, Novartis AG, Dr. Reddy’s Laboratories, Sandoz, Sun Pharmaceutical Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Specialty Generics Market Strategic Shifts & Innovations
Specialty generic production is pivoting from scale-centric batch operations toward flexible, quality-integrated manufacturing systems that align with evolving EMA guidance on complex product equivalence and hospital procurement sustainability requirements.
Continuous manufacturing technology for oral solid dosage forms is decentralizing production economics across European manufacturing networks. Mid-scale facilities in Portugal and Ireland are adopting modular continuous processing units that reduce batch failure risk and enable rapid product changeover. This technology is decentralizing geographic concentration of oral generic supply, enabling regional production hubs to serve national markets with reduced inventory carrying costs and compressed lead times.
The EU F-Gas Regulation is mandating phasedown of hydrofluorocarbon use in pharmaceutical cold-chain infrastructure by 2030. Refrigerated transport and warehouse operators are retrofitting fleets with CO2-based transcritical systems or ammonia alternatives. Parenteral distribution networks spanning the Benelux and Nordic regions are most affected, with logistics providers accelerating asset replacement to maintain contracts with hospital systems imposing environmental compliance deadlines.
Centralized hospital procurement bodies are consolidating supplier panels and demanding multi-year volume commitments with price predictability clauses. German university hospital alliances and French regional hospital groups are displacing fragmented purchasing with coordinated tenders covering oncology, anesthesia, and intensive care injectables. This consolidation is most visible in chemotherapy supportive care, where three-year framework agreements now dominate transaction patterns previously characterized by quarterly competitive bidding.
Europe Specialty Generics Market Segmentation
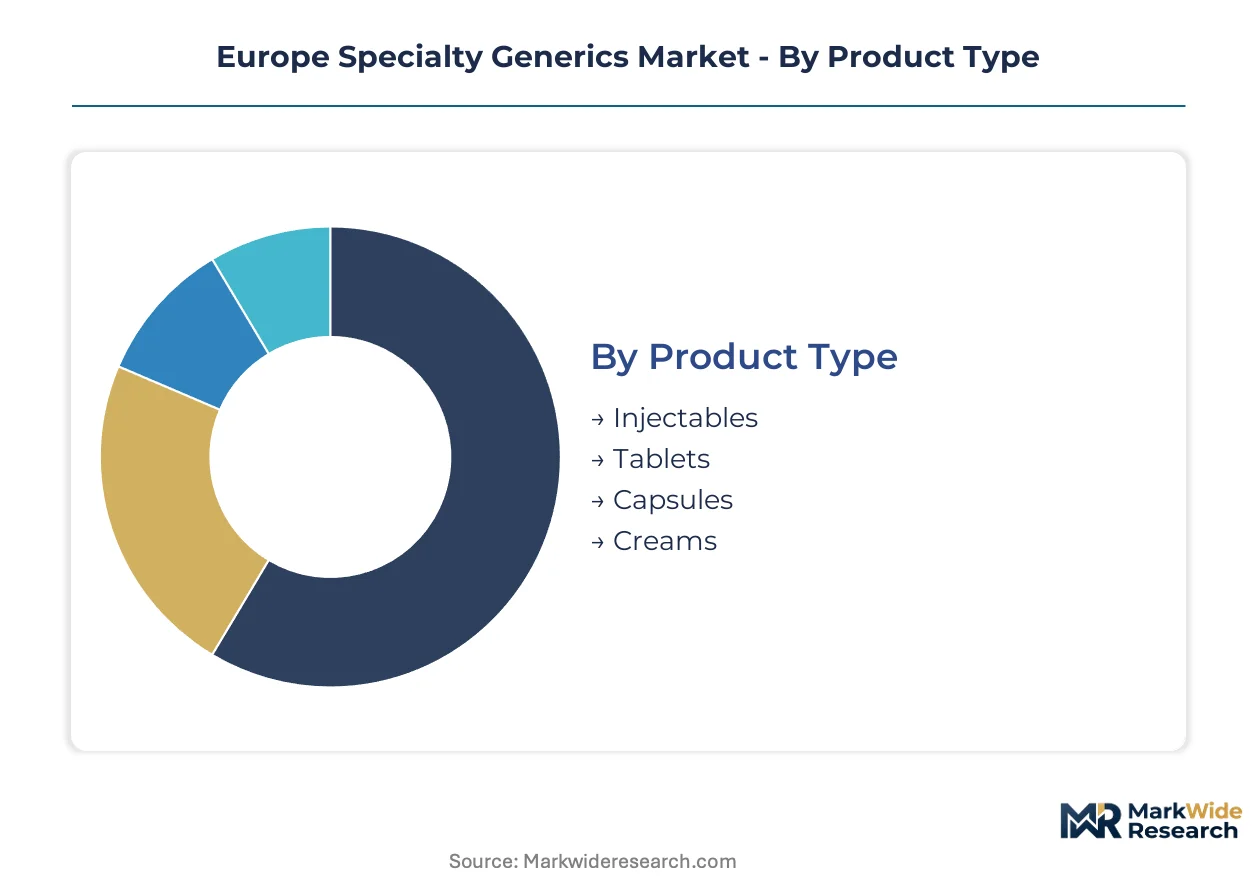
Specialty generics segmentation in Europe maps directly to manufacturing complexity tiers and procurement channel economics. Each dimension—product form, delivery route, care setting, and therapeutic focus—carries distinct regulatory pathways and margin structures that shape supplier strategy.
Product Type:
Supply concentration for sterile dosage forms creates divergent competitive dynamics across manufacturing investment thresholds.
- Injectables:Aseptic parenteral formulations requiring isolator technology and validated sterility assurance command premium positioning. Hospital oncology centers in Germany and France concentrate procurement of chemotherapy supportive care injectables through multi-year framework agreements, with limited qualified suppliers creating supply security premiums.
- Tablets:Oral solid dosage forms compete on scale economics and bioequivalence demonstration through in-vitro dissolution profiling. Continuous manufacturing adoption in Portugal and Ireland is decentralizing production networks and compressing batch failure risk for modified-release formulations targeting retail pharmacy channels.
- Capsules:Encapsulation of complex actives demands specialized excipient compatibility testing and moisture barrier validation.
- Creams:Semi-solid topical preparations require homogenization equipment and stability testing under ICH guidelines for European distribution.
Today's leader: Injectables. Tomorrow's challenger: Tablets with continuous processing differentiation.
Delivery Mode:
Route of administration determines cold-chain infrastructure requirements and reimbursement categorization across national health systems.
- Oral:Systemic absorption through gastrointestinal tract enables patient self-administration and retail pharmacy dispensing. Spain and Poland are expanding oral oncology generic access through hospital outpatient programs, with EMA centralized authorizations streamlining cross-border formulary inclusion.
- Parenteral:Direct vascular or tissue delivery bypasses first-pass metabolism for critical-care applications. REACH compliance costs for API synthesis and F-Gas Regulation mandates for refrigerated distribution are elevating barriers to parenteral supply chain participation.
- Topical:Localized dermal application minimizes systemic exposure for dermatological and localized pain indications.
- Transdermal:Rate-controlled absorption through intact skin requires adhesive matrix engineering and patch manufacturing precision.
Oral formats dominate volume; parenteral commands value per dose administered.
End User:
Procurement centralization is restructuring channel economics and supplier relationship models across European care settings.
- Hospitals:Centralized purchasing bodies in German university hospital alliances and French regional hospital groups are consolidating supplier panels for oncology, anesthesia, and intensive care injectables. EU Green Deal procurement mandates now require verified carbon-reduced manufacturing credentials in tender evaluations.
- Clinics:Outpatient specialist facilities concentrate demand for parenteral administration under medical supervision.
- Homecare:Patient-directed administration is expanding for pre-filled syringe and auto-injector formats with simplified training protocols.
- Retail Pharmacies:Community dispensing networks handle oral solid dosage form distribution with reimbursement price controls varying by national formulary.
Hospital procurement consolidation is the dominant demand-shaping force; homecare represents the steepest expansion trajectory.
Therapy Area:
Therapeutic focus determines clinical evidence requirements and biosimilar competitive intersection points.
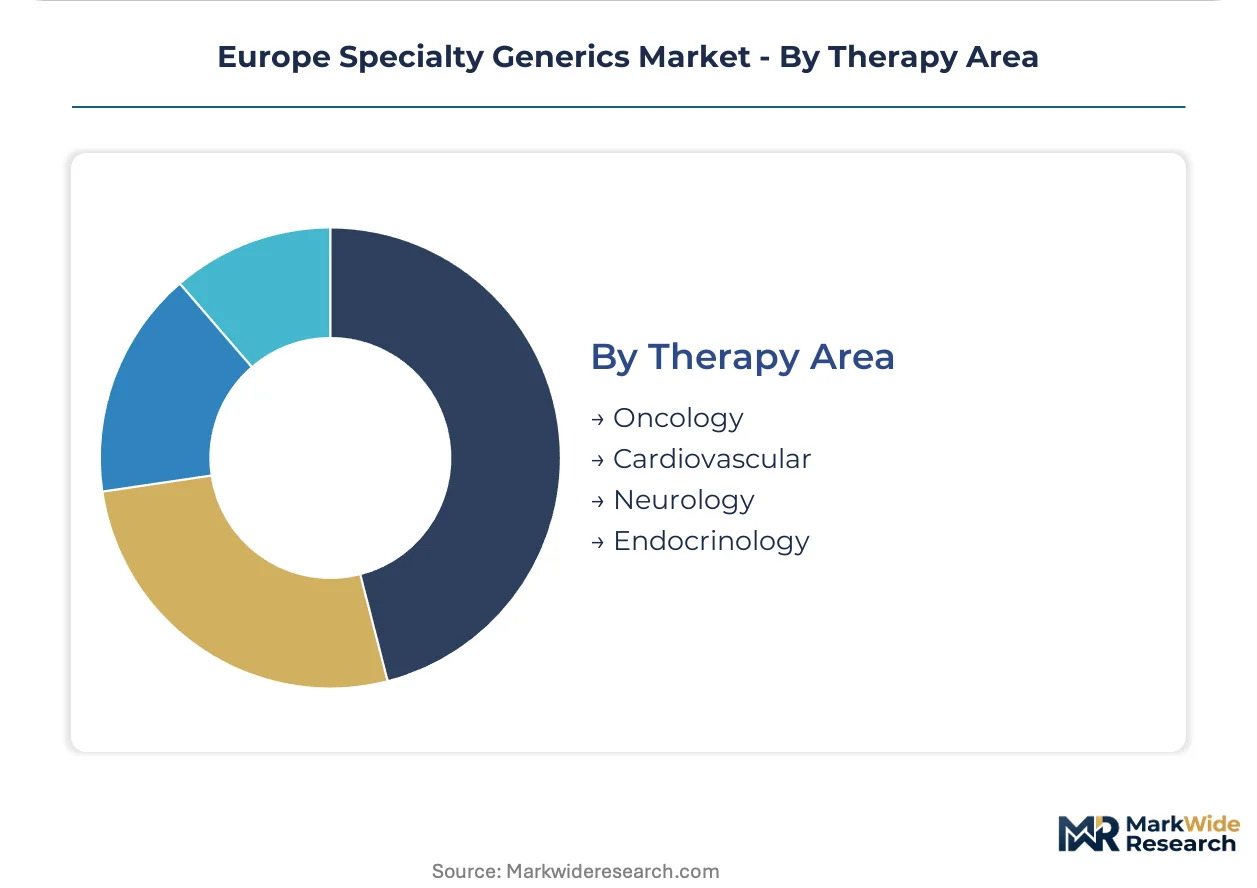
- Oncology:Chemotherapy supportive care agents and cytotoxic generics require validated handling protocols and specialized manufacturing containment. Oncology centers expanding across Central and Eastern Europe—Romania, Bulgaria, Hungary—present underpenetrated targets for EMA-authorized injectable suppliers.
- Cardiovascular:Chronic disease management through oral antihypertensive and anticoagulant generics competes on manufacturing scale and pharmacovigilance track record.
- Neurology:CNS-active formulations demand specialized bioequivalence studies and controlled-substance scheduling compliance.
- Endocrinology:Hormone therapies face REACH chemical registration burdens and complex stability profiles for peptide-based actives.
Oncology leads revenue concentration; neurology faces the tightest regulatory scrutiny.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized pharmaceutical formulation talent concentrates in Germany's Rhine-Main and Rhine-Ruhr corridors, anchoring Europe's sterile manufacturing capabilities and regulatory science expertise.
Germany
University hospital alliances in Baden-Württemberg and Bavaria drive concentrated procurement of chemotherapy supportive care injectables through multi-year framework agreements. BfArM enforces supplementary pharmacovigilance requirements that shape commercial timelines for hormone and CNS therapy launches. The Frankfurt-Rhine-Main cluster hosts captive parenteral production facilities serving centralized purchasing bodies across Hesse and North Rhine-Westphalia.
France
Regional hospital groups in Île-de-France and Auvergne-Rhône-Alpes consolidate oncology and anesthesia injectable demand into coordinated tenders with price predictability clauses. ANSM pricing negotiations directly determine reimbursement viability for complex generics entering the national formulary. The Lyon biocluster anchors specialized manufacturing for peptide-based endocrinology therapies facing REACH chemical registration burdens.
Italy
Lombardy and Emilia-Romagna concentrate demand for parenteral specialty generics through hospital procurement networks serving Milan and Bologna oncology centers. The EU Green Deal procurement mandates now require verified carbon-reduced manufacturing credentials in tender evaluations across northern Italian health systems. Pavia's pharmaceutical research corridor supports bioequivalence demonstration capabilities for modified-release oral dosage forms.
Spain
Oncology centers expanding across Madrid and Barcelona generate concentrated demand pull for EMA-authorized injectable chemotherapy agents. The F-Gas Regulation drives cold-chain distributors to retrofit refrigerated transport fleets serving hospital systems in Catalonia and the Basque Country. Valencia's manufacturing hub supports oral solid dosage form production for retail pharmacy channels under national price controls.
Poland
Hospital networks in Warsaw and Krakow expand access to parenteral oncology supportive care through EMA centralized marketing authorizations. The country's national pharmaceutical regulator aligns pharmacovigilance requirements with EMA guidance while maintaining distinct pricing negotiation frameworks. Wrocław's emerging pharmaceutical cluster attracts contract manufacturing investment for sterile dosage forms serving Central European markets.
Europe Specialty Generics Market Key Industry Players
Capital-heavy producers compete with asset-light portfolio specialists across Europe's specialty generics sector. The market structure tilts toward consolidated supply for sterile parenterals, where limited qualified manufacturers command premium positioning, while oral solid dosage forms fragment across scale-driven competitors. Three archetypes dominate: integrated pharmaceutical conglomerates with captive manufacturing, mid-cap specialists focused on injectable complexity, and diversified generics houses leveraging portfolio breadth. Competitive moves center on multi-year hospital framework agreements and sustainability credentialing aligned with EU Green Deal procurement mandates.
Among Israel-based pharmaceutical conglomerates, Teva Pharmaceutical Industries Ltd exemplifies the integrated archetype through broad injectable portfolio positioning. German specialists Fresenius Kabi AG and STADA Arzneimittel AG occupy distinct tier positions—one anchoring captive parenteral production capacity, the other differentiating through specialized therapeutic formats. These three represent the competitive spectrum from scale-integrated supply to focused therapeutic specialization.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd |
| Viatris Inc |
| Fresenius Kabi AG |
| STADA Arzneimittel AG |
| Hikma Pharmaceuticals PLC |
| Novartis AG |
| Dr. Reddy's Laboratories |
| Sandoz |
| Sun Pharmaceutical Industries |
| Others |
Cost & Logistics Intelligence
German university hospital alliances concentrate purchasing power into coordinated procurement bodies that negotiate multi-year framework agreements with price predictability clauses, anchoring a contract-based pricing model where volume commitments secure supply security premiums for qualified parenteral manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by sterility assurance grade and EMA authorization pathway. Premium positioning commands supply security premiums for isolator-produced oncology injectables, while standard tiers compete on bioequivalence validation speed and economy tiers face cost compression from centralized hospital procurement. French regional hospital groups exhibit highest price sensitivity in tender evaluations, whereas German oncology centers prioritize supply assurance over unit cost.
Supply Chain Analysis
API synthesis for complex parenterals rests on specialized European contract manufacturers and select Asian producers, with hormone and CNS therapy actives drawing from concentrated synthesis capacity in Germany and India. Cold-chain distribution hinges on F-Gas Regulation-compliant refrigeration infrastructure spanning the Benelux and Nordic regions. Single-source vulnerability in sterility assurance validation creates structural risk, while distribution feeds through national health system logistics networks with ESG credentialing requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European specialty generics stems from continuous manufacturing adoption compressing batch failure costs for oral solid dosage forms, while premium-tier positioning in parenteral oncology commands supply security premiums from consolidated hospital buyers.
For Market Incumbents: Acquire aseptic processing capacity with validated isolator technology to defend against biosimilar substitution pressure in oncology supportive care. Secure multi-year framework agreements with German university hospital alliances before EU Green Deal procurement mandates harden carbon-reduced manufacturing requirements. Backward integration into peptide-based API synthesis addresses REACH compliance cost escalation in endocrinology therapies. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer white-space entry into underpenetrated Central and Eastern European oncology centers in Romania, Bulgaria, and Hungary. Target EMA centralized authorization pathways for injectable chemotherapy supportive care agents, leveraging streamlined cross-border formulary inclusion. Position through CSRD-aligned sustainability disclosure to meet French and German hospital ESG scorecard integration. For Investors and Strategic Acquirers: Mid-cap pharmaceutical conglomerates with captive parenteral production are the most active acquirer in this space, seeking bolt-on sterile manufacturing capacity. Long-term viability hinges on continuous manufacturing technology deployment and cold-chain F-Gas compliance infrastructure. Watch EMA guidance evolution on complex generics equivalence as the inflection signal for regulatory pathway risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Adoption | Modular processing units in Portugal and Ireland reduce batch failure risk for modified-release oral dosage forms. |
| F-Gas Compliance Infrastructure | CO2-based transcritical refrigeration retrofits secure preferred supplier status with Nordic hospital systems. |
| EMA Centralized Authorization | Pan-European marketing approvals streamline formulary inclusion across Spanish and Polish oncology centers. |
| Multi-Year Framework Agreements | Three-year hospital procurement contracts displace quarterly competitive bidding in German chemotherapy supportive care. |
| CSRD Sustainability Disclosure | Early ESG metric alignment enables preferred positioning with French regional hospital group supplier scorecards. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down API manufacturing capacity tracking forms the analytical core of this study. Primary interviews with formulary directors, hospital procurement managers, regulatory affairs leads at EMA-authorized manufacturers, and payer access specialists combined with secondary validation from EMA centralized authorization databases, REACH registration filings, EU tender documentation, and national health system procurement records. Triangulation across stakeholder inputs and documentary sources ensures segment-level precision.
Historical trendline analysis of pricing trajectories and volume shifts across product type, delivery mode, care setting, and therapeutic focus dimensions informed projection modeling. CAGRs derive from regression-adjusted growth rates applied to base-year market sizing, with inputs including hospital procurement centralization indices, F-Gas Regulation compliance cost curves, and biosimilar substitution penetration rates across national formularies. Segmentation modeling captures manufacturing complexity tiers and procurement channel economics.
The model assumes a particular technology adoption path for continuous manufacturing; alternative pathways for batch-to-continuous transition timelines would alter the outlook. Forecasts reflect assumptions regarding EMA guidance stability, REACH cost trajectories, and hospital procurement consolidation velocity. A small set of triggers—biosimilar reimbursement preference shifts, F-Gas Regulation enforcement intensity, and centralized procurement body expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generics and Biosimilars
Global Adalimumab Drugs Market
Generics and Biosimilars
Europe Branded Generics Market
Generics and Biosimilars
Super Generics Market
Generics and Biosimilars
US Specialty Injectable Generics Market
Generics and Biosimilars
West Africa Generic Drug Market
Generics and Biosimilars
Adalimumab Market
Generics and Biosimilars
Latin America Generic Drug Market
Generics and Biosimilars
GCC Generic Drug Market