
 Ventricle Assist Device Market | 2026-2036
Ventricle Assist Device Market Size, Share, and Industry Trends Forecast 2026-2036
Ventricle Assist Device Market Analytics
Hospital procurement channels for ventricular assist devices is fragmenting as integrated delivery networks build direct relationships with manufacturers. Abbott leverages its structural heart portfolio to bundle VAD contracts with transcatheter valve programs. Medtronic sustains broad cath lab penetration that feeds downstream VAD referrals. Berlin Heart competes on pediatric mechanical support specialization with European regulatory pedigree.
A ventricle assist device is an electromechanical pump that supports cardiac circulation in patients with end-stage heart failure, typically operating at flow rates of 5 to 10 liters per minute while drawing power through a transcutaneous driveline or transcutaneous energy transfer system. Its primary purpose is to restore adequate systemic perfusion as bridge-to-transplant, bridge-to-recovery, or destination therapy when cardiac transplantation is unavailable or contraindicated. Left ventricular assist devices dominate installed base and revenue due to mature surgical techniques and established reimbursement, while total artificial heart systems occupy narrower but higher-acuity segments where biventricular failure precludes isolated left-sided support. Implantable delivery modes command premium positioning over extracorporeal configurations because they enable ambulatory patient management and reduce intensive care unit dependency.
FDA premarket approval pathways and CMS national coverage determinations shape United States market access timelines and reimbursement economics for new VAD entrants. EMA medical device regulation and notified body conformity assessments govern European commercialization, while Japan's PMDA sakigake designation accelerates review for innovative circulatory support technologies. Stakeholders must monitor evolving durability benchmarks and adverse event profiles as regulators tighten long-term safety requirements.
Market Dynamics
The convergence of transcutaneous energy transfer systems with miniaturized centrifugal pump architectures is compressing driveline infection rates while expanding ambulatory patient eligibility beyond traditional transplant center catchments.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated review pathways for next-generation VAD systems reduce commercialization timelines by 12-18 months, incentivizing R&D investment in magnetically levitated impeller technologies.
- Destination Therapy Reimbursement Expansion:CMS national coverage determinations now authorize durable mechanical circulatory support for non-transplant-eligible patients, broadening addressable populations in United States hospital systems.
- Aging Heart Failure Demographics:Germany and Japan exhibit sustained procedural volume growth as transplant waiting list mortality drives mechanical support adoption in patients over 65 years.
Market Restraints
- Titanium Alloy Supply Concentration:Biocompatible housing material sourcing clusters with three specialized foundries in Western Europe, creating vulnerability to aerospace sector demand surges.
- EMA MDR Transition Friction:European notified body capacity constraints extend conformity assessment timelines for novel VAD entrants, delaying commercial launches by 18-24 months.
- Transcatheter Heart Valve Substitution:MitraClip and transcatheter aortic valve replacement procedures capture intermediate heart failure patients who previously progressed to mechanical circulatory support.
Strategic Opportunities
- Pediatric Mechanical Support Underpenetration:Berlin Heart's EXCOR platform demonstrates scalable manufacturing templates for 5-15 kg patient segments where transplant availability remains critically constrained.
- Artificial Intelligence-Enabled Remote Monitoring:Machine learning algorithms analyzing pump power consumption patterns enable predictive thrombosis detection, creating service revenue streams beyond device implantation.
- Japan PMDA Sakigake Fast-Track:Priority review designation for innovative circulatory support technologies compresses regulatory timelines, rewarding first-mover investment in Japanese market entry.
Industry Challenges
- Perioperative VAD Specialist Scarcity:Cardiac surgery fellowship programs produce insufficient implanting surgeons relative to expanding destination therapy program demand across United States integrated delivery networks.
- Long-Term Durability Certification Burden:FDA post-approval study requirements for hemocompatibility and bearing wear mandate 5-year follow-up protocols that strain clinical trial infrastructure and delay label expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ventricle Assist Device Market |
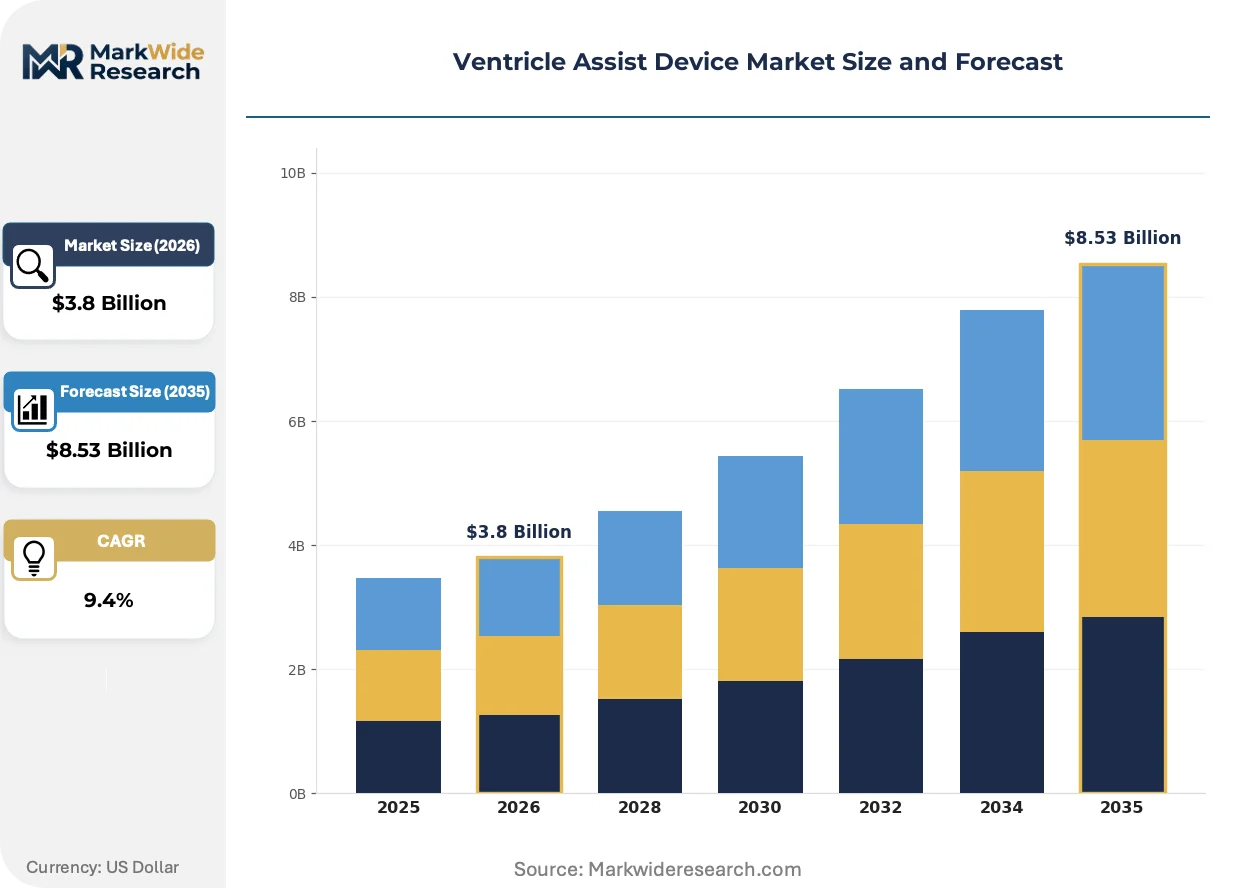
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Left Ventricular Assist Device, Right Ventricular Assist Device, Total Artificial Heart, Implantable Heart Pump Delivery Mode: Transcutaneous, Intravascular, Implantable, Extracorporeal End User: Hospitals, Cardiac Centers, Research Institutions, Specialty Clinics Indication: Heart Failure, Cardiomyopathy, Myocardial Infarction, Pulmonary Hypertension |
| Companies Covered | Abbott, ABIOMED, Medtronic, Berlin Heart, Jarvik Heart, Inc., Johnson & Johnson, SynCardia Systems, ReliantHeart, Inc., Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ventricle Assist Device Market Evolving Landscape
Digital twin simulation of patient-specific hemodynamics is compressing preoperative planning cycles while enabling personalized pump speed optimization that reduces adverse event profiles in destination therapy populations.
Fully magnetically levitated centrifugal pump designs eliminate mechanical bearing contact surfaces, reducing shear stress on formed blood elements. Academic medical centers in the United States and Germany are standardizing these platforms for bridge-to-transplant protocols. The technology is virtualizing traditional pulsatile flow paradigms by enabling continuous-flow physiology that mimics native cardiac output patterns through algorithmic speed modulation.
Japan's PMDA sakigake designation creates regulatory arbitrage opportunities for manufacturers prioritizing Asian market entry over European commercialization. Accelerated review timelines compress competitive windows for domestic Japanese manufacturers developing miniaturized implantable systems. Pediatric mechanical support applications receive disproportionate scrutiny under this framework, reflecting demographic priorities in Japan's congenital heart failure treatment protocols.
Hospital procurement committees are consolidating VAD vendor relationships around single-source contracts that bundle device acquisition with remote monitoring services and specialized nursing training. Integrated delivery networks in Texas and California are pioneering this consolidated purchasing model, displacing traditional multi-vendor cath lab arrangements. Germany's university hospital consortiums exhibit similar concentration patterns, favoring manufacturers with established structural heart portfolios that enable cross-product standardization.
Ventricle Assist Device Market Segmentation
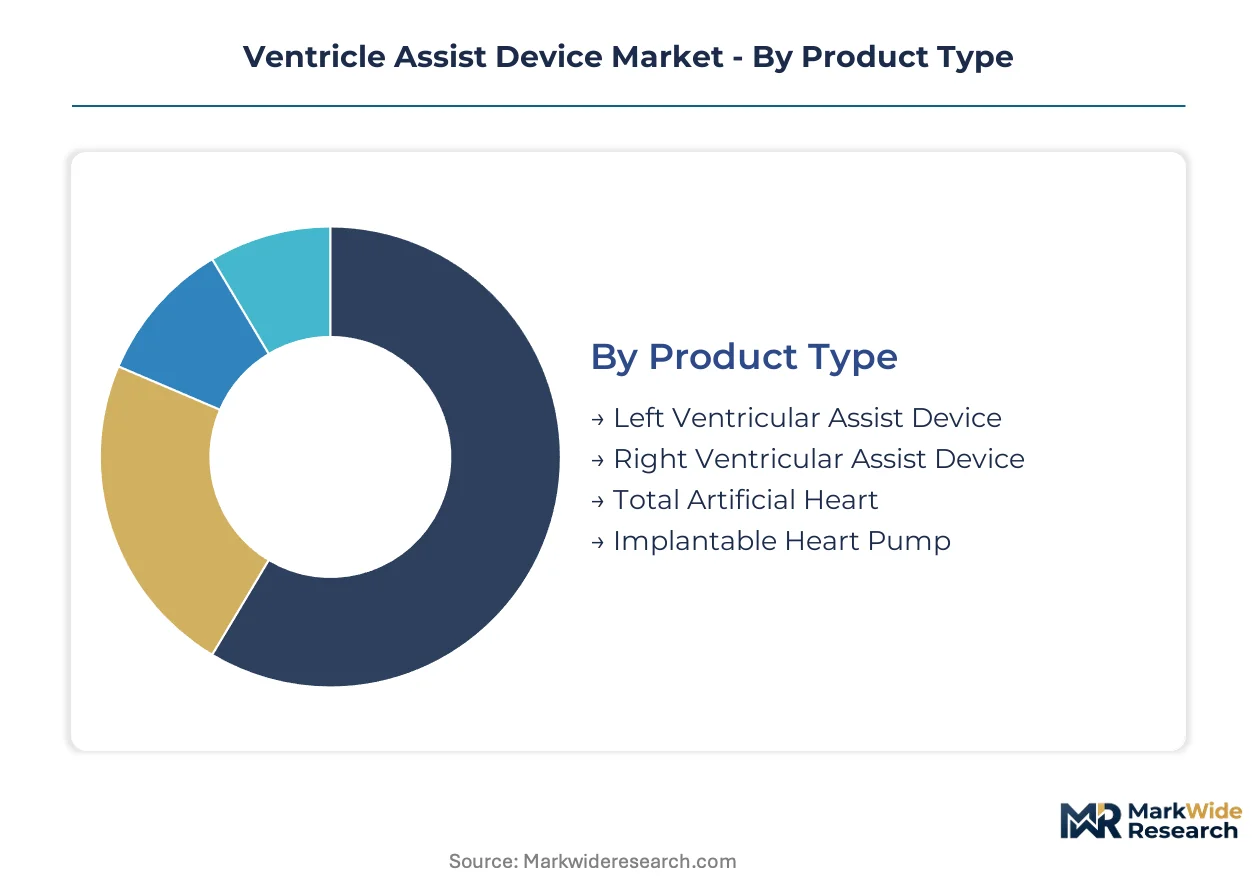
VAD market segmentation reveals distinct technology maturities and reimbursement pathways across product architectures. Delivery mode and end-user configurations determine procedural economics and patient eligibility criteria.
Product Type:
The use-case spectrum spans bridge-to-transplant protocols through permanent destination therapy, with each product architecture addressing specific ventricular failure patterns and patient hemodynamics.
- Left Ventricular Assist Device:Centrifugal or axial flow pumps supporting systemic circulation through left ventricular apex cannulation. Demand concentrates in United States transplant centers where CMS reimbursement authorization and established surgical volumes sustain implant growth. The HeartMate 3 and HVAD platforms dominate installed base through magnetically levitated bearing technologies that reduce thromboembolic events.
- Total Artificial Heart:Biventricular replacement systems occupying highest-acuity segments where isolated left-sided support proves insufficient. SynCardia's pneumatic driver technology captures this niche in German and United States academic medical centers managing irreversible biventricular failure. Device bulk and driver dependency limit ambulatory eligibility.
- Right Ventricular Assist Device:Temporary or durable support for isolated right heart failure, often deployed as biventricular configuration with LVAD.
- Implantable Heart Pump:Miniaturized systems enabling complete intrathoracic placement without abdominal pocket creation.
The dominant share belongs to Left Ventricular Assist Device, while Implantable Heart Pump configurations are closing the gap fastest through transcutaneous energy transfer miniaturization.
Delivery Mode:
Cost tier stratification separates premium implantable systems from temporary extracorporeal configurations, with reimbursement bandwidth determining hospital procurement patterns.
- Implantable:Fully internalized pumps with transcutaneous driveline or transcutaneous energy transfer, commanding highest reimbursement tiers through ambulatory patient management. United States integrated delivery networks prioritize these systems for destination therapy programs where ICU dependency reduction justifies acquisition costs.
- Transcutaneous:Percutaneous cannulation enabling rapid deployment in acute cardiogenic shock without sternotomy. German cardiac catheterization laboratories utilize these systems for bridge-to-decision protocols where transplant eligibility remains undetermined.
- Intravascular:Catheter-mounted microaxial pumps for temporary hemodynamic support.
- Extracorporeal:Paracorporeal pumps with external blood circuit, limited to intensive care settings.
Implantable systems capture the value concentration, though transcutaneous deployment is expanding most quickly through emergency department adoption.
End User:
Customer type differentiation reflects procedural complexity gradients and regulatory accreditation requirements across care settings.
- Hospitals:Comprehensive medical centers with cardiothoracic surgery programs, ECMO capabilities, and transplant affiliations. United States hospital systems in Texas and California are consolidating VAD programs within integrated delivery networks to capture CMS destination therapy reimbursement.
- Cardiac Centers:Specialized facilities with dedicated mechanical circulatory support teams and standardized protocols.
- Research Institutions:Academic medical centers conducting IDE trials and post-approval studies for FDA long-term durability requirements.
- Specialty Clinics:Outpatient VAD management programs focusing on driveline care and anticoagulation monitoring.
Hospitals retain the dominant patient volume, while Cardiac Centers are gaining share fastest through focused expertise and streamlined referral pathways.
Indication:
Application severity determines device selection, with chronic versus acute presentations dictating temporary versus durable support strategies.
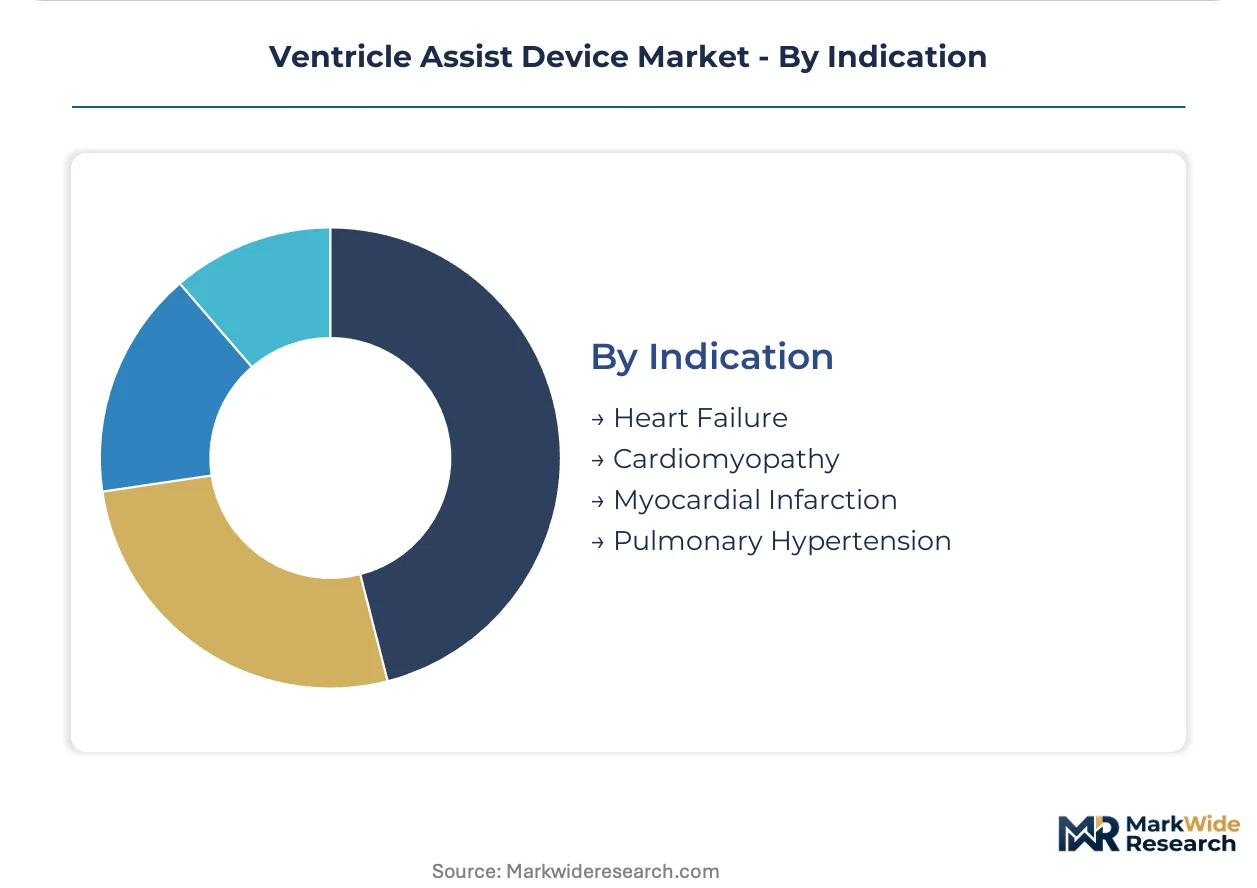
- Heart Failure:Chronic end-stage disease representing the primary addressable population, spanning ischemic and non-ischemic etiologies. Japan's aging demographic and transplant waiting list mortality sustain procedural growth in patients over 65 years where destination therapy replaces bridge-to-transplant candidacy.
- Cardiomyopathy:Structural myocardial disease including dilated and restrictive variants.
- Myocardial Infarction:Acute coronary events with cardiogenic shock requiring temporary mechanical support.
- Pulmonary Hypertension:Right heart failure indications where isolated RVAD or biventricular support becomes necessary.
Heart Failure indications command the dominant procedure volume, though Cardiomyopathy segments are climbing the fastest through improved early detection and referral protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German and Japanese benchmarks by margins reflecting CMS reimbursement bandwidth against constrained EMA pricing frameworks. Destination therapy program expansion in Texas and California integrated delivery networks sustains procurement premiums. Transplant waiting list mortality differentials between geographies directly shape mechanical circulatory support adoption curves.
United States
Bridge-to-transplant and destination therapy volumes concentrate in Texas Medical Center and Cleveland Clinic clusters where surgical fellowship pipelines feed program expansion. FDA breakthrough device designation for magnetically levitated pump platforms compresses commercialization timelines against standard PMA pathways. CMS national coverage determinations for durable mechanical circulatory support now authorize reimbursement for non-transplant-eligible patients over 65.
Germany
University hospital consortiums in Bavaria and North Rhine-Westphalia standardize biventricular support protocols for irreversible heart failure populations. EMA medical device regulation transition creates notified body capacity constraints extending conformity assessment timelines. Berlin Heart's EXCOR manufacturing base in Berlin anchors pediatric mechanical support supply for European transplant centers managing congenital heart failure.
Japan
Aging demographics and transplant waiting list mortality sustain procedural growth in patients exceeding 65 years where destination therapy replaces surgical candidacy. PMDA sakigake designation accelerates review timelines for innovative circulatory support technologies, rewarding first-mover investment. Tokyo and Osaka academic medical centers concentrate IDE trial activity for miniaturized implantable systems.
United Kingdom
NHS specialized commissioning frameworks concentrate VAD implantation in Harefield and Newcastle thoracic units with established mechanical circulatory support teams. MHRA post-Brexit regulatory autonomy enables divergence from EMA MDR implementation timelines. London integrated care systems are piloting remote monitoring reimbursement codes for ambulatory VAD management.
Canada
Provincial health authority procurement consolidates around single-source contracts bundling device acquisition with specialized nursing training. Health Canada medical device licensing pathways align with FDA PMA timelines for synchronous North American launches. Toronto and Vancouver transplant centers dominate national volume through established bridge-to-transplant surgical protocols.
Ventricle Assist Device Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biocompatible housings, magnetically levitated bearings, and transcutaneous energy transfer modules. Market structure consolidates around manufacturers with structural heart portfolios enabling cross-product bundling against standalone VAD pure-plays. Two strategic archetypes dominate: diversified cardiovascular conglomerates leveraging cath lab penetration for downstream referrals, and specialized mechanical circulatory support firms competing on pediatric or biventricular niches. Competitive moves center on integrated delivery network contract consolidation and remote monitoring service attachment to device sales.
Among diversified cardiovascular conglomerates, Abbott and Medtronic exemplify platform integrators bundling VAD contracts with transcatheter valve programs. Berlin Heart occupies the specialized tier, representing pediatric mechanical support concentration with European regulatory pedigree. These three anchors illustrate the competitive spectrum from broad structural heart portfolio leverage against narrow but defensible high-acuity specialization.
| Leading Market Players |
|---|
| Abbott |
| ABIOMED |
| Medtronic |
| Berlin Heart |
| Jarvik Heart, Inc. |
| Johnson & Johnson |
| SynCardia Systems |
| ReliantHeart, Inc. |
| Terumo Corporation |
| Others |
Value Network & Pricing Analysis
Titanium alloy foundry concentration across three Western European suppliers creates dual vulnerability to aerospace demand surges and export licensing friction, compressing margin structures for implantable pump manufacturers while forcing procurement committees toward multi-year offtake contracts that lock in biocompatible housing costs across premium and standard device tiers.
Pricing Analysis
Configured-to-order pricing for magnetically levitated centrifugal pumps commands spreads exceeding standard axial-flow configurations by margins reflecting customization depth and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA breakthrough designation status and remote monitoring attachment. Price erosion runs through transcutaneous temporary support segments as catheter-lab commoditization intensifies. Integrated delivery networks exhibit lowest price sensitivity due to CMS reimbursement bandwidth, while German university hospital consortiums negotiate hardest on per-unit acquisition costs.
Supply Chain Analysis
Biocompatible titanium alloy feedstock draws from specialized foundries in Germany, France, and Switzerland, with rare-earth magnet supply for levitated bearings resting on Chinese and Japanese processing capacity. Critical inputs span precision-machined pump housings, transcutaneous energy transfer coils, and implantable battery cells. Single-source vulnerability concentrates in magnet wire winding and sterile packaging sterilization capacity. Distribution runs through integrated delivery network procurement committees and GPO contracts that bundle device acquisition with specialized nursing training and remote monitoring subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote monitoring service layers attached to VAD implants are expanding faster than hardware revenue as predictive thrombosis detection algorithms create recurring subscription economics beyond single implantation events.
For Market Incumbents: Build regulatory data moats through FDA post-approval study infrastructure that newcomer entrants cannot replicate within viable commercialization timelines. Deepen backward integration into biocompatible titanium alloy sourcing through captive offtake agreements with German and French foundries. Transcatheter valve substitution in intermediate heart failure patients threatens downstream VAD referral pipelines, requiring structural heart portfolio bundling to defend cath lab penetration. For New Entrants and Emerging Players: Pursue pediatric mechanical support segments where Berlin Heart's dominance leaves white space in 5-15 kg patient configurations and Asian market entry protocols. Target Japan's PMDA sakigake fast-track pathway for miniaturized implantable systems, exploiting regulatory arbitrage against EMA MDR transition friction. Go-to-market positioning through academic medical center IDE trial partnerships accelerates clinical evidence generation ahead of commercial scale. For Investors and Strategic Acquirers: The market sits at a reimbursement-expansion phase that favors platform integrators with structural heart portfolio breadth over standalone VAD pure-plays. Five-to-ten year viability hinges on destination therapy program maturation and ambulatory patient management service attach rates. Acquisition target archetype: specialized mechanical circulatory support firms with pediatric or biventricular niches and European regulatory pedigree. Signal to watch: CMS remote monitoring reimbursement code expansion as inflection indicator for service revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Integrated delivery network contracts bundle VAD acquisition with transcatheter valve programs and remote monitoring services. |
| Reimbursement Strategy | CMS national coverage determination alignment unlocks destination therapy authorization for non-transplant-eligible patient populations. |
| Software Companion Development | Machine learning algorithms analyzing pump power consumption enable predictive thrombosis detection and recurring service revenue. |
| FDA Submission | Premarket approval pathways for magnetically levitated bearing technologies compress commercialization timelines against standard PMA review. |
| CE Marking Pathway | EMA MDR conformity assessment navigation addresses notified body capacity constraints delaying European commercial launches. |
Research Methodology
A standing panel of cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview rounds, supplemented by FDA PMA filings, CMS national coverage determinations, EMA MDR transition guidance documents, and hospital procurement database extracts. Bottom-up implant volume modeling triangulated against top-down reimbursement bandwidth analysis across United States, German, and Japanese health systems.
Scenario-bracketing around regulatory approval timelines, reimbursement expansion trajectories, and transcatheter substitution effects shaped projection boundaries across the analysis window. Segmentation dimensions spanned product architecture, delivery mode configuration, end-user facility type, and indication severity. CAGRs derived from procedural volume trajectories weighted by CMS and EMA pricing frameworks. Industry-specific inputs incorporated transplant waiting list mortality differentials and destination therapy eligibility expansion protocols.
Sensitivities concentrate around EMA notified body capacity recovery, titanium alloy aerospace demand diversion, and transcatheter valve substitution rates in intermediate heart failure. Forecasts reflect documented assumptions regarding regulatory pathway compression and reimbursement authorization breadth. Cross-checking against CMS Medicare claims data and hospital cost report filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Medical Device Regulatory Affairs Market
Medical Devices
Global Extremities Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Smart Patches Market
Medical Devices
Global Transradial Access Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
India Clear Aligners Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Peripheral Embolization Device Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Anti-Decubitus Dynamic Mattress Market
Medical Devices
Robotic Angiography Systems Market
Medical Devices
High Tibial Osteotomy (HTO) Plates Market
Medical Devices
Global Microelectronic Medical Implants Market