
 Incubator Devices Market | 2026-2036
Incubator Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Incubator Devices Market Foresight
EU MDR is consolidating the cost-of-entry calculus for incubator manufacturers seeking CE-marked distribution across European member states. GE Healthcare leverages its installed base of forced-air warming platforms to sustain service revenue streams in tertiary maternity centers. Drägerwerk AG & Co. KGaA anchors its competitive stance through precision thermal regulation engineering that dominates neonatal transport applications. Thermo Fisher Scientific Inc. differentiates via laboratory incubator portfolios that extend into pharmaceutical stability testing workflows.
Incubator devices are enclosed thermal regulation systems that maintain controlled temperature, humidity, and oxygen environments through convection, forced air, or water bath mechanisms, typically operating within ranges critical for neonatal survival or cell culture viability. Their primary commercial purpose centers on reducing thermoregulatory stress in premature infants and ensuring reproducible growth conditions for biological specimens. Transportable product types command premium positioning due to emergency transfer protocols between maternity centers and pediatric intensive care facilities, while laboratory configurations face margin compression from commoditized convection technology. End-user demand from pharmaceutical companies is accelerating fastest as cell and gene therapy manufacturing scales require validated hybrid control platforms.
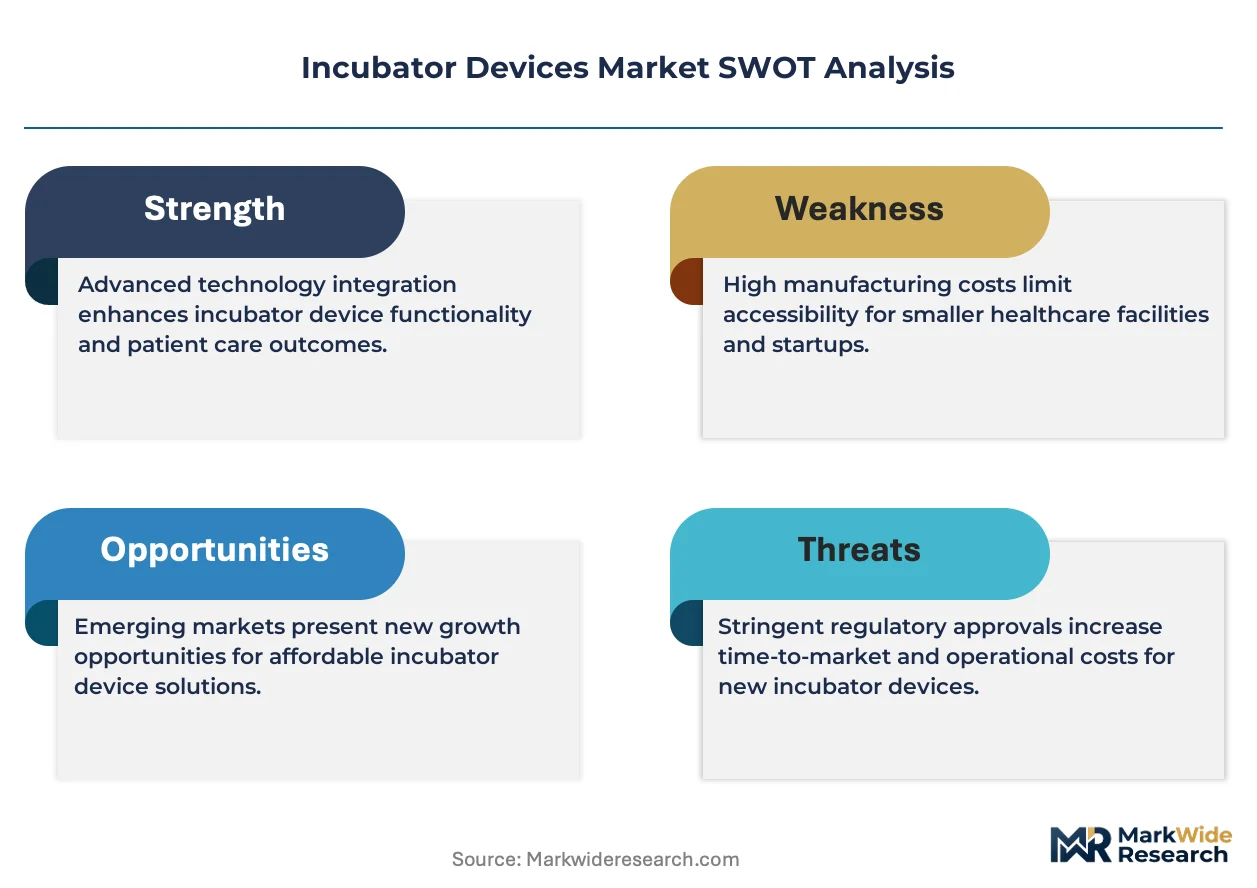
FDA premarket notification pathways and EU MDR conformity assessment frameworks shape product development timelines and clinical evidence requirements for US and European market access. BIS certification in India and NMPA registration in China add further compliance layers for manufacturers targeting hospital procurement tenders in Asia-Pacific jurisdictions. Stakeholders must monitor evolving electromagnetic compatibility standards and software-as-medical-device classifications that could reclassify digital control modules under stricter oversight regimes.
Market Dynamics
EU MDR conformity assessment timelines are compressing product development cycles while forcing manufacturers to consolidate thermal stability validation capabilities under single quality management systems. This regulatory density is reshaping competitive entry barriers across neonatal and laboratory incubator segments.
Growth Catalysts
- Neonatal transport protocols:Emergency transfer mandates between maternity centers and pediatric intensive care facilities are expanding procurement of mobile thermal regulation units with integrated oxygen delivery.
- EU MDR thermal stability requirements:Stricter conformity assessment for alarm systems and temperature uniformity is driving replacement demand for legacy incubator fleets in German university-affiliated perinatal centers.
- Cell therapy manufacturing scale-up:Pharmaceutical companies are deploying validated hybrid control platforms for reproducible growth conditions in gene therapy production workflows.
Market Restraints
- Precision sensor supply concentration:German and Japanese component suppliers dominate high-accuracy temperature probe manufacturing, creating input bottlenecks for mid-tier incubator assemblers.
- EU MDR notified body capacity:Limited designation of conformity assessment organizations under the 2017/745 regulation is extending CE marking timelines by 8-14 months for thermal regulation devices.
- Commoditized convection technology:Standard laboratory incubators face margin erosion from low-cost Asian manufacturers offering basic thermal control without validated documentation packages.
Strategic Opportunities
- India hospital procurement modernization:BIS certification requirements and government maternity infrastructure programs are creating first-mover advantages for compliant thermal regulation suppliers in tier-2 cities.
- Software-as-medical-device convergence:Digital control modules with predictive thermal algorithms are absorbing service revenue streams from traditional hardware maintenance contracts.
- Hybrid neonatal-laboratory platforms:Cross-functional incubators serving both clinical emergency transport and pharmaceutical stability testing are opening premium pricing tiers.
Industry Challenges
- Electromagnetic compatibility engineering talent:Shortage of specialists capable of integrating IEC 60601-1-2 compliant shielding into compact transportable designs is constraining product iteration velocity.
- Legacy system integration complexity:Hospital IT departments face mounting friction connecting new incubator alarm networks to existing patient monitoring architectures without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incubator Devices Market |
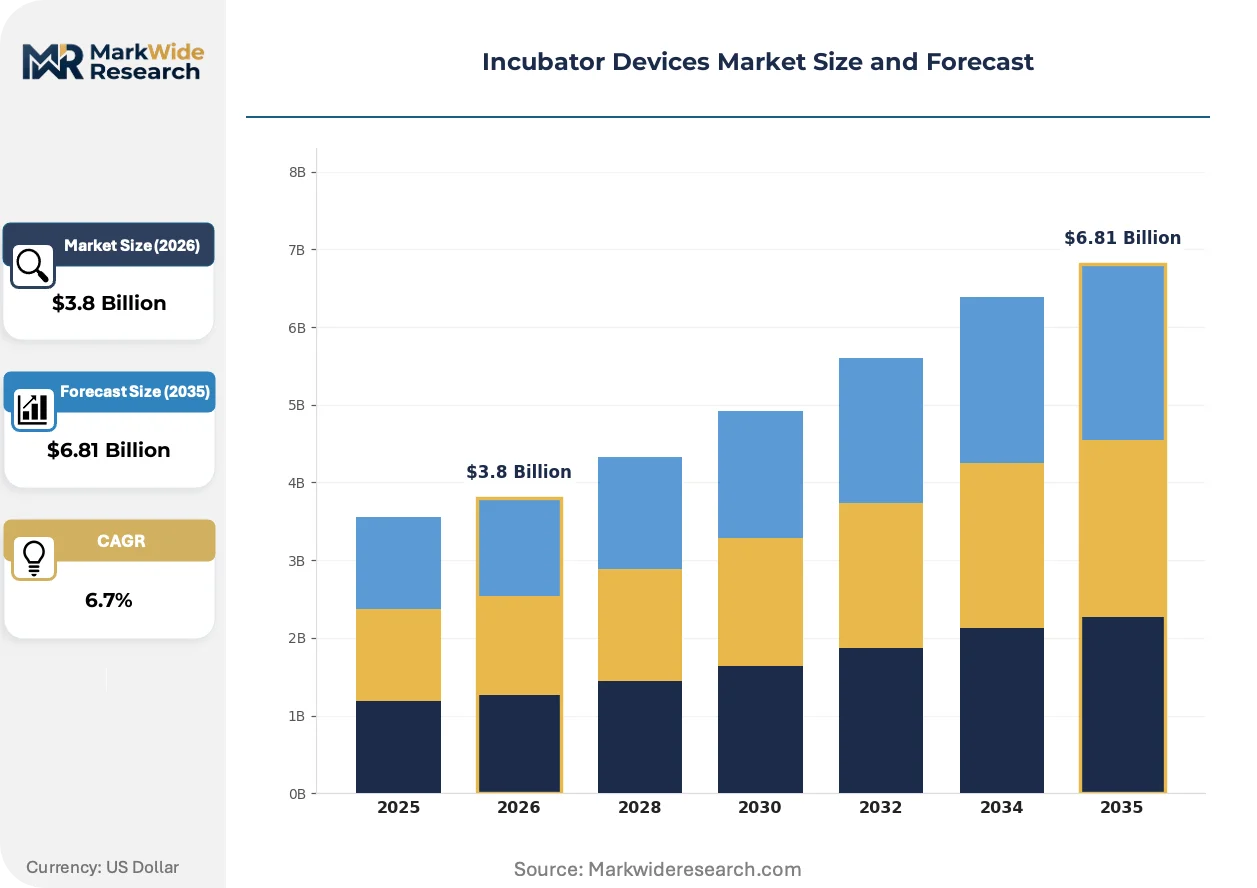
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sirona, Transportable, Laboratory, Portable Technology: Convection, Forced Air, Water Bath, Duo-Thermal End User: Research Institutes, Hospitals, Maternity Centers, Pharmaceutical Companies Usage Mode: Electromechanical, Manual, Digital, Hybrid |
| Companies Covered | GE Healthcare, Drägerwerk AG & Co. KGaA, Atom Medical Corporation, Andreas Hettich GmbH & Co. KG, BMT Medical Technology sro, Thermo Fisher Scientific Inc., PHC Corporation, Phoenix Medical Systems (P) Ltd, Ningbo David Medical Device Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incubator Devices Market Shifts & Advancements
Active thermal management architectures are displacing passive convection designs across both clinical and laboratory applications. This shift is compressing development timelines while expanding the addressable market for precision environmental control.
Phase-change material thermal buffering is absorbing peak load demands in transportable neonatal incubators, enabling battery-powered operation during ambulance transfers without compressor cycling. German emergency medical services are adopting these units for rural maternity center evacuations. The technology is absorbing margin pressure from conventional forced-air warming platforms by reducing mechanical component count.
EU MDR post-market surveillance requirements are mandating systematic thermal performance data collection across installed device fleets. Manufacturers must now maintain vigilance systems tracking temperature deviation events and alarm response times. Laboratory-grade incubator suppliers are responding by embedding continuous monitoring electronics that automate compliance documentation.
Pharmaceutical quality departments are unbundling after-sales service contracts from initial capital purchases, demanding itemized validation support and calibration scheduling. This procurement pattern shift is disrupting traditional distributor relationships in North American and European markets. Cell therapy contract manufacturers are driving this behavior, requiring documented thermal mapping for every production batch.
Incubator Devices Market Segmentation
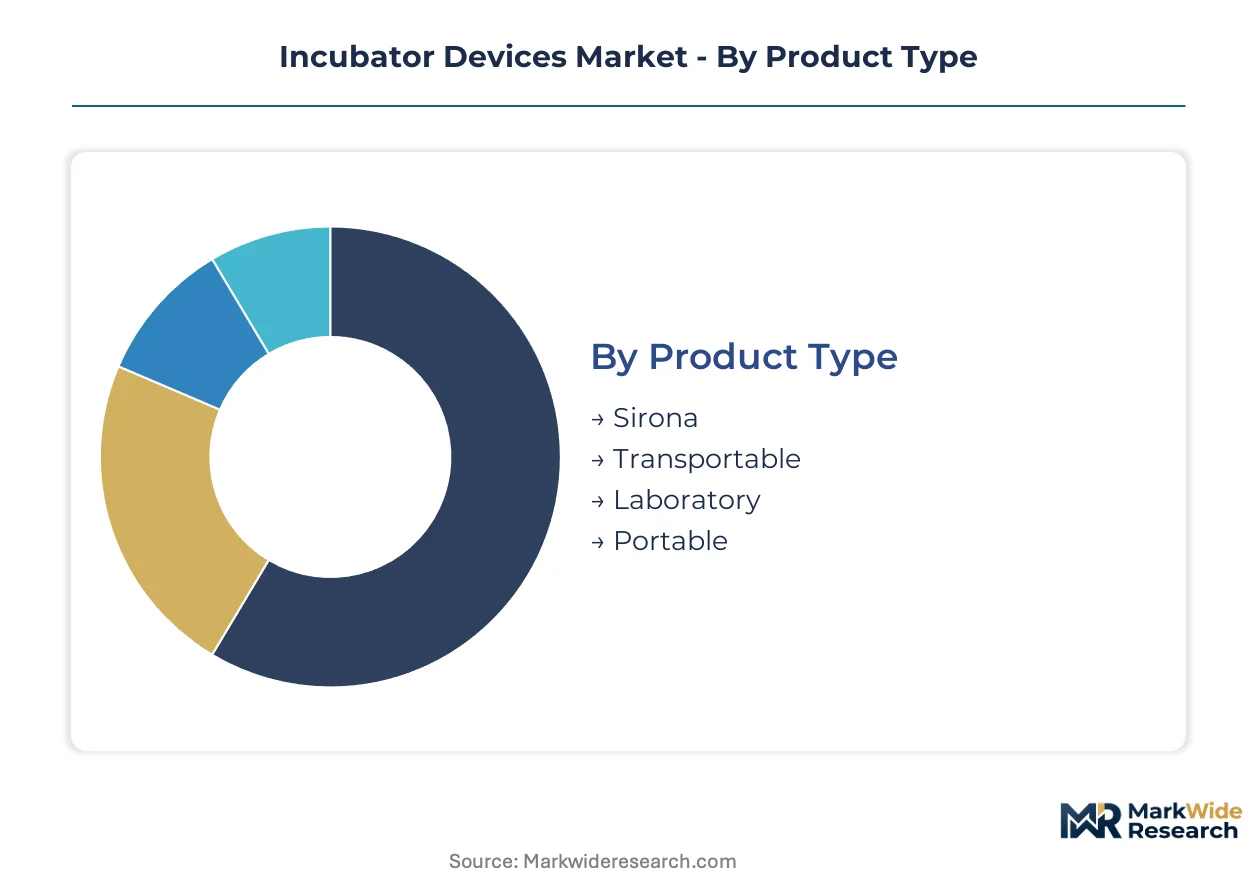
Incubator device procurement splits sharply between premium validated systems for pharmaceutical manufacturing and volume-oriented units for basic neonatal care. Understanding these tiered demand patterns reveals where margin compression and technology differentiation concentrate across the competitive landscape.
Product Type:
Volume concentration sits in standard neonatal units for hospital maternity wards, while premium positioning attaches to transportable and hybrid platforms serving emergency medical protocols.
- Transportable:Battery-powered thermal regulation systems integrate oxygen delivery and phase-change material buffering for ambulance transfers. German emergency medical services and rural maternity evacuation networks in Bavaria and Saxony drive replacement demand for these units.
- Laboratory:Validated hybrid control platforms maintain reproducible temperature, humidity, and gas environments for cell culture and pharmaceutical stability testing. Thermo Fisher Scientific anchors this segment through service contracts with gene therapy manufacturers requiring documented thermal mapping per production batch.
- Sirona:Fixed-installation neonatal intensive care units with forced-air warming and integrated patient monitoring interfaces.
- Portable:Lightweight convection-based units for temporary thermal stabilization in field medical settings or disaster response deployments.
Mature deployment sits with Sirona fixed-installation systems in established perinatal centers. Newer deployment is concentrated in transportable units serving inter-facility emergency transfer protocols.
Technology:
Cost tier separation runs from commodity convection designs facing Asian manufacturer competition to precision forced-air and hybrid systems commanding validation premiums.
- Forced Air:Active thermal management architectures displace passive designs through compressor-driven temperature uniformity and rapid recovery from door openings. GE Healthcare sustains service revenue streams by leveraging installed base relationships in tertiary maternity centers across the United States.
- Duo-Thermal:Hybrid platforms combine convection and conductive heating with redundant sensor arrays for pharmaceutical manufacturing workflows. Cell therapy contract manufacturers in Massachusetts and North Carolina deploy these systems for reproducible growth conditions under FDA process validation requirements.
- Convection:Basic passive heating through natural air circulation without active compressor control.
- Water Bath:Immersion-based thermal regulation for laboratory applications requiring precise temperature stability without air turbulence.
Commoditized deployment sits with convection technology from low-cost manufacturers. Validated deployment is concentrated in duo-thermal platforms serving pharmaceutical quality departments.
End User:
Application concentration shifts from clinical emergency care toward pharmaceutical manufacturing as cell and gene therapy production scales.
- Pharmaceutical Companies:Validated hybrid control platforms with continuous monitoring electronics automate EU MDR post-market surveillance documentation. These users unbundle after-sales service contracts from capital purchases, demanding itemized calibration scheduling and thermal mapping support.
- Hospitals:Neonatal intensive care units procure transportable incubator units for emergency transfer protocols between maternity centers and pediatric intensive care facilities. University-affiliated perinatal centers in Germany drive replacement cycles for laboratory-grade systems under tightened EU MDR conformity assessment.
- Research Institutes:Academic laboratories utilize standard convection and water bath incubators for biological specimen growth without pharmaceutical validation requirements.
- Maternity Centers:Primary care birthing facilities deploy basic thermal regulation units for initial neonatal stabilization before potential transfer.
Established procurement sits with hospital neonatal intensive care units. Steepest expansion trajectory is concentrated in pharmaceutical companies scaling cell therapy manufacturing capacity.
Usage Mode:
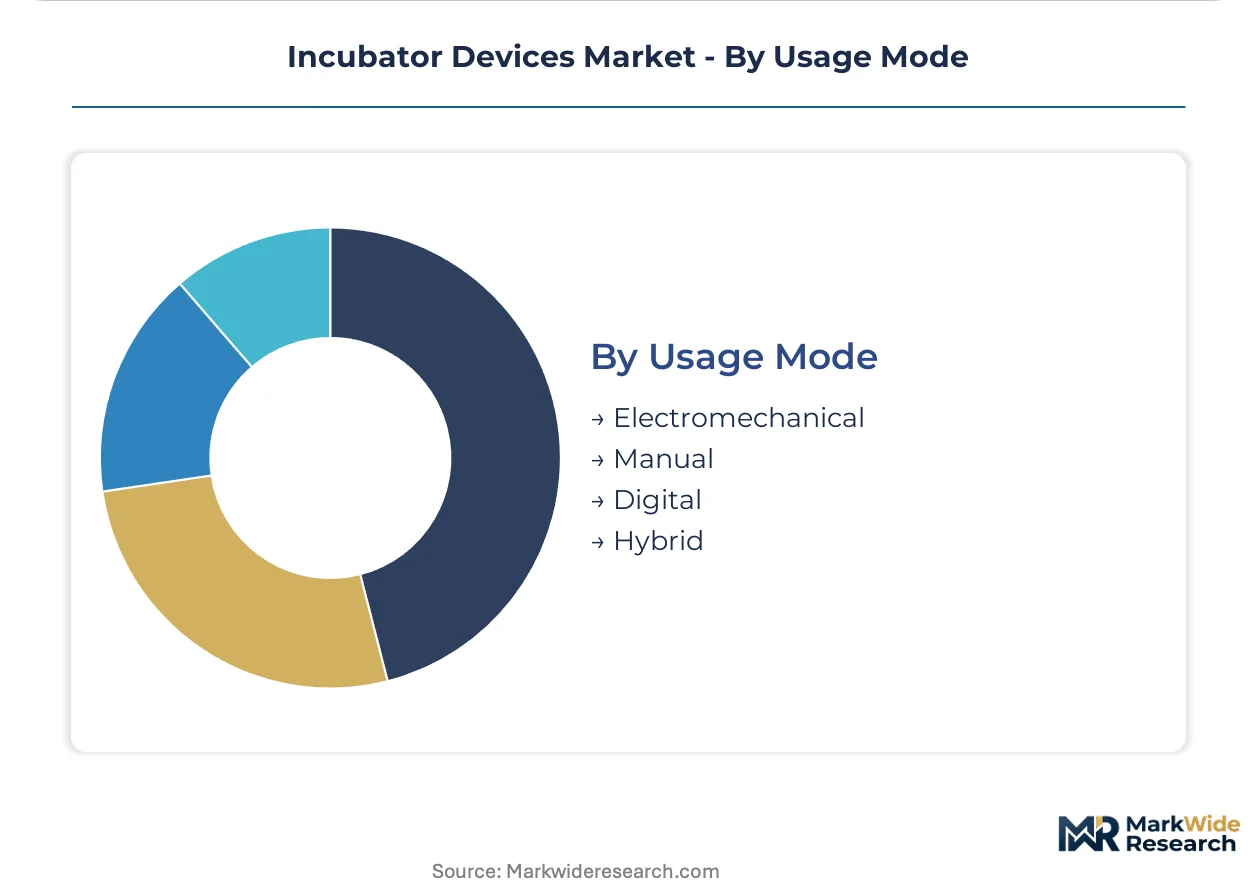
Customer type separation distinguishes between electromechanical and manual systems for cost-sensitive settings versus digital and hybrid platforms for regulated environments.
- Digital:Software-as-medical-device control modules with predictive thermal algorithms absorb service revenue from traditional hardware maintenance contracts. These systems face evolving electromagnetic compatibility standards and potential reclassification under stricter oversight regimes.
- Hybrid:Electromechanical base platforms with digital overlay for alarm networking and patient monitoring integration. Hospital IT departments encounter friction connecting these units to existing architectures without full infrastructure replacement.
- Electromechanical:Traditional relay-based control systems without software-dependent functionality.
- Manual:Basic thermostat regulation without automated alarm or monitoring capabilities.
Legacy deployment sits with electromechanical systems in under-resourced clinical settings. Connected deployment is concentrated in hybrid platforms serving integrated patient monitoring networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for incubator devices concentrates in Germany, the United States, China, India, and Japan, where neonatal care infrastructure expansion and pharmaceutical manufacturing scale-up create differentiated procurement patterns across clinical and laboratory segments.
Germany
University-affiliated perinatal centers in Bavaria and Saxony drive replacement cycles for laboratory-grade incubator systems. EU MDR conformity assessment requirements for thermal stability and alarm systems are tightening procurement specifications for hospital systems. Berlin-Brandenburg clusters anchor precision engineering supply chains serving transportable incubator manufacturers.
United States
Tertiary maternity centers in Massachusetts and North Carolina scale validated hybrid control platforms for cell therapy contract manufacturing. FDA premarket notification pathways shape product development timelines for neonatal intensive care unit equipment. Greater Boston pharmaceutical corridors absorb premium-priced laboratory incubators with documented thermal mapping capabilities.
China
NMPA registration requirements add compliance layers for manufacturers targeting hospital procurement tenders in tier-2 cities. Government maternity infrastructure programs accelerate domestic production capacity for basic neonatal thermal regulation units. Yangtze River Delta medical device clusters concentrate assembly operations for convection-based laboratory systems.
India
BIS certification requirements and government maternity infrastructure programs create first-mover advantages for compliant thermal regulation suppliers. Hospital procurement modernization in Maharashtra and Gujarat expands addressable markets for transportable emergency units. Delhi-NCR distribution networks channel mid-tier incubator imports into northern state health systems.
Japan
PMDA regulatory frameworks enforce electromagnetic compatibility standards for digital control modules in neonatal applications. METI industrial policy supports precision sensor manufacturing for high-accuracy temperature probe supply. Kanto region medical device exporters serve Southeast Asian hospital procurement through technology licensing arrangements.
Incubator Devices Market Competitive Landscape
German producers anchor the premium engineering tier; American and Japanese specialists hold validated laboratory segments. The vendor base splits between consolidated multinational platforms with installed base service relationships and regional assemblers competing on capital cost. Three archetypes dominate: precision thermal regulation engineers, pharmaceutical validation specialists, and volume-oriented maternity ward suppliers. Strategic moves concentrate on M&A for notified body capacity and geographic expansion into Indian and Chinese certification frameworks.
Within the precision engineering tier, Drägerwerk AG & Co. KGaA and Andreas Hettich GmbH & Co. KG exemplify German Mittelstand manufacturers with deep thermal regulation expertise. GE Healthcare occupies a position spanning clinical installed base leverage and service revenue capture. Thermo Fisher Scientific Inc. represents the pharmaceutical validation archetype, anchoring laboratory-grade portfolios through documented compliance support. Ningbo David Medical Device Co., Ltd. sits within the volume-oriented Asian fabrication cluster. Phoenix Medical Systems (P) Ltd exemplifies emerging market specialists navigating BIS certification requirements.
| Leading Market Players |
|---|
| GE Healthcare |
| Drägerwerk AG & Co. KGaA |
| Atom Medical Corporation |
| Andreas Hettich GmbH & Co. KG |
| BMT Medical Technology sro |
| Thermo Fisher Scientific Inc. |
| PHC Corporation |
| Phoenix Medical Systems (P) Ltd |
| Ningbo David Medical Device Co., Ltd |
| Others |
Supply & Pricing Matrix
Captive integration into precision sensor manufacturing anchors pricing power for German and Japanese component suppliers dominating high-accuracy temperature probe production. This upstream control insulates premium-tier manufacturers from margin erosion while forcing mid-tier assemblers into commodity positioning.
Pricing Analysis
Volume concentration in standard neonatal units faces margin compression from low-cost Asian manufacturers, while transportable and hybrid platforms command premium positioning through validated documentation packages. Price differentiation hinges on EU MDR certification grade and after-sales service bundling. Cost compression in laboratory-grade convection systems is intensifying because pharmaceutical quality departments now unbundle validation support from capital purchases. Hospital procurement committees in tier-2 cities exhibit highest price sensitivity; gene therapy contract manufacturers show least sensitivity due to FDA process validation requirements.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of precision temperature probes and electromagnetic compatibility shielding components. Manufacturing concentration centers on Germany for transportable neonatal systems, the United States for pharmaceutical-grade hybrid platforms, and China for basic convection laboratory units. Raw material dependencies include phase-change thermal buffering compounds, high-grade aluminum alloys for chassis fabrication, and medical-grade sensor arrays. Tariff exposure on precision electronics from Japanese suppliers threatens margin stability for European manufacturers. Distribution runs through hospital group purchasing organizations in North America, government procurement tenders in India, and direct sales relationships with pharmaceutical quality departments in Massachusetts and North Carolina.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR conformity assessment timelines and notified body capacity constraints are forcing consolidation among incubator manufacturers unable to sustain extended certification cycles. Weaker players lacking thermal stability validation capabilities face exit pressure.
For Market Incumbents: Deploy installed base service relationships to capture recurring revenue from predictive thermal algorithm modules. GE Healthcare and Drägerwerk AG sustain competitive moats by integrating digital control upgrades into legacy forced-air warming platforms. Backward integration into precision sensor supply reduces exposure to German and Japanese component bottlenecks. Incumbents must absorb software-as-medical-device reclassification risks through preemptive electromagnetic compatibility engineering investment. For New Entrants and Emerging Players: Government maternity infrastructure programs in Maharashtra and Gujarat offer white-space entry for BIS-certified transportable units. Tier-2 Indian cities present the most penetrable geography due to hospital procurement modernization and limited incumbent service presence. Contract manufacturing partnerships with Yangtze River Delta medical device clusters enable cost-competitive convection platform assembly without captive validation infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in precision thermal regulation engineering specialists with EU MDR notified body relationships. Long-term viability over the analysis window favors manufacturers with hybrid neonatal-laboratory platform portfolios serving both clinical emergency transport and pharmaceutical stability testing. Acquisition target archetypes include German Mittelstand precision engineering firms and Indian BIS-certified regional assemblers. The signal to watch is electromagnetic compatibility standard revisions that could trigger software module reclassification and reshape competitive barriers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Capacity Acquisition | CE marking timeline compression secures market access for thermal regulation devices. |
| Phase-Change Material Thermal Buffering Integration | Battery-powered ambulance operation reduces mechanical component count in transportable units. |
| Software-as-Medical-Device Control Module Development | Predictive thermal algorithms absorb service revenue from traditional hardware maintenance contracts. |
| Hybrid Neonatal-Laboratory Platform Launch | Cross-functional design opens premium pricing tiers for emergency transport and pharmaceutical testing. |
| India BIS Certification Pathway Investment | First-mover positioning in Maharashtra and Gujarat government maternity infrastructure programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with neonatal intensive care unit directors, hospital procurement committee members, biomedical engineers, pharmaceutical quality department heads, and GPO contracts managers combined with secondary validation from FDA premarket notification databases, EU MDR notified body registries, BIS certification listings, and NMPA registration records. Bottom-up modeling of installed base replacement cycles and top-down triangulation against pharmaceutical manufacturing capacity expansion supported demand estimation.
Granularity-level framing applied country-specific regulatory cluster modeling for Germany, the United States, China, India, and Japan alongside product-type segmentation across transportable, laboratory, Sirona fixed-installation, and portable configurations. Technology-tier differentiation between forced-air, duo-thermal, convection, and water bath systems informed margin structure assumptions. End-user splits across pharmaceutical companies, hospitals, research institutes, and maternity centers shaped volume allocation. CAGRs were derived from replacement cycle analysis and manufacturing capacity scaling trajectories. Forecast inputs incorporated EU MDR post-market surveillance data collection mandates and cell therapy manufacturing scale-up patterns in Massachusetts and North Carolina.
Caveats apply where electromagnetic compatibility standard revisions or software-as-medical-device reclassifications could materially shift the outlook for digital control module suppliers. Forecasts reflect assumptions about notified body designation timelines, precision sensor supply continuity, and pharmaceutical validation documentation requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intrathecal Pumps Market
Medical Devices
Artificial Respirator Market
Medical Devices
Spain Ultrasound Devices Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
North America Wheelchair Market
Medical Devices
Global Artificial Tendons and Ligaments Market
Medical Devices
Medical Face Shield Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Tear Duct Plugs Market
Medical Devices
Medical Device Cros Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Latin America Biomedical Sensors Market
Medical Devices
Veterinary Equipment and Disposables Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Global Active Implantable Medical Devices Market