
 Global Systemic Lupus Erythematosus Drugs Market | 2026-2036
Global Systemic Lupus Erythematosus Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Systemic Lupus Erythematosus Drugs Market Analysis
Specialist hospital networks are rotating demand toward biologic induction protocols for refractory systemic lupus erythematosus patients. GSK plc leverages its established belimumab manufacturing footprint to anchor supply security across North American and European infusion centers. AstraZeneca competes through anifrolumab's differentiated type I interferon mechanism, while F. Hoffmann-La Roche Ltd sustains rituximab's off-label positioning through extensive real-world evidence programs.
Systemic lupus erythematosus drugs comprise pharmaceutical agents targeting autoimmune-mediated tissue inflammation, with biologics engineered as monoclonal antibodies against B-cell survival factors or interferon receptors requiring cold-chain distribution at 2-8°C. These therapies suppress pathogenic autoantibody production and reduce end-organ damage in lupus nephritis, cutaneous, and neuropsychiatric manifestations. Biologics command the deepest margin pools due to biosimilar lag and infusion administration complexity, while oral antimalarials anchor maintenance-phase volume through hydroxychloroquine's first-line guideline position. Subcutaneous delivery is gaining fastest among self-administered biologics, though intravenous retains dominance in hospital-based induction protocols.
The FDA's Breakthrough Therapy and Accelerated Approval pathways shape development priorities for lupus drug candidates, while EMA's PRIME designation and conditional marketing authorization create parallel European access routes. REACH compliance and EudraLex Volume 4 GMP standards govern active pharmaceutical ingredient sourcing and biologic manufacturing facility qualification across EU member states. Stakeholders must monitor FDA advisory committee posture on confirmatory trial requirements for accelerated approvals, as withdrawal risk for lupus biologics would reshape prescriber confidence and payer contract terms.
Market Dynamics
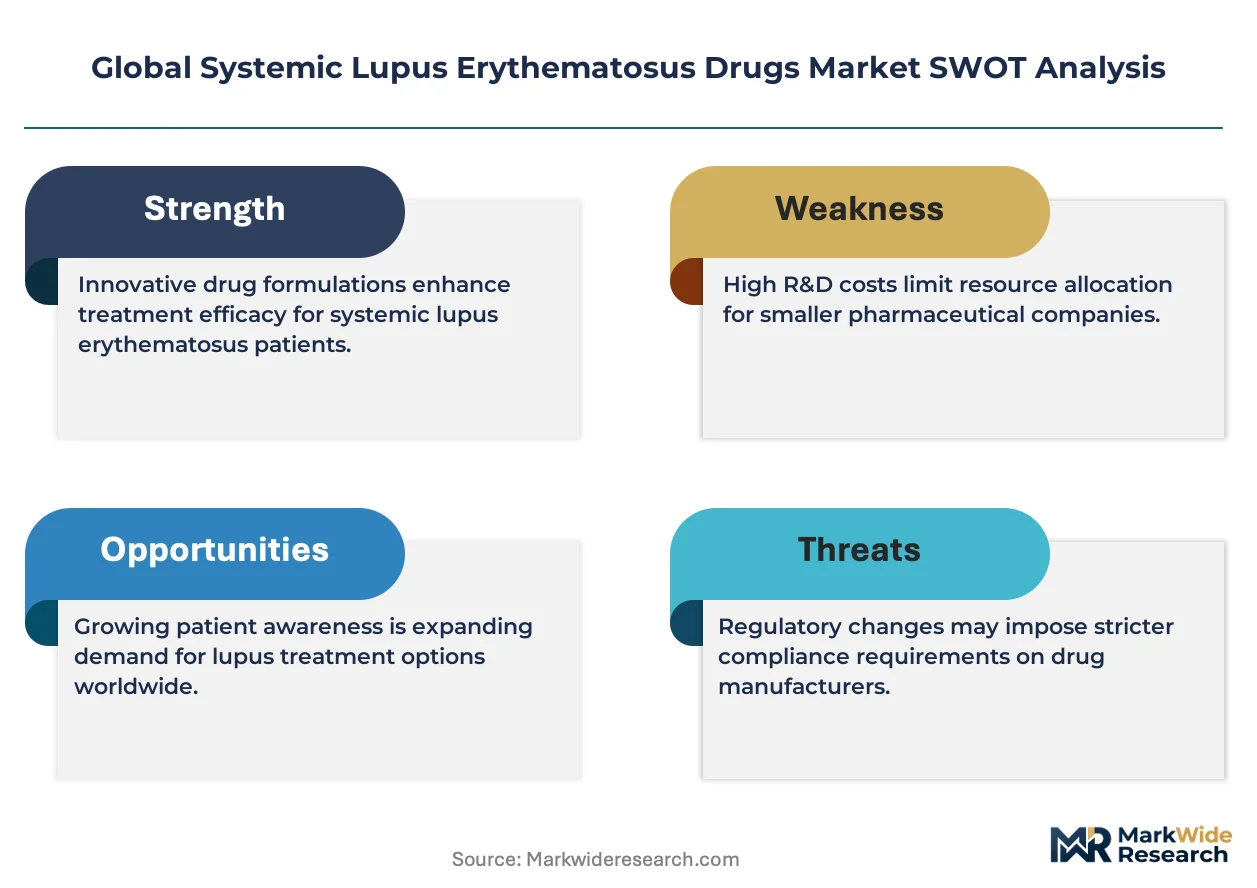
Biologic cold-chain infrastructure expansion is concentrating manufacturing investment around infusion-capable hospital networks, while FDA accelerated approval timelines compress development-to-commercialization cycles for monoclonal antibody candidates.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review pathway compresses clinical-to-market timelines for lupus biologics targeting unmet refractory populations.
- Specialist Infusion Network Expansion:Hospital systems in the United States and Germany are adding dedicated rheumatology biologic suites to capture high-acuity SLE patient volumes.
- Real-World Evidence Integration:EMA's adaptive pathways framework now accepts registry data as confirmatory evidence, enabling earlier European market access for type I interferon receptor antagonists.
Market Restraints
- Biosimilar Lag Complexity:Biologics maintain extended exclusivity periods due to manufacturing process patent thickets and immunogenicity concerns that delay substitutability determinations.
- Cold-Chain Distribution Cost:Temperature-controlled logistics for 2-8°C monoclonal antibodies impose 15-25% cost premiums versus small-molecule distribution networks.
- Prior Authorization Friction:US commercial payers require step-therapy documentation and specialist attestation that delays biologic initiation by 30-90 days for newly diagnosed patients.
Strategic Opportunities
- Subcutaneous Self-Administration:Prefilled syringe and autoinjector formats for B-cell targeting biologics unlock home-based maintenance dosing and reduce infusion center dependency.
- Japan's Sakigake Designation:PMDA's priority review system offers 50% fee reductions and dedicated consultation for lupus nephritis candidates with novel mechanisms.
- Lupus Nephritis Protocol Expansion:Renal biopsy-driven patient stratification creates addressable subpopulations for complement inhibition and anti-BDCA2 therapies outside broad SLE labels.
Industry Challenges
- Confirmatory Trial Execution:Accelerated approvals require post-marketing efficacy studies that strain recruitment in rare SLE phenotypes and risk regulatory withdrawal.
- Biologic Manufacturing Scale-Up:Single-use bioreactor capacity constraints and cell line stability issues create batch-to-batch variability that complicates supply security planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Systemic Lupus Erythematosus Drugs Market |
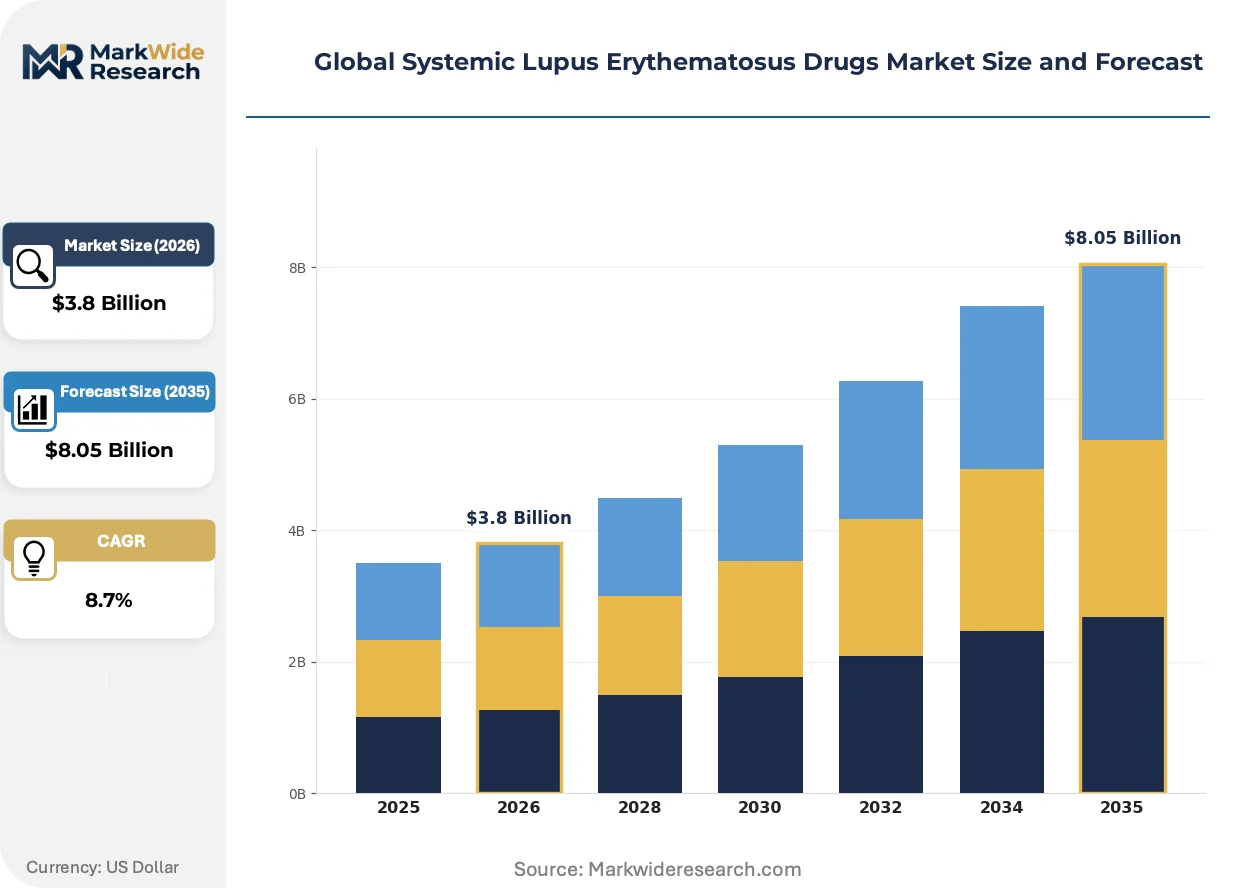
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Antimalarials, Immunosuppressants, Biologics Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Hospitals, Clinics, Homecare, Research Institutions Treatment Phase: Induction, Maintenance, Acute Attack, Long-term Management |
| Companies Covered | GSK plc, AstraZeneca, F. Hoffmann-La Roche Ltd, Bristol-Myers Squibb Company, Pfizer Inc., Sanofi, Novartis AG, Eli Lilly and Company, UCB S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Systemic Lupus Erythematosus Drugs Market Emerging Trajectories
Mechanism diversification and administration format innovation are fragmenting competitive positioning across the SLE therapeutic landscape, with interferon pathway modulation emerging as a distinct axis from B-cell depletion strategies.
Subcutaneous biologic delivery is bifurcating patient management models between hospital-based induction and home-based maintenance. Rheumatology practices in the United States and France are adopting hybrid protocols that transition stable patients from IV belimumab to SC formulations after six-month response confirmation. This shift compresses infusion center revenue per patient while expanding addressable prescriber pools to community rheumatologists without infusion infrastructure.
EMA's PRIME designation and conditional marketing authorization frameworks are reshaping European launch sequencing for lupus candidates. Developers now prioritize Germany and France for initial commercialization to leverage centralized health technology assessment precedents that influence subsequent national reimbursement. This regulatory concentration accelerates access for type I interferon receptor antagonists but creates two-tier availability lag for peripheral EU markets.
Patient registry integration into payer contracting is altering procurement evaluation criteria. US commercial insurers and England's NICE are incorporating SLEDAI response rates from national lupus cohorts into formulary placement decisions, displacing traditional clinical trial endpoint comparisons. This behavioral shift most visibly impacts biologic positioning in integrated delivery networks that operate their own disease registries and can generate internal effectiveness benchmarks.
Global Systemic Lupus Erythematosus Drugs Market Segmentation
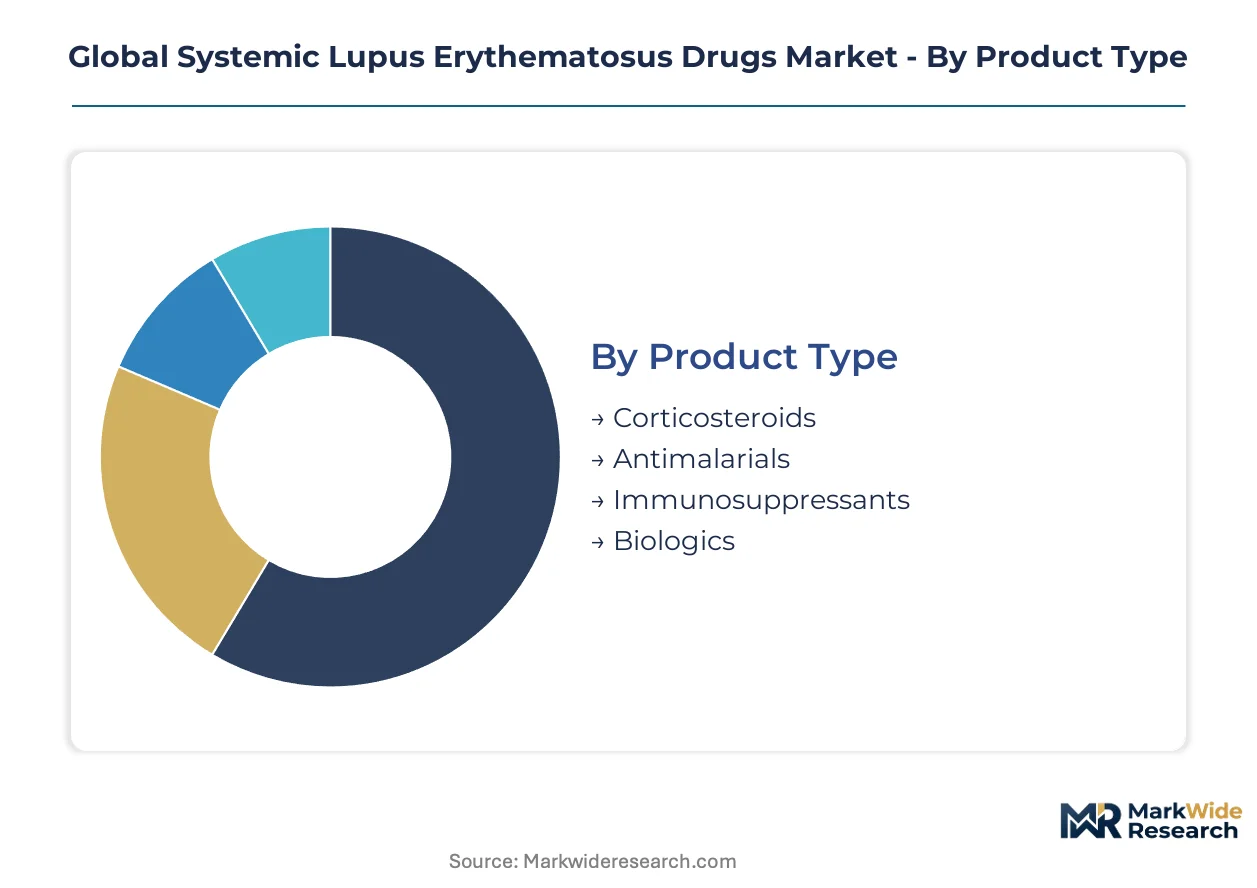
Segmentation in systemic lupus erythematosus therapeutics reveals distinct margin architectures across administration formats and care settings. Product type stratification separates commodity small-molecules from biologic premium tiers, while delivery mode choices determine patient access pathways and reimbursement complexity.
Product Type:
Biologics capture the deepest margin pools within this category due to manufacturing complexity and cold-chain requirements, while oral maintenance therapies anchor volume through first-line guideline positioning.
- Biologics:Monoclonal antibodies engineered against B-cell survival factors or type I interferon receptors require 2-8°C distribution and specialist infusion infrastructure. Demand concentrates in United States academic medical centers and German university hospitals serving refractory lupus nephritis populations, with FDA accelerated approval pathways compressing development-to-commercialization cycles for novel mechanisms.
- Antimalarials:Hydroxychloroquine and chloroquine constitute the pharmacologic backbone of SLE maintenance protocols per EULAR and ACR guidelines. Volume aggregates in community rheumatology practices across France and Spain where step-therapy requirements mandate first-line antimalarial trial before biologic escalation, though generic substitution has eroded manufacturer margins.
- Immunosuppressants:Mycophenolate mofetil and azathioprine bridge induction-to-maintenance transitions in lupus nephritis protocols.
- Corticosteroids:Prednisone and methylprednisolone address acute flares and bridge therapy during biologic onset.
The dominant share belongs to Antimalarials, while Biologics is closing the gap fastest.
Delivery Mode:
Administration format determines site-of-care economics and prescriber addressability, with self-injection formats expanding community rheumatology access beyond infusion-capable centers.
- Intravenous:Hospital-based monoclonal antibody infusion requires specialized rheumatology suites with adverse event monitoring capabilities. United States health systems in Boston and Houston are expanding dedicated biologic infusion capacity to capture high-acuity SLE patient volumes, though prior authorization friction delays initiation by 30-90 days.
- Subcutaneous:Prefilled syringe and autoinjector formats for belimumab and future interferon pathway inhibitors enable home-based maintenance dosing. Adoption is climbing fastest in French and United Kingdom community rheumatology practices lacking infusion infrastructure, compressing hospital revenue per patient while expanding prescriber pools.
- Oral:Small-molecule formulations dominate maintenance-phase volume through patient self-administration convenience.
- Intramuscular:Depot corticosteroid preparations serve acute flare management in emergency department settings.
Intravenous retains the largest patient volume, though Subcutaneous is gaining share most rapidly.
End User:
Care setting segmentation maps to disease severity stratification and reimbursement tiering, with hospital systems capturing biologic induction value and homecare capturing maintenance volume.
- Hospitals:Academic medical centers and tertiary referral hospitals manage induction-phase biologic therapy for lupus nephritis and neuropsychiatric manifestations. Germany's university hospital networks and United States integrated delivery systems anchor biologic infusion capacity, with real-world evidence generation supporting payer contracting.
- Homecare:Subcutaneous self-administration and oral maintenance therapies shift stable patients from facility-based care. Growth is steepest in United Kingdom and Netherlands markets where home nursing services support biologic injection training, reducing infusion center dependency.
- Clinics:Community rheumatology practices manage maintenance-phase patients and coordinate specialist referrals.
- Research Institutions:Academic centers conduct phase III and IV trials for accelerated approval confirmatory studies.
Hospitals command the highest revenue per patient, while Homecare is expanding most quickly.
Treatment Phase:
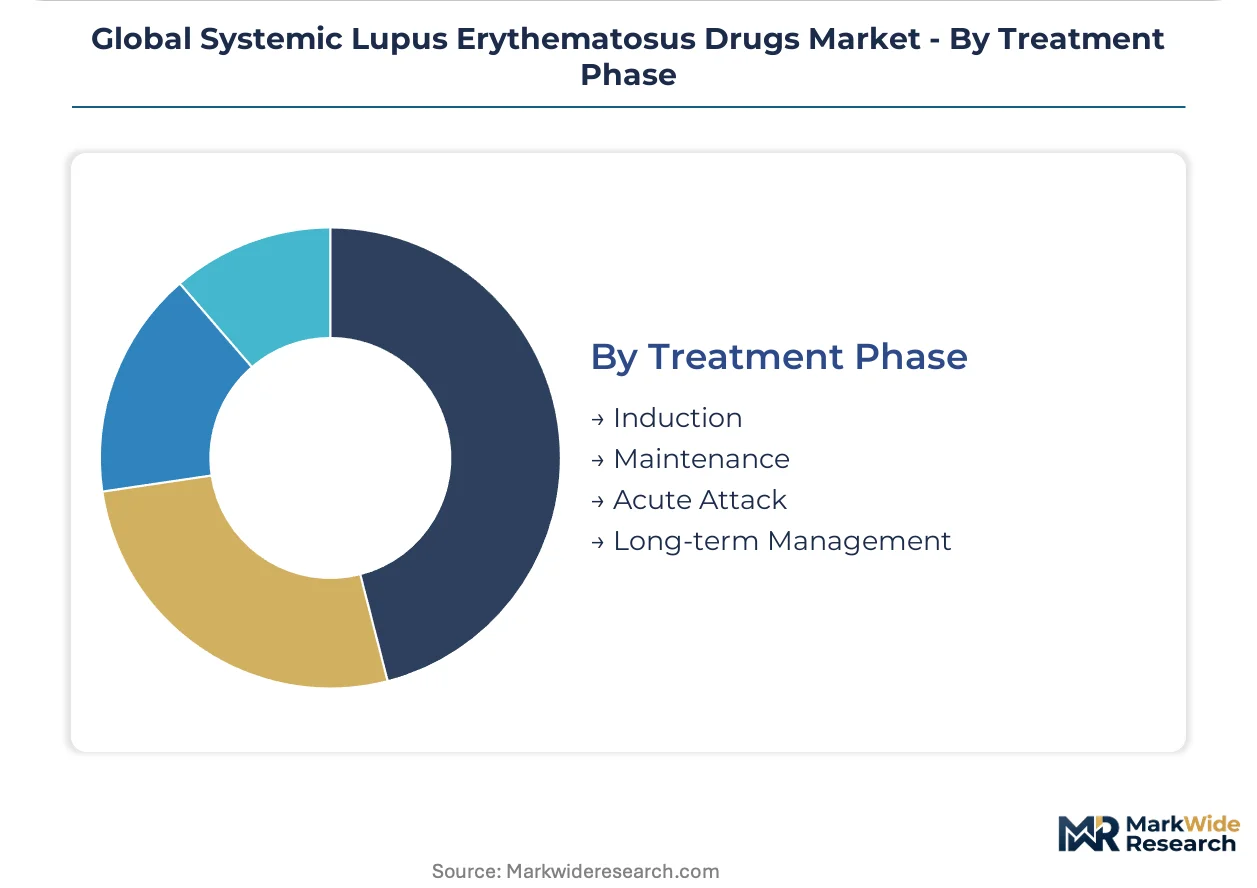
Phase-based segmentation aligns therapeutic intensity with disease activity, creating distinct procurement patterns between acute intervention and chronic maintenance.
- Induction:High-intensity immunosuppression and biologic initiation targets rapid disease control in lupus nephritis and severe cutaneous manifestations. United States and German protocols favor IV belimumab or rituximab for refractory cases, with renal biopsy-driven stratification creating addressable subpopulations for complement inhibition.
- Maintenance:Long-term disease suppression combines antimalarials, low-dose corticosteroids, and subcutaneous biologics. Patient registries in England and France are incorporating SLEDAI response rates into formulary placement decisions, displacing traditional clinical trial endpoint comparisons.
- Acute Attack:Pulse corticosteroid protocols and short-term immunosuppression escalation address disease flares.
- Long-term Management:Multidisciplinary coordination addresses cardiovascular risk, osteoporosis prevention, and fertility preservation.
Maintenance absorbs the greatest cumulative drug expenditure, while Induction commands the highest per-patient intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure anchors European distribution for temperature-sensitive biologics, while the United States maintains the deepest specialist infusion network density for refractory lupus populations.
United States
Academic medical centers in Boston and Houston drive biologic induction demand for lupus nephritis protocols. FDA's Breakthrough Therapy Designation compresses development timelines for monoclonal antibody candidates. The Southeast's integrated delivery networks are expanding dedicated rheumatology infusion suites to capture high-acuity patient volumes.
Germany
University hospital networks in Munich and Berlin anchor European biologic uptake through renal biopsy-driven patient stratification. EMA's PRIME designation creates accelerated access routes for type I interferon receptor antagonists. Baden-Württemberg's pharmaceutical manufacturing clusters concentrate fill-finish capacity for cold-chain monoclonal antibodies.
Japan
Tokyo's rheumatology referral centers manage refractory cutaneous and neuropsychiatric lupus manifestations. PMDA's Sakigake Designation offers priority review with fee reductions for lupus nephritis candidates with novel mechanisms. The Kansai region's biotech corridor supports domestic clinical trial execution for complement inhibition therapies.
United Kingdom
England's NICE incorporates SLEDAI response rates from national lupus cohorts into formulary placement decisions. The MHRA's reliance on EMA centralized procedures streamlines biologic authorization post-Brexit transition. Greater Manchester's health innovation clusters pilot home nursing services for subcutaneous biologic self-administration training.
France
Community rheumatology practices in Île-de-France adopt hybrid protocols transitioning stable patients from intravenous to subcutaneous biologics. ANSM's accelerated access programs enable earlier reimbursement for interferon pathway modulators. The Auvergne-Rhône-Alpes region's hospital networks generate real-world evidence supporting payer contracting for B-cell targeting therapies.
Global Systemic Lupus Erythematosus Drugs Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and regulatory sophistication, creating a tiered structure where large-cap pharmaceutical companies anchor biologic supply security while mid-tier developers pursue mechanism differentiation. The market consolidates around three strategic archetypes: integrated biologics manufacturers with established cold-chain infrastructure, specialty immunology players with focused autoimmune portfolios, and diversified pharmaceutical conglomerates leveraging broad payer relationships. Dominant competitive moves include portfolio diversification into interferon pathway modulation and strategic partnerships to secure single-use bioreactor capacity.
Within the integrated biologics tier, GSK plc and AstraZeneca exemplify divergent positioning strategies. GSK's established belimumab manufacturing footprint anchors supply security across North American and European infusion centers. AstraZeneca occupies a differentiated position through anifrolumab's type I interferon receptor mechanism. F. Hoffmann-La Roche Ltd represents the specialty immunology archetype, sustaining off-label rituximab positioning through extensive real-world evidence generation rather than formal lupus indications.
| Leading Market Players |
|---|
| GSK plc |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Sanofi |
| Novartis AG |
| Eli Lilly and Company |
| UCB S.A. |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory buffers at Belgian distribution hubs signal supply-chain concentration around infusion-capable hospital networks, amplifying pricing power for manufacturers with validated cold-chain capabilities while compressing margins for distributors lacking temperature-controlled infrastructure.
Pricing Analysis
Volume-discount tiering structures separate originator biologics from biosimilar candidates from generic small-molecules across procurement contracts. Price differentiation hinges on FDA Breakthrough Therapy certification and EMA PRIME designation tiers, with branded monoclonal antibodies commanding premiums over off-label alternatives. Cost compression in the antimalarial maintenance tier intensifies because of hydroxychloroquine generic substitution. Community rheumatology practices exhibit highest price sensitivity, while academic medical centers prioritize mechanism differentiation over unit cost.
Supply Chain Analysis
Single-use bioreactor capacity constraints in Ireland and Singapore create manufacturing chokepoints for monoclonal antibody production. Active pharmaceutical ingredient sourcing draws from Indian chemical synthesis clusters and Chinese fermentation facilities, with fill-finish operations concentrating in Germany and Switzerland. Tariff exposure on temperature-controlled logistics equipment poses structural risk to continental European distribution. Distribution runs through specialist pharmaceutical wholesalers with validated 2-8°C handling credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The systemic lupus erythematosus drugs market sits in early-cycle expansion, with subcutaneous self-administration formats penetrating community rheumatology practices previously excluded from biologic prescribing.
For Market Incumbents: Fortify cold-chain distribution partnerships with hospital systems expanding infusion capacity, and deepen manufacturing integration into single-use bioreactor supply to offset capacity constraints. Biosimilar entrants threaten originator pricing in the B-cell targeting segment, making EMA conditional marketing authorization maintenance a critical defensive lever. For New Entrants and Emerging Players: Lead with lupus nephritis biopsy-driven patient stratification as the most penetrable subpopulation, where complement inhibition mechanisms face limited established competition. Japan's Sakigake Designation offers a streamlined regulatory pathway for novel mechanisms, with homecare nursing partnerships enabling community rheumatology access without infusion infrastructure investment. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates spinning off autoimmune-focused development units with lupus pipeline assets. Long-term viability centers on mechanism diversification beyond B-cell and interferon pathways, with regulatory withdrawal risk for accelerated approvals serving as the critical inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA Breakthrough Therapy Designation compresses clinical-to-market timelines for refractory lupus populations. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion in Baden-Württemberg anchors European supply security. |
| Pipeline Diversification | Complement inhibition programs target biopsy-stratified lupus nephritis outside broad SLE labels. |
| Hospital System Partnership | Integrated delivery networks in Boston and Houston generate real-world evidence supporting payer contracting. |
| Reimbursement Strategy | NICE incorporation of SLEDAI response rates from national cohorts displaces traditional clinical trial benchmarks. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions, with secondary validation drawing from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segmentation dimensions modeled include treatment phase, delivery mode, product type, and regional regulatory cluster across the analysis window. CAGRs were derived from patient population epidemiology, biologic penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated SLEDAI response rate benchmarks from national lupus registries and prior authorization approval rate trends by payer type.
Underlying assumptions cover regulatory pathway durability and biosimilar substitution timelines, with deviation risk concentrated in accelerated approval confirmatory trial execution and cold-chain logistics cost volatility. Practitioners should keep alternative scenarios live as FDA advisory committee posture on withdrawal thresholds and EMA conditional renewal criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Antimalarial Drugs Market
Pharmaceuticals
Nephrology Drugs Market
Pharmaceuticals
Live Vaccines Market
Pharmaceuticals
Global Cardiovascular Drugs Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Global Liraglutide Market
Pharmaceuticals
Enteric Empty Capsules Sales Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
Opioid Induced Constipation Drug Market
Pharmaceuticals
Submucosal Lifting Agent Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Global Pharmaceutical Traceability Market