
 Global Liraglutide Market | 2026-2036
Global Liraglutide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liraglutide Market Foresight
Asset-light licensing and royalty-based partnerships is narrowing the capital barrier for biosimilar entrants. Novo Nordisk A/S leverages captive fermentation capacity to sustain cost leadership in active pharmaceutical ingredient supply. Eli Lilly and Company anchors its position through integrated R&D pipelines spanning obesity and metabolic indications. Teva Pharmaceutical Industries Ltd. competes on abbreviated regulatory pathways for follow-on biologics.
Liraglutide is a human glucagon-like peptide-1 (GLP-1) analog synthesized through recombinant DNA technology in yeast expression systems, formulated at 6 mg/mL for once-daily subcutaneous administration, and prescribed primarily for glycemic control and adiposity reduction. Pen injector formats dominate unit volume due to patient self-administration protocols and dose-titration flexibility, while prefilled syringe variants capture institutional procurement contracts where nursing staff manage injections. Weight management applications represent the fastest-expanding indication as off-label prescribing for obesity proliferates beyond formal cardiovascular risk reduction protocols.
FDA pharmacovigilance mandates and EMA GLP-1 class safety monitoring reshape clinical trial design and post-market surveillance obligations for all manufacturers. REACH compliance and ISO 13485 quality management standards govern device-drug combination products across European and international markets. Stakeholders must track evolving reimbursement thresholds for obesity indications versus diabetes to anticipate volume shifts between application segments.
Market Dynamics
GLP-1 receptor agonist manufacturing is consolidating around captive fermentation capacity, with API supply concentration in Denmark and South Korea dictating downstream formulation economics and biosimilar entry timelines.
Growth Catalysts
- Obesity reimbursement expansion:Germany's G-BA and Japan's MHLW are broadening coverage for weight management indications beyond diabetes, unlocking new prescription volumes in specialty clinics.
- REACH compliance harmonization:ECHA's streamlined substance registration for biologics is reducing regulatory duplication across EU member states, accelerating multi-country launch sequences.
- Pen-injector platform standardization:ISO 11608-1 compliance for needle-based injection systems is enabling interchangeable device sourcing and reducing manufacturing qualification costs.
Market Restraints
- Yeast expression system concentration:Active pharmaceutical ingredient production depends on Saccharomyces cerevisiae fermentation capacity concentrated in Northern Europe, creating single-source vulnerability.
- FDA pharmacovigilance burden:Post-market cardiovascular outcome study requirements for GLP-1 class expansions extend development timelines and inflate clinical trial budgets.
- Semaglutide substitution pressure:Weekly-dose alternatives with superior adherence profiles are compressing liraglutide's addressable market in diabetes care.
Strategic Opportunities
- Brazilian biosimilar pathway:ANVISA's abbreviated approval framework for follow-on biologics offers first-mover positioning in Latin America's largest reimbursed market.
- Prefilled syringe institutional contracts:Hospital procurement consolidation in the United States is creating volume anchor customers for nursing-administered formats.
- Dual-chamber device convergence:Integration of lyophilized peptide and diluent in single-use systems is virtualizing cold-chain requirements and expanding pharmacy distribution reach.
Industry Challenges
- Bioprocess engineering talent scarcity:Recombinant protein purification expertise concentrates at established fermentation facilities, constraining new entrant scale-up velocity.
- Combination product certification complexity:FDA's 510(k) and NDA coordination for device-drug submissions extends approval timelines beyond standalone biologic pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liraglutide Market |
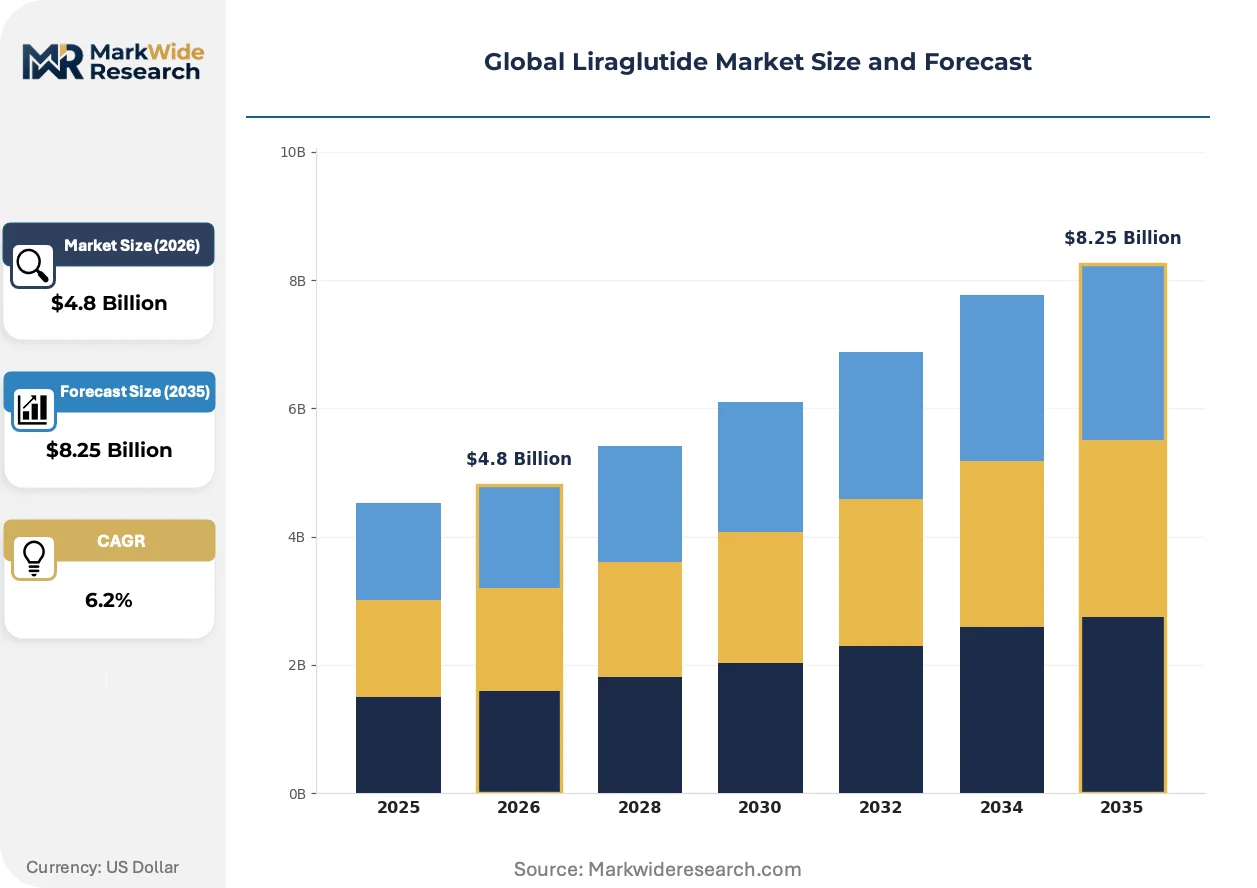
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pen Injector, Prefilled Syringe, Multi-dose Vial, Auto Injector Application: Type 2 Diabetes, Weight Management, Cardiovascular Risk Reduction, Nonalcoholic Steatohepatitis End User: Specialty Clinics, Primary Care Centers, Research Institutes, Outpatient Care Units Delivery Mode: Subcutaneous Injection, Intravenous Injection, Intramuscular Injection, Transdermal Patch |
| Companies Covered | Novo Nordisk A/S, Eli Lilly and Company, Sanofi S.A., Pfizer Inc., Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., AstraZeneca plc, Boehringer Ingelheim GmbH, Biocon Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liraglutide Market Shifts & Advancements
Digital therapeutics integration and manufacturing automation are compressing development cycles while regulatory data transparency mandates reshape competitive intelligence flows across the GLP-1 landscape.
Continuous manufacturing technology is virtualizing batch-based fermentation economics. Novo Nordisk and contract manufacturers in South Korea are adopting perfusion bioreactor systems that sustain cell viability for extended production runs. This shift is compressing capital intensity per gram of peptide produced and enabling modular capacity expansion without greenfield facility investments.
EMA's extended pharmacovigilance requirements for GLP-1 cardiovascular safety signals are mandating real-world evidence collection through patient registries. Manufacturers must now integrate electronic health record data streams into post-market surveillance infrastructure. The diabetes indication segment faces the steepest compliance cost escalation as legacy trial designs require retrofitting for longitudinal outcome tracking.
Self-administration training protocols are displacing clinic-dependent initiation models. Endocrinology practices in the United States and Germany are deploying video-based titration guidance and remote nurse coaching to reduce in-person visit burdens. This behavioral shift is most visible in weight management prescribing, where patient convenience preferences override traditional face-to-face monitoring frameworks.
Global Liraglutide Market Segmentation
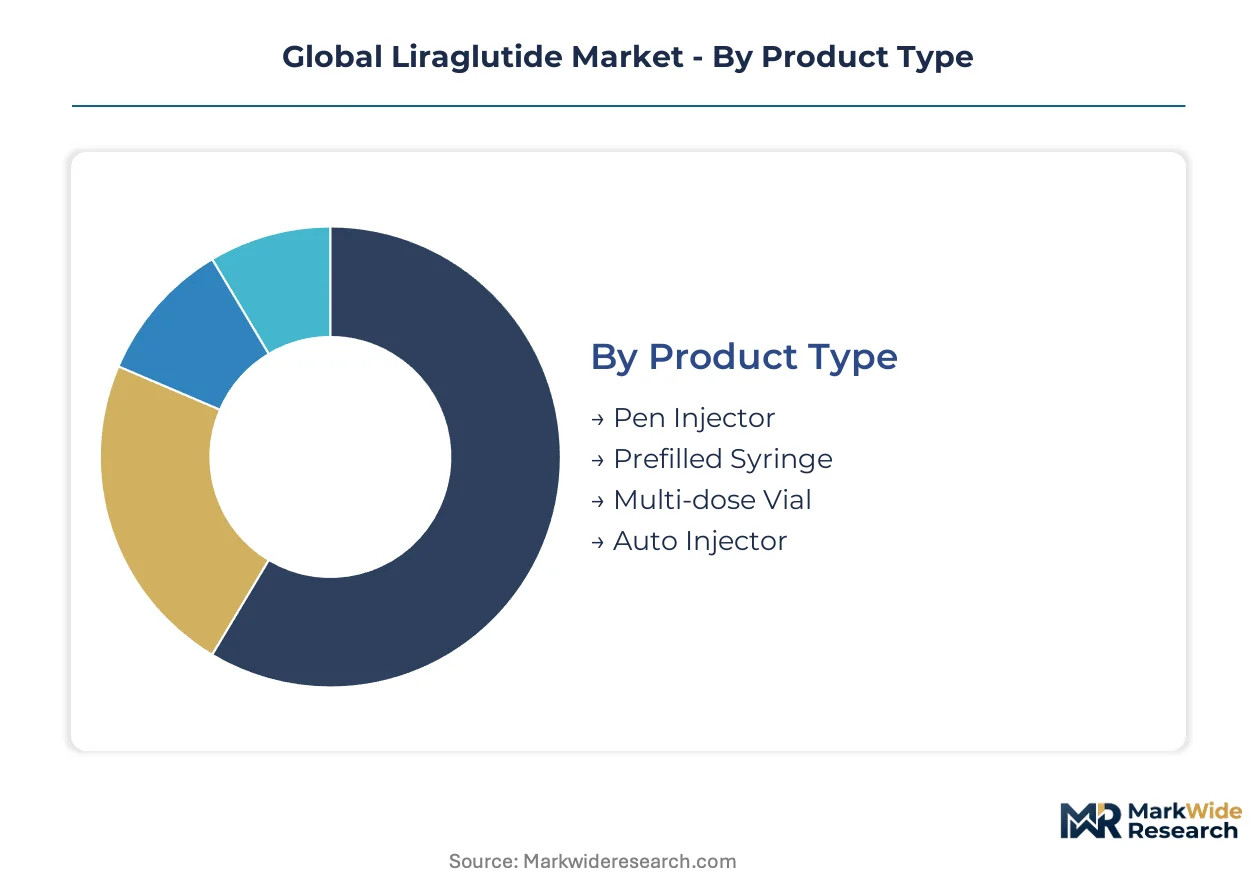
Segmentation in liraglutide markets reveals how device engineering, clinical indication expansion, and site-of-care economics fragment commercial opportunity across divergent stakeholder requirements. Manufacturers must align formulation investments with specific reimbursement pathways and administration protocols rather than pursuing undifferentiated volume strategies.
Product Type:
Mature pen-injector platforms coexist with emerging auto-injector designs as patient self-administration protocols reshape device preferences across diabetes and obesity care.
- Pen Injector:Dial-a-dose mechanisms enable 0.6 mg to 1.8 mg titration sequences for glycemic and weight protocols. Demand concentrates in United States specialty clinics where Novo Nordisk's Victoza brand loyalty and pharmacy benefit manager preferred tier placement sustain volume leadership despite semaglutide weekly alternatives.
- Prefilled Syringe:Institutional procurement contracts in German hospital networks favor nursing-administered formats with fixed-dose elimination of patient error risk. EMA device-drug combination regulations under MDR impose extended qualification timelines that favor established suppliers with ISO 13485-certified manufacturing.
- Multi-dose Vial:Compounding pharmacies and research protocols in Japan utilize bulk peptide formats for dose-flexibility requirements in investigator-initiated cardiovascular outcome studies.
- Auto Injector:Needle-retraction mechanisms and single-button activation address needle-phobia barriers in obesity patient populations, with South Korean contract manufacturers accelerating platform development for Western licensing partnerships.
Pen injectors retain volume leadership; auto injectors hold the steepest expansion curve.
Application:
Cost-tier stratification separates reimbursed diabetes indications from emerging obesity protocols where prior authorization requirements create prescription friction and revenue volatility.
- Type 2 Diabetes:Glycemic control protocols with HbA1c reduction endpoints dominate United States Medicare Part D and commercial formularies, though FDA cardiovascular outcome study mandates inflate post-approval surveillance costs.
- Weight Management:Off-label prescribing for BMI reduction now exceeds formal cardiovascular risk protocols in German G-BA reimbursement expansion territories, with endocrinology practices deploying remote nurse coaching to sustain adherence.
- Cardiovascular Risk Reduction:Formal indication pursuit requires longitudinal outcome registries per EMA pharmacovigilance guidance, constraining participation to sponsors with integrated electronic health record infrastructure.
- Nonalcoholic Steatohepatitis:Biopsy-endpoint trials in United States academic medical centers explore GLP-1 hepatic mechanisms, though liver-specific efficacy signals remain subordinate to metabolic benefits.
Type 2 diabetes commands reimbursement stability; weight management is expanding most quickly.
End User:
Customer-type fragmentation pits high-touch specialty clinic economics against primary care volume efficiency as prescriber scope-of-practice regulations vary across national healthcare systems.
- Specialty Clinics:United States endocrinology practices manage complex titration protocols and prior authorization navigation, capturing premium reimbursement rates for obesity indications beyond standard diabetes care.
- Primary Care Centers:German Hausarzt networks prescribe liraglutide for uncomplicated Type 2 diabetes under disease management program protocols, with G-BA quality indicators driving formulary alignment.
- Research Institutes:Academic medical centers in Japan conduct PMDA-registered cardiovascular outcome studies requiring specialized cold-chain logistics for multi-site peptide distribution.
- Outpatient Care Units:Hospital-based injection clinics in Brazil administer prefilled syringe formats under ANVISA biosimilar pathway expansion, bridging inpatient discharge and community pharmacy transitions.
Specialty clinics retain margin concentration; primary care centers hold the volume scaling opportunity.
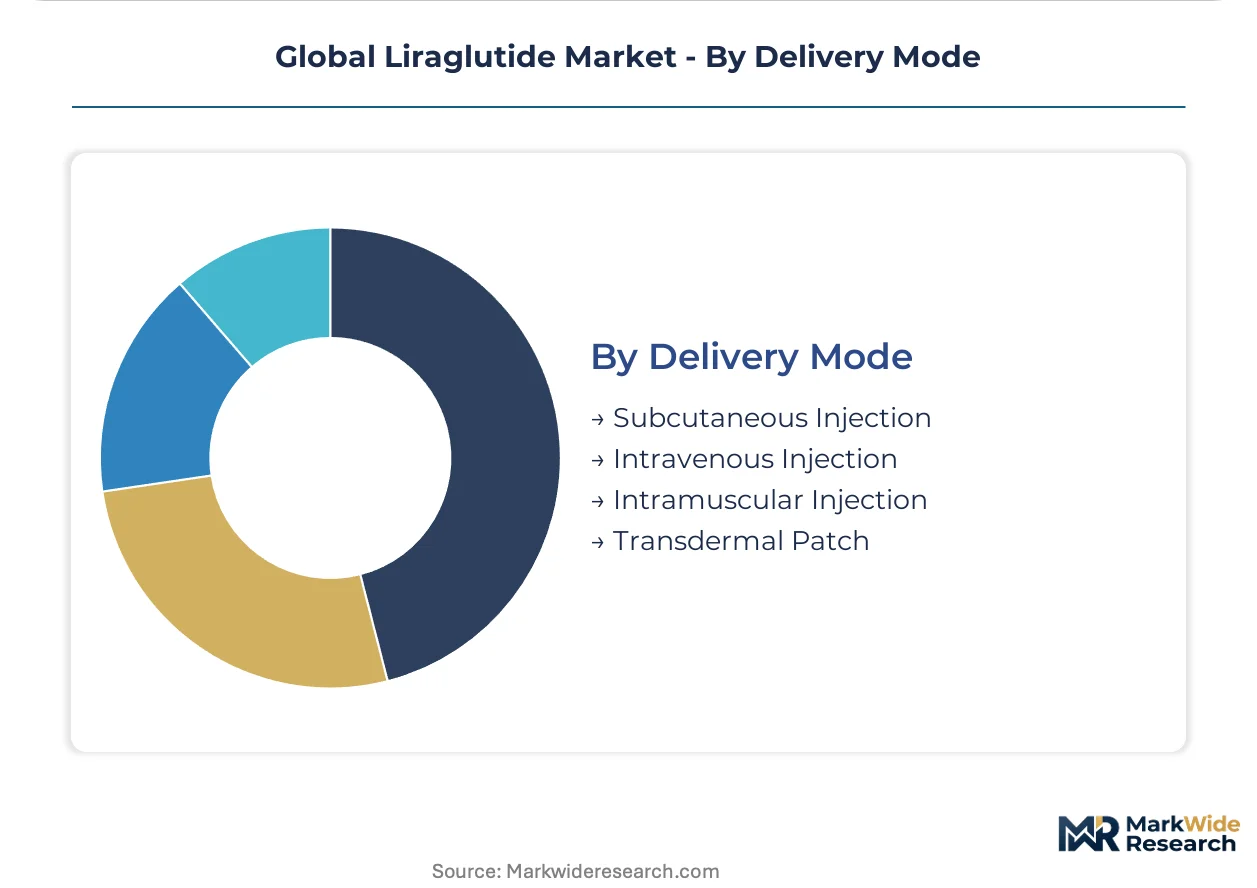
Delivery Mode:
Supply concentration in subcutaneous peptide engineering constrains alternative route development, with transdermal and parenteral alternatives facing bioavailability and immunogenicity barriers.
- Subcutaneous Injection:Abdominal, thigh, or upper arm administration of 6 mg/mL recombinant peptide dominates all approved indications, with pen-injector training protocols standardized across United States, German, and Japanese diabetes educator certification programs.
- Intravenous Injection:Investigational protocols in South Korean academic hospitals explore acute glycemic control applications, though peptide half-life and immunogenicity risks limit commercialization prospects.
- Intramuscular Injection:Depot formulation research in Danish fermentation facilities investigates extended-release peptide engineering for monthly dosing alternatives to daily administration.
- Transdermal Patch:Microneedle array development at contract research organizations faces stratum corneum penetration limits for GLP-1 analog molecular weight, with no approved products in any jurisdiction.
Subcutaneous injection retains absolute volume dominance; transdermal patches represent the most distant technical horizon.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States specialty clinics extract premium pricing for obesity indications while German G-BA reimbursement protocols compress margins through quality-indicator benchmarking. This asymmetry concentrates R&D investment in American endocrinology networks and manufacturing scale-up in Northern European fermentation clusters.
United States
Medicare Part D formularies and commercial pharmacy benefit manager tier placement drive diabetes prescribing volume. FDA cardiovascular outcome study mandates for GLP-1 class expansions extend post-approval surveillance timelines and inflate clinical trial budgets. Greater Boston academic medical centers host PMDA-registered cardiovascular outcome studies requiring specialized cold-chain logistics.
Germany
G-BA quality indicators and disease management program protocols standardize Hausarzt network prescribing for uncomplicated Type 2 diabetes. EMA device-drug combination regulations under MDR impose extended qualification timelines for prefilled syringe formats. Bavarian hospital procurement consolidation creates volume anchor customers for nursing-administered institutional contracts.
Japan
MHLW reimbursement expansion for weight management indications beyond diabetes protocols unlocks new prescription volumes in specialty clinics. PMDA pharmacovigilance requirements for GLP-1 cardiovascular safety signals mandate real-world evidence collection through patient registries. Tokyo-Kanto endocrinology practices deploy remote nurse coaching to reduce in-person visit burdens for self-administration training.
Brazil
ANVISA's abbreviated approval framework for follow-on biologics offers first-mover positioning in Latin America's largest reimbursed market. Hospital-based injection clinics in São Paulo administer prefilled syringe formats under biosimilar pathway expansion, bridging inpatient discharge and community pharmacy transitions. Southeast regional procurement networks concentrate volume for nursing-administered formats.
South Korea
MFDS regulatory harmonization with ICH standards accelerates multi-country launch sequences for contract manufacturers. Seoul Capital Area fermentation facilities adopt perfusion bioreactor systems that sustain cell viability for extended production runs. Busan-Ulsan industrial clusters supply ISO 11608-1 compliant pen-injector platforms for Western licensing partnerships.
Global Liraglutide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in peptide engineering and device manufacturing. The vendor base stratifies between captive fermentation operators with backward integration into API supply and licensing-dependent entrants pursuing abbreviated regulatory pathways. Three archetypes dominate: originator biopharmaceuticals with integrated R&D pipelines, contract development and manufacturing organizations with modular bioreactor capacity, and biosimilar specialists exploiting regional abbreviated approval frameworks. Consolidation pressure manifests through strategic partnerships for device-drug combination certification and geographic licensing arrangements for emerging market access.
Within the originator tier, Novo Nordisk A/S and Eli Lilly and Company exemplify divergent platform strategies. Novo Nordisk's Danish captive fermentation infrastructure anchors cost leadership in active pharmaceutical ingredient supply. Eli Lilly's integrated R&D pipeline spans obesity and metabolic indications. Teva Pharmaceutical Industries Ltd. occupies a position within the biosimilar archetype, representing abbreviated regulatory pathway exploitation for follow-on biologics.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Eli Lilly and Company |
| Sanofi S.A. |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| AstraZeneca plc |
| Boehringer Ingelheim GmbH |
| Biocon Limited |
| Others |
Supply & Pricing Matrix
Overcapacity in South Korean perfusion bioreactor installations is compressing API spot pricing and forcing Danish captive fermenters into longer-term offtake commitments to defend margin structures. This utilization asymmetry rewards backward-integrated incumbents with cost absorption capacity while licensing-dependent entrants face working capital strain from volatile peptide input costs.
Pricing Analysis
The customization-premium spread between patient-configured pen-injector titration protocols and fixed-dose institutional formats runs wide in this market. Three-tier pricing structure across premium, standard, and economy levels separates originator brand loyalty in United States specialty clinics from G-BA quality-indicator compression in German Hausarzt networks and ANVISA biosimilar penetration in Brazilian hospital procurement. Pricing pressure stems from semaglutide weekly substitution in diabetes care, with primary care centers exhibiting highest price sensitivity and academic medical centers in Japan showing lowest elasticity due to research protocol requirements.
Supply Chain Analysis
Export-control regimes on recombinant DNA expression vectors and specialized chromatography resins constrain technology transfer to emerging biosimilar manufacturers. Active pharmaceutical ingredient production concentrates in Denmark, South Korea, and Northern Germany, drawing from Saccharomyces cerevisiae fermentation capacity, glass-cartridge molding expertise, and ISO 11608-1 compliant needle-based injection systems. Single-source vulnerability in yeast expression strain banking creates supply chain risk. Distribution runs through cold-chain logistics networks serving specialty clinic, hospital, and pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liraglutide market is cycling through a post-patent cliff recovery as obesity reimbursement expansion in Germany and Japan reopens volume growth vectors previously compressed by semaglutide substitution.
For Market Incumbents: Harden captive fermentation capacity utilization through perfusion bioreactor technology adoption in South Korean contract manufacturing partnerships, insulating API cost structures from spot market volatility. Deepen backward integration into glass-cartridge supply through ISO 15378-certified primary packaging investments, defending margin position against prefilled syringe format commoditization in European hospital procurement consolidation. For New Entrants and Emerging Players: Brazilian ANVISA abbreviated approval pathways for follow-on biologics represent the most penetrable entry point, with São Paulo hospital-based injection clinics offering volume anchor positioning ahead of Mexican and Colombian regulatory harmonization. ANVISA biosimilar pathway exploitation paired with South Korean CDMO pen-injector platform licensing enables rapid commercialization without greenfield fermentation investment. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across perfusion bioreactor-enabled contract manufacturing as modular capacity expansion displaces greenfield facility requirements. Mid-scale CDMOs with ISO 13485 device-drug combination certification and established MFDS regulatory track records offer acquisition profiles aligned with five-to-ten year GLP-1 manufacturing demand trajectories. The signal to watch is ANVISA approval velocity for follow-on biologics as inflection indicator for Latin American biosimilar market depth.| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Bioreactor Adoption | Novo Nordisk's Danish facilities and South Korean CDMOs compress capital intensity per gram of peptide produced. |
| ANVISA Biosimilar Pathway Exploitation | First-mover positioning in Latin America's largest reimbursed market accelerates follow-on biologic commercialization timelines. |
| ISO 13485 Device Certification Investment | EMA MDR compliance for pen-injector and prefilled syringe formats extends qualification timelines favoring established suppliers. |
| Remote Nurse Coaching Deployment | United States and German endocrinology practices reduce in-person visit burdens for self-administration training protocols. |
| Dual-Chamber Device Development | Integration of lyophilized peptide and diluent virtualizes cold-chain requirements and expands pharmacy distribution reach. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA pharmacovigilance databases, EMA submission filings, ClinicalTrials.gov outcome registries, and G-BA reimbursement decision documents. Drug development executives, regulatory affairs leads at originator and biosimilar firms, formulary directors at United States pharmacy benefit managers, and hospital procurement managers in German and Japanese networks provided qualitative input. Bottom-up prescription volume modeling triangulates against top-down manufacturer shipment data.
Forecast inputs include patient population epidemiology, reimbursement expansion trajectories, and substitution elasticity between daily and weekly GLP-1 administration formats across the analysis window. Segmentation dimensions span product type, application indication, end-user site of care, and delivery mode. CAGRs derive from regression analysis of historical pricing and volume trends, adjusted for regulatory approval timelines and pharmacovigilance cost escalation in cardiovascular outcome study requirements.
Practitioners should monitor ANVISA biosimilar approval velocity, MHLW obesity reimbursement threshold adjustments, and FDA GLP-1 class safety signal updates for early signals of forecast deviation. Material shifts in semaglutide manufacturing capacity expansion or EMA extended pharmacovigilance mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
North America Analgesics Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Mouth Ulcers Treatment Market
Pharmaceuticals
Global Pericarditis Drugs Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
2-Valent HPV Vaccine (2vHPV) Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Europe Anesthesia Drugs Market