
 Artemisinin Antimalarial Drugs Market | 2026-2036
Artemisinin Antimalarial Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Artemisinin Antimalarial Drugs Market Insights
Project finance for large-scale artemisinin cultivation is rewriting competitive access to raw material supply. Novartis AG leverages its long-standing partnership with the WHO to sustain preferential pricing agreements for public-sector buyers. Guilin Pharmaceutical anchors Chinese domestic production capacity while competing aggressively in African tender markets. Kunming Pharmaceutical dominates extraction from sweet wormwood cultivation bases in Yunnan province.
Artemisinin antimalarial drugs are sesquiterpene lactone derivatives derived from Artemisia annua plant material, formulated as artemisinin-based combination therapies with specific pharmacokinetic profiles requiring rapid parasite clearance and minimal recrudescence. Their primary purpose is first-line treatment of uncomplicated Plasmodium falciparum malaria and management of emerging drug-resistant infections. The therapy area segments show malaria treatment occupying the largest volume share while drug-resistant cases generate premium pricing for next-generation combinations. Delivery mode segments reveal oral formulations capturing routine outpatient volumes as injectable artesunate displaces quinine for severe malaria management in hospital settings.
FDA, EMA, and WHO prequalification programs collectively govern market access through bioequivalence requirements and Good Manufacturing Practice audits that filter out substandard suppliers. The WHO's Model List of Essential Medicines and Global Fund procurement criteria directly shape national formularies and donor-funded purchasing volumes. Stakeholders must monitor artemisinin resistance surveillance data from the Greater Mekong Subregion to anticipate which combination therapies will retain therapeutic utility.
Market Dynamics
Artemisinin resistance surveillance in the Greater Mekong Subregion is forcing rapid reformulation of combination therapies and reshaping R&D investment priorities across the supply base. This biological pressure operates in parallel with procurement consolidation by the Global Fund and WHO prequalification bottlenecks that filter manufacturer participation.
Growth Catalysts
- First-line ACT adoption:National malaria control programs in sub-Saharan African countries are expanding procurement of artemisinin-based combination therapies as standard uncomplicated malaria treatment, driving volume demand through public health channels.
- WHO prequalification pathways:The WHO's stringent bioequivalence and Good Manufacturing Practice standards are elevating quality benchmarks that reward compliant manufacturers with preferential access to donor-funded purchasing pools.
- Injectable artesunate displacement:Hospital settings across malaria-endemic regions are replacing quinine with intravenous artesunate for severe malaria management, creating new delivery mode demand.
Market Restraints
- Sweet wormwood supply concentration:Cultivation of Artemisia annua raw material concentrates in Yunnan province and select Chinese growing regions, exposing extraction capacity to climatic volatility and geographic supply risk.
- Artemisinin resistance biology:Parasite strains exhibiting delayed clearance in the Greater Mekong Subregion are eroding therapeutic utility of existing combination formulations and compressing product lifecycles.
- EMA bioequivalence stringency:European Medicines Agency requirements for complex generic artemisinin derivatives create regulatory friction that extends approval timelines and elevates development costs for new entrants.
Strategic Opportunities
- Next-generation combination development:Triple artemisinin combination therapies targeting resistant parasite populations represent emerging white space as current dual therapies face efficacy erosion.
- Sub-Saharan tender market expansion:Underpenetrated national procurement systems in West and Central African countries offer volume growth potential for manufacturers meeting WHO prequalification standards.
- Biotechnology extraction methods:Microbial fermentation and synthetic biology approaches to artemisinin production are converging with traditional agricultural extraction, potentially decoupling supply from seasonal cultivation cycles.
Industry Challenges
- Pharmacovigilance talent scarcity:Post-market surveillance of antimalarial safety in resource-limited settings requires specialized epidemiological and regulatory affairs capabilities that manufacturers struggle to staff.
- Resistance monitoring integration:Real-time incorporation of WHO and national malaria program surveillance data into formulation strategy demands cross-functional coordination between R&D, regulatory, and commercial teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artemisinin Antimalarial Drugs Market |
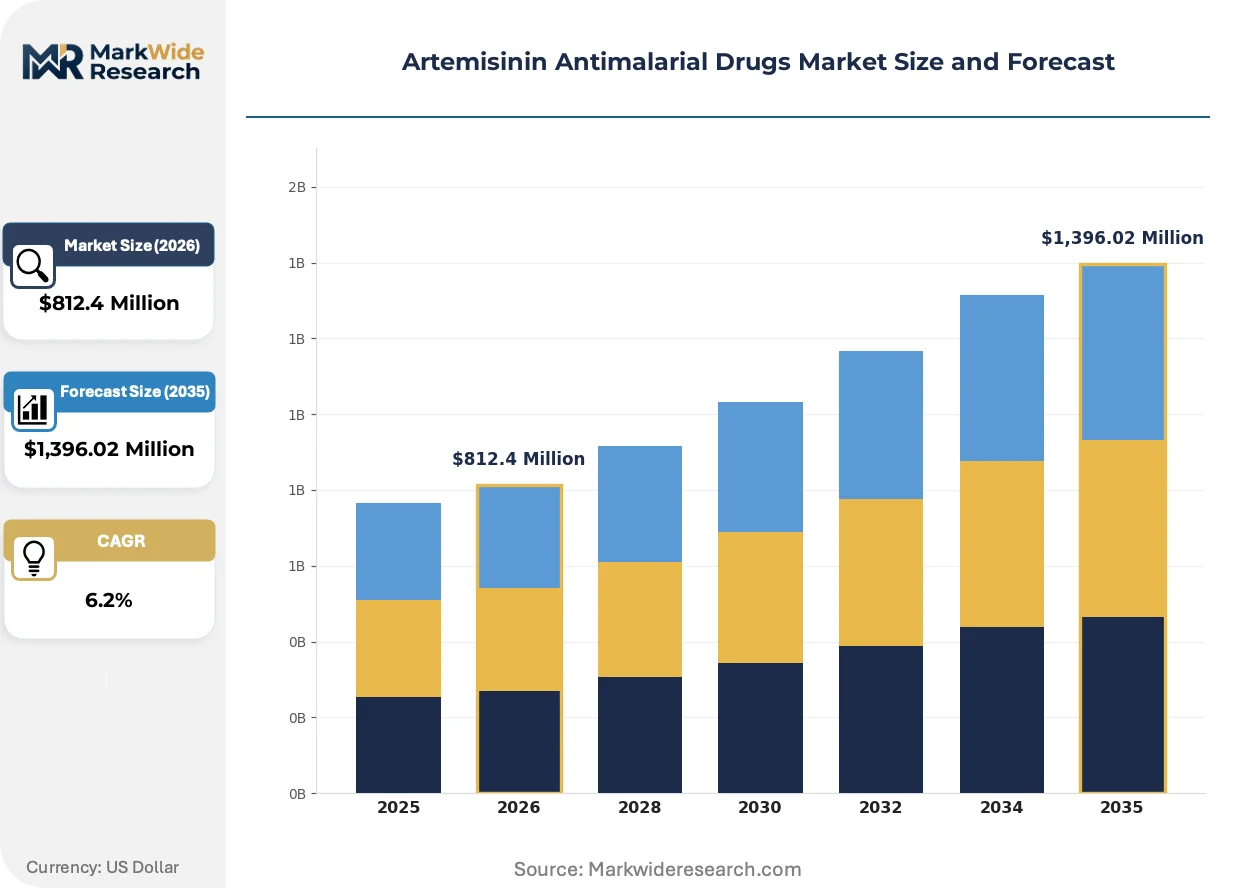
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,396.02 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Artemether, Lumefantrine, Dihydroartemisinin, Piperaquine Therapy Area: Malaria, Mixed Infections, Drug-Resistant Cases, Prophylaxis Delivery Mode: Oral, Injectable, Inhalation, Combination Therapy End User: Hospitals, Retail Pharmacies, Clinics, Home Care |
| Companies Covered | Sanofi, KPC Pharmaceuticals, Guilin Pharmaceutical, Novartis AG, Cipla Ltd., Fosun Pharmaceutical, Ipca Laboratories Ltd., Calyx Chemicals and Pharmaceuticals Ltd., Kunming Pharmaceutical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artemisinin Antimalarial Drugs Market Trends and Innovations
Biological resistance evolution and digital integration across the pharmaceutical value chain are compressing product development timelines while elevating precision requirements for manufacturing and distribution. These forces are reshaping competitive capabilities across the artemisinin supply base.
Continuous manufacturing technologies for artemisinin extraction and formulation are digitizing quality control through real-time release testing and automated compliance documentation. Mid-scale manufacturers in India and China are adopting these platforms to accelerate WHO prequalification timelines. The technology is digitizing batch record management and reducing manual intervention points that previously generated regulatory findings.
EMA's tightened bioequivalence standards for complex generics are extending approval pathways for artemisinin derivative formulations seeking European market access. The regulation is compressing the number of qualified suppliers and elevating analytical method validation requirements. Manufacturers targeting European tenders must now demonstrate higher resolution pharmacokinetic profiling than historical standards required.
Hospital procurement committees in high-burden African countries are consolidating supplier relationships around vertically integrated manufacturers offering both oral ACT and injectable severe malaria products. This buyer concentration is displacing fragmented multi-source purchasing and rewarding suppliers with full portfolio coverage. The pattern is most visible in Kenya, Nigeria, and Tanzania where national hospital formularies are narrowing approved vendor lists.
Artemisinin Antimalarial Drugs Market Segmentation
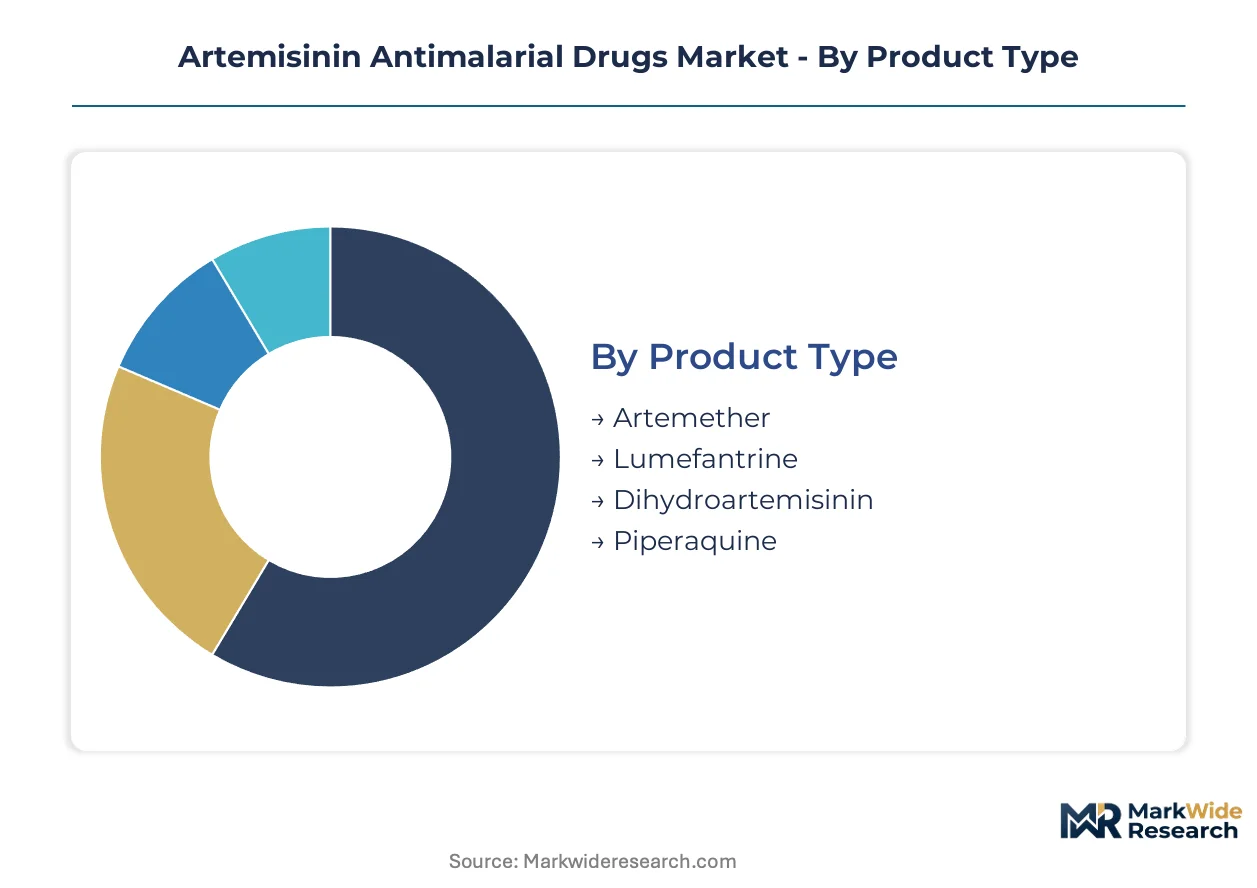
Segmentation in the artemisinin antimalarial drugs market reveals how formulation chemistry, resistance patterns, and care settings fragment demand across distinct procurement channels. Each dimension carries implications for manufacturing scale, regulatory pathway, and pricing power.
Product Type:
Mature derivatives anchor volume procurement while emerging analogs target resistance evolution in Southeast Asian parasite populations.
- Artemether:Lipid-soluble methyl ether derivative formulated in fixed-dose combinations with lumefantrine. Public health programs in Nigeria and the Democratic Republic of Congo concentrate procurement through WHO prequalified suppliers for first-line uncomplicated malaria treatment.
- Lumefantrine:Synthetic arylaminoalcohol partner compound in the standard ACT formulation. Hospital formularies across Kenya and Tanzania specify this combination for outpatient management, with demand reinforced by Global Fund tender specifications.
- Dihydroartemisinin:Water-soluble hemisuccinate derivative with rapid absorption kinetics.
- Piperaquine:Long-acting bisquinoline partner in next-generation triple combinations.
Artemether handles the majority of throughput; dihydroartemisinin is gaining share fastest as resistance surveillance drives reformulation.
Therapy Area:
Application concentration varies by epidemiological burden, with resistance biology forcing portfolio diversification.
- Malaria:Uncomplicated Plasmodium falciparum infection management through standard ACT protocols. National control programs in Ghana and Uganda drive volume through mass drug administration campaigns and facility-based dispensing.
- Drug-Resistant Cases:Delayed parasite clearance requiring modified combination regimens. The Greater Mekong Subregion generates concentrated demand as Cambodia and Myanmar health systems deploy alternative first-line protocols.
- Mixed Infections:Co-infection scenarios with non-falciparum species.
- Prophylaxis:Pre-travel and seasonal chemoprevention in high-transmission zones.
Malaria treatment commands the dominant share; drug-resistant cases are expanding most quickly as surveillance expands.
Delivery Mode:
Route selection tracks severity stratification and care setting infrastructure across endemic regions.
- Oral:Tablet and dispersible formulations for outpatient uncomplicated cases. Retail pharmacy networks in Senegal and Burkina Faso move substantial volume through community health worker distribution programs.
- Injectable:Intravenous and intramuscular artesunate for severe malaria hospitalization. Nigerian teaching hospitals and Tanzanian referral centers are displacing quinine with this route per WHO severe malaria guidelines.
- Inhalation:Nebulized delivery for specific pediatric or vomiting patient populations.
- Combination Therapy:Co-packaged or fixed-dose partner drug presentations.
Oral formulations carry the volume base; injectable artesunate shows the steepest expansion trajectory.
End User:
Channel structure reflects healthcare system tiering and donor funding flows across endemic countries.
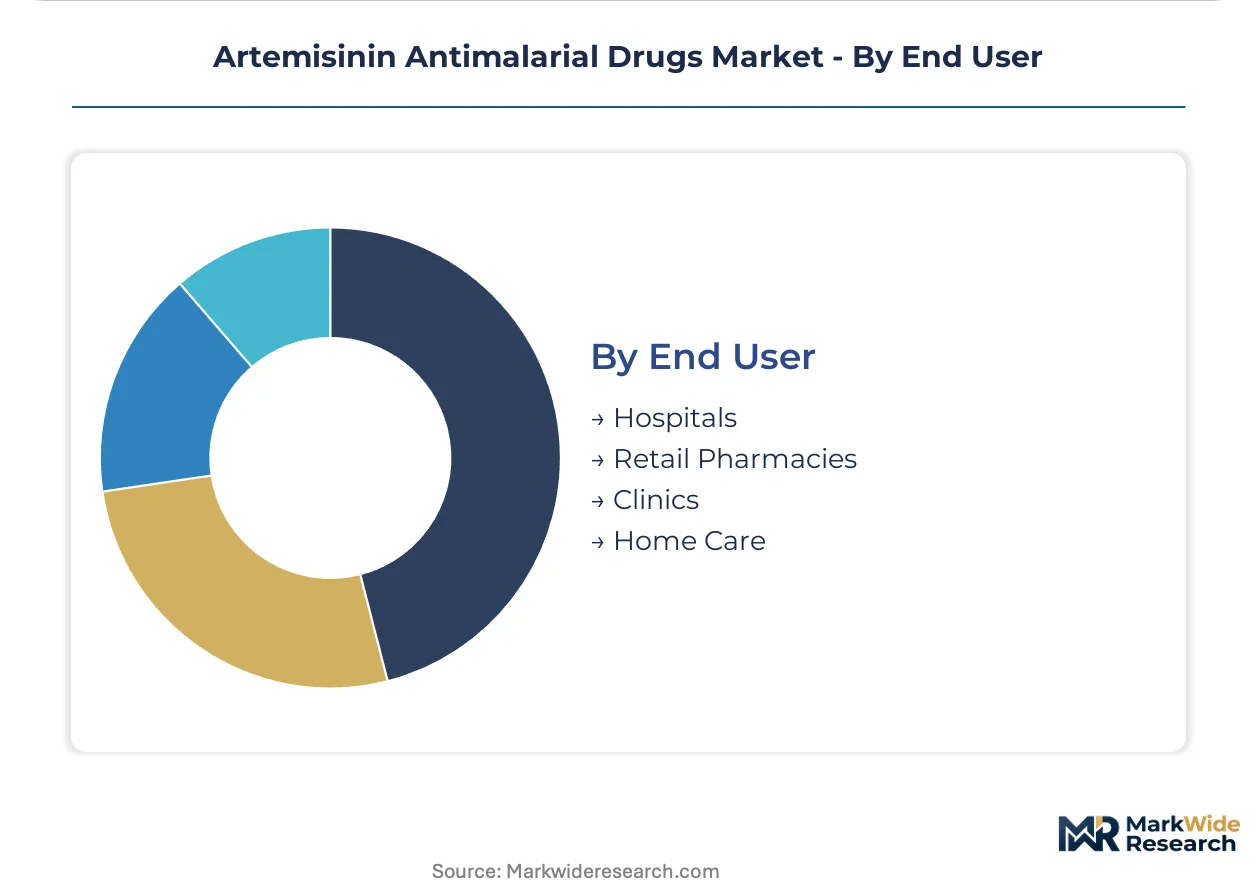
- Hospitals:Inpatient and emergency departments managing severe malaria with parenteral formulations. National hospital formularies in Ethiopia and Mozambique consolidate procurement around vertically integrated suppliers offering full portfolio coverage.
- Retail Pharmacies:Private sector outpatient dispensing with higher price realization. Urban pharmacy chains in Côte d'Ivoire and Cameroon capture substantial self-pay demand outside public procurement channels.
- Clinics:Primary health center and community-based case management.
- Home Care:Community health worker and family-administered treatment.
Retail pharmacies generate the highest throughput; hospital procurement is climbing fastest on injectable conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global Fund procurement criteria and WHO prequalification pathways are redirecting manufacturing investment toward compliant production hubs. National malaria control programs in high-burden countries are consolidating supplier relationships around vertically integrated manufacturers with full portfolio coverage.
Nigeria
Federal Ministry of Health procurement drives volume demand for artemether-lumefantrine combinations through mass drug administration campaigns. The National Agency for Food and Drug Administration and Control enforces bioequivalence standards for imported ACTs. Lagos and Abuja anchor distribution networks serving West African regional supply.
China
Yunnan province cultivation bases supply concentrated raw material extraction capacity for global artemisinin production. The National Medical Products Administration governs export certification under WHO prequalification alignment protocols. Kunming hosts integrated extraction and formulation clusters serving international procurement channels.
India
Central Drugs Standard Control Organization approvals enable participation in Global Fund and WHO prequalified supplier pools. Mumbai-Pune pharmaceutical corridors concentrate generic ACT manufacturing for African tender markets. Ipca Laboratories and Cipla anchor production capacity targeting public-sector procurement systems.
Kenya
Pharmacy and Poisons Board registration requirements filter supplier participation in national hospital formularies. Nairobi teaching hospitals are displacing quinine with intravenous artesunate per WHO severe malaria guidelines. The Kenya Medical Supplies Authority consolidates procurement around approved vendor lists with full portfolio coverage.
Thailand
Artemisinin resistance surveillance in border regions with Cambodia and Myanmar drives demand for modified combination protocols. The Thai Food and Drug Administration accelerates approval pathways for next-generation triple therapies. Bangkok anchors regional coordination for Greater Mekong Subregion treatment guideline harmonization.
Artemisinin Antimalarial Drugs Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with integrated cultivation-to-formulation capabilities and WHO prequalification status. Three archetypes dominate: vertically integrated Chinese producers controlling raw material extraction, Indian generic specialists with African tender expertise, and multinational pharmaceutical companies leveraging preferential pricing agreements with public health institutions. Competitive dynamics center on securing cultivation acreage in Yunnan province and achieving WHO prequalification for combination therapy portfolios.
Within the multinational tier, Novartis AG and Sanofi occupy positions shaped by long-standing WHO partnership frameworks and preferential access mechanisms. Among Chinese integrated producers, Kunming Pharmaceutical Corporation and Guilin Pharmaceutical exemplify the cultivation-backed supply model. KPC Pharmaceuticals represents the mid-scale specialist archetype competing on prequalification compliance and regional tender execution.
| Leading Market Players |
|---|
| Sanofi |
| KPC Pharmaceuticals |
| Guilin Pharmaceutical |
| Novartis AG |
| Cipla Ltd. |
| Fosun Pharmaceutical |
| Ipca Laboratories Ltd. |
| Calyx Chemicals and Pharmaceuticals Ltd. |
| Kunming Pharmaceutical Corporation |
| Others |
Pricing and Supply Chain Analysis
Yunnan province cultivation bases concentrate upstream artemisinin extraction capacity, anchoring margin capture with Chinese integrated producers while downstream African tender markets compress realized prices for non-prequalified suppliers. WHO prequalification status and EMA bioequivalence certification stratify pricing power across the value chain.
Pricing Analysis
Certification level creates the primary spread between supplier tiers, with WHO-prequalified manufacturers commanding premium positioning in Global Fund procurement pools against uncertified competitors relegated to spot-market transactions. Three-tier pricing structure separates premium-certified from standard-compliant from economy-tier suppliers. Cost compression in the economy tier is intensifying as Indian generic specialists absorb margin pressure to secure African tender volumes. National malaria control programs exhibit highest price sensitivity, while hospital procurement committees in Kenya and Nigeria demonstrate reduced sensitivity when bundled with injectable severe malaria portfolios.
Supply Chain Analysis
Extended payment terms from Global Fund procurement cycles strain working capital for mid-scale manufacturers, favoring larger players with supply-chain finance facilities. Raw material extraction concentrates in China, with formulation finishing distributed across India and selected African markets. The supply chain draws from Artemisia annua cultivation, synthetic biology fermentation, and partner drug API manufacturing. Single-source vulnerability in Yunnan province extraction capacity exposes the chain to climatic disruption. Distribution runs through WHO-prequalified supplier networks into national medical stores and hospital formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing capabilities tethered to WHO prequalification compliance represent the scarcest asset class, with fewer than two dozen suppliers globally meeting current bioequivalence and GMP standards for artemisinin combination therapies.
For Market Incumbents: Insulate market position through captive cultivation acreage expansion in Yunnan province and accelerated WHO prequalification for next-generation triple combination portfolios. Synthetic biology competitors threaten long-term agricultural extraction economics. Backward integration into sweet wormwood seed stock and extraction capacity anchors supply security against climatic volatility and emerging microbial fermentation substitutes. For New Entrants and Emerging Players: West African tender markets outside Nigeria and Ghana present the most penetrable procurement channels for manufacturers achieving WHO prequalification status. Central African Republic, Chad, and Burkina Faso national malaria programs operate with less consolidated supplier relationships. Target injectable artesunate registration as the fastest-expanding delivery mode segment, leveraging severe malaria guideline adoption in teaching hospital networks. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated specialists with demonstrated WHO prequalification execution and African tender market presence. The five-to-ten year viability window favors suppliers with cultivation-backed raw material security and formulation diversification across oral and injectable presentations. Artemisinin resistance surveillance data from the Greater Mekong Subregion serves as the critical inflection indicator for portfolio obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks preferential access to Global Fund and national procurement pools across malaria-endemic countries. |
| Triple Combination Development | Addresses emerging artemisinin resistance in Greater Mekong Subregion parasite populations. |
| Backward Integration into Cultivation | Secures captive Artemisia annua supply against Yunnan province climatic and concentration risks. |
| Injectable Artesunate Registration | Captures hospital formulary consolidation as quinine displacement accelerates per WHO guidelines. |
| Synthetic Biology Partnership | Positions for potential decoupling from seasonal agricultural extraction through microbial fermentation. |
Research Methodology
The analysis maps artemisinin derivative formulations, combination therapy portfolios, and delivery mode segments, each validated through procurement officers at national malaria control programs, regulatory affairs leads at prequalified manufacturers, and hospital pharmacy directors across endemic regions. Primary interviews with Global Fund procurement specialists and WHO prequalification auditors combined with secondary validation from FDA Orange Book filings, EMA assessment reports, and WHO prequalification lists. Bottom-up demand modeling from national treatment guidelines and top-down supply verification from cultivation and extraction capacity data provided triangulation.
Assumptions held constant include WHO prequalification standards, EMA bioequivalence thresholds, and Global Fund procurement criteria across the projection horizon; variables included artemisinin resistance evolution rates and synthetic biology production cost curves. Segmentation dimensions modeled encompass product type, therapy area, delivery mode, and end-user channel, with regional regulatory clusters capturing FDA, EMA, and national competent authority variations. CAGRs derived from volume-weighted price trajectories and procurement expansion patterns in high-burden countries, incorporating hospital injectable conversion rates and mass drug administration campaign frequencies as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in donor funding flows, currency volatility in African tender markets, or trade restriction implementation would shift the trajectory. Forecasts reflect documented assumptions regarding resistance surveillance data integration into formulation strategy. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Injectable Drugs Market
Pharmacology
Apixaban Market
Pharmacology
Influenza Medication Market
Pharmacology
Drug Repurposing Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Antitussive Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Aspirin API Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Angiotensin II Receptor Blockers (Arbs) Market
Pharmacology
Medication Adherence Market
Pharmacology
Aldosterone Receptor Antagonists Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Propranolol Drug Market
Pharmacology
Antithrombotic Drugs Market