
 Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market | 2026-2036
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market Outlook
REACH compliance on pharmaceutical impurities is realigning manufacturing cost structures for generic 5-HT3 antagonists. Merck & Co., Inc. leverages its legacy position in the NK1 receptor antagonist class through sustained clinical validation. Heron Therapeutics, Inc. differentiates via extended-release depot formulations that reduce administration frequency. Helsinn Group anchors European supply through specialized oncology supportive care manufacturing.
Chemotherapy-Induced Nausea and Vomiting treatment encompasses pharmacologic interventions targeting serotonergic, neurokinin, and corticosteroid pathways to prevent or suppress emesis triggered by cytotoxic agents, with formulations requiring precise timing relative to chemotherapy infusion schedules. The NK1 receptor antagonist segment leads in revenue per patient day due to combination therapy positioning in highly emetogenic regimens, while the transdermal route of administration shows fastest expansion as outpatient clinics seek alternatives to intravenous administration. Cancer treatment centers represent the most concentrated margin pool, capturing bundled reimbursement for prophylactic antiemetic protocols.
FDA, EMA, and WHO guideline frameworks shape CINV treatment demand by mandating prophylaxis stratification based on chemotherapy emetogenic risk categories, which directly determines formulary placement and prescribing patterns. The EU MDR and FDA's enhanced pharmacovigilance requirements for antiemetic biologics are tightening post-market surveillance obligations. Stakeholders must monitor evolving NCCN and ASCO guideline harmonization on triple-combination prophylaxis to anticipate shifts in first-line therapy positioning.
Market Dynamics
Prophylactic antiemetic protocols are displacing rescue therapy as the standard of care, with oncology infusion centers bundling NK1 receptor antagonists, 5-HT3 antagonists, and corticosteroids into pre-chemotherapy administration workflows. This protocol standardization is compressing prescribing discretion and concentrating formulary decisions around guideline-concordant triple-combination regimens.
Growth Catalysts
- CMS reimbursement alignment:Medicare Part D coverage for oral antiemetics eliminates cost barriers to outpatient adherence, particularly for extended-duration prophylaxis following highly emetogenic chemotherapy.
- REACH compliance mandates:The EU's pharmaceutical impurity regulations are forcing manufacturing upgrades for generic 5-HT3 antagonists, accelerating quality differentiation among European suppliers.
- Transdermal delivery systems:Patch-based granisetron formulations reduce nursing administration burden in ambulatory oncology clinics, expanding route-of-administration options beyond intravenous and oral.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production for palonosetron concentrates among Chinese manufacturers, creating vulnerability to environmental compliance shutdowns and export licensing delays.
- Biosimilar substitution limits:The absence of interchangeable biosimilar pathways for aprepitant under FDA guidance preserves originator pricing power and restricts payer leverage.
- Formulary exclusion mechanics:Pharmacy benefit manager tiering protocols place newer NK1 receptor antagonist combinations on non-preferred tiers, requiring prior authorization and delaying therapy initiation.
Strategic Opportunities
- Home-based administration:Subcutaneous depot formulations enable patient self-administration outside infusion centers, capturing value from site-of-care migration toward outpatient and home oncology models.
- Pediatric indication expansion:EMA's pediatric investigation plan requirements for oncology supportive care create regulatory pathways for age-appropriate dosing formulations in previously untapped patient populations.
- Real-world evidence integration:FDA's Project Orbis framework permits synchronized oncology drug approval across multiple jurisdictions, accelerating label expansion for combination antiemetic regimens.
Industry Challenges
- Clinical trial recruitment constraints:Patient enrollment for CINV prevention studies competes with oncology therapeutic trials, extending development timelines for novel mechanism agents.
- Legacy EHR integration:Electronic health record systems require customization to support automated antiemetic order sets, demanding substantial health system IT expenditure and change management.
- Multinational protocol harmonization:Divergent NCCN, ESMO, and ASCO guideline recommendations on corticosteroid dosing create prescriber confusion and formulary fragmentation across health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market |
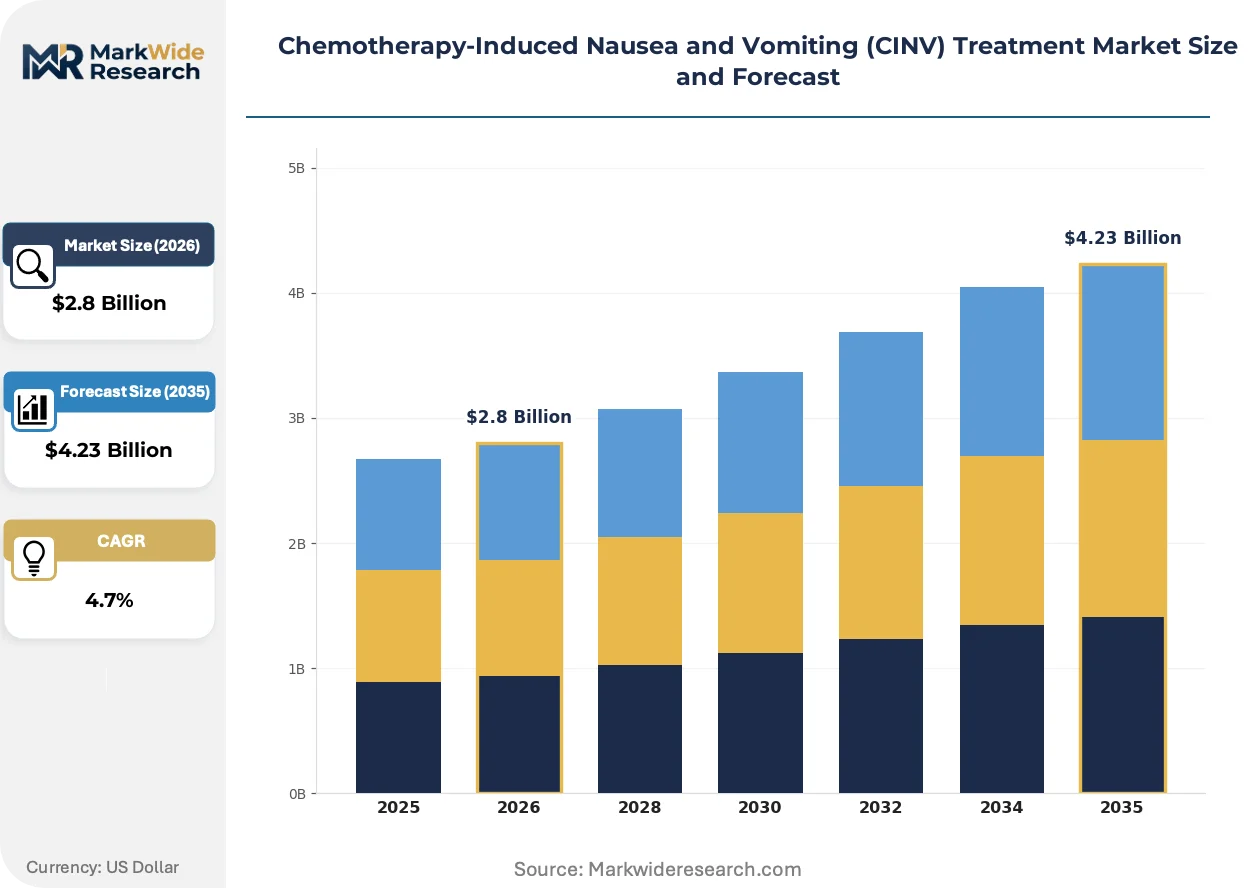
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 5-HT3 Receptor Antagonists, NK1 Receptor Antagonists, Corticosteroids, Benzodiazepines Route of Administration: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Outpatient Clinics, Home Care, Cancer Treatment Centers Therapy Area: Oncology, Palliative Care, Acute Care, Supportive Care |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Heron Therapeutics, Inc., Helsinn Group, Novartis AG, Pfizer Inc., AbbVie Inc., Ono Pharmaceutical Co., Ltd., Kyowa Kirin, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market Strategic Shifts
Extended-release depot technologies are compressing administration frequency from daily to multi-day intervals, while regulatory convergence across FDA and EMA pathways accelerates combination therapy approvals. These forces are restructuring competitive positioning around formulation innovation rather than mechanism-of-action novelty alone.
Subcutaneous extended-release formulations of 5-HT3 antagonists deliver sustained plasma concentrations over five to seven days through polymer-based depot matrices. Ambulatory oncology clinics in the United States are adopting these formulations to eliminate post-discharge oral adherence gaps. This technology is expanding into same-day chemotherapy protocols by reducing nursing touchpoints and enabling earlier patient discharge.
EMA's updated guideline on clinical investigation of antiemetic medicinal products now mandates patient-reported outcome measures as primary endpoints, displacing investigator-assessed vomiting frequency. European sponsors must redesign Phase III protocols to incorporate electronic diary capture of nausea severity scores. The NK1 receptor antagonist segment faces the steepest compliance burden given existing reliance on historical endpoint definitions.
Oncology group purchasing organizations are consolidating antiemetic procurement across health system networks, displacing individual hospital formulary committees. Premier and Vizient in the United States now negotiate enterprise-wide contracts for prophylactic antiemetic bundles. This concentration is most visible in community oncology practices acquired by hospital systems, where standardized protocols override individual physician preference.
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market Segmentation
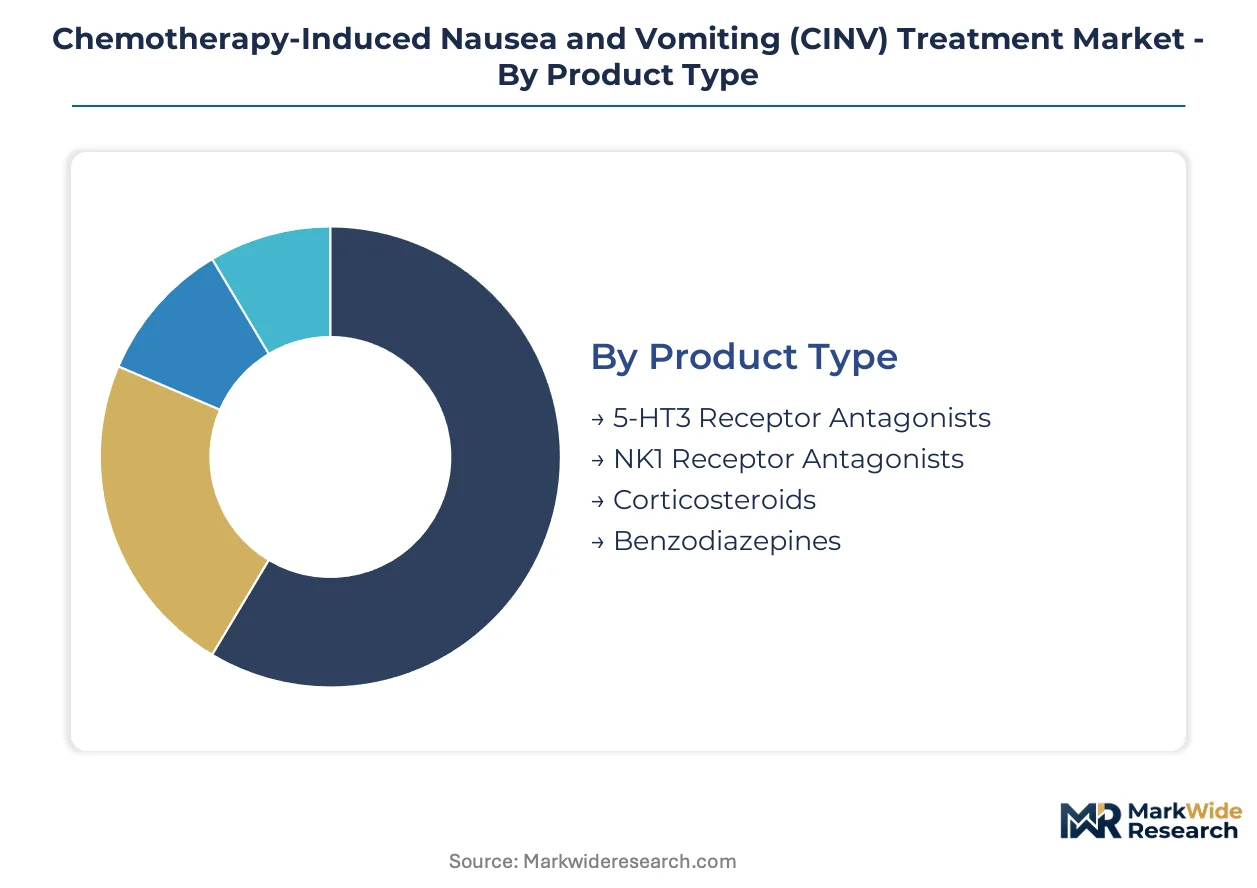
CINV treatment segmentation reflects how oncology practices bundle prophylactic regimens around chemotherapy emetogenic risk tiers and site-of-care economics. Formulary placement and reimbursement mechanics vary sharply across these dimensions, concentrating margin in high-compliance institutional settings.
Product Type:
Prescribers select agents based on emetogenic risk stratification and combination protocol requirements rather than monotherapy preference.
- NK1 Receptor Antagonists:These agents block substance P at the neurokinin-1 receptor in the brainstem vomiting center. Demand concentrates in United States cancer treatment centers administering highly emetogenic cisplatin regimens, where triple-combination prophylaxis is now standard.
- 5-HT3 Receptor Antagonists:Serotonin antagonists targeting peripheral and central 5-HT3 receptors remain the backbone of acute-phase prophylaxis. Volume sits with generic ondansetron in cost-sensitive outpatient clinics, though palonosetron captures premium positioning in delayed-phase prevention.
- Corticosteroids:Dexamethasone-based protocols provide cost-effective antiemetic synergy across all emetogenic risk categories. United Kingdom NHS formularies mandate corticosteroid inclusion in first-line prophylaxis, anchoring volume in European institutional procurement.
- Benzodiazepines:Lorazepam addresses anticipatory nausea and breakthrough emesis through anxiolytic mechanisms. Demand clusters in palliative care settings where psychological conditioning to chemotherapy complicates pharmacologic control.
Volume sits with 5-HT3 Receptor Antagonists; growth tilts toward NK1 Receptor Antagonists.
Route of Administration:
Site-of-care migration from inpatient infusion centers to ambulatory and home settings is restructuring administration modality preferences.
- Intravenous:IV delivery ensures rapid onset for acute-phase prophylaxis timed to chemotherapy infusion. United States hospital outpatient departments retain IV dominance for same-day highly emetogenic regimens requiring nursing supervision.
- Oral:Tablet and capsule formulations enable patient self-administration of delayed-phase prophylaxis. Medicare Part D reimbursement in the United States removes cost barriers to outpatient oral adherence over multi-day regimens.
- Transdermal:Granisetron patches deliver sustained 5-HT3 antagonism without gastrointestinal absorption variables. Ambulatory oncology clinics in Germany and France are adopting transdermal alternatives to reduce nursing touchpoints.
- Subcutaneous:Extended-release depot formulations compress dosing frequency to weekly or biweekly intervals. Home care agencies in the United States are piloting subcutaneous protocols for patient self-administration outside infusion centers.
Intravenous retains volume leadership; subcutaneous depot technology is expanding most quickly.
End User:
Procurement authority and reimbursement bundling determine how antiemetic value flows across care settings.
- Cancer Treatment Centers:Specialized oncology facilities capture bundled reimbursement for prophylactic antiemetic protocols integrated with chemotherapy administration. United States-based NCCN-designated centers standardize triple-combination regimens across physician practices.
- Hospitals:Acute care institutions manage CINV in inpatient oncology units and emergency departments. United Kingdom NHS Trusts consolidate antiemetic purchasing through regional pharmacy procurement hubs.
- Outpatient Clinics:Community oncology practices require flexible formulary options across varying emetogenic risk profiles. United States group purchasing organizations now negotiate enterprise-wide antiemetic contracts for acquired community practices.
- Home Care:Home infusion and hospice services administer prophylaxis and rescue therapy outside institutional settings. French home hospitalization programs are expanding reimbursement for nurse-administered subcutaneous antiemetics.
Cancer Treatment Centers command premium positioning; Home Care is gaining share fastest.
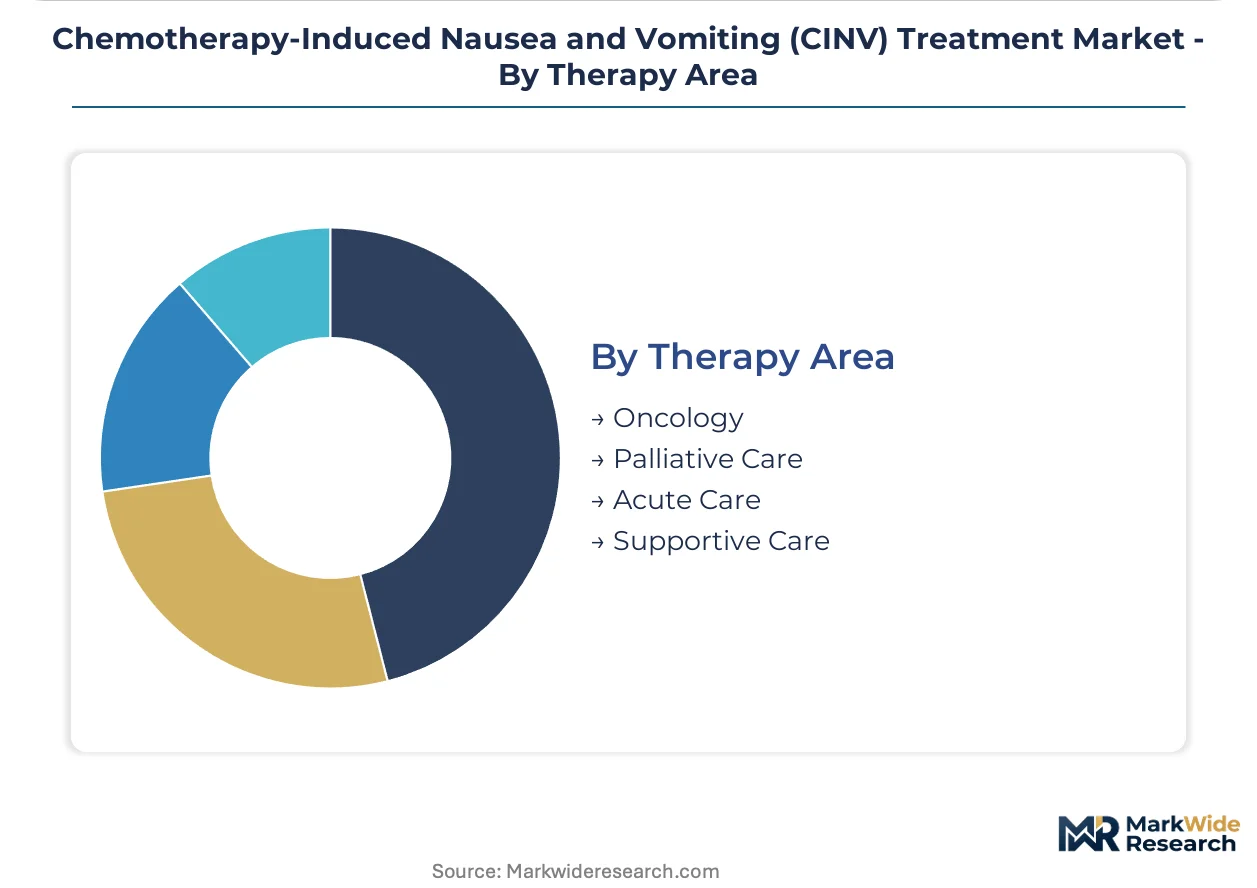
Therapy Area:
Clinical context shapes antiemetic selection through urgency, comorbidity burden, and therapeutic goal alignment.
- Oncology:Curative and adjuvant chemotherapy regimens demand guideline-concordant prophylaxis to maintain dose intensity. United States ASCO guidelines mandate risk-stratified antiemetic protocols across all oncology subspecialties.
- Supportive Care:Dedicated supportive care services optimize quality of life through aggressive emesis prevention. German comprehensive cancer centers integrate supportive care physicians into chemotherapy planning workflows.
- Palliative Care:End-of-life symptom management prioritizes patient comfort over protocol rigidity. United Kingdom Marie Curie hospices emphasize anticipatory antiemetic coverage for home-dying patients.
- Acute Care:Emergency departments and urgent care settings manage breakthrough CINV requiring rapid rescue intervention. United States emergency medicine protocols standardize 5-HT3 antagonist rescue dosing for oncology patients.
Oncology dominates volume; supportive care shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oncology biotechnology parks in Massachusetts and North Carolina concentrate CINV treatment R&D, while specialized manufacturing zones in Switzerland and Ireland anchor European supply chains for high-potency antiemetics.
United States
Medicare Part D reimbursement for oral antiemetics drives outpatient adherence to guideline-concordant regimens. FDA label expansions for NK1 receptor antagonist combinations broaden first-line prevention eligibility. The Research Triangle Park in North Carolina hosts clinical trial operations for extended-release depot formulations.
Germany
Ambulatory oncology clinics adopt transdermal granisetron to reduce nursing touchpoints in same-day chemotherapy protocols. EMA's updated antiemetic guideline mandates patient-reported outcomes as primary endpoints. The Rhine-Main region concentrates manufacturing of specialized oncology supportive care products.
Japan
PMDA accelerated approval pathways compress development timelines for combination antiemetic regimens. METI subsidizes domestic production of critical API precursors to reduce import dependency. The Kansai region around Osaka anchors formulation development for polymer-based depot technologies.
Switzerland
Swissmedic's streamlined oncology supportive care review attracts sponsors seeking synchronized EMA-FDA submissions. Basel's pharmaceutical cluster houses specialized manufacturing for high-potency NK1 receptor antagonist APIs. The country's bilateral trade agreements facilitate API transit to European formulation sites.
India
CDSCO's phased manufacturing compliance deadlines force upgrades at generic 5-HT3 antagonist facilities. The country's national pharmaceutical regulator prioritizes bioequivalence data for palonosetron copy products. Hyderabad's genome valley hosts contract research operations for antiemetic pharmacokinetic studies.
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the CINV treatment landscape. Large pharmaceutical houses leverage existing oncology portfolios to bundle antiemetics with cytotoxic agents. Three archetypes dominate: originator developers of NK1 receptor antagonists, generic manufacturers of 5-HT3 antagonists, and formulation innovators delivering extended-release depot technologies. Competitive moves concentrate on M&A to acquire depot formulation capabilities and strategic partnerships to secure API supply.
Among diversified pharmaceutical conglomerates, Merck & Co., Inc. and Novartis AG occupy positions anchored by legacy oncology portfolios. Heron Therapeutics, Inc. exemplifies the formulation innovation archetype through its focus on extended-release delivery systems. Helsinn Group represents the specialized oncology supportive care manufacturer, with geographic concentration reflecting European regulatory alignment.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Heron Therapeutics, Inc. |
| Helsinn Group |
| Novartis AG |
| Pfizer Inc. |
| AbbVie Inc. |
| Ono Pharmaceutical Co., Ltd. |
| Kyowa Kirin, Inc. |
| Others |
Value Chain & Pricing Dynamics
Palonosetron API spot prices on Chinese chemical exchanges cascade through formulation tiers, compressing margins for generic 5-HT3 antagonists while originator NK1 receptor antagonists maintain premium positioning through EMA-certified manufacturing. REACH compliance costs in Europe and FDA pharmacovigilance mandates in the United States bifurcate procurement into quality-validated and price-competitive streams.
Pricing Analysis
Short lead-time premiums for NK1 receptor antagonist APIs command 15-20% markups over contract-scheduled deliveries, while spot-market palonosetron concentrates trade at discounts in oversupply conditions. Three-tier pricing structure across originator, authorized generic, and commodity generic levels reflects FDA bioequivalence certification status and EMA GMP inspection history. Pricing pressure stems from Chinese API oversupply and European manufacturing upgrade pass-through costs. Community oncology practices in the United States exhibit highest price sensitivity due to Medicare reimbursement compression, while NCCN-designated cancer centers prioritize protocol compliance over acquisition cost.
Supply Chain Analysis
Palonosetron API production rests on specialty chemical manufacturers in Zhejiang and Jiangsu provinces, with secondary sourcing from Indian CDMOs in Hyderabad and Ahmedabad. Granisetron transdermal patch substrates draw from Japanese polymer suppliers, while corticosteroid APIs feed from European fermentation facilities in Italy and Spain. Single-source vulnerability concentrates in Chinese environmental compliance shutdowns disrupting export licensing. Distribution runs through oncology group purchasing organizations in the United States and regional pharmacy procurement hubs in the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CINV treatment market sits in a formulation-technology transition, with extended-release depot systems displacing daily oral regimens and transdermal alternatives eroding intravenous dominance in ambulatory settings.
For Market Incumbents: Cement formulary lock-in through EHR-integrated order set partnerships with Epic and Cerner installations at NCCN-designated centers. Acquire subcutaneous depot formulation capabilities to defend against site-of-care migration toward home administration. The threat of biosimilar aprepitant substitution limits pricing power and demands backward integration into polymer-based delivery technology.
For New Entrants and Emerging Players: Oncology home care agencies represent the most penetrable channel partner type for subcutaneous depot pilots, bypassing entrenched GPO contracts at infusion centers. Target French home hospitalization programs expanding nurse-administered antiemetic reimbursement. Pediatric indication gaps under EMA investigation plan requirements offer regulatory-fast-track entry with age-appropriate dosing formulations.
For Investors and Strategic Acquirers: The window for entry favors formulation innovators with depot technology platforms over commodity generic manufacturers. Long-term viability centers on patient-reported outcome data packages supporting label differentiation. Watch for FDA Project Orbis synchronized approval announcements as inflection signals for combination therapy positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Release Depot Development | Reduces nursing touchpoints and enables same-day chemotherapy discharge protocols. |
| Pediatric Investigation Plan Submission | EMA mandates create regulatory pathways for previously untapped age-specific formulations. |
| Home Care Channel Partnership | French home hospitalization reimbursement expansion captures site-of-care migration value. |
| API Supply Security Investment | METI subsidies for domestic Japanese precursor production reduce import dependency exposure. |
| Real-World Evidence Integration | FDA's Project Orbis framework accelerates multi-jurisdictional label expansion timelines. |
Study Parameters
Independent corroboration across oncology pharmacy directors, regulatory affairs specialists at EMA-aligned sponsors, and formulary committee chairs at United States cancer centers underwrites the qualitative findings. Primary interviews with hospital procurement managers and GPO contract negotiators combined with secondary validation from FDA Orange Book listings, EMA EPAR assessments, ClinicalTrials.gov protocol registries, and CMS Medicare Part D claims data. Bottom-up patient-volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in the NK1 receptor antagonist, 5-HT3 antagonist, and corticosteroid segments. The analytical framework models administration route substitution elasticities, emetogenic risk stratification protocol adoption curves, and regional reimbursement bundling mechanics. CAGRs derive from chemotherapy regimen volume forecasts and antiemetic penetration rates by treatment line, with sensitivity analysis around biosimilar substitution timelines and depot formulation uptake curves.
Caveats apply where FDA biosimilar interchangeability determinations, EMA manufacturing inspection outcomes, or Chinese environmental enforcement actions could materially shift the outlook. Forecasts reflect assumptions on guideline harmonization across NCCN, ESMO, and ASCO protocols and site-of-care reimbursement stability in Medicare and NHS frameworks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Amoxicillin Drugs Market
Pharmaceuticals
Global Hepatitis B Vaccines Market
Pharmaceuticals
Specialty Active Pharmaceutical Ingredients Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Global Alpha-Blocker Market
Pharmaceuticals
Global Thin Film Drugs Market
Pharmaceuticals
Radiopharmaceutical (Oral Route) Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Cyclosporine Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Long-Acting Beta-Agonists Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
Respiratory Disease Vaccine Market