
 Global Lupus Market | 2026-2036
Global Lupus Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lupus Market Intelligence
Multi-source API procurement for monoclonal antibodies is hardening as manufacturers hedge against supply disruption. GlaxoSmithKline sustains one of the deepest lupus therapy portfolios through its immunology division. AstraZeneca leverages its rare-disease infrastructure to extend belimumab access into emerging markets. Aurinia Pharmaceuticals anchors its position with voclosporin as the only FDA-approved oral therapy for lupus nephritis.
Lupus comprises a heterogeneous family of autoimmune disorders characterized by loss of self-tolerance, immune complex deposition, and multi-organ inflammation, with systemic lupus erythematosus representing the most severe form involving kidneys, skin, joints, and cardiovascular systems. Biologics command the highest margin pool in the product-type dimension due to targeted mechanism and premium positioning, while immunosuppressants retain substantial volume share in maintenance protocols. Intravenous delivery dominates hospital-based administration, though subcutaneous formulations are gaining traction in specialty clinics seeking to shift care settings.
FDA orphan-drug designations and EMA PRIME eligibility reshape competitive timelines by granting priority review and protocol assistance for lupus developers. The EU MDR and FDA's strengthened REMS requirements for immunosuppressive agents elevate manufacturing and post-market surveillance costs. Stakeholders must monitor how CMS and NICE reimbursement negotiations for biologics versus biosimilars reshape prescribing economics across outpatient and infusion-center settings.
Market Dynamics
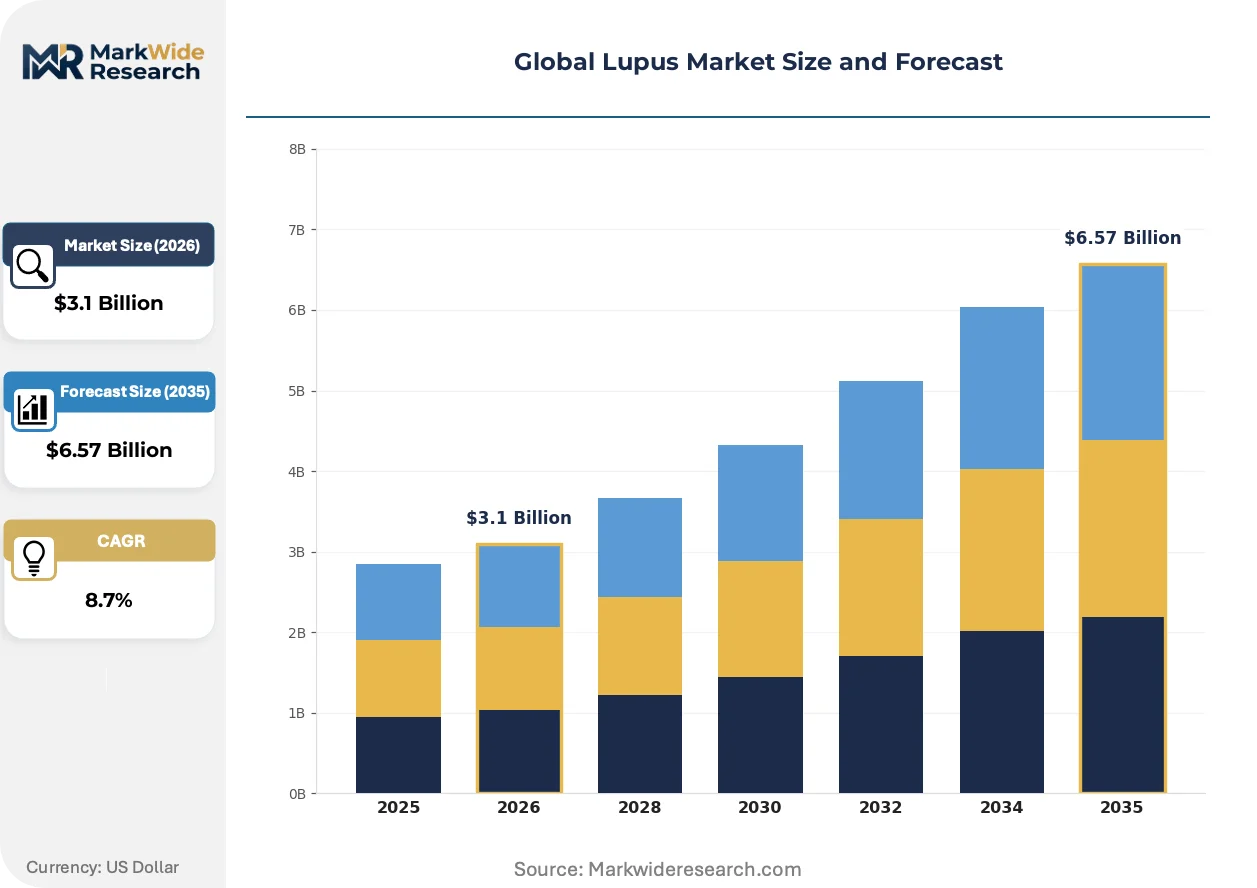
Biologic infusion capacity expansion across rheumatology centers is compressing patient wait times and shifting site-of-care economics, while FDA and EMA accelerated review pathways are shortening development-to-commercialization cycles for novel lupus therapies.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Priority review vouchers and rolling submissions compress regulatory timelines for lupus nephritis candidates. Developers leverage this pathway to reach commercialization faster than standard BLA routes.
- Subcutaneous formulation adoption:Specialty clinics in the United States and Germany are converting IV infusion suites to self-administration training centers. This shift reduces hospital overhead and expands patient access.
- Type I interferon pathway targeting:Anifrolumab's mechanism validation has opened competitive development of interferon receptor antagonists. Multiple candidates now advance through Phase II trials.
Market Restraints
- Plasma-derived raw material concentration:Immunoglobulin and albumin supply chains concentrate among fractionators in the United States and Germany. Any disruption to Cohn fractionation capacity propagates through biologic manufacturing.
- EU MDR compliance burden:Legacy immunosuppressant devices and combination products face recertification costs that disproportionately burden mid-cap sponsors. Notified body capacity constraints extend timelines.
- Biosimilar erosion threat:Belimumab biosimilars entering European markets are compressing originator pricing power. Reference product sponsors face margin defense in maintenance therapy segments.
Strategic Opportunities
- Japan's aging SLE population:PMDA's Sakigake designation offers priority review for lupus nephritis therapies addressing this demographic. Local partnership requirements create JV opportunities for Western sponsors.
- Digital biomarker integration:Wearable-derived disease activity indices are converging with electronic patient-reported outcomes. This combination enables decentralized trial designs and real-world evidence generation.
- Infusion-center network gaps in Brazil:ANVISA's streamlined approval for reference biologics allows first-movers to establish captive infusion infrastructure before biosimilar competition intensifies.
Industry Challenges
- Lupus heterogeneity in trial design:Flare-based endpoints require larger enrollment than sustained response measures. Sponsors struggle to power studies for heterogeneous phenotypes without biomarker stratification.
- REMS program operational complexity:FDA-mandated risk evaluation and mitigation strategies for immunosuppressants require certified prescriber networks. Healthcare systems face administrative burden in maintaining compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lupus Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.57 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Non-Steroidal Anti-Inflammatory Drugs, Corticosteroids, Antimalarials, Immunosuppressants Therapy Area: Systemic Lupus Erythematosus, Discoid Lupus, Drug-Induced Lupus, Neonatal Lupus End User: Specialty Clinics, Research Institutes, Rheumatology Centers, Diagnostic Laboratories Delivery Mode: Oral, Intravenous, Subcutaneous, Topical, Intramuscular |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Sanofi, Roche, Bristol-Myers Squibb, Pfizer, Novartis, Aurinia Pharmaceuticals, UCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lupus Market Strategic Shifts & Innovations
Targeted B-cell depletion and interferon modulation are displacing broad immunosuppression as first-line biologic strategies, while real-world evidence generation is reshaping post-approval differentiation and payer negotiation leverage.
CAR-T constructs adapted for SLE are absorbing preclinical investment from oncology-focused cell therapy platforms. Academic medical centers in Germany and the United States have opened first-in-human protocols. This technology is absorbing development resources that previously flowed to small-molecule BTK inhibitors, compressing that competitive set's expansion timeline.
EMA's PRIME eligibility criteria now explicitly reward lupus nephritis programs with biomarker-enriched patient selection. Sponsors gain accelerated assessment and scientific advice meeting access. Renal biopsy stratification protocols are most affected, with EU5 sites adopting centralized pathology review to meet qualification standards.
Specialty pharmacy distribution is consolidating patient onboarding and adherence monitoring functions previously fragmented across hospital outpatient departments. Hub services now manage prior authorization, copay assistance, and injection training. This consolidation is most visible in United States commercial plans, where pharmacy benefit managers have carved out lupus biologics into limited distribution networks.
Global Lupus Market Segmentation
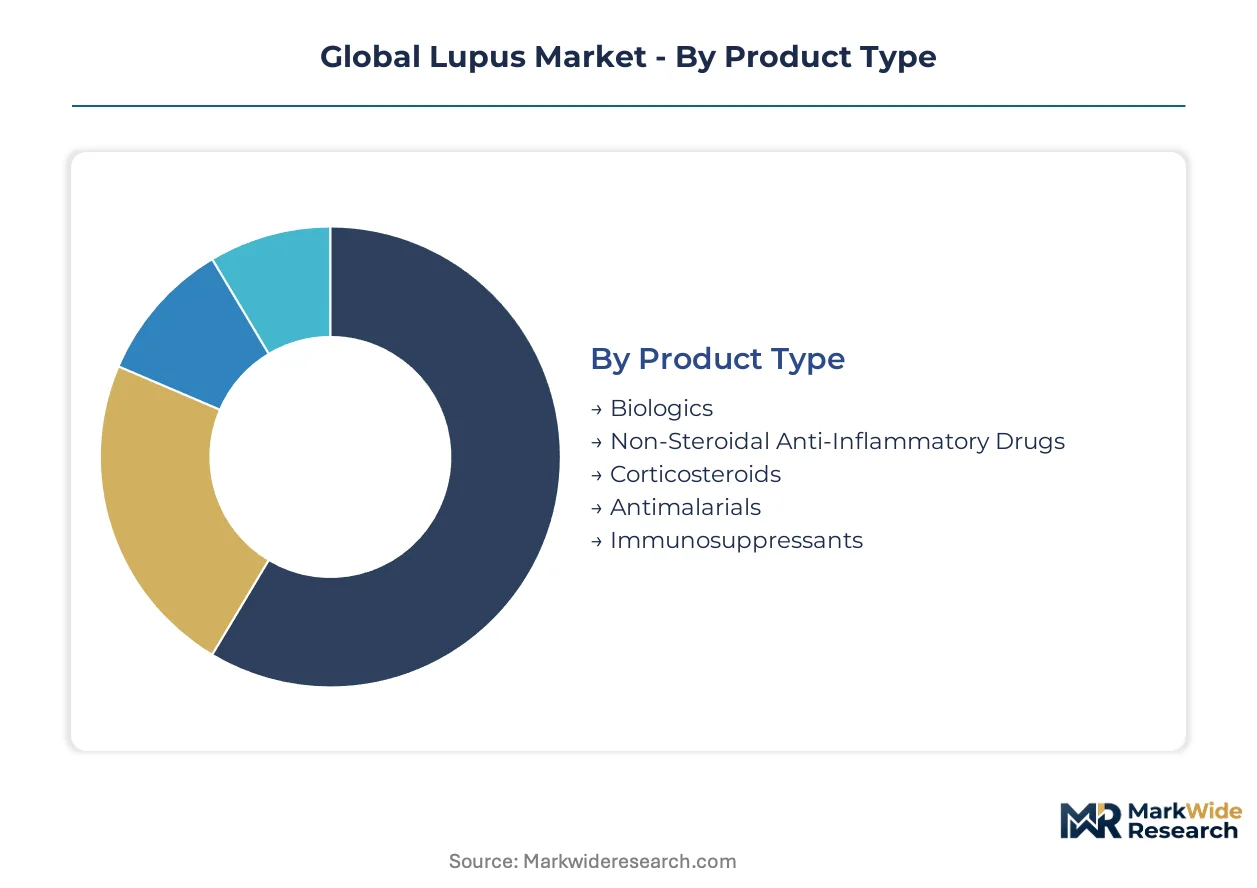
Lupus market segmentation reflects the tension between precision immunology and cost-driven maintenance protocols. Therapy selection varies sharply by organ involvement severity, reimbursement tier, and site-of-care infrastructure across major markets.
Product Type:
Standardization dominates maintenance categories while biologics demand customization through companion diagnostics and biomarker stratification.
- Biologics:Engineered monoclonal antibodies and fusion proteins target specific cytokine pathways or B-cell populations. Demand concentrates in systemic lupus erythematosus with renal involvement, where belimumab and anifrolumab have established reimbursement pathways in the United States and Germany. Premium positioning depends on demonstrated steroid-sparing effects in lupus nephritis.
- Immunosuppressants:Small-molecule agents including mycophenolate mofetil and azathioprine form the backbone of maintenance protocols. Volume flows through rheumatology centers in Japan and the United States managing moderate-to-severe flares, constrained by teratogenicity warnings and mandatory REMS documentation.
- Corticosteroids:Prednisone and methylprednisolone remain ubiquitous for acute flare management.
- Antimalarials:Hydroxychloroquine serves as first-line background therapy across all lupus subtypes.
- Non-Steroidal Anti-Inflammatory Drugs:Ibuprofen and naproxen address mild musculoskeletal symptoms with limited organ involvement.
Most installed capacity flows through Immunosuppressants. Expansion is steepest in Biologics.
Therapy Area:
Clinical complexity and unmet need intensity create divergent investment returns across this category.
- Systemic Lupus Erythematosus:Multi-organ autoimmune disorder with highest mortality and hospitalization burden. Development pipelines concentrate here, with FDA Breakthrough Therapy designations and EMA PRIME eligibility accelerating renal biopsy-stratified trials in the United States and EU5 markets.
- Discoid Lupus:Cutaneous-limited form with lower mortality but significant quality-of-life impairment. Demand localizes to dermatology practices seeking topical alternatives to systemic immunosuppression, particularly in Germany and France where phototherapy access is well-established.
- Drug-Induced Lupus:Reversible syndrome triggered by procainamide, hydralazine, or minocycline.
- Neonatal Lupus:Transient condition associated with maternal anti-Ro/SSA antibodies.
Systemic Lupus Erythematosus commands the deepest development investment. Discoid Lupus offers the most accessible entry point for topical biologic formulations.
End User:
Site-of-care economics and infusion infrastructure availability determine prescribing patterns across customer types.
- Rheumatology Centers:Hospital-affiliated departments with biologic infusion capacity and renal pathology partnerships. Germany and Japan have expanded dedicated lupus units, capturing complex nephritis referrals and biologic-naive patients requiring induction therapy.
- Specialty Clinics:Outpatient settings converting IV suites to subcutaneous self-administration training. United States commercial plans increasingly route maintenance biologics through these sites to reduce hospital overhead.
- Research Institutes:Academic medical centers running interventional trials and CAR-T protocols.
- Diagnostic Laboratories:Centralized pathology services supporting renal biopsy stratification and complement testing.
Rheumatology Centers process the highest-acuity cases. Specialty Clinics are gaining share fastest in maintenance therapy segments.
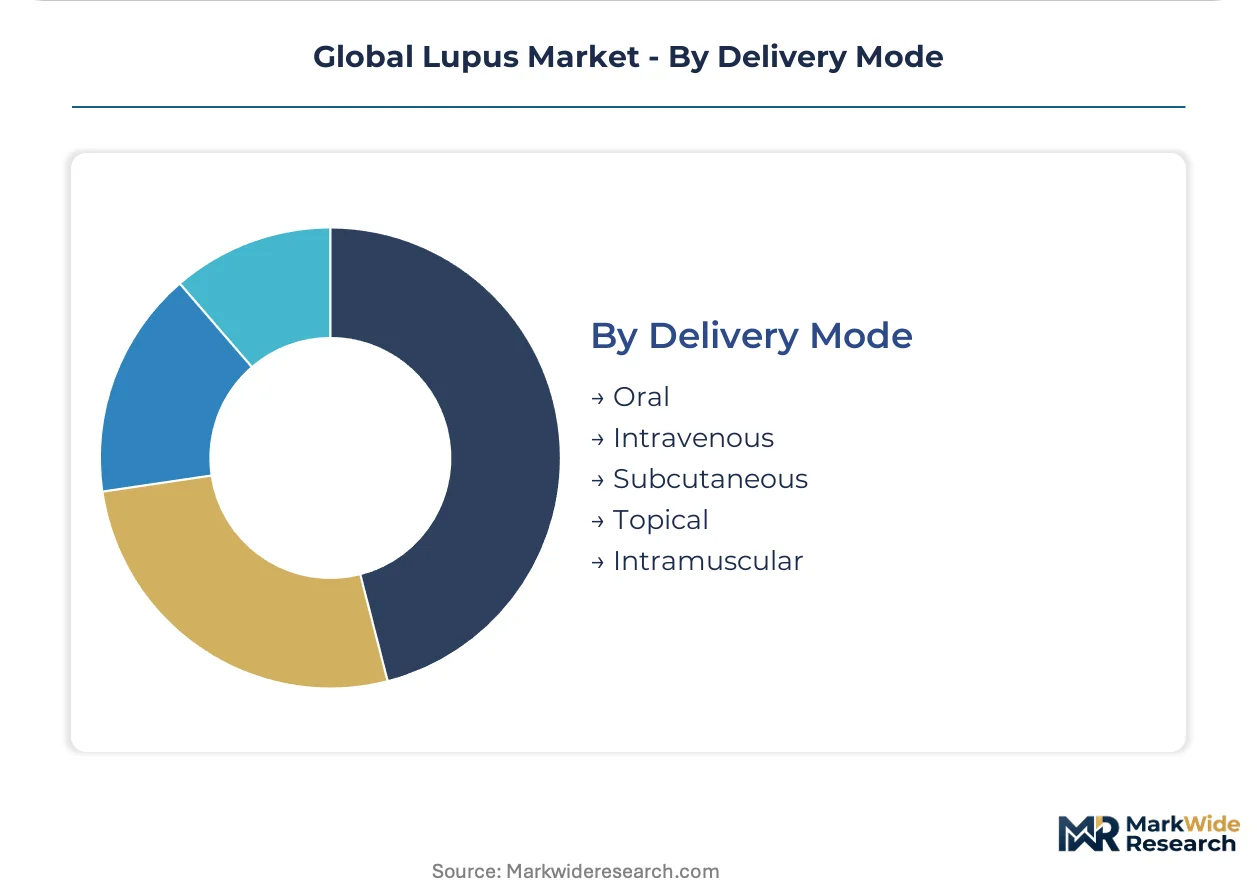
Delivery Mode:
Patient convenience and reimbursement site-of-care differentials are reshaping formulation development priorities.
- Intravenous:Hospital-based administration for induction dosing and acute flares requiring monitoring. Capacity expansion across United States infusion centers has compressed wait times, though Germany retains stricter hospital-only policies for certain biologics.
- Subcutaneous:Self-administered formulations reducing healthcare utilization. Adoption accelerates in United States specialty pharmacy networks and German ambulatory care settings where patients demonstrate injection competence.
- Oral:Small-molecule maintenance therapies including voclosporin for lupus nephritis.
- Topical:Localized cutaneous lupus management with limited systemic exposure.
- Intramuscular:Depot corticosteroid formulations for bridging therapy.
Intravenous retains dominance in induction phases. Subcutaneous formulations are climbing the fastest as maintenance protocols shift to outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatology centers in the United States, Germany, and Japan anchor global biologic infusion capacity for lupus therapeutics. Regulatory pathways at FDA, EMA, and PMDA compress development timelines. Demand concentrates where hospital infrastructure and reimbursement frameworks align.
United States
Specialty clinics in Texas and Florida convert IV suites to subcutaneous training centers for maintenance therapy. FDA Breakthrough Therapy designation accelerates lupus nephritis trials through rolling submissions. The Boston-Cambridge corridor hosts academic medical centers running CAR-T protocols for refractory systemic lupus erythematosus.
Germany
Hospital-affiliated rheumatology departments in Bavaria and North Rhine-Westphalia capture complex nephritis referrals requiring induction biologics. EMA PRIME eligibility grants accelerated assessment for biomarker-stratified trials. Berlin and Munich maintain centralized renal pathology review networks qualifying EU5 trial sites.
Japan
PMDA's Sakigake designation prioritizes review for therapies addressing the aging SLE population in Kanto and Kansai regions. Local partnership requirements create joint venture opportunities for Western sponsors. Tokyo and Osaka house dedicated lupus units with biologic-naive patient capture.
United Kingdom
NICE reimbursement negotiations for biologics versus biosimilars reshape prescribing economics across NHS infusion centers. London and Manchester rheumatology departments balance cost containment with access to novel interferon pathway inhibitors. MHRA post-Brexit recognition pathways influence sponsor filing strategies.
Brazil
ANVISA's streamlined approval for reference biologics allows first-movers to establish captive infusion infrastructure in São Paulo and Rio de Janeiro. Network gaps outside southeast metros create opportunity before biosimilar competition intensifies. Private insurance expansion drives biologic access beyond public formulary limitations.
Global Lupus Market Key Industry Players
Global majors compete with regional champions across immunology infrastructure and rare-disease reach. The structure tiers between large-cap pharmaceutical conglomerates with diversified autoimmune portfolios and mid-cap specialists concentrated in nephrology indications. Three archetypes dominate: diversified immunology platforms, rare-disease infrastructure deployers, and nephrology-focused developers. Competitive moves center on M&A for pipeline assets and strategic partnerships for emerging market access.
Within the large-cap immunology tier, GlaxoSmithKline and AstraZeneca exemplify platform breadth. GlaxoSmithKline occupies a position anchored by deep portfolio development through dedicated immunology divisions. AstraZeneca represents the rare-disease infrastructure archetype, extending access into emerging markets through existing specialty networks. Aurinia Pharmaceuticals sits within the nephrology specialist category, holding position through oral therapy differentiation in lupus nephritis.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Sanofi |
| Roche |
| Bristol-Myers Squibb |
| Pfizer |
| Novartis |
| Aurinia Pharmaceuticals |
| UCB |
| Others |
Cost & Logistics Intelligence
Plasma protein fractionation indices in the United States and Germany cascade through monoclonal antibody production costs, stratifying lupus biologics into premium infusion-tier, standard subcutaneous, and economy maintenance segments based on raw material exposure and manufacturing complexity.
Pricing Analysis
Input-cost pass-through from immunoglobulin and albumin supply volatility shapes three-tier pricing structure across premium, standard, and economy levels. FDA REMS compliance costs and EMA MDR recertification burdens differentiate certified biologic tiers from legacy immunosuppressant maintenance protocols. Pricing pressure stems from belimumab biosimilar entry into European markets, compressing originator margins in maintenance segments. Hospital procurement committees exhibit highest price sensitivity for induction-phase biologics, while specialty pharmacy networks absorb premium positioning for self-administered formulations.
Supply Chain Analysis
Dual-sourcing requirements for plasma-derived raw materials mandate qualification of multiple Cohn fractionation suppliers across the United States, Germany, and Japan. Monoclonal antibody production draws from recombinant cell culture media, single-use bioreactor systems, and chromatography resins. Single-source vulnerability concentrates in albumin supply from North American fractionators. Distribution runs through captive infusion-center networks in major metros, with specialty pharmacy hubs managing last-mile delivery for subcutaneous formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
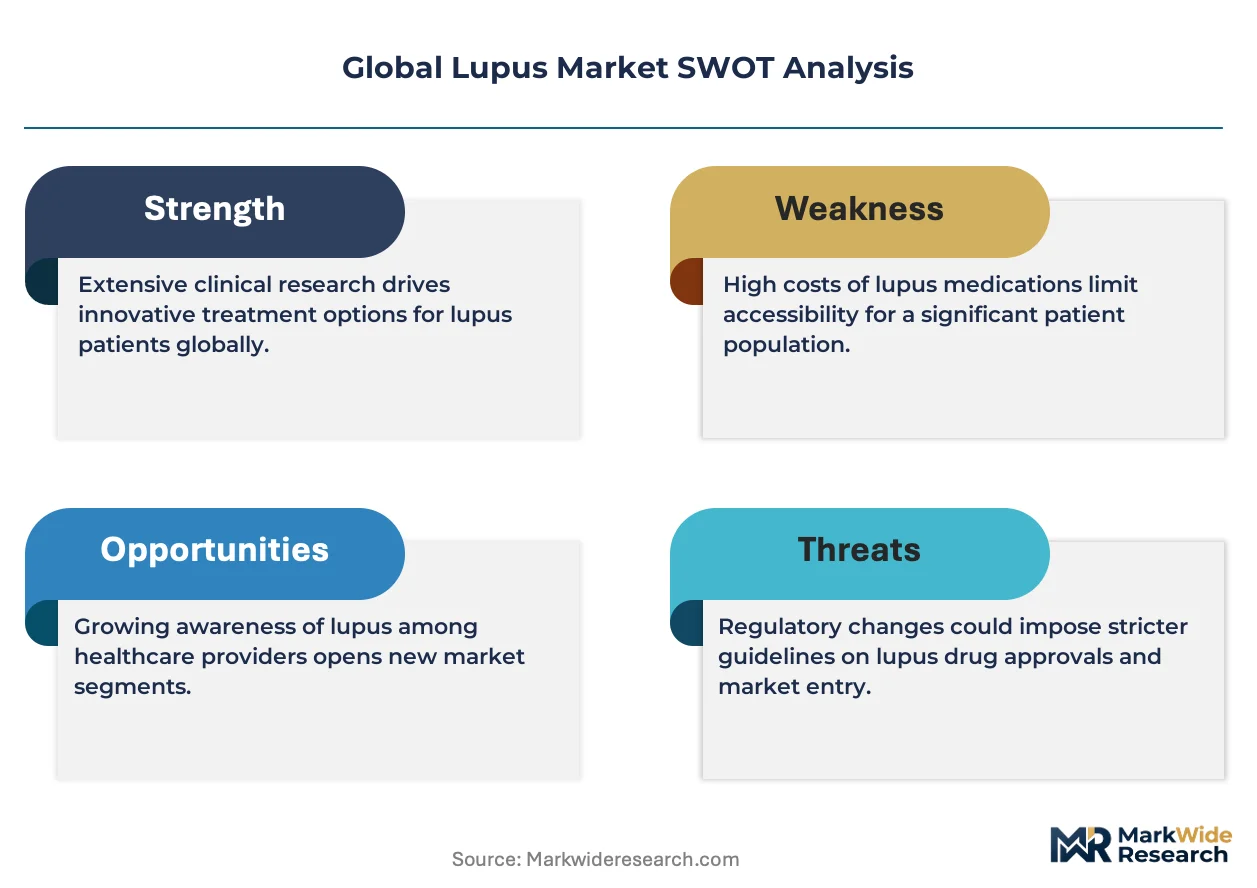
Margin expansion in lupus therapeutics rests on steroid-sparing clinical differentiation commanding premium tier positioning, while subcutaneous formulation adoption reduces hospital overhead and shifts site-of-care economics toward outpatient capture.
For Market Incumbents: Deploy biomarker-stratified trial designs to defend against interferon-pathway competitor entry. Deepen renal biopsy partnership networks in Germany and Japan to lock high-acuity referral flows. Expand subcutaneous training infrastructure in United States specialty clinics before biosimilar pressure intensifies in maintenance segments. For New Entrants and Emerging Players: The price-point gap between IV induction biologics and oral maintenance small-molecules offers entry through hybrid clinic-infusion models in Brazil and Southeast Asian markets. Target ANVISA-streamlined approval pathways to establish captive infrastructure before reference biologic competition saturates. Lead with real-world evidence generation partnerships to differentiate in payer negotiations. For Investors and Strategic Acquirers: Asymmetric upside sits with nephrology-focused developers holding oral therapy differentiation and renal biopsy stratification capabilities. Long-term viability favors platforms with both biologic and small-molecule assets spanning induction and maintenance protocols. Watch CAR-T protocol enrollment velocity in German and United States academic centers as inflection signal for cell therapy platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Enriched Trial Design | EMA PRIME eligibility accelerates assessment for renal biopsy-stratified lupus nephritis programs. |
| Subcutaneous Formulation Conversion | Specialty clinics in Texas and Florida reduce hospital overhead through self-administration training infrastructure. |
| Plasma Fractionator Dual-Qualification | Multi-source API procurement hedges against Cohn fractionation disruption in United States and Germany. |
| Infusion-Center Network Expansion | First-movers in São Paulo and Rio de Janeiro establish captive infrastructure before biosimilar entry. |
| Digital Biomarker Integration | Wearable-derived disease activity indices enable decentralized trial designs and real-world evidence generation. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded qualitative findings, validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down revenue triangulation cross-verified segment sizing across therapy area, product type, and delivery mode dimensions.
Bottom-up volume estimates tracked treatment lines, dosage forms, administration routes, and regional regulatory clusters, while top-down approaches validated against immunology division revenue disclosures. CAGRs derived from patient prevalence projections, biologic penetration curves, and pricing trajectory assumptions across the analysis window. Forecast inputs incorporated rheumatology center expansion rates, subcutaneous conversion velocities, and biosimilar launch sequencing.
The model assumes a particular technology adoption path; alternative pathways for CAR-T constructs or interferon receptor antagonists would alter the outlook. Forecasts reflect assumptions about regulatory pathway efficiency, reimbursement negotiation outcomes, and plasma supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Generalized Anxiety Disorder (GAD) Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Epistaxis Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Bartter Syndrome Treatment Market
Specialty Medicine
Global Interstitial Cystitis Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Cystic Fibrosis Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
Herpes Zoster (Shingles) Market
Specialty Medicine
Paediatric Sports Medicine Market