
 Nephrology Drugs Market | 2026-2036
Nephrology Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrology Drugs Market Outlook
The buyer base for nephrology therapeutics is broadening as dialysis chains consolidate procurement while independent clinics fragment into specialized renal care networks. AstraZeneca leverages its SGLT2 inhibitor portfolio to anchor presence across chronic kidney disease stages. Amgen Inc. sustains dominance in erythropoiesis-stimulating agents through manufacturing scale and biologic production expertise. F. Hoffmann-La Roche competes in diagnostic-anchored therapy protocols that pair biomarker testing with drug selection.
Nephrology drugs comprise pharmaceutical agents engineered to modulate renal function, electrolyte balance, and hematologic parameters in compromised kidneys, with formulations requiring precise bioavailability profiles due to altered glomerular filtration. These agents serve to delay disease progression, manage uremic complications, and reduce cardiovascular mortality in renal patient populations. Erythropoiesis-stimulating agents and phosphate binders represent mature categories where biosimilar competition intensifies, while SGLT2 inhibitors and novel non-steroidal mineralocorticoid receptor antagonists capture expanding margin pools in earlier-stage chronic kidney disease. Oral delivery modes dominate outpatient prescribing, though intravenous administration retains structural importance in dialysis center protocols where adherence monitoring is centralized.
The FDA oversees nephrology drug approval through renal-specific efficacy endpoints and cardiovascular outcome trial requirements, while the EMA's Committee for Medicinal Products for Human Use evaluates renal-adjusted dosing guidelines across European markets. The IRA's Medicare price negotiation provisions directly reshape revenue trajectories for top-selling agents in the United States, forcing manufacturers to recalibrate launch strategies and geographic prioritization. Stakeholders must monitor evolving biomarker-driven trial designs and real-world evidence requirements that regulators increasingly embed into labeling decisions.
Market Dynamics
Medicare price negotiation under the IRA is compressing revenue trajectories for established nephrology agents while accelerating manufacturer investment in earlier-stage chronic kidney disease categories with longer exclusivity windows.
Growth Catalysts
- SGLT2 inhibitor expansion:Cardiovascular outcome data drives nephrologist prescribing toward glucose-lowering agents with renal protective effects. Dialysis chains now integrate these into pre-ESKD protocols.
- EMA renal-adjusted dosing harmonization:Streamlined European guidelines reduce clinical trial duplication costs. Manufacturers gain faster cross-border label extensions for dose-optimized formulations.
- Biomarker-driven trial designs:Urine proteomics and GFR slope endpoints accelerate FDA approval pathways. Regulators accept surrogate markers that shorten development timelines by 18-24 months.
Market Restraints
- Active pharmaceutical ingredient concentration:China dominates synthesis of phosphate binder raw materials. Single-source dependencies expose formulators to geopolitical supply interruptions.
- Biosimilar erosion in erythropoiesis-stimulating agents:Reference product price declines exceed 60% in European tenders. Originators face margin compression with limited differentiation levers.
- Reimbursement lag for novel mechanisms:CMS national coverage determinations trail FDA approval by 14-18 months. Payers demand real-world evidence before formulary inclusion.
Strategic Opportunities
- Non-steroidal mineralocorticoid receptor antagonists:Finerenone-class agents address residual albuminuria risk in diabetic kidney disease. Prescribing shifts earlier in disease progression capture lifetime value.
- Home dialysis penetration:Peritoneal dialysis growth in Brazil and Mexico outpaces clinic-based hemodialysis. Oral agent demand rises where infusion infrastructure is scarce.
- Real-world evidence mandates:FDA's Project Orbis creates parallel review pathways across US, Canada, Australia. Post-market study commitments become competitive differentiators.
Industry Challenges
- Nephrology-specialized clinical trial infrastructure:Principal investigator scarcity delays enrollment in rare renal disease indications. Academic medical centers with dedicated renal units command premium site fees.
- Legacy electronic health record integration:Dialysis center software platforms lack interoperability with biomarker reporting systems. Data fragmentation obstructs quality-based contracting.
- Patent cliff coordination:Loss of exclusivity on oral phosphate binders overlaps with IRA negotiation timelines. Portfolio managers face simultaneous generic and government pricing pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrology Drugs Market |
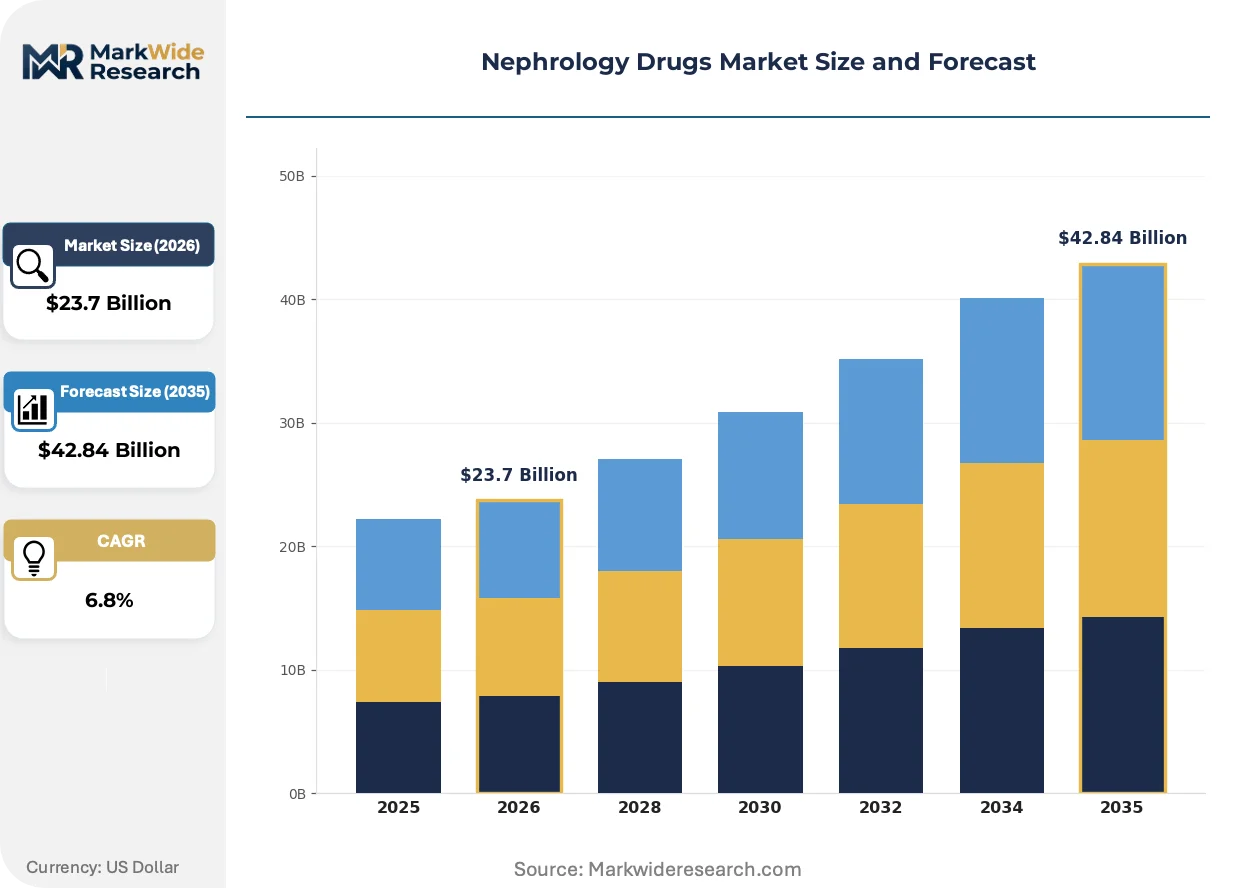
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erythropoiesis-Stimulating Agents, Phosphate Binders, Diuretics, Antihypertensive Agents Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular Indication: Chronic Kidney Disease, End-Stage Renal Disease, Acute Kidney Injury, Hypertensive Urgency End User: Hospitals, Clinics, Dialysis Centers, Home Care |
| Companies Covered | AstraZeneca, Amgen Inc., F. Hoffmann-La Roche, Pfizer Inc., Johnson & Johnson, AbbVie Inc., Novartis AG, Teva Pharmaceutical Industries Limited, GlaxoSmithKline plc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrology Drugs Market Strategic Shifts
Renal therapeutics development is pivoting from end-stage complication management toward interceptive strategies that preserve residual kidney function. Three intersecting developments define this transition.
Oral small-molecule formulations are modularizing nephrology drug development by enabling fixed-dose combinations that previously required separate infusions. Dialysis-dependent patients now receive iron supplementation, phosphate control, and active vitamin D through single tablet regimens. DaVita and Fresenius Medical Care are consolidating formularies around these streamlined protocols to reduce nursing administration burden.
The IRA's Medicare price negotiation provisions are restructuring launch sequencing for renal agents with cardiovascular indications. Manufacturers now prioritize commercial payer contracts before Medicare exposure to establish pricing floors. Agents with dual kidney-heart labels face compressed commercial-to-Medicare transition windows that reshape lifecycle management investments.
Specialized renal pharmacies are displacing traditional retail distribution for complex oral therapies. Accredo and BioScrip anchor hub-and-spoke models that integrate adherence monitoring with refill logistics. United States nephrology practices increasingly mandate these channels for phosphate binders and calcimimetics to capture performance-based reimbursement tied to laboratory targets.
Nephrology Drugs Market Segmentation
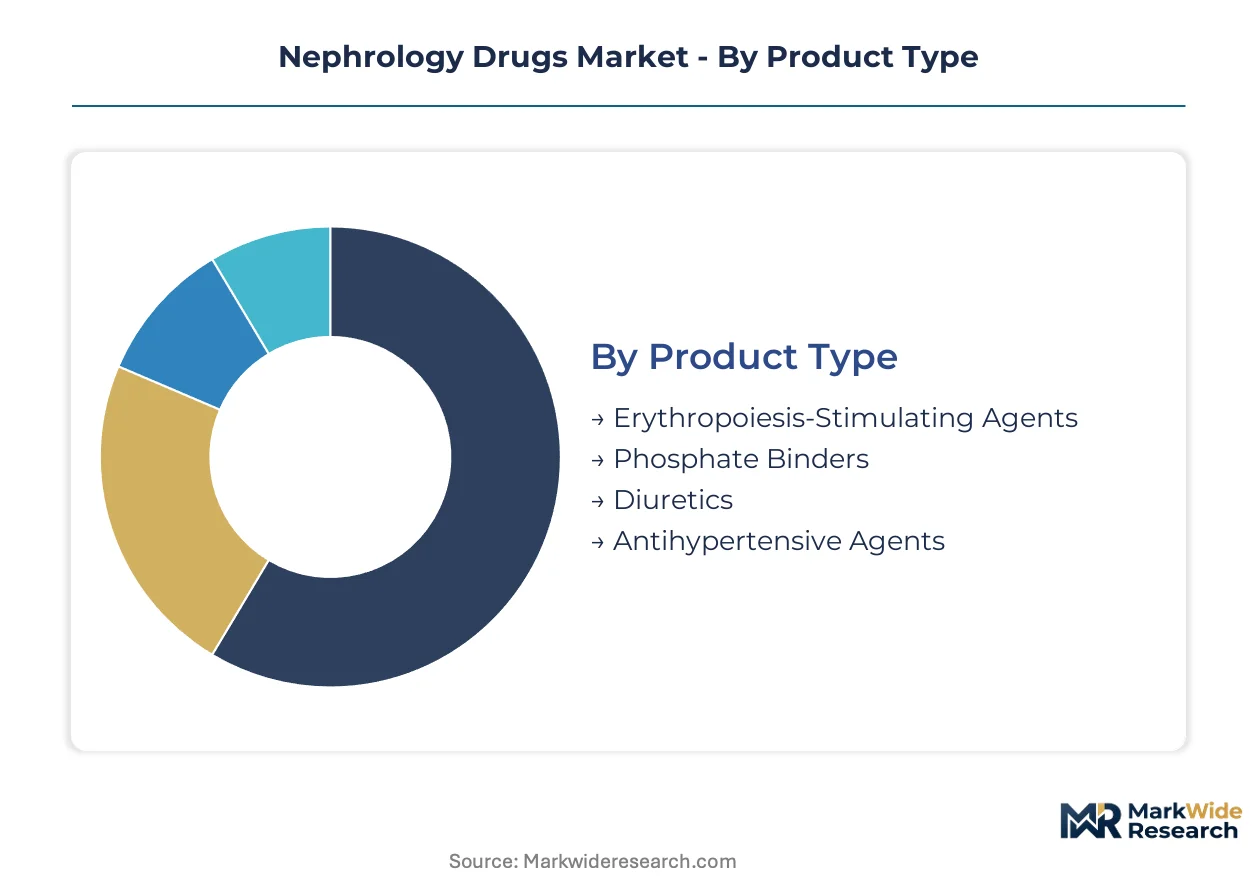
Nephrology drug segmentation reveals divergent margin structures across therapeutic categories. Product type and delivery mode classifications expose where biosimilar pressure concentrates versus where novel mechanisms command premium pricing.
Product Type:
Volume-heavy erythropoiesis agents contrast with premium-priced SGLT2 inhibitors and mineralocorticoid antagonists entering earlier disease stages.
- Erythropoiesis-Stimulating Agents:Recombinant proteins (epoetin alfa, darbepoetin alfa) stimulate red blood cell production in anemic dialysis patients. Demand concentrates in United States dialysis centers where Medicare bundled payments incentivize efficient anemia management. Biosimilar entry has compressed originator margins by over sixty percent in European tenders.
- Phosphate Binders:Calcium-based and polymer-based formulations (sevelamer, lanthanum, sucroferric oxyhydroxide) control hyperphosphatemia in end-stage renal disease. Oral tablet demand dominates outpatient prescribing in Brazil and Mexico where home dialysis penetration outpaces clinic infrastructure expansion. Generic competition and IRA price negotiation create simultaneous pricing pressure.
- Diuretics:Loop and thiazide agents manage fluid overload in earlier chronic kidney disease stages.
- Antihypertensive Agents:ACE inhibitors and ARBs slow glomerular filtration rate decline in proteinuric patients.
Today's leader: Phosphate Binders. Tomorrow's challenger: SGLT2 inhibitor expansion reshaping the category map.
Delivery Mode:
Route of administration determines reimbursement coding, site-of-care economics, and patient adherence monitoring requirements across renal therapy protocols.
- Oral:Fixed-dose combinations of phosphate binders, iron supplements, and active vitamin D streamline outpatient regimens. Dialysis chains DaVita and Fresenius consolidate formularies around single-tablet protocols to reduce nursing burden in United States clinics.
- Intravenous:Iron sucrose and sodium ferric gluconate complex enable direct hemoglobin response monitoring in dialysis center settings. Administration retains structural importance where adherence verification is centralized and reimbursement ties to laboratory targets.
- Subcutaneous:Erythropoiesis-stimulating agent delivery in home dialysis programs.
- Intramuscular:Depot formulations for long-acting vitamin D analogs in resource-limited settings.
Oral agents capture volume growth as home dialysis expands. Intravenous retains value capture in consolidated clinic networks.
Indication:
Disease stage segmentation separates mature end-stage markets from earlier-intervention opportunities with longer exclusivity windows.
- Chronic Kidney Disease:SGLT2 inhibitors and finerenone-class mineralocorticoid antagonists target albuminuria reduction before dialysis dependency. Prescribing shifts earlier as cardiovascular outcome data drives nephrologist adoption in United States academic medical centers.
- End-Stage Renal Disease:Established erythropoiesis support, phosphate control, and calcimimetic therapies dominate dialysis center procurement. Medicare bundled payments in the United States create price-sensitive volume concentration.
- Acute Kidney Injury:Diuretic and vasopressor protocols in intensive care settings.
- Hypertensive Urgency:Rapid-acting antihypertensive bridging to chronic kidney disease management.
End-stage disease commands current revenue concentration. Chronic kidney disease prevention represents the steepest expansion trajectory for novel mechanisms.
End User:
Site-of-care economics fragment procurement authority between consolidated dialysis chains and distributed hospital systems.
- Dialysis Centers:Consolidated buyers DaVita and Fresenius Medical Care negotiate formulary placement for high-volume erythropoiesis and phosphate binder agents. United States Medicare reimbursement policies directly influence prescribing patterns through quality-based payment adjustments.
- Hospitals:Academic medical centers with dedicated renal units command premium clinical trial site fees. Biomarker-driven protocols pair diagnostic testing with therapeutic selection in tertiary care settings.
- Clinics:Independent nephrology practices fragment into specialized renal care networks.
- Home Care:Peritoneal dialysis growth in Latin America drives oral agent demand where infusion infrastructure remains scarce.
Dialysis centers anchor procurement volume. Home care channels are climbing fastest as infrastructure constraints reshape geographic prescribing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dialysis chains consolidate procurement power while Brazil's home dialysis expansion creates divergent demand patterns for oral versus intravenous formulations. Medicare reimbursement structures in North America contrast sharply with Latin America's infrastructure-constrained prescribing environments.
United States
Dialysis center consolidation drives formulary standardization across DaVita and Fresenius Medical Care networks. The IRA's Medicare price negotiation provisions directly reshape revenue trajectories for established erythropoiesis-stimulating agents and phosphate binders. Boston and New York academic medical centers anchor biomarker-driven trial enrollment for novel SGLT2 inhibitor protocols.
Germany
Home dialysis penetration outpaces European averages, elevating demand for fixed-dose oral combinations of phosphate binders and iron supplements. The EMA's Committee for Medicinal Products for Human Use evaluates renal-adjusted dosing guidelines that streamline cross-border label extensions. Baden-Württemberg's pharmaceutical manufacturing corridor hosts formulation facilities serving Central European dialysis networks.
Japan
Aging demographics concentrate end-stage renal disease prevalence in urban centers with established dialysis infrastructure. PMDA review pathways accept cardiovascular outcome data from regional trials for SGLT2 inhibitor label expansions. The Kansai region's Osaka-Kobe medical cluster specializes in peritoneal dialysis device and drug co-development programs.
Brazil
Peritoneal dialysis growth outpaces clinic-based hemodialysis as public health programs expand home-based care coverage. ANVISA regulatory frameworks prioritize bioequivalence studies for generic phosphate binder entry. São Paulo's private hospital networks pilot integrated renal care protocols combining diagnostic testing with therapeutic selection.
China
Domestic production of active pharmaceutical ingredients for phosphate binders concentrates supply chain control within national borders. NMPA accelerated approval pathways target renal protective agents with cardiovascular outcome benefits. The Yangtze River Delta's Shanghai-Suzhou corridor anchors contract manufacturing for oral small-molecule nephrology formulations.
Nephrology Drugs Market Competitive Environment
United States-based pharmaceutical conglomerates anchor one tier with integrated cardiovascular-renal portfolios; European specialists hold differentiated positions in diagnostic-anchored therapy protocols. Market structure tilts toward consolidated procurement power as dialysis chains consolidate formularies around streamlined administration protocols. Three archetypes dominate: biologic manufacturers with manufacturing scale advantages, diversified conglomerates leveraging SGLT2 inhibitor cross-indication data, and diagnostic-therapy integrators pairing biomarker testing with drug selection. Dominant competitive moves include portfolio diversification into earlier-stage chronic kidney disease categories and strategic partnerships with dialysis center networks for formulary placement.
Among diversified pharmaceutical conglomerates, AstraZeneca and Pfizer occupy positions defined by cardiovascular-renal cross-label expansion strategies. Amgen Inc. exemplifies the biologic manufacturing archetype through erythropoiesis-stimulating agent production expertise. F. Hoffmann-La Roche sits within the diagnostic-therapy integration tier, pairing biomarker testing infrastructure with therapeutic selection protocols in tertiary care settings.
| Leading Market Players |
|---|
| AstraZeneca |
| Amgen Inc. |
| F. Hoffmann-La Roche |
| Pfizer Inc. |
| Johnson & Johnson |
| AbbVie Inc. |
| Novartis AG |
| Teva Pharmaceutical Industries Limited |
| GlaxoSmithKline plc. |
| Others |
Value Chain & Pricing Dynamics
Oral small-molecule formulation advances are compressing manufacturing costs for fixed-dose combinations while concentrating procurement leverage within consolidated dialysis chains. This production-method transition simultaneously lowers per-unit production expenses and amplifies buyer power in formulary negotiations.
Pricing Analysis
Capacity additions in China are reshaping price floors for phosphate binder active pharmaceutical ingredients. Contract-based long-term offtake agreements dominate procurement between dialysis chains and manufacturers, with price differentiation resting on manufacturing scale and FDA certification tier. Cost compression in erythropoiesis-stimulating agents is intensifying because biosimilar entry erodes originator margins. Dialysis center networks exhibit highest price sensitivity due to Medicare bundled payment constraints, while academic medical centers show lowest sensitivity where biomarker-driven protocols command therapeutic premiums.
Supply Chain Analysis
Single-source vulnerability sits with China for phosphate binder raw material synthesis. Active pharmaceutical ingredient production concentrates in China, India, and the United States, drawing from lanthanum carbonate, sevelamer hydrochloride, and iron sucrose precursor chemicals. Tariff exposure on Chinese-sourced intermediates presents structural risk for formulators lacking alternative supplier qualification. Distribution runs through specialized renal pharmacies that integrate adherence monitoring with direct-to-patient logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in nephrology therapeutics rests on the shift toward earlier-stage chronic kidney disease intervention, where SGLT2 inhibitors and novel mineralocorticoid antagonists command premium pricing before Medicare exposure.
For Market Incumbents: Extend manufacturing scale advantages into biosimilar-ready categories by securing captive supply of active pharmaceutical ingredients from Yangtze River Delta contract manufacturers. Fortify formulary placement through fixed-dose combination development that reduces nursing administration burden for DaVita and Fresenius Medical Care networks. IRA price negotiation timelines threaten established phosphate binder revenue streams, necessitating earlier-stage pipeline investment. For New Entrants and Emerging Players: Launch via hub-and-spoke specialty pharmacy partnerships that integrate adherence monitoring with refill logistics, bypassing consolidated dialysis chain gatekeepers. Home dialysis penetration in Brazil and Mexico represents the most penetrable geography, where oral agent demand outpaces infusion infrastructure. Target peritoneal dialysis patient populations with single-tablet regimens combining phosphate control, iron supplementation, and active vitamin D. For Investors and Strategic Acquirers: Roll-up economics work for diagnostic-therapy integrators because biomarker-driven trial designs increasingly pair testing infrastructure with therapeutic selection protocols. Five-to-ten year viability favors platforms combining renal-adjusted dosing expertise with cardiovascular outcome trial capabilities. Watch FDA Project Orbis parallel review commitments as inflection indicator for cross-border label extension velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | DaVita and Fresenius consolidate formularies around single-tablet protocols to reduce nursing burden. |
| Specialty Pharmacy Partnership | Accredo and BioScrip anchor hub-and-spoke models integrating adherence monitoring with refill logistics. |
| Biomarker-Driven Trial Enrollment | Boston and New York academic medical centers anchor novel SGLT2 inhibitor protocol adoption. |
| Active Pharmaceutical Ingredient Backward Integration | Shanghai-Suzhou corridor contract manufacturers secure phosphate binder raw material supply. |
| Home Dialysis Channel Expansion | Peritoneal dialysis growth in São Paulo private hospital networks pilots integrated renal care protocols. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare reimbursement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Segment-weighted forecasting applied therapeutic category, delivery mode, disease stage, and end-user site-of-care dimensions across the projection horizon. CAGRs derived from patent expiry timelines, biosimilar entry curves, and regulatory approval velocity for novel mechanisms. Forecast inputs incorporated IRA Medicare price negotiation phase-in schedules and dialysis center consolidation trajectories.
Several conditions sit outside the modeled scope, including geopolitical supply interruptions for Chinese-sourced active pharmaceutical ingredients and unanticipated cardiovascular outcome trial failures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Chickenpox Vaccine Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Photophobia Drug Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Dystonia Drugs Market
Pharmaceuticals
Xerostomia Therapeutics Market
Pharmaceuticals
Pembrolizumab Market
Pharmaceuticals
Global Orphan Drugs Market
Pharmaceuticals
Triamcinolone Ointment Chlorofluorocarbons Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Systemic Antibiotics Market
Pharmaceuticals
Anti-Inflammatory Biologics Market
Pharmaceuticals
Ocular Excipients Market
Pharmaceuticals
Global Seasonal Influenza Vaccines Therapeutics Market
Pharmaceuticals
Prostaglandin Analogs Market