
 Global Cardiovascular Drugs Market | 2026-2036
Global Cardiovascular Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiovascular Drugs Market Foresight
Biologics licensing and post-market surveillance revenue is reconfiguring how cardiovascular drug manufacturers capture lifetime value per patient. Pfizer Inc. leverages its manufacturing scale to dominate oral anticoagulant supply chains across North American hospital networks. Novartis AG anchors its position through deep specialization in heart failure therapy portfolios. AstraZeneca PLC differentiates via upstream control over active pharmaceutical ingredient production for its hypertension franchises.
Cardiovascular drugs comprise pharmacological agents formulated to modulate cardiac output, vascular tone, platelet aggregation, and lipid metabolism through precise molecular targeting of renin-angiotensin, beta-adrenergic, or coagulation cascade pathways, typically manufactured via recombinant protein synthesis or small-molecule chemical synthesis under strict purity specifications exceeding 99.5 percent. These agents serve the primary commercial purpose of reducing myocardial infarction, stroke, and heart failure hospitalization rates in diagnosed patient populations. Anticoagulants command substantial margin pools due to chronic administration requirements and narrow therapeutic indices that limit generic substitution. The oral administration route retains volume leadership while subcutaneous delivery formats gain traction in ambulatory care centers seeking to reduce infusion chair time.
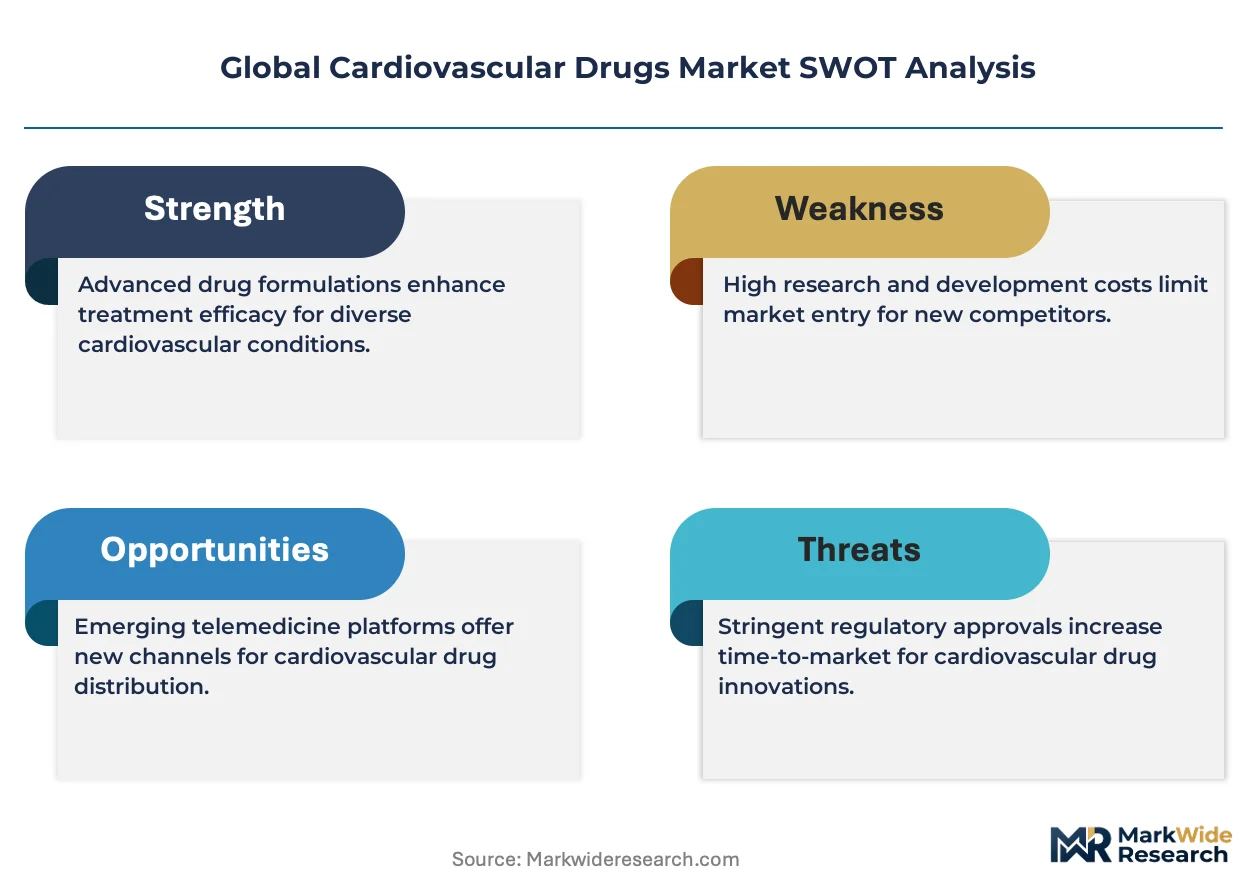
FDA breakthrough therapy designation and EMA priority medicine pathways are compressing development timelines for novel anticoagulants and heart failure therapies, directly shaping R&D investment allocation across the industry. Japan's PMDA has tightened pharmacovigilance reporting requirements for beta blockers and calcium channel blockers, elevating compliance costs for market entrants. China's NMPA accelerated review reforms for innovative cardiovascular compounds are redrawing market access sequencing for multinational portfolios. Stakeholders must monitor how evolving FDA real-world evidence standards and EU MDR clinical data requirements will reshape post-approval study obligations and lifecycle management strategies.
Market Dynamics
FDA breakthrough therapy designation and EMA priority medicine pathways are compressing development timelines for novel anticoagulants and heart failure therapies, directly reshaping R&D investment allocation across the industry.
Growth Catalysts
- Accelerated Regulatory Pathways:FDA breakthrough therapy designation compresses clinical trial phases for novel cardiovascular compounds. EMA priority medicine status expedites market access for heart failure therapies in Germany and France.
- Ambulatory Care Expansion:Hospital-at-home programs in the United States and Japan are expanding subcutaneous anticoagulant administration outside traditional infusion centers. This shift extends therapy duration and patient adherence monitoring.
- Preventive Cardiology Protocols:Germany's statutory health insurance system now reimburses lipid-lowering biologics for high-risk primary prevention populations. This policy expands addressable patient pools beyond established cardiovascular disease diagnoses.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China dominates synthesis of key antihypertensive intermediates including valsartan and amlodipine building blocks. Supply disruptions at NMPA-registered manufacturing facilities create formulation bottlenecks for European and North American finished dose producers.
- Narrow Therapeutic Index Burden:Warfarin and related vitamin K antagonists require continuous INR monitoring infrastructure. This monitoring cost structure limits generic substitution despite patent expirations, preserving originator pricing power but constraining volume expansion in cost-sensitive markets.
- Japan Pharmacovigilance Escalation:PMDA tightened adverse event reporting requirements for beta blockers and calcium channel blockers in 2023. Compliance cost elevation disproportionately burdens mid-scale market entrants without established Japanese safety databases.
Strategic Opportunities
- China NMPA Accelerated Review:Innovative cardiovascular compounds now access priority review timelines previously reserved for oncology. Multinational portfolios can sequence China launches earlier, capturing volume in the world's second-largest pharmaceutical market before European reimbursement negotiations conclude.
- RNA Interference Convergence:Combination of siRNA lipid metabolism modulators with existing statin infrastructure creates novel dyslipidemia treatment paradigms. This technology pairing addresses residual cardiovascular risk in statin-intolerant or insufficiently responsive populations.
- Direct-to-Patient Distribution:Chronic anticoagulant therapy is migrating toward specialty pharmacy and mail-order channels in the United States. This channel innovation reduces hospital outpatient pharmacy dependency and enables adherence program integration.
Industry Challenges
- Real-World Evidence Generation:FDA's evolving standards for post-approval safety and effectiveness data require continuous patient registry investment. Cardiovascular drug sponsors must maintain expensive observational study infrastructure throughout product lifecycles.
- Legacy System Integration:Electronic health record interoperability gaps between hospital cardiology departments and ambulatory monitoring services fragment patient data. This technical debt complicates integrated care pathway implementation for chronic cardiovascular conditions.
- Specialized Manufacturing Workforce:Recombinant protein synthesis for biologic cardiovascular therapies requires technicians trained in single-use bioreactor operations and continuous processing. Talent scarcity in these specialized functions constrains capacity expansion at contract manufacturing organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiovascular Drugs Market |
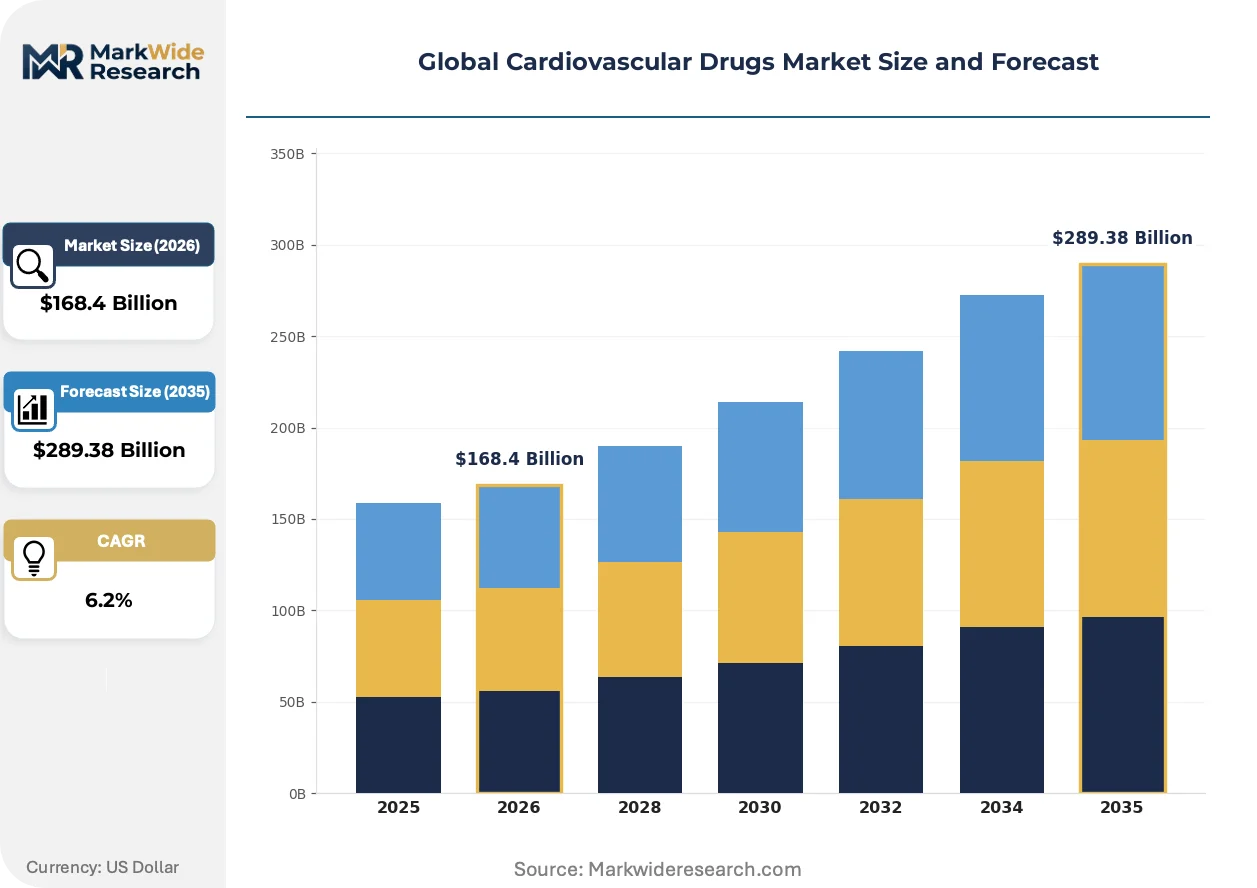
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Beta Blockers, ACE Inhibitors, Calcium Channel Blockers, Anticoagulants, Diuretics Therapy Area: Hypertension, Arrhythmia, Heart Failure, Hyperlipidemia, Atherosclerosis End User: Hospitals, Cardiology Clinics, Specialty Pharmacies, Ambulatory Care Centers Administration Route: Oral, Intravenous, Subcutaneous, Transdermal, Inhalation |
| Companies Covered | Pfizer Inc., Novartis AG, AstraZeneca PLC, Bayer AG, Bristol-Myers Squibb Company, Sanofi S.A., Merck & Co., Inc., Boehringer Ingelheim GmbH, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiovascular Drugs Market Shifts & Advancements
Cardiovascular drug development is pivoting toward precision dosing algorithms and continuous biomarker monitoring, collapsing traditional trial-and-error prescribing models.
Gene-silencing oligonucleotides targeting PCSK9 and lipoprotein(a) are collapsing the chronic administration burden of injectable lipid-lowering therapies. Hospital systems in the United States and Germany are adopting these agents for biannual dosing protocols. This dosing compression reduces infusion chair utilization and enables care migration to lower-acuity settings.
EMA's Medical Device Regulation (MDR) and FDA's Digital Health Software Precertification program are converging on software-as-medical-device classification for cardiovascular risk algorithms. This regulatory alignment accelerates companion diagnostic and therapeutic pairing approvals. Combination product sponsors must now integrate quality management systems across pharmaceutical and device manufacturing standards.
Hospital procurement committees are consolidating anticoagulant formularies around integrated bleed management protocols. This purchasing concentration displaces fragmented physician preference purchasing with system-wide therapeutic interchange policies. The United States exhibits the most pronounced consolidation, with integrated delivery networks standardizing across dozens of affiliated facilities simultaneously.
Global Cardiovascular Drugs Market Segmentation
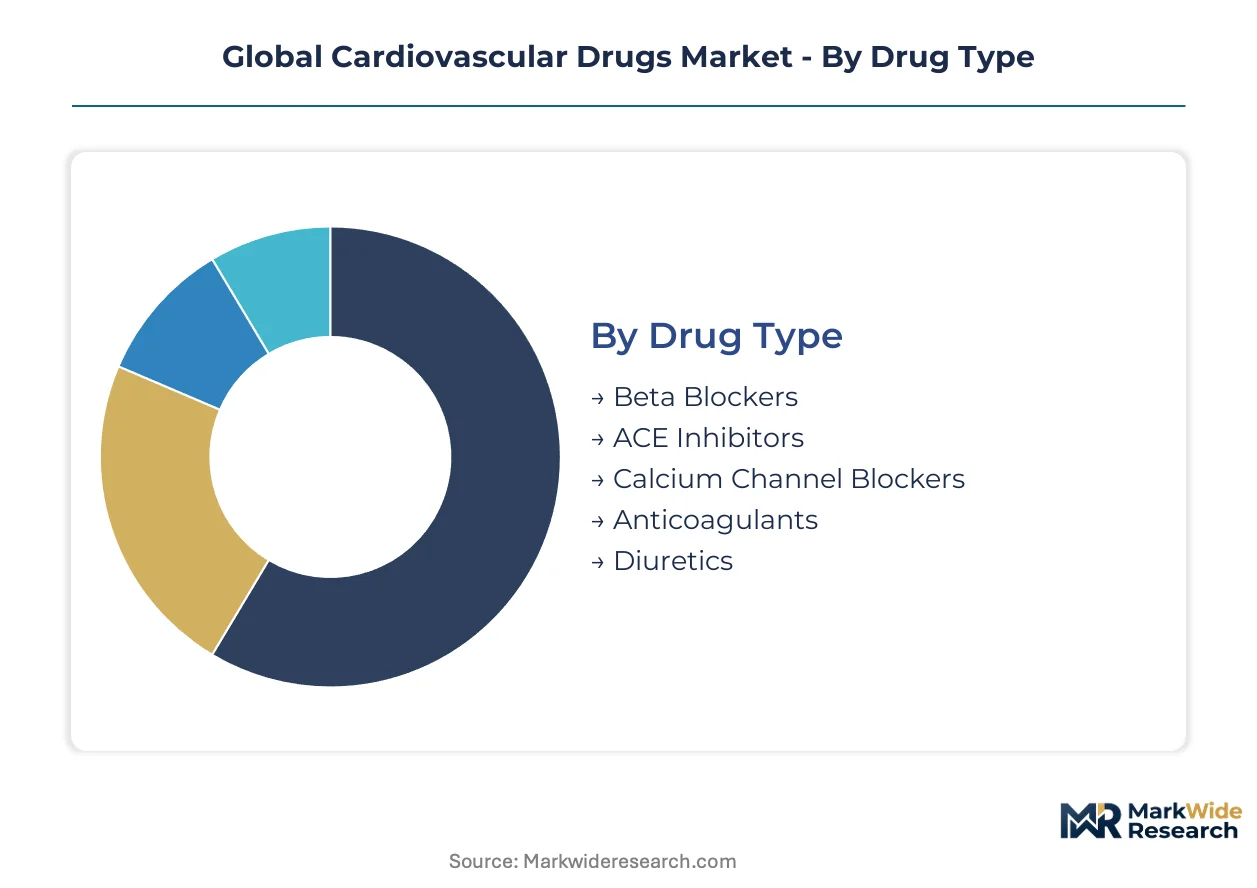
Cardiovascular drug segmentation reveals distinct manufacturing footprints, regulatory pathways, and patient adherence requirements across each dimension. Drug type and therapy area classifications determine reimbursement coding complexity, while administration route selection directly shapes distribution infrastructure and cold chain investments.
Drug Type:
After-sales service intensity varies sharply across drug types, with anticoagulants demanding continuous INR monitoring support and beta blockers requiring minimal patient follow-up infrastructure.
- Anticoagulants:These agents modulate coagulation cascade proteins to prevent thromboembolic events, requiring precise dosing algorithms due to narrow therapeutic indices. Demand concentrates in United States hospital systems deploying integrated bleed management protocols, driven by chronic administration requirements that extend revenue capture per patient. Compliance costs escalate under evolving FDA real-world evidence standards for post-approval safety monitoring.
- Beta Blockers:Competitive antagonists at beta-adrenergic receptors reduce myocardial oxygen demand and control ventricular rate. German statutory health insurance reimbursement patterns favor these agents for hypertension first-line therapy, constrained by Japan PMDA pharmacovigilance reporting requirements that elevate compliance burdens for market entrants.
- ACE Inhibitors:Renin-angiotensin pathway modulators manufactured via small-molecule synthesis with purity specifications exceeding 99.5 percent.
- Calcium Channel Blockers:Vascular smooth muscle relaxants requiring electrocardiogram monitoring infrastructure in ambulatory settings.
- Diuretics:Sodium and water excretion promoters with established generic substitution patterns limiting originator pricing power.
Anticoagulants hold the largest share; momentum sits with beta blockers in preventive cardiology protocols.
Therapy Area:
Cost tier stratification separates biologic-intensive hyperlipidemia therapies from small-molecule hypertension treatments with mature generic competition.
- Hyperlipidemia:Lipid metabolism modulators including statins and emerging siRNA constructs target residual cardiovascular risk. United States specialty pharmacy channels concentrate demand for biannual dosing protocols, enabled by hospital-at-home program expansion that reduces infusion chair utilization. Germany's statutory health insurance system now reimburses lipid-lowering biologics for high-risk primary prevention populations.
- Hypertension:Chronic blood pressure management therapies represent the highest-volume therapy area with extensive generic penetration. China's NMPA accelerated review reforms are redrawing market access sequencing for innovative fixed-dose combinations, compressing development timelines relative to European reimbursement negotiations.
- Heart Failure:Neurohormonal antagonists and SGLT2 inhibitors requiring specialized cardiology monitoring infrastructure.
- Arrhythmia:Antiarrhythmic agents with electrophysiology laboratory dependency for initiation and titration.
- Atherosclerosis:Plaque stabilization therapies integrating with interventional cardiology procedural volumes.
Hypertension commands volume leadership; hyperlipidemia exhibits the steepest expansion trajectory from RNA interference convergence.
End User:
Application requirements diverge between acute care settings demanding immediate availability and ambulatory channels prioritizing adherence program integration.
- Hospitals:Inpatient cardiology departments maintain formularies for acute myocardial infarction and stroke protocols, with procurement committees consolidating purchasing around integrated bleed management standards. United States integrated delivery networks standardize anticoagulant selection across dozens of affiliated facilities simultaneously.
- Ambulatory Care Centers:Subcutaneous administration capabilities enable care migration from hospital infusion chairs to lower-acuity settings. Japan's hospital-at-home program expansion drives demand for portable monitoring infrastructure compatible with chronic anticoagulant therapy.
- Cardiology Clinics:Outpatient diagnostic and therapeutic management requiring electrocardiogram and echocardiography co-location.
- Specialty Pharmacies:Mail-order and direct-to-patient distribution channels enabling adherence monitoring program integration.
Hospitals retain the largest share; momentum sits with ambulatory care centers from hospital-at-home program scaling.
Administration Route:
Supply concentration for active pharmaceutical ingredients shapes finished dose availability across oral, injectable, and emerging delivery formats.
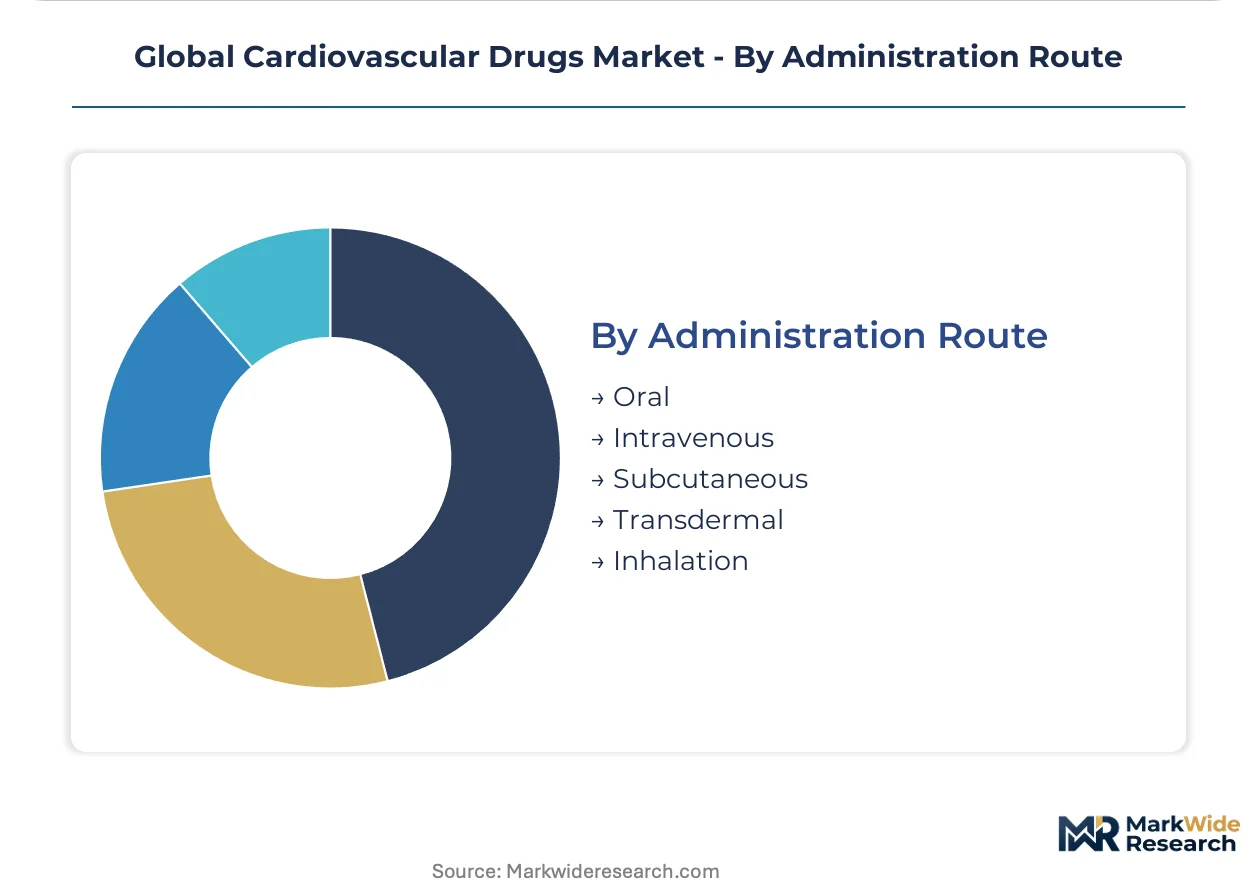
- Oral:Tablet and capsule formulations dominate volume through patient self-administration convenience and established manufacturing infrastructure. China's dominance of antihypertensive intermediate synthesis creates formulation bottlenecks for European and North American finished dose producers when NMPA-registered facilities experience disruptions.
- Subcutaneous:Prefilled syringes and autoinjector devices enable administration outside traditional infusion centers. Germany and United States hospital systems adopt these formats for biannual lipid-lowering therapies, reducing healthcare facility utilization.
- Intravenous:Acute care administration requiring sterile compounding infrastructure and infusion pump compatibility.
- Transdermal:Patch-based delivery with absorption variability challenges limiting cardiovascular application scope.
- Inhalation:Pulmonary delivery formats with specialized device quality management requirements under EMA MDR and FDA combination product regulations.
Oral administration holds the largest share; momentum sits with subcutaneous formats from ambulatory care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital systems exhibit the lowest price elasticity for novel anticoagulants, while India's outpatient market demonstrates acute sensitivity to generic substitution. Germany's statutory insurance framework occupies a middle position, reimbursing biologics for primary prevention while maintaining reference pricing pressure.
United States
Integrated delivery networks consolidate anticoagulant formularies across dozens of affiliated facilities, concentrating procurement power. FDA breakthrough therapy designation compresses development timelines for heart failure therapies, accelerating market access. The Boston-Cambridge corridor anchors biologic cardiovascular R&D, with Massachusetts General Hospital and Brigham and Women's Hospital driving clinical trial enrollment for siRNA lipid modulators.
Germany
Statutory health insurance reimbursement for lipid-lowering biologics in high-risk primary prevention populations expands addressable pools beyond established diagnoses. EMA priority medicine status expedites heart failure therapy access, compressing negotiation timelines with GKV-Spitzenverband. The Rhine-Main cluster around Frankfurt hosts Boehringer Ingelheim's cardiovascular operations, while Baden-Württemberg's Stuttgart region concentrates medical device-cardiovascular drug combination product development.
Japan
Hospital-at-home program expansion drives demand for subcutaneous administration formats and portable monitoring infrastructure. PMDA tightened pharmacovigilance reporting requirements for beta blockers and calcium channel blockers in 2023, elevating compliance costs for entrants without established safety databases. The Kanto region around Tokyo concentrates cardiovascular clinical research, with University of Tokyo Hospital and National Cerebral and Cardiovascular Center anchoring post-market surveillance networks.
China
NMPA accelerated review reforms for innovative cardiovascular compounds redraw market access sequencing, enabling earlier launches than European reimbursement negotiations. Domestic demand concentrates in tier-one cities for novel therapies while generic antihypertensives penetrate lower-tier markets. The Yangtze River Delta around Shanghai hosts multinational cardiovascular manufacturing operations, with Zhangjiang Hi-Tech Park specializing in biologic API synthesis under NMPA GMP standards.
India
Domestic manufacturers dominate oral antihypertensive supply through cost-optimized small-molecule synthesis, exporting to Africa and Southeast Asia. CDSCO tightened bioequivalence requirements for cardiovascular generics in 2022, elevating facility inspection intensity. Hyderabad's Genome Valley and Mumbai-Pune corridor concentrate contract research and manufacturing for cardiovascular APIs, with Piramal and Suven Life Sciences anchoring intermediate production for global finished dose formulators.
Global Cardiovascular Drugs Market Competitive Landscape
Capability concentration sits with specialized biologic manufacturers possessing recombinant protein synthesis expertise; scale advantage sits with diversified pharmaceutical conglomerates commanding hospital network procurement relationships. The market structures around three tiers: originators with integrated device-drug portfolios, mid-scale specialists in narrow therapeutic index agents, and generic manufacturers competing on API cost position. Dominant competitive moves include backward integration into active pharmaceutical ingredient production and strategic partnerships for real-world evidence generation infrastructure.
Among Swiss-origin pharmaceutical conglomerates, Novartis AG and Roche anchor the biologic cardiovascular therapy segment through heart failure and dyslipidemia portfolios. Pfizer Inc. exemplifies the scale-driven archetype, leveraging North American hospital network relationships to dominate oral anticoagulant supply chains. AstraZeneca PLC occupies a position bridging both tiers, combining upstream control over hypertension API production with SGLT2 inhibitor leadership in heart failure. These three entities represent distinct strategic postures: deep specialization, manufacturing scale, and vertical integration respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Novartis AG |
| AstraZeneca PLC |
| Bayer AG |
| Bristol-Myers Squibb Company |
| Sanofi S.A. |
| Merck & Co., Inc. |
| Boehringer Ingelheim GmbH |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
China's dominance in valsartan and amlodipine intermediate synthesis concentrates upstream margin capture with NMPA-registered manufacturers, while downstream pricing power pools with anticoagulant originators exploiting narrow therapeutic indices to limit generic substitution. This structural asymmetry rewards finished dose formulators with captive API supply while exposing others to formulation bottlenecks.
Pricing Analysis
After-sales service revenue from continuous INR monitoring infrastructure drives lifetime value for anticoagulant manufacturers, with pricing stratifying across premium originator, authorized generic, and commodity substitution tiers. Price differentiation hinges on bleed management protocol integration and FDA real-world evidence compliance certification. Cost compression in the generic tier intensifies as Indian CDSCO bioequivalence requirements elevate facility inspection costs. Hospital procurement committees in the United States exhibit the lowest price sensitivity, while India's outpatient retail channel demonstrates acute generic preference.
Supply Chain Analysis
Export control restrictions on recombinant protein synthesis equipment constrain biologic cardiovascular manufacturing capacity expansion outside established OECD hubs. Active pharmaceutical ingredient production concentrates in China, India, and Switzerland, with finished dose formulation drawing from German and Italian sterile compounding infrastructure. Single-source vulnerability sits with NMPA-registered facilities supplying antihypertensive intermediates. Distribution runs through hospital procurement committees in acute care and specialty pharmacy direct-to-patient channels in chronic therapy management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiovascular drug markets fragment across therapy-specific expertise domains, with hospital-at-home program expansion creating distinct ambulatory care niches requiring portable monitoring infrastructure and subcutaneous formulation capabilities.
For Market Incumbents: Pre-empt biosimilar erosion in anticoagulant portfolios by securing exclusive bleed management protocol partnerships with United States integrated delivery networks. Anchor defensive positioning through backward integration into siRNA lipid modulator API production, countering emerging RNA interference specialists threatening statin-adjacent revenue pools.
For New Entrants and Emerging Players: Mid-scale hospital-at-home service providers in Japan represent the most penetrable entry point for subcutaneous anticoagulant administration infrastructure, with portable INR monitoring device integration as the primary go-to-market wedge. Germany's statutory health insurance reimbursement expansion for primary prevention biologics opens parallel white-space for lipid-lowering therapy adherence program specialists.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing organizations possessing single-use bioreactor capacity and cardiovascular biologic synthesis expertise. Five-to-ten year viability hinges on regulatory inspection history and NMPA dual-filing capabilities. The signal to watch is FDA real-world evidence standard tightening, which would elevate observational study infrastructure valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses anticoagulant development timelines against standard review benchmarks. |
| Manufacturing Scale-Up | Single-use bioreactor capacity expansion addresses recombinant protein synthesis bottlenecks for heart failure biologics. |
| Licensing Agreement | siRNA platform partnerships enable biannual dosing protocols that reduce hospital infusion chair utilization. |
| Pipeline Diversification | SGLT2 inhibitor expansion into heart failure indications captures neurohormonal antagonist market share. |
| Clinical Trial Advancement | Decentralized trial infrastructure aligns with hospital-at-home program requirements for ambulatory monitoring. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored market sizing across the analysis window.
Forecast inputs span drug type, therapy area, administration route, and regional regulatory cluster segmentation. CAGRs were derived from epidemiological trend extrapolation, pricing elasticity modeling, and therapy penetration curve analysis. The projection horizon incorporates NMPA accelerated review reform impacts, PMDA pharmacovigilance cost escalation, and hospital-at-home program scaling assumptions.
Practitioners should monitor FDA real-world evidence standard evolution, China API supply disruptions, and RNA interference technology adoption curves for early signals of forecast deviation. Material shifts in breakthrough therapy designation criteria or NMPA manufacturing inspection intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
API Contract Manufacturing Market
Pharmaceuticals
Global Human Growth Hormone (HGH) Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Global Manidipine Hydrochloride Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Global Chemotherapy-Induced Neutropenia (CIN) Treatment Market
Pharmaceuticals
Multiple Myeloma Drugs Market
Pharmaceuticals
India Opioids Market
Pharmaceuticals
Postmenopausal Vaginal Atrophy Drugs Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Vaginitis Therapeutics Market