
 Live Vaccines Market | 2026-2036
Live Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Live Vaccines Market Outlook
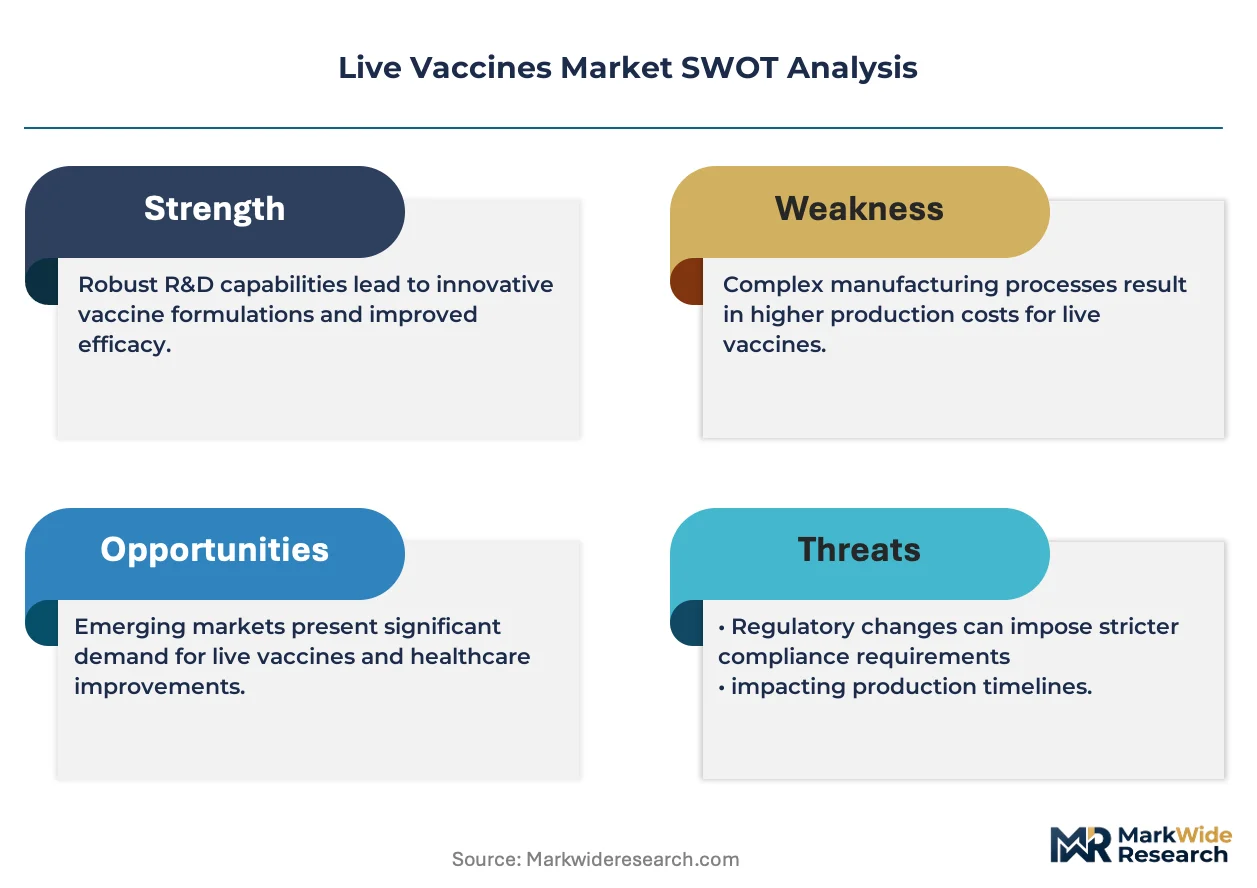
FDA potency testing guidance for live attenuated products is hardening the cost-of-entry calculus for new manufacturers. Merck & Co., Inc. leverages decades of experience in measles-mumps-rubella production to sustain its manufacturing dominance. GlaxoSmithKline plc anchors its position through specialized cold-chain infrastructure for thermolabile formulations. Sanofi competes across multiple therapy areas with differentiated recombinant vector platforms.
Live vaccines contain weakened pathogens that replicate minimally in host tissue, stimulating durable cellular and humoral immunity through controlled infection mimicry; they typically require stringent cold storage between 2°C and 8°C to maintain viability. Attenuated vaccines occupy the largest revenue share due to established efficacy profiles in pediatric populations, while recombinant vaccines represent the fastest-expanding category as vector engineering advances enable safer immunization against complex pathogens. Combination vaccines concentrate margin pools by reducing administration costs and improving compliance in public health programs.
The FDA, EMA, and WHO prequalification standards collectively govern product approval, batch release, and international procurement eligibility for live vaccine manufacturers. These frameworks shape demand by determining which products qualify for national immunization schedules and donor-funded purchasing mechanisms. Stakeholders must monitor evolving stability testing requirements and vector platform patent landscapes to anticipate competitive shifts in manufacturing access.
Market Dynamics
FDA potency testing guidance for live attenuated products is hardening manufacturing compliance requirements and reshaping competitive entry barriers across the live vaccines market.
Growth Catalysts
- Pediatric program expansion:National immunization schedules in India and Nigeria are broadening access to measles-mumps-rubella formulations through public health infrastructure investments.
- WHO prequalification pathways:Accelerated review frameworks are enabling faster procurement eligibility for manufacturers targeting Gavi Alliance and UNICEF supply contracts.
- Cold-chain infrastructure modernization:Solar-powered refrigeration networks in sub-Saharan Africa are reducing thermolabile product wastage and extending distribution reach.
Market Restraints
- Attenuated strain supply concentration:Global dependency on a limited number of seed strain repositories creates vulnerability to contamination events or geopolitical access restrictions.
- Stability testing cost inflation:FDA's updated potency validation protocols are extending batch release timelines and elevating quality control expenditures for new entrants.
- Recombinant vector substitution:Safer non-replicating platforms are capturing preference in immunocompromised patient populations where live attenuated products carry contraindication risks.
Strategic Opportunities
- Indonesia archipelago penetration:Fragmented island geography and expanding primary healthcare networks create whitespace for combination vaccine introductions reducing cold-chain touchpoints.
- Vector engineering convergence:Integration of CRISPR-based attenuation with mRNA amplification platforms is enabling rapid response vaccine development against emerging zoonotic threats.
- Digital cold-chain monitoring:IoT temperature logging and blockchain verification are opening direct-to-clinic distribution models bypassing traditional wholesale intermediaries.
Industry Challenges
- Cell culture technician scarcity:Specialized expertise in primary chicken embryo fibroblast propagation remains concentrated among legacy manufacturers, constraining capacity expansion.
- Multi-year facility validation:Constructing EU GMP-compliant fill-finish lines for live biological products demands extended commissioning periods before commercial batch release authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Live Vaccines Market |
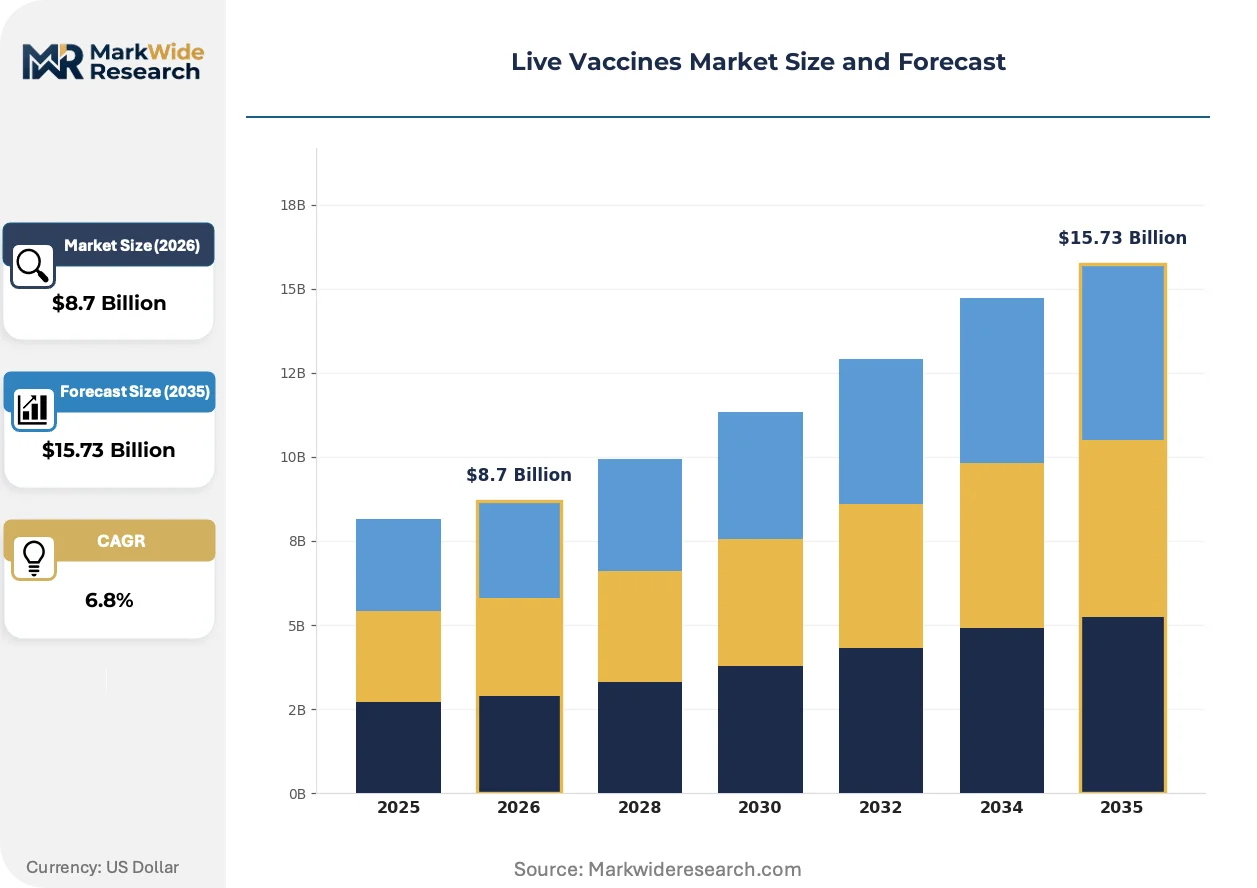
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attenuated Vaccines, Recombinant Vaccines, Combination Vaccines, Conjugate Vaccines Therapy Area: Pediatric, Travel Medicine, Infectious Diseases, Oncology End User: Hospitals, Clinics, Research Institutions, Public Health Organizations Delivery Mode: Subcutaneous, Intramuscular, Oral, Nasal |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Sanofi, Pfizer Inc., Johnson & Johnson, Serum Institute of India Pvt. Ltd., AstraZeneca, CSL Limited, Bavarian Nordic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Live Vaccines Market Strategic Shifts
Vector platform engineering and regulatory science advances are compressing development timelines while cold-chain innovations are redrawing distribution economics across temperature-sensitive biological supply.
Stable lyophilization formulations are rewriting viability preservation standards for live attenuated products. Pediatric immunization programs in Brazil and Mexico are adopting these dried-powder presentations to reduce freezer dependency. The technology is compressing last-mile logistics costs and enabling ambient-temperature transport windows previously unattainable with liquid formulations.
EMA's revised guideline on quality, non-clinical and clinical aspects of live recombinant viral vectored vaccines is elevating immunogenicity benchmark requirements for European market authorization. Manufacturers must now demonstrate superior or equivalent cellular response profiles against licensed comparators. Vector platform developers are responding by investing in adjuvant co-formulation capabilities and enhanced T-cell epitope mapping.
Consolidated tendering by national procurement agencies is concentrating purchasing power and compressing supplier margins across emerging markets. UNICEF's long-term supplier agreements and volume guarantees are displacing fragmented national tender processes in sub-Saharan Africa. This behavioral shift is most visible in Nigeria and Ethiopia, where federal ministries are delegating vaccine acquisition to multilateral procurement mechanisms.
Live Vaccines Market Segmentation
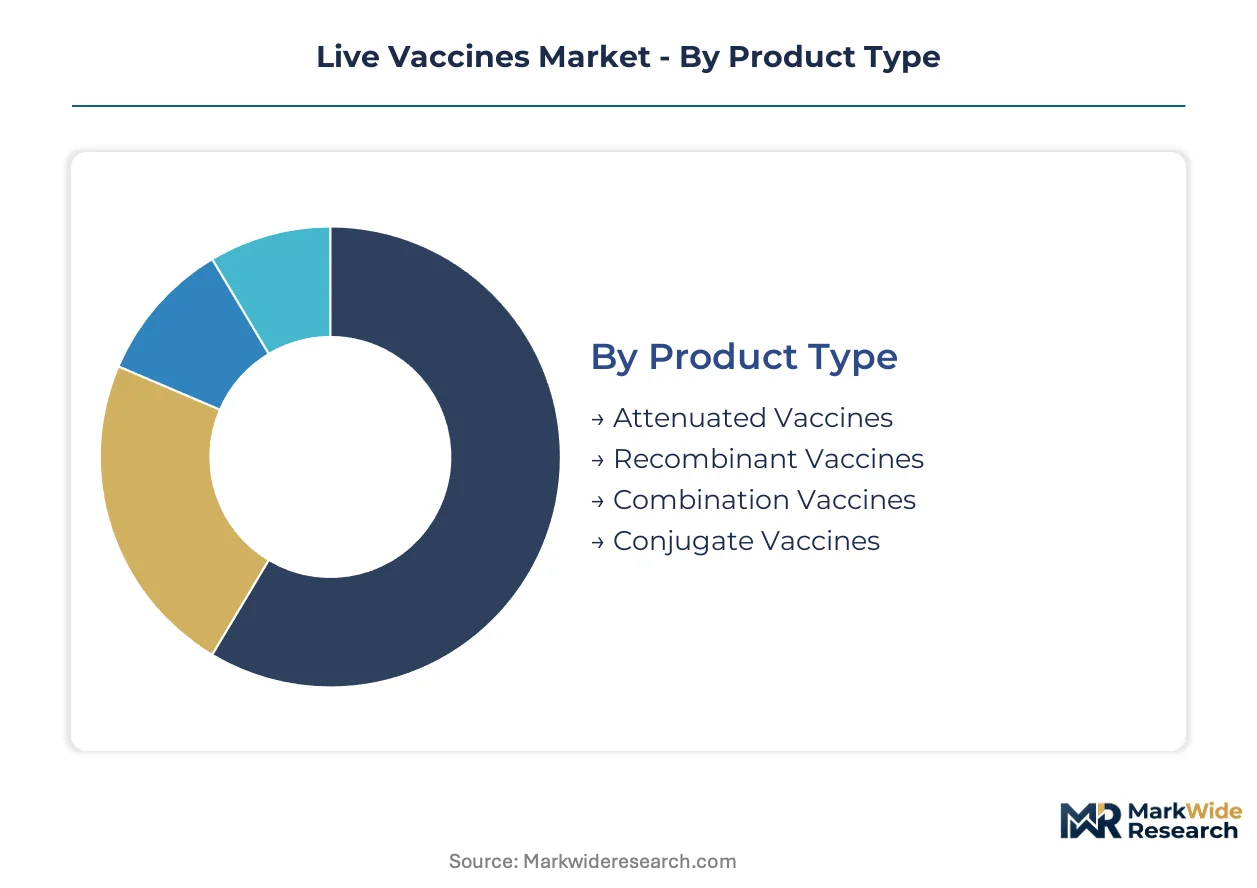
Live vaccines fragment across four distinct dimensions, each shaping manufacturing investment and distribution strategy. Product type determines cold-chain intensity and regulatory pathway complexity. Therapy area and delivery mode dictate formulation stability requirements and administration infrastructure needs.
Product Type:
Volume production concentrates in legacy attenuated platforms while premium pricing attaches to engineered recombinant systems.
- Attenuated Vaccines:Weakened pathogen formulations replicate minimally in host tissue to stimulate durable cellular immunity. Demand clusters in India's national immunization schedule and Nigeria's measles eradication campaigns where established cold-chain infrastructure supports thermolabile distribution.
- Recombinant Vaccines:Viral vector platforms deliver antigen-encoding genes without pathogen replication risk. GlaxoSmithKline plc and Sanofi are expanding manufacturing capacity in Belgium and France as EMA immunogenicity benchmarks harden for European market authorization.
- Combination Vaccines:Multi-antigen formulations reduce administration costs and improve pediatric compliance in public health programs.
- Conjugate Vaccines:Polysaccharide-protein linkages enhance immunogenicity in infant populations.
Mature deployment sits with attenuated vaccines. Newer deployment is concentrated in recombinant platforms.
Therapy Area:
Pediatric applications anchor procurement volume while oncology vectors command development-stage investment.
- Pediatric:Routine immunization schedules in Brazil, Mexico, and Ethiopia drive attenuated measles-mumps-rubella demand through UNICEF consolidated tendering mechanisms.
- Travel Medicine:Yellow fever and typhoid formulations serve outbound travelers from Germany, Switzerland, and Australia with specialized clinic networks.
- Infectious Diseases:Outbreak response stockpiles concentrate demand for cholera and oral polio vaccines in sub-Saharan Africa.
- Oncology:Therapeutic cancer vaccines represent experimental pipeline activity with vector engineering convergence in CRISPR-based attenuation platforms.
Procurement volume clusters in pediatric applications. Pipeline investment flows fastest into oncology vectors.
End User:
Public procurement channels dominate volume while research institutions shape early-stage platform adoption.
- Hospitals:Tertiary care centers in India and South Africa administer combination vaccines to inpatients with compromised immune status requiring recombinant alternatives.
- Clinics:Primary healthcare networks in Indonesia's archipelago geography are adopting lyophilized presentations to reduce cold-chain touchpoints.
- Research Institutions:Academic medical centers in the US and UK conduct Phase I/II trials for novel vector platforms under FDA and MHRA exploratory IND frameworks.
- Public Health Organizations:Gavi Alliance and national ministries in Nigeria and Ethiopia delegate vaccine acquisition to multilateral procurement mechanisms with volume guarantees.
Established procurement runs through public health organizations. Emerging demand is concentrating in clinic networks with digital cold-chain monitoring.
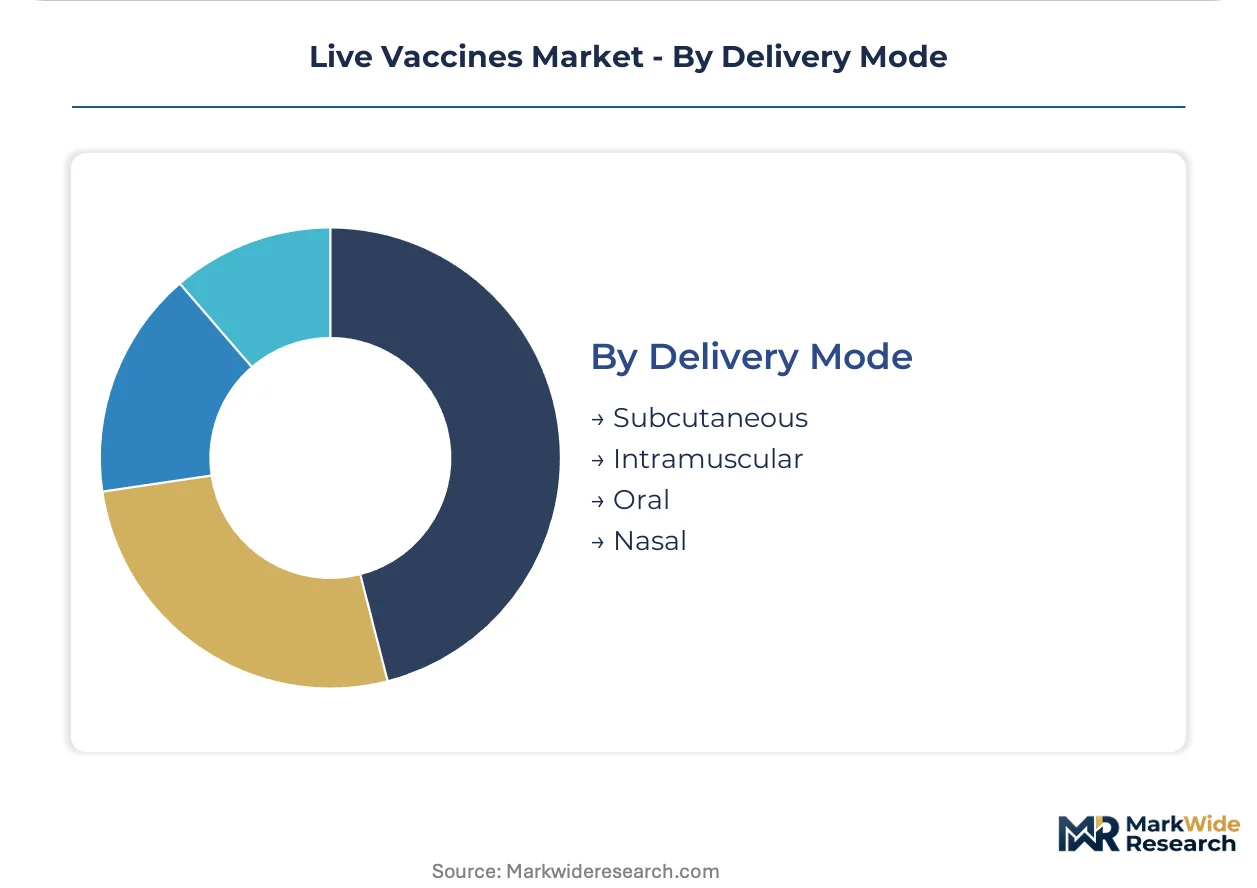
Delivery Mode:
Injection routes retain volume leadership while mucosal delivery is gaining share fastest for thermostable formulations.
- Subcutaneous:Measles-mumps-rubella administration requires precise needle depth control in pediatric populations.
- Intramuscular:Deltoid site injection dominates adolescent and adult immunization in hospital settings.
- Oral:Polio and rotavirus formulations eliminate cold-chain requirements for last-mile distribution in sub-Saharan Africa.
- Nasal:Mucosal delivery platforms are advancing through clinical trials for influenza and COVID-19 vector applications.
Standard administration sits with intramuscular delivery. Novel deployment is concentrating in oral and nasal mucosal routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pune's biotechnology special economic zone concentrates contract manufacturing capacity for attenuated vaccine bulk production. India's PLI scheme for pharmaceuticals is attracting multinational fill-finish investments into Gujarat and Telangana clusters. Cold-chain infrastructure gaps in sub-Saharan Africa and Southeast Asia are redirecting procurement toward thermostable lyophilized formulations.
India
Serum Institute of India Pvt. Ltd. anchors domestic measles-mumps-rubella supply for UNICEF tenders while expanding recombinant vector capacity. CDSCO's accelerated approval pathway for WHO-prequalified products is compressing market entry timelines for indigenous manufacturers. Hyderabad's Genome Valley cluster houses GSK's specialized cold-chain infrastructure for thermolabile formulations.
United States
FDA's updated potency testing guidance is elevating compliance costs for attenuated strain manufacturers serving pediatric immunization schedules. The Biomedical Advanced Research and Development Authority maintains stockpiles of smallpox and anthrax vaccines through long-term procurement contracts. Massachusetts' Kendall Square biotech corridor concentrates vector platform engineering expertise for emerging infectious disease response.
Germany
Paul-Ehrlich-Institut batch release requirements govern EU market access for live recombinant viral vectored products. EMA's revised immunogenicity benchmarks are forcing adjuvant co-formulation investments among developers seeking European authorization. Marburg's BSL-4 facility cluster supports high-containment manufacturing for exotic pathogen vaccines.
Brazil
ANVISA's alignment with WHO prequalification standards is streamlining procurement eligibility for manufacturers targeting national immunization program tenders. Butantan Institute's domestic yellow fever production reduces import dependency for Amazon basin outbreak response. São Paulo's biomedical research corridor concentrates public-private partnership activity for dengue and Zika vector development.
Nigeria
Federal Ministry of Health delegation to Gavi Alliance procurement mechanisms is consolidating supplier relationships for measles eradication campaigns. Solar-powered refrigeration networks in northern states are reducing thermolabile product wastage during last-mile distribution. Lagos' pharmaceutical import hub serves as consolidation point for cold-chain logistics into West African Economic and Monetary Union markets.
Live Vaccines Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across vector platform categories. The market structure concentrates manufacturing capability among legacy attenuated vaccine producers with decades of seed strain repository access. Three archetypes dominate: integrated pharmaceutical conglomerates with biologicals divisions, dedicated vaccine pure-plays with WHO prequalification portfolios, and emerging vector technology specialists. Competitive moves center on cold-chain infrastructure partnerships and regulatory pathway acceleration through prequalification alignment.
Within the integrated conglomerate tier, Merck & Co., Inc. and GlaxoSmithKline plc occupy positions shaped by decades of measles-mumps-rubella production experience and specialized thermolabile distribution networks. Sanofi exemplifies the diversified biologicals archetype through recombinant vector platform investments across multiple therapy areas. Serum Institute of India Pvt. Ltd. represents the high-volume pure-play model, anchoring procurement contracts for Gavi Alliance and UNICEF supply mechanisms through cost-optimized attenuated formulation manufacturing.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Sanofi |
| Pfizer Inc. |
| Johnson & Johnson |
| Serum Institute of India Pvt. Ltd. |
| AstraZeneca |
| CSL Limited |
| Bavarian Nordic |
| Others |
Value Chain & Pricing Dynamics
Cold-chain certification tiers bifurcate live vaccines into premium thermostable lyophilized formulations and commodity liquid presentations, with the former commanding procurement preference from Gavi Alliance and UNICEF mechanisms while the latter concentrates in domestic Indian tenders where Serum Institute of India Pvt. Ltd. optimizes cost structures. This tier divergence manifests in supply chain configurations: lyophilized products deploy solar-powered refrigeration networks in Nigeria's northern states, while liquid formulations depend on continuous 2-8°C distribution through fragmented wholesale intermediaries.
Pricing Analysis
Short lead-time premiums attach to WHO-prequalified stockpiles for outbreak response, while spot inventory of non-prequalified attenuated strains trades at discounts in secondary markets. Three-tier pricing structure across premium lyophilized, standard liquid-attenuated, and economy bulk-antigen levels reflects cold-chain intensity and regulatory validation depth. Cost compression in standard liquid tiers is intensifying because FDA potency testing protocols are extending batch release timelines. Public health organizations exhibit highest price sensitivity, while travel medicine clinics serving German and Swiss outbound travelers absorb premium positioning.
Supply Chain Analysis
Freight costs for temperature-controlled air cargo from Pune's biotechnology special economic zone to sub-Saharan African markets represent 15-25% of delivered product value, driving procurement localization efforts. Manufacturing concentrates in India, Belgium, and France, with bulk antigen production anchored in Pune and fill-finish capacity expanding in Gujarat and Telangana clusters under PLI scheme incentives. Primary chicken embryo fibroblast and specialized viral seed strains feed from legacy repositories in the United States and Russia. Single-source vulnerability in attenuated strain repositories creates geopolitical access risk. Distribution runs through UNICEF consolidated tendering mechanisms displacing fragmented national procurement in Nigeria and Ethiopia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Live vaccine supply remains structurally constrained by multi-year EU GMP facility validation timelines and concentrated technician expertise in primary cell culture propagation, bottlenecks that sustain pricing power for incumbent manufacturers with validated capacity.
For Market Incumbents: Anchor manufacturing dominance through backward integration into specialized cold-chain infrastructure and captive seed strain repository control. Merck & Co., Inc. and GlaxoSmithKline plc should expand lyophilization capacity in India to preempt recombinant vector substitution threats. CDSCO accelerated approval pathway investments will defend position against emerging vector technology specialists. For New Entrants and Emerging Players: Capture whitespace in Indonesia's archipelago clinic networks where fragmented island geography and expanding primary healthcare infrastructure create demand for reduced cold-chain touchpoint solutions. Lyophilized combination vaccine introductions targeting measles-mumps-rubella procurement through digital cold-chain monitoring partnerships offer the most penetrable entry angle. For Investors and Strategic Acquirers: Re-rating potential sits with recombinant vector platform specialists given EMA immunogenicity benchmark hardening and CRISPR-based attenuation convergence. Long-term viability favors manufacturers with WHO prequalification portfolios and Gavi Alliance supply contracts. Watch for FDA potency testing guidance enforcement as inflection indicator for compliance cost escalation and incumbent margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Acceleration | UNICEF tender eligibility compresses market entry timelines for Indian manufacturers. |
| Lyophilization Manufacturing Scale-Up | Thermostable formulations reduce last-mile logistics costs in sub-Saharan Africa. |
| CRISPR-Based Vector Engineering Investment | Recombinant platform advances enable safer immunization against zoonotic threats. |
| Solar-Powered Cold-Chain Partnership | IoT temperature monitoring extends distribution reach in Nigeria's northern states. |
| Regulatory Affairs Capability Buildout | FDA potency testing expertise defends batch release authorization timelines. |
Study Parameters
Document review covered FDA guidance documents, EMA revised guidelines on live recombinant viral vectored vaccines, WHO prequalification standards, and UNICEF procurement databases, complemented by interviews with vaccine manufacturing executives, regulatory affairs leads at CDSCO and Paul-Ehrlich-Institut, hospital procurement managers in India and Brazil, and cold-chain logistics specialists. Secondary validation drew from ClinicalTrials.gov vector platform entries, Gavi Alliance supply contract disclosures, and national immunization schedule publications. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Cross-referencing historical procurement volume patterns against expert panel input on regulatory timeline shifts shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, delivery mode, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted demand projections and capacity-constrained supply curves. Industry-specific forecast inputs incorporated attenuated strain repository access constraints and cold-chain infrastructure modernization rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA potency testing enforcement intensity, recombinant vector substitution velocity, and geopolitical access restrictions to seed strain repositories. Forecasts reflect documented assumptions about regulatory pathway stability and procurement mechanism continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Soft Capsules Drugs CMO Market
Pharmaceuticals
US Pharmaceutical CMO Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Sleeping Medications Market
Pharmaceuticals
Pharmaceutical Water Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Lipid-Lowering Drugs Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market
Pharmaceuticals
Hyperphosphatemia Drugs Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
HIV Antivirals Market