
 Organ Transplant Rejection Medications Market | 2026-2036
Organ Transplant Rejection Medications Market Size, Share, and Industry Trends Forecast 2026-2036
Organ Transplant Rejection Medications Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing competitive access for companion diagnostics that guide immunosuppressant dosing, forcing pharmaceutical manufacturers to align with in-vitro diagnostic partners. Astellas Pharma leverages its dominance in tacrolimus formulations across major transplant centers. Novartis AG anchors its position through mycophenolate mofetil supply chains that sustain high-volume hospital procurement. F. Hoffmann-La Roche Ltd differentiates via IL-6 receptor antagonist development for antibody-mediated rejection protocols.
Organ transplant rejection medications comprise small-molecule immunosuppressants and biologic agents that modulate T-cell activation, cytokine signaling, or B-cell response to prevent allograft destruction, with critical quality parameters including narrow therapeutic indices requiring therapeutic drug monitoring. These therapies serve the essential commercial purpose of enabling long-term graft survival following solid organ transplantation. Calcineurin inhibitors occupy the largest revenue pool due to their irreplaceable role in standard triple-therapy regimens. mTOR inhibitors represent the fastest-expanding medication type as sirolimus and everolimus gain traction in calcineurin-sparing protocols that protect renal function. The intravenous administration route commands premium pricing during perioperative induction phases, while oral formulations generate recurring volume through decades-long maintenance therapy.
The FDA enforces bioequivalence standards for narrow therapeutic index immunosuppressants that limit generic substitution without therapeutic drug monitoring, directly shaping prescriber behavior and pharmacy benefit design. EMA's Good Manufacturing Practice inspections for active pharmaceutical ingredient facilities in Asia-Pacific supplier nations determine supply continuity for European transplant programs. The WHO Essential Medicines List inclusion of tacrolimus, mycophenolate, and prednisone establishes procurement benchmarks that influence national health system purchasing across low- and middle-income transplant markets. Stakeholders must monitor biosimilar entry timelines for basiliximab and evolving reimbursement policies for cellular therapies that could displace chronic pharmaceutical immunosuppression.
Market Dynamics
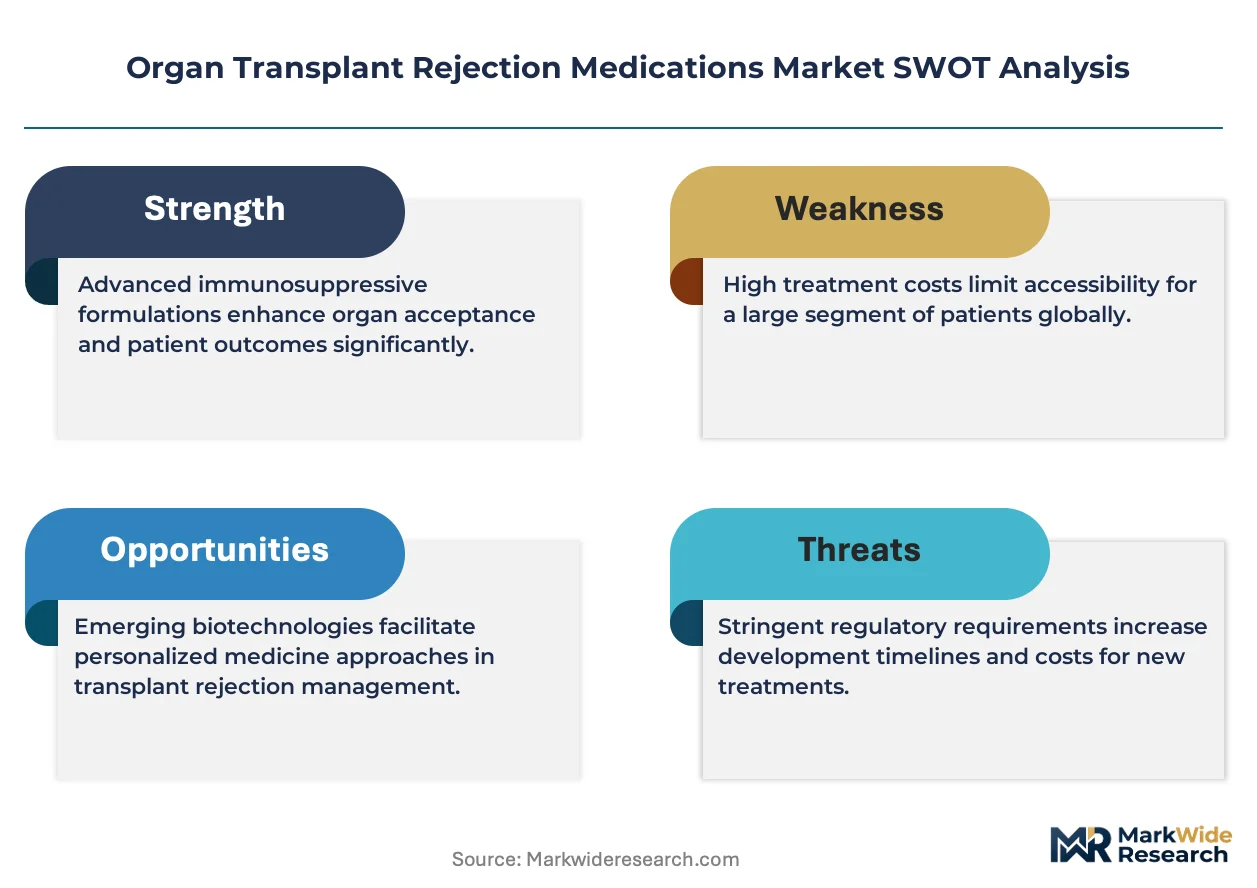
The Organ Transplant Rejection Medications Market is being fundamentally restructured by the FDA's tightened bioequivalence standards for narrow therapeutic index drugs, which are elevating the barrier to generic substitution and reinforcing branded tacrolimus and cyclosporine positions at major transplant centers.
Growth Catalysts
- Medicare lifetime immunosuppression coverage:The United States federal program eliminated the 36-month cap on drug benefits, removing cost barriers that previously drove non-adherence among post-transplant patients and expanding the addressable patient pool for maintenance therapy.
- Calcineurin-sparing protocol adoption:Nephrology transplant programs are integrating mTOR inhibitors into de novo immunosuppression regimens to preserve renal function, creating incremental demand for sirolimus and everolimus beyond traditional rescue indications.
- Kidney paired donation expansion:Living donor exchange programs are increasing transplant volumes at academic medical centers, directly enlarging the cohort requiring induction and maintenance immunosuppression.
Market Restraints
- Active pharmaceutical ingredient concentration:Tacrolimus and mycophenolate mofetil synthesis depends on facilities concentrated in India and China, exposing supply continuity to EMA Good Manufacturing Practice inspection outcomes and geopolitical trade friction.
- Therapeutic drug monitoring infrastructure gaps:Rural transplant follow-up clinics lack mass spectrometry capacity for narrow therapeutic index drug level verification, limiting protocol adherence outside metropolitan hospital systems.
- Cellular therapy substitution threat:Tolerogenic dendritic cell and regulatory T-cell trials aim to induce operational tolerance, potentially eliminating chronic pharmaceutical immunosuppression requirements for select patient populations.
Strategic Opportunities
- Companion diagnostic integration:Pharmacogenomic testing for CYP3A5 polymorphisms enables personalized tacrolimus dosing, creating partnership opportunities between immunosuppressant manufacturers and in-vitro diagnostic firms pursuing CE marking under EU Medical Device Regulation.
- Low- and middle-income procurement expansion:WHO Essential Medicines List inclusion of core immunosuppressants establishes procurement benchmarks that national health systems in Brazil, Mexico, and Thailand are adopting to scale deceased donor programs.
- Biosimilar basiliximab entry:The IL-2 receptor antagonist's patent expiration creates white space for cost-competitive induction agents that could capture share from high-priced depleting antibody protocols.
Industry Challenges
- Therapeutic drug monitoring technologist shortage:Clinical laboratories face recruitment gaps for mass spectrometry specialists capable of validating immunosuppressant assays under CLIA high-complexity requirements.
- Multi-site trial coordination complexity:Investigator-initiated studies comparing calcineurin-inhibitor minimization protocols require harmonization across UNOS regions with disparate organ allocation policies and follow-up infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organ Transplant Rejection Medications Market |
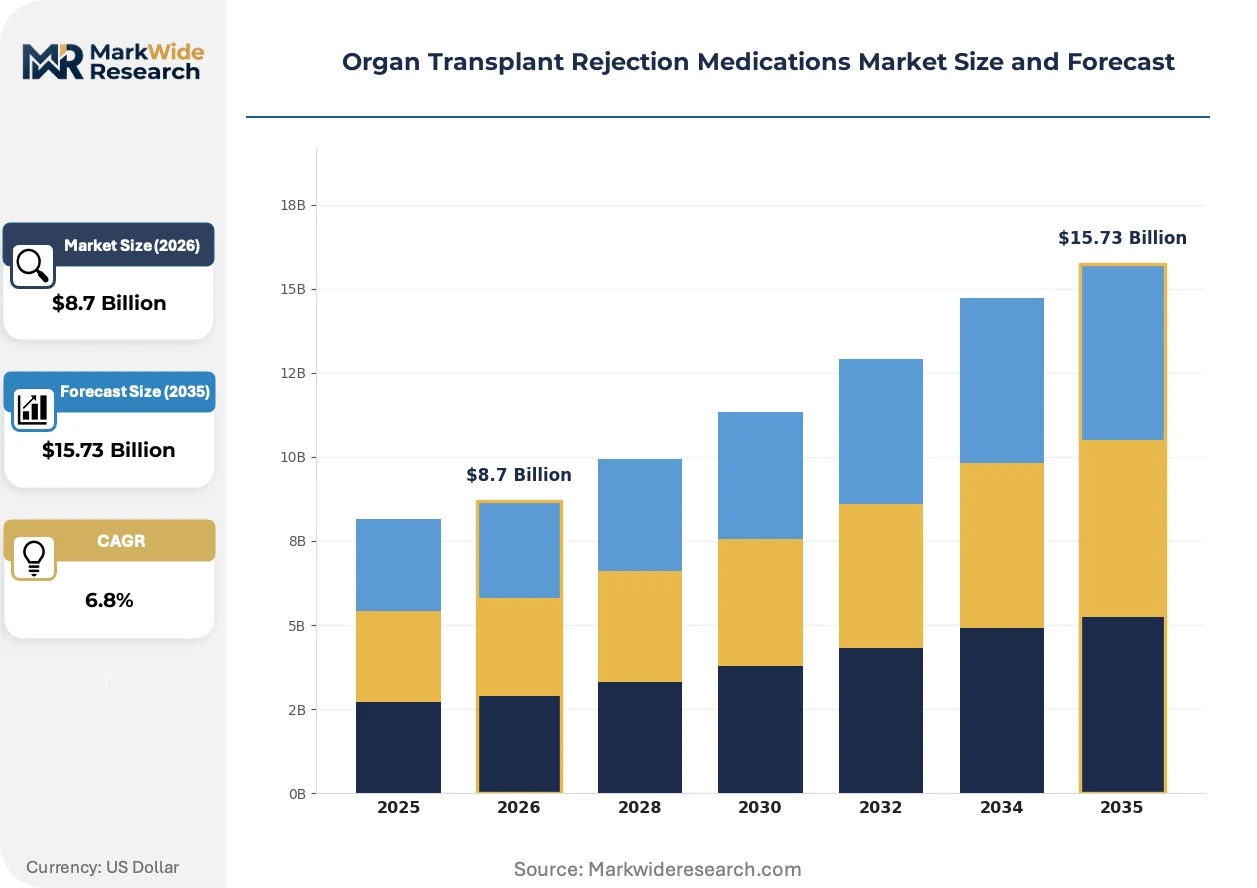
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Medication Type: Calcineurin Inhibitors, Antimetabolites, mTOR Inhibitors, Corticosteroids Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Homecare, Research Institutions Patient Demographics: Adults, Pediatric Patients, Geriatric Patients, High-Risk Individuals |
| Companies Covered | Astellas Pharma, Novartis AG, F. Hoffmann-La Roche Ltd, Sanofi, Bristol-Myers Squibb Company, GlaxoSmithKline plc, Pfizer, AbbVie, Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organ Transplant Rejection Medications Market Strategic Shifts
Immunosuppression practice is pivoting toward precision dosing and organ-function preservation, with technology and regulatory forces converging to reshape how transplant programs select and monitor drug therapy across induction and maintenance phases.
Pharmacogenomic-guided dosing algorithms are displacing weight-based tacrolimus initiation protocols at high-volume transplant centers. Mayo Clinic and Cleveland Clinic have implemented CYP3A5 genotype testing into standard care pathways, compressing time-to-therapeutic range and reducing early rejection episodes. This precision approach is displacing empirical dosing as the default standard in Medicare-reimbursed transplant programs.
EMA's Medical Device Regulation is reorganizing market access for immunosuppressant companion diagnostics, requiring pharmaceutical manufacturers to align technical documentation with in-vitro diagnostic partners seeking CE marking. The regulation forces joint clinical evidence generation that delays launch timelines but creates durable competitive moats for integrated drug-diagnostic offerings. European transplant programs are responding by consolidating procurement around suppliers with regulatory-validated testing platforms.
Hospital pharmacy benefit managers are consolidating immunosuppressant purchasing through specialty pharmacy networks that disintermediate retail distribution. This channel shift concentrates volume with distributors offering therapeutic drug monitoring integration and adherence packaging. The model is most visible in United States integrated delivery networks where transplant centers own downstream specialty pharmacy operations.
Organ Transplant Rejection Medications Market Segmentation
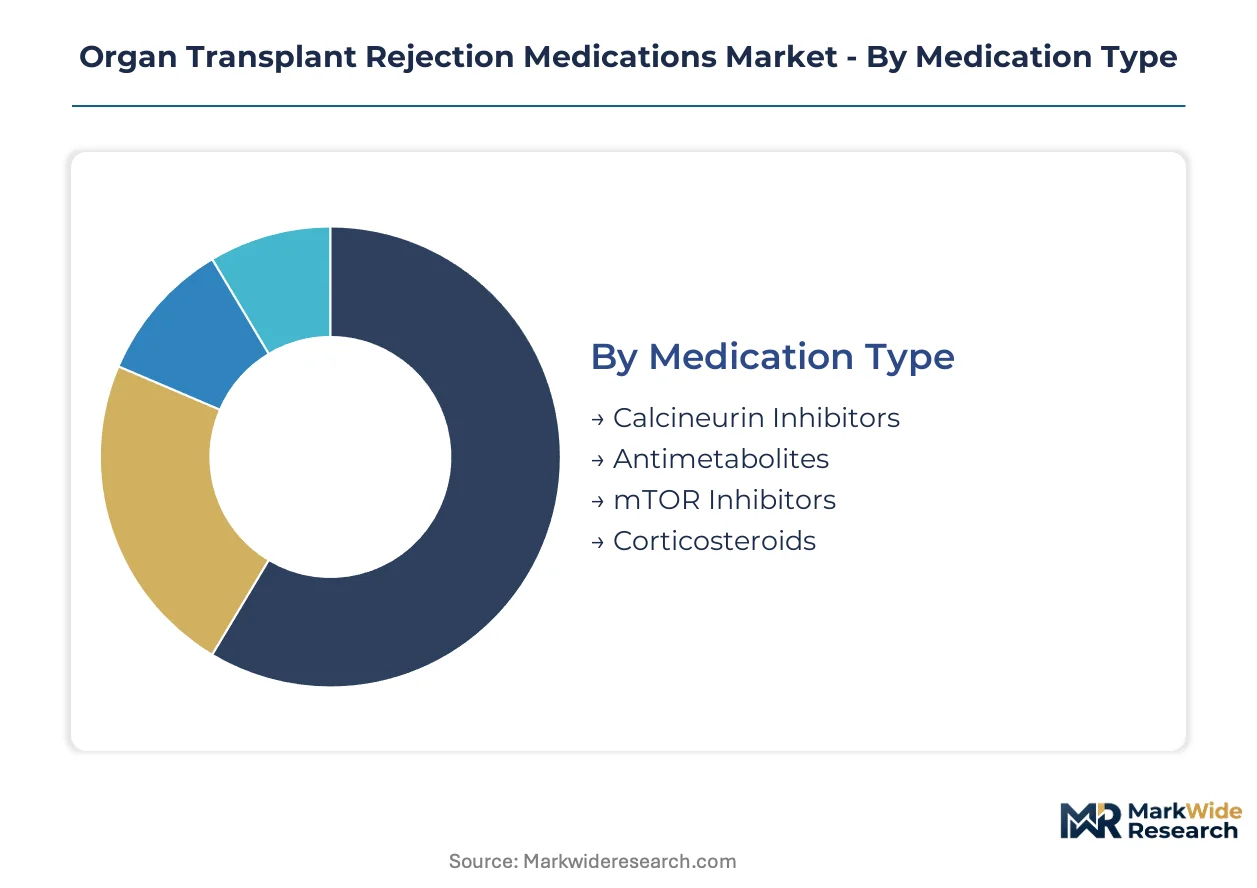
Segmentation in this market reveals how immunosuppressant procurement channels diverge across acute care versus chronic maintenance settings. Hospital pharmacy buyers, specialty distributors, and homecare infusion services each dominate distinct medication-route combinations.
Medication Type:
Hospital procurement channels favor calcineurin inhibitors and antimetabolites for their established reimbursement codes, while mTOR inhibitors flow increasingly through specialty pharmacy networks supporting calcineurin-sparing protocols.
- Calcineurin Inhibitors:Tacrolimus and cyclosporine form the backbone of triple-therapy regimens through their calcineurin-NFAT pathway blockade. Demand concentrates in United States academic medical centers where Medicare lifetime coverage sustains decades-long maintenance prescriptions. Supply continuity hinges on FDA bioequivalence standards that limit generic substitution without therapeutic drug monitoring.
- mTOR Inhibitors:Sirolimus and everolimus target the mTORC1 complex to inhibit IL-2-driven T-cell proliferation. Nephrology transplant programs in Germany and the United Kingdom are adopting these agents for calcineurin-sparing protocols that preserve renal function in kidney recipients. Volume is climbing fastest among programs with mass spectrometry capacity for drug level verification.
- Antimetabolites:Mycophenolate mofetil disrupts purine synthesis to block lymphocyte proliferation, supplied through high-volume hospital procurement contracts.
- Corticosteroids:Prednisone provides broad anti-inflammatory coverage during induction and tapering phases, distributed through retail and specialty pharmacy channels.
By volume, calcineurin inhibitors lead. By growth pace, mTOR inhibitors are expanding most quickly.
Administration Route:
Route selection determines pricing architecture and channel control, with intravenous formulations commanding hospital markup during perioperative phases while oral generics compete on pharmacy benefit manager formularies.
- Intravenous:Perioperative induction dosing of basiliximab and high-dose corticosteroids occurs exclusively in hospital infusion centers. United States transplant centers capture premium reimbursement for these acute administrations under diagnosis-related group coding.
- Oral:Maintenance tacrolimus and mycophenolate prescriptions generate recurring volume through decades-long therapy. Patient adherence programs in Medicare Advantage plans now integrate directly with specialty pharmacy networks to reduce non-compliance-driven rejection episodes.
- Subcutaneous:Limited applications include investigational tolerogenic cell therapies and select biologic agents in clinical trial settings.
- Topical:Restricted to dermatologic manifestations of graft-versus-host disease in bone marrow transplant populations.
Intravenous routes dominate acute revenue per dose. Oral formulations generate the largest cumulative prescription volume.
End User:
Customer type shapes contract structure, with integrated delivery networks consolidating purchasing across hospital and homecare settings while independent specialty clinics rely on group purchasing organization leverage.
- Hospitals:Academic medical centers with UNOS designation control induction therapy procurement through 340B discount programs and specialty pharmacy carve-outs. Cleveland Clinic and Mayo Clinic models demonstrate vertical integration from transplant surgery through maintenance dispensing.
- Homecare:Post-discharge immunosuppression management shifts to infusion services and mail-order specialty pharmacies. Medicare's lifetime coverage expansion has enlarged this channel's patient census substantially.
- Specialty Clinics:Independent nephrology and hepatology practices depend on therapeutic drug monitoring partnerships with reference laboratories.
- Research Institutions:Investigator-initiated trials of calcineurin-minimization protocols source comparator drugs through NIH-funded pharmacy cores.
Hospitals anchor procurement value. Homecare is gaining share fastest as post-acute management extends graft survival timelines.
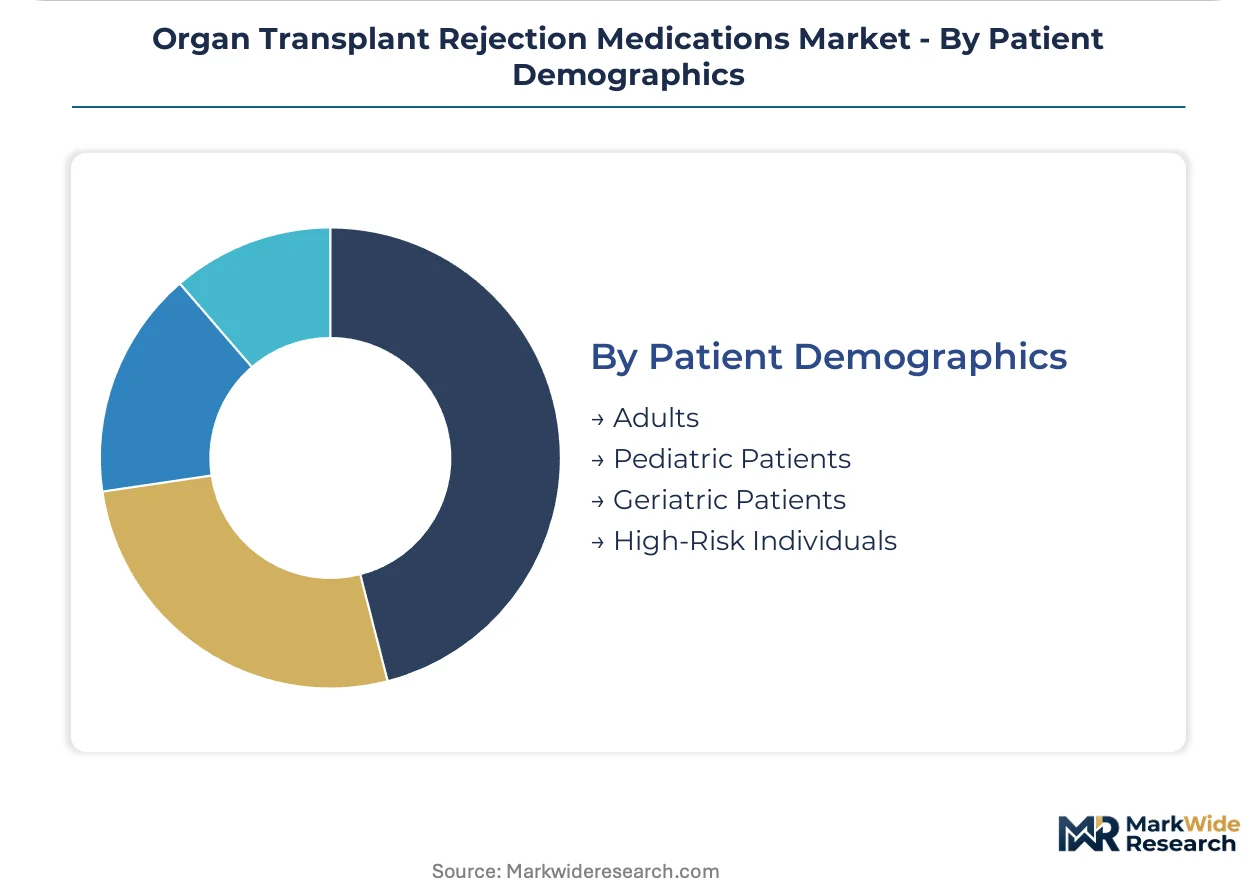
Patient Demographics:
Age-stratified protocols create dosing complexity that pharmaceutical manufacturers address through formulation strength portfolios and pediatric indication expansions.
- Pediatric Patients:Weight-based tacrolimus initiation and CYP3A5 pharmacogenomic testing are standard at Children's Hospital of Philadelphia and Boston Children's Hospital. Regulatory incentives for pediatric exclusivity extensions drive formulation development in this cohort.
- Adults:The largest absolute transplant volume group receives standardized triple-therapy with therapeutic drug monitoring at metropolitan transplant centers.
- Geriatric Patients:Expanded kidney paired donation programs have enlarged this segment, requiring dose adjustments for altered drug metabolism and comorbidity burden.
- High-Risk Individuals:Sensitized recipients with donor-specific antibodies receive intensified immunosuppression through IL-6 receptor antagonist protocols.
Adults represent the largest patient pool. Pediatric applications show the steepest protocol evolution trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare's lifetime immunosuppression coverage eliminated cost barriers for post-transplant patients in the United States, while EMA bioequivalence standards and WHO procurement benchmarks reshape access patterns across Europe and emerging economies.
United States
Kidney paired donation expansion and calcineurin-sparing protocol adoption drive volume growth at academic medical centers. FDA tightened bioequivalence standards for narrow therapeutic index drugs, limiting generic tacrolimus substitution without therapeutic drug monitoring. Cleveland Clinic and Mayo Clinic anchor procurement consolidation through vertically integrated specialty pharmacy operations.
Germany
Nephrology transplant programs adopt mTOR inhibitors for renal function preservation in calcineurin-sparing regimens. EMA Medical Device Regulation reorganizes companion diagnostic access, requiring pharmaceutical alignment with in-vitro diagnostic partners pursuing CE marking. Heidelberg and Berlin transplant centers concentrate mass spectrometry capacity for therapeutic drug monitoring.
United Kingdom
NHS England procurement frameworks standardize immunosuppressant purchasing across deceased donor program expansion. NICE technology appraisals influence formulary positioning for biologic induction agents versus small-molecule maintenance therapy. London and Manchester academic centers coordinate multi-site trials of calcineurin-minimization protocols.
India
Deceased donor program scaling in Tamil Nadu and Maharashtra enlarges the addressable patient pool for maintenance therapy. CDSCO manufacturing inspections for active pharmaceutical ingredient facilities determine supply continuity for domestic tacrolimus and mycophenolate production. Hyderabad and Ahmedabad house concentrated API synthesis operations serving European export markets.
Brazil
WHO Essential Medicines List inclusion of core immunosuppressants establishes procurement benchmarks for national health system purchasing. ANVISA bioequivalence requirements shape generic substitution patterns for maintenance therapy. São Paulo and Rio de Janeiro transplant centers concentrate therapeutic drug monitoring infrastructure and specialist nephrology follow-up capacity.
Organ Transplant Rejection Medications Market Competitive Environment
Listed leaders compete with private specialists across calcineurin inhibitor and biologic portfolios, producing a tiered structure where large-cap pharmaceutical corporations anchor standard-of-care maintenance therapy while mid-size firms capture calcineurin-sparing and induction segments. Three archetypes dominate: diversified Big Pharma with transplant-dedicated divisions, generic-heavy manufacturers exploiting FDA bioequivalence complexity, and biologic specialists developing IL-6 pathway antagonists. Competitive moves concentrate on companion diagnostic partnerships for pharmacogenomic dosing and specialty pharmacy network integration to capture lifetime maintenance value.
Within the diversified pharmaceutical tier, Astellas Pharma, Novartis AG, and F. Hoffmann-La Roche Ltd occupy positions that exemplify distinct strategic vectors. Astellas represents calcineurin inhibitor dominance through tacrolimus formulation concentration at major transplant centers. Novartis anchors antimetabolite supply chains sustaining high-volume hospital procurement for mycophenolate mofetil. Roche sits within the biologic development arc, with IL-6 receptor antagonist positioning for antibody-mediated rejection protocols. These three entities collectively illustrate how market position derives from molecule-class specialization rather than portfolio breadth alone.
| Leading Market Players |
|---|
| Astellas Pharma |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Sanofi |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Pfizer |
| AbbVie |
| Viatris |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day API inventory buffers at European formulation plants concentrate pricing power with Indian and Chinese tacrolimus manufacturers, while Medicare reimbursement floors in the United States insulate branded maintenance therapy from acute cost compression. This inventory-sensitivity nexus rewards manufacturers with backward-integrated active pharmaceutical ingredient capabilities and punishes pure-play formulators exposed to EMA inspection-triggered supply interruptions.
Pricing Analysis
FDA bioequivalence certification tiers for narrow therapeutic index drugs create the primary spread between premium branded tacrolimus and economy generic cyclosporine. Three-tier pricing structure across innovator, authorized generic, and unbranded generic levels concentrates margin in the top tier where therapeutic drug monitoring bundling justifies persistence pricing. Cost compression in the generic tier intensifies because CDSCO inspection outcomes in Hyderabad trigger spot shortages that force emergency procurement at inflated spot rates. Hospital pharmacy buyers at academic medical centers show least price sensitivity due to 340B discount capture, while independent nephrology clinics in Brazil and Mexico face acute budget constraints under WHO Essential Medicines List procurement benchmarks.
Supply Chain Analysis
Just-in-time inventory strategies dominate European transplant centers with mass spectrometry capacity, while strategic stockpiling prevails in United States integrated delivery networks facing Medicare lifetime coverage volume certainty. Active pharmaceutical ingredient synthesis concentrates in India, China, and Switzerland, with tacrolimus fermentation and mycophenolate mofetil chemical synthesis drawing from fermentation feedstocks and specialized solvent systems. Single-source vulnerability pervades the tacrolimus supply base where CDSCO and EMA inspection cycles determine lot release timing. Distribution runs through hospital-owned specialty pharmacy networks in the United States and government procurement warehouses in European national health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medicare lifetime immunosuppression coverage expansion signals early-cycle penetration growth in maintenance therapy adherence, with calcineurin-sparing protocol adoption representing a secondary volume tailwind in nephrology transplant programs.
For Market Incumbents: Fortify CYP3A5 pharmacogenomic testing integration through companion diagnostic partnerships before EMA Medical Device Regulation CE marking deadlines consolidate procurement around validated drug-diagnostic bundles. Secure backward integration into tacrolimus API fermentation capacity in India to neutralize CDSCO inspection disruption risks. Prioritize Cleveland Clinic and Mayo Clinic specialty pharmacy carve-outs as channel control anchors against biosimilar basiliximab entry. For New Entrants and Emerging Players: Differentiate on mass spectrometry-integrated adherence packaging for rural transplant follow-up clinics lacking therapeutic drug monitoring infrastructure. Target Brazil, Mexico, and Thailand national health system procurement tenders as the most penetrable geography cluster, where WHO Essential Medicines List benchmarks create transparent access pathways. Pursue investigator-initiated trial sponsorship of calcineurin-minimization protocols as the primary go-to-market credibility builder. For Investors and Strategic Acquirers: Long-term, this sits as a chronic-therapy annuity play because Medicare lifetime coverage eliminates the 36-month adherence cliff that previously truncated patient lifetime value. Acquisition target archetype: mid-size generic manufacturers with FDA-approved narrow therapeutic index portfolios and existing therapeutic drug monitoring laboratory partnerships. Watch tolerogenic dendritic cell trial readouts as the inflection signal that could displace chronic pharmaceutical immunosuppression requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Partnership | EMA Medical Device Regulation CE marking creates durable competitive moats for integrated drug-testing offerings. |
| API Backward Integration | Captive tacrolimus fermentation capacity in India neutralizes CDSCO inspection-driven supply interruptions. |
| Specialty Pharmacy Network Acquisition | Vertical control from transplant surgery through maintenance dispensing captures Medicare lifetime value. |
| Pharmacogenomic Algorithm Development | CYP3A5 genotype-guided dosing compresses time-to-therapeutic range at Cleveland Clinic and Mayo Clinic. |
| Biosimilar Basiliximab Manufacturing Scale-Up | Patent expiration creates white space for cost-competitive induction agents against depleting antibody protocols. |
Study Parameters
Operator-level perspectives from transplant pharmacy directors, formulary committee chairs, therapeutic drug monitoring laboratory managers, and CDSCO inspection compliance officers anchored the qualitative base for this analysis. Primary interview findings combined with secondary validation from FDA bioequivalence guidance documents, EMA Good Manufacturing Practice inspection reports, ClinicalTrials.gov protocol registries, and UNOS organ allocation policy filings. Bottom-up prescription volume modeling and top-down pharmaceutical manufacturer revenue triangulation cross-checked segment-level estimates.
Sensitivity analysis across CYP3A5 pharmacogenomic adoption rates, biosimilar basiliximab entry timing, and cellular therapy substitution scenarios tested forecast robustness over the projection horizon. Segmentation dimensions modeled encompass medication type, administration route, end-user channel, and patient demographic stratification. CAGRs derived from log-linear trend fitting to Medicare claims data and hospital procurement database extracts, with calcineurin-sparing protocol penetration and kidney paired donation volume serving as key demand-side inputs.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and EMA inspection cadence; material deviation would warrant model refresh. Specific risk factors include tolerogenic cell therapy trial success, generic tacrolimus bioequivalence standard relaxation, and API facility regulatory enforcement intensity. Revision becomes warranted when cellular therapy substitution crosses threshold efficacy in operational tolerance induction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Esomeprazole Market
Pharmaceuticals
Complement-Targeted Therapeutics Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Global Non-Small Cell Lung Cancer Drugs Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Global Fibrinogen Concentrates Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market