
 Radiopharmaceutical (Oral Route) Market | 2026-2036
Radiopharmaceutical (Oral Route) Market Size, Share, and Industry Trends Forecast 2026-2036
Radiopharmaceutical (Oral Route) Market Insights
The buyer base for oral radiopharmaceuticals is broadening beyond traditional hospital nuclear medicine departments to include outpatient clinics and specialized diagnostic laboratories seeking point-of-care capabilities. Novartis AG leverages its integrated radiopharmaceutical platform to sustain leadership in therapeutic and diagnostic isotope development. Bayer AG anchors its position through deep manufacturing scale in radiopharmaceutical precursors. Curium competes aggressively on geographic reach across European and North American radiopharmacy networks.
Radiopharmaceuticals administered via oral route consist of radioisotope-bearing compounds formulated for gastrointestinal absorption, typically incorporating iodine-131, strontium-89, or samarium-153 in liquid or capsule matrices designed for specific organ targeting. These agents serve primarily to diagnose metabolic disorders or deliver localized therapeutic radiation to bone metastases and thyroid malignancies with minimal invasive intervention. Diagnostic radiopharmaceuticals occupy the largest revenue pool currently, while therapeutic radiopharmaceuticals represent the fastest-expanding margin segment as alpha-emitter therapies gain clinical traction. Liquid formulations dominate operational volumes due to established compounding workflows, though solid formulations are gaining preference for patient compliance and dosing precision in outpatient settings.
The FDA maintains stringent current good manufacturing practice requirements for radiopharmaceutical production, while the EMA enforces centralized marketing authorization through the European Pharmacopoeia's monograph standards for isotope purity and sterility. These frameworks elevate capital barriers for new entrants but simultaneously validate premium pricing for manufacturers achieving dual FDA-EMA compliance. Stakeholders must monitor evolving orphan drug designation pathways and investigational new drug filing trends to anticipate which isotope platforms will secure priority review status.
Market Dynamics
The FDA's streamlined approval pathways for radiopharmaceuticals are compressing development timelines and pulling venture capital toward alpha-emitter platforms, fundamentally restructuring how manufacturers prioritize isotope portfolios.
Growth Catalysts
- Orphan Drug Designation:The FDA's priority review vouchers for rare disease indications accelerate commercialization timelines for neuroendocrine tumor therapies.
- Radiopharmacy Network Expansion:Academic medical centers in the United States, Germany, and Japan are building dedicated compounding facilities to support outpatient administration.
- Alpha-Emitter Clinical Validation:Lead-212 and actinium-225 therapies demonstrate superior therapeutic indices in bone metastasis protocols.
Market Restraints
- Isotope Supply Concentration:High-enriched uranium and reactor-produced molybdenum-99 depend on aging facilities in Canada and the Netherlands.
- cGMP Capital Intensity:Current good manufacturing practice compliance for sterile radiopharmaceutical production requires specialized hot cells and real-time release testing infrastructure.
- Short Half-Life Logistics:Fluorine-18 and gallium-68 decay rates constrain distribution radii to four-hour driving distances from production sites.
Strategic Opportunities
- Point-of-Care Synthesis:Compact cyclotron installations at outpatient oncology clinics bypass centralized radiopharmacy bottlenecks.
- EMA Centralized Authorization:The European Medicines Agency's mutual recognition procedure enables simultaneous market access across 27 member states.
- Theranostic Pairing:Diagnostic lutetium-177 imaging preceding therapeutic dosing optimizes patient selection and reimbursement justification.
Industry Challenges
- Radiochemist Talent Scarcity:The specialized synthesis expertise required for carbon-11 and zirconium-89 labeling exceeds current training pipeline output.
- Cold Chain Integrity:Temperature excursions during transport of temperature-sensitive biomolecule conjugates compromise batch viability.
- Legacy IT Integration:Hospital information systems lack standardized interfaces for radiopharmaceutical dose tracking and decay-corrected billing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiopharmaceutical (Oral Route) Market |
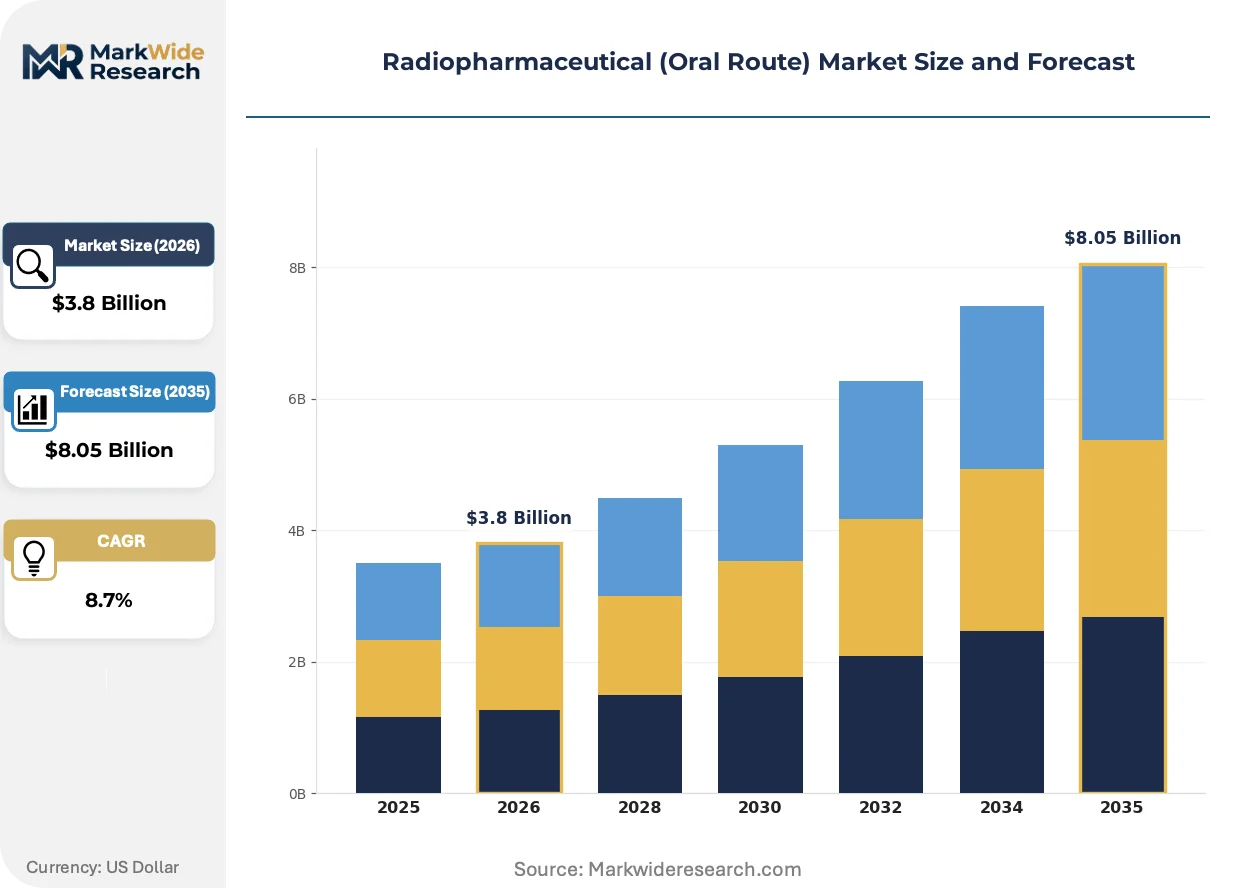
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Radiopharmaceuticals, Therapeutic Radiopharmaceuticals, Radioisotopes, Radiopharmaceutical Kits End User: Hospitals, Research Institutions, Diagnostic Laboratories, Outpatient Clinics Delivery Mode: Liquid Formulations, Solid Formulations, Compounded Preparations, Stable Isotopes Regulatory Category: FDA Approved, CE Mark, Investigational New Drug, Orphan Drug Designation |
| Companies Covered | Novartis AG, Bayer AG, Curium, GE Healthcare, Cardinal Health, Lantheus Medical Imaging, Jubilant Pharma, Nordion, Bracco Imaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiopharmaceutical (Oral Route) Market Trends and Innovations
Automation and miniaturization are compressing production footprints while expanding patient access, with three convergent developments reshaping competitive positioning.
Microfluidic synthesis platforms are modularizing radiochemistry workflows by integrating purification, formulation, and quality control into single-instrument footprints. Regional hospital networks in Germany and Japan are piloting these systems to decentralize fluorine-18 production. The technology is modularizing supply chain economics by eliminating batch-scale minimums and enabling patient-specific dosing.
REACH regulation amendments governing radiometal impurities are forcing European manufacturers to revalidate precursor supply chains. The industrial consequence is accelerated adoption of non-carrier-added isotope grades. Therapeutic radiopharmaceutical developers face the steepest compliance costs, with several reformulating to meet the European Pharmacopoeia's revised monograph standards.
Hospital purchasing consortia are consolidating procurement authority for high-cost therapeutic isotopes, displacing traditional distributor relationships. Integrated delivery networks in the United States now negotiate directly with manufacturers for lutetium-177 supply. This concentration is most visible in multi-state oncology alliances seeking volume-based pricing guarantees.
Radiopharmaceutical (Oral Route) Market Segmentation
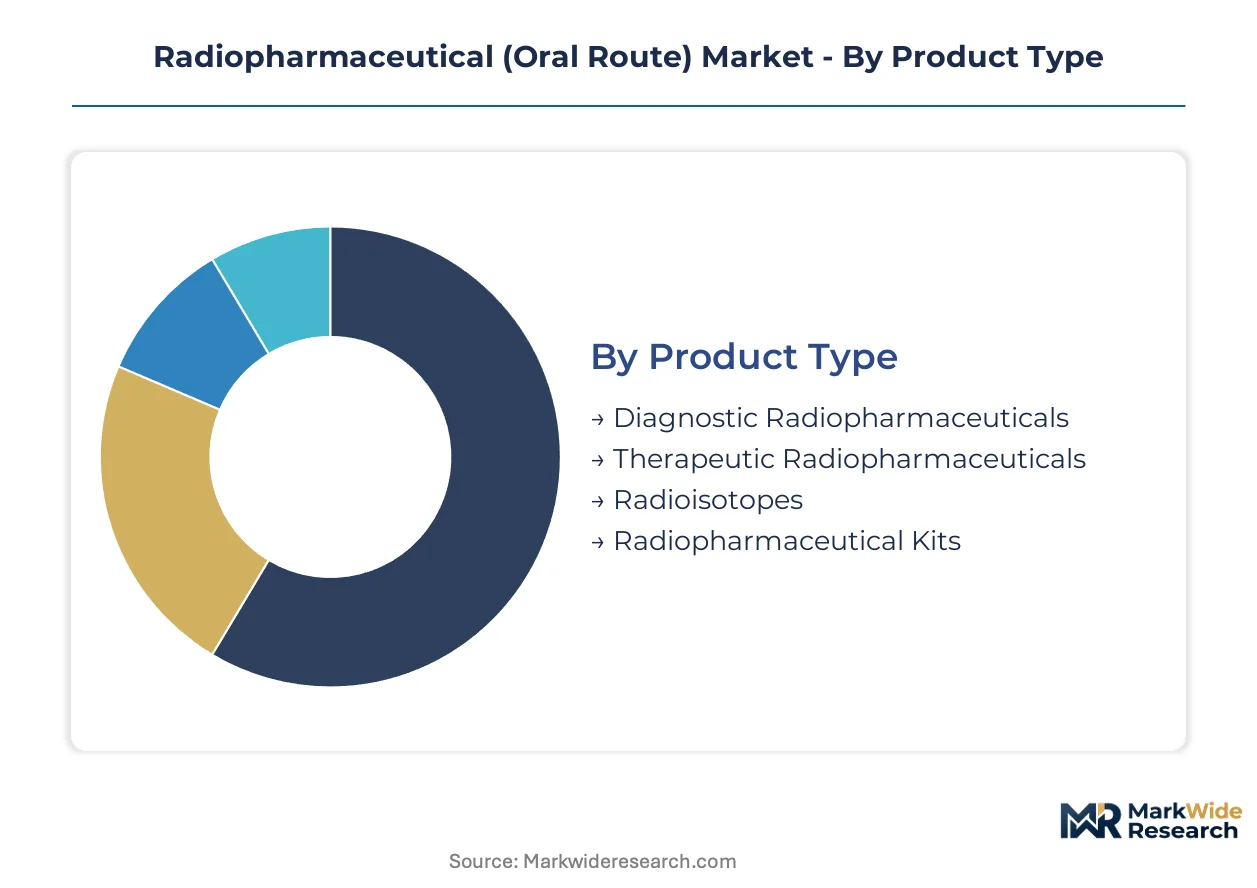
Segmentation in oral radiopharmaceuticals reveals how clinical utility, regulatory pathway, and administration setting intersect to determine commercial strategy. Manufacturers must align formulation choices with specific end-user infrastructure and reimbursement mechanisms.
Product Type:
Formulation chemistry and clinical intent define how value accumulates across product categories, with diagnostic and therapeutic agents following divergent development economics.
- Diagnostic Radiopharmaceuticals:Iodine-131 and technetium-99m compounds enable metabolic imaging and organ function assessment through gamma emission detection. United States academic medical centers drive procurement volumes as they expand theranostic programs pairing diagnostic scans with subsequent therapeutic dosing.
- Therapeutic Radiopharmaceuticals:Alpha-emitter and beta-emitter formulations deliver targeted radiation to bone metastases and neuroendocrine tumors. Germany's university hospital networks are accelerating adoption as EMA centralized authorizations streamline cross-border patient access.
- Radioisotopes:Strontium-89 and samarium-153 supply the active pharmaceutical ingredient foundation for compounded therapies.
- Radiopharmaceutical Kits:Cold kits enable on-site radiolabeling by hospital nuclear pharmacies.
Diagnostic Radiopharmaceuticals lead on scale; Therapeutic Radiopharmaceuticals lead on momentum.
End User:
Infrastructure investment patterns across care settings are redistributing where oral radiopharmaceuticals are prepared and administered.
- Hospitals:Integrated nuclear medicine departments with cyclotron access or radiopharmacy partnerships handle complex therapeutic protocols requiring inpatient monitoring. Japan's designated cancer centers anchor regional referral networks for oral iodine-131 thyroid therapies.
- Outpatient Clinics:Specialized oncology clinics with point-of-care synthesis capabilities are capturing routine diagnostic procedures. United States multi-site oncology alliances negotiate directly with manufacturers for lutetium-177 supply guarantees.
- Research Institutions:Academic centers conduct investigator-initiated trials for novel isotope platforms.
- Diagnostic Laboratories:Independent imaging centers perform standardized metabolic scans.
Hospitals retain the deepest therapeutic case volume; Outpatient Clinics are expanding most quickly into diagnostic services.
Delivery Mode:
Physical formulation determines stability windows, patient compliance, and compounding workflow requirements.
- Liquid Formulations:Aqueous solutions of iodine-131 sodium iodide or strontium-89 chloride permit precise dose titration and established quality control protocols. Liquid matrices dominate current operational volumes due to mature radiopharmacy infrastructure.
- Solid Formulations:Capsule and tablet matrices improve patient compliance and reduce radiation exposure to handlers during administration. Outpatient settings in Germany and Japan are driving preference shifts toward solid dosage forms for take-home therapeutic regimens.
- Compounded Preparations:Patient-specific formulations address individualized dosing requirements.
- Stable Isotopes:Non-radioactive precursors support diagnostic and research applications.
Liquid Formulations lead on scale; Solid Formulations lead on momentum.
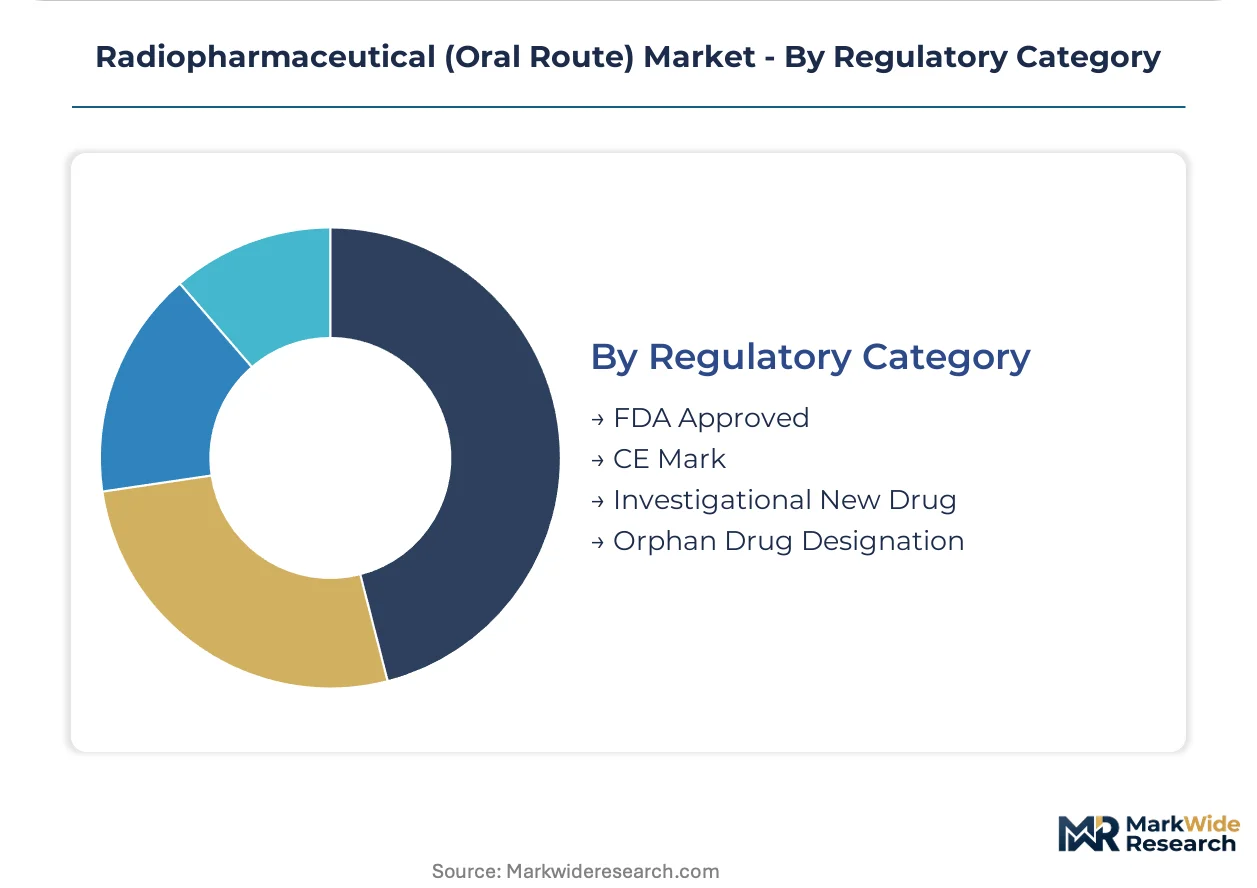
Regulatory Category:
Approval pathway selection shapes development timelines, exclusivity periods, and reimbursement positioning.
- FDA Approved:Full new drug application approvals carry the highest validation for reimbursement and clinical adoption. United States commercial payers require FDA approval for coverage of high-cost therapeutic radiopharmaceuticals.
- Orphan Drug Designation:Priority review vouchers and market exclusivity incentives accelerate rare disease indications. Neuroendocrine tumor therapies with orphan designation are compressing commercialization timelines.
- CE Mark:European conformity assessment enables access across EEA member states.
- Investigational New Drug:IND status supports clinical trial supply and early access programs.
FDA Approved products lead on scale; Orphan Drug Designation pathways lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands the largest share of oral radiopharmaceutical consumption, while Germany's university hospital networks are accelerating therapeutic adoption at comparable velocity. Japan's designated cancer centers anchor Asia-Pacific demand for thyroid and neuroendocrine protocols. Switzerland and the Netherlands concentrate manufacturing infrastructure for isotope precursors.
United States
Academic medical centers in Boston and Houston are expanding dedicated radiopharmacy facilities to support outpatient therapeutic administration. The FDA's streamlined approval pathways for radiopharmaceuticals are compressing development timelines for alpha-emitter platforms. Multi-state oncology alliances in the Southeast and Midwest now negotiate directly with manufacturers for lutetium-177 supply guarantees.
Germany
University hospital networks in Munich and Heidelberg are accelerating adoption of oral radiopharmaceuticals for neuroendocrine tumor management. EMA centralized authorizations through the European Pharmacopoeia's monograph standards streamline cross-border patient access. The Rhine-Ruhr industrial corridor hosts specialized hot cell manufacturing facilities serving domestic and export markets.
Japan
Designated cancer centers in Tokyo and Osaka anchor regional referral networks for oral iodine-131 thyroid therapies. PMDA regulatory frameworks align with international standards while maintaining stringent isotope purity requirements. The Kansai region's radiopharmacy infrastructure is expanding to support decentralized outpatient administration.
Switzerland
Specialized manufacturing clusters in Basel and Geneva concentrate precursor production for European and North American markets. Swissmedic maintains rigorous current good manufacturing practice oversight that validates premium positioning for export-oriented producers. The country's neutrality in pharmaceutical trade agreements facilitates dual FDA-EMA compliance pathways.
Netherlands
Aging reactor facilities in Petten continue supplying high-enriched uranium and molybdenum-99 despite infrastructure vulnerability concerns. The national pharmaceutical regulator enforces European Pharmacopoeia sterility standards that elevate capital barriers for new entrants. Rotterdam's logistics hub manages cold chain distribution for temperature-sensitive biomolecule conjugates across Western Europe.
Radiopharmaceutical (Oral Route) Market Competitive Landscape
United States producers anchor one tier; European specialists hold manufacturing scale advantages in precursor supply. The market structure concentrates around integrated radiopharmaceutical platforms, diversified healthcare conglomerates, and dedicated radiopharmacy network operators. Three strategic archetypes dominate: theranostic pair developers, isotope infrastructure owners, and geographic reach specialists. Competitive moves center on radiopharmacy network expansion and alpha-emitter portfolio diversification.
Within the integrated platform tier, Novartis AG and Bayer AG exemplify archetypes combining diagnostic and therapeutic isotope development with deep manufacturing infrastructure. Curium occupies a position as a geographic reach specialist across European and North American radiopharmacy networks. These three companies represent distinct strategic postures: Novartis AG sits within the theranostic integration archetype, Bayer AG anchors the precursor manufacturing scale tier, and Curium exemplifies the network density competitive vector.
| Leading Market Players |
|---|
| Novartis AG |
| Bayer AG |
| Curium |
| GE Healthcare |
| Cardinal Health |
| Lantheus Medical Imaging |
| Jubilant Pharma |
| Nordion |
| Bracco Imaging |
| Others |
Pricing and Supply Chain Analysis
Molybdenum-99 spot pricing volatility cascades through radiopharmaceutical supply chains into three distinct procurement tiers: academic medical centers with cyclotron partnerships command volume discounts, outpatient clinics absorb premium markups for unit-of-use packaging, and research institutions negotiate flexible pricing for investigational batches.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for oral radiopharmaceuticals across contract-based long-term offtake structures. Price differentiation separates FDA-validated premium tiers from CE-marked standard offerings and compounded economy alternatives. Cost compression in the economy tier is intensifying as hospital purchasing consortia consolidate procurement authority. Outpatient clinics exhibit highest price sensitivity due to reimbursement lag, while integrated delivery networks leverage volume scale for preferential terms.
Supply Chain Analysis
Single-source vulnerability sits with aging reactor facilities in Canada and the Netherlands for high-enriched uranium feedstock. Isotope production draws from Belgium, South Africa, and Australia as secondary supply nodes. Raw material dependencies center on uranium hexafluoride, enriched molybdenum targets, and radiometal precursors. Tariff exposure on isotope imports from non-FTA countries presents structural risk. Distribution runs through specialized radiopharmacy networks with four-hour decay-corrected logistics windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oral radiopharmaceutical market functions as a geographic-arbitrage play: EMA centralized authorization costs in Germany run substantially below fragmented national pathway expenses in Southern Europe, creating margin expansion for cross-border suppliers.
For Market Incumbents: Deploy theranostic platform bundling to lock in academic medical center loyalty against alpha-emitter specialist entrants. Secure backward integration into isotope precursor production to insulate margins from molybdenum-99 supply shocks. Deepen radiopharmacy network density in the United States Southeast where outpatient clinic expansion outpaces infrastructure investment. For New Entrants and Emerging Players: The premium-to-economy price-point gap in therapeutic radiopharmaceuticals creates entry opportunity for solid-formulation specialists targeting German outpatient compliance preferences. White-space exists in point-of-care synthesis equipment for United States multi-site oncology alliances. Pursue orphan drug designation pathways for neuroendocrine tumor indications to compress regulatory timelines and secure priority review positioning. For Investors and Strategic Acquirers: Asymmetric upside sits with geographic reach specialists possessing radiopharmacy network assets across both FDA and EMA jurisdictions. Long-term viability hinges on alpha-emitter portfolio breadth over the next decade. Acquisition targets should demonstrate dual-compliance manufacturing infrastructure. Monitor IND filing velocity for lead-212 and actinium-225 platforms as inflection signal for therapeutic radiopharmaceutical momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Radiopharmacy Network Expansion | Decentralized compounding facilities in Germany and Japan bypass centralized production bottlenecks. |
| Alpha-Emitter Portfolio Diversification | Lead-212 and actinium-225 investments capture fastest-expanding therapeutic margin segment. |
| Dual FDA-EMA Compliance Investment | Simultaneous validation unlocks premium pricing across United States and European hospital systems. |
| Point-of-Care Synthesis Partnership | Compact cyclotron installations at outpatient clinics enable patient-specific dosing economics. |
| Orphan Drug Designation Pathway | Priority review vouchers for neuroendocrine tumor therapies compress commercialization timelines. |
Research Methodology
Direct dialogue with nuclear medicine department heads, radiopharmacy operations managers, regulatory affairs specialists at isotope manufacturers, and hospital procurement directors grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, EMA centralized authorization decisions, ClinicalTrials.gov radiopharmaceutical protocols, and European Pharmacopoeia monograph revisions. Bottom-up demand modeling across end-user segments triangulated with top-down isotope production capacity assessments.
Segment-level value outputs were generated across product type, end user, delivery mode, and regulatory category dimensions over the projection horizon. CAGRs were derived from patient volume forecasts, reimbursement trajectory assumptions, and isotope supply expansion timelines. Forecast inputs incorporated PMDA regulatory alignment patterns in Japan and REACH amendment impacts on European precursor supply chains.
Caveats apply where reactor facility decommissioning schedules or orphan drug designation pathway modifications could materially shift the outlook. Forecasts reflect documented assumptions about isotope supply continuity and payer coverage expansion for therapeutic radiopharmaceuticals. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
OTC Cough, Cold & Allergy Medicine Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Etoricoxib Market
Pharmaceuticals
Global Azithromycin Market
Pharmaceuticals
Cough Oral Solution Market
Pharmaceuticals
North America Sodium-Dependent Glucose Co-Transporter 2 (Sglt2) Market
Pharmaceuticals
Global Parkinson's Disease Drugs Market
Pharmaceuticals
Mitochondrial-Based Therapeutics Market
Pharmaceuticals
Macrolides Market
Pharmaceuticals
Tranquilizer Drugs Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Global Atrial Fibrillation Drugs Market