
 Africa Generic Pharmaceutical Market | 2026-2036
Africa Generic Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Generic Pharmaceutical Market Analytics
Blister-to-bottle packaging flexibility is decoupling procurement decisions from traditional tender formats, letting buyers mix pack sizes across treatment courses. Teva Pharmaceutical Industries Ltd. leverages its WHO-prequalified portfolio to anchor institutional contracts in multiple African markets. Aspen Holdings sustains regional manufacturing scale through its South African facilities, while Cipla South Africa competes on respiratory and antiretroviral specialization.
Africa generic pharmaceuticals comprise off-patent small-molecule drugs manufactured to identical active pharmaceutical ingredient strength, dosage form, and route of administration as originator references, with bioequivalence demonstration against pharmacopeial standards serving as the primary quality gate. These products address chronic disease burdens and infectious disease protocols where cost minimization determines treatment access at population scale. Tablet formulations occupy the largest volume share across therapy areas, while injectable generics capture concentrated margin pools in hospital segments where cold-chain reliability and sterility assurance command procurement premiums. Distribution through wholesale channels dominates volume flow, though direct sales to government tenders concentrate value capture for manufacturers with in-house regulatory affairs capacity.
South Africa's SAHPRA, Nigeria's NAFDAC, and the WHO prequalification program collectively set the tripartite regulatory framework governing market access across the continent. National bioequivalence study requirements and good manufacturing practice inspections shape which suppliers qualify for public sector tenders, creating structural barriers for non-compliant manufacturers. Stakeholders must monitor divergence between harmonized African Medicines Regulatory Harmonization standards and country-specific labeling or stability requirements that fragment compliance costs.
Market Dynamics
Public hospital procurement consolidation across East Africa is compressing supplier margins while amplifying volume commitments to WHO-prequalified manufacturers, fundamentally restructuring competitive positioning around regulatory compliance rather than price alone.
Growth Catalysts
- WHO Prequalification Program:Institutional buyers in Nigeria's northern states now mandate WHO-prequalified suppliers for state drug revolving fund purchases, locking in compliant manufacturers.
- Chronic Disease Burden:Rising diabetes and cardiovascular treatment protocols across sub-Saharan Africa expand prescription volumes for metformin and statin generics.
- Bioequivalence Harmonization:South Africa's SAHPRA alignment with African Medicines Regulatory Harmonization standards reduces redundant testing costs for regional suppliers.
Market Restraints
- API Import Dependency:Active pharmaceutical ingredient sourcing concentrates in Indian and Chinese suppliers, exposing African formulators to currency volatility and shipping disruptions.
- Cold-Chain Infrastructure Gaps:Injectable generics requiring 2-8°C storage face spoilage rates exceeding 15% in last-mile distribution to rural clinics.
- Regulatory Fragmentation:Divergent labeling requirements between Nigeria's NAFDAC and Kenya's PPB force manufacturers to maintain multiple packaging SKUs.
Strategic Opportunities
- West African Manufacturing:Ghana's emerging pharmaceutical zone offers tariff advantages for exports to ECOWAS markets under regional trade protocols.
- Fixed-Dose Combination Expansion:HIV triple-therapy co-formulations address patient adherence gaps while capturing higher per-unit margins than single-agent generics.
- Direct Hospital Contracting:Bypassing wholesale layers through tender participation lets manufacturers capture value previously lost to distributor markups.
Industry Challenges
- Bioequivalence Study Capacity:Qualified clinical pharmacology units in South Africa and Egypt face 8-12 month booking backlogs, delaying product launches.
- Legacy Distribution Integration:Informal pharmaceutical markets in Lagos and Kinshasa resist traceability system adoption, complicating anti-counterfeiting efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Generic Pharmaceutical Market |
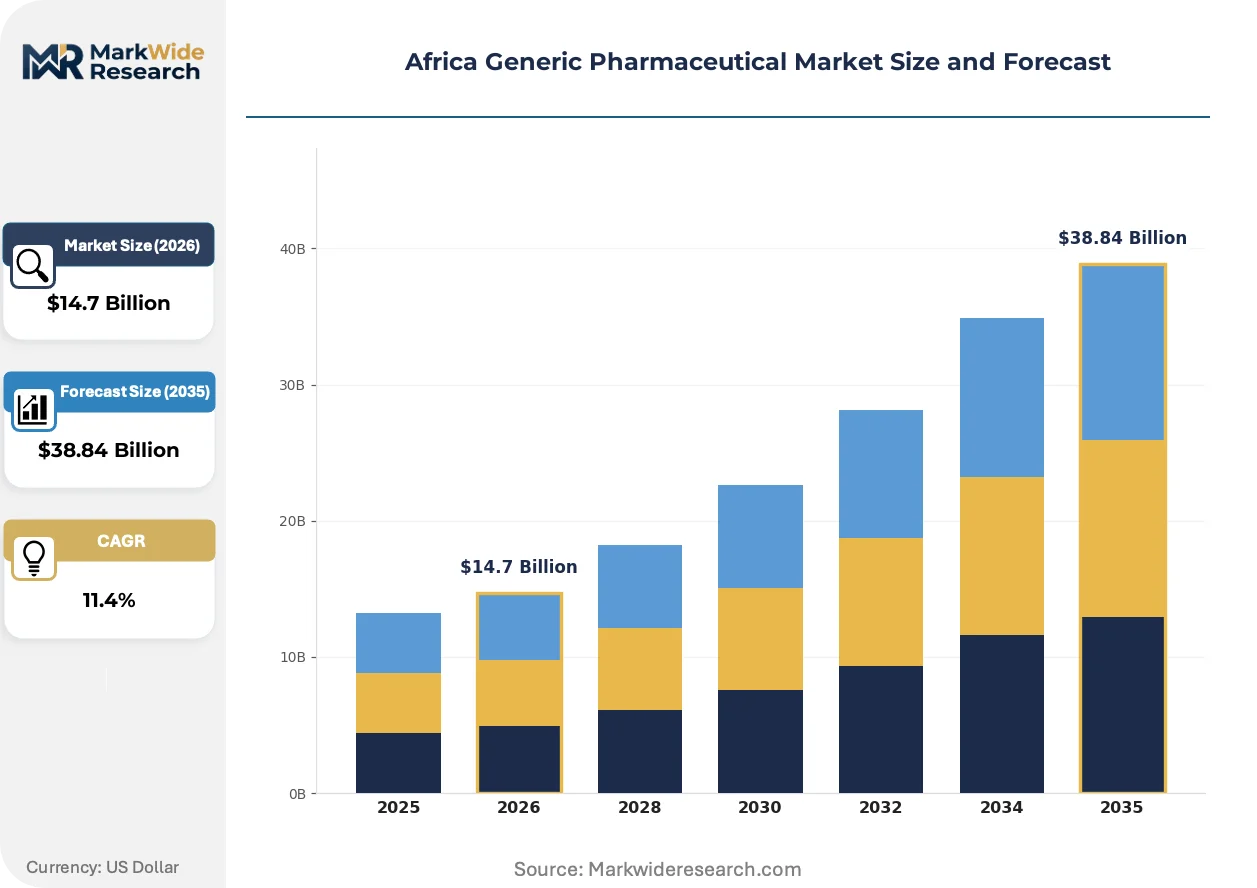
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Topical End User: Hospitals, Pharmacies, Clinics, Distributors Therapy Area: Cardiovascular, Antibiotics, Antipyretics, Antidiabetics Distribution Channel: Wholesale, Online, Direct Sales, Retail |
| Companies Covered | Teva Pharmaceutical Industries Ltd., Lupin, Aspen Holdings, Hikma Pharmaceuticals, Aurobindo Pharma, Cipla South Africa, Sun Pharmaceutical Industries Ltd., Dr. Reddy’s Laboratories Ltd., Adcock Ingram Holdings Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Generic Pharmaceutical Market Evolving Landscape
Continuous manufacturing technologies and regulatory data harmonization are compressing development timelines while enabling smaller batch sizes that match fragmented African market demand patterns.
Continuous direct compression is converging with real-time release testing to slash batch validation periods from weeks to hours. Mid-scale African manufacturers in South Africa and Egypt are piloting these lines to serve tender orders with shorter lead times. This technology convergence is enabling just-in-time production that reduces working capital requirements for products with unpredictable demand cycles.
South Africa's SAHPRA has mandated electronic common technical document submissions for all new generic applications starting 2024, eliminating paper-based dossier reviews. The industrial consequence is a 40% reduction in regulatory review cycles for prepared filers. Respiratory and antiretroviral specialists are responding fastest, leveraging existing quality management system investments to accelerate portfolio expansion.
State drug revolving funds in Nigeria and Tanzania are consolidating purchases through framework agreements that replace annual tenders with multi-year volume commitments. Hospital procurement officers now negotiate directly with manufacturers rather than through central medical stores. This shift is most visible in Kenya's public sector, where county health departments bypass national procurement bodies for high-volume chronic disease medications.
Africa Generic Pharmaceutical Market Segmentation
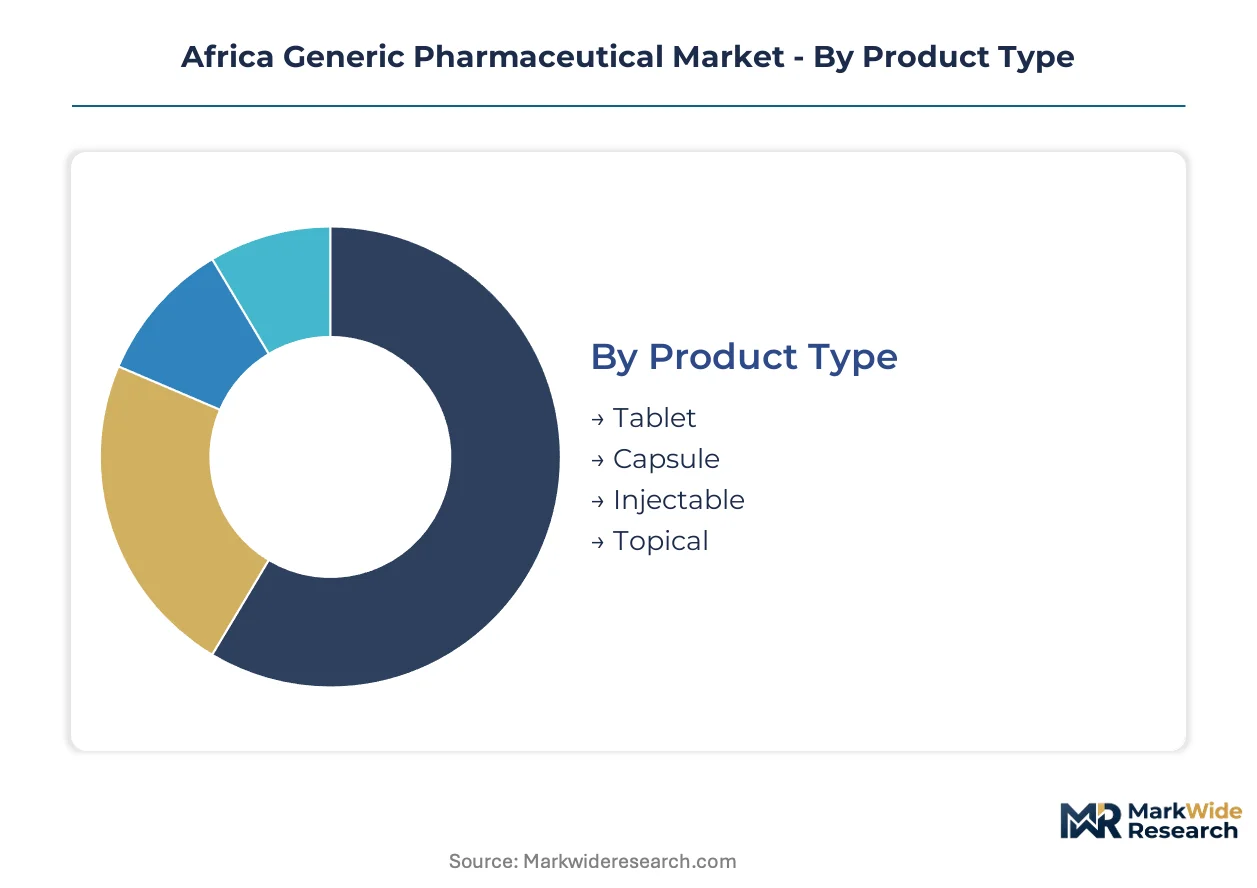
Segmentation in Africa's generic pharmaceutical market exposes how capital requirements, regulatory compliance burdens, and distribution economics concentrate value capture across distinct product and channel configurations. Manufacturers optimize portfolio mix against therapy-area procurement patterns and cold-chain infrastructure availability.
Product Type:
Capital intensity varies sharply across dosage forms, with sterile manufacturing demanding tenfold higher upfront investment than solid oral facilities.
- Tablet:Solid oral dosages dominate procurement volumes for chronic disease protocols, with metformin and statin formulations absorbing the largest share of East African hospital tenders. SAHPRA's bioequivalence requirements favor manufacturers with in-house dissolution testing capacity.
- Injectable:Sterile parenteral products command procurement premiums in hospital segments where 2-8°C cold-chain reliability determines supplier qualification. Nigerian state drug revolving funds now mandate temperature-validated distribution for injectable antibiotics.
- Capsule:Gelatin and HPMC shell formulations serve pediatric and geriatric populations with swallowing difficulties, particularly in Kenya's county health department purchases.
- Topical:Cream and ointment manufacturing requires lower capital outlay but faces margin compression from informal market competition in Lagos and Kinshasa distribution channels.
Tablet production absorbs the bulk of installed capacity; Injectable is expanding most quickly.
End User:
Procurement authority concentration determines contract structure complexity and payment security risk for manufacturers.
- Hospitals:Public sector institutions in Nigeria's northern states consolidate purchases through framework agreements, locking in multi-year volume commitments to WHO-prequalified suppliers. County health departments in Kenya bypass central medical stores for direct manufacturer negotiation.
- Pharmacies:Retail dispensaries in urban centers face working capital constraints that favor distributors with extended payment terms, fragmenting manufacturer margin capture.
- Clinics:Primary care facilities in rural Tanzania and Uganda rely on state drug revolving funds, concentrating demand around essential medicines lists.
- Distributors:Wholesale intermediaries in Ghana's emerging pharmaceutical zone leverage ECOWAS tariff advantages for regional re-export.
Hospital procurement commands the largest contract values; Direct sales to clinics are climbing the fastest as county-level decentralization accelerates.
Therapy Area:
Disease burden demographics and treatment protocol standardization shape which therapy categories support viable generic substitution economics.
- Cardiovascular:Statin and antihypertensive protocols expand across sub-Saharan Africa as urbanization drives metabolic disease prevalence. Nigerian state tenders now specify fixed-dose combination products to improve adherence.
- Antibiotics:Injectable cephalosporins and oral amoxicillin formulations face procurement price caps in public tenders, squeezing margin pools for non-integrated manufacturers.
- Antipyretics:Paracetamol and ibuprofen tablets serve over-the-counter demand through retail pharmacy chains with minimal regulatory friction.
- Antidiabetics:Metformin generics anchor chronic disease formularies in East African public hospitals, with bioequivalence demonstration against European pharmacopeial references now standard.
Cardiovascular manufacturing absorbs the bulk of capacity expansion; Antidiabetics are gaining share fastest as treatment protocols penetrate rural clinics.
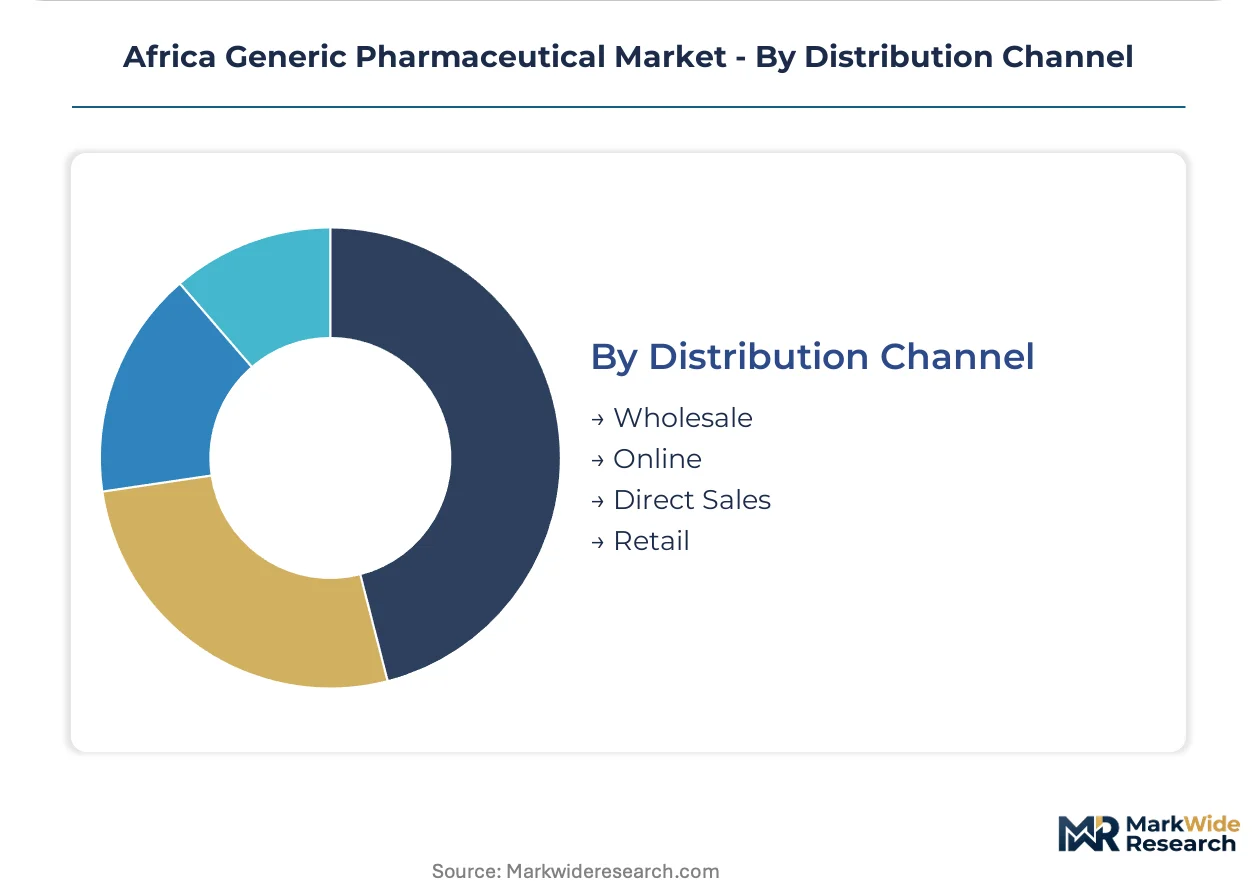
Distribution Channel:
Channel selection determines working capital intensity and exposure to payment default risk across African markets.
- Wholesale:Traditional distributor networks dominate volume flow to retail pharmacies, though markups erode manufacturer value capture by 15-25 percentage points.
- Direct Sales:Tender participation bypasses wholesale layers, letting manufacturers with in-house regulatory affairs capacity capture full contract value in South African and Nigerian public procurement.
- Online:E-pharmacy platforms in Nairobi and Lagos pilot prescription fulfillment with limited cold-chain capability, restricting assortment to ambient-stable solid oral products.
- Retail:Pharmacy chain consolidation in urban South Africa concentrates purchasing power, enabling private-label generic sourcing direct from manufacturers.
Wholesale channels handle the bulk of transaction volume; Direct sales are expanding most quickly as procurement decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in South Africa and Egypt while consumption spreads across sub-Saharan markets, creating a structural trade flow that exposes formulators to API import costs and currency volatility. National procurement systems are diverging in sophistication, with some markets consolidating around WHO-prequalified suppliers while others fragment across informal distribution layers.
South Africa
SAHPRA's electronic common technical document mandate from 2024 compresses regulatory review cycles for prepared filers. The regulator's alignment with African Medicines Regulatory Harmonization standards reduces redundant bioequivalence testing costs for regional suppliers. Manufacturing clusters in Gauteng and the Western Cape anchor sterile injectable and solid oral dosage production for export to SADC markets.
Nigeria
State drug revolving funds in northern states now mandate WHO-prequalified suppliers for consolidated framework agreements, locking volume commitments to compliant manufacturers. NAFDAC maintains divergent labeling requirements from regional neighbors, forcing multiple packaging SKUs. Lagos and Kano distribution hubs concentrate wholesale flow, though informal markets in both cities resist traceability system adoption.
Kenya
County health departments bypass central medical stores for direct manufacturer negotiation on high-volume chronic disease medications. The Pharmacy and Poisons Board enforces bioequivalence demonstration for public sector tenders. Nairobi anchors East African distribution while Mombasa port infrastructure shapes import lead times for Indian and Chinese API shipments.
Ghana
An emerging pharmaceutical zone offers tariff advantages for exports to ECOWAS markets under regional trade protocols. The national food and drugs authority tightens quality thresholds for market entry. Tema manufacturing facilities serve as a staging point for regional re-export to landlocked neighbors including Burkina Faso and Mali.
Egypt
Qualified clinical pharmacology units in Cairo and Alexandria face 8-12 month booking backlogs for bioequivalence studies, delaying product launches for regional suppliers. The national drug authority participates in African Medicines Regulatory Harmonization initiatives. The Suez Canal corridor positions Egyptian formulators for API import efficiency and re-export to Levant and North African markets.
Africa Generic Pharmaceutical Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across therapy-area and dosage-form segments. The market structure tiers around regulatory compliance capacity, with WHO-prequalified manufacturers commanding institutional contract positions. Three archetypes dominate: Indian-origin integrated formulators with API-to-finished-dose pipelines, regional African manufacturers with proximity advantages, and multinational generics divisions leveraging global portfolios. Competitive moves concentrate on direct tender participation bypassing wholesale layers and backward integration into API sourcing to reduce import dependency exposure.
Among Indian-origin integrated formulators, Teva Pharmaceutical Industries Ltd., Lupin, and Cipla South Africa exemplify the archetype of manufacturers leveraging WHO-prequalified portfolios to anchor institutional contracts across multiple African markets. These companies occupy positions where regulatory affairs capacity and bioequivalence study investments translate into framework agreement eligibility. Their geographic naming conventions—South Africa-domiciled operations, Indian parentage—signal regional manufacturing scale combined with global portfolio breadth.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Ltd. |
| Lupin |
| Aspen Holdings |
| Hikma Pharmaceuticals |
| Aurobindo Pharma |
| Cipla South Africa |
| Sun Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories Ltd. |
| Adcock Ingram Holdings Ltd |
| Others |
Value Network & Pricing Analysis
Qualified bioequivalence study capacity concentrated in South Africa and Egypt compresses labor-cost differentials between premium WHO-prequalified tiers and standard domestic-manufactured products, widening pricing spreads as regulatory compliance investments compound.
Pricing Analysis
Cost-down pressure on hospital tender tiers accelerates because Nigerian state drug revolving funds now mandate WHO-prequalified suppliers, forcing non-compliant manufacturers into steeper discounts. Three-tier pricing structure across WHO-prequalified, national bioequivalence-certified, and unverified economy levels separates procurement eligibility. Price differentiation hinges on SAHPRA inspection status and cold-chain validation capability. County health departments in Kenya exhibit highest price sensitivity; private hospital chains in South Africa show lowest.
Supply Chain Analysis
WHO prequalification status gates supplier participation in Nigeria's northern state frameworks and East African hospital procurement, concentrating qualified manufacturing in South Africa, Egypt, and India. Active pharmaceutical ingredient sourcing draws from Chinese and Indian chemical manufacturers, with Egyptian formulators leveraging Suez Canal corridor efficiency. Single-source vulnerability concentrates in API import channels exposed to currency volatility. Distribution runs through wholesale intermediaries in Lagos and Nairobi, with direct manufacturer contracting gaining share in Kenyan county health departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from tightening bioequivalence requirements and framework agreement consolidation will displace sub-scale manufacturers lacking WHO prequalification or SAHPRA alignment.
For Market Incumbents: Lock in multi-year volume commitments with Nigerian state drug revolving funds and Kenyan county health departments before tender windows narrow. Backward integration into API sourcing reduces Indian and Chinese supplier dependency exposure. Anchor positioning through continuous manufacturing investments that compress lead times for unpredictable tender cycles. For New Entrants and Emerging Players: Capture Ghana's emerging pharmaceutical zone tariff advantages for ECOWAS re-export to landlocked neighbors. West African manufacturing white space offers lowest regulatory compliance barriers among high-volume markets. Lead with fixed-dose combination antiretroviral or cardiovascular portfolios where adherence protocols command procurement premiums. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale African manufacturers possessing SAHPRA alignment and idle bioequivalence study capacity given Egyptian clinical pharmacology unit backlogs. Five-to-ten year viability favors assets with WHO-prequalified portfolios and established state tender relationships. Watch Nigerian NAFDAC labeling harmonization progress as inflection signal for packaging SKU consolidation savings.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Nigerian state drug revolving fund and East African hospital framework agreement eligibility. |
| Continuous Manufacturing Scale-Up | Enables just-in-time production matching fragmented African tender demand cycles. |
| API Backward Integration | Reduces currency volatility exposure from Indian and Chinese chemical supplier concentration. |
| Direct Hospital Contracting | Bypasses wholesale markups in Kenyan county health department and South African public procurement. |
| Fixed-Dose Combination Expansion | Captures adherence-protocol premiums in HIV triple-therapy and cardiovascular co-formulation segments. |
Research Methodology
Independent corroboration across regulatory affairs directors, hospital procurement managers, and pharmaceutical distribution channel heads underwrites the qualitative findings. Primary interviews with formulary committee members, bioequivalence study principal investigators, and state drug revolving fund administrators combined with secondary validation against SAHPRA submission databases, NAFDAC registration records, and WHO prequalification listings. Bottom-up tender volume aggregation and top-down therapy-area demand modeling triangulate market sizing.
Rate-of-change decomposition across dosage form, therapy area, and distribution channel dimensions structures the analytical framework over the projection horizon. CAGRs derive from segment-level volume trajectories weighted by procurement price points observed in public tender awards. Modeled inputs include chronic disease protocol expansion rates, bioequivalence study completion timelines, and cold-chain infrastructure deployment in rural clinic networks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to African Medicines Regulatory Harmonization adoption pace and API import tariff shifts. Forecasts reflect assumptions around WHO prequalification queue processing and state drug revolving fund consolidation timelines. A model refresh is warranted upon material change in SAHPRA electronic submission mandate enforcement or Nigerian federal procurement decentralization policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Pharma 4.0 Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Global Calcitonin Salmon Market
Pharmaceuticals
Farm Animal Drugs Market
Pharmaceuticals
Non-Sterile Liquids/Suspensions Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Global Central Nervous System (CNS) Stimulant Drugs Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Aripiprazole Market
Pharmaceuticals
Bendamustin Market
Pharmaceuticals
Iron Deficiency Injectables Market