
 Opioid Induced Constipation Drug Market | 2026-2036
Opioid Induced Constipation Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Opioid Induced Constipation Drug Market Intelligence
The lengthy Investigational New Drug (IND) application and multi-phase clinical trial process is unwinding the traditional R&D timeline for new chemical entities targeting this condition. Takeda Pharmaceutical Company Limited leverages its established gastrointestinal portfolio to maintain a strong market presence in key markets. Salix Pharmaceuticals specializes exclusively in gastroenterology, competing through a highly focused product pipeline. In contrast, Bausch Health Companies Inc. operates with a diversified strategy across several relevant therapeutic areas.
Opioid-induced constipation drugs are pharmacological agents specifically designed to counteract the constipating effects of opioids on the gastrointestinal tract without compromising their central analgesic properties. These therapies often utilize a mechanism that targets peripheral mu-opioid receptors, as seen in peripherally acting mu-opioid receptor antagonists (PAMORAs), to block opioid effects locally in the gut. PAMORAs represent the most clinically specific and fastest-growing drug type. The oral route of administration dominates the market due to superior patient convenience, particularly for chronic non-cancer pain and palliative care therapy areas.
The US Food and Drug Administration's (FDA) stringent requirements for demonstrating safety and efficacy set a high barrier for market entry. In parallel, the European Medicines Agency (EMA) in Europe and Japan's Pharmaceuticals and Medical Devices Agency (PMDA) enforce rigorous post-approval monitoring, shaping lifecycle management strategies for approved drugs. Future investment decisions will hinge on navigating these complex international regulatory pathways while differentiating products for specific patient populations in postoperative care and oncology.
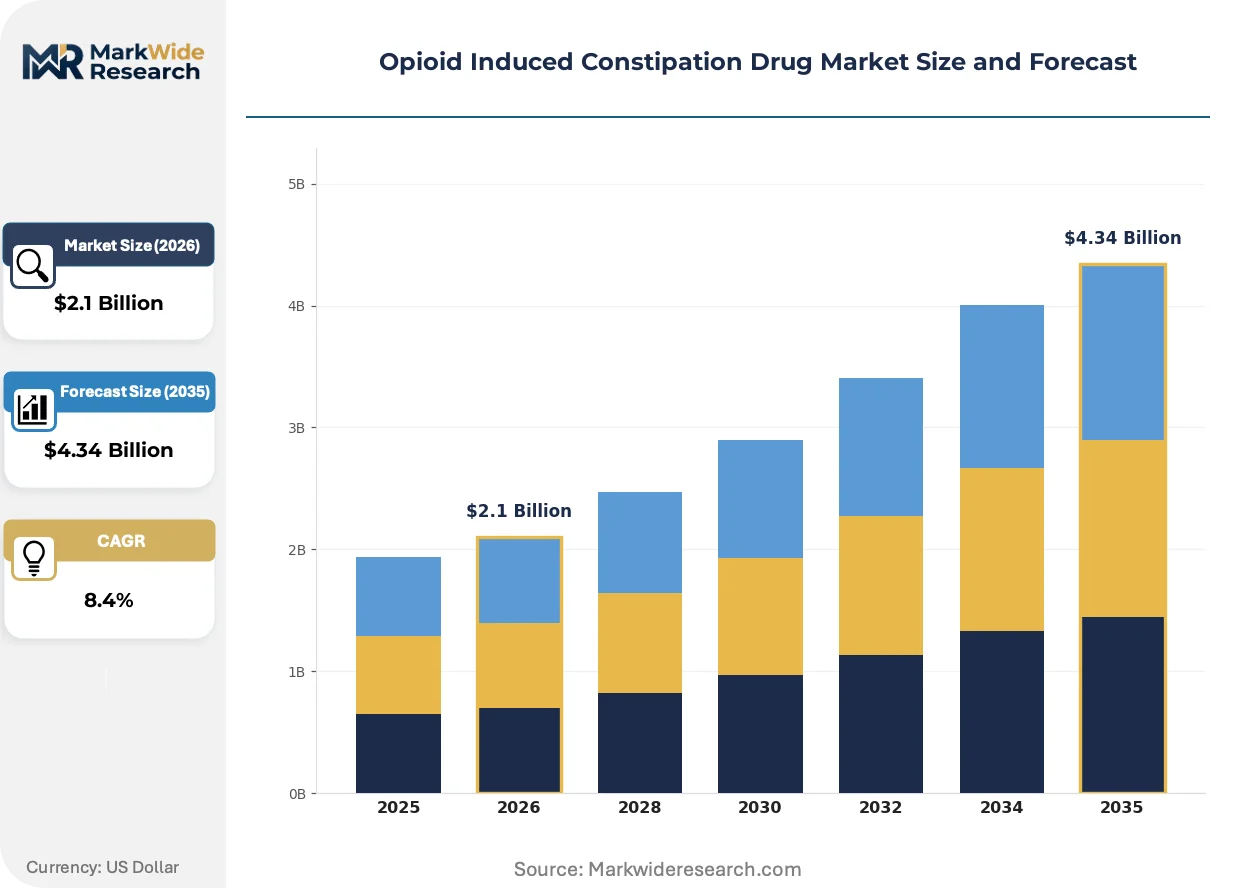
Market Dynamics
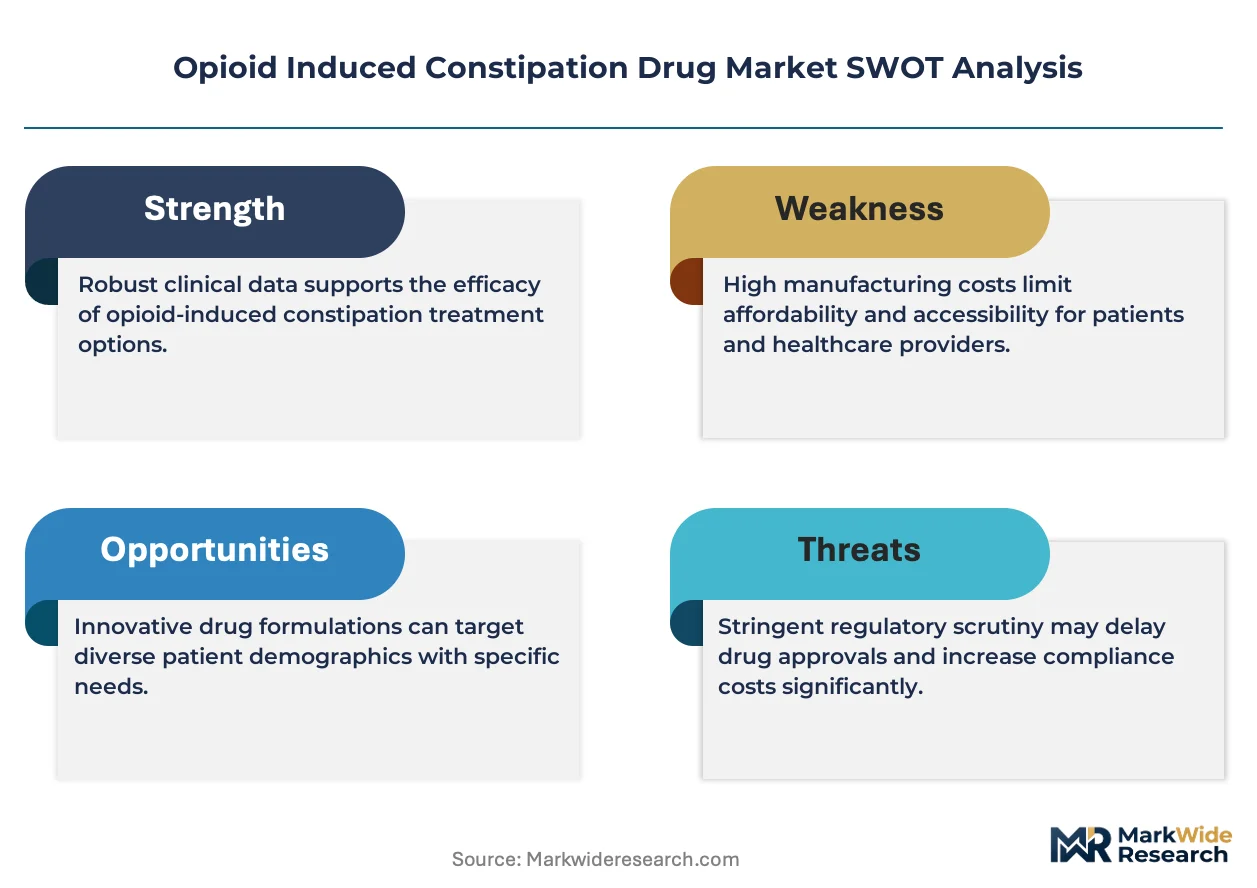
The central dynamic shaping the market is the heightened regulatory scrutiny over drug safety and efficacy. Mandates from bodies like the US FDA and Europe's EMA for extensive post-market surveillance are lengthening development timelines and increasing R&D costs for new therapies.
Growth Catalysts
- Palliative Care Integration:An increasing focus within healthcare systems on improving quality of life for patients undergoing long-term opioid therapy for chronic pain is a primary catalyst, driving demand for effective management of adverse effects.
- Aging Demographics:Advanced economies with significant aging populations, such as Germany and Japan, exhibit higher prevalence of chronic conditions requiring opioid analgesics, which in turn fuels the need for corresponding constipation treatments.
- PAMORA Specificity:The clinical advantages of peripherally acting mu-opioid receptor antagonists (PAMORAs), which selectively target gut receptors without affecting central pain relief, are accelerating their adoption over less specific laxatives.
Market Restraints
- Extended R&D Timelines:The multi-phase clinical trial process, complicated by stringent Investigational New Drug (IND) application requirements from regulators like the FDA, creates a significant time and cost barrier to market entry for new chemical entities.
- Generic Substitution Pressure:The availability of lower-cost, over-the-counter laxatives, while less clinically specific for OIC, presents a substitution threat, particularly in cases where reimbursement for branded specialty drugs is limited.
- Reimbursement Hurdles:Securing favorable formulary placement and navigating complex reimbursement negotiations with payers can restrict patient access to newer, more expensive pharmacological agents, thus constraining market penetration.
Strategic Opportunities
- Postoperative Care Expansion:There is a significant opportunity to develop and market therapies specifically for short-term use in postoperative settings, a patient population distinct from the chronic pain segment.
- Pediatric Formulation Development:Addressing the unmet need for safe and effective OIC treatments in pediatric patients receiving opioid therapy represents a key area for product line extension and market differentiation.
- Targeting Emerging Markets:Expanding into large healthcare markets like Brazil, where regulatory frameworks under ANVISA are maturing, offers new growth avenues beyond the saturated markets of North America and Europe.
Industry Challenges
- Post-Approval Monitoring Burden:Complying with rigorous post-approval monitoring and reporting requirements, such as those enforced by Japan's PMDA, demands substantial and ongoing investment in pharmacovigilance systems.
- Intellectual Property Defense:Protecting patent exclusivity for novel drug formulations and mechanisms of action against challenges from generic manufacturers is a persistent and resource-intensive operational challenge.
- Complex Clinical Trial Recruitment:Identifying, recruiting, and retaining suitable patients for long-term clinical studies, especially within the diverse chronic non-cancer pain population, complicates and delays the drug approval process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opioid Induced Constipation Drug Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Peripherally Acting Mu-Opioid Receptor Antagonists, Stool Softeners, Lubricants, Osmotic Laxatives, Others Therapy Area: Oncology Pain Relief, Postoperative Care, Chronic Non-Cancer Pain, Palliative Care End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Healthcare Providers, Long-Term Care Facilities Route of Administration: Oral, Rectal, Injectable, Sublingual, Transdermal |
| Companies Covered | Pfizer Inc, AstraZeneca plc, Merck & Co Inc, Shionogi & Co Ltd, Salix Pharmaceuticals, Takeda Pharmaceutical Company Limited, Ironwood Pharmaceuticals Inc, Bausch Health Companies Inc, RedHill Biopharma Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opioid Induced Constipation Drug Market Strategic Shifts & Innovations
Movement toward greater therapeutic specificity is the defining trend. This evolution is driven by a convergence of advanced pharmacological mechanisms and regulatory demands for improved safety profiles, pushing development away from generalized treatments toward targeted interventions.
Development of peripherally acting mu-opioid receptor antagonists (PAMORAs) provides a mechanism to counteract constipation locally in the gut without compromising central analgesia. Gastroenterology and palliative care specialists are rapidly adopting these agents for patients on long-term opioid regimens. The rise of PAMORAs is bifurcating the treatment landscape, creating a clear divide between these targeted prescription drugs and traditional, non-specific laxatives.
Regulatory agencies are implementing stricter post-market surveillance protocols. For instance, the US FDA's mandates for long-term safety and efficacy data for new drug approvals significantly influence clinical development strategies. This regulatory pressure most acutely affects companies developing new chemical entities, forcing them to demonstrate substantial clinical advantages to justify market entry and secure reimbursement.
A notable shift in patient and provider preference is elevating the importance of administration route. The historical tolerance for injectable or complex dosing schedules is giving way to a strong demand for the convenience of oral formulations. This preference is particularly strong in the palliative care and chronic non-cancer pain segments, where ease of use in a home-care setting is a critical factor for long-term adherence.
Opioid Induced Constipation Drug Market Segmentation
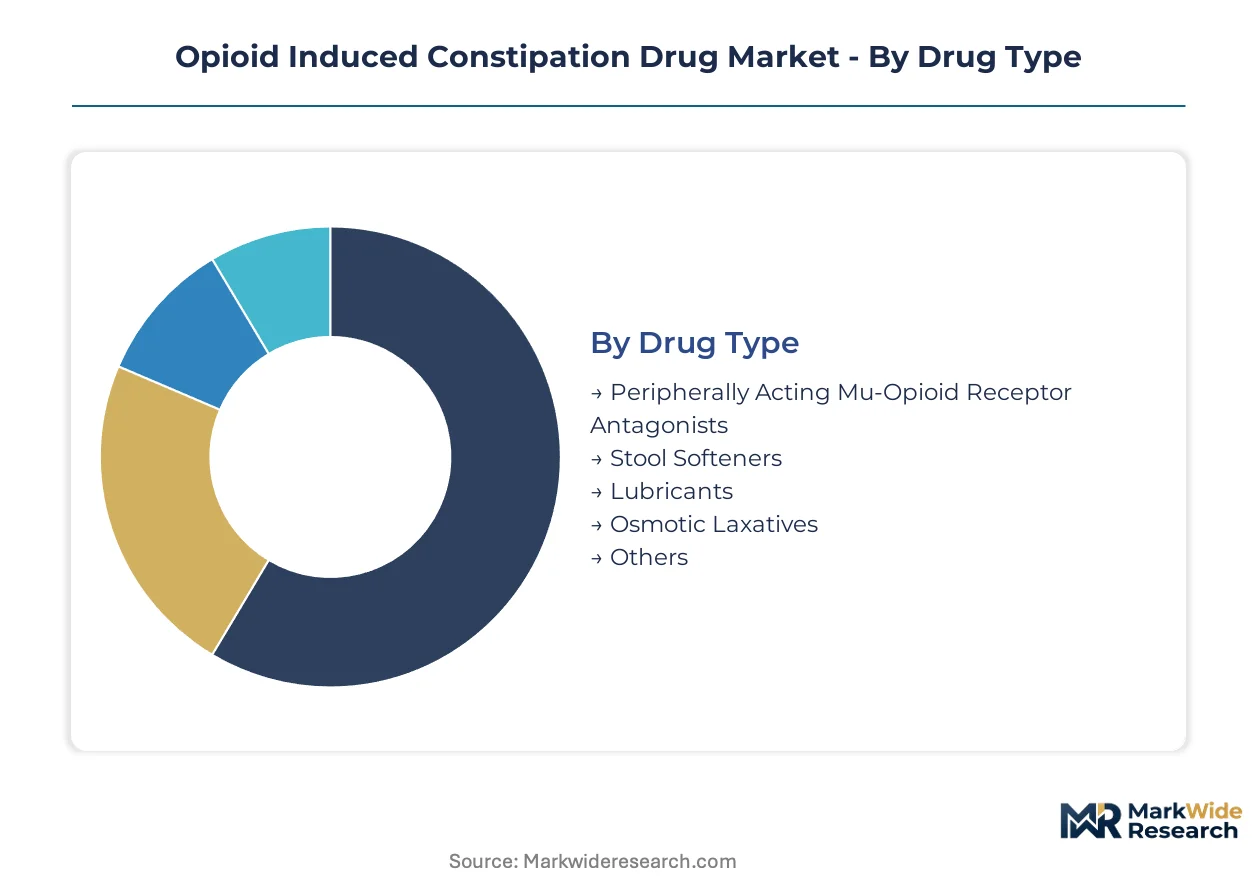
Understanding the Opioid Induced Constipation Drug market's segmentation reveals critical insights into patient needs and treatment preferences. The distinct categories highlight where pharmaceutical innovation and healthcare delivery are converging to address the complex challenges of OIC. This granular view helps stakeholders identify specific growth pockets and unmet clinical requirements across diverse patient populations.
Drug Type:
Margin pools within the drug type segment concentrate heavily on novel pharmacological mechanisms offering superior specificity and efficacy. Peripherally acting mu-opioid receptor antagonists, for instance, command premium pricing due to their targeted action and improved patient outcomes.
- Peripherally Acting Mu-Opioid Receptor Antagonists (PAMORAs):These agents selectively block opioid binding to mu-receptors in the gastrointestinal tract, counteracting constipation without affecting central pain relief. Demand concentrates in palliative care and chronic non-cancer pain, driven by their clinical specificity and reduced systemic side effects.
- Osmotic Laxatives:These non-specific agents draw water into the colon, softening stool and promoting bowel movements through osmotic action. Their widespread availability and lower cost make them a primary choice for initial OIC management, particularly in settings with budget constraints.
- Stool Softeners:These drugs increase water and fat penetration into the stool, making it softer and easier to pass. They are commonly used as an adjunctive therapy or for milder cases of opioid-induced constipation.
- Lubricants:Lubricant laxatives coat the stool surface, preventing water reabsorption and easing its passage through the bowel. These are typically considered for short-term relief in patients unable to use other methods.
- Others:This category encompasses various less common or experimental agents, including prokinetic drugs and novel formulations. Innovation in this segment often targets specific patient subgroups or refractory OIC cases.
Stool Softeners hold installed capacity. Peripherally Acting Mu-Opioid Receptor Antagonists are rotating up the share rankings.
Therapy Area:
The market's application landscape is shaped by the specific clinical context in which opioids are administered, influencing treatment duration and patient profiles. Each therapy area presents distinct challenges and opportunities for OIC drug development and deployment.
- Palliative Care:This area focuses on improving the quality of life for patients with serious illnesses, where long-term opioid use is common for pain management. Demand for OIC drugs in palliative care is high, driven by the need to manage adverse effects and enhance patient comfort.
- Chronic Non-Cancer Pain:Patients with chronic non-cancer pain often require prolonged opioid therapy, making them highly susceptible to OIC. The convenience of oral formulations is a critical factor for adherence in this large and diverse patient population.
- Oncology Pain Relief:Opioid-induced constipation is a frequent complication in cancer patients receiving analgesics, impacting their overall well-being. Effective OIC management supports better pain control and reduces treatment discontinuation rates.
- Postoperative Care:Short-term opioid use following surgical procedures frequently leads to acute constipation, necessitating rapid-acting and effective OIC interventions. This segment represents a distinct opportunity for targeted drug development.
Palliative Care exhibits significant expansion, driven by an increasing focus on patient comfort. Postoperative Care is gaining share fastest as targeted solutions emerge.
End User:
Customer type significantly influences the procurement and administration of OIC drugs, with institutional settings often requiring bulk purchasing and home care prioritizing ease of use. Each end-user segment has unique operational considerations for product selection.
- Hospitals:These facilities serve a broad patient base, including acute care, surgical recovery, and initial chronic pain management. Hospitals require a diverse range of OIC drug formulations to address varying patient needs and clinical scenarios.
- Home Healthcare Providers:As patient care increasingly shifts to home settings, the demand for convenient, easy-to-administer OIC treatments rises. Home healthcare providers prioritize oral formulations that can be managed effectively by patients or caregivers.
- Ambulatory Surgical Centers:These centers focus on outpatient procedures where short-term opioid use is common. They require efficient OIC solutions for quick patient recovery and discharge.
- Specialty Clinics:Clinics specializing in pain management or gastroenterology often prescribe OIC drugs for chronic conditions. They seek advanced therapies that offer superior efficacy and patient-specific dosing.
- Long-Term Care Facilities:Residents in these facilities often receive long-term opioid therapy, making OIC a prevalent issue. These settings require reliable and cost-effective OIC management protocols for their patient populations.
Hospitals demonstrate broad adoption of established OIC therapies. Home Healthcare Providers are rapidly increasing their market penetration with user-friendly options.
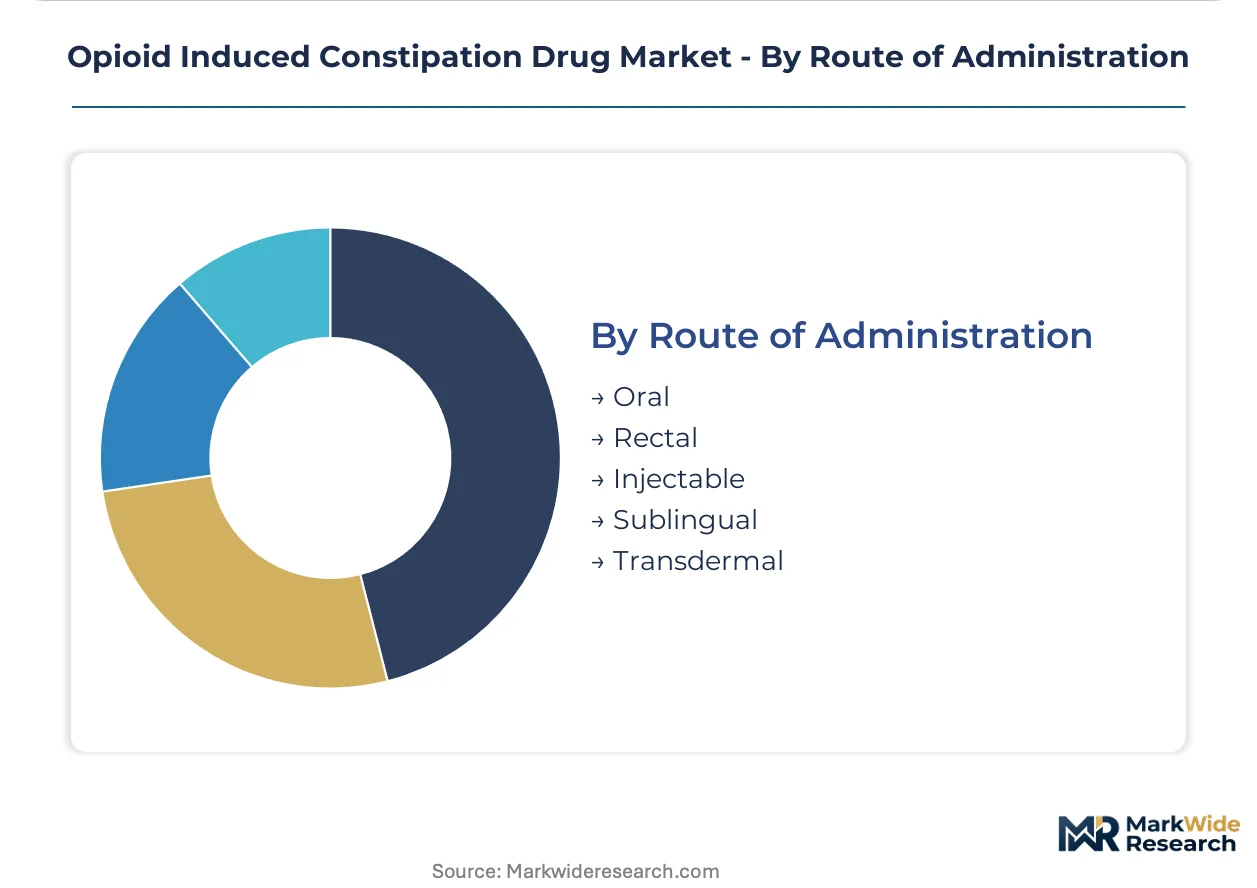
Route of Administration:
Volume distribution across administration routes reflects patient preference, clinical urgency, and the chronicity of opioid use. Oral formulations dominate due to their convenience, while other routes serve specific clinical niches or acute needs.
- Oral:Oral administration is the most preferred route due to its superior patient convenience and ease of long-term adherence, particularly for chronic non-cancer pain and palliative care. This route dominates the market.
- Injectable:Injectable OIC drugs are typically reserved for acute settings, such as postoperative care, or for patients unable to take oral medications. They offer rapid onset of action and precise dosing.
- Rectal:Rectal administration provides a local effect in the gastrointestinal tract and is sometimes used when oral intake is difficult. This route offers an alternative for specific patient situations.
- Sublingual:Sublingual formulations allow for rapid absorption through the oral mucosa, bypassing first-pass metabolism. This route is considered for patients requiring quick relief or those with swallowing difficulties.
- Transdermal:Transdermal patches offer continuous drug delivery, potentially improving adherence and reducing dosing frequency. This route represents an innovative approach for sustained OIC management.
The Oral route represents a mature segment with high patient acceptance. Innovation in Transdermal delivery pathways is evolving rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration drives regional market dynamics, with advanced healthcare systems and aging populations creating significant demand for opioid-induced constipation drugs. These demographic and infrastructural factors concentrate market activity in developed economies. Stricter regulatory environments also shape product availability and market penetration across these key regions.
United States
High prevalence of chronic non-cancer pain and extensive opioid prescribing patterns fuel demand for OIC therapies. The US FDA's stringent requirements for new drug approvals significantly influence clinical development pipelines. Major pharmaceutical clusters in states like New Jersey and Massachusetts actively pursue novel OIC treatments.
Germany
An aging demographic and a robust palliative care system contribute to a substantial patient pool requiring OIC management. The European Medicines Agency (EMA) enforces rigorous post-market surveillance for approved drugs, shaping lifecycle management strategies. Biotech hubs in Munich and Berlin are contributing to innovative pharmacological solutions.
Japan
Significant aging populations and a cultural emphasis on patient comfort drive the need for effective OIC treatments, particularly in palliative care. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) enforces rigorous post-approval monitoring, impacting pharmacovigilance investments. Pharmaceutical research in Tokyo and Osaka focuses on patient-centric formulations.
United Kingdom
Increasing focus on quality of life in palliative care and chronic pain management boosts demand for OIC drugs. The Medicines and Healthcare products Regulatory Agency (MHRA) ensures safety and efficacy standards for market entry and post-market activity. Life sciences clusters in London and Cambridge are exploring new therapeutic avenues.
Canada
A growing aging population and comprehensive healthcare coverage contribute to steady demand for OIC solutions. Health Canada's regulatory framework guides drug approvals and market access for pharmaceutical products. Research institutions in Toronto and Montreal are involved in clinical trials for OIC therapies.
Opioid Induced Constipation Drug Market Key Industry Players
Player mix skews toward established pharmaceutical companies with diversified portfolios and specialized gastroenterology firms. The market structure exhibits a tiered consolidation, with a few large players dominating while smaller biotechs focus on niche innovations. Portfolio diversification and strategic R&D investments represent dominant competitive moves among these entities. Companies also leverage their existing market presence to maintain strong positions in key therapeutic areas.
Specialists in gastroenterology, such as Salix Pharmaceuticals, exemplify a highly focused product pipeline strategy. Takeda Pharmaceutical Company Limited leverages its established gastrointestinal portfolio to maintain a strong market presence. Bausch Health Companies Inc. occupies a position as a diversified player, operating across several relevant therapeutic areas. These companies represent distinct approaches to market penetration and product development within the OIC drug landscape.
| Leading Market Players |
|---|
| Pfizer Inc |
| AstraZeneca plc |
| Merck & Co Inc |
| Shionogi & Co Ltd |
| Salix Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Ironwood Pharmaceuticals Inc |
| Bausch Health Companies Inc |
| RedHill Biopharma Ltd |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for active pharmaceutical ingredients (APIs) lock in both supply access and price visibility for OIC drug manufacturers. This structure mitigates volatility in critical raw material costs, particularly for novel PAMORA compounds.
Pricing Analysis
Value-based pricing, often indexed to clinical outcomes and patient quality of life improvements, governs premium OIC drugs like PAMORAs. Price differentiation stems from the FDA/EMA certification tier, the brand premium associated with novel mechanisms, and the level of patient support services offered. Pricing softness affects osmotic laxatives due to generic substitution pressure and payer pushback on less specific treatments. Hospitals and large healthcare systems demonstrate higher price sensitivity for established therapies, while palliative care patients prioritize efficacy regardless of cost.
Supply Chain Analysis
Strategic stockpiling of critical active pharmaceutical ingredients (APIs) characterizes the OIC drug supply chain, ensuring continuity amidst geopolitical uncertainties. Geographic supply concentration for key APIs centers in India and China, with advanced formulation and packaging largely occurring in the United States and Europe. The market relies on specialized chemical precursors and sterile packaging components. Single-source vulnerability for novel PAMORA APIs presents a structural risk, while distribution runs primarily through pharmaceutical wholesalers to hospitals and retail pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Opioid Induced Constipation Drug market is experiencing a significant shift in buyer power, driven by the increasing formulary consolidation among large hospital networks and pharmacy benefit managers. This dynamic places greater emphasis on value demonstration and cost-effectiveness for OIC therapies.
For Market Incumbents:Secure patent exclusivity for next-generation PAMORA formulations through sustained R&D investment to counter generic substitution threats. Incumbents should deepen vertical integration into specialized API manufacturing to control input costs and ensure supply stability. Invest in real-world evidence generation to demonstrate superior patient outcomes and justify premium pricing against increasing payer scrutiny. Expand patient support programs to enhance adherence and differentiate products in a competitive landscape.
For New Entrants and Emerging Players:Lead with novel mechanisms targeting refractory OIC cases or specific patient populations like pediatric or postoperative patients, where unmet needs remain high. Focus on developing oral formulations for these segments, leveraging patient convenience as a primary differentiator. The postoperative care segment represents a penetrable target due to its acute, short-term need for rapid-acting solutions. Employ direct-to-specialist marketing strategies to gastroenterologists and pain management clinics.
For Investors and Strategic Acquirers:Capital is best deployed toward innovative biotechs specializing in peripherally acting mu-opioid receptor antagonists (PAMORAs) with strong intellectual property and late-stage clinical pipelines. These investments offer long-term viability over the next decade as therapeutic specificity gains further traction. Seek out companies with proven regulatory expertise, particularly for navigating FDA and EMA pathways. The signal to watch is the successful completion of Phase III trials for new chemical entities with superior safety profiles.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerating Phase III trials for novel PAMORAs strengthens market position against generic competition. |
| Regulatory Approval Pathway | Streamlining FDA and EMA submissions ensures faster market access for differentiated OIC therapies. |
| Pipeline Diversification | Investing in pediatric OIC formulations addresses an unmet need and expands the target patient demographic. |
| Manufacturing Scale-Up | Securing API production capacity mitigates supply chain risks and supports global market demand. |
| Strategic Partnership | Collaborating with palliative care providers enhances market penetration and patient access for new drugs. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data gathered insights from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers across key geographies. Secondary sources included FDA filings, EMA submissions, ClinicalTrials.gov, and company annual reports, triangulated for accuracy. This approach combined bottom-up market sizing with top-down validation.
The forecasting window spans a nine-year horizon, modeling market dynamics across the analysis window. Segmentation dimensions included drug type, therapy area, end user, and route of administration, alongside regional regulatory clusters. Compound annual growth rates were derived from historical data trends and projected future demand influenced by opioid prescription rates. Aging population demographics also served as a critical input for demand projections.
The analysis sits within stated boundaries; outcomes outside new opioid prescribing guidelines or unexpected regulatory shifts would require recalibration. Forecasts reflect current market assumptions and known clinical development pipelines. Practitioners should keep alternative scenarios live as pharmaceutical innovation and healthcare policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Daratumumab Market
Pharmaceuticals
Russia Diabetes Drugs Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
United States Over the Counter (OTC) Drugs Market
Pharmaceuticals
Hard Gelatin Capsules Market
Pharmaceuticals
Sterile Dosage Form Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis (NASH) Therapeutics and Diagnostics Market
Pharmaceuticals
Global Fluorouracil (5FU) Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
PD-1/PD-L1 Inhibitor Market