
 Paediatric Neuropsychiatric Disorders Treatment Market | 2026-2036
Paediatric Neuropsychiatric Disorders Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Paediatric Neuropsychiatric Disorders Treatment Market Analytics
ISO 14155 for clinical investigation of medicinal products is rotating toward paediatric neuropsychiatric protocols as sponsors face heightened scrutiny on juvenile trial design. Pfizer Inc leverages its established vaccine and paediatric medicine infrastructure to sustain competitive positioning across developmental disorder therapeutics. Eli Lilly and Company anchors its presence through deep specialisation in attention-deficit and mood disorder compounds. Novartis AG differentiates via geographic breadth and established relationships with European paediatric research networks.
Paediatric neuropsychiatric disorders treatment encompasses pharmacological and non-pharmacological interventions targeting behavioural, cognitive, and emotional disturbances in children and adolescents, with formulations requiring weight-based dosing, palatability engineering, and age-appropriate delivery mechanisms to ensure therapeutic adherence. The primary purpose centres on symptom management, functional improvement, and developmental trajectory optimisation across clinical and educational settings. Stimulants retain dominant share within product type segmentation due to entrenched ADHD prescribing patterns and decades of paediatric safety data. Intranasal delivery mode exhibits the fastest structural expansion as developers pursue rapid-onset alternatives to oral tablets for acute agitation and breakthrough symptoms. Antipsychotics concentrate margin pools where long-acting injectable formulations command premium positioning in residential treatment settings.
FDA paediatric study requirements and EMA's Paediatric Investigation Plans jointly shape trial investment timelines and label extension strategies for neuropsychiatric drug developers. The EU AI Act introduces new compliance dimensions for algorithmic diagnostic tools used in childhood behavioural assessment, constraining deployment velocity for digital phenotyping platforms. Stakeholders must monitor evolving reimbursement thresholds for combination pharmacotherapy and digital therapeutic bundles as payers recalibrate value frameworks for chronic paediatric conditions.
Market Dynamics
ISO 14155 protocols for paediatric clinical investigations are tightening trial design requirements, forcing sponsors to restructure juvenile neuropsychiatric study frameworks and escalating compliance costs across development pipelines.
Growth Catalysts
- Paediatric Investigation Plans:EMA mandates under Regulation (EC) No 1901/2006 create enforceable development timelines that expand addressable patient populations for approved compounds.
- Intranasal delivery engineering:Rapid-onset formulations for acute agitation episodes address unmet needs in emergency paediatric psychiatric settings, opening new therapeutic modalities.
- United States reimbursement density:Commercial and Medicaid frameworks for childhood behavioural health services sustain specialist infrastructure investment and patient access expansion.
Market Restraints
- Long-acting injectable concentration:Manufacturing complexity and cold-chain requirements for antipsychotic depot formulations limit supplier base to established pharmaceutical infrastructure holders.
- Paediatric safety data scarcity:Ethical constraints on juvenile trial enrollment perpetuate off-label prescribing liability exposure and label expansion delays.
- Palatability engineering costs:Taste-masking and age-appropriate delivery mechanism development adds formulation expense without commensurate pricing power in generic-dominated oral segments.
Strategic Opportunities
- Digital therapeutic bundling:FDA breakthrough device designation pathways enable combined pharmacotherapy and algorithmic behavioural intervention reimbursement pilots with commercial payers.
- Residential treatment channel penetration:Long-acting injectable formulations command premium positioning in institutional settings where medication adherence monitoring is constrained.
- EU AI Act compliance services:Algorithmic diagnostic tools for childhood behavioural phenotyping require validation frameworks, creating advisory and certification service revenue streams.
Industry Challenges
- Juvenile trial recruitment:Parental consent complexity and site capacity constraints compress enrollment velocity, extending development timelines and inflating study costs.
- Formulation stability:Weight-based dosing requirements across developmental age spans necessitate multiple strength SKUs, complicating manufacturing scale economics and inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paediatric Neuropsychiatric Disorders Treatment Market |
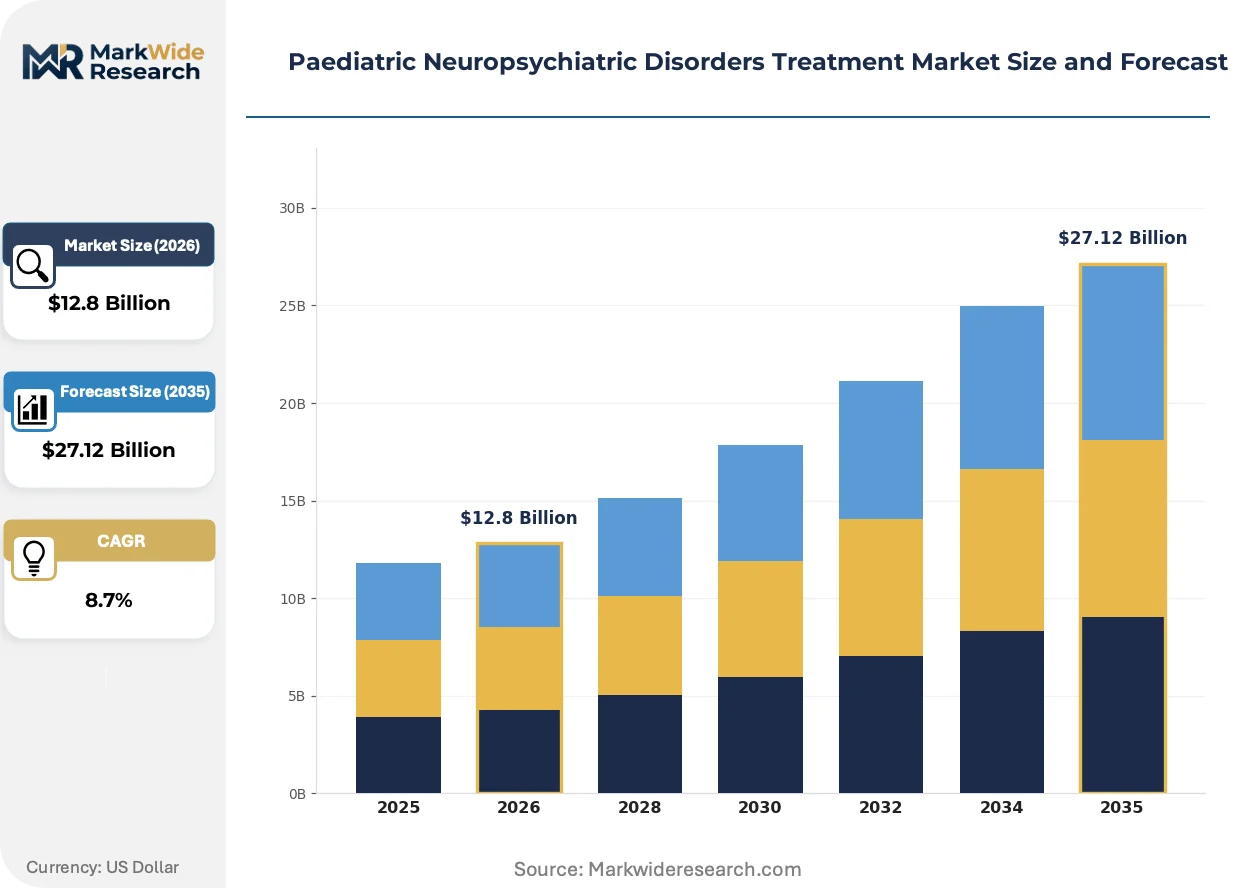
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antidepressants, Stimulants, Antipsychotics, Mood Stabilizers Therapy Area: ADHD, Autism Spectrum Disorder, Anxiety Disorders, Depression Delivery Mode: Oral, Injectable, Transdermal, Intranasal End User: Pediatric Hospitals, Outpatient Clinics, Residential Treatment Centers, Private Practices |
| Companies Covered | Johnson & Johnson, Pfizer Inc, Novartis AG, AbbVie Inc, Eli Lilly and Company, AstraZeneca PLC, GlaxoSmithKline plc, Bristol-Myers Squibb Company, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paediatric Neuropsychiatric Disorders Treatment Market Evolving Landscape
Intranasal delivery platforms and algorithmic diagnostic tools are restructuring competitive positioning across acute intervention and assessment segments, while regulatory frameworks for digital therapeutics mature.
Intranasal ketamine and benzodiazepine formulations are decomposing the oral tablet monopoly for acute agitation management in paediatric emergency departments. Hospital pharmacy committees in the United States are accelerating formulary reviews for rapid-onset alternatives. This delivery mode is compressing time-to-sedation benchmarks and displacing intramuscular injection as first-line rescue therapy.
The EU AI Act's risk classification system for biometric and emotion-recognition algorithms imposes conformity assessment obligations on digital phenotyping platforms used in ADHD and autism spectrum diagnosis. Developers must establish CE marking pathways and post-market surveillance systems for machine-learning diagnostic aids. European paediatric research networks are prioritising validation studies for regulatory submission packages.
Commercial payers in the United States are unbundling behavioural health service reimbursement from acute medical episodes, creating standalone reimbursement codes for chronic paediatric neuropsychiatric management. Provider organisations are reorganising care delivery around episode-based payment structures. This shift is most visible in Medicaid-managed care contracts where per-member-per-month capitation rates are being renegotiated.
Paediatric Neuropsychiatric Disorders Treatment Market Segmentation
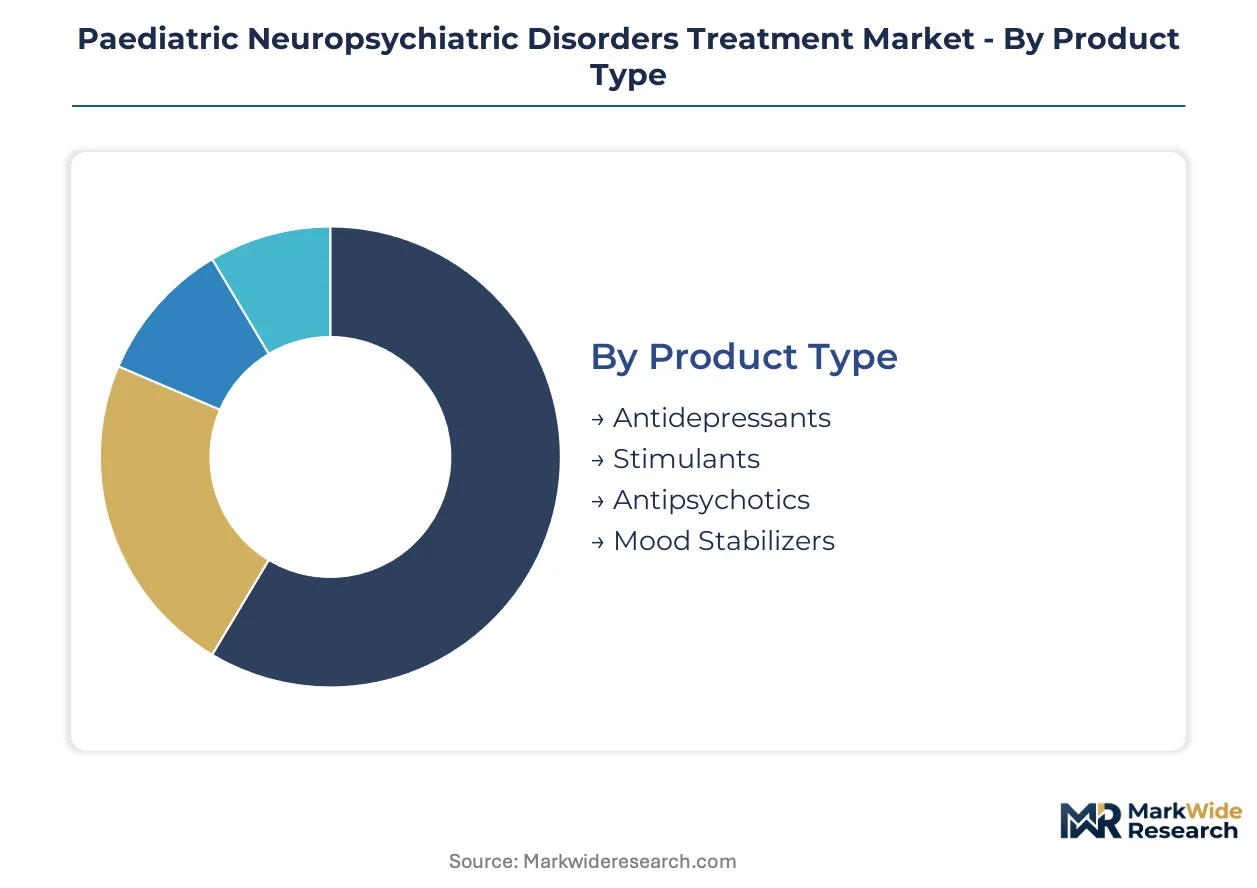
Paediatric neuropsychiatric treatment segmentation reflects divergent regulatory pathways, reimbursement structures, and formulation requirements across therapeutic modalities. FDA paediatric study mandates and EMA investigation plans create distinct compliance burdens that reshape competitive positioning within each category.
Product Type:
FDA's Best Pharmaceuticals for Children Act and EMA paediatric investigation requirements impose differentiated trial obligations across pharmacological classes, with stimulants benefiting from decades of accumulated juvenile safety data while newer antipsychotic formulations face extended development timelines.
- Stimulants:Methylphenidate and amphetamine derivatives constitute the pharmacological backbone of ADHD management, with established weight-based dosing protocols and extensive paediatric safety databases satisfying FDA label requirements. United States Medicaid and commercial payers maintain broad formulary coverage for immediate-release and extended-release formulations, though generic substitution pressures compress margin pools for originator products.
- Antipsychotics:Second-generation compounds including aripiprazole and risperidone command premium positioning for irritability associated with autism spectrum disorder and acute agitation episodes, with long-acting injectable variants capturing institutional procurement contracts. European hospital pharmacy committees increasingly require head-to-head juvenile efficacy data for formulary inclusion, extending EMA submission preparation cycles.
- Antidepressants:Selective serotonin reuptake inhibitors face heightened FDA black box warnings for suicidality in adolescents, constraining prescribing patterns and necessitating risk evaluation and mitigation strategies.
- Mood Stabilizers:Lithium carbonate and anticonvulsant derivatives serve bipolar spectrum presentations in adolescent populations, with narrow therapeutic indices demanding frequent serum monitoring protocols.
Established volume favors stimulants; emerging adoption favors antipsychotics.
Therapy Area:
Diagnostic prevalence variations and reimbursement code density concentrate commercial investment toward conditions with measurable functional endpoints and established care pathways.
- ADHD:The most extensively validated paediatric neuropsychiatric indication drives sustained pharmacological innovation, with diagnostic instruments including the Vanderbilt Assessment Scale and Conners Rating Scales enabling standardized treatment response measurement. United States school-based intervention mandates and Section 504 accommodation requirements sustain demand for symptom management pharmacotherapy across educational settings.
- Autism Spectrum Disorder:Rising diagnostic incidence and expanded service eligibility under the Individuals with Disabilities Education Act propel investment in both core symptom and co-occurring condition treatments, with irritability and aggression representing addressable pharmacological targets. European research networks prioritize biomarker stratification to identify treatment-responsive subpopulations.
- Anxiety Disorders:Selective serotonin reuptake inhibitors and cognitive-behavioural therapy combinations dominate evidence-based protocols, though paediatric-specific trial data remain sparser than for ADHD.
- Depression:Adolescent major depressive disorder treatment faces regulatory scrutiny following FDA meta-analyses of antidepressant suicidality signals, compressing development investment relative to adult indications.
Clinical trial infrastructure concentrates on ADHD; unmet need intensity concentrates on autism spectrum disorder.
Delivery Mode:
Formulation engineering investments correlate with acute intervention requirements and adherence monitoring constraints across care settings.
- Oral:Tablet and liquid formulations retain dominant share through manufacturing scale economies and established palatability engineering protocols, with taste-masking technologies addressing paediatric acceptance barriers.
- Injectable:Intramuscular and subcutaneous depot antipsychotics command premium positioning in residential treatment centers where daily medication supervision is impractical, with United States institutional procurement contracts sustaining supplier concentration.
- Intranasal:Rapid-onset benzodiazepine and ketamine formulations are gaining formulary acceptance in paediatric emergency departments as alternatives to intramuscular injection for acute agitation, compressing time-to-sedation benchmarks.
- Transdermal:Methylphenidate patches offer extended duration coverage with reduced abuse liability, though skin irritation rates and application site rotation requirements limit adoption velocity.
Oral formulations retain volume concentration; intranasal delivery is expanding most quickly.
End User:
Reimbursement mechanism and care intensity requirements segment demand across institutional settings with divergent procurement authority structures.
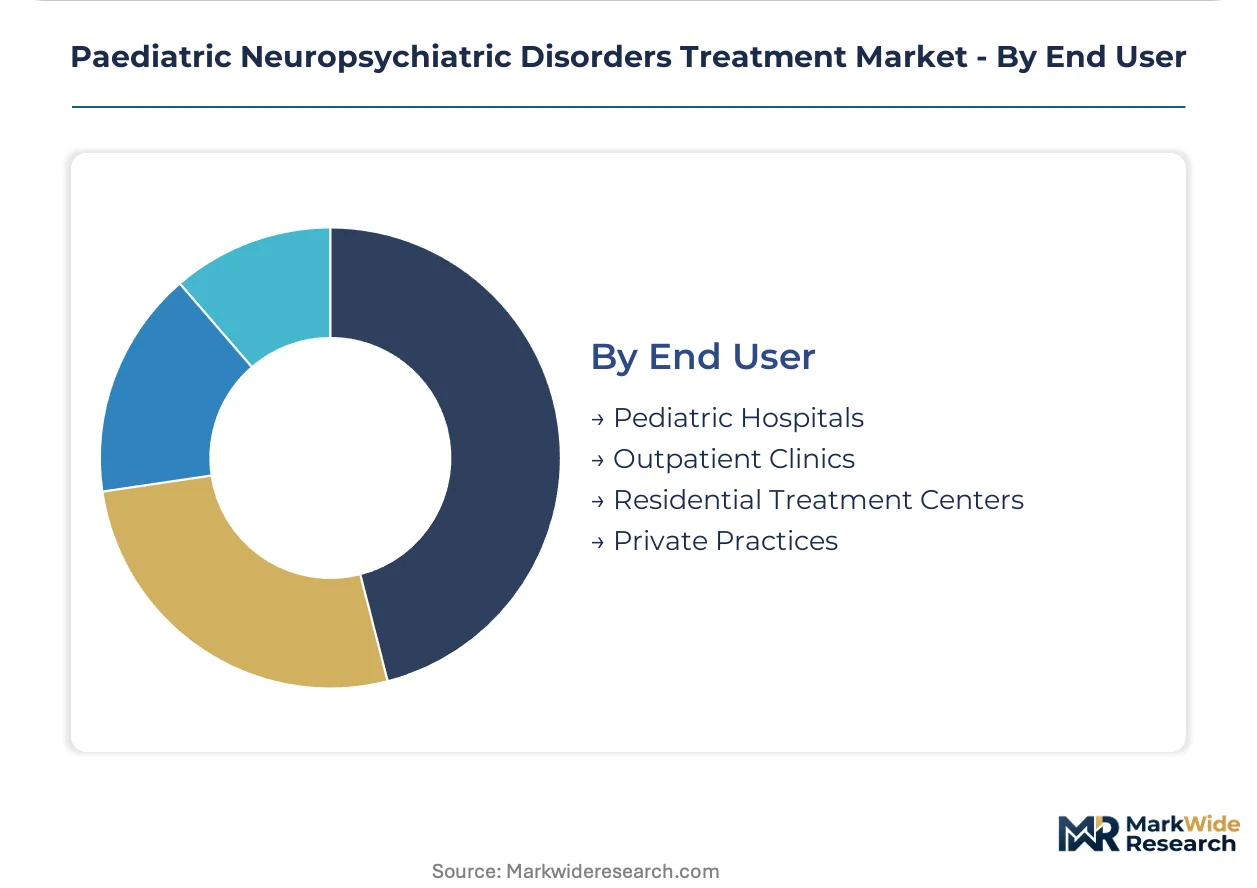
- Paediatric Hospitals:Academic medical centers and children's hospitals concentrate subspecialty psychiatry capacity, with pharmacy and therapeutics committees exercising formulary control over high-cost biologic and long-acting injectable agents.
- Residential Treatment Centers:Institutional settings with 24-hour supervision requirements drive demand for long-acting injectable formulations and medication adherence monitoring technologies, with per-diem reimbursement structures influencing pharmaceutical budget allocations.
- Outpatient Clinics:Community mental health centers and hospital-affiliated ambulatory services manage chronic medication regimens with varying prior authorization requirements across United States state Medicaid programs.
- Private Practices:Independent paediatric psychiatrists and developmental-behavioural paediatricians prescribe within commercial insurance and self-pay frameworks, with formulary tier placement influencing therapeutic selection.
Institutional procurement concentrates in paediatric hospitals; margin expansion concentrates in residential treatment centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA paediatric study requirements under the Best Pharmaceuticals for Children Act and EMA's Paediatric Investigation Plans create divergent compliance burdens that reshape investment allocation across national markets. Specialist care infrastructure density and reimbursement framework maturity determine regional demand concentration.
United States
Medicaid-managed care contracts and commercial insurance carve-outs for childhood behavioural health sustain the world's densest specialist psychiatry infrastructure. The FDA's paediatric exclusivity incentive drives sponsor investment in juvenile trial extensions. Academic medical centres in Boston and Philadelphia anchor multi-site neuropsychiatric research networks.
Germany
EMA centralised procedures and established paediatric research network relationships attract phase II-III trial investment. The country's statutory health insurance system maintains broad reimbursement for ADHD and autism spectrum interventions. Berlin and Heidelberg host leading university hospital psychiatry departments with dedicated juvenile units.
United Kingdom
NHS England's Long Term Plan commitments to children and young people's mental health services expand referral pathways and prescribing volumes. NICE guideline updates for ADHD and autism spectrum disorder reshape treatment algorithms. The Maudsley Biomedical Research Centre in London coordinates national cohort studies.
Japan
PMDA paediatric drug development consultations accelerate regulatory submission preparation for multinational sponsors. School-based mental health screening mandates expand addressable patient identification. Tokyo and Osaka metropolitan areas concentrate child psychiatry specialist capacity and university-affiliated research hospitals.
Australia
Medicare reimbursement for paediatric psychiatrist consultations and psychological interventions sustains community-based care access. The TGA's paediatric medicines initiative streamlines juvenile indication expansion pathways. Melbourne and Sydney children's hospitals operate dedicated neurodevelopmental disorder assessment and treatment centres.
Paediatric Neuropsychiatric Disorders Treatment Market Competitive Landscape
Listed pharmaceutical conglomerates compete with private biotech specialists across development-stage asset portfolios and geographic reach. Market structure concentrates around diversified multinational players with established paediatric medicine infrastructure, supplemented by mid-cap firms with focused neuropsychiatric pipelines. Three archetypes dominate: vaccine-and-paediatric-diversified giants, CNS-specialised mid-caps, and rare-disease biotechs with autism spectrum assets. Competitive dynamics centre on M&A-driven pipeline expansion and strategic partnerships with academic paediatric research networks.
Among the diversified pharmaceutical tier, Pfizer Inc and Johnson & Johnson exemplify scale-driven positioning through established paediatric medicine distribution infrastructure and vaccine development capabilities. Eli Lilly and Company occupies a specialist position within attention-deficit and mood disorder therapeutic areas, while Novartis AG represents geographic breadth through European paediatric research network integration. These three entities anchor competitive intensity across regulatory submission timelines and institutional procurement contracting.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc |
| Novartis AG |
| AbbVie Inc |
| Eli Lilly and Company |
| AstraZeneca PLC |
| GlaxoSmithKline plc |
| Bristol-Myers Squibb Company |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day inventory cycles for long-acting injectable antipsychotics concentrate margin capture with established pharmaceutical infrastructure holders, while weight-based dosing SKU proliferation across developmental age spans fragments pricing power toward generic oral segments. FDA paediatric exclusivity incentives and EMA investigation plan compliance costs feed directly into originator pricing structures for novel delivery mechanisms.
Pricing Analysis
Certification level (FDA paediatric label, EMA paediatric investigation plan completion, ISO 14155 compliance) creates the primary spread between originator and generic tiers, with three-tier pricing structure across premium, standard, and economy levels dominating institutional procurement. Price differentiation rests on palatability engineering investment and cold-chain handling capability for depot formulations. Pricing pressure stems from Medicaid generic substitution mandates and 340B program discount obligations. Residential treatment centers exhibit lowest price sensitivity due to per-diem reimbursement structures, while outpatient clinics face highest sensitivity under state Medicaid prior authorization constraints.
Supply Chain Analysis
United States, Germany, and Switzerland anchor active pharmaceutical ingredient synthesis and formulation finishing for paediatric neuropsychiatric compounds, with India and China supplying intermediate chemical precursors. Manufacturing draws from specialized excipient streams including taste-masking polymers and intranasal absorption enhancers. Single-source vulnerability concentrates in long-acting injectable depot formulation capacity, where sterile manufacturing suites require multi-year qualification timelines. Distribution runs through hospital pharmacy committees and institutional procurement consortia, with cold-chain logistics for biologic and depot products adding fulfillment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paediatric neuropsychiatric treatment demand follows cyclical patterns tied to school-year diagnostic surges and Medicaid enrollment expansion cycles, with the current window reflecting upward pressure from post-pandemic behavioural health service normalization.
For Market Incumbents: Consolidate formulary positioning through backward integration into palatability engineering capabilities and captive supply of age-appropriate delivery mechanism components. Defend against intranasal delivery disruptors by accelerating long-acting injectable lifecycle management programs. Prioritize certification investment in EU AI Act conformity assessment for algorithmic diagnostic companions. For New Entrants and Emerging Players: Lead with acute agitation intranasal formulations targeting paediatric emergency department formulary gaps, where rapid-onset kinetic profiles command premium positioning absent generic competition. White-space concentrates in autism spectrum disorder irritability management, where biomarker-stratified subpopulation targeting enables differentiated value demonstration. Pursue FDA breakthrough device designation pathways for digital therapeutic bundling with pharmacotherapy. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical conglomerates divesting paediatric medicine units to refocus on oncology and immunology. Long-term viability hinges on regulatory exclusivity duration and reimbursement code density for combination therapy bundles. Watch FDA paediatric study requirement enforcement intensity as inflection signal for trial investment return expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Paediatric Investigation Plan Completion | EMA-mandated development timelines expand addressable patient populations and extend market exclusivity for approved compounds. |
| Intranasal Delivery Platform Development | Rapid-onset formulations displace intramuscular injection in emergency paediatric psychiatric settings and capture formulary premium. |
| EU AI Act Compliance Certification | Conformity assessment for algorithmic diagnostic tools unlocks European market access for digital phenotyping platforms. |
| Residential Treatment Channel Partnership | Long-acting injectable procurement contracts in institutional settings sustain adherence monitoring revenue and reduce generic substitution risk. |
| Digital Therapeutic Bundling Strategy | FDA breakthrough device designation enables standalone reimbursement codes for combined pharmacotherapy and behavioural intervention pilots. |
Research Methodology
A standing panel of paediatric psychiatrists, hospital pharmacy directors, regulatory affairs leads, and payer access specialists provided ongoing calibration across primary interview rounds, with secondary validation drawing from FDA paediatric exclusivity determinations, EMA paediatric investigation plan submissions, ClinicalTrials.gov enrollment data, and United States Medicaid formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical revenue triangulation anchored segmentation estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks segmenting by pharmacological class, delivery mechanism, therapy area, and regional regulatory cluster. CAGRs derived from patient prevalence trend extrapolation, diagnostic incidence normalization, and treatment penetration rate assumptions, incorporating paediatric safety data accumulation timelines and label expansion probability weightings.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid reimbursement density, FDA paediatric study requirement enforcement, and EMA investigation plan timeline adherence would require recalibration. Forecasts reflect documented assumptions regarding regulatory exclusivity duration, generic entry timing, and digital therapeutic bundling reimbursement adoption velocity. Recalibration cycles align with material shifts in FDA paediatric guidance updates, CMS behavioural health carve-out policy changes, and EU AI Act implementing act releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pediatrics
Pediatric Home Healthcare Market
Pediatrics
Pediatric Brain Tumor Market
Pediatrics
Global Pediatric Home Healthcare Services Market
Pediatrics
Pediatric Obesity Management Market
Pediatrics
Pediatric Asthma Treatment Market
Pediatrics
Paediatric Spasticity Treatment Market
Pediatrics
Pediatric Healthcare Market
Pediatrics
Pediatric Oncology Treatment Market
Pediatrics
Pediatric Palliative Care Drugs Market
Pediatrics
Pediatric Craniosynostosis Treatment Market
Pediatrics
Pediatric Dental Market
Pediatrics
Paediatric Wheelchairs Market
Pediatrics
Pediatric Growth Hormone Deficiency Market
Pediatrics
Global Cerebral Palsy Treatment Market
Pediatrics
Pediatric MRI Market
Pediatrics
Global Pediatric Radiology Market