
 Global Nasal Drug Delivery Technology Market | 2026-2036
Global Nasal Drug Delivery Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasal Drug Delivery Technology Market Foresight
The nasal drug delivery technology sector is pivoting between high-precision pressurized devices for biologics and commodity atomization systems for generic decongestants. GlaxoSmithKline leverages its respiratory heritage to dominate metered-dose nasal spray platforms. Pfizer sustains competitive positioning through backward integration into formulation science for intranasal vaccines. OptiNose differentiates via its breath-powered delivery mechanism that targets the upper posterior nasal cavity.
Nasal drug delivery technology encompasses devices and formulations engineered to administer therapeutic agents through the nasal mucosa, typically achieving bioavailability of 30-50% for small molecules via absorption across the respiratory epithelium and olfactory region. The technology serves both local treatment targets such as allergic rhinitis and systemic delivery applications including migraine therapeutics and emergency opioid reversal. Spray formulations occupy the largest volume tier due to decades of clinical familiarity and manufacturing scalability. Needle-free delivery systems represent the fastest-expanding segment as pandemic-era vaccine programs validated intranasal immunization pathways. Pressurized devices command premium pricing through precise droplet size control that optimizes deposition patterns across the nasal cavity.
The FDA's 505(b)(2) regulatory framework shapes reformulation economics by permitting reduced clinical data requirements for nasal versions of approved drugs. EMA's MDR and CE marking requirements for combination drug-device products create compliance complexity that favors established manufacturers with quality management infrastructure. The EU F-Gas Regulation constrains propellant choices for pressurized nasal systems, accelerating transitions to hydrofluoroalkane alternatives. Stakeholders must monitor how evolving pharmacopeial standards for nasal spray performance testing reshape product development timelines and competitive barriers.
Market Dynamics
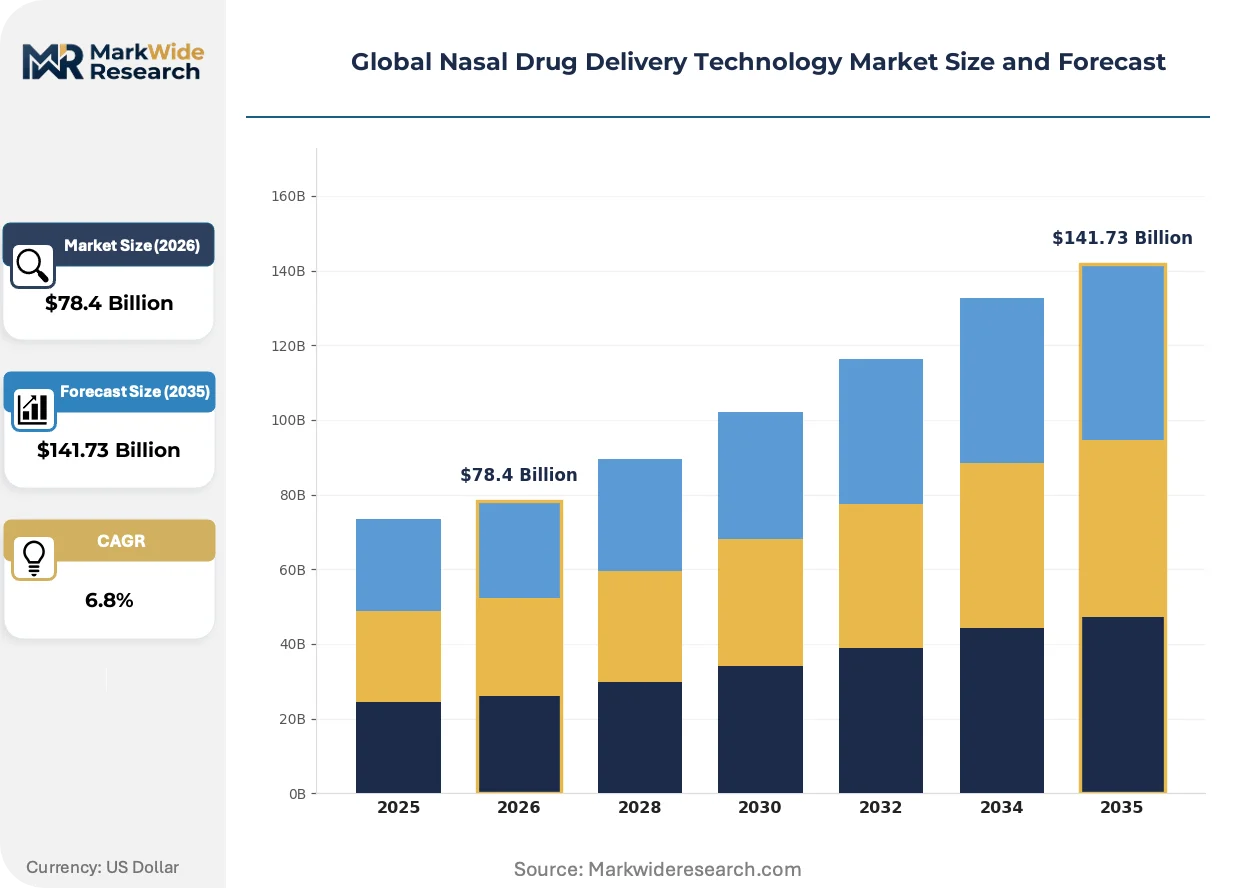
The nasal drug delivery technology sector is bifurcating between precision-engineered pressurized systems for biologics and commodity atomizers for generic formulations, with FDA's 505(b)(2) pathway compressing reformulation timelines and reshaping competitive economics.
Growth Catalysts
- Biologics Pipeline Expansion:Systemic absorption via nasal mucosa is displacing injectable routes for migraine therapeutics and emergency reversal agents, with biologics manufacturers investing in olfactory-targeting formulations.
- FDA 505(b)(2) Framework:Reduced clinical data requirements for nasal reformulations of approved drugs are accelerating time-to-market for repurposed small molecules and combination products.
- Pandemic-Era Immunization Validation:Intranasal vaccine programs in the United States, United Kingdom, and India established proof-of-concept for needle-free systemic delivery, expanding addressable applications beyond respiratory indications.
Market Restraints
- Propellant Supply Constraints:EU F-Gas Regulation phase-down of hydrofluorocarbons is forcing transitions to hydrofluoroalkane alternatives, elevating raw material costs and reformulation expenses for European manufacturers.
- Device-Drug Combination Complexity:EMA's MDR and CE marking requirements for combination products create compliance friction that favors established players with captive quality management infrastructure.
- Deposition Pattern Variability:Anatomical differences in nasal cavity geometry across patient populations generate bioavailability inconsistency, limiting reproducibility for precision-dosed therapeutics.
Strategic Opportunities
- Central Nervous System Delivery:Direct nose-to-brain transport via olfactory and trigeminal pathways offers bypass of blood-brain barrier for neurodegenerative therapeutics, with Japan's PMDA actively reviewing intranasal Alzheimer's candidates.
- Pediatric and Geriatric Needle Avoidance:Unmet demand for pain-free administration in aging populations and vaccine-hesitant demographics positions breath-powered devices for household adoption.
- Emerging Market Manufacturing:India's CDSCO streamlined medical device registration and PLI scheme incentives for pharmaceutical machinery are attracting contract manufacturing investment for nasal spray assembly.
Industry Challenges
- Formulation-Device Integration Talent:Scarcity of specialists combining nasal mucosal pharmacokinetics with mechanical engineering for spray pump optimization is elongating product development cycles.
- Pharmacopeial Testing Standardization:Evolving USP and EP requirements for droplet size distribution, plume geometry, and spray pattern analysis are forcing repeated method validation and equipment recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasal Drug Delivery Technology Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sprays, Powders, Gels, Solutions End User: Pharmacies, Hospitals, Home Care, Clinics Technology: Needle-Free Delivery, Microneedle Technology, Pressurized Devices, Atomization Formulation: Liquid, Semi-Solid, Solid, Others |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Pfizer, Johnson & Johnson, Novartis, Boehringer Ingelheim, AptarGroup, Merck, OptiNose, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasal Drug Delivery Technology Market Shifts & Advancements
Device architecture is fragmenting into application-specific platforms, with manufacturers abandoning universal designs in favor of modality-optimized systems that match deposition mechanics to therapeutic targets.
Microelectromechanical systems (MEMS) are modularizing nasal spray actuation, enabling programmable droplet size distributions that shift between 10-30 micron ranges for upper respiratory deposition and sub-10 micron fractions for olfactory transport. Biologics developers in Germany and Switzerland are adopting these platforms for peptide formulations previously limited to parenteral routes. The technology is modularizing supply chains by decoupling electronic control modules from disposable drug reservoirs.
EMA's MDR Article 117 combination product requirements are mandating notified body involvement for nasal sprays containing drug substances, elevating documentation burdens and third-party audit costs. Manufacturers serving European markets are consolidating device and formulation development under single quality management systems to streamline technical file compilation. High-volume generic producers are exiting the EU market rather than absorbing compliance overhead, concentrating supply among mid-cap specialists with dedicated regulatory affairs functions.
Hospital procurement is consolidating nasal delivery devices into formulary contracts that bundle multiple respiratory modalities, displacing brand-specific purchasing for individual therapeutic categories. Integrated delivery networks in the United States are negotiating multi-year agreements covering metered-dose sprays, dry powder inhalers, and nebulizer systems under single vendor relationships. This concentration is most visible in migraine and emergency medicine units where standardization reduces nursing training burden and inventory complexity.
Global Nasal Drug Delivery Technology Market Segmentation
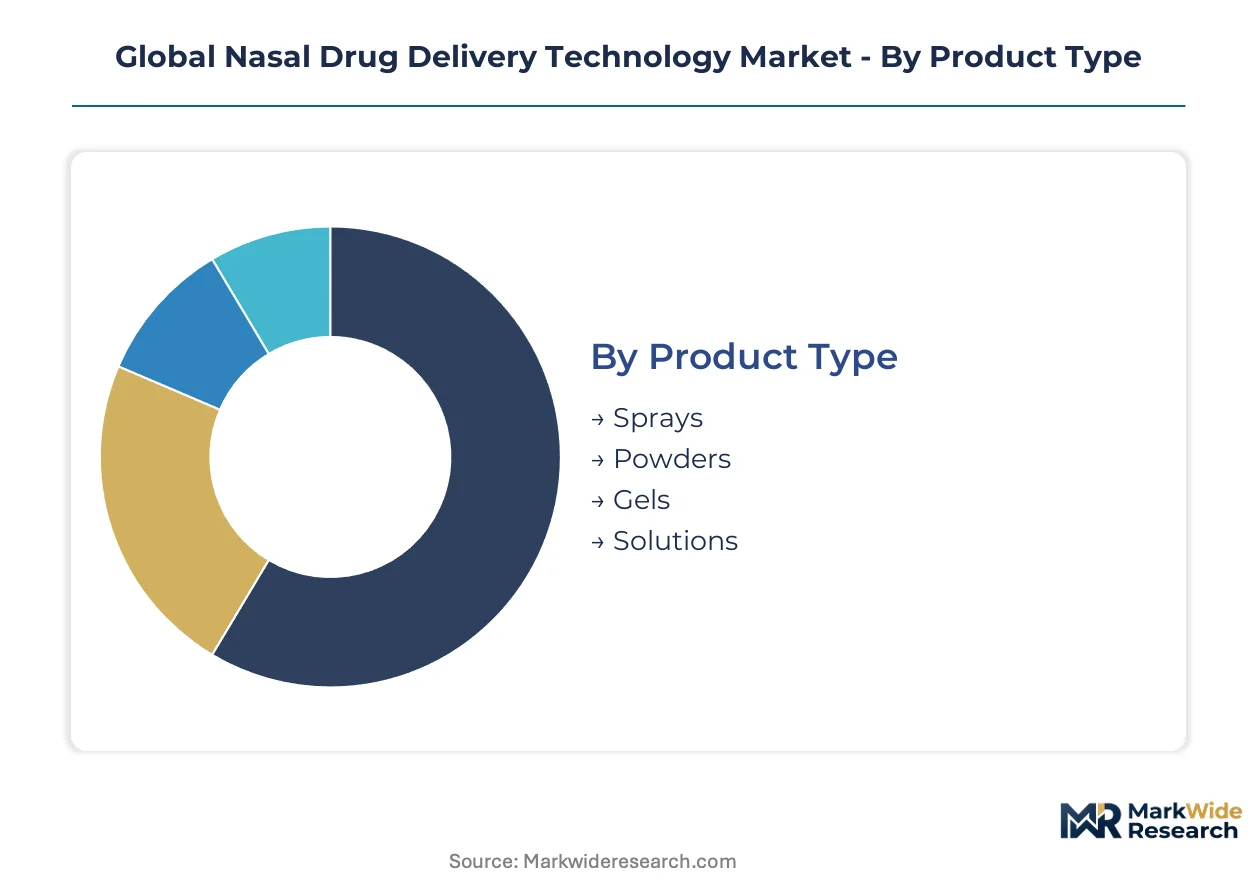
Nasal drug delivery technology segments diverge sharply between established spray platforms optimized for scale and emerging precision systems targeting biologics. Each category reflects distinct trade-offs between manufacturing familiarity and therapeutic performance requirements.
Product Type:
Standardization dominates commodity formats while spray pumps and powder devices demand customization for deposition geometry and dose reproducibility.
- Sprays:Metered-dose pump systems deliver 30-50% bioavailability for small molecules through respiratory epithelium absorption. Demand concentrates in United States migraine therapeutics and German allergic rhinitis markets, driven by decades of clinical familiarity and FDA 505(b)(2) reformulation approvals.
- Powders:Dry powder inhalers engineered for nasal deposition achieve superior stability for biologics and peptides requiring cold chain alternatives. Japanese and Swiss manufacturers are advancing these platforms for olfactory-targeting neurodegenerative candidates reviewed by PMDA.
- Gels:Mucoadhesive formulations extend residence time for local corticosteroid delivery.
- Solutions:Liquid formulations serve generic decongestant and saline irrigation volumes.
Leading the category by volume: Sprays. Growing fastest: Powders.
End User:
Procurement authority shifts from hospital formularies toward retail and direct-to-patient channels as needle-free devices enable self-administration.
- Pharmacies:Retail dispensing captures over-the-counter decongestants and prescription migraine therapeutics, with United States pharmacy benefit managers consolidating preferred nasal spray tiers into therapeutic class management programs.
- Hospitals:Emergency departments and operating suites deploy intranasal opioid reversal agents and sedative premedications, with German university hospitals standardizing breath-powered devices across anesthesia and toxicology units.
- Home Care:Self-administration devices for chronic rhinitis and pediatric vaccination are gaining share fastest among aging populations and vaccine-hesitant demographics seeking needle avoidance.
- Clinics:Outpatient settings balance convenience with clinical oversight for allergy immunotherapy and migraine rescue protocols.
Volume leadership: Pharmacies. Steepest expansion trajectory: Home Care.
Technology:
Cost tiers separate precision-engineered systems from commodity atomizers, with premium devices commanding pricing through droplet control and programmable actuation.
- Needle-Free Delivery:Intranasal immunization platforms validated through pandemic-era programs in United States, United Kingdom, and India now expand toward systemic biologics. CDSCO streamlined registration and PLI scheme incentives are attracting Indian contract manufacturing investment.
- Pressurized Devices:Hydrofluoroalkane-propelled systems achieve precise 10-30 micron droplet distributions for upper posterior cavity targeting. EU F-Gas Regulation constraints on hydrofluorocarbon propellants are elevating European raw material costs and accelerating alternative transitions.
- Microneedle Technology:Dissolving arrays for intranasal mucosal disruption remain developmental.
- Atomization:Basic mechanical pumps serve high-volume generic segments with minimal differentiation.
Dominant by revenue: Pressurized Devices. Climbing the fastest: Needle-Free Delivery.
Formulation:
Physical state determines stability requirements, device compatibility, and manufacturing capital intensity across the value chain.
- Liquid:Aqueous and non-aqueous solutions dominate commercial volumes through compatibility with standard pump mechanisms and established sterilization protocols. United States and German facilities run continuous manufacturing lines for these formulations.
- Solid:Powder and lyophilized formats enable biologics stability without refrigeration, with Swiss and Japanese developers advancing these for peptide and protein nasal delivery previously limited to parenteral routes.
- Semi-Solid:Mucoadhesive gels and ointments balance residence time with patient acceptability.
- Others:Novel carrier systems including nanoparticle suspensions and lipid complexes remain precommercial.
Widest deployment: Liquid. Gaining share fastest: Solid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotechnology corridor anchors intranasal formulation development, with the United States, Germany, Japan, India, and Switzerland hosting the dominant clinical trial networks and manufacturing infrastructure for nasal drug delivery systems.
United States
FDA's 505(b)(2) pathway accelerates nasal reformulation approvals for migraine therapeutics and emergency reversal agents. The IRA's drug pricing provisions reshape commercialization economics for combination products. Massachusetts and North Carolina clusters concentrate metered-dose spray manufacturing and olfactory-targeting biologics development.
Germany
University hospitals in Bavaria and Baden-Württemberg standardize breath-powered devices across anesthesia and toxicology units. EMA's MDR Article 117 elevates documentation burdens for combination products, favoring manufacturers with captive quality systems. Frankfurt-Rhine-Main pharmaceutical machinery suppliers are transitioning pressurized device propellants under EU F-Gas Regulation constraints.
Japan
PMDA actively reviews intranasal Alzheimer's candidates exploiting nose-to-brain transport pathways. METI incentives support peptide formulation stability research for cold chain alternatives. Osaka-Kobe pharmaceutical manufacturing corridor advances dry powder platforms for neurodegenerative therapeutics previously limited to parenteral routes.
India
CDSCO streamlined medical device registration and PLI scheme incentives attract contract manufacturing investment for nasal spray assembly. Domestic migraine and allergic rhinitis patient volumes drive generic spray demand. Hyderabad and Ahmedabad clusters expand pharmaceutical machinery capacity for needle-free delivery device production.
Switzerland
Swissmedic oversight of combination products aligns with EMA standards while preserving national flexibility for novel delivery mechanisms. Basel-area biologics developers adopt MEMS-enabled programmable actuation for sub-10 micron droplet fractions targeting olfactory transport. Geneva regulatory consulting specialists support technical file compilation for EU market access.
Global Nasal Drug Delivery Technology Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation-device integration capability, with precision-engineered pressurized systems commanding pricing power over generic mechanical pumps. The vendor base stratifies between respiratory heritage multinationals with captive spray platforms and mid-cap specialists with dedicated regulatory affairs functions. Three archetypes dominate: biologics-integrated developers, device-pure manufacturers, and reformulation service providers. Consolidation pressures favor backward integration into formulation science and geographic expansion toward Indian contract manufacturing hubs.
Within the respiratory heritage tier, GlaxoSmithKline and AstraZeneca exemplify platform-leveraged positioning through decades of clinical familiarity with metered-dose systems. Pfizer occupies a position bridging pharmaceutical formulation and intranasal vaccine development. OptiNose represents the specialization archetype, anchoring breath-powered delivery innovation targeting posterior nasal cavity deposition. These three entities collectively illustrate the competitive spectrum from scale-driven commodity supply to precision-engineered biologics enablement.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Pfizer |
| Johnson & Johnson |
| Novartis |
| Boehringer Ingelheim |
| AptarGroup |
| Merck |
| OptiNose |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation phase-down mandates gate qualified supply for hydrofluoroalkane propellant systems, restricting premium-tier pricing access to manufacturers with captive formulation science capabilities and notified body certification infrastructure.
Pricing Analysis
Value-based pricing anchored to deposition precision and bioavailability outcomes separates pressurized biologics platforms from commodity atomizers. Three-tier pricing structure across premium, standard, and economy levels reflects droplet size control certification, with EMA MDR compliance tier and FDA 505(b)(2) approval status as primary differentiation drivers. Pricing pressure stems from Indian contract manufacturers entering generic spray segments with PLI scheme cost advantages. Hospital procurement committees exhibit lowest price sensitivity for emergency reversal and migraine rescue categories, while retail pharmacy chains drive commoditization of decongestant volumes.
Supply Chain Analysis
Direct-to-pharmacy channels handle retail volumes, while direct-to-hospital contracts capture emergency medicine and anesthesia unit demand. Manufacturing concentrates in United States, Germany, and India, with Swiss and Japanese facilities specializing in peptide stability platforms. Raw material flows draw from hydrofluoroalkane propellant suppliers, precision-machined pump component foundries, and biologics-grade polymer reservoirs. Single-source vulnerability in propellant chemistry creates exposure to EU regulatory phase-down timelines. Distribution runs through pharmaceutical wholesalers and integrated delivery networks consolidating formulary contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward integration into formulation science separates precision-device developers from commodity assemblers, with regulatory compliance infrastructure as the decisive downstream lever.
For Market Incumbents: Anchor competitive position through captive olfactory-targeting formulation capabilities that emerging Indian contract manufacturers cannot replicate without decade-long pharmacopeial validation cycles. Defend against breath-powered device specialists by consolidating hospital formulary contracts across multiple respiratory modalities. Prioritize EMA MDR Article 117 technical file completion to forestall mid-cap competitor EU market access. For New Entrants and Emerging Players: MEMS-enabled programmable droplet actuation offers technology-first wedge into biologics partnerships previously monopolized by respiratory heritage multinationals. Target Japanese neurodegenerative candidates under PMDA review for white-space penetration, where nose-to-brain transport validation creates partnership entry points. Pursue CDSCO registration and PLI scheme qualification for Indian contract manufacturing scale as primary go-to-market anchor. For Investors and Strategic Acquirers: FDA 505(b)(2) approval acceleration for nasal reformulations is the leading indicator that formulation-device integration specialists will command acquisition premiums over pure-play device manufacturers. Long-term viability favors mid-cap developers with dedicated regulatory affairs functions and single quality management systems spanning both device and drug components. Watch for EMA notified body queue congestion as inflection signal for compliance infrastructure scarcity value.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 505(b)(2) Submission | Streamlined approval pathway accelerates nasal reformulation timelines for migraine therapeutics. |
| EMA MDR Technical File Compilation | Notified body involvement mandates elevate compliance barriers for combination product market access. |
| Backward Integration into Formulation Science | In-house peptide stability capabilities reduce reliance on external biologics developers. |
| CDSCO Registration and PLI Qualification | Indian regulatory streamlining attracts contract manufacturing investment for nasal spray assembly. |
| Hospital System Formulary Consolidation | Integrated delivery network bundling reduces competitor access across respiratory device categories. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with regulatory affairs leads, formulary directors at integrated delivery networks, biomedical engineers, and GPO contracts managers. FDA 505(b)(2) submission databases, EMA MDR Article 117 technical files, ClinicalTrials.gov intranasal protocol registrations, and EU F-Gas Regulation compliance disclosures provided secondary validation. Bottom-up device shipment analysis triangulated against top-down therapeutic class expenditure estimates.
Data-stream reconciliation across formulation type, technology platform, end-user channel, and regional regulatory cluster generated volume and value outputs over the projection horizon. CAGRs derived from segmented growth rate modeling incorporating biologics pipeline advancement, pandemic-era immunization validation carryover effects, and propellant transition cost impacts. Forecast inputs included PMDA review queue status for neurodegenerative candidates and CDSCO medical device registration velocity indices.
Several conditions sit outside the modeled scope, including preclinical-stage nose-to-brain transport mechanisms, microneedle array commercialization timelines, and unforeseen pharmacopeial standard revisions for droplet size distribution testing. Forecasts reflect base-case assumptions regarding regulatory pathway stability and propellant supply continuity. Periodic stress-testing of base assumptions is recommended against EMA notified body capacity constraints and Indian PLI scheme renewal parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Chloramphenicol Eye Drops Market
Pharmaceuticals
Monkeypox Vaccine and Treatment Market
Pharmaceuticals
US Plasma Fractionation Market
Pharmaceuticals
Respiratory Disease Vaccine Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Middle East and Africa Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Lipid Injectable Market
Pharmaceuticals
Global Hepatitis a Vaccine Market
Pharmaceuticals
Spain OTC Drugs Market
Pharmaceuticals
Global Interleukin Inhibitors Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Global Heparin Sodium Market
Pharmaceuticals
Oral Solid Dosage Pharmaceutical Formulation Market