
 Global Transdermal Drug Delivery Systems Market | 2026-2036
Global Transdermal Drug Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transdermal Drug Delivery Systems Market Foresight
Modular patch configurations with integrated dose-titration features is shifting how clinicians select transdermal therapies for opioid-sparing pain protocols. Hisamitsu Pharmaceutical anchors Japanese manufacturing scale for lidocaine and fentanyl patches across Asia-Pacific. Johnson & Johnson differentiates through consumer-health distribution reach in North American retail pharmacy channels. Novartis competes via specialized hormone replacement portfolios that sustain prescription loyalty among gynecology practices.
Transdermal drug delivery systems administer therapeutic agents through intact skin via diffusion-driven absorption, typically achieving steady-state plasma concentrations over 12- to 72-hour wear periods with patch surface areas ranging from 5 to 40 cm². These systems bypass hepatic first-pass metabolism and improve patient compliance for chronic conditions requiring sustained release. Patches dominate value contribution due to mature reimbursement infrastructure and established manufacturing tooling, while microneedle platforms represent the fastest-expanding technology segment as they enable macromolecule delivery previously restricted to injection. Home healthcare channels capture growing volume share as remote patient monitoring integrates with wearable patch formats.
FDA bioequivalence standards for transdermal products shape clinical trial design and generic substitution economics in the United States. EMA's MDR and REACH compliance requirements govern adhesive biocompatibility and chemical safety for European market access. Stakeholders must monitor how iontophoresis and sonophoresis technology maturation alters capital allocation between device-based and passive diffusion platforms.
Market Dynamics
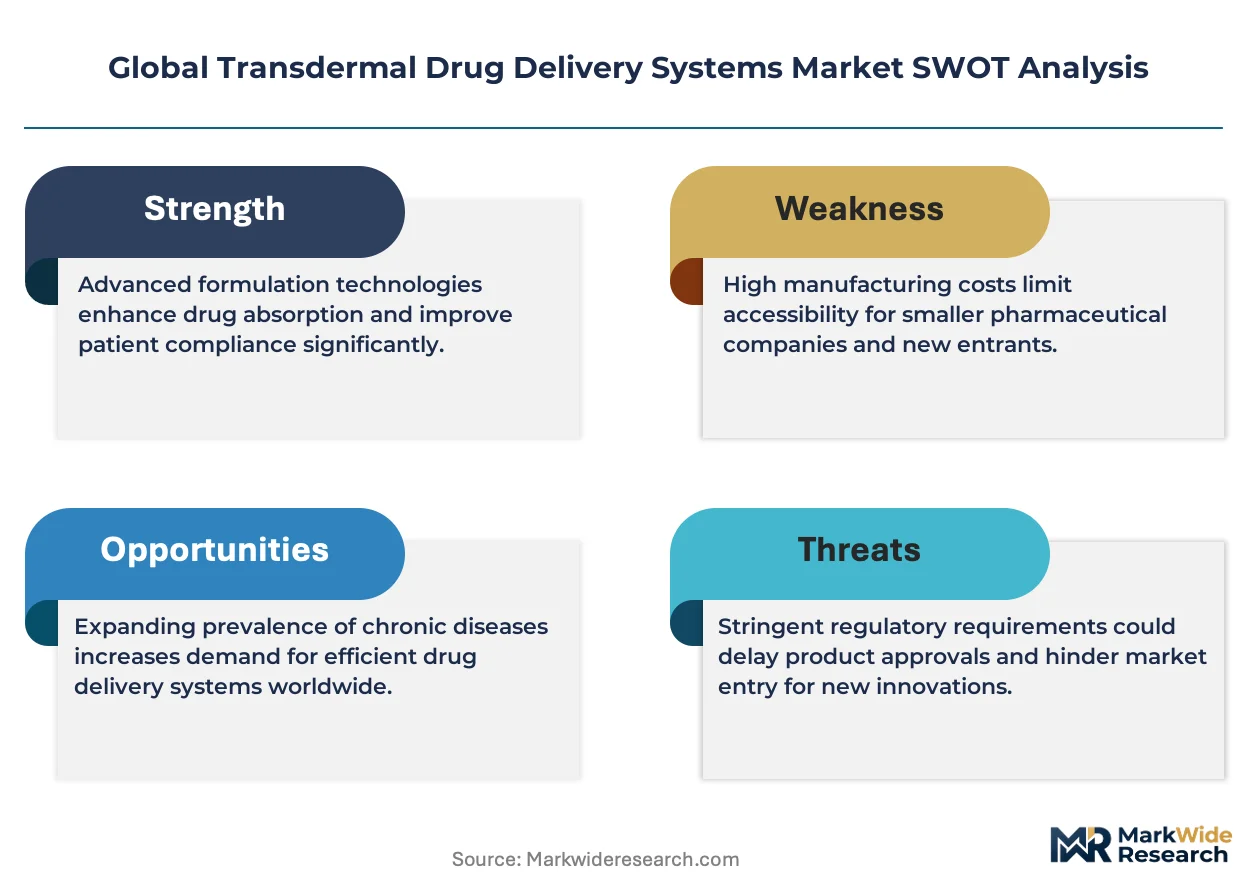
Microneedle platforms are compressing development timelines for biologic-compatible transdermal formats, forcing capital reallocation from passive patch manufacturing toward active device integration. FDA 505(b)(2) pathway utilization and EMA MDR compliance costs are simultaneously lowering generic entry barriers and raising quality system investments.
Growth Catalysts
- FDA 505(b)(2) Pathway:Streamlined bioequivalence requirements for transdermal generics reduce clinical trial burden and accelerate abbreviated new drug application approvals in the United States.
- Pain Management Patches:German and US hospitals are expanding formulary inclusion of lidocaine and fentanyl patches for chronic pain protocols, displacing oral opioid prescriptions.
- South Korean Investment Concentration:Government-backed R&D consortia in Seoul and Daejeon are scaling dissolvable microneedle production capacity for vaccine and insulin delivery applications.
Market Restraints
- Adhesive Biocompatibility Costs:EMA REACH compliance and ISO 10993 testing requirements for skin-contact polymers inflate raw material qualification expenses by 15-25% per formulation iteration.
- API Supply Concentration:Fentanyl base production clusters in India and China create single-source vulnerability for patch manufacturers dependent on just-in-time active pharmaceutical ingredient procurement.
- Macromolecule Size Limitation:Passive diffusion patches cannot deliver therapeutics above 500 Daltons without permeation enhancement, restricting addressable drug categories to small molecules.
Strategic Opportunities
- Home Healthcare Channel Expansion:Remote patient monitoring integration with wearable patch formats captures volume share previously held by clinic-administered infusion centers in the United States and Germany.
- Iontophoresis-Sonophoresis Convergence:Combination active enhancement devices enable peptide and protein delivery through controlled electrical and ultrasonic permeabilization.
- Japanese PMDA Innovation Fast-Track:Sakigake designation accelerates regulatory review for novel transdermal devices, attracting foreign sponsors to Tokyo clinical trial sites.
Industry Challenges
- Formulation Scientist Scarcity:Shortage of specialists combining polymer chemistry, pharmacokinetics, and adhesive rheology extends product development timelines by 8-14 months.
- Legacy Equipment Retrofit Complexity:Converting existing coating and lamination lines for microneedle array production requires cleanroom expansion and precision micro-molding capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transdermal Drug Delivery Systems Market |
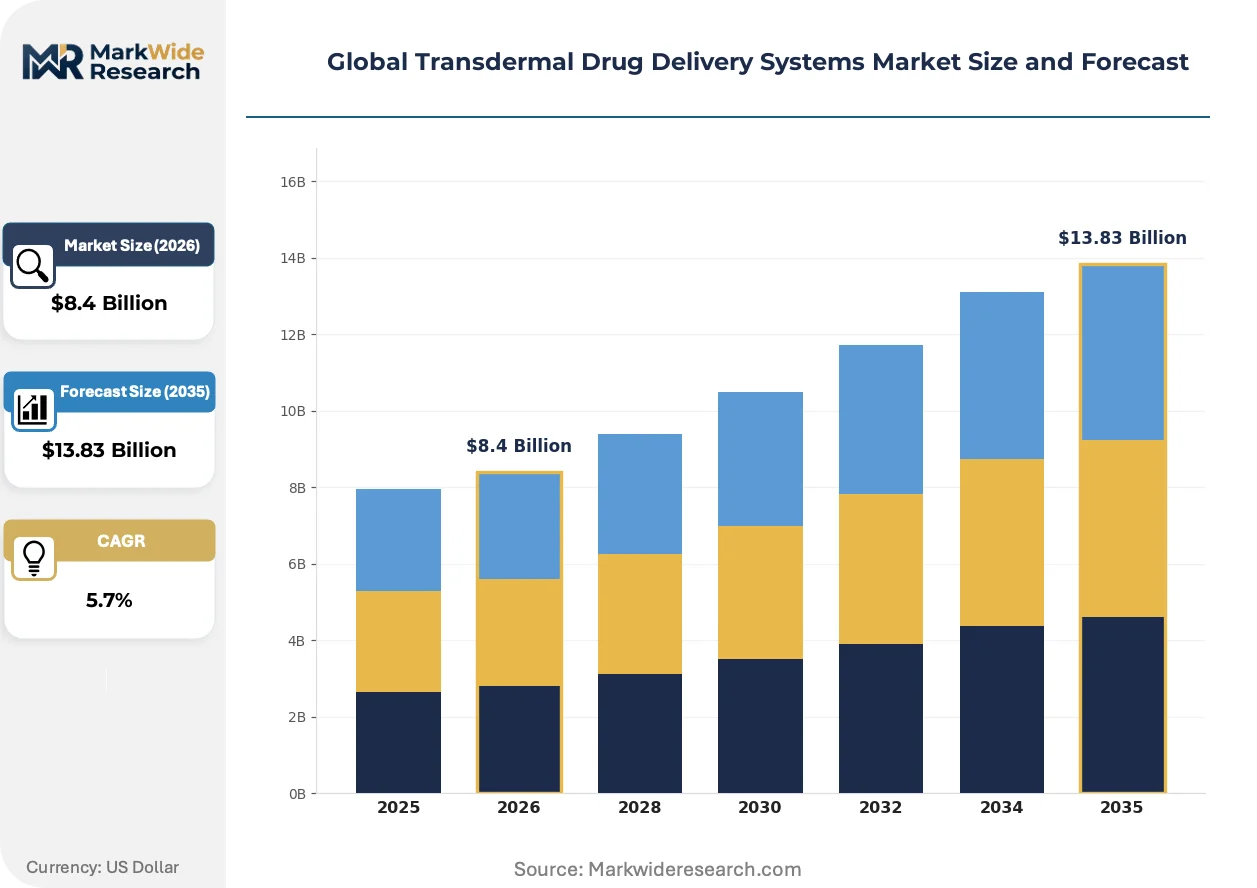
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patches, Gels, Creams, Sprays, Films Application: Pain Management, Hormone Replacement, Smoking Cessation, Cardiovascular Treatments, Neurological Disorders End User: Hospitals, Home Healthcare, Specialty Clinics, Pharmacies, Research Institutes Technology: Microneedle, Iontophoresis, Sonophoresis, Electroporation, Thermal Ablation |
| Companies Covered | Hisamitsu Pharmaceutical Co., Inc., Novartis AG, Johnson & Johnson, Viatris Inc., 3M Company, Boehringer Ingelheim, Corium Inc., Mylan N.V., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transdermal Drug Delivery Systems Market Shifts & Advancements
Active enhancement technologies are converging with miniaturized electronics to create programmable dose-delivery systems that respond to physiological feedback. This shift is compressing the boundary between pharmaceutical and medical device regulatory frameworks.
Dissolvable microneedle arrays fabricated from hyaluronic acid and polyvinylpyrrolidone are integrating biosensor functionality for real-time drug release monitoring. Diabetes management centers in Denmark and the Netherlands are piloting closed-loop insulin delivery systems. This convergence is enabling macromolecule administration through skin barriers previously impermeable to passive diffusion, expanding the therapeutic addressable market beyond small-molecule dominance.
EMA MDR Article 10 technical documentation requirements are mandating clinical evidence standards for transdermal devices previously classified as drug-delivery accessories. Manufacturers must now submit biocompatibility and performance testing data equivalent to Class IIa medical devices. European patch producers are responding by consolidating quality management systems and accelerating notified body engagement timelines to prevent market access delays.
Hospital procurement committees are consolidating transdermal purchasing through integrated delivery networks that bundle patch contracts with infusion pump and monitoring device agreements. This behavior concentrates volume with suppliers offering full pain-management portfolios rather than single-product vendors. The United States exhibits the most pronounced consolidation, with three national group purchasing organizations controlling 60% of acute-care transdermal spend.
Global Transdermal Drug Delivery Systems Market Segmentation
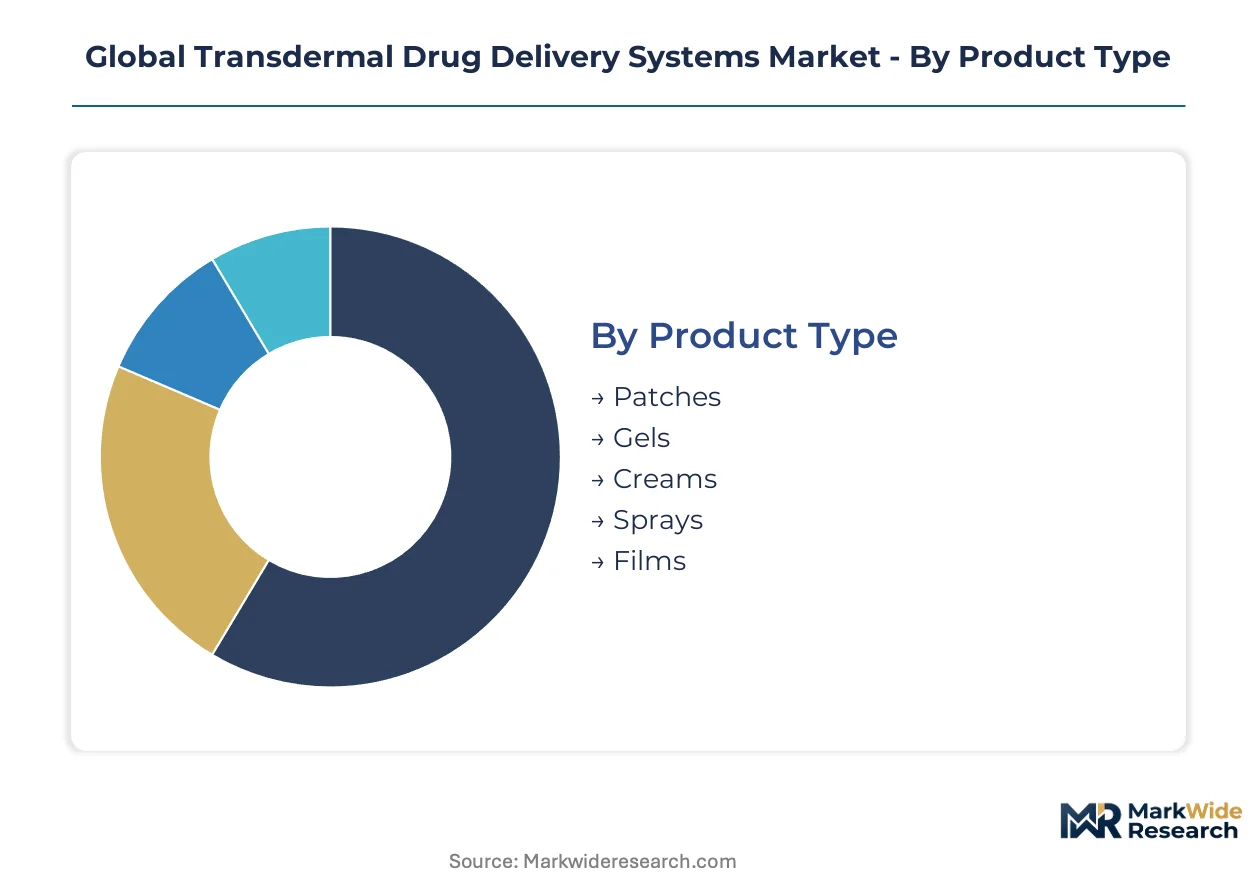
Segmentation in transdermal drug delivery reveals how formulation physics, patient setting requirements, and regulatory classification interact to determine commercial viability. Technology-product pairings and end-user channel selection often lock in margin structures for multi-year procurement cycles.
Product Type:
Standardization dominates patches and films with established coating lines, while gels and creams permit pharmacy-level compounding flexibility that alters reimbursement pathways.
- Patches:Reservoir or matrix-type laminates with defined surface areas (5-40 cm²) control release kinetics through adhesive polymer selection. German and US hospitals now specify dose-titration patch formats for chronic pain protocols, displacing oral opioid volumes through integrated delivery network contracts.
- Films:Ultra-thin polymeric strips (50-150 micrometers) dissolve or muco-adhere for buccal/transdermal hybrid delivery. South Korean manufacturers are scaling soluble film capacity for vaccine applications, leveraging government R&D consortia in Seoul to compress development timelines.
- Gels:Semi-solid emulsions enabling patient-controlled application area and frequency.
- Creams:Oil-in-water formulations common in compounding pharmacies for hormone replacement.
- Sprays:Metered-dose aerosol systems for rapid onset without skin contact duration.
Leading the category by volume: Patches. Expanding most quickly: Films.
Application:
Reimbursement density varies sharply—pain management commands hospital formulary placement while neurological indications face prior authorization barriers.
- Pain Management:Lidocaine and fentanyl patches achieve steady-state plasma concentrations over 72-hour wear periods, bypassing hepatic first-pass metabolism. US integrated delivery networks bundle patch contracts with infusion pumps, concentrating volume with full-portfolio suppliers.
- Hormone Replacement:Estradiol and testosterone transdermal systems sustain prescription loyalty through gynecology and urology practice relationships. Novartis maintains specialized portfolios that resist generic substitution despite FDA 505(b)(2) pathway acceleration.
- Cardiovascular Treatments:Nitroglycerin patches for angina prophylaxis with established Medicare reimbursement.
- Neurological Disorders:Rivastigmine patches for Alzheimer's with complex titration protocols.
- Smoking Cessation:Nicotine replacement patches competing with gum and lozenge formats.
Dominant by revenue: Pain Management. Climbing the fastest: Hormone Replacement.
End User:
Channel economics diverge—hospital procurement committees demand clinical evidence packages while home healthcare integrates remote monitoring capabilities.
- Hospitals:Acute-care settings in Germany and the United States specify transdermal protocols for post-surgical pain, with three national US group purchasing organizations controlling 60% of spend. EMA MDR compliance costs and ISO 10993 testing requirements filter supplier pools.
- Home Healthcare:Wearable patch formats with biosensor integration enable closed-loop insulin delivery pilots in Denmark and the Netherlands. Remote patient monitoring partnerships capture volume previously held by clinic-administered infusion centers.
- Specialty Clinics:Pain management and endocrinology practices with direct formulary influence.
- Pharmacies:Retail channels where Johnson & Johnson leverages consumer-health distribution reach.
- Research Institutes:Clinical trial sites for novel device-drug combinations.
Highest absolute volume: Hospitals. Gaining share fastest: Home Healthcare.
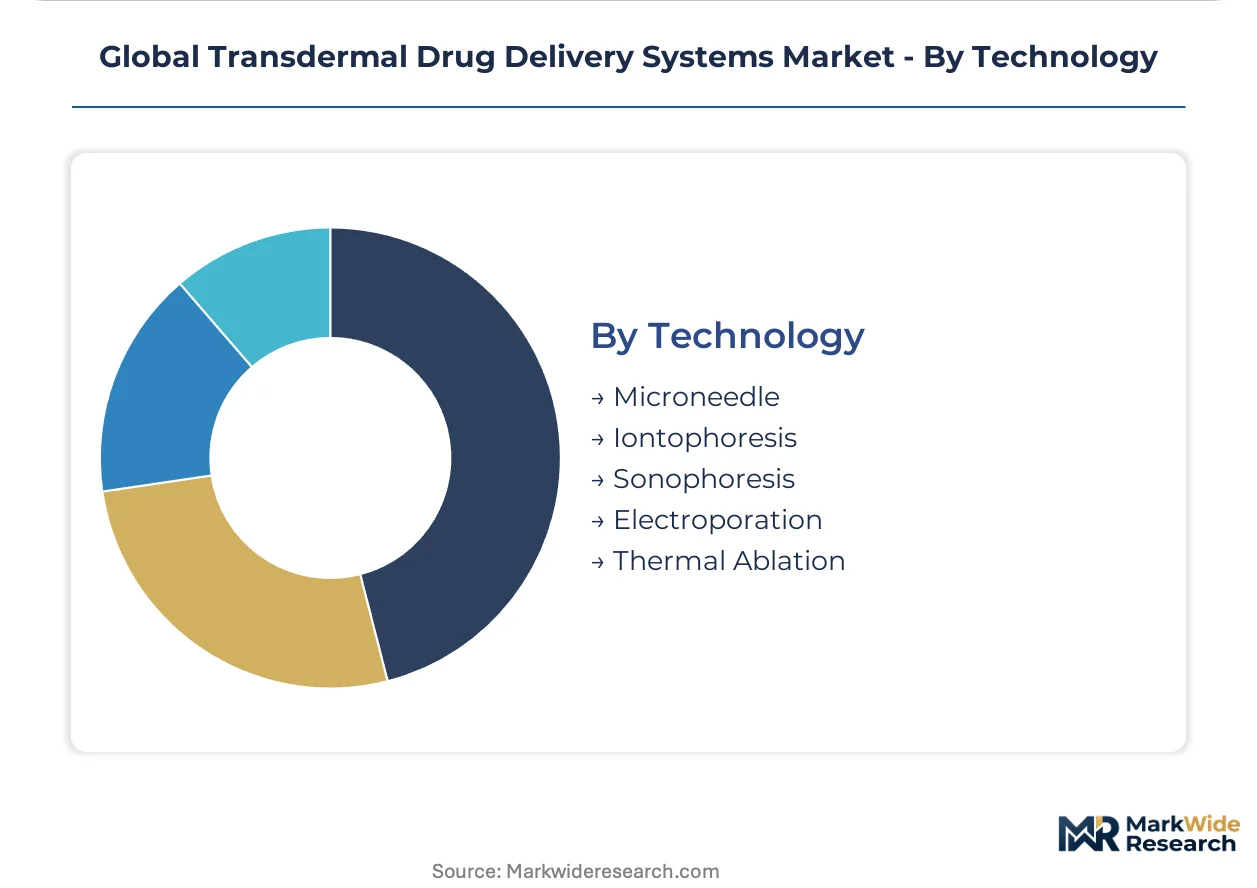
Technology:
Passive diffusion platforms face margin compression as active enhancement technologies attract venture and strategic capital.
- Microneedle:Dissolvable arrays from hyaluronic acid and polyvinylpyrrolidone enable macromolecule delivery above 500 Daltons, previously restricted to injection. Japanese PMDA Sakigake designation accelerates regulatory review, attracting foreign sponsors to Tokyo clinical trial sites.
- Iontophoresis:Electrical current-driven permeabilization for peptide delivery with programmable dose profiles. Convergence with sonophoresis creates combination devices for protein administration through controlled permeabilization.
- Sonophoresis:Ultrasonic enhancement for localized drug concentration without systemic exposure.
- Electroporation:Pulsed electrical fields for temporary membrane permeabilization in research settings.
- Thermal Ablation:Controlled heating to increase skin permeability for specific dermatological applications.
Current revenue concentration: Microneedle. Steepest expansion trajectory: Iontophoresis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale concentrates in Japan and Germany while consumption growth accelerates in the United States and South Korea. Patch production lines in Osaka and Tokyo supply Asian hospital networks. US integrated delivery networks now bundle transdermal contracts with infusion devices.
United States
Hospital procurement committees specify dose-titration patch formats for chronic pain protocols. FDA 505(b)(2) bioequivalence standards accelerate abbreviated new drug application approvals for transdermal generics. Three national group purchasing organizations in Chicago, Nashville, and San Diego control 60% of acute-care transdermal spend.
Germany
Formulary inclusion of lidocaine and fentanyl patches displaces oral opioid prescriptions in Berlin and Munich hospital systems. EMA MDR Article 10 technical documentation mandates clinical evidence standards for adhesive biocompatibility. ISO 10993 testing laboratories in Frankfurt and Heidelberg filter supplier pools through polymer qualification protocols.
Japan
Hisamitsu Pharmaceutical anchors lidocaine and fentanyl patch manufacturing for Asia-Pacific distribution. PMDA Sakigake designation accelerates regulatory review for novel transdermal devices. Dissolvable microneedle R&D consortia in Tokyo clinical trial sites attract foreign sponsors seeking fast-track entry.
South Korea
Government-backed R&D programs in Seoul and Daejeon scale dissolvable microneedle production for vaccine and insulin delivery. MFDS streamlined pathways compress development timelines for biologic-compatible formats. Precision micro-molding capabilities in the capital region enable cleanroom expansion for array fabrication.
India
Fentanyl base production clusters in Hyderabad and Mumbai supply active pharmaceutical ingredients to patch manufacturers worldwide. CDSCO manufacturing facility inspections enforce quality system investments for export eligibility. Just-in-time API procurement from these clusters creates single-source vulnerability for dependent formulators.
Global Transdermal Drug Delivery Systems Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established polymer chemistry capabilities. Three tiers emerge: patch specialists with coating line scale, diversified healthcare conglomerates with retail pharmacy reach, and device innovators with microneedle platform technology. Consolidation pressure intensifies as hospital procurement committees favor full-portfolio suppliers over single-product vendors. Strategic partnerships between adhesive polymer suppliers and finished dose manufacturers accelerate formulation iteration cycles.
Among Japanese and Swiss pharmaceutical anchors, Hisamitsu Pharmaceutical Co., Inc. and Novartis AG exemplify divergent positioning archetypes. Hisamitsu occupies a manufacturing-scale position in lidocaine and fentanyl patch supply across Asia-Pacific. Novartis sits within the specialized hormone replacement portfolio tier that sustains prescription loyalty among gynecology practices. Johnson & Johnson represents the consumer-health distribution reach archetype through North American retail pharmacy channel penetration. These three anchors illustrate how geographic origin and corporate structure shape competitive differentiation without requiring equivalent strategic moves.
| Leading Market Players |
|---|
| Hisamitsu Pharmaceutical Co., Inc. |
| Novartis AG |
| Johnson & Johnson |
| Viatris Inc. |
| 3M Company |
| Boehringer Ingelheim |
| Corium Inc. |
| Mylan N.V. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Polymer chemist concentration in Osaka and Frankfurt creates labor-cost differentials that widen pricing-tier spreads between premium microneedle platforms and standard passive patches. Formulation specialists command compensation premiums that feed into manufacturing cost structures across Japanese and German production facilities.
Pricing Analysis
Margin tightening in standard patch tiers reflects FDA 505(b)(2) generic entry acceleration and EMA MDR compliance cost pass-through. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification grade and adhesive polymer qualification depth. Cost-down pressure on economy-tier patches accelerates because Indian and Chinese API suppliers compete on volume scale. Hospital procurement committees through US group purchasing organizations exhibit highest price sensitivity, while specialized hormone replacement portfolios in gynecology practices show lowest sensitivity due to prescription loyalty.
Supply Chain Analysis
Single-source vulnerability sits with fentanyl base production clusters in Hyderabad and Mumbai that supply patch manufacturers worldwide. Raw material dependencies include hyaluronic acid for dissolvable microneedles, medical-grade silicones for adhesive layers, and polyimide films for reservoir membranes. Tariff exposure on Chinese-sourced active pharmaceutical ingredients creates supply chain risk for European and North American formulators. Distribution runs through hospital integrated delivery networks in the United States and Germany, with home healthcare channels capturing growing volume share through remote patient monitoring partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EMA MDR compliance costs and ISO 10993 testing requirements force capital-constrained single-product vendors toward exit or acquisition.
For Market Incumbents: Anchor manufacturing scale in Osaka or Daejeon to capture microneedle platform growth while defending against Korean device innovators. Deepen backward integration into adhesive polymer production to offset raw material qualification cost inflation from REACH compliance. Prioritize hospital system partnership consolidation through integrated delivery network bundling that displaces single-product competitors. For New Entrants and Emerging Players: Dissolvable microneedle arrays for insulin delivery represent the most penetrable white-space target given South Korean government R&D consortium acceleration and Danish pilot program validation. Target home healthcare channels in the Netherlands where remote patient monitoring integration creates new procurement entry points. Lead with biosensor-enabled closed-loop systems that command premium positioning outside commoditized patch tiers. For Investors and Strategic Acquirers: Re-rating potential sits with microneedle platform specialists given Japanese PMDA Sakigake fast-track designation accelerating regulatory timelines. Long-term viability hinges on therapeutic addressable market expansion beyond 500 Dalton macromolecule limits through active enhancement convergence. Watch iontophoresis-sonophoresis device approvals as the inflection signal for capital reallocation from passive to active delivery platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Microneedle Platform Scale-Up | Dissolvable array production in Seoul and Daejeon enables vaccine and biologic delivery previously restricted to injection. |
| EMA MDR Compliance Investment | ISO 10993 testing laboratory certification in Frankfurt filters European supplier pools and accelerates notified body engagement. |
| Hospital System Partnership | Integrated delivery network bundling in Chicago and Nashville concentrates volume with full-portfolio pain management suppliers. |
| Active Enhancement Convergence | Iontophoresis-sonophoresis combination devices in Tokyo clinical trials attract foreign sponsors through PMDA Sakigake fast-track. |
| Home Healthcare Channel Expansion | Remote patient monitoring integration in Denmark and Netherlands captures volume from clinic-administered infusion centers. |
Research Methodology
Independent corroboration across FDA 505(b)(2) filing databases, EMA MDR technical documentation submissions, and hospital formulary records underwrites the qualitative findings. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and polymer chemistry specialists combined with secondary validation from ClinicalTrials.gov, SEC 10-K filings, and GPO contract databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation outputs.
Rate-of-change decomposition across technology adoption curves, regulatory pathway acceleration, and channel shift dynamics structured the analytical framework. Segmentation dimensions modeled include product type, application, end user, and technology platform across the analysis window. CAGRs derived from patent filing trajectories, manufacturing capacity announcements, and reimbursement code expansion patterns. Forecast inputs incorporated microneedle clinical trial advancement rates and EMA notified body capacity constraints.
Several conditions sit outside the modeled scope, including unforeseen regulatory pathway reversals, adhesive biocompatibility test standard revisions, and API supply disruptions from geopolitical events. Forecasts reflect documented assumptions about technology maturation timelines and reimbursement code stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Combination Vaccine Market
Pharmaceuticals
Dermatological Drugs Market
Pharmaceuticals
Sarcoidosis Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Omega 3 Prescription Drugs Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Musculoskeletal Disorders Drugs Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Generic Pharmaceuticals Contract Manufacturing Market
Pharmaceuticals
Global Caspofungin Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
Asia Pacific Radiopharmaceuticals Market
Pharmaceuticals
Global Basal Insulin Market
Pharmaceuticals
Cough Cold and Allergy Hay Fever Remedies in Mexico Market
Pharmaceuticals
TNF Inhibitors Market