
 Hydroxychloroquine Drugs Market | 2026-2036
Hydroxychloroquine Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxychloroquine Drugs Market Foresight
Continuous manufacturing technology is rewriting production economics for hydroxychloroquine active pharmaceutical ingredients, enabling faster batch cycles and tighter purity control than conventional batch methods. Sanofi leverages its integrated European manufacturing network to sustain supply security for autoimmune indications. Zydus Cadila anchors its position through backward integration into 4-aminoquinoline chemistry, while Ipca Laboratories dominates API export volumes to regulated markets.
Hydroxychloroquine is a 4-aminoquinoline derivative formulated as the sulfate salt, with tablet specifications typically containing 200 mg of the base compound for oral administration; it functions primarily as an immunomodulatory agent suppressing Toll-like receptor signaling in systemic lupus erythematosus and rheumatoid arthritis. The tablet segment leads volume due to decades of clinical familiarity and stable cold-chain requirements, while the lupus therapy area generates premium pricing through chronic dosing protocols. Retail pharmacies capture the largest margin pool through prescription refill density, though online pharmacies are gaining share among immunocompromised patients prioritizing home delivery.
FDA bioequivalence standards and EMA's active substance master file requirements shape market access for generic entrants, with India's CDSCO imposing additional stability testing for tropical climate zones. The WHO prequalification program influences procurement decisions across malaria-endemic regions, creating tiered quality benchmarks that filter supplier pools. Stakeholders must monitor evolving pharmacovigilance signals around retinal toxicity thresholds, as regulatory repositioning of risk-benefit frameworks could redirect prescribing volumes toward alternative immunomodulators.
Market Dynamics
Continuous manufacturing technology is compressing batch cycle times from weeks to days while tightening purity specifications beyond what conventional batch reactors can achieve. This shift is redrawing capital allocation patterns across API production networks.
Growth Catalysts
- India's PLI scheme:The production-linked incentive program for active pharmaceutical ingredients is redirecting capital toward domestic 4-aminoquinoline synthesis capabilities.
- Chronic lupus protocols:Rheumatology clinics are expanding maintenance dosing regimens that lock patients into long-term prescription cycles.
- EMA active substance master file pathway:Streamlined regulatory documentation is accelerating generic market entry timelines for European hospital tenders.
Market Restraints
- 4-aminoquinoline feedstock concentration:China dominates precursor chemical supply, creating single-source vulnerability for non-integrated manufacturers.
- Retinal toxicity thresholds:FDA and EMA pharmacovigilance reviews are tightening risk-benefit frameworks around long-term dosing.
- Biologic substitution:TNF-alpha inhibitors and IL-6 pathway blockers are capturing refractory rheumatoid arthritis cases.
Strategic Opportunities
- Online pharmacy channel:Home delivery models are capturing immunocompromised patient segments that avoid retail exposure.
- WHO prequalification:The program opens procurement pipelines across malaria-endemic African markets with distinct formulation requirements.
- Continuous processing convergence:Integration of real-time release testing with flow chemistry is enabling point-of-production quality verification.
Industry Challenges
- Process analytical technology talent:The shortage of engineers trained in PAT implementation is delaying continuous manufacturing deployments.
- Cold-chain reconfiguration:Temperature excursion risks during distribution to tropical climate zones demand redundant monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxychloroquine Drugs Market |
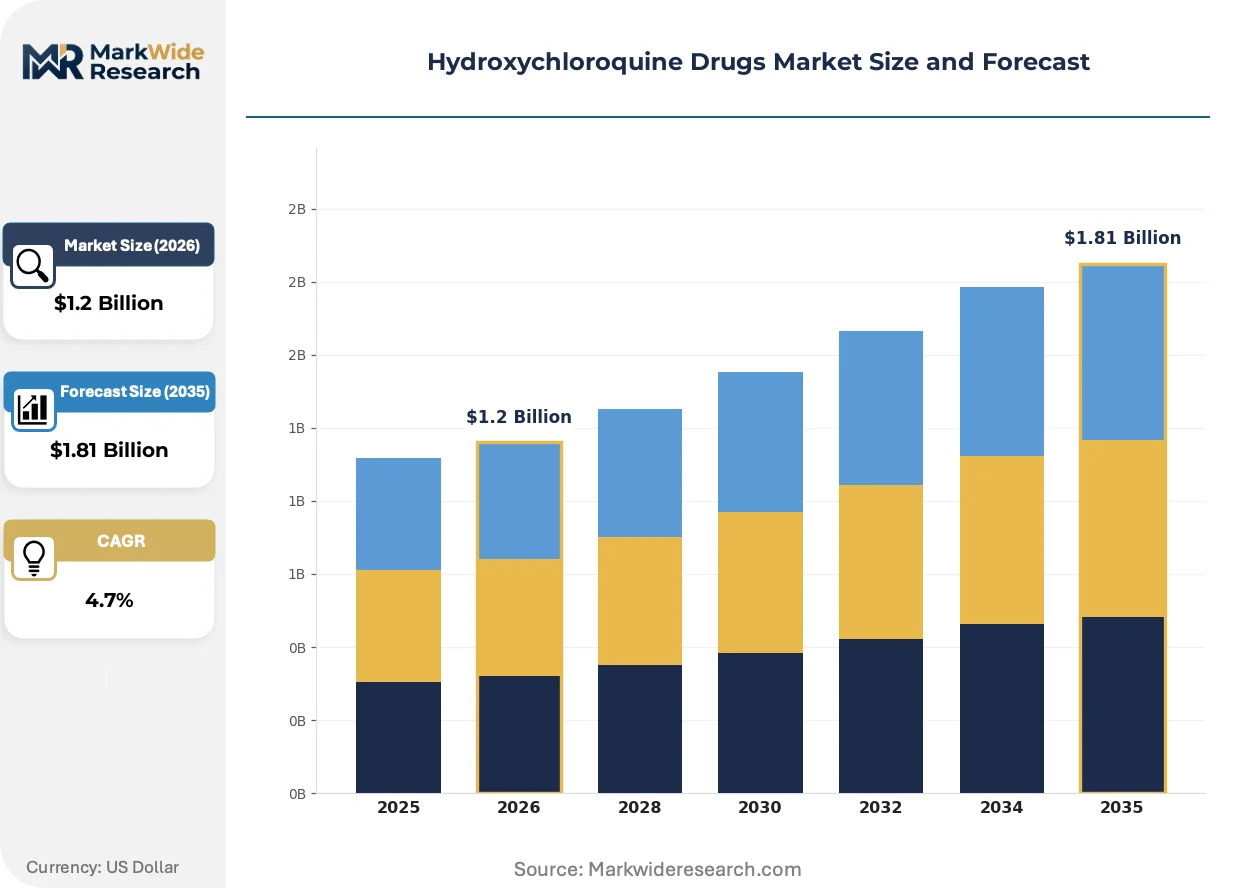
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $1.81 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injections, Oral Solutions, Dosage Forms Therapy Area: Rheumatoid Arthritis, Malaria, Lupus, COVID-19 End User: Hospitals, Clinics, Pharmacies, Homecare Distribution Channel: Online Pharmacies, Retail Pharmacies, Wholesale Distributors, Others |
| Companies Covered | Sanofi, Zydus Cadila, Teva Pharmaceutical Industries, Mylan, Novartis, Ipca Laboratories, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Hikma Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxychloroquine Drugs Market Shifts & Advancements
Digital twin technology is virtualizing process development workflows, allowing manufacturers to simulate scale-up scenarios before committing physical assets. This capability is compressing technology transfer timelines between R&D and commercial production.
Flow chemistry platforms equipped with inline spectroscopic monitoring are virtualizing traditional quality control steps. Mid-sized API producers in India are adopting these systems to meet EMA documentation requirements without building separate QC laboratories. The technology is virtualizing the boundary between manufacturing and testing functions.
EMA's revised active substance master file guidelines are mandating enhanced impurity profiling for 4-aminoquinoline derivatives. Generic sponsors must now submit forced degradation studies under tropical stability conditions. European hospital procurement bodies are filtering supplier pools based on these documentation tiers.
Prescription refill density is concentrating with retail pharmacy chains that offer automated adherence programs. Rheumatology patients in North American markets are migrating toward subscription-based delivery models that synchronize dosing schedules with insurance authorization cycles. This behavioral shift is most visible in lupus therapy segments where compliance directly correlates with flare prevention.
Hydroxychloroquine Drugs Market Segmentation
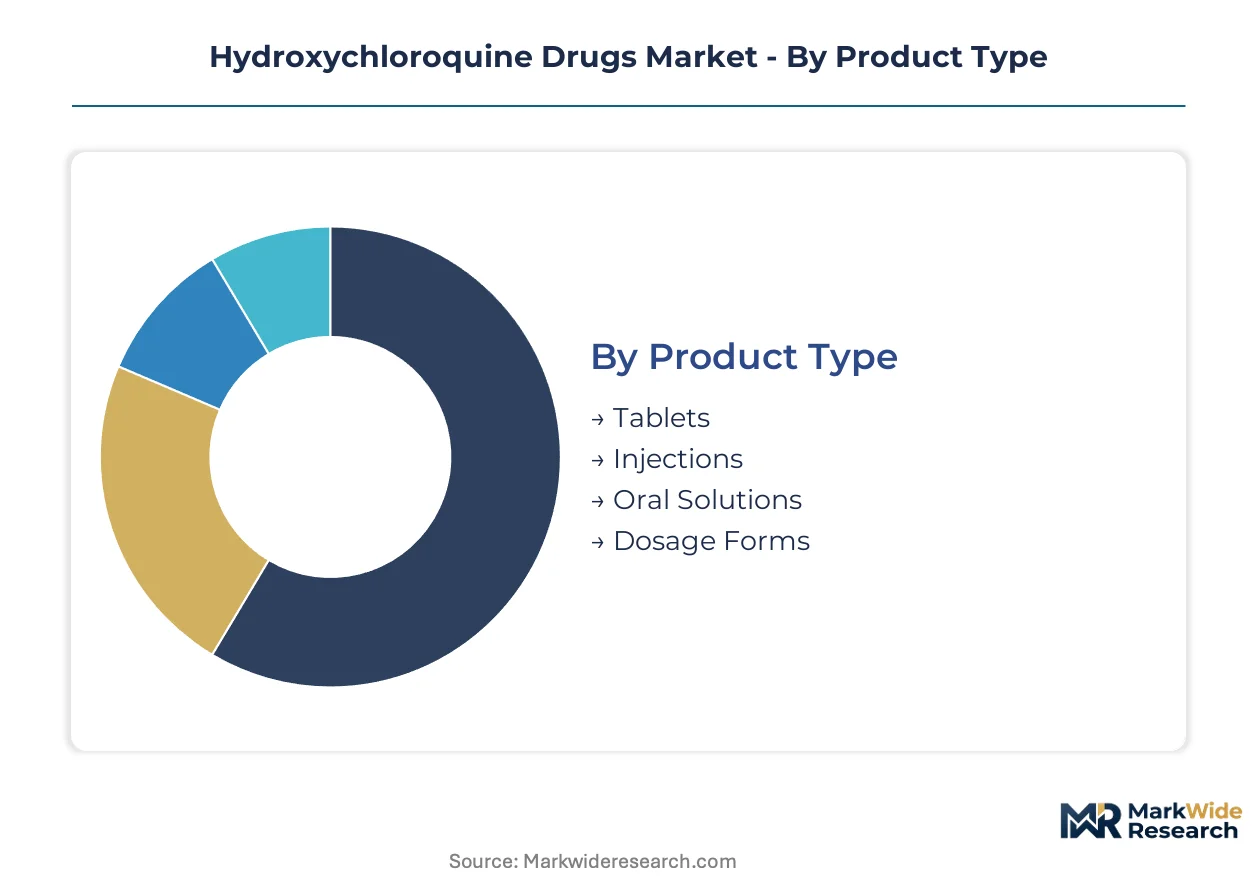
Segmentation in hydroxychloroquine drugs reveals distinct service intensity profiles across formulation types and therapy areas. Tablet formulations demand minimal clinical support, while injectable protocols require intensive nursing oversight and cold-chain logistics.
Product Type:
After-sales service intensity varies sharply across formulation categories, with parenteral forms requiring sustained clinical training support and stability monitoring infrastructure.
- Tablets:The 200 mg base compound sulfate salt dominates prescription volumes through decades of established bioequivalence protocols. North American hospital systems concentrate demand here for lupus maintenance regimens where chronic dosing familiarity reduces adverse event rates.
- Injections:Parenteral formulations serve acute malaria protocols and hospital-confirmed rheumatoid arthritis flares requiring rapid immunomodulatory response. Indian CDSCO mandates additional sterility assurance documentation that filters supplier pools for institutional tenders.
- Oral Solutions:Pediatric and geriatric populations drive demand where swallowing difficulties complicate tablet administration.
- Dosage Forms:Compounding pharmacy preparations address niche weight-based dosing requirements outside standard tablet strengths.
By volume, Tablets lead. By growth pace, Injections are climbing the fastest through hospital formulary expansion.
Therapy Area:
Cost tier stratification separates chronic autoimmune maintenance from acute infectious disease protocols, with lupus therapy commanding premium pricing through indefinite treatment horizons.
- Lupus:Systemic lupus erythematosus maintenance protocols lock patients into multi-year prescription cycles with quarterly ophthalmology monitoring for retinal toxicity. North American rheumatology clinics generate the densest refill concentration through established flare-prevention dosing schedules.
- Rheumatoid Arthritis:Early-stage disease management favors hydroxychloroquine as first-line immunomodulator before biologic escalation. European EMA guidelines emphasize combination therapy with methotrexate that sustains prescription volumes despite TNF-alpha inhibitor competition.
- Malaria:WHO prequalification requirements shape procurement across endemic African regions with distinct formulation stability demands.
- COVID-19:Emergency use authorizations have contracted sharply following regulatory repositioning of risk-benefit frameworks.
By revenue concentration, Lupus dominates. By prescription expansion, Rheumatoid Arthritis is gaining share fastest.
End User:
Customer type determines compliance infrastructure requirements, with homecare segments demanding telemedicine integration and automated refill systems.
- Hospitals:Inpatient formulary control governs acute malaria and severe lupus nephritis protocols. EMA active substance master file compliance filters supplier selection for European hospital tenders where documentation tiers determine procurement eligibility.
- Clinics:Rheumatology and infectious disease specialty practices concentrate chronic disease management with quarterly monitoring requirements.
- Pharmacies:Retail chains capture prescription refill density through automated adherence programs synchronized with insurance cycles.
- Homecare:Immunocompromised patient segments prioritize delivery models that eliminate retail exposure risks.
By prescription volume, Pharmacies lead. By service intensity, Hospitals are expanding their clinical protocol influence.
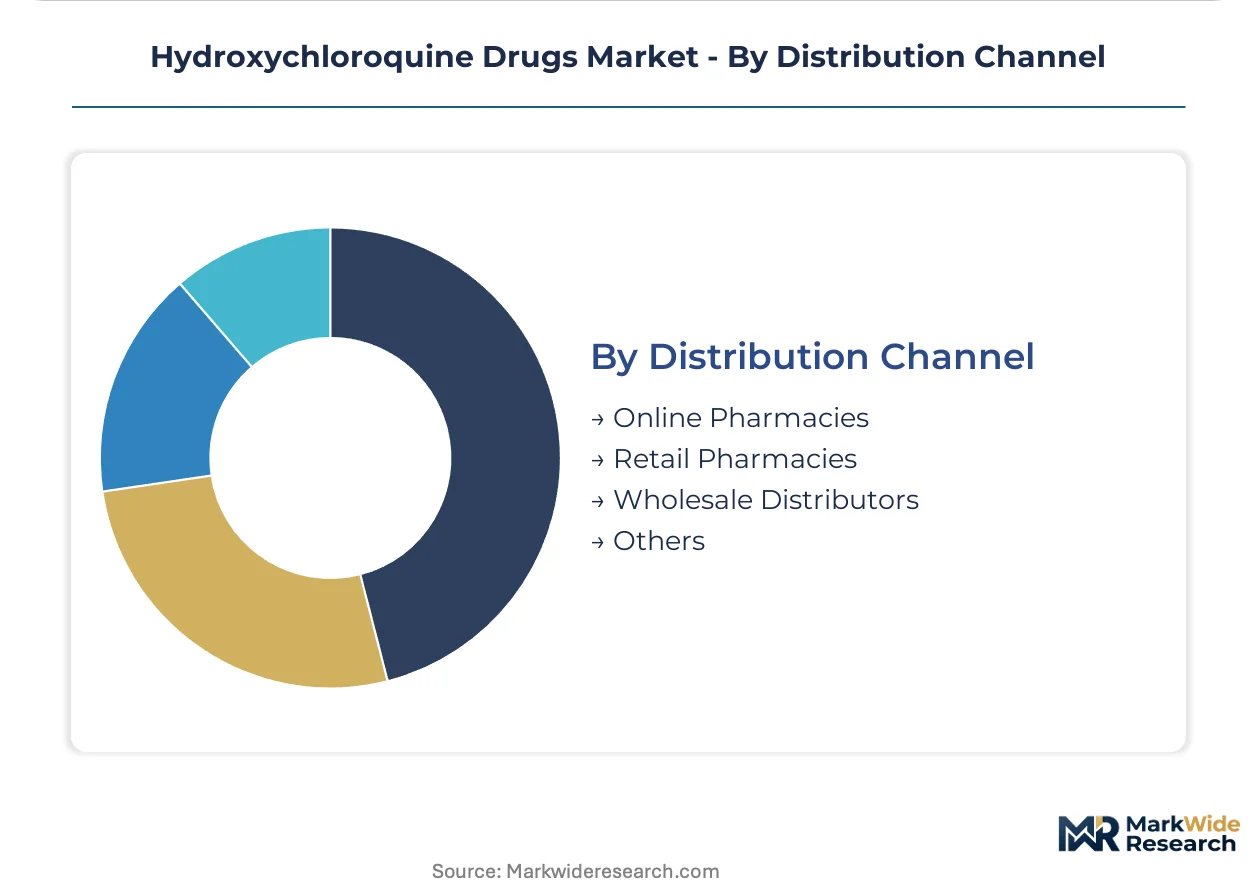
Distribution Channel:
Margin concentration follows channel control over patient data and adherence monitoring capabilities, with direct-to-patient models capturing premium economics.
- Retail Pharmacies:Physical location density determines prescription capture in lupus therapy where same-day access supports compliance. Major chains deploy automated refill synchronization that locks patients into recurring revenue streams.
- Online Pharmacies:Home delivery models expand fastest among immunocompromised populations avoiding infection exposure. India's DGFT e-commerce regulations shape cross-border shipment permissions for API-integrated manufacturers.
- Wholesale Distributors:Institutional procurement consolidation drives volume through centralized hospital system contracts.
- Others:Direct manufacturer programs serve government stockpile requirements and humanitarian procurement pipelines.
By current share, Retail Pharmacies lead. By expansion trajectory, Online Pharmacies are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatology clinics in the United States concentrate the densest prescription refill volumes for lupus maintenance protocols. Hospital systems in Germany and France anchor European autoimmune therapy demand through established formulary control. Indian API manufacturers leverage production-linked incentives to capture export share into regulated markets.
United States
North American hospital systems drive volume through chronic lupus erythematosus maintenance regimens with quarterly ophthalmology monitoring requirements. FDA bioequivalence standards filter generic market entry for 200 mg tablet formulations. The Boston-Cambridge corridor concentrates rheumatology research institutions that shape clinical dosing protocols adopted nationwide.
Germany
EMA active substance master file compliance determines supplier eligibility for European hospital procurement tenders. German rheumatology clinics favor combination therapy protocols with methotrexate that sustain hydroxychloroquine prescription cycles. The Rhine-Main industrial cluster hosts pharmaceutical distributors coordinating centralized purchasing for hospital networks across Central Europe.
India
CDSCO stability testing mandates for tropical climate zones shape export documentation requirements for API manufacturers. India's PLI scheme redirects capital toward domestic 4-aminoquinoline synthesis capabilities. The Hyderabad-Visakhapatnam pharmaceutical belt anchors active pharmaceutical ingredient production with backward-integrated feedstock control.
France
ANSM pharmacovigilance reviews influence retinal toxicity monitoring thresholds across European prescribing guidelines. French hospital systems concentrate demand for injectable formulations during acute rheumatoid arthritis flares. The Paris-Saclay biocluster hosts regulatory consulting firms specializing in EMA documentation for generic sponsors.
United Kingdom
NHS formulary committees govern hydroxychloroquine placement in rheumatoid arthritis treatment pathways before biologic escalation. MHRA post-Brexit regulatory divergence creates separate approval timelines from EMA centralized procedures. The Golden Triangle research corridor influences lupus clinical trial design that propagates through European treatment protocols.
Hydroxychloroquine Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation and therapy area segments. The vendor base organizes around three archetypes: integrated pharmaceutical conglomerates with European manufacturing networks, Indian API-integrated generic specialists with backward feedstock control, and regional hospital-supply distributors with formulary access. Consolidation pressure operates through M&A activity targeting EMA documentation capabilities and strategic partnerships securing 4-aminoquinoline precursor supply.
Within the integrated multinational tier, Sanofi anchors European supply security through manufacturing network control. Among Indian API-integrated specialists, Zydus Cadila and Ipca Laboratories occupy positions exemplifying backward integration into 4-aminoquinoline chemistry. These companies represent the archetype of export-focused manufacturers leveraging domestic synthesis capabilities to meet regulated market documentation requirements.
| Leading Market Players |
|---|
| Sanofi |
| Zydus Cadila |
| Teva Pharmaceutical Industries |
| Mylan |
| Novartis |
| Ipca Laboratories |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Hikma Pharmaceuticals |
| Others |
Supply & Pricing Matrix
Single-source dependency on Chinese 4-aminoquinoline precursor supply compresses margin spreads between integrated and non-integrated manufacturers while forcing pricing tier differentiation around feedstock security. This structural vulnerability elevates API producers with backward-integrated chemistry into premium contract positions while squeezing pure-formulation players into spot-market volatility.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient indexation dominate hospital procurement agreements, locking in quarterly price adjustments tied to 4-aminoquinoline feedstock movements. Price differentiation separates EMA-ASMF documented suppliers from CDSCO-only certified producers, with the former commanding 15-20% contract premiums through regulatory filing depth. Pricing pressure stems from biologic substitution in refractory rheumatoid arthritis cases, eroding volume-based discounts in European tenders. Hospital systems exhibit lowest price sensitivity due to formulary control and chronic patient lock-in, while retail pharmacy chains negotiate aggressively on refill density rebates.
Supply Chain Analysis
Upstream 4-aminoquinoline chemistry concentrates in Chinese specialty chemical manufacturers, Indian API-integrated producers, and European captive synthesis operations. Raw material dependencies include 4,7-dichloroquinoline, hydroxyaniline derivatives, and pharmaceutical-grade sulfuric acid for salt formation. Single-source vulnerability in Chinese precursor supply creates tariff exposure risk for non-integrated formulation houses. Distribution runs through wholesale distributors serving hospital networks, with direct-to-pharmacy models gaining traction among immunocompromised patient segments prioritizing delivery reliability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in hydroxychloroquine concentrate around automated adherence monitoring and ophthalmology coordination platforms, with recurring-revenue per-patient metrics expanding faster than tablet unit economics alone.
For Market Incumbents: Build regulatory documentation moats through EMA active substance master file tier advancement and CDSCO tropical stability certification depth. Deepen backward integration into 4-aminoquinoline chemistry to neutralize Chinese feedstock volatility. Secure formulary control through integrated adherence platform deployment that locks rheumatology clinics into multi-year service contracts. For New Entrants and Emerging Players: Pursue WHO prequalification pathways for malaria-endemic African procurement pipelines where documentation barriers filter incumbent competition. Target online pharmacy channel partnerships serving immunocompromised home-delivery segments with limited incumbent presence. Anchor market entry through continuous manufacturing technology differentiation that compresses batch cycle economics below conventional reactor benchmarks. For Investors and Strategic Acquirers: API-integrated generic specialists with EMA documentation capabilities and captive 4-aminoquinoline synthesis represent the most defensible acquisition archetype against biologic substitution headwinds. Long-term viability hinges on chronic lupus protocol durability and regulatory risk-benefit framework stability. Monitor FDA pharmacovigilance signals on retinal toxicity threshold repositioning as the critical inflection indicator for prescription volume trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Active Substance Master File Advancement | Unlocks European hospital tender eligibility through streamlined regulatory documentation pathways. |
| Backward Integration into 4-Aminoquinoline Chemistry | Neutralizes Chinese precursor supply vulnerability while capturing API margin pool expansion. |
| Continuous Manufacturing Technology Deployment | Compresses batch cycle timelines and enables real-time release testing for quality verification. |
| Online Pharmacy Channel Partnership | Captures immunocompromised patient segments prioritizing home delivery over retail exposure. |
| WHO Prequalification Program Entry | Opens procurement pipelines across malaria-endemic African markets with distinct formulation requirements. |
Research Methodology
A standing panel of rheumatology clinic directors, hospital formulary managers, API manufacturing executives, and regulatory affairs specialists provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with these stakeholder categories against FDA 483 inspection observations, EMA assessment reports, CDSCO export documentation requirements, and WHO prequalification product dossiers. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical trade flow analysis.
Scenario-bracketing around regulatory risk-benefit repositioning and biologic substitution velocity shaped the analytical framework across the projection horizon. Segmentation dimensions included formulation type, therapy area, end-user channel, and regional regulatory cluster. CAGRs derived from patient population epidemiology, dosing protocol persistence, and pricing trajectory assumptions specific to autoimmune maintenance regimens.
Sensitivities concentrate around FDA retinal toxicity threshold revisions, EMA impurity profiling guideline changes, and Chinese 4-aminoquinoline export restriction scenarios. Forecasts reflect documented assumptions on chronic disease protocol durability and generic entry timeline compression. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Drug Repurposing Market
Pharmacology
Olanzapine API Market
Pharmacology
Apixaban Market
Pharmacology
Clot Busting Drugs Market
Pharmacology
Immunotherapy Drugs Market
Pharmacology
Injectable Drugs Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Drug Eruptions Treatment Market
Pharmacology
Antimycotics Market
Pharmacology
Attention Deficit Hyperactivity Disorder (ADHD) Therapeutics Market
Pharmacology
Drug Delivery Across the Blood-Brain Barrier Market
Pharmacology
Alzheimer Drugs Market
Pharmacology
Thromboprophylactic Drugs Market
Pharmacology
ACE Inhibitors Market
Pharmacology
Hypertension Drug Market