
 Enteric Empty Capsules Sales Market | 2026-2036
Enteric Empty Capsules Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Enteric Empty Capsules Sales Market Analysis
Pharmaceutical-grade HPMC specifications is reorganizing procurement priorities across the enteric empty capsules value chain. Lonza Group Ltd. leverages its integrated capsule-polymer platform to control supply consistency for European and North American drug developers. ACG sustains manufacturing scale across multiple continents, anchoring volume contracts with multinational pharmaceutical companies. Suheung specializes in precision enteric coating technologies, differentiating its output for probiotic and enzyme applications where gastric survival rates determine commercial viability.
Enteric empty capsules are dosage form shells engineered to resist gastric acid degradation and dissolve at intestinal pH thresholds, typically constructed from hydroxypropyl methylcellulose or gelatin substrates with polymethacrylate-based coating systems. Their primary purpose is to protect acid-labile active ingredients from stomach denervation while enabling targeted release in the duodenum or jejunum. Gelatin retains volume leadership in established markets where cost sensitivity and decades of regulatory familiarity preserve its position, while HPMC is capturing accelerated interest from vegan-formulation nutraceutical companies and halal-certification-driven pharmaceutical procurement in Southeast Asia. The probiotics application segment is expanding fastest as live microbial therapeutics advance through clinical pipelines, creating specialized demand for capsules with validated gastric resistance exceeding two hours.
The US FDA enforces dissolution profile standards through its Center for Drug Evaluation and Research, directly shaping capsule qualification requirements for abbreviated new drug applications. India's CDSCO and BIS jointly govern enteric capsule imports through mandatory dissolution testing protocols and polymer safety certifications, raising barriers for uncertified suppliers. The EU's EMA maintains harmonized pharmacopeial standards via the European Pharmacopoeia, ensuring cross-border capsule acceptance while the MDR extends quality traceability expectations to contract manufacturers. Stakeholders must monitor how tightening dissolution specification bands and polymer sourcing disclosure rules reshape supplier qualification timelines and captive manufacturing decisions.
Market Dynamics
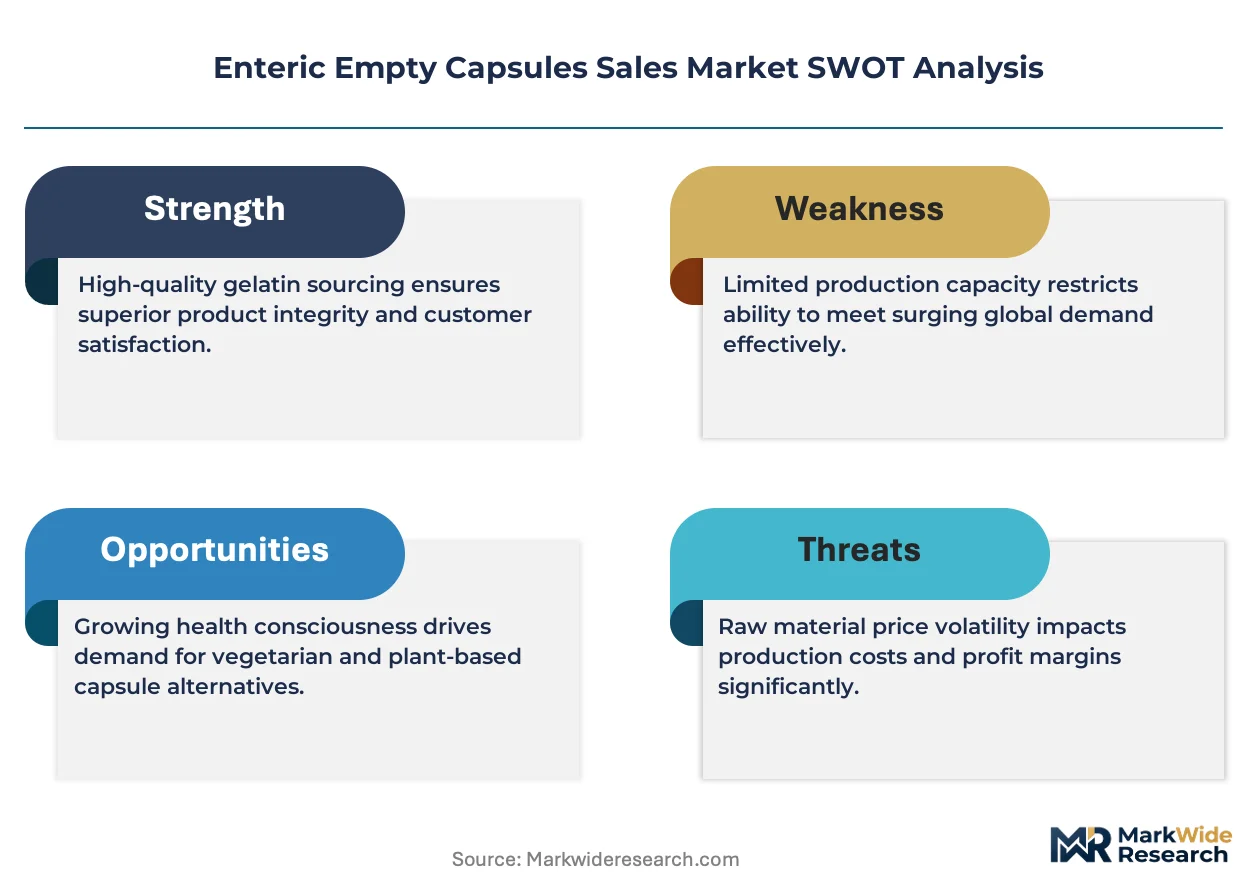
Pharmaceutical-grade HPMC specifications is reorganizing procurement priorities across the enteric empty capsules value chain. Lonza Group Ltd. leverages its integrated capsule-polymer platform to control supply consistency for European and North American drug developers. ACG sustains manufacturing scale across multiple continents, anchoring volume contracts with multinational pharmaceutical companies. Suheung specializes in precision enteric coating technologies, differentiating its output for probiotic and enzyme applications where gastric survival rates determine commercial viability.
Growth Catalysts
- CDSCO Accelerated Approval Pathways:India's streamlined complex generic reviews are pulling contract manufacturers toward domestic capsule sourcing under the PLI scheme for active pharmaceutical ingredients.
- Live Microbial Therapeutics Pipeline:Probiotic and enzyme applications are creating specialized demand for capsules with validated gastric resistance exceeding two hours.
- HPMC Polymer Substitution:Vegan-formulation nutraceutical companies and halal-certification-driven pharmaceutical procurement in Southeast Asia are accelerating HPMC adoption over gelatin substrates.
Market Restraints
- Gelatin Raw Material Volatility:Bovine and porcine collagen supply fluctuations from concentrated rendering operations in Brazil and Argentina create input cost instability for traditional capsule manufacturers.
- Polymethacrylate Coating Supply Concentration:European chemical suppliers dominate specialized enteric polymer production, exposing capsule coaters to single-source risk during REACH regulatory transitions.
- Dissolution Testing Standard Divergence:The US FDA's evolving gastric resistance benchmarks conflict with EMA harmonized pharmacopeial standards, forcing dual qualification protocols for multinational suppliers.
Strategic Opportunities
- Indian Domestic Sourcing Mandates:The PLI scheme's localization incentives are creating captive manufacturing opportunities for enteric capsule producers serving CDSCO-regulated drug developers.
- Biologics Cold Chain Integration:Acid-sensitive biologics requiring enteric protection are converging with temperature-controlled logistics, enabling capsule suppliers to bundle gastric resistance with thermal stability validation.
- Halal Certification Premium Tier:Southeast Asian pharmaceutical procurement is segmenting around religious compliance, rewarding suppliers with dual HPMC-halal certification above standard gelatin pricing.
Industry Challenges
- Dissolution Methodologist Talent Scarcity:The specialized skill set for USP <711> and <724> apparatus operation is concentrating in legacy pharmaceutical hubs, constraining new facility staffing.
- Polymer Sourcing Disclosure Burden:EMA's extended quality traceability expectations under MDR are forcing contract manufacturers to reconfigure supplier qualification timelines for coating raw materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enteric Empty Capsules Sales Market |
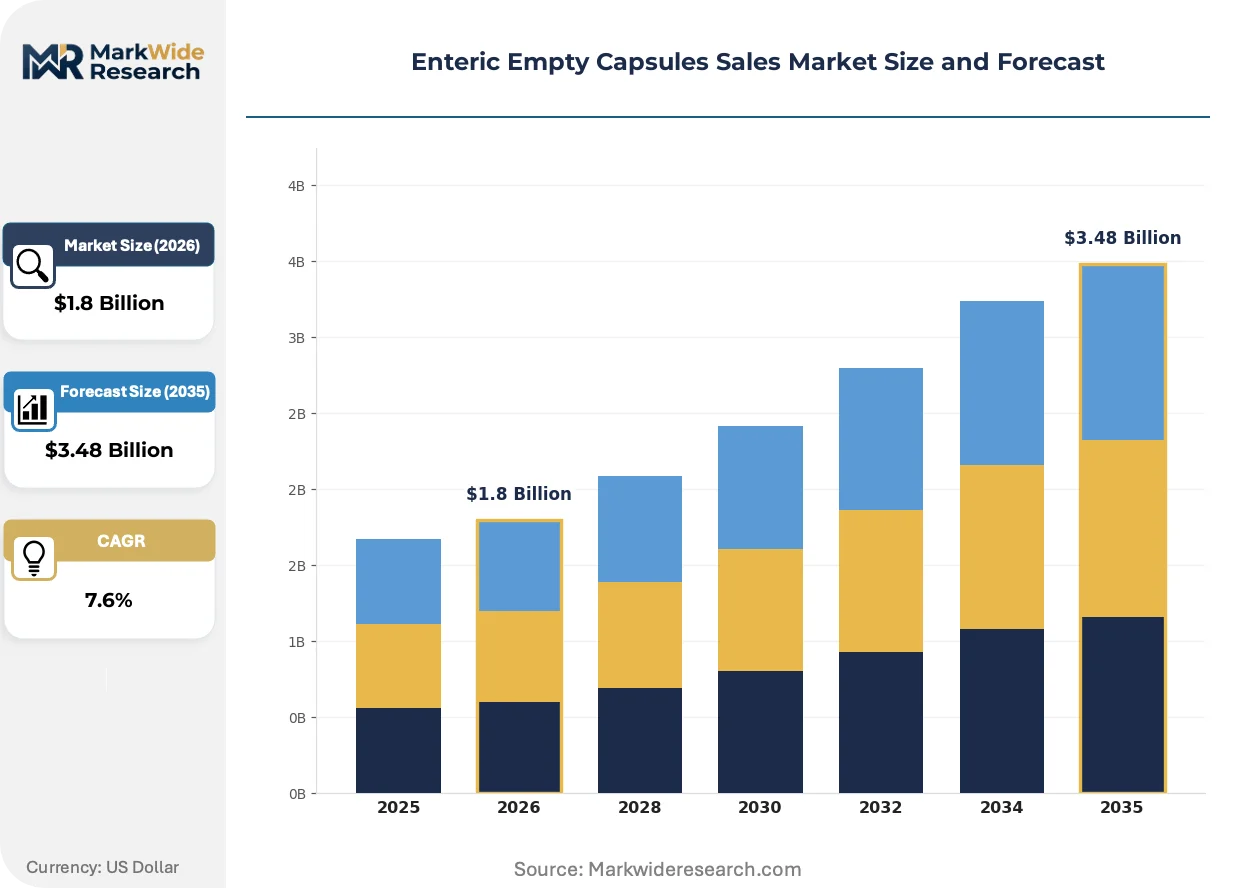
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, HPMC, Pullulan, Others End User: Pharmaceutical Companies, Nutraceutical Companies, Contract Manufacturers, Research Institutions Distribution Channel: Online Retail, Pharmacy, Direct Sales, Distributors Application: Enteric Coated Drugs, Dietary Supplements, Probiotics, Antacids |
| Companies Covered | Lonza Group Ltd., ACG, Roquette Frères, Qualicaps, Suheung, Nectar Lifesciences Ltd., Natural Capsules Limited, Anhui Huangshan Capsule Co., Ltd., CapsCanada Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enteric Empty Capsules Sales Market Emerging Trajectories
Coating technology architectures are fragmenting along performance-versus-cost fault lines as probiotic applications demand validated gastric survival metrics. Material science advances and regulatory disclosure mandates are simultaneously compressing formulation flexibility while opening certification-driven premium tiers.
HPMC substrate technology is bifurcating the enteric capsule market between legacy gelatin volumes and vegan-certified premium supply. Nutraceutical formulators in Germany and the United States are adopting HPMC at accelerated pace for clean-label positioning. This bifurcation is compressing gelatin's share in halal-sensitive procurement while enabling price stratification around religious and dietary certification tiers.
The EU's MDR extended quality traceability expectations are reshaping polymer sourcing disclosure rules for contract manufacturers. Industrial consequence includes mandatory batch-level documentation for polymethacrylate coating systems entering European pharmaceutical supply chains. Small and mid-sized capsule suppliers in India are responding by consolidating coating operations under centralized BIS-certified facilities to manage compliance overhead.
Buyer concentration among multinational pharmaceutical companies is consolidating volume contracts around suppliers with integrated polymer-capsule platforms. Direct sourcing agreements are displacing distributor-mediated procurement for enteric capsules in North American and European markets. This concentration is most visible in Germany and Switzerland, where Lonza's integrated manufacturing anchors multi-year supply commitments from biologics developers.
Enteric Empty Capsules Sales Market Segmentation
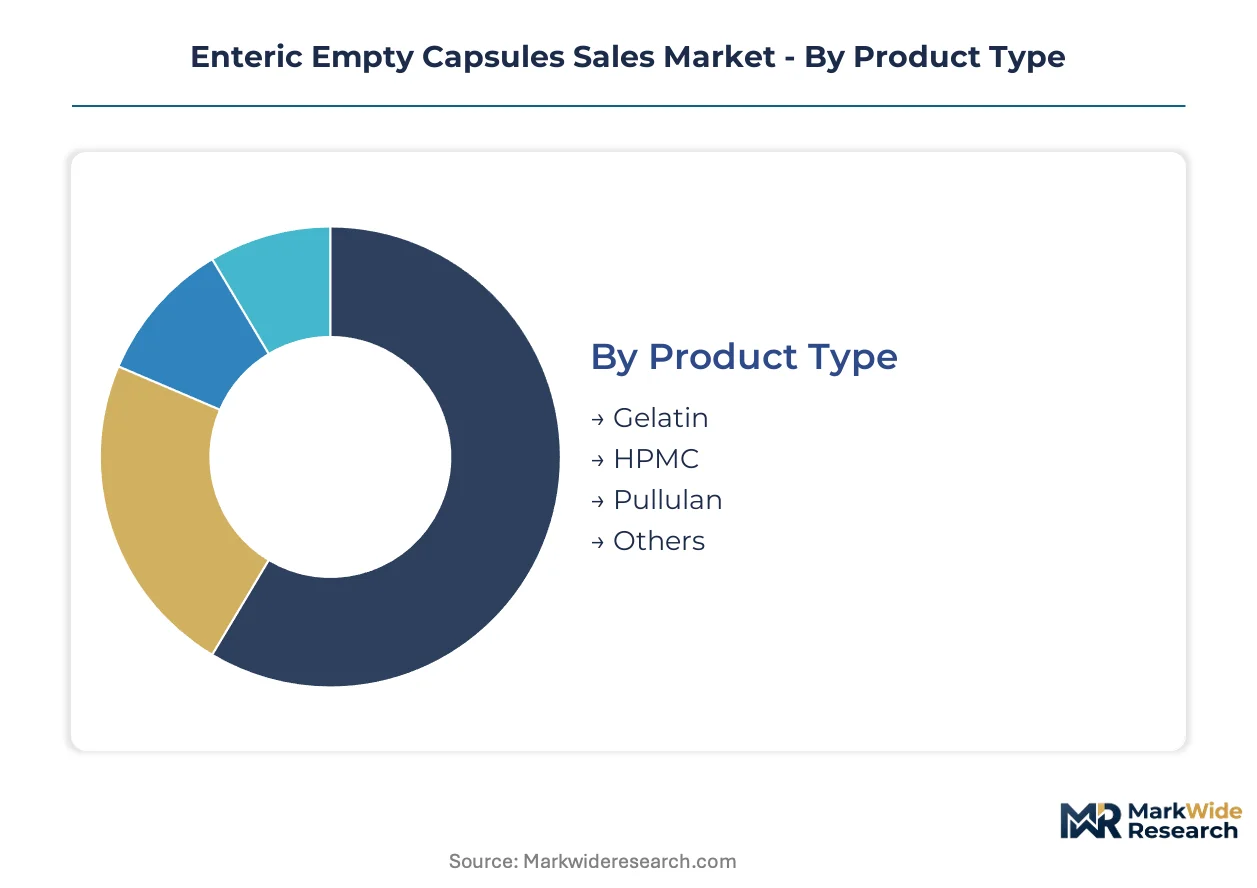
Enteric capsule procurement diverges sharply across substrate chemistry, end-use regulatory intensity, and channel control requirements. Each segmentation dimension reveals distinct margin architecture and supplier qualification barriers.
Product Type:
Premium margin pools concentrate in polymer platforms offering certification-tier differentiation and supply security.
- HPMC:Cellulose-based shells eliminate animal-derived inputs entirely, enabling vegan-label positioning and halal-kosher compliance without secondary certification layers. Demand clusters in Southeast Asian pharmaceutical procurement where religious compliance commands price premiums above standard gelatin sourcing.
- Gelatin:Bovine and porcine collagen substrates retain volume leadership through decades of dissolution validation and established USP monograph familiarity. Cost sensitivity in Indian contract manufacturing preserves gelatin's position despite raw material volatility from Brazilian and Argentine rendering operations.
- Pullulan:Fermented polysaccharide shells offer superior oxygen barrier properties for oxidation-sensitive actives.
- Others:Starch and carrageenan alternatives serve niche clean-label nutraceutical positioning.
Gelatin holds installed capacity. HPMC is rotating up the share rankings.
End User:
Volume concentration tracks regulatory filing intensity and dissolution testing sophistication.
- Pharmaceutical Companies:ANDA and NDA filers demand batch-level dissolution documentation and polymer traceability under FDA Center for Drug Evaluation and Research protocols. Direct sourcing agreements with integrated capsule-polymer platforms displace distributor relationships for gastric resistance validation.
- Contract Manufacturers:CDSCO-registered facilities in India face PLI scheme localization incentives pulling toward domestic capsule sourcing. Multi-continent manufacturing scale anchors volume contracts with multinational sponsors requiring harmonized EMA-FDA qualification.
- Nutraceutical Companies:German and US formulators adopt HPMC at accelerated pace for clean-label consumer positioning.
- Research Institutions:Preclinical and Phase I suppliers prioritize gastric resistance validation over commercial-scale coating consistency.
Pharmaceutical companies hold installed capacity. Contract manufacturers are rotating up the share rankings.
Distribution Channel:
Channel economics split between specification complexity and order fragmentation.
- Direct Sales:Integrated polymer-capsule platforms anchor multi-year supply commitments through dissolution profile co-development. Biologics developers in Germany and Switzerland bypass distribution layers for gastric resistance specification alignment.
- Distributors:Mid-tier capsule coaters in India consolidate coating operations under centralized BIS-certified facilities to manage EMA MDR compliance overhead for European-bound shipments.
- Online Retail:Small-batch nutraceutical formulators source standard enteric specifications without qualification documentation.
- Pharmacy:Compounding pharmacies access capsule shells through regional medical distributors.
Direct sales hold installed capacity. Distributor-mediated procurement is rotating up the share rankings in mid-tier supply.
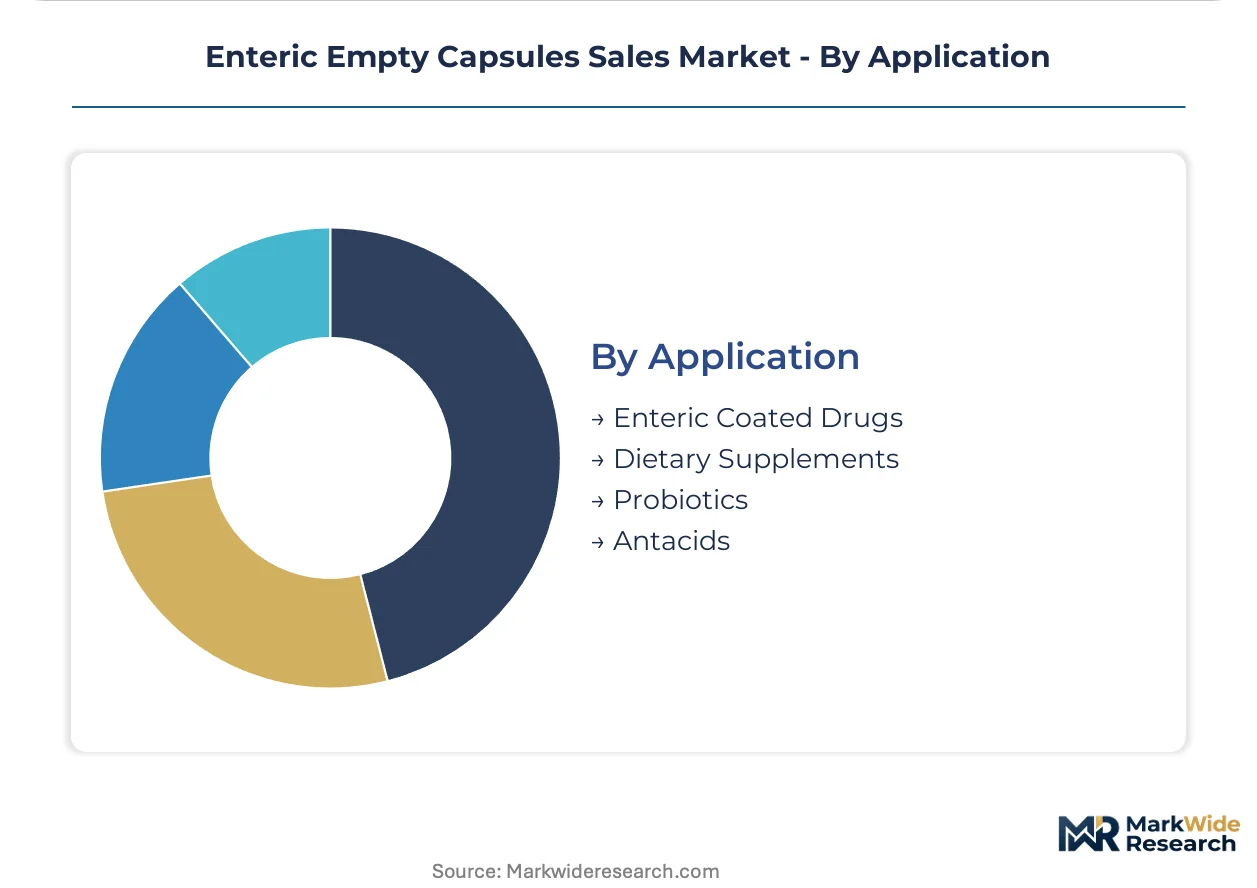
Application:
Performance validation requirements create steepest expansion trajectory in live microbial delivery.
- Probiotics:Live microbial therapeutics demand validated gastric resistance exceeding two hours with intestinal release precision. Suheung's coating technology differentiation targets enzyme and probiotic applications where survival rates determine commercial viability and repeat purchase.
- Enteric Coated Drugs:Acid-labile small molecules and biologics require duodenal or jejunal release with USP <711> dissolution profile documentation. FDA evolving gastric resistance benchmarks force dual qualification protocols for multinational suppliers serving US and European markets simultaneously.
- Dietary Supplements:Clean-label positioning drives HPMC substitution in German and US nutraceutical formulation.
- Antacids:Standard enteric protection for acid suppression actives faces generic pricing pressure.
Enteric coated drugs hold installed capacity. Probiotics are climbing the fastest among application segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in enteric empty capsules tilt toward manufacturing hubs with integrated polymer supply chains and regulatory validation infrastructure. India and China supply volume to North American and European drug developers, while Switzerland and Germany anchor premium-tier procurement for biologics applications.
United States
FDA Center for Drug Evaluation and Research dissolution protocols drive qualification requirements for abbreviated new drug applications. The agency's evolving gastric resistance benchmarks force dual certification for suppliers serving US and European markets simultaneously. New Jersey and Massachusetts pharmaceutical clusters source directly from integrated capsule-polymer platforms to bypass distribution layers.
Germany
Nutraceutical formulators adopt HPMC substrates at accelerated pace for clean-label consumer positioning. EMA harmonized pharmacopeial standards via the European Pharmacopoeia ensure cross-border capsule acceptance while MDR extends quality traceability to contract manufacturers. Bavaria's biologics developers anchor multi-year supply commitments through dissolution profile co-development with specialized suppliers.
India
CDSCO accelerated approval pathways for complex generics pull contract manufacturers toward domestic capsule sourcing. The PLI scheme for active pharmaceutical ingredients creates captive manufacturing opportunities for enteric capsule producers serving regulated drug developers. Maharashtra and Gujarat pharmaceutical manufacturing belts consolidate coating operations under centralized BIS-certified facilities.
Switzerland
Swissmedic maintains stringent batch-level documentation requirements for polymethacrylate coating systems entering pharmaceutical supply chains. The country's precision manufacturing heritage supports premium-tier capsule procurement for enzyme and probiotic applications where gastric survival rates determine commercial viability. Basel's biotech cluster demands validated gastric resistance exceeding two hours for live microbial therapeutics.
China
NMPA governance of pharmaceutical excipients raises barriers for uncertified capsule suppliers while domestic HPMC production scales to meet Southeast Asian halal-certification-driven demand. Anhui province capsule manufacturers serve both export markets and domestic nutraceutical formulators seeking cost-competitive enteric protection. Yangtze River Delta pharmaceutical clusters integrate regional polymer sourcing with dissolution testing capabilities.
Enteric Empty Capsules Sales Market Vendor Landscape
Concentration sits with integrated polymer-capsule platforms that control supply consistency across dissolution validation and regulatory qualification. The vendor base stratifies between multinational chemical-pharmaceutical conglomerates with backward integration into HPMC production and specialized coating technology houses serving probiotic applications. Two strategic archetypes dominate: scale-driven integrated manufacturers anchoring volume contracts with direct sales relationships, and precision coating specialists differentiating on gastric survival metrics for live therapeutics. Competitive moves center on geographic expansion into Indian PLI scheme zones and portfolio diversification toward halal-certified HPMC tiers.
Among the integrated platform operators, Lonza Group Ltd. and ACG exemplify the scale-driven archetype with multi-continent manufacturing footprints. Suheung occupies a specialist position within the precision coating tier. These three names illustrate how competitive positioning fragments between volume-contract anchoring and technology differentiation for acid-sensitive biologics applications.
| Leading Market Players |
|---|
| Lonza Group Ltd. |
| ACG |
| Roquette Frères |
| Qualicaps |
| Suheung |
| Nectar Lifesciences Ltd. |
| Natural Capsules Limited |
| Anhui Huangshan Capsule Co., Ltd. |
| CapsCanada Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between multinational pharmaceutical companies and integrated capsule-polymer platforms lock in supply access while providing price visibility across volatile HPMC and gelatin input cycles. These arrangements concentrate procurement power with buyers in Germany and Switzerland who demand batch-level dissolution documentation, while Indian contract manufacturers under CDSCO oversight negotiate spot-adjacent terms for domestic sourcing mandates.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with tiered pricing separating halal-certified HPMC premiums from standard gelatin volumes. Price differentiation hinges on certification grade for religious compliance and volume scale for multi-year commitments. Cost compression in gelatin tiers is intensifying because bovine and porcine collagen supply fluctuations from Brazilian rendering operations create input instability. Contract manufacturers in India exhibit highest price sensitivity, while Swiss biologics developers accept premium positioning for validated gastric resistance exceeding two hours.
Supply Chain Analysis
India and China anchor enteric capsule manufacturing for export markets, while Switzerland and Germany concentrate premium-tier production for biologics applications. Raw material dependencies center on pharmaceutical-grade HPMC from cellulose processors, bovine and porcine collagen from Argentine and Brazilian rendering operations, and polymethacrylate coating systems from European chemical suppliers. Single-source vulnerability in specialized enteric polymer production exposes coaters to REACH regulatory transition risks. Distribution runs through direct sales relationships with integrated platforms for multinational pharmaceutical companies, while mid-tier Indian suppliers consolidate under centralized BIS-certified facilities for European-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in enteric capsules is reaching an inflection as integrated polymer-capsule systems displace distributor-mediated procurement, with interoperability between dissolution validation and regulatory qualification becoming the decisive competitive moat.
For Market Incumbents: Fortify backward integration into HPMC production to control supply consistency amid raw material volatility from concentrated rendering operations. Expand BIS-certified coating capacity in Maharashtra and Gujarat to capture PLI scheme localization incentives pulling contract manufacturers toward domestic sourcing. Certification investment in dual HPMC-halal tiers secures premium positioning against gelatin substitution threats in Southeast Asian procurement. For New Entrants and Emerging Players: Precision coating services for probiotic applications represent a service-layer gap where incumbents under-serve live microbial therapeutics developers requiring validated gastric resistance exceeding two hours. Target CDSCO-registered contract manufacturers in India seeking dissolution testing outsourcing to avoid capital-intensive in-house apparatus investment. A co-development go-to-market angle with biologics startups in Basel and Boston bypasses entrenched direct sales relationships. For Investors and Strategic Acquirers: Specialized coating technology houses with validated gastric survival metrics command acquisition interest as live therapeutics pipelines advance. Long-term viability hinges on differentiation durability against integrated platform scale advantages over a five-to-ten year horizon. The signal to watch is FDA-EMA dissolution standard convergence or divergence, which would reshape dual qualification overhead and supplier consolidation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HPMC Production | Captive supply of pharmaceutical-grade cellulose reduces exposure to gelatin raw material volatility from Brazilian rendering. |
| Halal Certification Program | Dual HPMC-halal tiers capture price premiums in Southeast Asian pharmaceutical procurement above standard gelatin sourcing. |
| CDSCO Registration Pathway | Domestic capsule qualification under India's accelerated approval protocols anchors volume contracts with PLI scheme beneficiaries. |
| Dissolution Testing Co-Development | USP 711 and 724 apparatus partnerships with biologics developers in Germany and Switzerland lock in multi-year supply commitments. |
| Centralized BIS-Certified Facility Consolidation | Single-site coating operations manage EMA MDR compliance overhead for polymethacrylate traceability in European-bound shipments. |
Methodological Framework
A spread of perspectives from pharmaceutical procurement directors, CDSCO regulatory affairs leads, capsule manufacturing plant managers, and biologics formulation scientists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA Center for Drug Evaluation and Research dissolution protocols, EMA European Pharmacopoeia standards, CDSCO complex generic approval databases, and BIS polymer safety certifications. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates across substrate chemistry and application segments.
Segmentation dimensions modeled include substrate type, end-user regulatory intensity, distribution channel control requirements, and application performance validation tiers across the projection horizon. CAGRs were derived from weighted scenario analysis incorporating live microbial therapeutics pipeline advancement, PLI scheme localization pull, and HPMC substitution trajectories in halal-sensitive procurement. Industry-specific forecast inputs center on dissolution testing standard evolution and polymethacrylate coating supply concentration dynamics.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO dissolution protocols; material policy shifts in gastric resistance benchmarks or polymer sourcing disclosure rules would require re-modeling. Specific risks that could revise projections include REACH regulatory transitions disrupting European chemical supplier relationships, gelatin raw material export restrictions from South American rendering operations, and divergence between USP and Ph. Eur. dissolution specifications forcing dual qualification cost escalation. Recalibration cycles align with material shifts in regulatory guidance releases, live therapeutics commercialization milestones, and PLI scheme incentive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Global Eylea Market
Pharmaceuticals
Calcimimetic Market
Pharmaceuticals
Asia-Pacific Contraceptives Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Dopamine and Norepinephrine Reuptake Inhibitor Market
Pharmaceuticals
MRSA Antibiotic Preparations Market
Pharmaceuticals
Cardiometabolic Drugs Market
Pharmaceuticals
Drug Delivery Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Latin America FMD Vaccine Market
Pharmaceuticals
Global Immune Checkpoint Inhibitors Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Oral Vaccines Market