
 Submucosal Lifting Agent Market | 2026-2036
Submucosal Lifting Agent Market Size, Share, and Industry Trends Forecast 2026-2036
Submucosal Lifting Agent Market Insights
Hyaluronic acid is consolidating its position as the preferred biomaterial over gelatin-based alternatives in submucosal lifting formulations. Boston Scientific Corporation leverages its endoscopy portfolio depth to sustain leadership in North American distribution channels. Olympus Corporation anchors its competitive stance through integrated endoscope-lifting agent system compatibility. Medtronic competes on the strength of its therapeutic endoscopy R&D pipeline across multiple geographies.
Submucosal lifting agents comprise injectable biocompatible materials—typically hyaluronic acid, collagen, or synthetic polymer formulations at concentrations between 10 and 20 mg/mL—designed to create a fluid cushion beneath the mucosal layer during endoscopic resection procedures. Their primary purpose is to elevate lesions away from the muscularis propria, enabling safer polypectomy and endoscopic submucosal dissection while minimizing perforation risk. Hyaluronic acid products command the dominant revenue share due to superior tissue residence time and safety profiles, while synthetic polymer segments represent the fastest-expanding margin pool as manufacturers seek alternatives with longer-lasting lift duration. Hospitals absorb the majority of volume as end-user demand concentrates where complex interventional gastroenterology procedures are performed.
The FDA's device classification framework for endoscopic accessories directly shapes product registration pathways and clinical evidence requirements for market entry in the United States. EMA's Medical Device Regulation and Japan's PMDA standards similarly govern biocompatibility testing and post-market surveillance obligations across their respective jurisdictions. ISO 10993 biocompatibility series provides the foundational reference for material safety assessment worldwide. Stakeholders must monitor evolving reimbursement codes for endoscopic submucosal dissection procedures as these determine procedural economics and directly influence purchasing decisions for lifting agent selection.
Market Dynamics
The Submucosal Lifting Agent Market is experiencing structural compression as hyaluronic acid formulations consolidate share against gelatin-based alternatives, driven by differential safety profiles and tissue residence characteristics that reshape procurement criteria across hospital systems.
Growth Catalysts
- FDA Endoscopy Device Guidance:Evolving classification frameworks for endoscopic accessories streamline registration pathways for novel lifting agents, accelerating commercialization timelines for compliant manufacturers in the United States.
- Endoscopic Submucosal Dissection (ESD) Proliferation:Complex interventional gastroenterology procedures are expanding across tertiary hospital networks, creating procedural pull-through for specialized lifting formulations.
- Hyaluronic Acid Biomaterial Superiority:Extended tissue residence time and favorable safety profiles position this material class as the default selection in high-volume resection centers.
Market Restraints
- Reimbursement Code Uncertainty:Evolving procedural economics for ESD create purchasing hesitation as hospital administrators await definitive coding determinations from CMS and private payers.
- Biocompatibility Testing Burden:ISO 10993 series compliance requirements impose substantial pre-market validation costs and timeline extensions for novel polymer entrants.
- Input Material Concentration:Pharmaceutical-grade hyaluronic acid supply concentrates among a limited cohort of fermentation-derived producers, creating vulnerability to batch variability and qualification delays.
Strategic Opportunities
- Synthetic Polymer Formulation White Space:Longer-lasting lift duration properties position engineered polymer segments to capture premium positioning in complex resection cases.
- Integrated Endoscope-Agent System Compatibility:Device manufacturers seek captive supply relationships that bundle lifting agents with proprietary injection systems, creating channel control opportunities.
- Japan PMDA Fast-Track Pathways:Accelerated review designations for innovative endoscopic devices offer timeline advantages for manufacturers with robust clinical evidence packages.
Industry Challenges
- Interventional Gastroenterologist Training Pipeline:ESD proficiency requires substantial proctored case volume that outpaces current fellowship program output, constraining addressable procedure growth.
- Legacy Injection System Integration:Novel lifting formulations must demonstrate compatibility with installed bases of endoscopic injection needles across heterogeneous hospital equipment fleets.
- Post-Market Surveillance Infrastructure:MDR and PMDA vigilance obligations demand pharmacovigilance capabilities that exceed traditional medical device monitoring frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submucosal Lifting Agent Market |
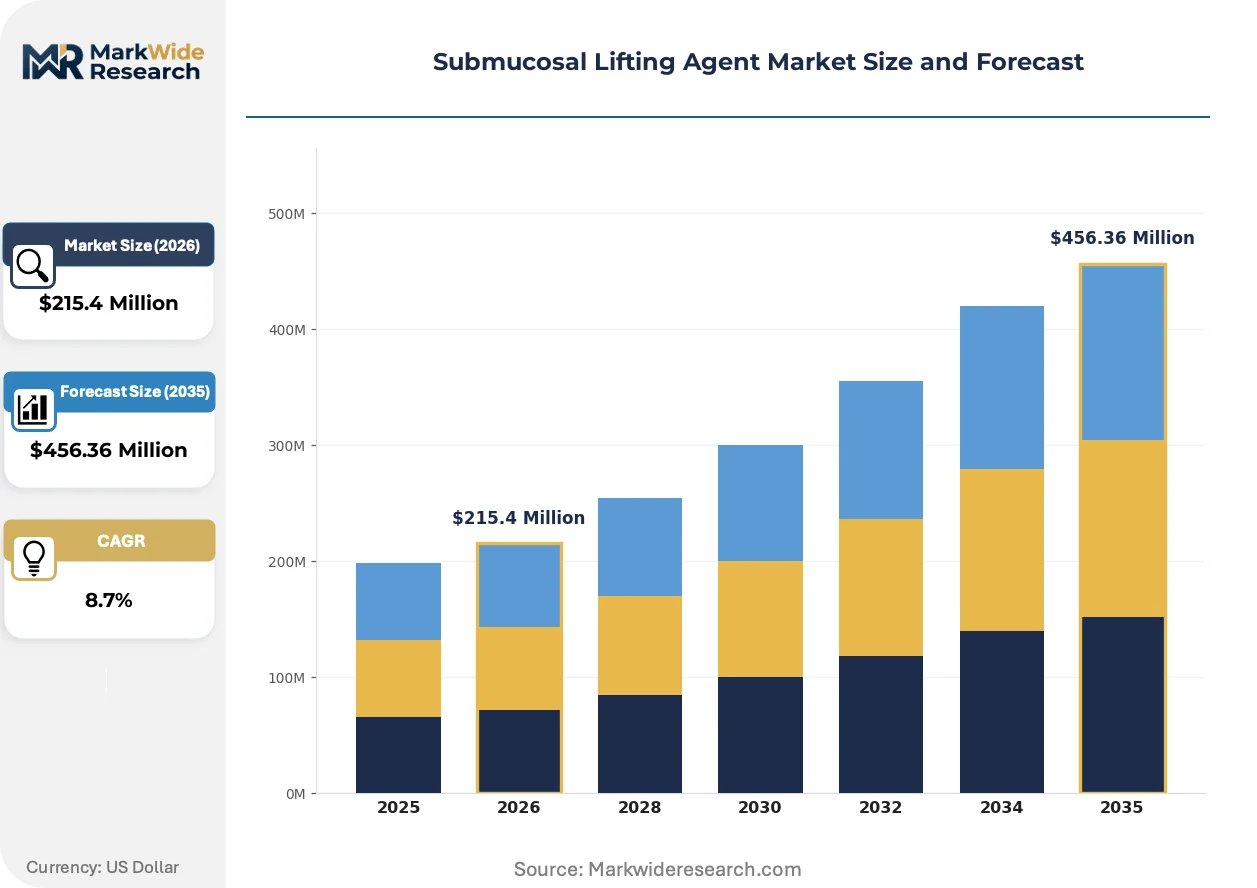
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $456.36 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Collagen-Based, Gelatin-Based, Synthetic Polymers Application: Endoscopic Procedures, Surgical Interventions, Cosmetic Enhancements, Therapeutic Uses Delivery Mode: Injection, Oral Administration, Topical Application, Device-Assisted Delivery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Medtronic, FUJIFILM Medical Systems, STERIS, Sumitomo Bakelite Co., Ltd., Ovesco Endoscopy AG, GI Supply, ERBE Elektromedizin GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submucosal Lifting Agent Market Trends and Innovations
Formulation science and procedural technique are converging to redefine performance benchmarks in submucosal lifting, with manufacturers competing on lift duration, viscosity control, and injection system integration rather than commodity biomaterial supply.
Next-generation synthetic polymer formulations are unifying extended lift duration with tunable rheological properties. Tertiary care centers in Germany and Japan are piloting these materials in complex ESD cases requiring prolonged submucosal cushion maintenance. This unification is compressing the performance gap between hyaluronic acid dominance and synthetic alternatives, forcing incumbent suppliers to differentiate on safety databases rather than functional equivalence.
EMA's Medical Device Regulation (MDR) implementation is tightening biocompatibility documentation requirements for endoscopic accessories. Manufacturers must now submit comprehensive biological evaluation reports aligned with ISO 10993-1 risk management frameworks, extending technical file preparation timelines. Small-to-mid sized European suppliers are responding by consolidating regulatory affairs functions and pursuing notified body partnerships with MDR-designated conformity assessment organizations.
Hospital procurement committees are consolidating lifting agent selection authority at the health system level rather than individual physician preference. GPO-negotiated contracts and formulary restrictions are displacing decentralized purchasing across integrated delivery networks in the United States. This concentration is most visible in multi-hospital systems where standardization incentives override individual endoscopist product familiarity.
Submucosal Lifting Agent Market Segmentation
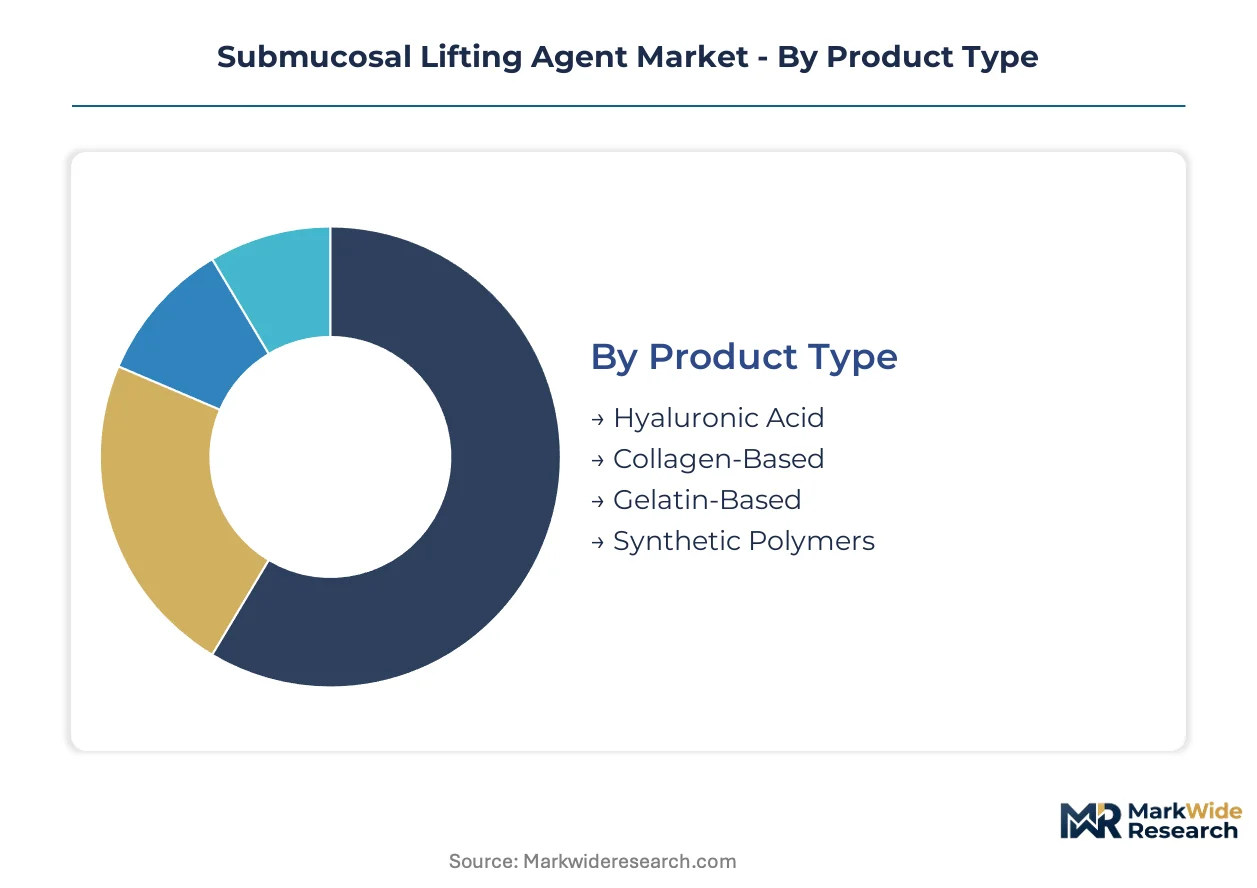
Submucosal lifting agent procurement varies sharply across clinical settings and procedural complexity. Material selection, delivery mechanism, and institutional purchasing power create distinct demand profiles that manufacturers must address through targeted formulation and channel strategies.
Product Type:
Cost tier and performance duration separate buyers in this category, with premium formulations commanding preference in complex resection cases.
- Hyaluronic Acid:Fermentation-derived polysaccharide at 10-20 mg/mL concentrations provides extended tissue residence time. Demand concentrates in United States tertiary hospitals performing high-volume endoscopic submucosal dissection, where safety databases and lift reliability override procurement cost sensitivity.
- Synthetic Polymers:Engineered polymer matrices deliver tunable rheological properties and prolonged cushion maintenance. German and Japanese centers pilot these materials in complex ESD cases, attracted by duration advantages that reduce procedural interruption risk.
- Collagen-Based:Bovine or porcine-derived matrices offer biocompatibility with shorter residence profiles.
- Gelatin-Based:Lower-cost alternatives face share erosion as hyaluronic acid safety data accumulates.
Volume sits with hyaluronic acid; growth tilts toward synthetic polymers.
Application:
Procedural reimbursement codes determine purchasing authority and material specification rigor across use cases.
- Endoscopic Procedures:Polypectomy and ESD applications require precise submucosal cushion formation with perforation risk mitigation. United States hospital systems concentrate demand where CMS coding determinations shape procedural economics and material selection authority.
- Surgical Interventions:Open and laparoscopic applications leverage lifting agents for tissue plane identification. Volume concentrates in Japan's specialized gastrointestinal surgery centers, where PMDA device classifications govern registration requirements.
- Cosmetic Enhancements:Dermal and soft tissue applications operate outside gastrointestinal reimbursement frameworks.
- Therapeutic Uses:Drug delivery and barrier applications represent emerging indication expansion.
Revenue concentrates in endoscopic applications; therapeutic uses are expanding most quickly.
Delivery Mode:
Installed base compatibility constrains formulation choice across heterogeneous hospital equipment fleets.
- Injection:Endoscopic needle delivery through working channels dominates clinical practice. Demand clusters where Olympus, Boston Scientific, and Medtronic injection systems have established installed bases, creating compatibility requirements for viscosity and particulate specifications.
- Device-Assisted Delivery:Integrated injection-lifting agent systems enable controlled flow rates and pressure monitoring. German university hospitals evaluate these configurations for complex resection standardization.
- Oral Administration:Systemic absorption applications remain investigational.
- Topical Application:Surface barrier indications occupy niche therapeutic positioning.
Injection captures procedural volume; device-assisted delivery shows steepest expansion trajectory.
End User:
Purchasing consolidation and formulary authority differentiate institutional buyers in this category.
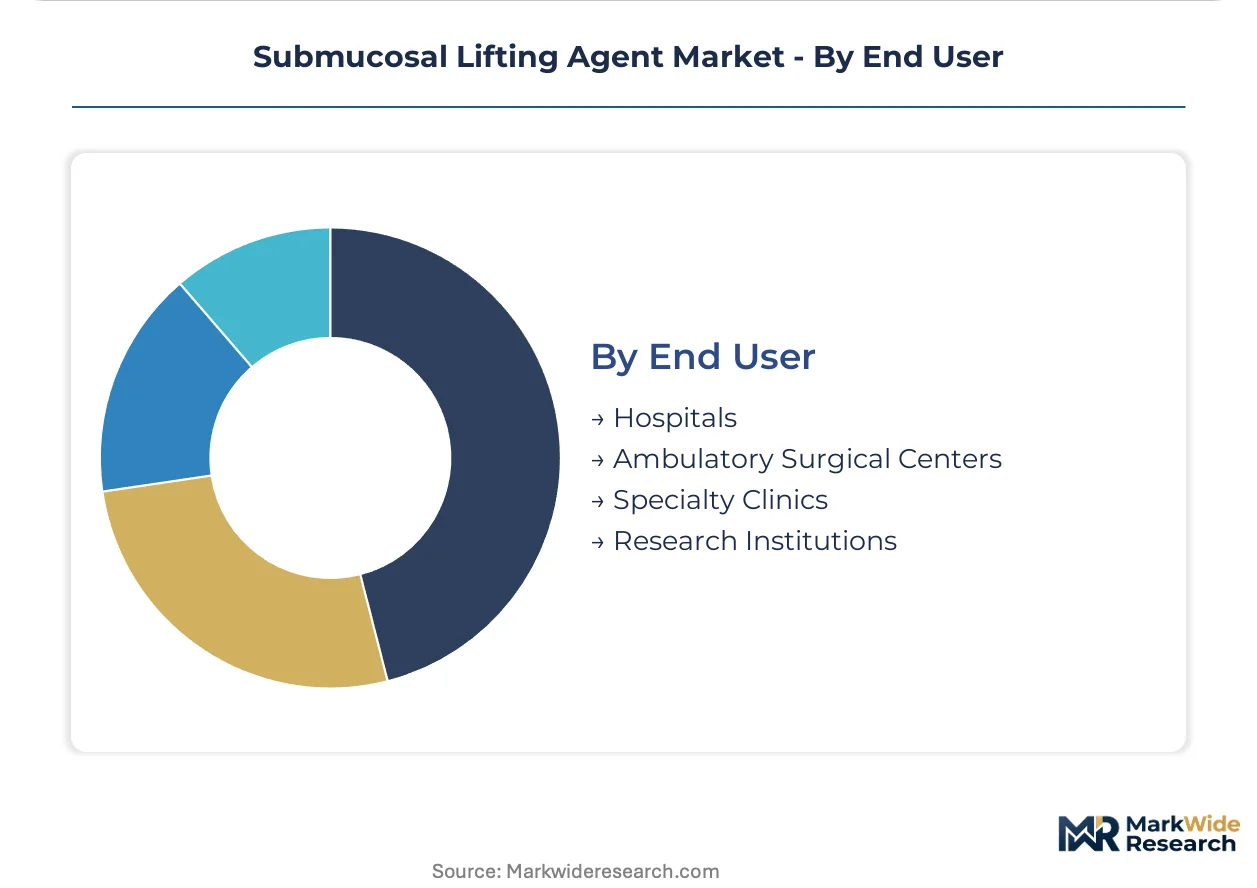
- Hospitals:Integrated delivery networks and academic medical centers perform complex interventional gastroenterology with GPO-negotiated contracts. United States multi-hospital systems centralize lifting agent selection at health system level, displacing individual physician preference.
- Ambulatory Surgical Centers:Outpatient endoscopy facilities prioritize cost efficiency and storage stability. Volume concentrates in United States freestanding centers where procedure volume economics favor standardized material selection.
- Specialty Clinics:Gastroenterology-focused practices operate with limited formulary flexibility.
- Research Institutions:Clinical trial sponsors and academic laboratories drive investigational use demand.
Procurement volume sits with hospitals; ambulatory surgical centers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for submucosal lifting agents clusters in tertiary hospitals performing complex endoscopic resection procedures, with procurement authority concentrating in integrated health systems across five major markets.
United States
CMS reimbursement determinations for endoscopic submucosal disshape hospital purchasing committees toward standardized formulary selection. FDA device classification frameworks govern biocompatibility documentation requirements for hyaluronic acid formulations. The Cleveland Clinic and Mayo Clinic anchor procedural volume in the Midwest, where GPO-negotiated contracts displace individual physician preference.
Germany
University hospitals in Bavaria and Baden-Württemberg pilot synthetic polymer formulations for complex ESD cases requiring extended lift duration. EMA Medical Device Regulation implementation tightens ISO 10993 compliance obligations for endoscopic accessories. The Berlin-Brandenburg cluster concentrates regulatory affairs expertise as manufacturers consolidate notified body partnerships.
Japan
PMDA fast-track pathways accelerate review timelines for innovative endoscopic devices with robust clinical evidence packages. Specialized gastrointestinal surgery centers in Tokyo and Osaka drive demand for integrated endoscope-lifting agent systems. The Nagoya medical device corridor anchors manufacturing partnerships between domestic suppliers and global endoscopy manufacturers.
United Kingdom
NHS procurement frameworks centralize lifting agent selection at integrated care system level, compressing vendor margins through volume aggregation. MHRA post-Brexit regulatory alignment with MDR extends technical file preparation timelines for market entrants. London's academic medical centers concentrate interventional gastroenterology training programs that constrain addressable procedure growth.
South Korea
MFDS regulatory harmonization with international standards streamlines registration pathways for hyaluronic acid formulations. The Seoul Capital Area absorbs majority procedural volume where multi-hospital systems standardize on premium biomaterial selections. Busan-Ulsan manufacturing clusters supply pharmaceutical-grade fermentation-derived inputs to regional formulation specialists.
Submucosal Lifting Agent Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated endoscopy system vendors commanding premium positioning in hospital procurement channels. The vendor base organizes around three strategic archetypes: diversified medical device conglomerates with endoscopy portfolio depth, pure-play lifting agent formulation specialists, and regional fermentation-derived input suppliers. Competitive moves concentrate on M&A for injection system compatibility and strategic partnerships with academic medical centers for clinical evidence generation.
Among diversified medical device conglomerates, Boston Scientific Corporation, Olympus Corporation, and Medtronic occupy positions that exemplify the integrated system vendor archetype. These corporations anchor competitive positioning through captive supply relationships and proprietary injection system compatibility. Olympus Corporation represents the endoscope-lifting agent system integration model, while Boston Scientific Corporation and Medtronic exemplify therapeutic endoscopy R&D pipeline approaches across multiple geographies.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Medtronic |
| FUJIFILM Medical Systems |
| STERIS |
| Sumitomo Bakelite Co., Ltd. |
| Ovesco Endoscopy AG |
| GI Supply |
| ERBE Elektromedizin GmbH |
| Others |
Pricing and Supply Chain Analysis
EMA MDR biocompatibility documentation requirements gate qualified supply access and premium-tier pricing power for hyaluronic acid formulations, compressing margins for non-compliant entrants while rewarding ISO 10993-certified manufacturers with formulary placement in United States hospital systems. Pharmaceutical-grade fermentation-derived inputs concentrate among limited suppliers, creating tiered procurement economics where batch qualification timelines directly shape contract pricing flexibility.
Pricing Analysis
Volume concentrates in standard-grade hyaluronic acid at 10-20 mg/mL concentrations, while margin pools shift toward synthetic polymer formulations with tunable rheological properties. Three-tier pricing structure across premium, standard, and economy levels separates extended-residence formulations from commodity gelatin alternatives, with FDA device classification tier and GPO contract scale as primary price differentiation drivers. Cost compression in economy tiers is intensifying as hospital procurement committees consolidate selection authority at health system level. Ambulatory surgical centers exhibit highest price sensitivity; tertiary ESD centers prioritize lift reliability over procurement cost.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive fermentation-derived hyaluronic acid elevate landed costs for European and North American formulators sourcing from South Korean and Japanese input suppliers. Supply concentrates in Busan-Ulsan fermentation clusters for pharmaceutical-grade polysaccharide inputs, with secondary sourcing from German and Swiss precision chemical manufacturers for synthetic polymer precursors. Single-source vulnerability pervades the fermentation-derived input tier, where batch variability creates qualification delays. Distribution runs through GPO-negotiated contracts and direct hospital system agreements, displacing distributor intermediaries in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic polymer formulation technology is displacing legacy gelatin-based alternatives, compressing the performance gap with hyaluronic acid dominance and forcing incumbent suppliers to differentiate on safety databases rather than functional equivalence alone.
For Market Incumbents: Cement channel control through captive supply relationships bundling lifting agents with proprietary injection systems, while deepening backward integration into pharmaceutical-grade fermentation capacity to secure input supply against batch variability risks. ISO 10993-1 risk management framework certification investment represents the critical defensive lever as EMA MDR implementation tightens biocompatibility documentation requirements. For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable buyer archetype, as cost efficiency priorities and storage stability requirements favor standardized material selection over premium-tier formulations. Target synthetic polymer white space in German and Japanese tertiary centers piloting extended-lift-duration materials, with device-assisted delivery compatibility as the primary go-to-market angle. For Investors and Strategic Acquirers: PMDA fast-track pathway designations for innovative endoscopic devices are the leading indicator that clinical evidence generation capabilities will command acquisition premiums. The five-to-ten year viability window favors vertically integrated formulation specialists with captive injection system partnerships. Watch for CMS reimbursement code finalization for ESD procedures as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Novel Polymer Formulation | Streamlined review accelerates United States commercialization timelines for compliant manufacturers. |
| CE Marking Pathway under MDR | Notified body partnership requirements extend technical file preparation for European market entry. |
| Hospital System Partnership for Clinical Evidence Generation | Academic medical center collaboration builds safety databases that differentiate against commodity alternatives. |
| Integrated Injection-Lifting Agent System Development | Device compatibility creates formulary lock-in through proprietary flow rate and pressure monitoring. |
| Reimbursement Strategy for ESD Procedure Coding | CMS determination alignment shapes hospital purchasing committee material selection authority. |
Research Methodology
Document review covered FDA 510(k) filings, EMA MDR technical file submissions, PMDA device registration databases, and hospital GPO contract disclosures, complemented by interviews with interventional gastroenterologists, biomedical engineers, hospital purchasing committee members, and regulatory affairs specialists at formulation manufacturers. Secondary validation drew from ISO 10993 biocompatibility standards documentation, CMS Medicare reimbursement coding determinations, and customs trade data for pharmaceutical-grade hyaluronic acid imports. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across the analysis window.
Output projections span product type, application, delivery mode, and end user segments, with material concentration tier and regional regulatory cluster as additional industry-specific dimensions. CAGRs were derived from procedure volume elasticity to reimbursement code adoption, input material supply expansion rates, and interventional gastroenterologist training pipeline output. Forecast inputs incorporated ESD proliferation trajectories in tertiary hospital networks and synthetic polymer formulation pilot program conversion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PMDA fast-track pathway utilization rates and CMS coding determination timing for endoscopic submucosal dissection procedures. Forecasts reflect assumptions regarding reimbursement alignment and regulatory harmonization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
US External Analgesics Market
Pharmaceuticals
Testosterone Nasal Gels Market
Pharmaceuticals
Global Genitourinary Drugs Market
Pharmaceuticals
Global Vasopressin Market
Pharmaceuticals
Global Sterile Injectable Drugs Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Riociguat Tablets Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
HPV Vaccines Market
Pharmaceuticals
Global Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
US Sex Reassignment Hormone Therapy Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Antidepressants Market
Pharmaceuticals
Candidiasis Drug Market
Pharmaceuticals
Polypill Products Market