
 Respiratory Disease Vaccine Market | 2026-2036
Respiratory Disease Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Disease Vaccine Market Analytics
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for respiratory vaccine manufacturers seeking European market access. GSK plc leverages its adjuvant platform and decades of influenza vaccine production to sustain manufacturing scale across multiple continents. Sanofi anchors its position through recombinant protein expertise and established pediatric vaccine portfolios. Pfizer Inc. competes with mRNA capabilities inherited from its COVID-19 franchise, now extending toward respiratory syncytial virus candidates.
Respiratory disease vaccines comprise immunological preparations designed to induce protective humoral and cellular responses against pathogens affecting the pulmonary system, including influenza viruses, Streptococcus pneumoniae, and respiratory syncytial virus, typically formulated with aluminum salts, lipid nanoparticles, or novel adjuvant systems to enhance immunogenicity. Their primary purpose is preventing morbidity and mortality from acute lower respiratory tract infections in vulnerable populations including infants, elderly patients, and immunocompromised individuals. The mRNA vaccine type segment is capturing disproportionate R&D investment as platform flexibility enables rapid strain adaptation, while the prevention application category dominates commercial volume through routine immunization schedules administered at hospitals and clinics. The direct sales distribution channel controls institutional procurement for government tenders, whereas retail pharmacy networks are expanding access for adult booster programs.
The FDA's accelerated approval pathways and the EMA's adaptive licensing frameworks compress development timelines while demanding robust immunological correlates of protection. India's CDSCO and the Serum Institute of India's manufacturing scale create parallel pathways for affordable supply to low-income country programs through WHO prequalification requirements. China's NMPA vaccine registration reforms are reshaping market entry requirements for multinational sponsors. Stakeholders must monitor how national immunization technical advisory groups revise priority pathogen lists and whether mRNA platform standardization reduces cost differentials against traditional inactivated formulations.
Market Dynamics
mRNA platform standardization is compressing cost differentials against traditional inactivated formulations while reshaping manufacturing footprints across North America, Europe, and Asia-Pacific. National immunization technical advisory groups are revising priority pathogen lists in response to post-pandemic surveillance data, creating procurement momentum for next-generation candidates.
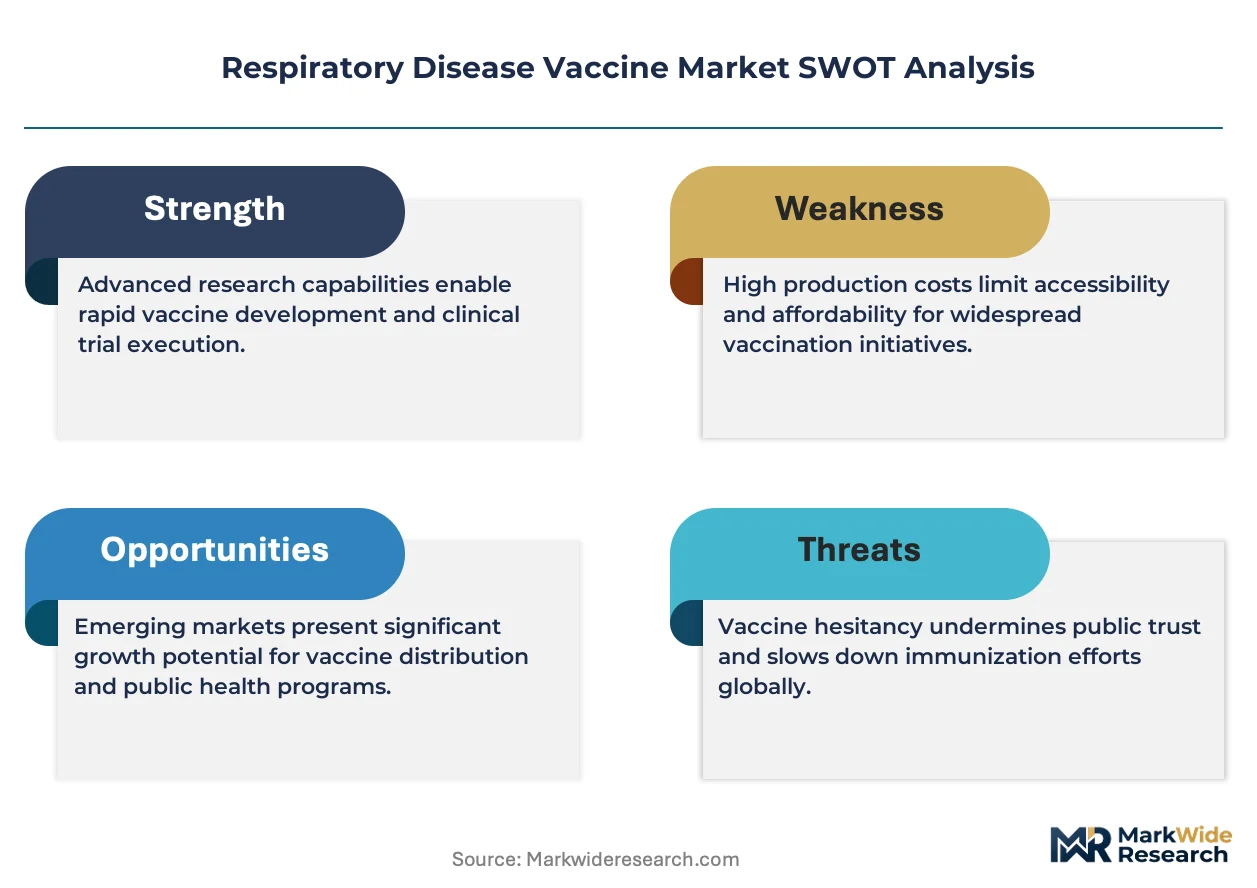
Growth Catalysts
- Accelerated Approval Pathways:The FDA's accelerated approval pathways compress development timelines by accepting immunological correlates of protection as surrogate endpoints, enabling earlier market entry for respiratory syncytial virus and next-generation influenza candidates.
- Pediatric Program Expansion:National health ministries in low-income countries are expanding procurement volumes through Gavi alliance funding mechanisms, creating sustained demand for pentavalent and hexavalent combination vaccines.
- Adjuvant Platform Maturation:Novel adjuvant systems including AS01 and MF59 are enhancing immunogenicity in elderly populations, opening addressable markets where age-related immunosenescence previously limited vaccine efficacy.
Market Restraints
- Cold Chain Infrastructure Gaps:Ultra-low temperature storage requirements for mRNA formulations impose distribution constraints in tropical climates and rural health networks, limiting penetration outside metropolitan hospital systems.
- Antigenic Drift Uncertainty:Seasonal strain mismatch between vaccine composition and circulating influenza viruses creates efficacy volatility that complicates public health messaging and payer reimbursement negotiations.
- Regulatory Divergence:China's NMPA vaccine registration reforms impose localized clinical trial requirements that extend timelines for multinational sponsors seeking market access.
Strategic Opportunities
- Maternal Immunization Expansion:India's CDSCO is evaluating expanded indications for respiratory syncytial virus vaccines in pregnant populations, creating a new delivery channel through antenatal care clinics.
- Pharmacy Retail Integration:Adult booster programs are migrating into community pharmacy networks, reducing reliance on hospital-based administration and capturing working-age populations outside traditional clinic hours.
- WHO Prequalification Pathways:The Serum Institute of India's manufacturing scale creates parallel supply channels for low-income country programs, enabling volume commitments that amortize fixed production costs.
Industry Challenges
- Bioprocessing Talent Scarcity:Lipid nanoparticle formulation expertise remains concentrated among a limited pool of specialists, constraining workforce expansion for mRNA manufacturing scale-up.
- Immunological Correlate Validation:Establishing standardized correlates of protection for novel platforms requires prolonged clinical follow-up, creating uncertainty for accelerated approval submissions.
- Legacy System Integration:National immunization registries in emerging markets lack interoperability with digital certificate platforms, complicating dose tracking and coverage monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Disease Vaccine Market |
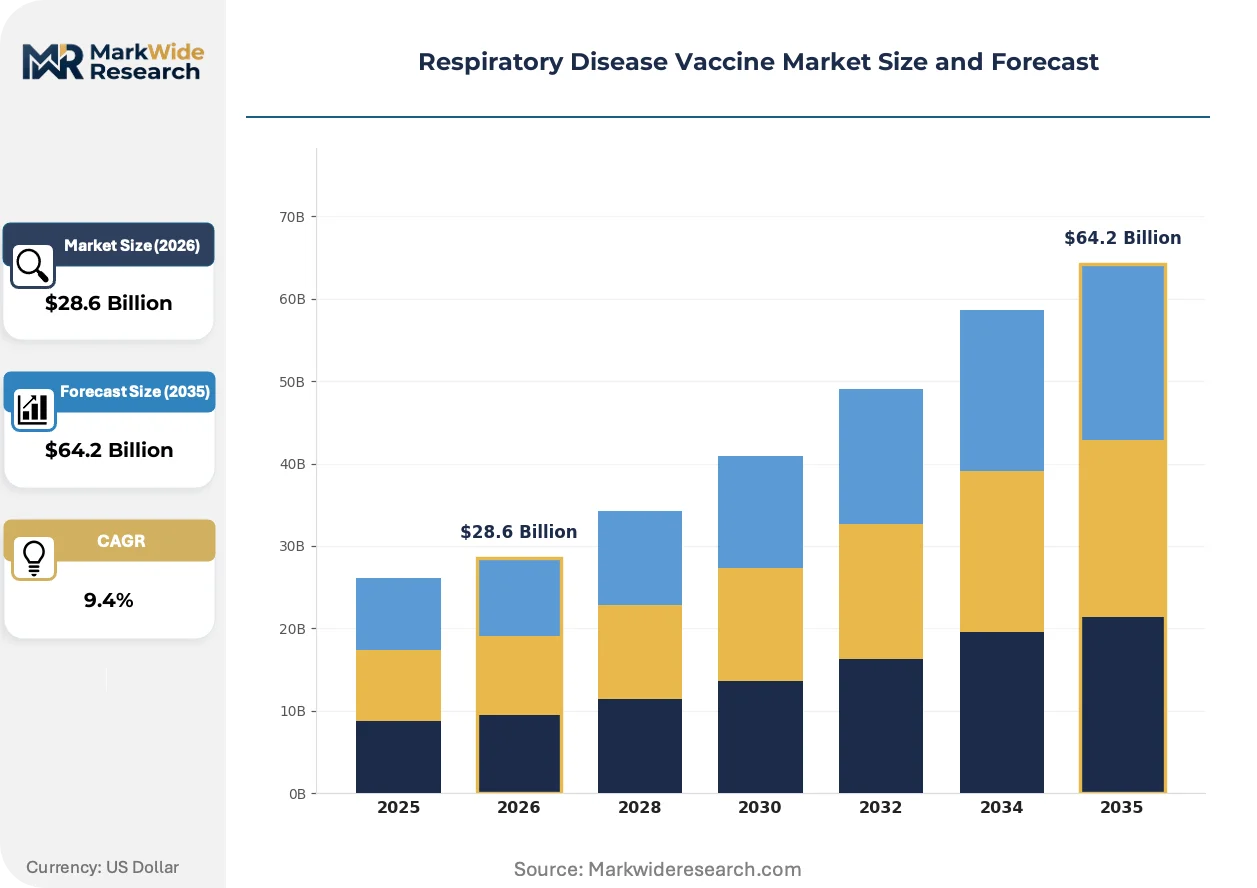
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Inactivated, Live Attenuated, Subunit, mRNA Application: Prevention, Treatment, Prophylaxis, Booster End User: Hospitals, Clinics, Research Facilities, Pharmacies Distribution Channel: Direct Sales, Wholesalers, Retail Pharmacy, Online |
| Companies Covered | GSK plc, Sanofi, Pfizer Inc., Merck & Co., Inc., Moderna, Inc., AstraZeneca, Johnson & Johnson Services, Inc., Serum Institute of India Pvt. Ltd., Bavarian Nordic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Disease Vaccine Market Evolving Landscape
Platform flexibility is enabling rapid strain adaptation that collapses traditional vaccine development timelines from years to months. Manufacturers are reconfiguring production networks around modular mRNA facilities that can pivot between respiratory pathogens. Regulatory frameworks are adapting to accommodate these compressed development cycles without compromising safety standards.
Self-amplifying mRNA technology is supplanting conventional mRNA constructs in late-stage pipelines by enabling lower dose requirements and reduced reactogenicity profiles. Pediatric vaccine developers at academic medical centers are adopting these constructs for respiratory syncytial virus candidates. The technology is supplanting protein subunit approaches in maternal immunization programs by shortening the dosing interval required for protective antibody transfer.
The EU Medical Device Regulation's CE marking requirements are redrawing competitive boundaries for combination devices that integrate vaccine delivery with digital adherence monitoring. Manufacturers seeking European market access must now demonstrate usability validation for auto-injector platforms alongside immunogenicity data. Hospital procurement committees in Germany and France are prioritizing prequalified devices that reduce nursing administration time.
Adult consumers are requesting consolidated immunization appointments that bundle respiratory boosters with routine preventive care, compressing the traditional seasonal vaccination window. Occupational health clinics and employer-sponsored wellness programs are capturing this demand through on-site administration models. This pattern is most visible in the United States, where pharmacy benefit managers are redesigning formularies to incentivize combination scheduling.
Respiratory Disease Vaccine Market Segmentation
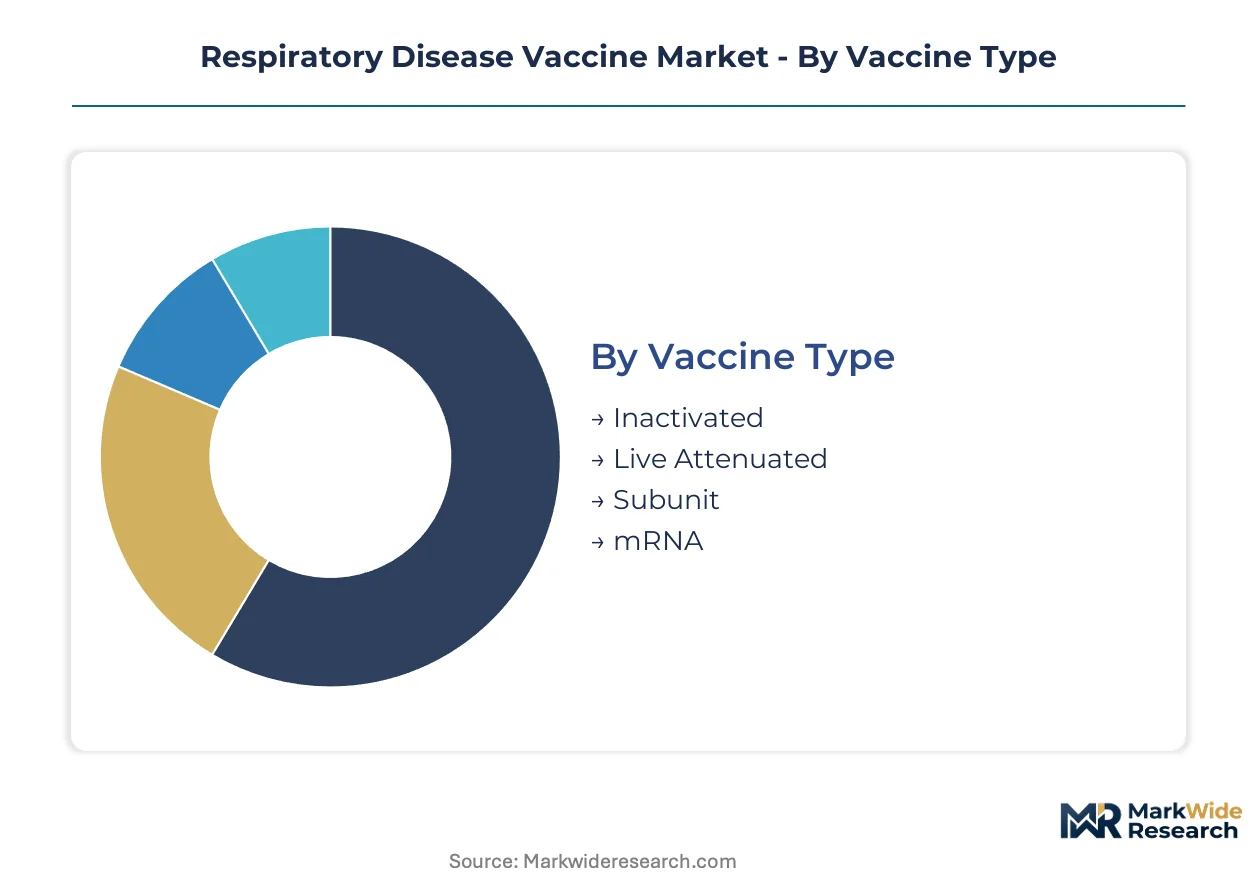
Respiratory vaccine segmentation reveals divergent channel economics across institutional procurement and consumer-facing retail. Each category carries distinct margin profiles, cold chain requirements, and regulatory touchpoints that shape manufacturer portfolio strategy.
Vaccine Type:
mRNA formulations flow through hospital systems and government tenders, while inactivated and live attenuated products dominate retail pharmacy networks with established cold chain infrastructure.
- Inactivated:Viral particles chemically treated to destroy replication capacity while preserving immunogenic surface antigens, typically formulated with aluminum hydroxide adjuvants. Demand concentrates in India's national immunization program and Gavi-eligible countries where WHO prequalification drives procurement at CDSCO-regulated manufacturing sites.
- Live Attenuated:Weakened viral strains that replicate transiently to stimulate cellular immunity without causing disease, delivered as nasal sprays or intramuscular injections. Nasal formulations are gaining share in Japan's PMDA-regulated pediatric market and US pharmacy retail chains targeting school-age populations.
- Subunit:Purified protein antigens or virus-like particles produced through recombinant DNA technology in yeast or insect cell systems. Recombinant hemagglutinin vaccines from Sanofi's Flublok platform serve egg-allergic populations through US hospital outpatient clinics.
- mRNA:Lipid nanoparticle-encapsulated nucleic acids encoding viral surface proteins, manufactured through cell-free enzymatic synthesis. Ultra-cold storage requirements restrict distribution to metropolitan hospital systems in Germany, France, and the United States with validated -70°C infrastructure.
Inactivated vaccines dominate installed base across low-income country programs. mRNA is where expansion concentrates as platform standardization reduces cost differentials.
Application:
Prevention and booster applications split between institutional procurement at national scale, while treatment and prophylaxis indications serve niche immunocompromised populations through specialty pharmacy channels.
- Prevention:Primary immunization series administered to naive individuals to establish baseline immunity, constituting the volume anchor for pediatric national immunization schedules. India's Universal Immunization Program procures pentavalent and hexavalent combinations through CDSCO-registered suppliers at Serum Institute of India scale.
- Treatment:Therapeutic vaccination in already-infected individuals to modulate disease severity, an emerging indication for chronic respiratory infections. Academic medical centers in Boston and London are evaluating therapeutic candidates for recurrent respiratory papillomatosis.
- Prophylaxis:Pre-exposure protection for high-risk occupational groups including healthcare workers and laboratory personnel. German hospital procurement committees prioritize prequalified products for nursing staff under occupational health mandates.
- Booster:Periodic re-exposure to maintain antibody titers above protective thresholds as natural immunity wanes. US pharmacy benefit managers redesigned formularies to bundle influenza and COVID-19 boosters into single appointment windows.
Prevention commands procurement volume through government tenders. Booster applications are climbing the fastest as adult immunization platforms mature.
End User:
Hospitals and clinics capture pediatric and elderly vaccination through appointment-based administration, while pharmacies and research facilities serve distinct population segments with divergent reimbursement pathways.
- Hospitals:Integrated health systems with cold chain infrastructure, nursing staff, and electronic immunization registries for inpatient and outpatient administration. US hospital formulary committees evaluate respiratory vaccines alongside seasonal influenza procurement cycles.
- Clinics:Community-based primary care settings handling routine immunization without overnight patient capacity. French vaccination centers established during COVID-19 are being repurposed for RSV and influenza campaigns.
- Research Facilities:Academic medical centers and contract research organizations conducting Phase I-III trials or post-marketing surveillance. PMDA-registered sites in Tokyo and Osaka anchor Asia-Pacific respiratory vaccine development.
- Pharmacies:Retail drugstore chains with walk-in vaccination capacity, pharmacist immunization certification, and direct-to-consumer marketing. CVS Health and Walgreens capture working-age adults through evening and weekend availability.
Hospitals dominate installed base for pediatric and geriatric populations. Pharmacies represent the steepest expansion trajectory as scope-of-practice laws expand pharmacist administration authority.
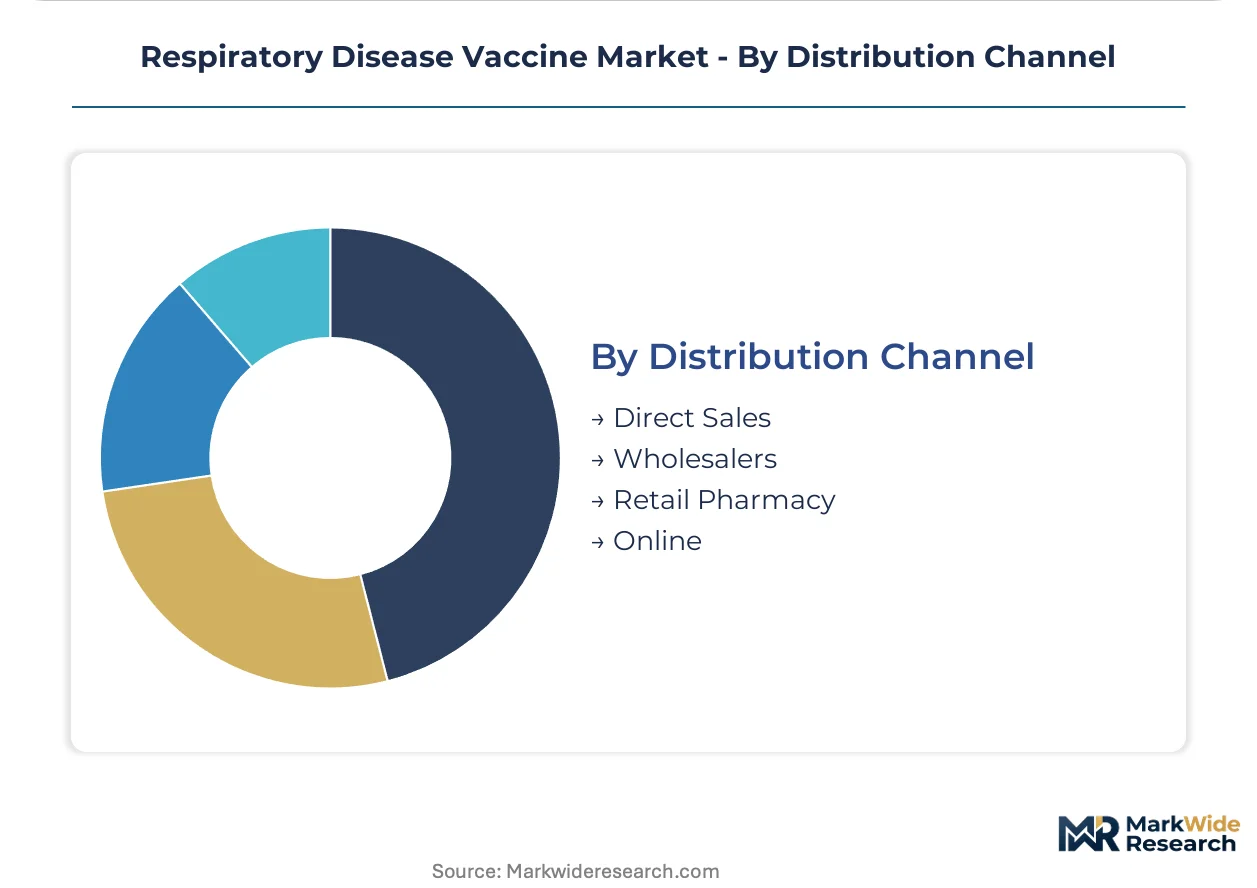
Distribution Channel:
Direct sales and wholesalers handle institutional volume with negotiated tenders, while retail pharmacy and online channels fragment toward consumer-direct models with distinct margin and logistics profiles.
- Direct Sales:Manufacturer-to-institution contracting for government tenders, hospital systems, and national immunization programs with volume commitments and multi-year pricing. GSK plc's direct sales force manages European Union member state procurement under EMA centralized marketing authorizations.
- Wholesalers:Regional distributors with cold chain warehousing, lot tracking systems, and last-mile delivery to clinics and smaller hospitals. McKesson and AmerisourceBergen control US wholesale distribution with validated 2-8°C and -20°C storage capabilities.
- Retail Pharmacy:Chain drugstores with in-store vaccination capacity, inventory management systems, and consumer marketing programs. Boots UK and Shoppers Drug Mart in Canada leverage loyalty program data to target high-risk populations.
- Online:Digital platforms facilitating appointment scheduling, vaccine education, and home delivery of temperature-stable formulations. Alibaba Health and JD Health in China pilot online-to-offline models linking e-commerce to physical clinic administration.
Direct sales dominate installed base through government tenders. Online channels are gaining share fastest as digital health infrastructure and consumer convenience preferences converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways compress development timelines for respiratory syncytial virus candidates in the United States. Germany's EMA centralized marketing authorizations enable cross-border procurement coordination under EU joint purchasing mechanisms.
United States
Hospital formulary adoption and pharmacy retail networks drive commercial volume for adult booster programs. The FDA accepts immunological correlates of protection as surrogate endpoints for accelerated submissions. Manufacturing scale concentrates around Boston-Cambridge biotech clusters and Maryland vaccine production corridors.
Germany
EMA centralized procedures streamline multi-country launches for combination respiratory vaccines. Hospital procurement committees in Berlin and Munich prioritize prequalified auto-injector platforms that reduce nursing administration time. Bavarian manufacturing sites anchor European supply for lipid nanoparticle formulations.
India
CDSCO regulatory reforms and Serum Institute manufacturing scale create supply channels for Gavi-eligible country programs. The Universal Immunization Program procures pentavalent combinations through government tenders. Pune-based production facilities supply WHO-prequalified doses across sub-Saharan Africa and Southeast Asia.
China
NMPA vaccine registration reforms impose localized clinical trial requirements that extend multinational sponsor timelines. Yangtze River Delta biotech parks in Shanghai and Suzhou host domestic mRNA platform development. State-backed immunization programs prioritize indigenous candidates for influenza and pneumonia prevention.
Japan
PMDA regulatory frameworks accommodate rapid strain adaptation for seasonal influenza updates. Tokyo and Osaka academic medical centers anchor Phase I-III respiratory vaccine trials. Nasal spray formulations gain share in pediatric markets through school-based delivery programs.
Respiratory Disease Vaccine Market Competitive Landscape
Listed leaders compete with private specialists across platform technology and manufacturing scale dimensions. The market structures around three tiers: multinational pharmaceutical conglomerates with adjuvant and mRNA capabilities, mid-scale regional manufacturers serving national immunization programs, and emerging biotech specialists advancing novel delivery technologies. Competitive moves concentrate on strategic partnerships for lipid nanoparticle formulation access and geographic licensing arrangements for tropical market penetration.
Within the multinational tier, GSK plc and Sanofi occupy positions anchored by decades of influenza vaccine production and recombinant protein expertise respectively. Pfizer Inc. exemplifies the mRNA platform pivot, leveraging capabilities developed through prior franchise experience toward respiratory syncytial virus candidates. These three entities represent divergent technical approaches to respiratory pathogen immunization.
| Leading Market Players |
|---|
| GSK plc |
| Sanofi |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Moderna, Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Serum Institute of India Pvt. Ltd. |
| Bavarian Nordic |
| Others |
Value Network & Pricing Analysis
Ninety-day lipid nanoparticle inventory cycles at Bavarian Nordic's Danish manufacturing sites concentrate pricing power with mRNA platform holders while compressing margins for traditional inactivated vaccine suppliers. This lead-time structure amplifies cost differentials between ultra-cold chain formulations and temperature-stable alternatives, reshaping procurement negotiations across European hospital systems and Gavi-eligible country tenders.
Pricing Analysis
Certification level (FDA-grade vs. WHO-prequalified vs. national-only) creates the primary spread across respiratory vaccine pricing tiers, with EMA centralized marketing authorizations commanding premium positioning in German and French hospital formularies. Three-tier pricing structure across premium, standard, and economy levels reflects adjuvant sophistication, cold chain requirements, and pediatric combination complexity. Cost compression in the economy tier is intensifying because Serum Institute of India scale economies are resetting baseline expectations for pentavalent procurement. Government tenders through national immunization programs exhibit highest price sensitivity, while US pharmacy retail networks for adult boosters absorb moderate premiums for convenience access.
Supply Chain Analysis
Lipid nanoparticle formulation expertise concentrated in Massachusetts and Bavaria constrains mRNA manufacturing expansion, creating single-source vulnerability for novel adjuvant systems. Active pharmaceutical ingredient production draws from India, China, and Switzerland, with fill-finish capacity distributed across Belgium, Singapore, and North Carolina. Supply chain risk centers on ultra-low temperature logistics chokepoints between metropolitan cold storage hubs and last-mile rural clinics. Distribution runs through direct manufacturer-to-institution contracting for government tenders, supplemented by regional wholesalers with validated cold chain credentials for smaller hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Respiratory vaccine markets are approaching a platform-economics inflection as mRNA standardization enables rapid strain adaptation protocols that collapse development timelines and reshape interoperability requirements across national immunization registries.
For Market Incumbents: Shield manufacturing scale advantages by deepening captive supply of lipid nanoparticle components and securing exclusive adjuvant platform licensing from academic medical centers. Consolidate position through backward integration into plasmid DNA manufacturing, neutralizing emerging biotech threats with novel delivery technologies. Prioritize EMA centralized marketing authorization maintenance as CDSCO and NMPA reforms extend competitor timelines. For New Entrants and Emerging Players: Differentiate on self-amplifying mRNA constructs that reduce dose requirements and enable tropical distribution without -70°C infrastructure. White-space targets include maternal immunization programs in India's antenatal care networks and therapeutic vaccination for chronic respiratory infections at US academic medical centers. Go-to-market angle should emphasize pharmacy retail integration for adult booster bundling. For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical parents seeking to monetize legacy inactivated vaccine franchises as mRNA platforms displace traditional formulations. Long-term viability favors specialists with lipid nanoparticle formulation expertise and WHO prequalification pathways. Signal to watch is CDSCO expanded indication approvals for respiratory syncytial virus in pregnant populations, which would validate maternal immunization as a distinct revenue stream.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Self-amplifying mRNA candidates in Phase III at Boston academic medical centers validate platform flexibility. |
| Regulatory Approval Pathway | FDA accelerated approval using immunological correlates compresses RSV vaccine timelines versus traditional endpoints. |
| Manufacturing Scale-Up | Modular mRNA facility deployment across Maryland and Bavaria enables rapid pivot between respiratory pathogens. |
| Licensing Agreement | Adjuvant platform partnerships with AS01 and MF59 holders expand addressable markets in elderly populations. |
| Pipeline Diversification | Combination pentavalent and hexavalent formulations for India's Universal Immunization Program amortize fixed production costs. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this respiratory vaccine market assessment. Primary interview findings triangulated against FDA filings, EMA centralized marketing authorization databases, ClinicalTrials.gov protocol records, and Gavi alliance procurement disclosures. Secondary validation incorporated WHO prequalification lists, CDSCO registration data, and national immunization program tender announcements. Bottom-up volume estimates across vaccine type, application, and end-user segments reconciled with top-down market sizing derived from manufacturer production capacity disclosures.
Sensitivity analysis across the projection horizon tested immunological correlate validation timelines, mRNA platform cost compression trajectories, and pediatric program expansion rates in Gavi-eligible countries. Segmentation dimensions modeled include vaccine technology platform, prevention versus therapeutic indication, institutional versus retail channel, and regional regulatory cluster. CAGRs were derived from polynomial trend fitting of historical procurement volumes and scenario-weighted adoption curves for novel platform entrants. Forecast inputs incorporated cold chain infrastructure deployment rates and national immunization technical advisory group priority pathogen revisions.
Material uncertainties — antigenic drift severity in seasonal influenza, regulatory divergence between NMPA and FDA accelerated pathways, and lipid nanoparticle manufacturing talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about platform standardization timelines and adjuvant system licensing accessibility that could shift materially. Practitioners should keep alternative scenarios live as maternal immunization indication expansions and pharmacy retail scope-of-practice evolutions reshape delivery economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Liquid Filled Hard Capsules Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Lansoprazole API Market
Pharmaceuticals
Levofloxacin Lactate Injection Market
Pharmaceuticals
Targeted Liposomes Drug Delivery Market
Pharmaceuticals
Advanced Parenteral Drug Market
Pharmaceuticals
US Pharmaceutical Warehousing Market
Pharmaceuticals
Epigenetics Drugs and Diagnostic Technologies Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Asia-Pacific Cancer Vaccines Market
Pharmaceuticals
Osteoarthritis Drugs Market
Pharmaceuticals
Asia-Pacific Anesthesia Drugs Market