
 Gearless Elevator Traction Motor Market | 2026-2036
Gearless Elevator Traction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Gearless Elevator Traction Motor Market Insights
Commercial building developers are collapsing the distance between premium and mid-tier procurement specifications for high-rise projects. KONE Corporation leverages its integrated elevator-to-motor platform to capture specification lock-in across mixed-use towers. Mitsubishi Electric Corporation anchors its position through permanent magnet motor R&D intensity, particularly in ultra-high-speed applications above 10 meters per second. Otis Elevator Company sustains manufacturing scale advantages across its multi-regional plant network.
Gearless elevator traction motors eliminate reduction gearboxes by coupling the drive sheave directly to a low-speed, high-torque electric motor, typically achieving synchronous speeds below 200 rpm with permanent magnet rotor configurations for efficiency above 90 percent. These motors serve the primary purpose of enabling smooth vertical transportation in mid-rise and high-rise structures while minimizing mechanical wear and acoustic emissions. Permanent magnet product types dominate installed base value due to rare-earth magnet performance density, while direct drive configurations represent the fastest-expanding category as building owners prioritize energy recovery and reduced maintenance intervals. New construction installations absorb the majority of unit volume, though retrofit activity is accelerating where existing geared systems face mandatory efficiency upgrades.
China's SAMR enforces GB standards for elevator energy consumption that effectively disqualify conventional geared systems from new high-rise permits. The EU F-Gas Regulation and Ecodesign directives pressure OEMs to demonstrate lifecycle carbon metrics across motor and refrigerant-adjacent building systems. India's BIS certification requirements for elevator safety components create compliance barriers for non-domestic suppliers seeking public infrastructure contracts. Stakeholders must monitor how regional efficiency mandates diverge between absolute energy thresholds and carbon-intensity metrics, as this split determines which motor architectures qualify for preferred procurement status.
Market Dynamics
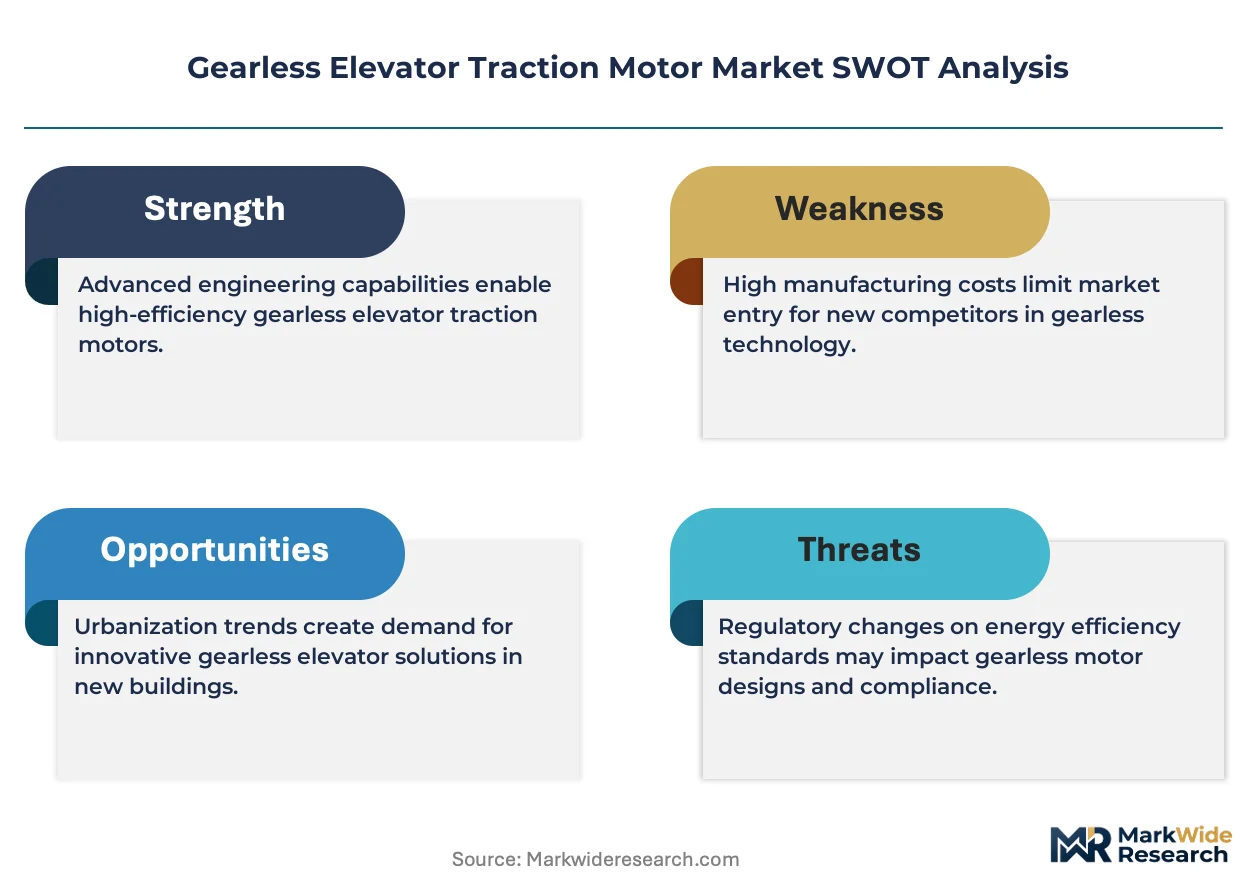
China's SAMR enforcement of GB energy-efficiency standards is structurally disqualifying geared elevator systems from new high-rise permits, forcing permanent magnet synchronous motor adoption across the supply base and collapsing the specification gap between premium and mid-tier procurement.
Growth Catalysts
- Permanent magnet rotor density:Rare-earth magnet performance enables torque output above 90 percent efficiency at synchronous speeds below 200 rpm, eliminating mechanical reduction stages in high-rise vertical transportation.
- India's smart city infrastructure:Urban verticalization mandates and BIS certification requirements for public building contracts are accelerating retrofit installations in existing building stock.
- EU F-Gas Regulation:Lifecycle carbon disclosure requirements for motor-adjacent building systems pressure OEMs to demonstrate energy recovery capabilities across permanent magnet configurations.
Market Restraints
- Rare-earth supply concentration:Neodymium and dysprosium processing capacity concentrates in Chinese refining operations, exposing motor manufacturers to input cost volatility and export restriction risk.
- Geared system installed base:Conventional reduction gearbox elevators in mid-rise commercial buildings face extended replacement cycles, delaying permanent motor penetration in retrofit channels.
- REACH substance restrictions:ECHA classification of certain magnet coatings and winding insulations creates compliance friction for permanent magnet motor configurations entering European markets.
Strategic Opportunities
- Direct drive convergence:Integration of permanent magnet motors with regenerative drive electronics and IoT condition monitoring creates bundled specification lock-in for mixed-use tower developers.
- India's PLI scheme:Production-linked incentives for advanced manufacturing components reduce effective capital intensity for domestic motor assembly operations serving public infrastructure contracts.
- Ultra-high-speed applications:Elevator systems above 10 meters per second in supertall structures require specialized torque density that permanent magnet architectures uniquely deliver.
Industry Challenges
- Electromagnetic compatibility certification:IEC 61000 series testing for variable frequency drive emissions extends product validation timelines and increases engineering headcount requirements.
- Legacy building integration:Existing machine room footprints and hoistway dimensions constrain direct drive motor form factors, requiring custom engineering for retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gearless Elevator Traction Motor Market |
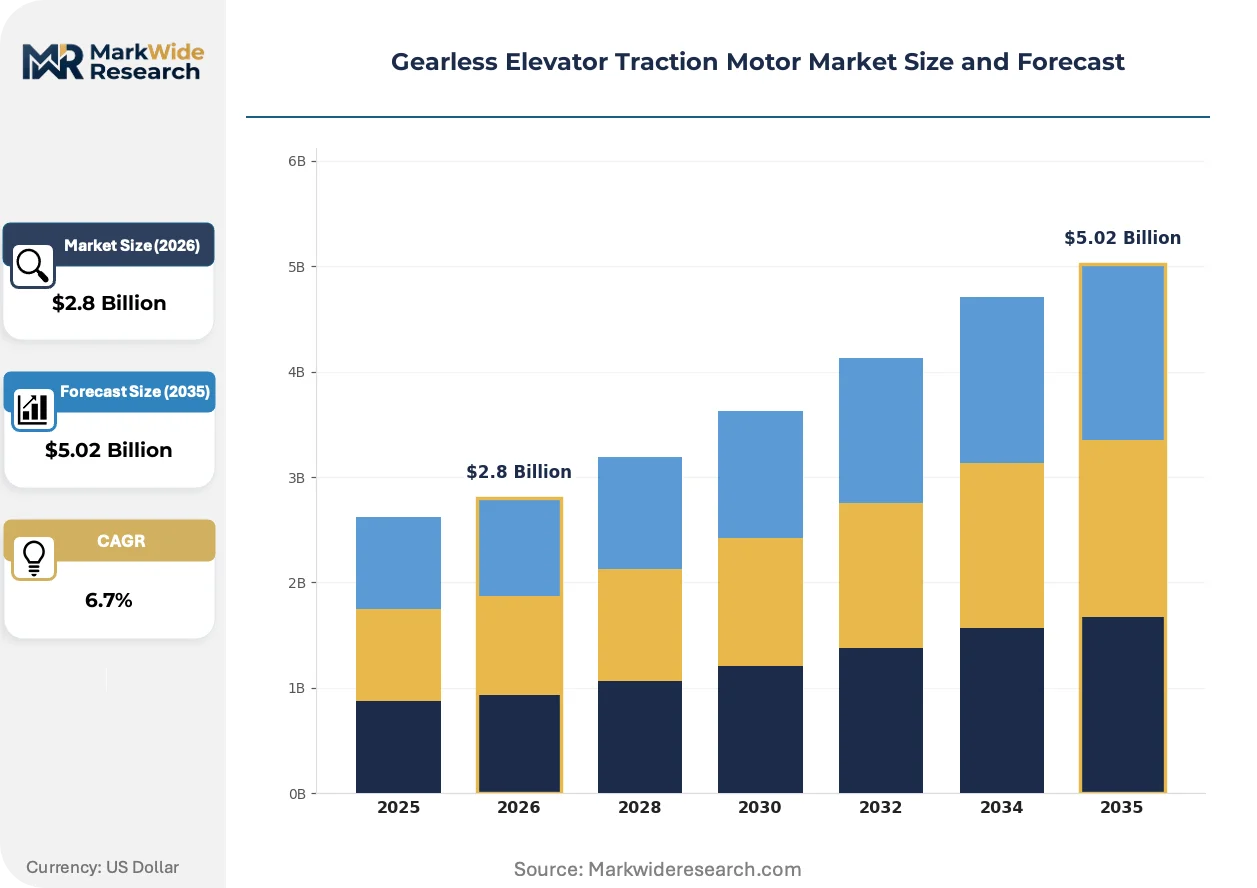
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Belt Drive, Direct Drive, Linear Motor, Permanent Magnet Installation Type: Indoor, Outdoor, Retrofit, New Construction End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Hospitals Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | KONE Corporation, Otis Elevator Company, Mitsubishi Electric Corporation, Yaskawa Electric Corporation, Thyssenkrupp Elevator, Xizi Forvorda, Ningbo Xinda Elevator Traction Technology, Suzhou Torin Drive Equipment, Schindler Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gearless Elevator Traction Motor Market Trends and Innovations
Permanent magnet synchronous motor architectures are decomposing the traditional gearbox-motor-controller stack into integrated electromechanical systems, compressing supplier tiers and reshaping how building developers specify vertical transportation equipment.
Silicon carbide power semiconductors in motor drive inverters are decomposing the thermal and switching-loss constraints that limited permanent magnet motor efficiency at ultra-low speeds. High-rise commercial developers in Shanghai and Shenzhen specify SiC-enabled drives for towers exceeding 300 meters. This semiconductor substitution reduces cooling system mass and enables machine-room-less configurations.
The EU F-Gas Regulation and Ecodesign directives are forcing lifecycle carbon accounting across elevator motor and refrigerant-adjacent building systems. OEMs must now document embodied carbon in magnet supply chains and end-of-life recovery protocols. Permanent magnet configurations with documented rare-earth recycling pathways gain preferred procurement status in German and French public infrastructure tenders.
Building owners are unbundling long-term service contracts from initial equipment procurement, compressing the traditional 15-20 year maintenance lock-in that protected incumbent motor suppliers. Facility managers in Singapore and Dubai now tender motor replacement and modernization separately from original installation contracts. This disaggregation exposes gearless motor manufacturers to price competition on aftermarket components and remote diagnostics subscriptions.
Gearless Elevator Traction Motor Market Segmentation
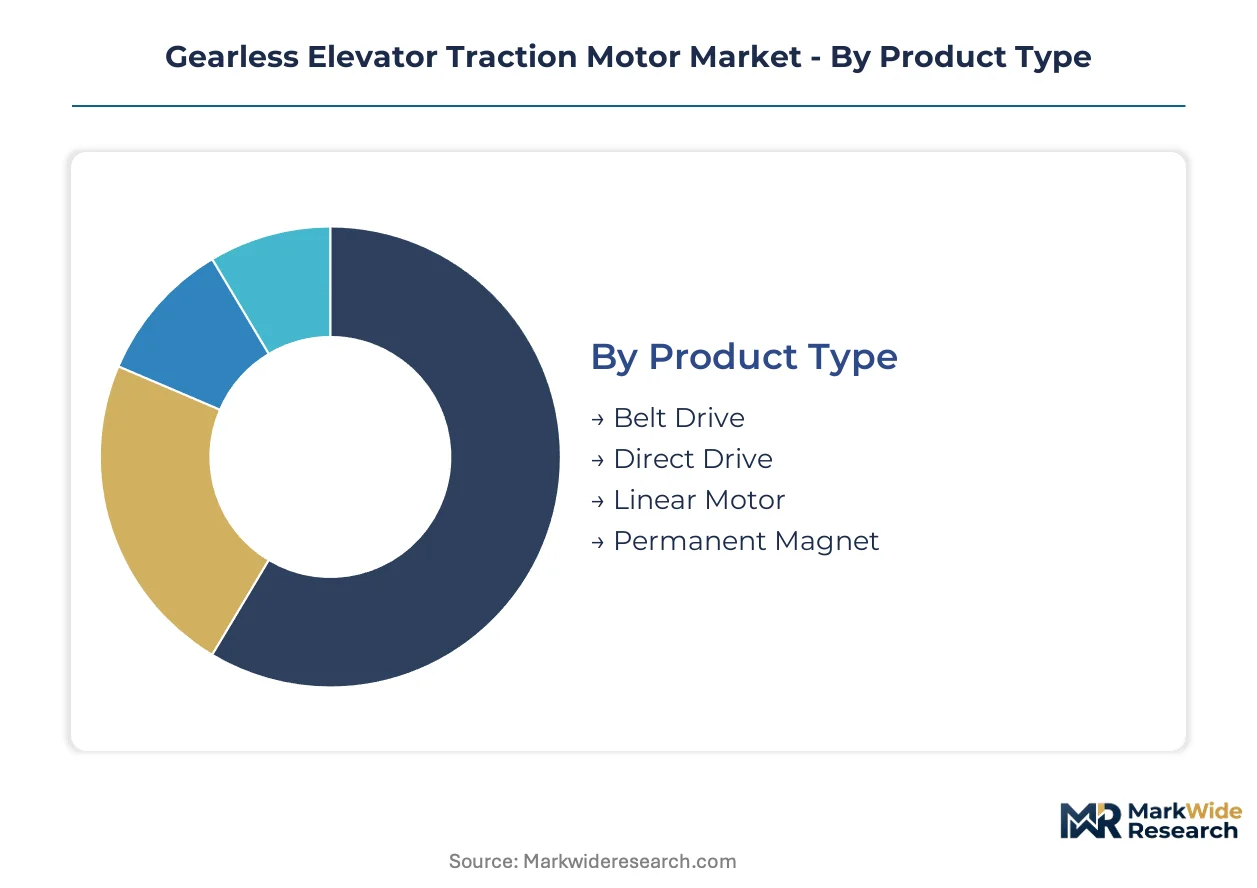
Channel configuration for gearless elevator traction motors varies sharply by segment. Direct drive and permanent magnet systems flow through OEM-integrated platforms, while belt drive and retrofit installations concentrate in independent service contractor networks.
Product Type:
Channel mix splits between integrated OEM supply for high-performance architectures and third-party distribution for legacy-compatible configurations.
- Permanent Magnet:Rare-earth magnet rotor assemblies achieve torque density above 90 percent efficiency at synchronous speeds below 200 rpm. Demand concentrates in Shanghai and Shenzhen supertall towers where China's SAMR enforces GB energy-efficiency standards that disqualify geared alternatives.
- Direct Drive:Elimination of mechanical reduction stages couples the drive sheave directly to a low-speed, high-torque motor. Building owners in Singapore and Dubai prioritize this architecture for machine-room-less configurations and regenerative energy recovery.
- Belt Drive:Flat or toothed belt power transmission suits mid-rise commercial retrofits with constrained hoistway dimensions.
- Linear Motor:Magnetically levitated propulsion eliminates cables and counterweights for specialized high-rise applications.
By volume, permanent magnet leads. By growth pace, direct drive is gaining share fastest.
Installation Type:
Cost tier separation is pronounced: new construction absorbs premium permanent magnet systems, while retrofit channels favor phased modernization with belt drive or direct drive drop-in replacements.
- New Construction:Greenfield high-rise developments specify integrated permanent magnet synchronous motors with SiC-enabled drives during initial procurement. India's smart city infrastructure mandates in Mumbai and Bengaluru accelerate specification lock-in for mixed-use towers.
- Retrofit:Existing geared system replacement demands custom engineering for legacy machine room footprints and hoistway constraints. India's BIS certification requirements for public building contracts filter non-domestic suppliers from this channel.
- Indoor:Climate-controlled environments enable compact motor form factors with reduced thermal management overhead.
- Outdoor:Weatherproof enclosures and extended temperature range windings serve transit infrastructure and coastal high-rises.
New construction dominates absolute unit flow. Retrofit exhibits the steepest expansion trajectory as mandatory efficiency upgrades displace aging geared installations.
End User:
Application concentration determines margin structure: commercial towers sustain premium pricing, while residential and industrial segments drive volume through standardized configurations.
- Commercial Buildings:Mixed-use towers and corporate headquarters demand ultra-high-speed applications above 10 meters per second. Developers in Shanghai and Shenzhen specify permanent magnet architectures with documented rare-earth recycling pathways to satisfy EU F-Gas Regulation lifecycle carbon disclosure.
- Hospitals:Continuous-duty reliability requirements and acoustic emission limits favor direct drive configurations with IoT condition monitoring.
- Residential Buildings:Mid-rise apartment stock in India and Southeast Asia absorbs belt drive and low-power permanent magnet units through cost-optimized procurement.
- Industrial Facilities:Heavy-duty freight elevators and automotive plant vertical logistics require high-torque direct drive motors with extended maintenance intervals.
Commercial buildings anchor revenue concentration. Hospitals are climbing the fastest as healthcare infrastructure verticalizes in Tier-2 Indian cities.
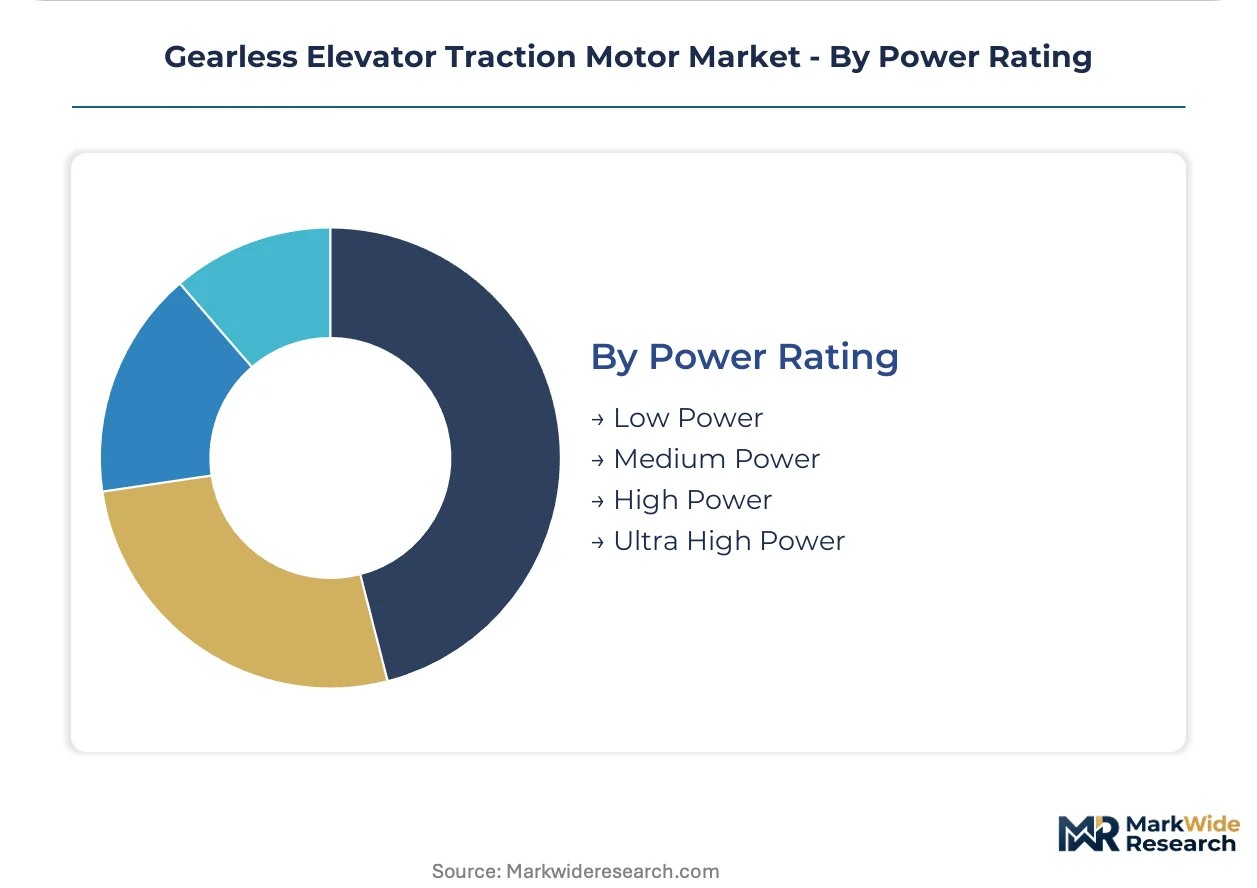
Power Rating:
Customer type alignment shows clear stratification: real estate investment trusts specify ultra high power for signature towers, while facility managers at mid-rise commercial assets cluster in medium power tiers.
- High Power:Motors rated for elevators above 5 meters per second serve supertall structures exceeding 300 meters. China's dual carbon goals and updated GB standards reshape procurement criteria toward these configurations.
- Medium Power:Standard high-rise commercial and residential applications balance capital cost against efficiency gains.
- Low Power:Compact permanent magnet units for mid-rise residential and light commercial installations.
- Ultra High Power:Specialized torque density for mega-tower observation decks and heavy-capacity freight systems.
Medium power leads by installed base volume. High power is expanding most quickly as Asia-Pacific high-rise construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Suzhou-Nantong bridge-tunnel complex anchors Asia-Pacific elevator motor demand by connecting the world's densest high-rise construction corridor. Germany's Rhine-Alpine freight corridor sustains European specification leadership through integrated building systems procurement. The Dubai Metro Red Line extension demonstrates how Gulf transit infrastructure concentrates vertical transportation demand in supertall clusters.
China
Shanghai and Shenzhen supertall towers exceeding 300 meters absorb permanent magnet synchronous motors for ultra-high-speed applications above 10 meters per second. SAMR enforcement of GB energy-efficiency standards structurally disqualifies geared systems from new high-rise permits. The Yangtze River Delta manufacturing belt around Suzhou hosts domestic motor assembly operations serving both local tower developers and export markets.
India
Mumbai and Bengaluru smart city infrastructure mandates accelerate specification lock-in for mixed-use towers requiring machine-room-less configurations. BIS certification requirements for elevator safety components filter non-domestic suppliers from public infrastructure contracts. The Maharashtra industrial corridor around Pune hosts emerging domestic motor assembly operations leveraging PLI scheme incentives.
Germany
Frankfurt and Munich commercial tower developers specify permanent magnet architectures with documented rare-earth recycling pathways. ECHA REACH substance restrictions on magnet coatings and winding insulations create compliance friction for non-European motor configurations. The Baden-Württemberg industrial cluster around Stuttgart anchors R&D intensity for ultra-high-speed elevator applications.
United States
New York and Chicago high-rise retrofits demand custom engineering for legacy machine room footprints and hoistway constraints. ASME A17 elevator safety standards mandate electromagnetic compatibility certification extending product validation timelines. The Southeast construction corridor from Atlanta to Miami absorbs belt drive and direct drive drop-in replacements for aging geared installations.
United Arab Emirates
Dubai supertall observation decks and luxury hospitality towers require specialized torque density for elevator systems above 10 meters per second. MOHAP building safety regulations align with EU F-Gas lifecycle carbon disclosure requirements for imported equipment. The Dubai South logistics district concentrates aftermarket service operations for regional tower portfolios.
Gearless Elevator Traction Motor Market Competitive Landscape
Concentration sits with integrated elevator-to-motor platforms and rare-earth magnet R&D specialists. The vendor base stratifies across three tiers: multinational OEMs with captive motor production, dedicated traction motor fabricators serving multiple elevator brands, and emerging Asian component suppliers capturing retrofit volume. Strategic moves center on backward integration into permanent magnet supply chains and geographic expansion through production-linked incentive schemes in India and Southeast Asia.
Among Finland-based integrated platform providers, KONE Corporation exemplifies specification lock-in across mixed-use tower developments. Japanese electrical conglomerates including Mitsubishi Electric Corporation and Yaskawa Electric Corporation occupy positions defined by permanent magnet motor R&D intensity. Chinese specialists including Ningbo Xinda Elevator Traction Technology and Suzhou Torin Drive Equipment represent the cost-optimized tier serving domestic retrofit demand and export markets.
| Leading Market Players |
|---|
| KONE Corporation |
| Otis Elevator Company |
| Mitsubishi Electric Corporation |
| Yaskawa Electric Corporation |
| Thyssenkrupp Elevator |
| Xizi Forvorda |
| Ningbo Xinda Elevator Traction Technology |
| Suzhou Torin Drive Equipment |
| Schindler Group |
| Others |
Pricing and Supply Chain Analysis
China's SAMR enforcement of GB energy-efficiency standards gates both supplier qualification and price differentiation simultaneously, collapsing the specification gap between premium and mid-tier procurement while concentrating pricing power among permanent magnet motor architectures that satisfy permit requirements.
Pricing Analysis
Volume-discount tiering separates OEM-integrated platforms from independent service contractor channels, with premium pricing anchored to permanent magnet synchronous motor efficiency certifications and documented rare-earth recycling pathways. Price differentiation centers on GB standard compliance tier and SiC-enabled drive integration depth. Cost compression in mid-tier retrofit channels intensifies as India's PLI scheme attracts domestic assembly operations. Real estate investment trusts exhibit lowest price sensitivity for supertall tower specifications, while facility managers at aging mid-rise commercial assets drive hardest bargain negotiations.
Supply Chain Analysis
Strategic stockpiling of rare-earth magnet inventories dominates procurement behavior as motor manufacturers buffer against neodymium and dysprosium processing concentration in Chinese refining operations. Raw material dependencies center on rare-earth oxides, silicon carbide semiconductors, and specialized winding insulations. Single-source vulnerability in magnet supply exposes fabricators to export restriction risk. Distribution runs through OEM captive networks for new construction and independent service contractors for retrofit channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gearless elevator traction motor demand tracks commercial construction cycles, with Asia-Pacific high-rise development serving as the primary cyclical recovery engine.
For Market Incumbents: Compound specification lock-in through backward integration into permanent magnet supply chains and captive SiC drive electronics production. Defend against emerging Chinese cost-optimized entrants by accelerating IEC 61000 electromagnetic compatibility certification timelines. Prioritize machine-room-less configuration R&D to capture India's smart city infrastructure mandates.
For New Entrants and Emerging Players: Lead with India's BIS-certified domestic assembly operations targeting public infrastructure retrofit contracts filtered from non-domestic suppliers. Exploit white-space in Tier-2 Indian city hospital verticalization where healthcare infrastructure demands IoT-enabled direct drive configurations. Pursue white-label partnerships with European independent service contractors seeking REACH-compliant magnet sourcing alternatives.
For Investors and Strategic Acquirers: China's dual carbon goal enforcement reshapes the acquisition landscape toward permanent magnet motor specialists with documented rare-earth recycling pathways. Long-term viability favors integrated elevator-to-motor platforms over standalone traction motor fabricators. Watch for EU F-Gas Regulation lifecycle carbon disclosure threshold tightening as the inflection signal for preferred procurement status reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | SAMR GB standard compliance locks in permanent magnet motor procurement for Shanghai supertall towers. |
| SiC-Enabled Drive Electronics Development | Machine-room-less configurations satisfy Shenzhen developer specifications for towers exceeding 300 meters. |
| India PLI Scheme Manufacturing Footprint | BIS certification eligibility opens public infrastructure contracts in Mumbai and Bengaluru smart city zones. |
| Documented Rare-Earth Recycling Pathways | EU F-Gas lifecycle carbon disclosure qualifies motors for German and French public tender preference. |
| IoT Condition Monitoring Platform Integration | Aftermarket service disaggregation in Singapore and Dubai demands remote diagnostics subscription revenue. |
Research Methodology
The analysis maps permanent magnet synchronous motor, direct drive, belt drive, and linear motor sub-sectors, each validated through elevator OEM procurement directors, independent service contractor operations managers, and building developer specification engineers. Primary interview intelligence triangulates against customs trade data, SAMR GB standard filings, EU ECHA REACH substance registrations, and India BIS certification databases. Bottom-up unit demand modeling reconciles with top-down construction spend forecasts.
Consistency checks validate volume and value outputs against Asia-Pacific high-rise construction permits, EU Ecodesign directive compliance disclosures, and India smart city infrastructure tender awards. Segmentation dimensions span product architecture, installation type, end-user application, power rating tier, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to construction pipeline data and mandatory efficiency upgrade cycles. Industry-specific inputs include rare-earth magnet price indices and SiC semiconductor supply constraints.
Forecasts assume regulatory continuity in China's SAMR enforcement, India's BIS certification regime, and EU F-Gas lifecycle carbon disclosure requirements; material policy shifts would require re-modeling. Revision becomes warranted when rare-earth export restriction severity or REACH substance reclassification crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
China AC Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Power Scraper Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Hoist and Elevator Motors Market