
 Asia Pacific and Middle East and Africa Submerged Arc Furnace Market | 2026-2036
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market Outlook
CE marking under the EU Machinery Directive is collapsing as a de facto gate for equipment exports into Middle Eastern markets, compelling Chinese and Indian fabricators to pursue parallel conformity routes. Metso Outotec leverages its integrated smelter technology portfolio to anchor large-scale ferroalloy projects across Indonesia and Oman. SMS Group competes through specialized submerged arc furnace designs optimized for high-carbon ferrochrome. Xi'an Abundance Electric Technology Co., Ltd dominates domestic Chinese retrofits and extends its footprint into Central Asian copper smelting upgrades.
A submerged arc furnace employs electric arcs buried beneath a conductive slag and charge layer to generate temperatures exceeding 1,800°C for reducing metal oxides into ferroalloys, pig iron, or non-ferrous matte. Electrode arrays—typically Søderberg or pre-baked carbon—penetrate the charge column to deliver sustained megawatt-scale thermal energy with minimal fugitive emission exposure. Ferroalloy production commands the largest installed base owing to sustained stainless steel demand, while non-ferrous metals processing represents the fastest-growing technology application as battery-metal smelters adopt submerged arc configurations for nickel and cobalt recovery. Resistance heating variants retain niche positions in small-scale foundry operations where arc stability proves economically impractical.
India's Central Electricity Authority enforces mandatory efficiency audits for furnaces above 25 MVA, directly shaping capital equipment specifications across Maharashtra and Odisha. China's Ministry of Ecology and Environment imposes particulate and SOx discharge limits that filter out legacy open-furnace designs from new project approvals. Saudi Arabia's SFDA-aligned industrial safety protocols for high-current installations add compliance layers for European entrants targeting Gulf smelter expansions. Stakeholders must monitor how carbon-border adjustment mechanisms reshape the cost calculus for alloy exports originating from coal-intensive submerged arc operations.
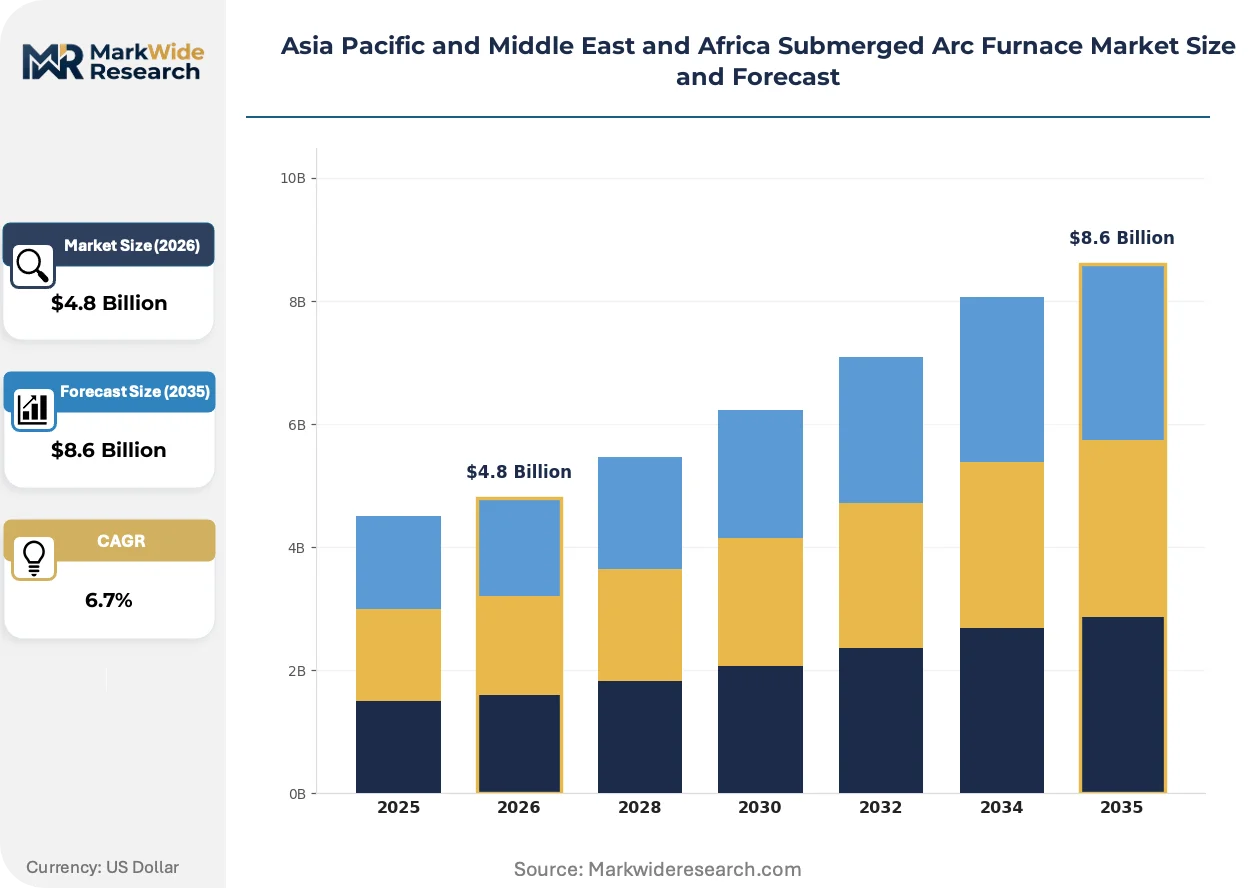
Market Dynamics
China's MIIT energy-efficiency mandates and India's BIS emission standards are collapsing legacy open-furnace designs from new project approvals, forcing fabricators to pursue parallel conformity routes for export qualification.
Growth Catalysts
- India's BIS emission standards:Tightening equipment qualification thresholds across Maharashtra and Odisha are accelerating replacement cycles for captive ferrochrome operations feeding stainless steel expansion.
- Non-ferrous metals processing:Battery-metal smelters adopting submerged arc configurations for nickel and cobalt recovery represent the fastest-growing technology application segment.
- Eastern India steel belt concentration:Captive ferrochrome operations clustered in Odisha and Jharkhand are driving sustained infrastructure-grade ferroalloy furnace demand.
Market Restraints
- Electrode input cost volatility:Søderberg and pre-baked carbon electrode supply fluctuations compress margins for operators running megawatt-scale thermal arrays.
- Chinese fabricator supply concentration:Dominance of domestic Chinese retrofits limits equipment diversity and creates bottleneck risk for regional project timelines.
- CE marking collapse as de facto gate:Loss of European conformity recognition as automatic export passport forces costly parallel certification for Middle Eastern market entry.
Strategic Opportunities
- Saudi Arabia SFDA-aligned industrial safety protocols:New compliance layers for high-current installations create first-mover advantage for European entrants targeting Gulf smelter expansions.
- Indonesia nickel processing integration:Large-scale ferroalloy projects seeking integrated smelter technology anchor points for equipment suppliers with full technology portfolios.
- Central Asian copper smelting upgrades:Retrofit demand extending beyond domestic Chinese markets offers geographic diversification for furnace technology providers.
Industry Challenges
- Carbon-border adjustment mechanism readiness:Alloy exporters from coal-intensive submerged arc operations face cost calculus disruption requiring emission accounting system overhauls.
- 25 MVA efficiency audit compliance:India's Central Electricity Authority mandatory requirements demand specialized engineering talent scarce across Maharashtra and Odisha.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific and Middle East and Africa Submerged Arc Furnace Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferroalloys, Pig Iron, Steel, Non-Ferrous Metals Technology: Electric Arc, Induction Furnace, Resistance Heating, Plasma Arc End User: Steel Manufacturers, Foundries, Mining, Recycling Application: Metal Production, Alloy Manufacturing, Casting, Smelting |
| Companies Covered | Shanghai Electric Group Co., Ltd, Metso Outotec, Xi’an Abundance Electric Technology Co., Ltd, Danieli, SMS Group, CHNZBTECH, Electrotherm, Paul Wurth, Dalian Huarui Heavy Industry Group Co., Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market Strategic Shifts
Equipment architecture is compressing around closed furnace designs that bury electric arcs beneath conductive slag layers, eliminating fugitive emission exposure while sustaining temperatures exceeding 1,800°C for metal oxide reduction.
Closed furnace shell technology is miniaturizing the footprint required for equivalent ferroalloy throughput. Indonesian nickel smelters adopting these configurations achieve comparable output in 40% less physical plant space. Battery-grade cobalt recovery operations across Southeast Asia are compressing capex timelines by specifying these compact thermal arrays.
China's Ministry of Ecology and Environment particulate and SOx discharge limits are filtering legacy open-furnace designs from new project approvals. Fabricators must now engineer closed-loop gas handling systems to qualify for environmental permits. Ferrochrome producers in Shanxi and Inner Mongolia are retrofitting existing installations to meet these tightened thresholds.
Buyers are consolidating procurement around integrated smelter technology providers capable of delivering electrode arrays, furnace shells, and emission control as unified packages. Traditional component vendors face displacement as Indonesian and Omani project developers specify single-source accountability. This bundling preference is most pronounced in large-scale ferroalloy investments exceeding 50 MVA rated capacity.
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market Segmentation
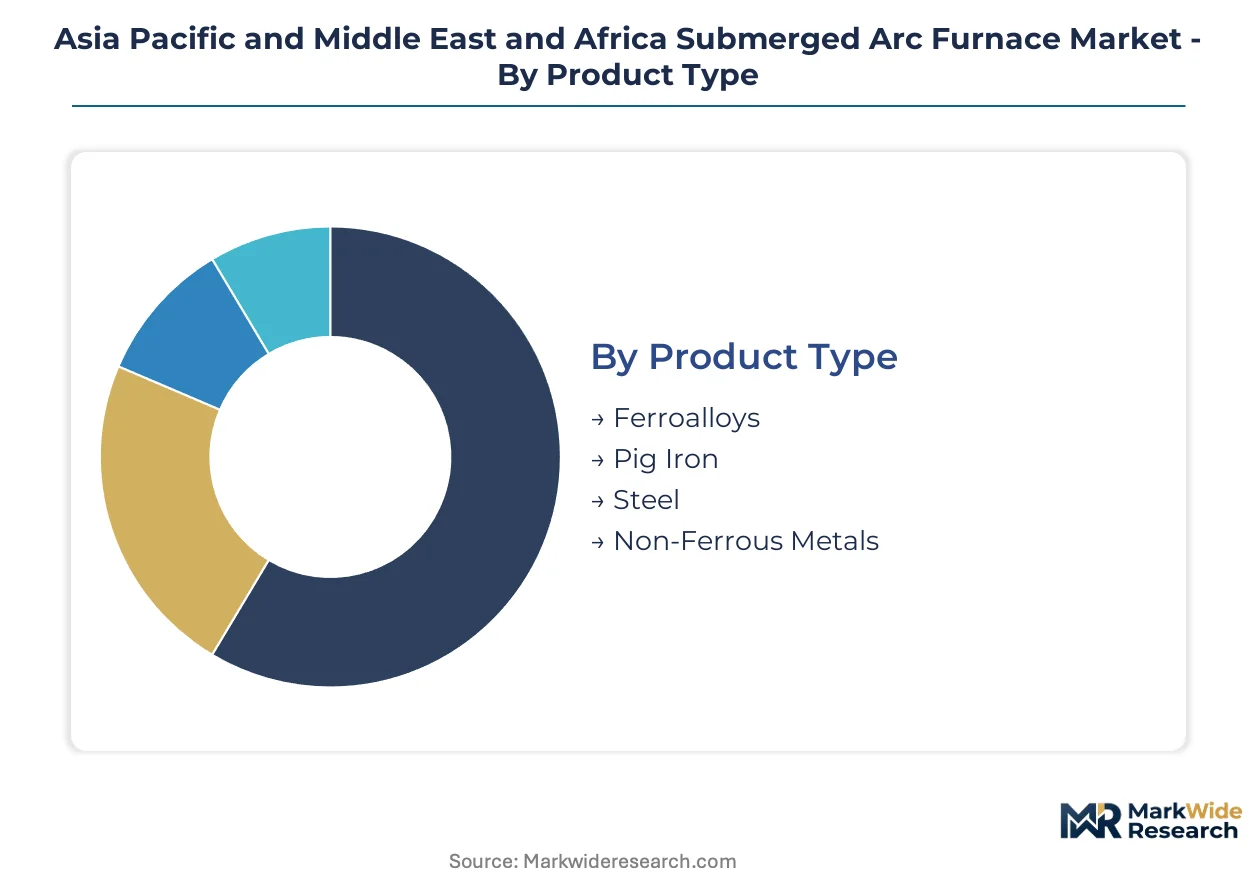
Segmentation reveals how submerged arc furnace demand fractures across metallurgical applications, thermal technologies, and customer procurement patterns. Understanding these divides exposes where equipment specifications diverge and which buyer categories command premium engineering resources.
Product Type:
Margin pools concentrate in ferroalloy production systems where stainless steel feedstock demand sustains long-delivery, high-specification contracts.
- Ferroalloys:Electric arc configurations buried beneath conductive slag layers reduce metal oxides at temperatures exceeding 1,800°C for chromium and silicon alloys. India's eastern steel belt in Odisha and Jharkhand drives captive ferrochrome furnace procurement as stainless steel capacity expands.
- Non-Ferrous Metals:Battery-metal smelters across Indonesia and Southeast Asia are adopting submerged arc configurations for nickel and cobalt recovery. This segment is expanding most quickly as cathode material supply chains localize.
- Pig Iron:Foundry-grade installations in Maharashtra and Gujarat serve automotive casting demand with smaller furnace footprints.
- Steel:Integrated mills in China and India deploy large-scale systems for direct reduction and refining operations.
The dominant share belongs to Ferroalloys, while Non-Ferrous Metals is closing the gap fastest.
Technology:
Equipment selection hinges on thermal efficiency mandates from China's MIIT and India's CEA, which filter out legacy designs from new project approvals.
- Electric Arc:Electrode arrays penetrating charge columns deliver sustained megawatt-scale thermal energy with minimal fugitive emission exposure. China's Ministry of Ecology and Environment particulate discharge limits are forcing fabricators toward closed-loop gas handling configurations.
- Resistance Heating:Niche positioning in small-scale foundry operations where arc stability proves economically impractical. Indian component suppliers dominate this cost-sensitive tier serving Maharashtra job shops.
- Induction Furnace:Deployed where precise temperature control outweighs throughput requirements in specialty alloy batches.
- Plasma Arc:Emerging configurations for high-purity non-ferrous recovery in Southeast Asian battery material plants.
Electric Arc retains the installed base majority, though Resistance Heating maintains stubborn presence in fragmented foundry procurement.
End User:
Customer scale determines whether procurement consolidates around integrated technology providers or fragments across component vendors.
- Steel Manufacturers:Large-scale ferroalloy investments exceeding 50 MVA rated capacity specify single-source accountability for electrode arrays, furnace shells, and emission control. Indonesian and Omani project developers are bundling procurement to reduce interface risk.
- Mining:Captive smelter operations in Central Asia and Saudi Arabia are driving retrofit demand as SFDA-aligned safety protocols add compliance layers for high-current installations.
- Foundries:Maharashtra and Gujarat job shops prioritize capital efficiency over thermal optimization in smaller batch operations.
- Recycling:Secondary metal processors in Southeast Asia are piloting submerged arc configurations for complex feedstock recovery.
Steel Manufacturers absorb the dominant equipment volume, while Mining is gaining share fastest on Gulf smelter expansion timelines.
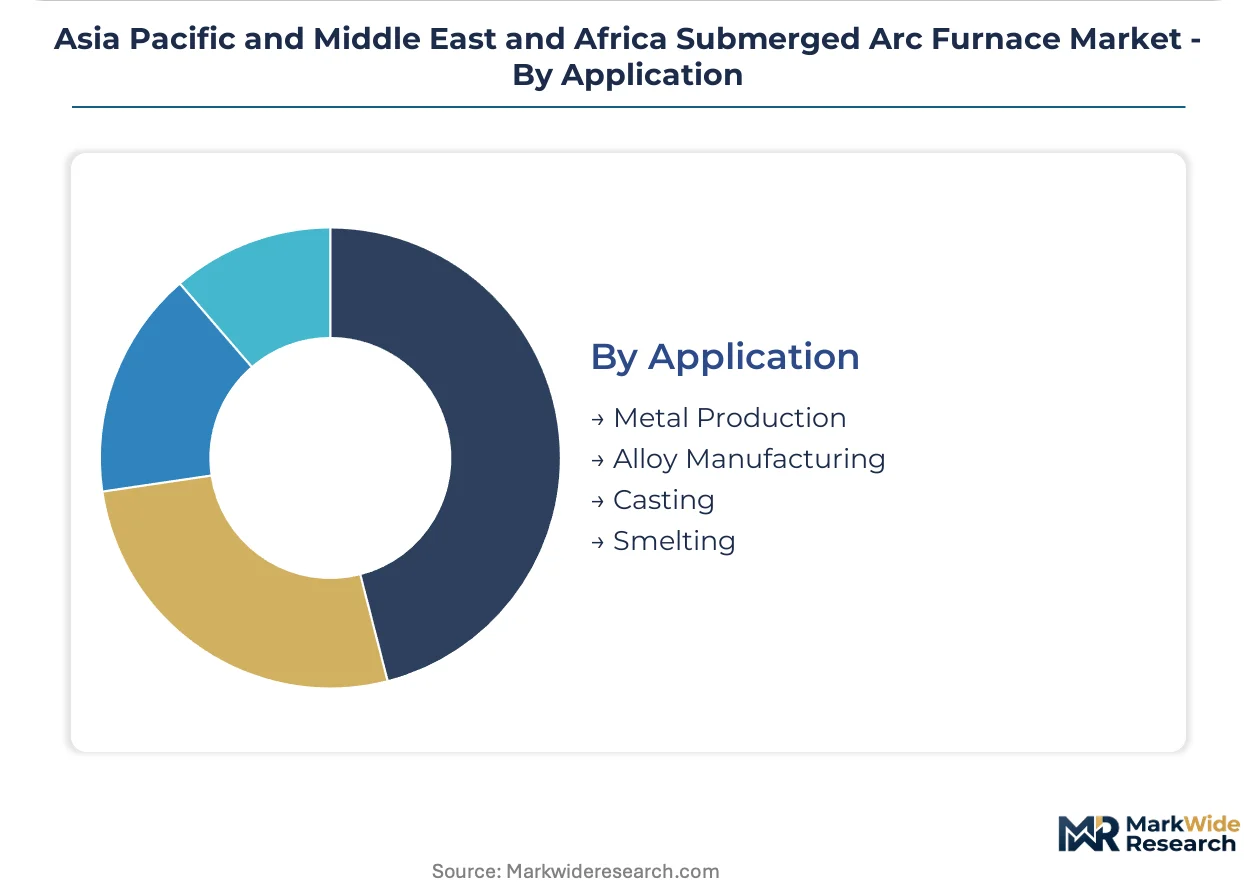
Application:
Process intensity separates applications requiring continuous operation from batch configurations with intermittent thermal cycles.
- Metal Production:Primary reduction of iron ores and metal oxides commands the longest furnace campaign lives and highest electrode consumption rates. Shanxi and Inner Mongolia ferrochrome producers are retrofitting existing installations to meet China's tightened environmental thresholds.
- Smelting:Concentrated matte formation for copper and nickel recovery is climbing the fastest as battery supply chains localize in Indonesia and the Philippines.
- Alloy Manufacturing:Precise chemistry control in ferrosilicon and ferromanganese batches serves stainless steel specification tightening.
- Casting:Foundry melt shops in India's western industrial corridors prioritize rapid heat-up cycles over energy efficiency.
Metal Production holds the dominant application share, though Smelting is closing the gap fastest on battery metal investment waves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel manufacturers and ferroalloy producers dominate procurement across the Asia Pacific and Middle East and Africa region, with captive smelter investments clustering around stainless steel expansion corridors and battery metal processing hubs.
China
MIIT energy-efficiency mandates and MEE particulate discharge limits are filtering legacy open-furnace designs from new project approvals. Fabricators in Shanxi and Inner Mongolia are retrofitting existing ferrochrome installations to meet tightened environmental thresholds. Xi'an Abundance Electric Technology anchors domestic retrofit demand while extending into Central Asian copper smelting upgrades.
India
CEA mandatory efficiency audits for furnaces above 25 MVA are shaping capital equipment specifications across Maharashtra and Odisha. BIS emission standards are accelerating replacement cycles for captive ferrochrome operations. The eastern steel belt in Jharkhand and Odisha drives sustained infrastructure-grade ferroalloy furnace procurement as stainless steel capacity expands.
Indonesia
Battery-metal smelters are adopting submerged arc configurations for nickel and cobalt recovery as cathode material supply chains localize. Large-scale ferroalloy projects exceeding 50 MVA rated capacity specify single-source accountability for integrated smelter technology. Closed furnace shell designs are compressing physical plant space requirements by 40% compared to legacy configurations.
Saudi Arabia
SFDA-aligned industrial safety protocols for high-current installations are adding compliance layers for European entrants targeting Gulf smelter expansions. Mining-sector captive smelter operations are driving retrofit demand across the Kingdom's industrial cities. European fabricators are pursuing parallel conformity routes to replace collapsed CE marking recognition as automatic export passport.
Oman
Integrated smelter technology providers are anchoring large-scale ferroalloy projects through bundled procurement of electrode arrays, furnace shells, and emission control systems. Project developers are consolidating procurement around unified packages to reduce interface risk. Gulf smelter expansions are creating first-mover advantages for equipment suppliers with full technology portfolios.
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market Competitive Environment
Player mix skews toward integrated technology providers and specialized furnace fabricators competing across distinct procurement tiers. The vendor base separates between full-portfolio suppliers capable of single-source accountability and component specialists serving cost-sensitive retrofit segments. Three archetypes dominate: integrated smelter technology providers, specialized submerged arc furnace designers, and domestic retrofit specialists. Competitive moves center on geographic expansion into battery metal processing hubs and portfolio diversification through emission control bundling.
Among integrated technology providers, Metso Outotec and SMS Group exemplify the premium-tier positioning that project developers in Indonesia and Oman specify for large-scale ferroalloy investments. Xi'an Abundance Electric Technology occupies a position within the domestic Chinese retrofit specialist archetype, representing the supply concentration that creates bottleneck risk for regional project timelines. Danieli sits within the European fabricator tier navigating parallel conformity routes as CE marking collapses as de facto gate for Middle Eastern market entry.
| Leading Market Players |
|---|
| Shanghai Electric Group Co., Ltd |
| Metso Outotec |
| Xi'an Abundance Electric Technology Co., Ltd |
| Danieli |
| SMS Group |
| CHNZBTECH |
| Electrotherm |
| Paul Wurth |
| Dalian Huarui Heavy Industry Group Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Pre-baked carbon electrode substitution for Søderberg variants is simultaneously shifting procurement geography toward Japanese and South Korean specialty carbon producers and compressing electrode input cost volatility into more predictable long-term contract structures for Indian and Southeast Asian furnace operators.
Pricing Analysis
Cost-plus contracts indexed to Shanghai Futures Exchange ferrochrome benchmarks dominate large-scale procurement above 50 MVA capacity. Price differentiation rests on CEA efficiency audit certification tier and integrated emission control bundling. Margins are tightening due to Chinese fabricator supply concentration compressing equipment diversity. Foundry-grade operators in Maharashtra exhibit highest price sensitivity, while Indonesian nickel smelters with single-source accountability requirements show lowest.
Supply Chain Analysis
Inbound logistics costs through Singapore port congestion and Red Sea container availability constraints are elevating landed cost premiums for European fabricators serving Gulf smelter expansions. Electrode arrays and furnace shell fabrication concentrates in China, Germany, and Finland. Raw material dependencies center on high-purity graphite electrodes, copper contact assemblies, and refractory ceramic linings. Single-source vulnerability from Chinese domestic retrofit specialist dominance creates bottleneck risk. Distribution runs through EPC contractor-led project bundling for large-scale ferroalloy investments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket electrode management and predictive maintenance subscriptions are expanding faster than hardware sales as Indonesian and Omani operators prioritize uptime guarantees over capital expenditure minimization.
For Market Incumbents: Compound service revenue through captive electrode supply arrangements and remote thermal monitoring subscriptions. Defend position against Xi'an Abundance Electric Technology's Central Asian expansion by securing CEA efficiency audit pre-certification for Maharashtra and Odisha retrofit cycles. Prioritize backward integration into pre-baked carbon electrode sourcing.
For New Entrants and Emerging Players: Aftermarket retrofit engineering for sub-25 MVA furnaces escaping mandatory CEA audit thresholds represents the most penetrable white-space. Target Maharashtra and Gujarat foundry clusters with resistance heating variant specialization. Pursue go-to-market through component vendor partnerships rather than EPC prime contracting.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated smelter technology providers with emission control bundling capabilities. Long-term viability hinges on carbon-border adjustment mechanism readiness and SFDA-aligned safety protocol compliance depth. Acquisition target archetype: European fabricators with parallel conformity route completion for Middle Eastern market entry. Signal to watch: BIS emission standard threshold tightening accelerating replacement cycle velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Manufacturing | Captive graphite electrode supply secures margin protection against Søderberg-pre-baked substitution volatility. |
| CEA Pre-Certification Program | Pre-approved furnace designs compress Maharashtra and Odisha project approval timelines. |
| Remote Thermal Monitoring Platform | Predictive maintenance subscriptions attach recurring revenue to Indonesian nickel smelter installations. |
| SFDA Safety Protocol Compliance Suite | High-current installation certification creates first-mover positioning for Gulf smelter expansions. |
| Closed Furnace Shell Miniaturization | 40% footprint reduction technology captures Indonesian battery-metal processing integration demand. |
Study Parameters
Desk research of customs trade filings, MIIT equipment registration databases, and BIS certification records preceded structured interviews with plant engineers at captive ferrochrome operations, EPC contractors in Indonesia and Oman, aftermarket service heads at integrated technology providers, and procurement leads at Saudi mining-sector smelter developments. Secondary validation drew from CEA efficiency audit disclosure summaries, MEE particulate discharge permit registries, and SFDA industrial safety protocol documentation. Bottom-up furnace installation tallies across Odisha, Jharkhand, Shanxi, and Inner Mongolia triangulated against top-down ferroalloy production capacity estimates.
Variance decomposition across product type, technology, end user, and application dimensions structured the analytical framework over the projection horizon. CAGRs derived from segment-level demand elasticity modeling against stainless steel capacity expansion timelines and battery-metal smelter investment waves. Industry-specific forecast inputs included BIS emission standard implementation velocity and carbon-border adjustment mechanism coverage scope for alloy exports.
Material uncertainties — regulatory threshold revisions, electrode input cost shocks, and Red Sea logistics disruption persistence — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding CEA audit enforcement consistency and MIIT energy-efficiency mandate adherence rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
China AC Motor Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Gear Motor Market