
 Global Linear Motors Market | 2026-2036
Global Linear Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Linear Motors Market Outlook
Permanent magnet arrays is broadening the addressable cost envelope for high-force linear motor systems. YASKAWA Electric Corporation leverages integrated servo architectures to dominate motion control in Japanese semiconductor fabs. Bosch Rexroth AG anchors European demand through its Stuttgart-based linear drive manufacturing campus. Aerotech Inc. specializes in ultra-precision air-bearing linear stages for lithography and metrology end uses.
Linear motors convert electrical energy directly into linear mechanical force without rotary-to-linear transmission elements, typically achieving positioning accuracy below one micron with accelerations exceeding 5 g. These devices eliminate mechanical backlash, reduce maintenance intervals, and enable direct-drive motion in precision automation equipment. Permanent magnet linear synchronous motors capture the dominant share of high-performance applications where force density and thermal efficiency determine system economics. Linear induction motors serve cost-sensitive material handling and transportation segments where simpler construction outweighs efficiency penalties. Servo control technology underpins the fastest-expanding application layer as real-time encoder feedback and digital fieldbus integration become standard in CNC machines and robotic cells.
FDA device manufacturing regulations in the United States enforce validated motion control in medical product assembly lines, directly specifying traceable positioning repeatability. The EU Machinery Directive and CE marking framework mandate functional safety integration in European-deployed linear motor systems, elevating compliance costs for non-integrated suppliers. China's GB standards and MIIT industrial policy accelerate domestic substitution in precision motion components. Stakeholders must weigh rare-earth supply exposure against magnet performance requirements when configuring product platforms for regional manufacturing footprints.
Market Dynamics
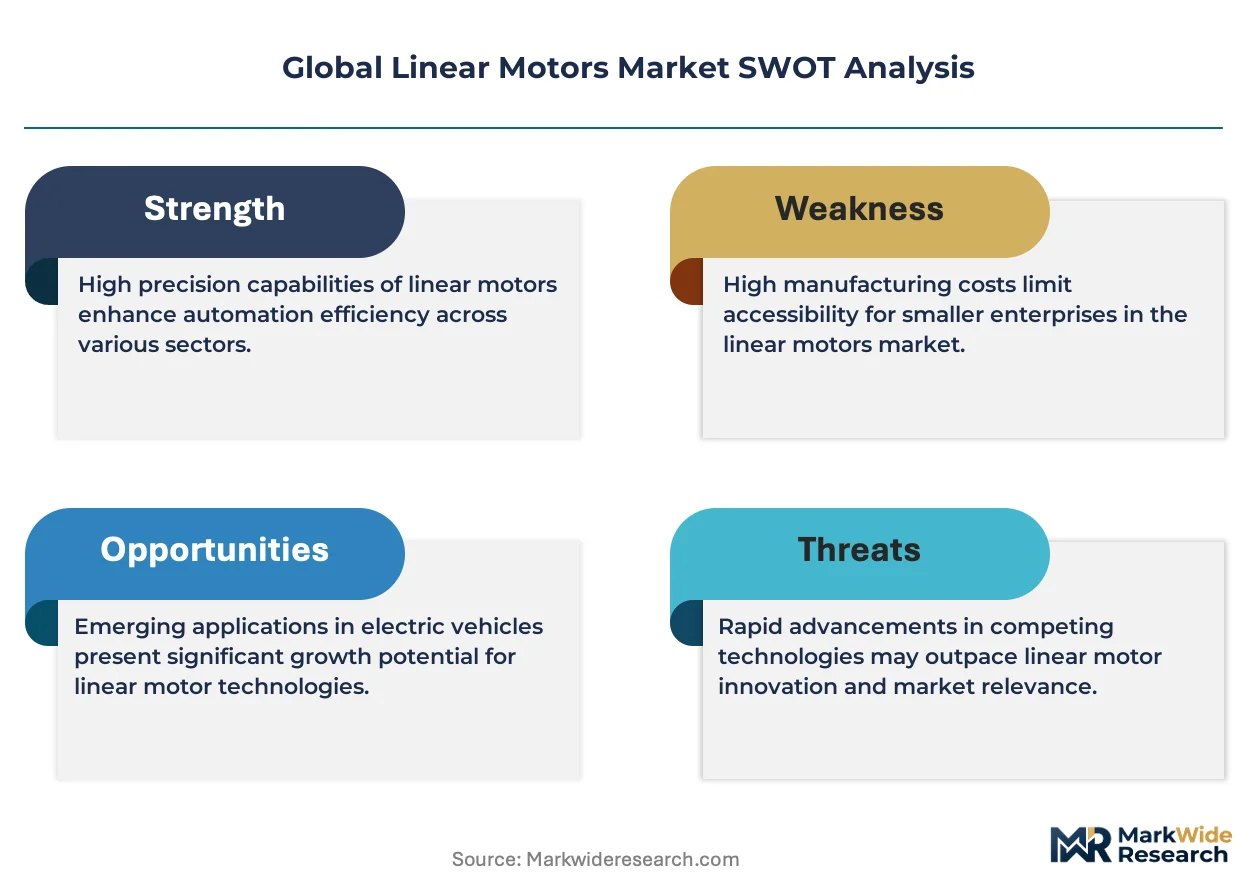
Rare-earth magnet supply concentration and REACH-compliant redesign mandates are forcing manufacturers to reconfigure product architectures around ferrite-enhanced or rare-earth-reduced magnetic circuits.
Growth Catalysts
- Semiconductor capital expenditure:East Asian fabrication facilities in Taiwan, South Korea, and Japan are procuring high-force linear motor stages for EUV lithography and wafer inspection equipment.
- EU F-Gas Regulation:Cooling system redesigns for linear motor thermal management are accelerating adoption of liquid-cooled architectures in precision automation.
- Ironless motor topologies:Elimination of attractive forces between forcer and platen is expanding addressable applications in delicate substrate handling.
Market Restraints
- Neodymium-dysprosium price volatility:Sintered rare-earth magnet costs fluctuate with Chinese export quota policies and Myanmar ore disruptions.
- Encoder supply concentration:Sub-micron resolution optical and magnetic encoders depend on specialized suppliers in Germany and Japan.
- Linear induction motor efficiency ceiling:Fundamental physics limits force-per-ampere ratios to roughly one-third of permanent magnet synchronous alternatives.
Strategic Opportunities
- India precision manufacturing:PLI scheme incentives for electronics and automotive component production are creating first-mover positioning for linear motor system integrators.
- Battery cell stacking:Z-fold and stacking processes for lithium-ion cells require high-acceleration linear actuation with micron-level repeatability.
- Digital twin integration:Real-time servo parameter optimization via cloud-connected drives is enabling predictive maintenance contracts.
Industry Challenges
- Mechatronics engineering scarcity:Cross-disciplinary expertise combining magnetic circuit design, thermal modeling, and servo tuning remains concentrated in Stuttgart, Munich, and Nagoya industrial corridors.
- CE marking functional safety:EU Machinery Directive compliance for STO/SS1 safe torque off integration extends certification timelines by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Linear Motors Market |
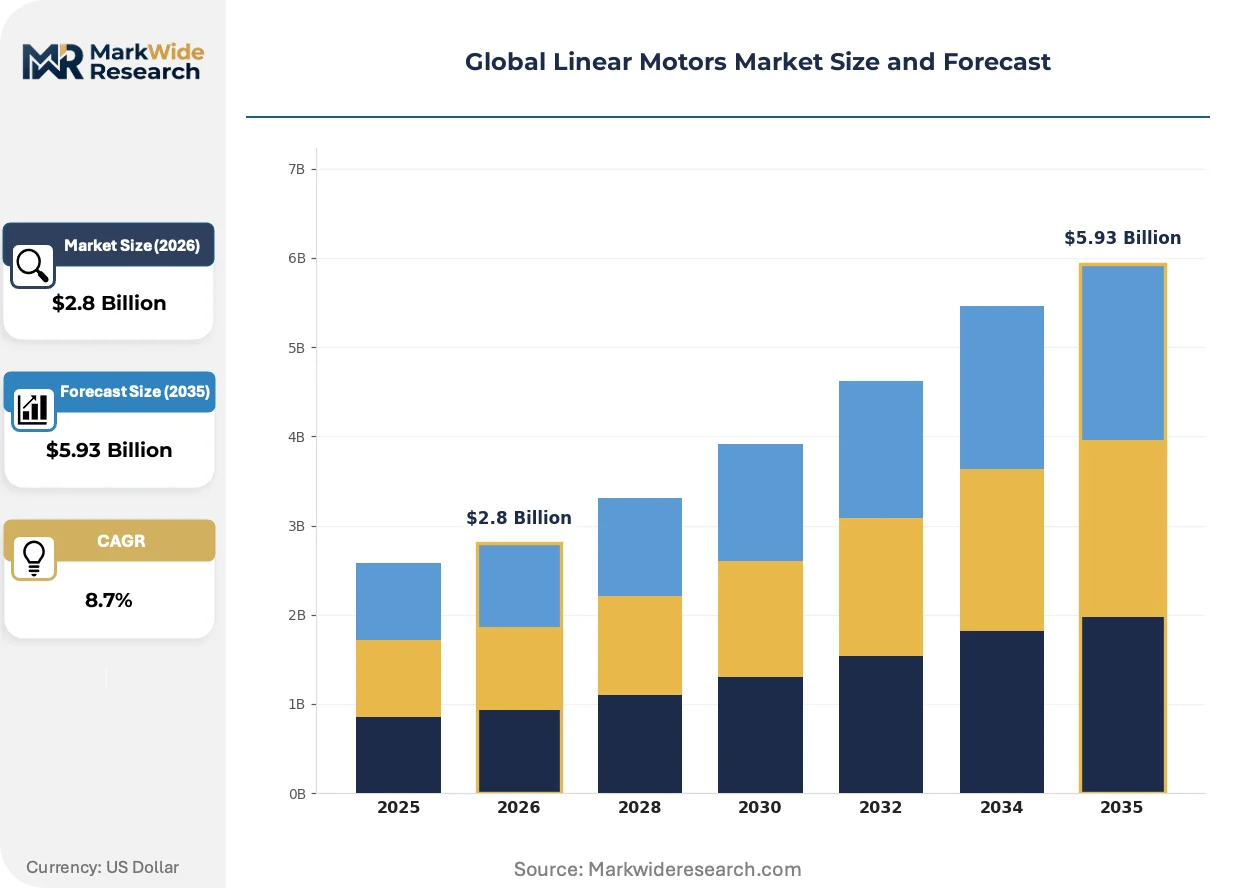
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
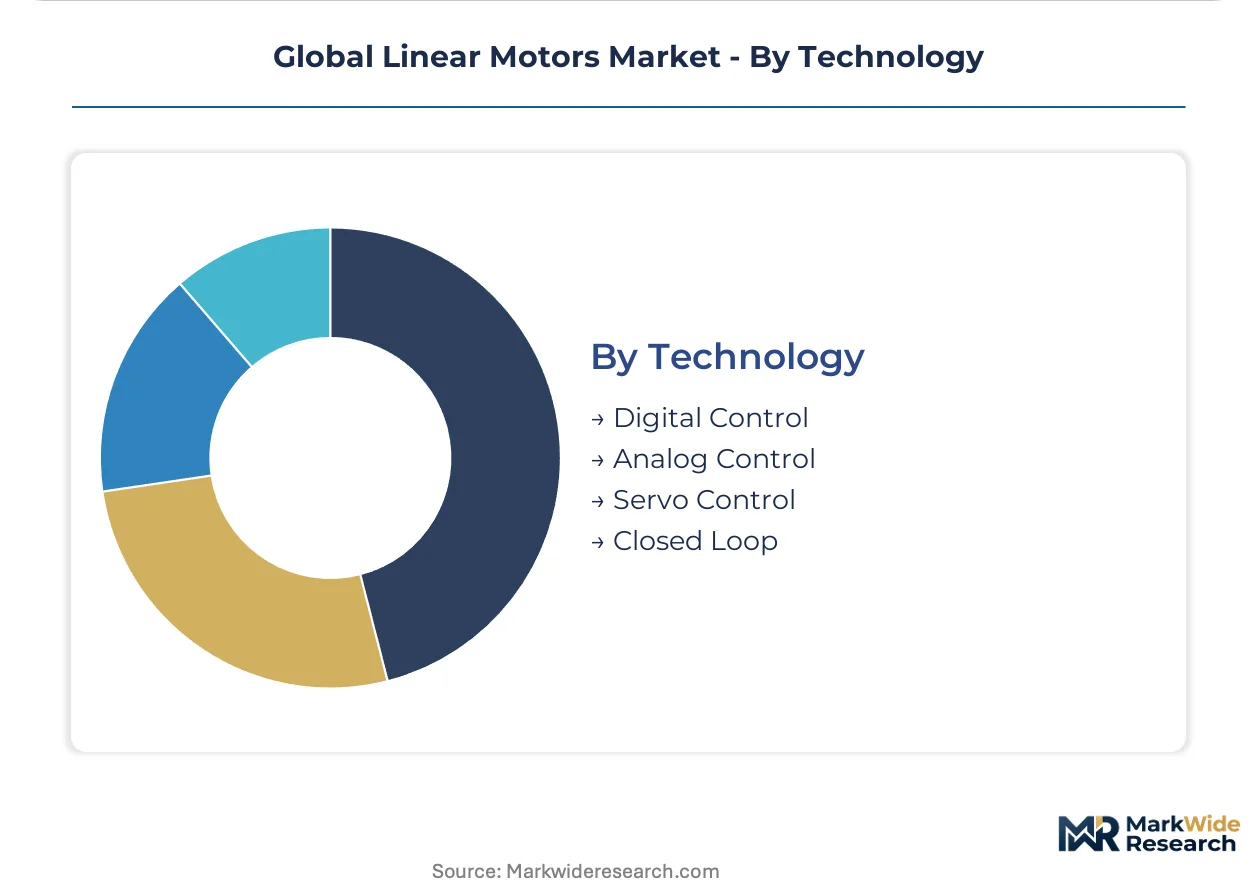
| Segmentation | Product Type: Permanent Magnet, Electromagnetic, Linear Synchronous, Linear Induction End User: Industrial Automation, Semiconductor, Robotics, Automotive Application: Material Handling, Packaging, CNC Machines, Print Production Technology: Digital Control, Analog Control, Servo Control, Closed Loop |
| Companies Covered | YASKAWA Electric Corporation, Mitsubishi Electric Corporation, FANUC Corporation, Bosch Rexroth AG, Rockwell Automation, Aerotech Inc., Hiwin Corporation, ETEL SA, Sumitomo Electric Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Linear Motors Market Strategic Shifts
Magnetic material science advances and digital servo architectures are compressing the performance-cost frontier for direct-drive linear motion systems.
Halbach magnet arrays is integrating permanent magnet configurations that cancel flux on one face while concentrating field on the active airgap surface. Semiconductor equipment OEMs in Japan and Taiwan are specifying Halbach-based ironless motors for wafer stage applications. This topology is integrating force density improvements of fifteen to twenty percent without rare-earth content increases.
REACH substance restrictions are compelling magnet manufacturers to eliminate hexavalent chromium coatings and certain epoxy formulations from lamination stacks. The ECHA authorization list expansion affects corrosion protection processes for linear motor forcers. German and Austrian automation suppliers are accelerating qualification of trivalent chromium and PVD alternatives.
Lifecycle service unbundling is separating hardware procurement from commissioning optimization and predictive maintenance subscriptions. Machine builders in the United States are purchasing linear motor stages while contracting motion tuning and encoder calibration as annual service agreements. This model is most visible in FDA-regulated medical device assembly where validated motion parameters require documented re-certification.
Global Linear Motors Market Segmentation

Linear motor procurement decisions hinge on force density requirements, thermal constraints, and encoder integration complexity. Segment boundaries blur as semiconductor OEMs demand customized ironless architectures and automotive battery lines specify high-duty-cycle synchronous systems.
Product Type:
Force-per-unit-volume and rare-earth magnet exposure dominate buyer evaluation across motor architectures.
- Permanent Magnet:NdFeB magnet arrays deliver peak force density exceeding 10 N/cm² in precision automation. Taiwan and South Korea semiconductor fabs specify Halbach-enhanced configurations for EUV wafer stages, though dysprosium price volatility forces dual-sourcing from Chinese and Vietnamese magnet processors.
- Linear Synchronous:Sinusoidal commutation via digital servo drives achieves sub-micron positioning in Stuttgart-area machine tool retrofits. Ironless variants eliminate cogging for delicate substrate handling in Japanese flat-panel display production.
- Electromagnetic:Copper-wound forcers suit cost-sensitive material handling where continuous duty cycles remain below 60%. German automotive Tier 1s deploy these in battery module assembly for reduced magnet supply risk.
- Linear Induction:Aluminum reaction plates enable maintenance-free operation in dusty packaging environments. Force-per-ampere penalties limit deployment to conveyor systems where precision requirements stay above 50 microns.
Permanent magnet leads on scale; linear synchronous leads on momentum.
End User:
Capital expenditure cycles and regulatory validation requirements fragment demand patterns across industries.
- Semiconductor:EUV lithography stages require 6-axis linear motor arrays with 0.1 nm resolution. Japanese equipment OEMs source integrated servo-linear systems from Nagoya-based motion control specialists.
- Industrial Automation:Stuttgart and Munich precision engineering corridors concentrate packaging and assembly line retrofits. CE marking functional safety mandates extend commissioning timelines for STO-integrated linear axes.
- Robotics:Direct-drive linear joints in delta robots eliminate gearbox backlash for pick-and-place operations exceeding 200 cycles per minute. Battery stacking applications in South Korea drive demand for cleanroom-rated ironless motors.
- Automotive:Z-fold cell stacking and tab welding stations specify liquid-cooled linear actuators with 5 g acceleration capability. Indian PLI scheme incentives are attracting first-mover system integrators to Pune and Chennai manufacturing corridors.
Semiconductor commands premium pricing; automotive is climbing the fastest.
Application:
Throughput specifications and contamination sensitivity determine motor topology selection.
- CNC Machines:Direct-drive linear axes in five-axis machining centers achieve 2 m/s rapids with zero backlash. German machine builders integrate liquid-cooled synchronous motors for continuous heavy milling operations.
- Material Handling:Long-stroke linear motor conveyors in Japanese distribution centers operate maintenance-free for 50,000+ hours. Induction motor economics dominate where positioning tolerance exceeds 100 microns.
- Packaging:Flying cutoff and cartoning machines deploy short-stroke ironless motors for 300+ cycles per minute. FDA-validated medical packaging lines in the United States require documented encoder calibration traceability.
- Print Production:Web tensioning and inkjet carriage positioning demand smooth velocity profiles without cogging. Newspaper press retrofits in India favor electromagnetic alternatives for lower capital outlay.
CNC machines anchor revenue concentration; battery-related material handling is expanding most quickly.
Technology:
Control architecture sophistication separates commodity hardware from value-captured system integration.
- Servo Control:Real-time encoder feedback with 1 MHz loop closure enables adaptive stiffness for varying payloads. Japanese semiconductor equipment specifies Yaskawa MECHATROLINK-III integration for deterministic synchronization.
- Digital Control:FPGA-based commutation supports advanced algorithms including vibration suppression and gain scheduling. German automation suppliers embed predictive maintenance analytics via OPC-UA cloud connectivity.
- Closed Loop:Dual-loop architectures with load-side encoders compensate for mechanical compliance in long-travel stages. Lithography OEMs demand 0.5 nm position stability over 300 mm travel ranges.
- Analog Control:Simplified velocity-mode drives persist in legacy material handling retrofits. Cost advantages erode as digital servo prices compress in high-volume Chinese manufacturing.
Servo control dominates value capture; digital control is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global linear motor procurement through its precision engineering corridor, where Bosch Rexroth AG maintains integrated manufacturing campuses. Taiwan, South Korea, and Japan drive semiconductor equipment demand. Germany, China, and the United States concentrate regulatory-mandated motion control validation.
Germany
Stuttgart and Munich precision engineering corridors concentrate packaging line retrofits and CNC machine tool demand. The EU Machinery Directive and CE marking framework mandate STO/SS1 safe torque off integration, extending certification timelines by four to six months. Baden-Württemberg hosts liquid-cooled synchronous motor production for continuous heavy milling operations.
China
MIIT industrial policy accelerates domestic substitution in precision motion components across Yangtze River Delta fabrication facilities. GB standards enforcement requires documented positioning repeatability in medical device assembly lines. Shenzhen and Shanghai clusters procure high-force linear stages for battery cell stacking and flat-panel display production.
Japan
Nagoya-based motion control specialists supply integrated servo-linear systems to Tokyo and Osaka semiconductor equipment OEMs. METI technology roadmaps prioritize Halbach magnet array qualification for EUV lithography wafer stages. Chubu region maintains mechatronics engineering expertise combining magnetic circuit design with servo tuning.
United States
FDA device manufacturing regulations enforce validated motion control with traceable positioning repeatability in medical product assembly. Greater Boston and Silicon Valley clusters demand micron-level linear actuation for diagnostics equipment manufacturing. EPA and OSHA frameworks govern thermal management system design in precision automation deployments.
South Korea
Busan-Ulsan and Seoul Capital Area battery manufacturers specify cleanroom-rated ironless motors for Z-fold cell stacking processes. MFDS medical device regulations align with FDA validation requirements for exported equipment. Gyeonggi Province concentrates procurement of high-acceleration linear actuators with 5 g capability for tab welding stations.
Global Linear Motors Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers scale liquid-cooled and ironless motor production lines to serve semiconductor and battery manufacturing demand. The vendor base organizes around three strategic tiers: integrated motion control conglomerates with captive servo drive technology, specialized linear stage fabricators focusing on ultra-precision air-bearing systems, and regional component suppliers serving cost-sensitive material handling retrofit markets. M&A activity concentrates on encoder technology and magnetic material processing capabilities, while strategic partnerships between motor manufacturers and cloud connectivity providers accelerate predictive maintenance service unbundling.
Among Japanese integrated motion control conglomerates, YASKAWA Electric Corporation and Mitsubishi Electric Corporation exemplify the servo-architecture-integrated tier, anchoring semiconductor fab equipment supply relationships through deterministic fieldbus integration. Bosch Rexroth AG represents the European precision engineering anchor, with its Stuttgart-based manufacturing campus serving as a reference point for liquid-cooled linear drive qualification under EU regulatory frameworks. Aerotech Inc. occupies the ultra-precision specialist position, with its archetype defining air-bearing linear stage specifications for lithography and metrology end uses where sub-micron positioning stability commands premium procurement economics.
| Leading Market Players |
|---|
| YASKAWA Electric Corporation |
| Mitsubishi Electric Corporation |
| FANUC Corporation |
| Bosch Rexroth AG |
| Rockwell Automation |
| Aerotech Inc. |
| Hiwin Corporation |
| ETEL SA |
| Sumitomo Electric Industries |
| Others |
Value Chain & Pricing Dynamics
Rare-earth magnet feedstock originating from Chinese and Vietnamese processors flows through three distinct pricing strata before reaching semiconductor equipment OEMs in Taiwan and Japan. Dysprosium and neodymium price volatility in upstream concentrate markets compresses margins for mid-tier electromagnetic motor suppliers serving German automotive Tier 1s, while liquid-cooled synchronous architectures command premium positioning through thermal performance guarantees.
Pricing Analysis
Input-cost pass-through from sintered NdFeB magnet processors determines landed pricing for permanent magnet linear motor arrays, with dysprosium content fluctuations transmitting directly to EUV lithography stage procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates Halbach-enhanced ironless motors with sub-nanometer stability from copper-wound electromagnetic alternatives for material handling. Pricing pressure stems from REACH-compliant coating qualification costs for German and Austrian automation suppliers. Semiconductor fabs in East Asia exhibit lowest price sensitivity due to force density requirements, while Indian battery cell manufacturers under PLI scheme incentives prioritize capital efficiency.
Supply Chain Analysis
Mechatronics engineering scarcity in Stuttgart, Munich, and Nagoya industrial corridors constrains production scaling for integrated servo-linear systems. Manufacturing concentrates in Germany, Japan, and China, with Baden-Württemberg hosting liquid-cooled synchronous motor production and Shenzhen clusters serving cost-sensitive electromagnetic variants. Magnet arrays draw from Chinese and Vietnamese rare-earth processors, while sub-micron encoders source from specialized German and Japanese suppliers. Single-source vulnerability in optical encoder technology creates procurement risk for lithography OEMs. Distribution runs through direct OEM relationships for semiconductor equipment and system integrator channels for industrial automation retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in linear motors rests on ferrite-enhanced magnetic circuit adoption reducing rare-earth exposure, alongside premium-tier shift toward predictive maintenance service unbundling in FDA-regulated medical device assembly.
For Market Incumbents: Anticipate REACH substance restriction expansion by accelerating trivalent chromium and PVD coating qualification ahead of ECHA authorization list updates. Consolidate encoder technology capabilities through targeted acquisition to reduce single-source dependency for lithography OEM customers. Prioritize liquid-cooled architecture capacity expansion in Stuttgart-area manufacturing campuses to capture battery cell stacking demand from South Korean and Indian automotive corridors. For New Entrants and Emerging Players: System integrator partnerships in India's Pune and Chennai manufacturing corridors offer lowest competitive density for PLI scheme-driven precision automation demand. Target cleanroom-rated ironless motor supply for Z-fold battery stacking applications where established Japanese vendors face capacity constraints. Pursue cloud-connected servo drive qualification through OPC-UA integration to differentiate on predictive maintenance service bundling. For Investors and Strategic Acquirers: Roll-up economics work for regional linear stage fabricators because mechatronics engineering scarcity concentrates value capture in Stuttgart, Munich, and Nagoya corridors with limited talent replication. Five-to-ten year viability hinges on magnetic material processing capabilities and servo architecture integration depth. Watch for ECHA authorization list expansion triggering coating process redesign costs as inflection indicator for margin compression in European-focused suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Halbach Magnet Array Qualification | Semiconductor equipment OEMs in Japan and Taiwan specify enhanced force density for EUV wafer stages. |
| Liquid-Cooled Architecture Expansion | Battery cell stacking applications in South Korea and India demand 5 g acceleration with thermal stability. |
| Encoder Technology Acquisition | German and Japanese sub-micron resolution suppliers face concentration risk in lithography supply chains. |
| Predictive Maintenance Service Unbundling | FDA-validated medical device assembly lines in the United States require documented re-certification contracts. |
| REACH-Compliant Coating Qualification | ECHA authorization list expansion affects corrosion protection processes for linear motor forcers in Europe. |
Study Parameters
Coverage spans Germany, Japan, China, South Korea, and the United States, with primary inputs from each region combining interviews with motion control engineering directors, semiconductor equipment procurement managers, automotive Tier 1 automation leads, and precision stage system integrators. Secondary validation draws from MIIT industrial policy disclosures, ECHA substance restriction updates, FDA device manufacturing guidance, METI technology roadmaps, and SEC filings from listed automation suppliers. Bottom-up segment sizing triangulates against top-down capital expenditure tracking across semiconductor fabrication and battery manufacturing facilities.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include motor topology, control architecture sophistication, end-use industry capital expenditure cycles, and regional regulatory compliance tiers. CAGRs derive from installed base growth in precision automation equipment coupled with technology substitution rates from rotary-to-linear drive conversions. Industry-specific forecast inputs incorporate EUV lithography stage procurement timelines and PLI scheme incentive disbursement patterns for Indian manufacturing.
Revisions become necessary when rare-earth export quota policies shift, REACH authorization timelines accelerate, or semiconductor capital expenditure cycles deviate from equipment procurement patterns. Forecasts reflect assumptions around magnet supply continuity and encoder technology availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Smart Motors Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Gear Motor Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Spargers Market