
 Europe Electric Vehicle Charging Cable Market | 2026-2036
Europe Electric Vehicle Charging Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Electric Vehicle Charging Cable Market Analytics
Fleet operators is rotating toward high-amperage charging hardware faster than residential buyers, reshaping order specifications across the supply base. HUBER+SUHNER AG leverages its Swiss manufacturing footprint to dominate high-voltage DC cable assemblies for highway corridor deployments. TE Connectivity Ltd. competes through integrated connector-cable systems that reduce installation complexity at public charging hubs. Leoni AG anchors its position with specialized silicone-insulated designs that sustain thermal performance across Nordic temperature extremes.
Europe electric vehicle charging cables are flexible power transmission assemblies, typically comprising multi-strand copper conductors sheathed in thermoplastic polyurethane or silicone rubber, rated for continuous operation between 16A and 500A depending on charging protocol. These assemblies transfer electrical energy from grid-connected infrastructure to onboard vehicle inverters, with conductor cross-sections and insulation thicknesses scaled to voltage class and duty cycle. Type 2 connectors occupy the largest volume share across the region due to EU regulatory harmonization, while Combined Charging System configurations lead growth as automakers consolidate around CCS2 for DC fast charging. Residential charging applications remain the most mature segment with price-sensitive procurement, whereas fleet charging commands premium margins through customized cable management and reinforced strain relief specifications.
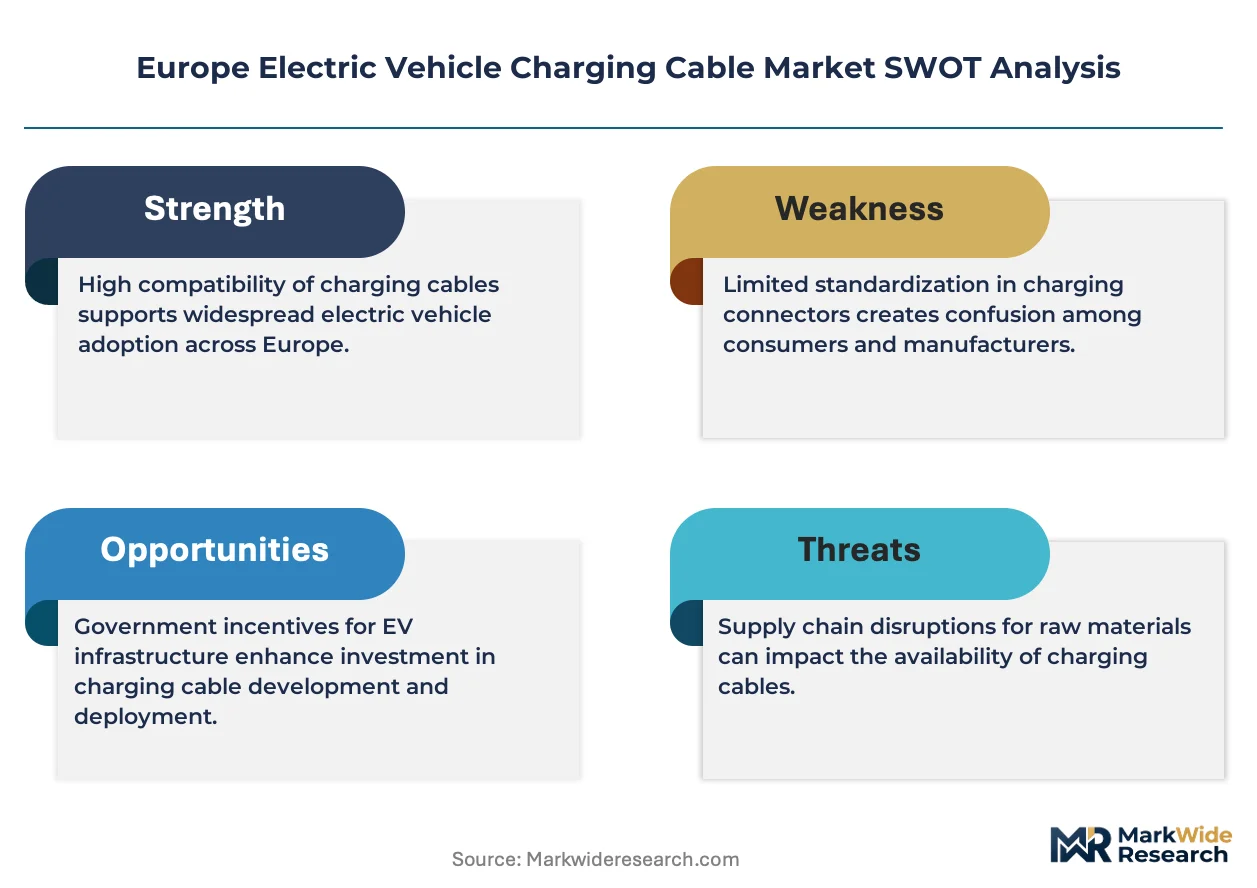
The EU Green Deal and F-Gas Regulation constrain halogenated insulation chemistries, pushing manufacturers toward low-smoke zero-halogen formulations that ECHA evaluates under REACH substance authorization. CE marking requirements under the EU Cable Directive enforce fire performance classifications that vary by installation environment, creating product line complexity for suppliers serving multiple member states. Stakeholders must monitor how the EU AI Act and pending Cyber Resilience Act extend compliance obligations to smart charging cables with embedded communication controllers.
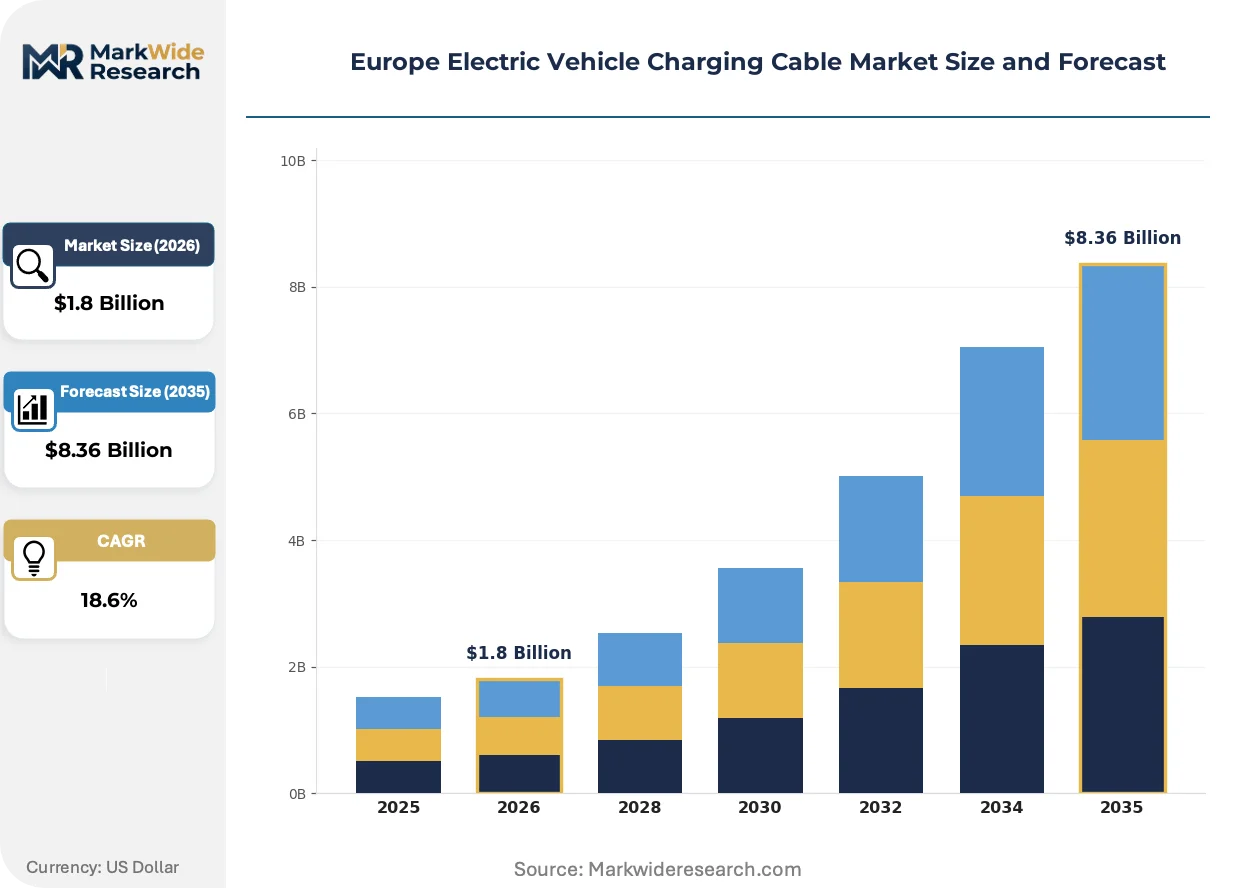
Market Dynamics
Fleet electrification mandates are compressing procurement cycles across European logistics operators, forcing cable suppliers to reconfigure production lines for high-amperage specifications before residential demand matures.
Growth Catalysts
- EU Green Deal implementation:Binding carbon reduction targets for commercial transport fleets are accelerating charging infrastructure deployment across German and Dutch highway corridors.
- Silicone insulation chemistry:Advances in thermally stable elastomer formulations enable continuous 500A operation without the bulk of conventional copper assemblies.
- Nordic temperature extremes:Norway and Finland's Arctic climate requirements are creating premium demand segments for cold-flexible cable designs.
Market Restraints
- Copper price volatility:Conductor material costs constitute 40-60% of finished cable value, exposing margins to London Metal Exchange fluctuations.
- REACH authorization timelines:ECHA's substance evaluation process for halogenated flame retardants extends product recertification cycles by 18-24 months.
- Connector standard fragmentation:Parallel CCS2 and CHAdeMO infrastructure investments split procurement volumes across incompatible hardware formats.
Strategic Opportunities
- Eastern European infrastructure gap:Poland and Romania's nascent highway charging networks offer first-mover positioning before tender competition intensifies.
- Smart cable integration:Embedded powerline communication controllers transform passive assemblies into grid-interactive assets under EU AI Act guidelines.
- Municipal bus electrification:French and Italian urban transit authorities are consolidating depot charging procurement into multi-year framework agreements.
Industry Challenges
- High-voltage safety certification:CE marking under the EU Cable Directive requires fire performance testing across multiple member-state classification schemes.
- Cross-border technician mobility:Installation competency for 1000V DC systems remains concentrated in German and Benelux labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Electric Vehicle Charging Cable Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1, Type 2, Combined Charging System, CHAdeMO, Tesla Connector Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Ultra High Voltage Application: Public Charging Stations, Workplace Charging, Fleet Charging, Residential Charging End User: Passenger Vehicles, Commercial Fleets, Electric Buses, Government Vehicles |
| Companies Covered | HUBER+SUHNER AG, TE Connectivity Ltd., Leoni AG, Aptiv PLC, Nexans S.A., Sumitomo Electric Industries, Ltd., Elkem ASA, Sinbon Electronics Co., Ltd., Coroplast Fritz Müller GmbH & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Electric Vehicle Charging Cable Market Evolving Landscape
Material science breakthroughs and regulatory chemistry bans are converging to remake European cable specifications, while fleet procurement centralization is compressing supplier qualification timelines.
High-flexibility thermoplastic polyurethane sheathing is fragmenting market share previously held by silicone rubber in moderate-climate applications. French and Italian fleet operators are specifying TPU for depot charging where ambient temperatures rarely drop below -10°C. This substitution is fragmenting supplier portfolios into climate-segmented product lines rather than universal designs.
REACH substance restrictions on halogenated compounds are mandating low-smoke zero-halogen insulation across all public installation environments. ECHA's authorization process favors phosphorus-nitrogen intumescent systems over traditional brominated alternatives. Cable manufacturers serving German rail and tunnel infrastructure are reformulating entire product families to maintain CE marking compliance.
Centralized procurement by multinational logistics operators is displacing fragmented distributor relationships across the supply base. Deutsche Post DHL and similar fleet aggregators are negotiating direct supply agreements with cable assemblers for standardized depot configurations. This consolidation is most visible in the Netherlands, where Rotterdam-Eindhoven corridor charging hubs are being specified under single-source frameworks.
Europe Electric Vehicle Charging Cable Market Segmentation
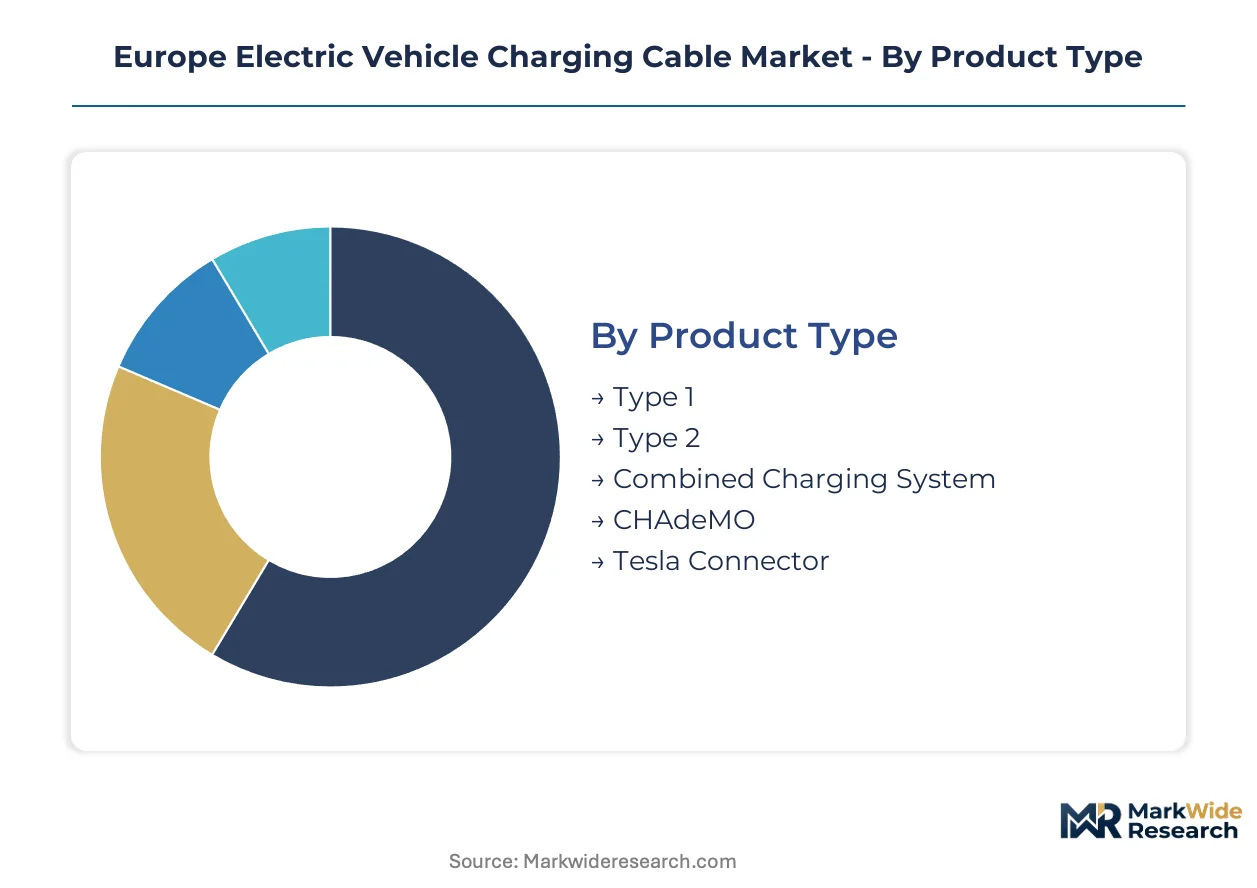
Charging cable specifications diverge sharply across European installation environments, with CE marking under the EU Cable Directive mandating distinct fire performance classifications for public versus residential deployments. Fleet procurement centralization and Nordic climate requirements further fragment product portfolios beyond connector geometry alone.
Product Type:
ECHA REACH substance restrictions and F-Gas Regulation chemistry bans are forcing reformulation of insulation systems across all connector formats, with CE marking compliance varying by halogen content and smoke density ratings.
- Type 2:This Mennekes-designed connector dominates European AC charging with its seven-pin configuration supporting single-phase and three-phase power delivery. German and Dutch highway corridor deployments concentrate the highest volumes, though CCS2 migration is compressing pure Type 2 growth in DC-capable installations.
- Combined Charging System:CCS2 integrates the Type 2 AC interface with two additional DC power pins beneath, enabling unified hardware for alternating and direct current charging. French and Italian fleet operators are consolidating procurement around this format as automakers standardize onboard inverters, with the connector climbing the fastest adoption trajectory across European public charging tenders.
- Type 1:This single-phase J1772-derived connector persists in legacy vehicle populations and import conversions, primarily serving older Japanese and American EV models in European circulation.
- CHAdeMO:The Japanese-developed DC fast charging standard retains installed base presence across early Nissan and Mitsubishi fleets, though new European infrastructure investment has shifted decisively toward CCS2.
- Tesla Connector:Tesla's proprietary North American design sees limited European deployment outside Supercharger networks, with the company actively transitioning European sites to CCS2 compatibility.
Established volume favors Type 2; emerging adoption favors Combined Charging System.
Voltage Rating:
Cost tier differentiation separates commodity residential hardware from premium fleet and highway corridor specifications, with conductor cross-section and insulation thickness scaling non-linearly with voltage class.
- Low Voltage:Rated up to 60V DC or 50V AC, these cables serve auxiliary and signaling functions within charging assemblies rather than primary power transfer. Workplace charging installations in France and Italy specify these for control pilot and proximity detection circuits.
- Medium Voltage:Spanning 60V to 1500V DC, this class captures the bulk of European AC charging and emerging DC fast charging below 350kW. German depot charging networks for municipal bus fleets are standardizing on 1000V DC medium voltage assemblies with silicone insulation.
- High Voltage:Covering 1500V to 35kV, these specialized assemblies appear in grid-connection infrastructure and distribution feeder applications rather than vehicle-tethered cables. Polish and Romanian highway corridor tenders are specifying high voltage-rated components for transformer-to-charger links.
- Ultra High Voltage:Exceeding 35kV, this category addresses transmission-level infrastructure and substation interconnections outside the vehicle charging interface itself.
Medium voltage commands the widest application footprint; high voltage is gaining share fastest in emerging European highway networks.
Application:
Customer type concentration—individual homeowners versus centralized fleet operators—determines procurement channel structure and margin architecture across the supply base.
- Residential Charging:Single-phase 16A to 32A cables with basic strain relief dominate this price-sensitive segment, typically sold through electrical distributors and automotive retail. Dutch and Belgian home installation subsidies are sustaining volumes despite slower hardware refresh cycles.
- Fleet Charging:High-amperage three-phase and DC-capable assemblies with reinforced cable management and customized length specifications command premium positioning. Deutsche Post DHL and similar logistics aggregators are negotiating direct supply agreements for standardized depot configurations across German and Benelux operations.
- Public Charging Stations:Retractable cable systems with active cooling and high-cycle durability ratings serve highway corridor and urban fast charging hubs. Norwegian and Finnish Arctic climate requirements are creating premium demand for cold-flexible designs in this channel.
- Workplace Charging:Mid-tier AC charging infrastructure serving employee parking and commercial property installations, with procurement typically managed through facility management contracts rather than automotive channels.
Fleet charging exhibits the steepest expansion trajectory; residential charging anchors absolute volume.
End User:
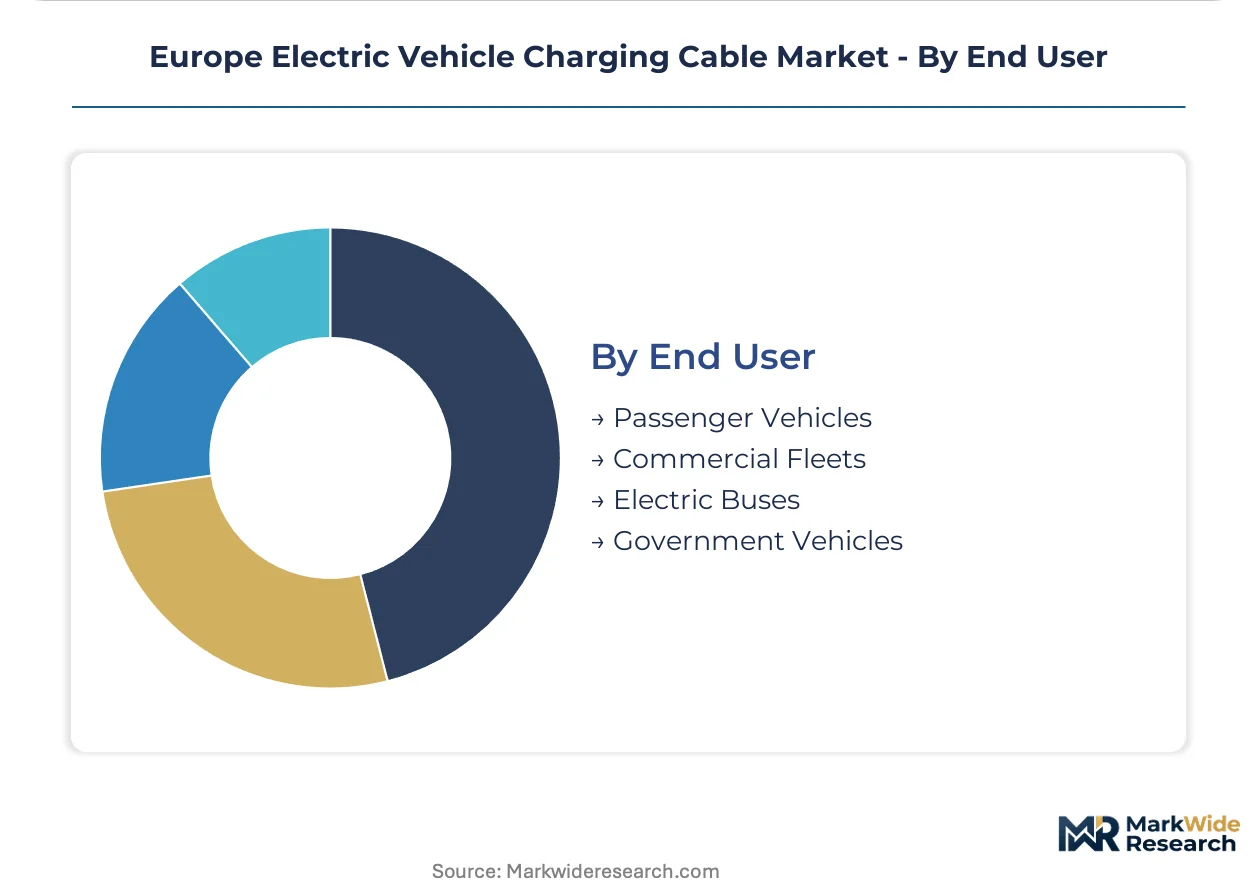
Application maturity separates early-adopter passenger vehicle segments from electrification mandates now reshaping commercial and government procurement.
- Passenger Vehicles:Private EV owners drive replacement and upgrade demand for home charging cables, with Type 2 and CCS2 formats dominating. French and Italian consumer markets show particular concentration of CCS2-equipped vehicle sales.
- Commercial Fleets:Logistics operators and delivery services are compressing procurement cycles for high-amperage depot charging hardware ahead of residential demand maturation. Rotterdam-Eindhoven corridor charging hubs exemplify the centralized framework agreements displacing fragmented distributor relationships.
- Electric Buses:Municipal transit authorities in France and Italy are consolidating depot charging procurement into multi-year framework agreements with specialized cable management requirements for high-utilization environments.
- Government Vehicles:Public sector electrification targets across German federal and state fleets are generating tender volumes with stringent domestic content and certification requirements.
Passenger vehicles maintain installed base dominance; commercial fleets are expanding most quickly under binding carbon reduction mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cable assembly capacity clusters in German-speaking industrial zones, with Swiss and Austrian manufacturing footprints extending into adjacent EU markets. Benelux logistics corridors and Nordic electrification programs are redrawing demand geography faster than production relocation.
Germany
Federal fleet electrification mandates and autobahn corridor charging tenders are compressing procurement timelines for high-amperage DC assemblies. KBA vehicle-type approval requirements enforce connector standardization that favors CCS2 consolidation. The Stuttgart-Munich industrial belt hosts specialized silicone cable production for Arctic-grade specifications.
Netherlands
Rotterdam port electrification and Eindhoven-Tilburg logistics clustering are generating framework agreements for depot charging hardware. National subsidies for workplace charging infrastructure exceed residential incentives by a factor of three. The Randstad urban agglomeration concentrates Europe's densest public charging network deployment.
France
Municipal bus fleet tenders in Paris, Lyon, and Marseille are consolidating multi-year procurement into standardized cable management specifications. ANSM safety evaluations for high-voltage assemblies add certification layers beyond baseline CE marking. The Auvergne-Rhône-Alpes region anchors silicone elastomer compounding for cold-flexible designs.
Norway
Arctic climate requirements for continuous operation below -30°C are creating premium demand segments for thermally stable insulation systems. Statens vegvesen highway authority tenders specify cold-bend testing protocols that exceed EU Cable Directive minima. Tromsø and Bodø corridor installations validate cable performance across temperature extremes.
Poland
Nascent highway charging infrastructure along the A2 and A4 corridors offers first-mover positioning before tender competition intensifies. National Recovery and Resilience Facility allocations prioritize cross-border freight electrification routes. The Silesian industrial region is emerging as an assembly location for medium-voltage distribution cables serving charger-to-grid links.
Europe Electric Vehicle Charging Cable Market Competitive Landscape
Concentration sits with diversified cable manufacturers possessing in-house silicone compounding and connector integration capabilities. The vendor base separates into three tiers: integrated industrial conglomerates with automotive heritage, specialized electrotechnical cable houses, and regional assembly operations serving distributor channels. Strategic moves center on backward integration into copper conductor drawing and forward integration into smart cable controllers.
Among Swiss and German industrial conglomerates, HUBER+SUHNER AG and Leoni AG exemplify the integrated archetype with captive silicone formulation expertise. TE Connectivity Ltd. occupies a position bridging connector technology and cable assembly integration. These three entities anchor the premium tier where fleet procurement centralization is concentrating qualification timelines.
| Leading Market Players |
|---|
| HUBER+SUHNER AG |
| TE Connectivity Ltd. |
| Leoni AG |
| Aptiv PLC |
| Nexans S.A. |
| Sumitomo Electric Industries, Ltd. |
| Elkem ASA |
| Sinbon Electronics Co., Ltd. |
| Coroplast Fritz Müller GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German fleet operators and Swiss cable assemblers lock in copper conductor access while capping price volatility exposure across the procurement cycle. These contractual structures concentrate purchasing power among logistics aggregators and fragment margin capture across smaller distributor channels.
Pricing Analysis
Volume-discount tiering structures separate multinational fleet frameworks from residential retail transactions, with Deutsche Post DHL-scale procurement commanding 15-25% unit cost advantages over distributor-sourced equivalents. Price differentiation hinges on CE marking certification grade and silicone insulation formulation purity, with Arctic-grade specifications carrying substantial premia over moderate-climate TPU alternatives. Cost compression in residential-tier cables is intensifying because Dutch and Belgian subsidy programs attract price-competitive Asian assembly imports. Fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership framing, whereas homeowner segments prioritize upfront hardware expenditure minimization.
Supply Chain Analysis
Inventory cycles extending 12-18 weeks for custom silicone formulations constrain just-in-time responsiveness across European cable assemblers. Manufacturing gravity centers on Germany, Switzerland, and Austria, with conductor drawing and elastomer compounding often captive within integrated industrial conglomerates. Raw material dependencies rest on Chilean copper cathode, German silicone monomer, and Chinese thermoplastic polyurethane granulate. Single-source vulnerability concentrates in high-purity silicone elastomer supply, where two Swiss-German compounders dominate qualification-dependent fleet procurement. Distribution runs through direct OEM supply agreements for fleet volumes and electrical wholesaler networks for residential endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized silicone compounding expertise and high-voltage DC certification capabilities constitute the critical scarcity assets differentiating viable competitors from commodity assemblers in this market.
For Market Incumbents: Compound defensive positioning through backward integration into copper conductor drawing and captive silicone formulation capacity, neutralizing margin pressure from London Metal Exchange volatility. Prioritize CE marking fire performance certification investment ahead of ECHA REACH authorization timelines for halogenated flame retardants, as regulatory compliance acceleration threatens product line obsolescence. For New Entrants and Emerging Players: Anchor in Poland and Romania's nascent highway corridor charging infrastructure, where tender competition remains sparse and first-mover qualification advantages persist. Target municipal bus electrification frameworks in France and Italy through depot charging specialization, leveraging standardized cable management specifications that favor focused technical competence over broad product portfolios. For Investors and Strategic Acquirers: Mid-cap cable assemblers with validated Arctic-grade silicone designs and active fleet procurement relationships represent the highest-probability acquisition archetype for capability consolidation. Monitor ECHA substance authorization announcements as the critical inflection signal, as REACH-driven reformulation cycles will separate qualified incumbents from recertification-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Conductor Drawing | Captive supply of the 40-60% cost-dominant input neutralizes LME price volatility exposure. |
| Silicone Elastomer Compounding Capacity Expansion | In-house formulation control accelerates REACH-compliant product development ahead of regulatory deadlines. |
| Smart Cable Controller Development | Embedded powerline communication transforms passive assemblies into grid-interactive assets under EU AI Act. |
| Arctic-Grade Certification Investment | Norwegian Statens vegvesen tender specifications reward cold-flexible designs with premium positioning. |
| Fleet Framework Agreement Consolidation | Direct supply relationships with Deutsche Post DHL-scale operators displace fragmented distributor economics. |
Research Methodology
Operator-level perspectives from fleet procurement directors, cable assembler plant managers, ECHA regulatory affairs specialists, and electrical distributor category buyers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Cable Directive implementation guidance, ECHA REACH substance evaluation databases, and KBA vehicle-type approval records. Bottom-up demand modeling from charging infrastructure deployment pipelines triangulated against top-down market sizing from customs trade flows and industrial production indices.
Sensitivity analysis across copper price scenarios, fleet electrification mandate acceleration cases, and silicone elastomer supply disruption events stress-tested projection robustness over the analysis window. Segmentation modeling captured product type, voltage rating, application, and end user dimensions, with connector format migration trajectories and climate-zone installation requirements as industry-specific forecast inputs. CAGRs derived from logistic curve penetration modeling applied to vehicle fleet electrification timelines and infrastructure deployment commitments.
Material uncertainties — copper commodity volatility, ECHA authorization timeline delays, and CCS2-CHAdeMO standard resolution — sit outside the modeled envelope and could materially revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicle Charging
Global EV Charger Market
Electric Vehicle Charging
Electric Vehicle Coin Charging Station Market
Electric Vehicle Charging
Global EV Charging Adapter Market
Electric Vehicle Charging
Copper in Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Infrastructure Market
Electric Vehicle Charging
Electric Vehicle Charger and Charging Station Market
Electric Vehicle Charging
Italy Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
EV Charging Station Market
Electric Vehicle Charging
South America Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Australia Electric Vehicle Charging Equipment Market
Electric Vehicle Charging
Electric Vehicle Grid Integration Solutions Market
Electric Vehicle Charging
Electric Vehicle (EV) Public Charging Station Market
Electric Vehicle Charging
Electric Vehicle (EV) Charging Station Operation Market
Electric Vehicle Charging
Electric Vehicle Rapid Charger Market
Electric Vehicle Charging
China Electric Vehicle Charging Infrastructure Market
Electric Vehicle Charging
Solar Charge Controller Market