
 Permanent Magnet Synchronous Motors Market | 2026-2036
Permanent Magnet Synchronous Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Permanent Magnet Synchronous Motors Market Outlook
Direct procurement channels between magnet suppliers and motor assemblers is tilting toward long-term offtake agreements. ABB leverages captive rare-earth sourcing partnerships to stabilize feedstock costs. Siemens AG anchors European industrial automation demand through localized stator winding facilities. Nidec Corporation dominates compact high-RPM designs for precision robotics.
Permanent magnet synchronous motors employ rotor-mounted rare-earth or ferrite magnets synchronized with stator winding frequency, achieving synchronous speeds without slip losses while delivering power densities exceeding induction alternatives. The motor's primary commercial purpose centers on variable-speed, high-efficiency torque delivery across electric traction and precision positioning systems. Low voltage configurations occupy the highest unit volume tier, though medium voltage architectures capture disproportionate margin pools in heavy industrial settings. Brushless DC technology leads across consumer-facing applications, while direct drive systems expand fastest in wind turbine generators where gearbox elimination cuts maintenance cycles.
FCC efficiency benchmarks and EPA industrial emissions guidelines tighten motor performance thresholds in North American installations, while EU Ecodesign regulations and REACH substance restrictions reshape magnet composition and recycling obligations. China's GB motor efficiency standards and MIIT rare-earth export licensing further constrain supply elasticity. Stakeholders must monitor magnet substitution R&D and regional compliance divergence to calibrate manufacturing footprints and qualification timelines.
Market Dynamics
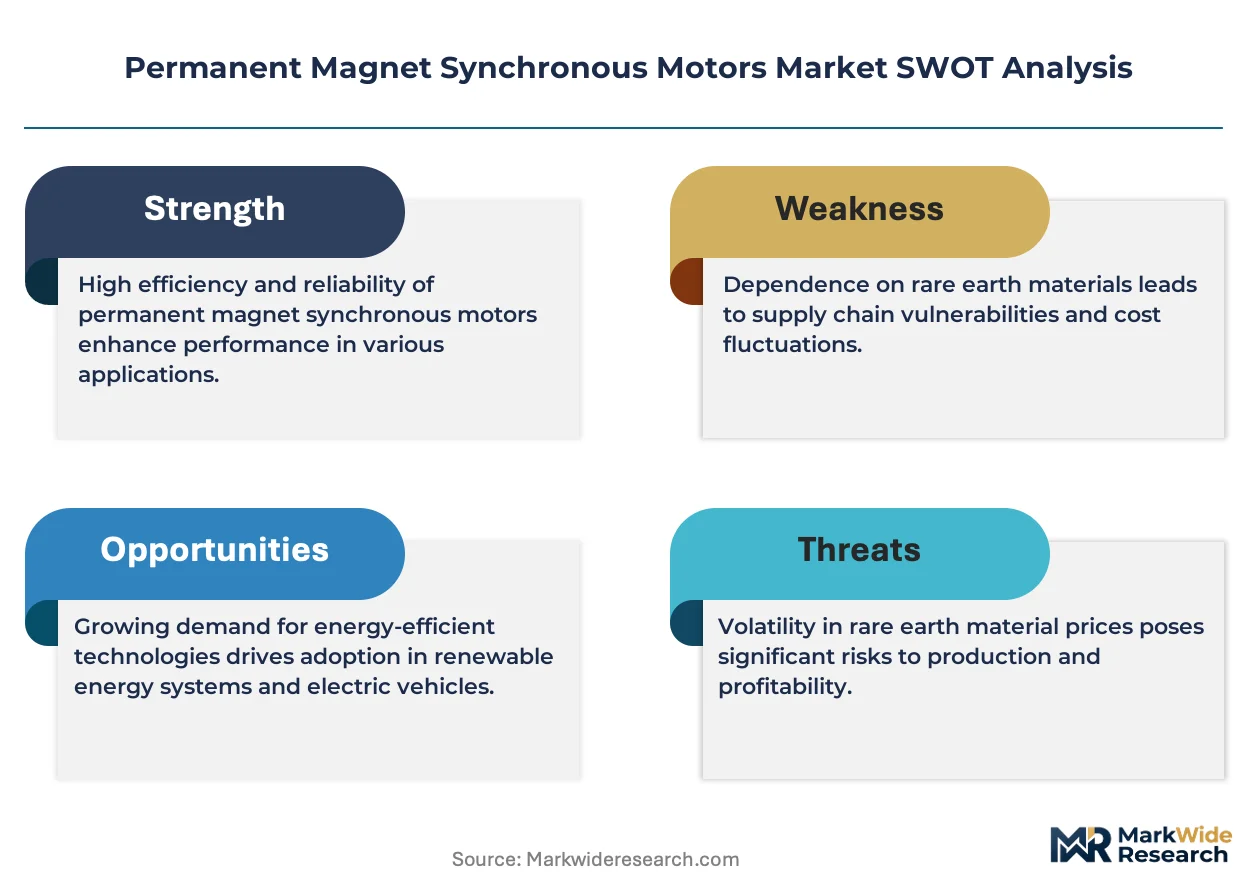
Rare-earth magnet supply concentration in China and the country's NMPA efficiency mandates are compressing motor procurement timelines while forcing OEMs to secure captive magnet offtake agreements.
Growth Catalysts
- China's GB motor efficiency standards:Tier-1 efficiency mandates under MIIT directives are accelerating factory retrofits and replacement cycles across industrial automation.
- Electric traction systems:Automotive OEM procurement volumes for EV powertrains are amplifying high-RPM compact motor demand with synchronous speed requirements.
- Wind turbine direct-drive architectures:Gearbox elimination in multi-MW generators is expanding permanent magnet rotor adoption for offshore installations.
Market Restraints
- Neodymium-dysprosium price volatility:Rare-earth oxide feedstock swings are destabilizing magnet cost structures and motor BOM forecasting.
- China MIIT export licensing:Centralized rare-earth magnet supply is creating single-point vulnerability for non-Chinese motor assemblers.
- Ferrite magnet performance ceiling:Lower remanence and coercivity in non-rare-earth alternatives limits power density in traction-grade applications.
Strategic Opportunities
- India PLI scheme for automotive:Domestic motor manufacturing incentives are opening greenfield capacity for suppliers targeting ASEAN export markets.
- Magnet-to-motor recycling闭环:Hydrometallurgical rare-earth recovery from end-of-life motors is creating circular feedstock streams independent of mining.
- Precision robotics integration:Collaborative robot joint actuators are demanding compact high-torque synchronous designs with absolute encoder compatibility.
Industry Challenges
- Stator winding automation talent:Shortage of technicians skilled in hairpin winding and automated insertion equipment is constraining high-volume output scaling.
- Multi-certification timelines:Simultaneous UL, CE, and CCC qualification cycles for industrial motors are extending product launch windows by 8-14 months.
- Legacy VFD compatibility:Retrofitting synchronous motors into existing induction-motor drive infrastructures requires parameter remapping and thermal derating analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Permanent Magnet Synchronous Motors Market |
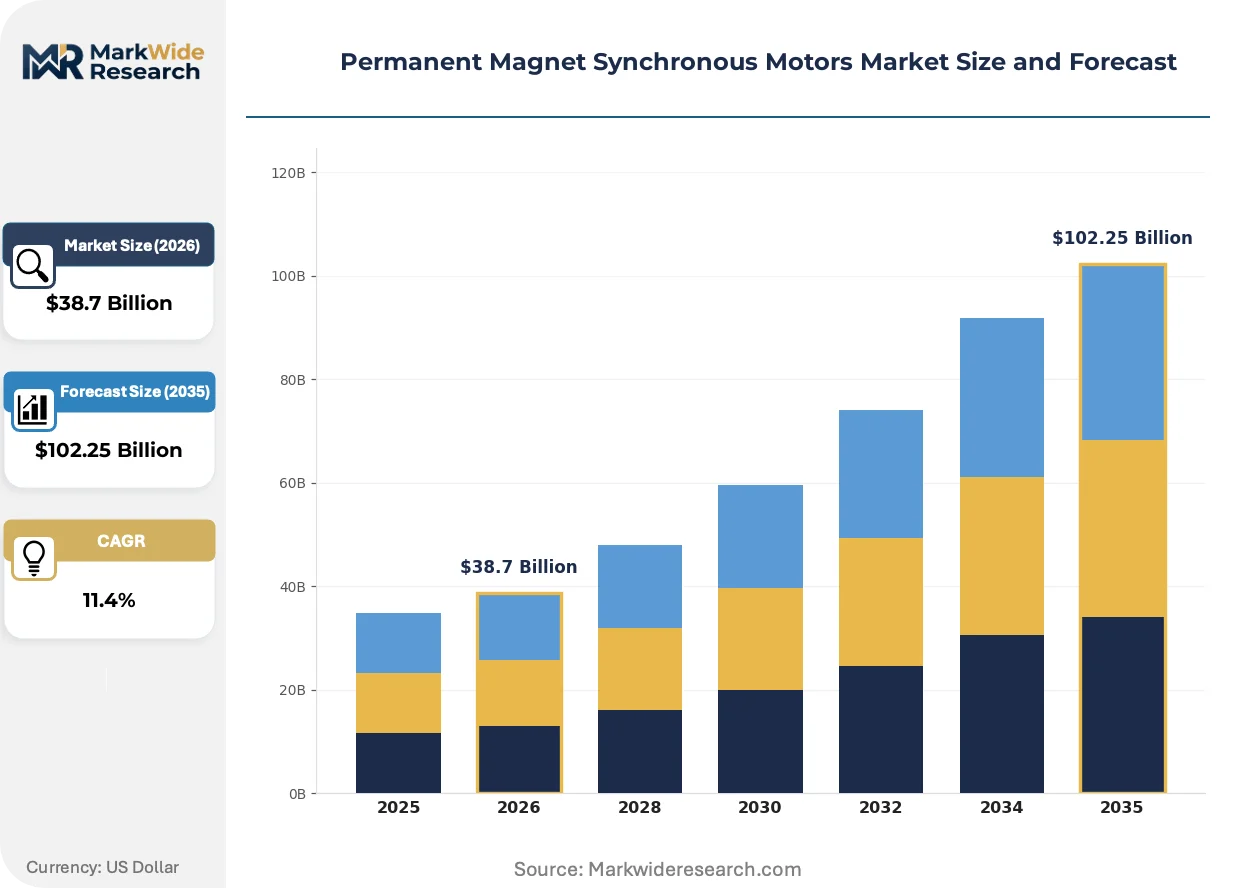
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Customized Solutions End User: Automotive OEMs, Industrial Automation, Renewable Energy, HVAC Technology: Brushless DC, Flux Switching, Direct Drive, Servo Motor Technology Application: Motor Drives, Robotics, Electric Vehicles, Home Appliances |
| Companies Covered | ABB, Hitachi Ltd., Siemens AG, Yaskawa Electric Corporation, Toshiba Corp., Mitsubishi Electric Corporation, WEG S.A., Wolong Electric, Nidec Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Permanent Magnet Synchronous Motors Market Strategic Shifts
Active magnet substitution R&D and digital-twin-based motor design are compressing development cycles while fragmenting competitive positioning around material efficiency.
Hairpin stator winding technology replaces traditional round-wire random windings with rectangular conductor pre-forming and laser welding. Tier-1 automotive suppliers are adopting this for 800V EV platforms at volume scale. The architecture is rendering obsolete hand-wound stator production for traction motors above 150kW.
EU Ecodesign regulations and REACH substance restrictions are tightening magnet composition disclosure and end-of-life recycling obligations. Motor assemblers must now document rare-earth provenance and establish take-back programs. Heavy industrial medium-voltage installations face the steepest compliance cost escalation.
Long-term magnet offtake agreements are displacing spot-market procurement for tier-1 motor manufacturers. Tier-2 and specialty motor houses are responding through consortium purchasing pools and shared warehousing in Shanghai and Seoul. This concentration is most visible in East Asian manufacturing clusters serving robotics and semiconductor equipment OEMs.
Permanent Magnet Synchronous Motors Market Segmentation
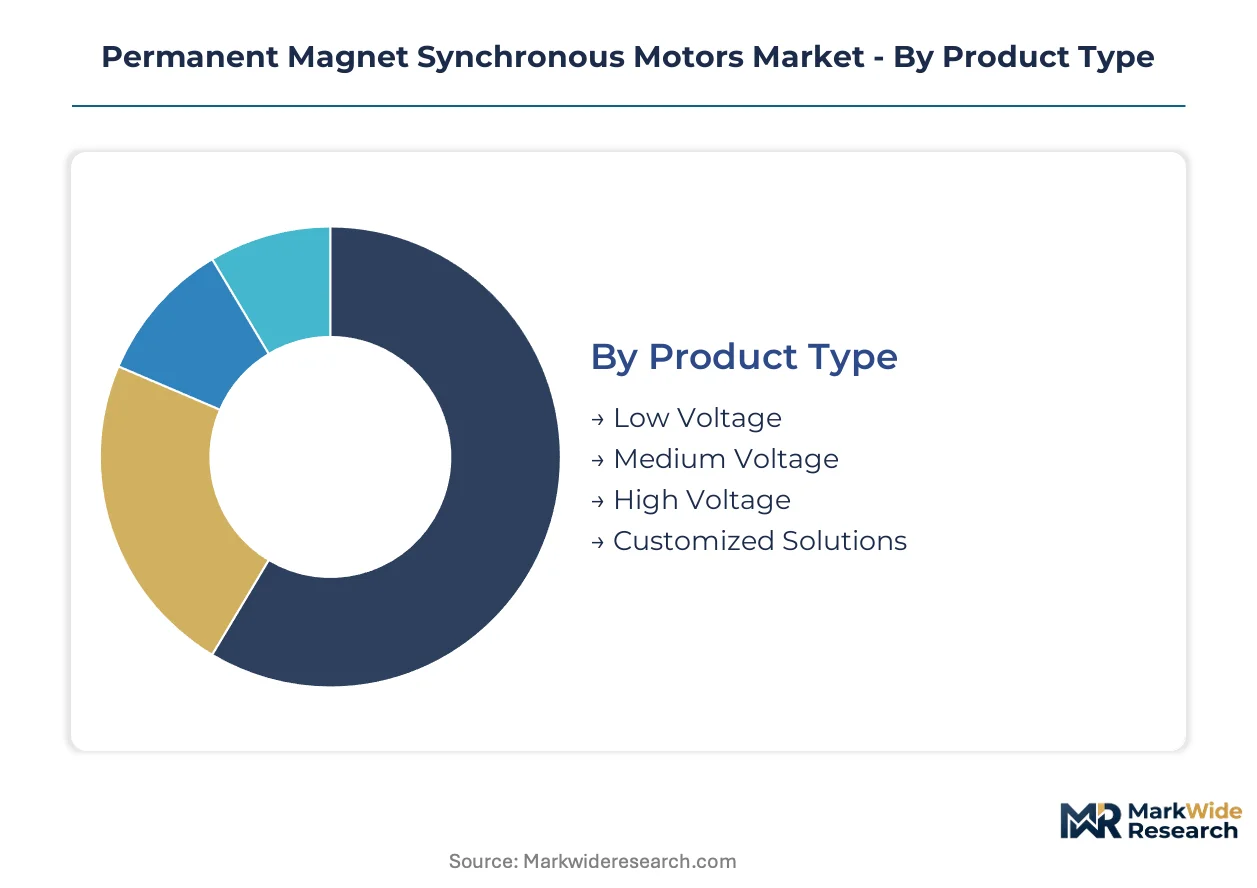
Permanent magnet synchronous motors fragment across voltage tiers, end-use applications, and technology architectures that determine magnet composition, winding complexity, and thermal management requirements. Procurement patterns diverge sharply between high-volume automotive traction and precision industrial positioning systems.
Product Type:
Voltage classification separates mass-market traction applications from heavy industrial power conversion systems with distinct insulation and cooling architectures.
- Low Voltage:These motors operate below 1kV with concentrated windings and surface-mounted rare-earth rotors. Automotive OEMs in Germany and Japan dominate procurement for 400V and 800V EV platforms where compact packaging and high RPM density are paramount.
- Medium Voltage:Operating between 1kV and 6.5kV, these designs employ form-wound stators and segmented magnet arrays for mining conveyors and steel mill drives. China's MIIT efficiency mandates are accelerating replacement cycles in heavy industrial clusters around Tangshan and Wuhan.
- High Voltage:Above 6.5kV class with vacuum pressure impregnated insulation systems for compressors and pumps in oil and gas extraction.
- Customized Solutions:Application-specific designs with non-standard shaft configurations, encoder integrations, or explosion-proof housings for semiconductor cleanrooms and chemical processing.
Low voltage commands the established base. The steepest expansion runs through medium voltage industrial retrofits.
End User:
Customer type determines torque precision requirements, certification burdens, and aftermarket service intensity across the value chain.
- Automotive OEMs:Tier-1 suppliers integrate hairpin-wound stators with oil-cooled rotors for 150kW+ traction motors. South Korea's Hyundai Motor Group and Germany's Volkswagen Group are consolidating magnet offtake agreements to secure neodymium-dysprosium supply.
- Industrial Automation:Servo-grade synchronous motors with absolute encoder feedback power CNC machine tools and packaging lines. Japan's FANUC and Germany's Siemens AG anchor demand through localized stator winding facilities.
- Renewable Energy:Direct-drive generators for offshore wind turbines eliminate gearbox maintenance through large-diameter permanent magnet rotors.
- HVAC:Variable-speed compressor motors with ferrite magnet rotors for residential heat pumps and commercial chillers.
Industrial automation commands the established base. The steepest expansion runs through automotive OEM electrification programs.
Technology:
Magnet arrangement and control methodology define power density, efficiency maps, and drive electronics compatibility.
- Brushless DC:Trapezoidal back-EMF designs with Hall sensor commutation for cost-sensitive consumer applications. China's Midea and Haier deploy these in washing machines and air conditioners where six-step control suffices.
- Direct Drive:Elimination of mechanical transmission through high-torque low-speed motor architectures. Vestas and Siemens Gamesa specify these for offshore wind turbines above 5MW where gearbox failure rates become prohibitive.
- Flux Switching:Concentrated windings with salient rotors reduce rare-earth content through flux modulation topologies.
- Servo Motor Technology:Sinusoidal drives with resolver or optical encoder feedback for multi-axis robotics.
Brushless DC commands the established base. The steepest expansion runs through direct drive renewable installations.
Application:
Functional deployment determines thermal cycling severity, duty cycle profiles, and electromagnetic compatibility requirements.
- Electric Vehicles:Traction motors with peak-to-continuous power ratios exceeding 3:1 and 15,000+ RPM maximum speeds. Tesla's Shanghai Gigafactory and BYD's Shenzhen plants are scaling integrated motor-inverter-axle assemblies.
- Robotics:Hollow-shaft frameless motors with low cogging torque for collaborative robot joints. Japan's Yaskawa Electric and Harmonic Drive Systems supply harmonic gear-integrated actuators.
- Motor Drives:General-purpose industrial pumps, fans, and compressors with VFD-matched voltage and frequency characteristics.
- Home Appliances:Single-phase inverter-fed motors for refrigerator compressors and vacuum cleaners.
Motor drives command the established base. The steepest expansion runs through electric vehicle powertrain integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port underwrites China's dominance in magnet-to-motor logistics, processing rare-earth concentrate shipments that feed stator winding facilities across the Yangtze River Delta. This maritime infrastructure locks in procurement velocity for automotive and industrial automation supply chains.
China
MIIT's GB motor efficiency mandates are forcing factory retrofits across Tangshan steel clusters and Wuhan industrial zones. NMPA certification timelines compress procurement cycles for medium-voltage drives. Shanghai and Shenzhen manufacturing nodes concentrate hairpin winding capacity for 800V EV platforms serving BYD and Tesla Gigafactory exports.
Germany
Volkswagen Group and BMW electrification programs anchor high-RPM compact motor demand for 400V and 800V traction systems. EU Ecodesign regulations and REACH substance restrictions tighten magnet composition disclosure for industrial servo motors. Bavaria's Munich-Stuttgart corridor hosts localized stator winding facilities supplying Siemens AG automation divisions.
United States
EPA industrial emissions guidelines and FCC efficiency benchmarks tighten performance thresholds for mining conveyors and steel mill drives. The Port of Long Beach handles neodymium-dysprosium concentrate imports feeding Michigan and Ohio automotive supplier parks. Tesla's Austin Gigafactory scales integrated motor-inverter-axle assemblies for North American EV deployment.
South Korea
Hyundai Motor Group's consolidated magnet offtake agreements secure rare-earth supply for 150kW+ traction motors. MFDS efficiency labeling extends to industrial equipment, accelerating replacement cycles in Busan-Ulsan manufacturing clusters. Seoul Capital Area facilities specialize in compact high-RPM designs for precision robotics and semiconductor equipment OEMs.
Japan
METI's JIS efficiency standards and carbon neutrality roadmaps reshape magnet sourcing for FANUC servo systems and Yaskawa Electric automation equipment. Kansai's Osaka-Kyoto industrial belt maintains hollow-shaft frameless motor production for collaborative robot joint actuators. Nagoya's Chubu region anchors stator winding automation talent pools for hairpin conductor pre-forming.
Permanent Magnet Synchronous Motors Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers: integrated conglomerates with captive magnet sourcing, specialized motor houses with winding automation expertise, and regional fabricators serving price-sensitive industrial replacement markets. Strategic archetypes include rare-earth supply chain integrators, hairpin winding technology specialists, and precision servo positioning providers. Dominant competitive moves involve long-term magnet offtake agreements displacing spot procurement and consortium purchasing pools consolidating warehousing in East Asian logistics nodes.
Among diversified industrial conglomerates, ABB and Siemens AG occupy positions exemplifying integrated supply chain control, while Nidec Corporation represents the compact high-RPM design archetype for precision robotics applications. These three anchors illustrate how geographic proximity to magnet processing infrastructure and stator winding automation capability determine competitive positioning across automotive traction and industrial automation segments.
| Leading Market Players |
|---|
| ABB |
| Hitachi Ltd. |
| Siemens AG |
| Yaskawa Electric Corporation |
| Toshiba Corp. |
| Mitsubishi Electric Corporation |
| WEG S.A. |
| Wolong Electric |
| Nidec Corporation |
| Others |
Value Chain & Pricing Dynamics
China's NMPA rare-earth export licensing regime concentrates magnet feedstock pricing power in the Yangtze River Delta, compressing margin pools for non-Chinese motor assemblers while amplifying returns for integrated suppliers with captive sourcing. Long-term offtake agreements now displace spot procurement across tier-1 automotive and industrial automation procurement desks.
Pricing Analysis
Volume-discount tiering structures separate premium hairpin-wound traction motors from standard random-wound industrial designs and economy-grade ferrite-magnet alternatives. Price differentiation centers on neodymium-dysprosium content grade and UL/CE/IEC certification tier, with automotive OEMs absorbing premium positioning for 800V platforms. Cost compression in medium-voltage industrial retrofits is intensifying because China's MIIT efficiency mandates are accelerating replacement cycles. Tier-2 motor houses exhibit highest price sensitivity, while integrated conglomerates with captive magnet sourcing maintain pricing resilience.
Supply Chain Analysis
Export-control regimes under China's MIIT and SAMR frameworks constrain rare-earth magnet flows to non-domestic motor assemblers, creating licensing bottlenecks. Geographic supply concentration centers on China for neodymium-dysprosium processing, Japan for advanced magnet alloying, and Germany for precision stator winding automation. Raw material dependencies span rare-earth oxides, electrical steel laminations, and high-temperature insulation systems. Single-source vulnerability in Chinese magnet refining creates structural risk. Distribution runs through Shanghai and Seoul logistics nodes serving East Asian manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet synchronous motors represent a high-growth disruption anchored by 800V EV platform proliferation and China's GB motor efficiency mandates forcing industrial retrofit cycles. Technological inflection in hairpin winding automation and magnet recycling hydrometallurgy is fragmenting incumbent positioning.
For Market Incumbents: Pre-empt ferrite-substitute R&D displacement by securing dysprosium-terbium offtake agreements with Chinese magnet processors. Accelerate hairpin winding capacity in Bavaria and Nagoya to defend against Korean automation specialists. Vertical integration into rare-earth recovery from end-of-life motors provides feedstock hedge against MIIT export restrictions. For New Entrants and Emerging Players: Build out precision servo motor capabilities for collaborative robotics in Busan-Ulsan clusters where FANUC and Yaskawa Electric anchor demand. Target India's PLI-automotive incentives for greenfield traction motor capacity serving ASEAN export markets. Go-to-market through consortium purchasing pools in Shanghai logistics nodes reduces working capital barriers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hairpin winding automation specialists in Japan's Chubu region and Germany's Munich-Stuttgart corridor. Five-to-ten year viability hinges on magnet recycling technology maturation and regional regulatory divergence on rare-earth provenance disclosure. Watch for MIIT export license volume triggers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Magnet Offtake Agreement | Captive neodymium-dysprosium supply secures BOM stability for ABB and Siemens AG against spot volatility. |
| Hairpin Winding Automation Scale-Up | Pre-formed rectangular conductor laser welding eliminates hand-wound production for 150kW+ EV traction motors. |
| Hydrometallurgical Recycling Buildout | Rare-earth recovery from end-of-life motors creates circular feedstock streams independent of Chinese mining. |
| Regional Stator Winding Localization | Bavaria and Nagoya facilities anchor Siemens AG and Nidec Corporation proximity to automotive OEM electrification programs. |
| Consortium Purchasing Pool Formation | Shared warehousing in Shanghai and Seoul reduces working capital for tier-2 motor houses against integrated conglomerates. |
Study Parameters
Operator-level perspectives from motor procurement directors at automotive OEMs, stator winding automation engineers, rare-earth magnet traders, and industrial maintenance managers anchored the qualitative base. Primary interviews triangulated with secondary validation from MIIT GB standard filings, EU Ecodesign directive documentation, SEC 10-K disclosures from listed motor manufacturers, and customs trade data on neodymium-dysprosium concentrate flows. Bottom-up unit economics across voltage tiers and top-down macroeconomic drivers were reconciled through iterative calibration.
Scenario-bracketing framed demand projections across the analysis window, modeling baseline, accelerated electrification, and magnet supply disruption cases. Segmentation dimensions included voltage classification, end-use application, magnet composition technology, and regional regulatory cluster. CAGRs derived from installed base turnover rates, EV platform rollout schedules, and industrial efficiency mandate compliance timelines. Industry-specific inputs encompassed hairpin winding equipment deployment curves and rare-earth oxide price elasticity assumptions.
Stress conditions across neodymium-dysprosium price volatility, MIIT export license restriction severity, and EU REACH substance ban scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on automotive electrification penetration and industrial automation replacement cycles. Material shifts in China's dual carbon policy stringency or breakthrough ferrite-magnet performance thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
China AC Motor Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market