
 Food Grade Hydraulic Oil Market | 2026-2036
Food Grade Hydraulic Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Hydraulic Oil Market Foresight
Multi-source procurement for base stocks is decoupling from traditional single-refiner relationships as compounders seek supply resilience. Fuchs Petrolub SE leverages its European additive blending network to serve bakery and dairy OEMs. TotalEnergies SE anchors its position through backward integration into Group III base oil production. Shell plc competes on global reach, extending food-grade certifications across its marine and industrial distribution arms.
Food grade hydraulic oil denotes lubricant formulations meeting NSF H1 or ISO 21469 standards for incidental food contact, typically incorporating polyalphaolefin or vegetable oil base stocks with ashless additive packages to prevent contamination of processed goods. These fluids maintain thermal stability between 120°C and 150°C while resisting oxidation in high-moisture environments common to food processing equipment. Vegetable oil based formulations lead volume in Europe due to biodegradability mandates, while polyalphaolefin dominates North American pharmaceutical equipment applications where oxidative stability extends drain intervals. Mineral oil based products retain share in cost-sensitive beverage bottling lines, though margin pools concentrate in synthetic grades serving clean-label manufacturing protocols.
NSF International governs H1 registration in the United States, while EFSA and REACH shape contaminant thresholds across European formulations. FDA compliance for incidental food contact under 21 CFR 178.3570 remains mandatory for U.S. food manufacturers, pushing reformulation away from certain sulfur-phosphorus extreme pressure additives. Stakeholders must monitor evolving PFAS restrictions under EU chemicals strategy, as these compounds appear in some fluorinated grease thickeners used alongside hydraulic systems in pharmaceutical cleanrooms.
Market Dynamics
NSF H1 compliance thresholds are tightening faster than reformulation cycles can absorb, forcing compounders to accelerate additive package redesigns while maintaining thermal stability above 120°C in high-moisture food processing environments.
Growth Catalysts
- REACH contaminant thresholds:ECHA is lowering acceptable limits for sulfur-phosphorus extreme pressure additives in European formulations, compelling manufacturers to source ashless alternatives and expand certified lubricant portfolios.
- Bakery equipment OEM specifications:Major equipment builders in Germany and Italy now mandate ISO 21469-certified hydraulic fluids for new bread and pastry processing lines, locking in synthetic base stock demand.
- Polyalphaolefin thermal stability:Pharmaceutical cleanroom equipment operators in North America are specifying PAO-based formulations to extend drain intervals beyond 8,000 operating hours in temperature-controlled environments.
Market Restraints
- Group III base oil supply concentration:European compounders depend on a limited number of refiners for high-purity Group III stocks, creating vulnerability when capacity tightens during seasonal turnaround periods.
- Vegetable oil oxidation limits:Biodegradable formulations using rapeseed or sunflower base stocks degrade faster above 130°C, restricting their deployment in high-temperature meat rendering applications.
- PFAS restriction uncertainty:EFSA is evaluating fluorinated compound risks in grease thickeners used adjacent to hydraulic systems, creating formulation hesitation before definitive rulings emerge.
Strategic Opportunities
- India food processing expansion:FSSAI is developing H1-equivalent certification frameworks as domestic dairy and edible oil processing capacity scales, creating first-mover positioning for NSF-registered suppliers.
- Digital fluid monitoring convergence:IoT sensors paired with predictive analytics are enabling condition-based hydraulic oil replacement in beverage bottling lines, opening subscription service models for lubricant vendors.
- Clean-label manufacturing protocols:Premium food brands are specifying synthetic food-grade fluids for all incidental contact points, expanding addressable market beyond regulatory minimums into brand-protection territory.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise combining food safety compliance with extreme pressure performance resides with a narrow cohort of specialists approaching retirement in European blending facilities.
- NSF registration timeline compression:H1 certification reviews now extend 14-18 months due to backlog, delaying product launches and freezing R&D roadmaps for compounders with pipeline dependencies.
- Legacy equipment compatibility:Older hydraulic systems in cost-sensitive beverage bottling plants use elastomer seals incompatible with synthetic base stocks, forcing dual inventory maintenance or costly retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Hydraulic Oil Market |
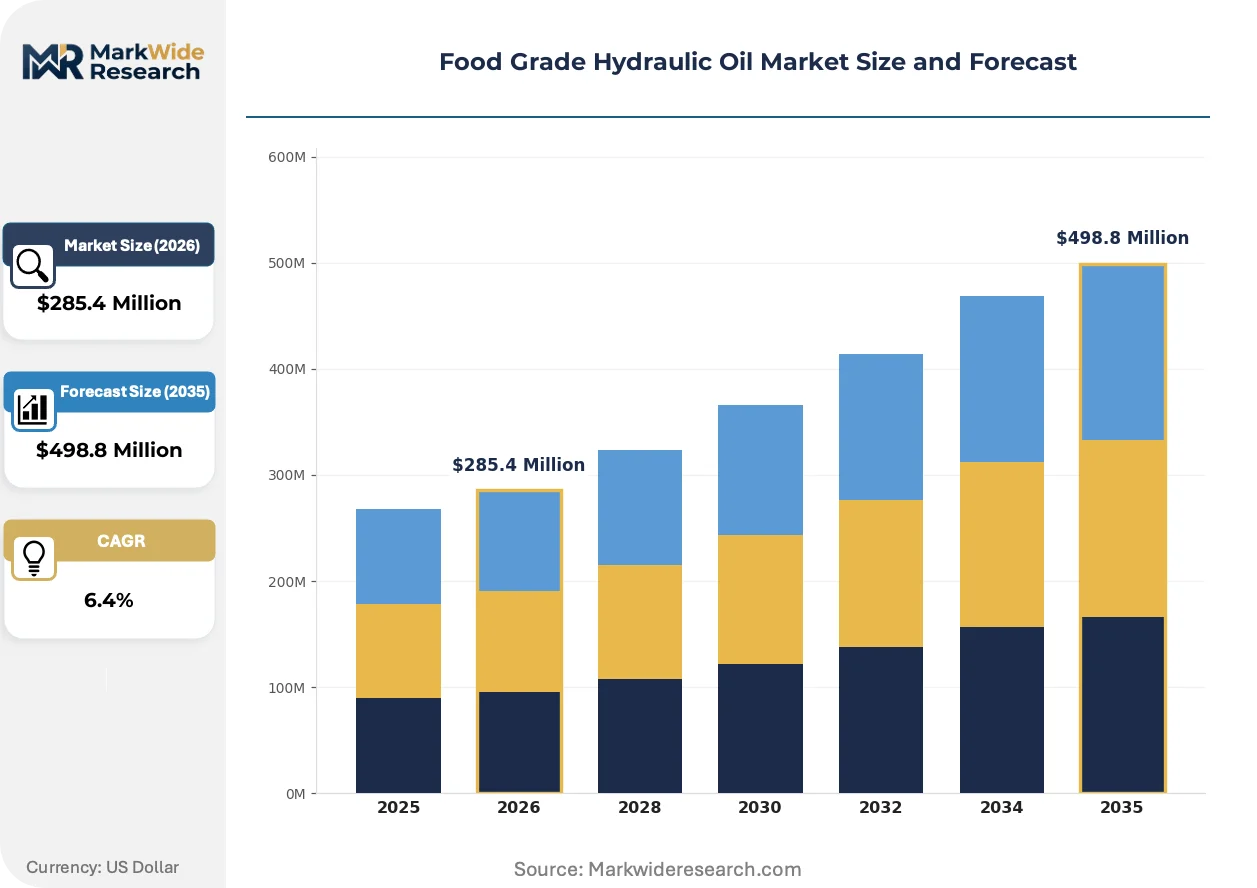
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $498.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phosphate Ester, Polyalphaolefin, Vegetable Oil Based, Mineral Oil Based Application: Food Processing Equipment, Packaging Machinery, Pharmaceutical Equipment, Bakery Machines End User: Food Manufacturers, Pharmaceutical Producers, Cosmetic Manufacturers, Beverage Developers Packaging Type: Drums, Totes, Cartridges, Bulk Tankers |
| Companies Covered | Fuchs Petrolub SE, TotalEnergies SE, Chevron Corporation, Exxon Mobil Corporation, Shell plc, BP p.l.c., Petro-Canada Lubricants Inc., AB SKF, Castrol Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Hydraulic Oil Market Shifts & Advancements
Biodegradable base stocks and predictive maintenance technologies are converging to redefine equipment lubrication strategies, while regulatory fragmentation between NSF H1 and emerging national standards forces parallel certification investments.
Synthetic ester formulations are integrating antioxidant packages derived from phenolic and aminic chemistry to achieve thermal stability above 150°C in continuous fryer hydraulic systems. Meat processors in Germany and the Netherlands are adopting these fluids to eliminate oxidative varnish deposits that contaminate product contact surfaces. This integration is compressing replacement intervals for mineral oil alternatives while raising performance benchmarks for incumbent synthetic grades.
EU chemicals strategy PFAS restrictions are forcing reformulation of fluorinated grease thickeners used in pharmaceutical cleanroom hydraulic adjacent equipment. ECHA's proposed limits on per- and polyfluoroalkyl substances will remove certain PTFE-thickened products from approved substance lists by 2027. Pharmaceutical equipment OEMs in Switzerland and Germany are accelerating qualification of calcium sulfonate and polyurea alternatives to maintain ISO 21469 compliance.
Direct procurement from compounders is displacing distributor intermediaries in large dairy cooperative accounts. Danish and Dutch dairy processors with centralized technical departments now negotiate volume contracts specifying base stock origin and additive package composition. This disintermediation concentrates purchasing power with buyers possessing in-house lubrication engineering capabilities while margin pressure transfers to regional distributors serving fragmented meat processing plants.
Food Grade Hydraulic Oil Market Segmentation
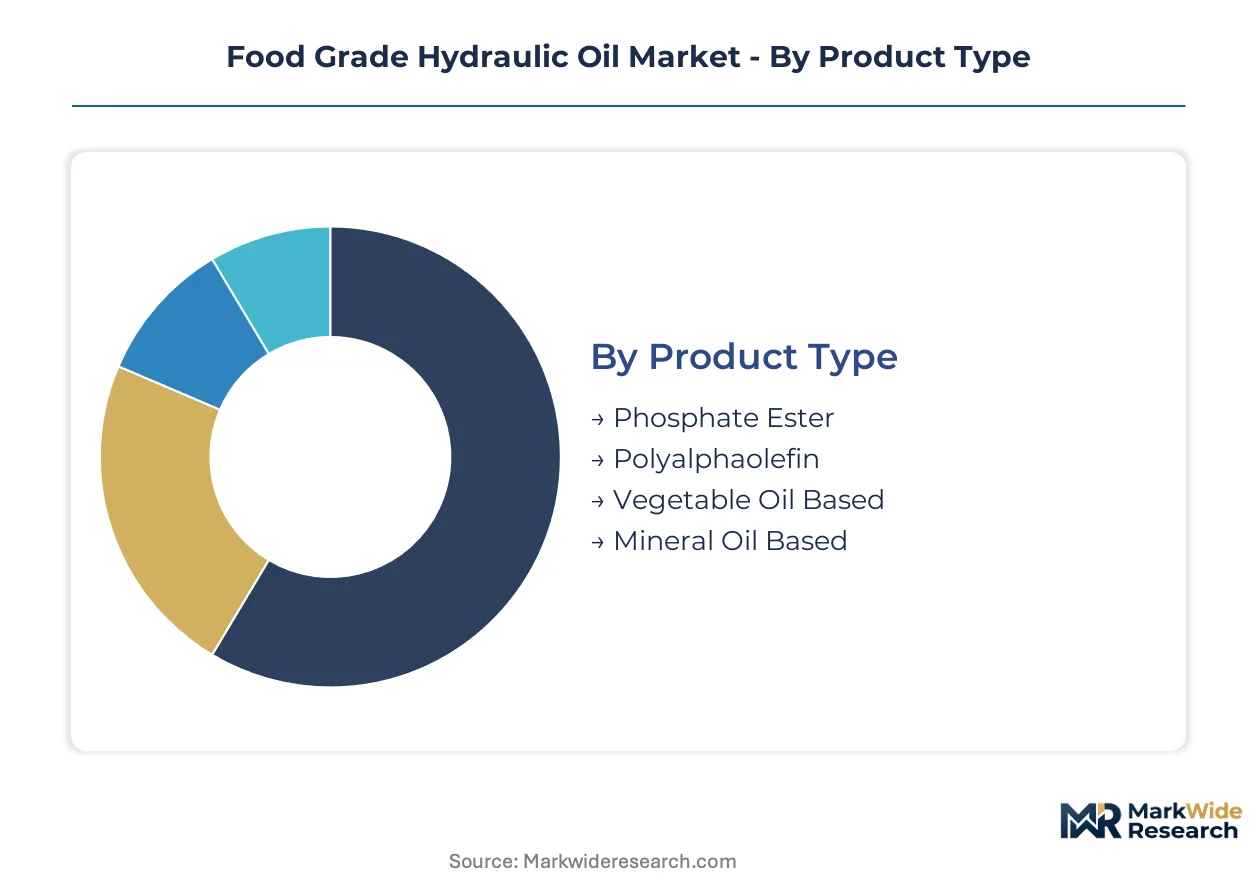
Food grade hydraulic oil buyers select formulations based on thermal load profiles, contamination risk tolerance, and drain interval economics. Segmentation reveals how synthetic base stocks command premium positioning in high-temperature applications while mineral alternatives retain footholds in cost-constrained bottling operations.
Product Type:
Cost tier differentiation separates buyers pursuing extended drain intervals from those prioritizing upfront fluid expenditure.
- Polyalphaolefin:Synthetic hydrocarbon base stocks deliver oxidative stability above 150°C with drain intervals exceeding 8,000 hours. Pharmaceutical cleanroom operators in temperature-controlled environments specify PAO formulations to minimize maintenance shutdowns and contamination risks.
- Vegetable Oil Based:Rapeseed and sunflower-derived formulations meet EU biodegradability mandates for environmental discharge scenarios. Meat processors in Germany and the Netherlands deploy these fluids in low-temperature hydraulic systems where oxidative degradation above 130°C is not a limiting factor.
- Phosphate Ester:Fire-resistant synthetic esters serve fryer adjacent hydraulic systems requiring thermal stability and ignition risk mitigation.
- Mineral Oil Based:Refined paraffinic stocks retain position in beverage bottling lines where equipment age and seal compatibility constrain synthetic adoption.
Volume sits with Mineral Oil Based formulations in legacy installed base; growth tilts toward Polyalphaolefin in pharmaceutical and clean-label manufacturing expansions.
Application:
Application segmentation tracks equipment thermal intensity and product contact proximity as determinants of formulation specification.
- Food Processing Equipment:Continuous fryer hydraulics and meat rendering systems impose the most severe thermal loads, driving specification of synthetic ester formulations with phenolic antioxidant packages. German meat processors are eliminating mineral oil alternatives to prevent varnish contamination of product contact surfaces.
- Pharmaceutical Equipment:Cleanroom hydraulic adjacent systems require ISO 21469 certification with stringent particulate and bioburden controls. Swiss and German pharmaceutical OEMs are accelerating qualification of calcium sulfonate grease alternatives ahead of EU PFAS restrictions.
- Packaging Machinery:Cartoning and capping equipment operates at moderate temperatures with intermittent duty cycles, accommodating broader formulation latitude.
- Bakery Machines:Bread and pastry processing lines in Italy and Germany now mandate ISO 21469-certified fluids as standard OEM specification for new equipment purchases.
Revenue concentrates in Food Processing Equipment; expansion rates are steepest in Pharmaceutical Equipment driven by cleanroom certification requirements.
End User:
End user categories reflect divergent procurement sophistication and in-house lubrication engineering capabilities.
- Food Manufacturers:Dairy cooperatives in Denmark and the Netherlands exercise direct procurement from compounders, negotiating volume contracts with specified base stock origins. Centralized technical departments displace distributor intermediaries in accounts exceeding 500,000 liter annual consumption.
- Pharmaceutical Producers:Multi-site operators harmonize formulations across manufacturing networks to simplify compliance documentation and reduce qualification burden for new suppliers.
- Beverage Developers:Bottling plant operators balance synthetic fluid performance against legacy equipment seal compatibility constraints, often maintaining dual inventory.
- Cosmetic Manufacturers:Personal care product facilities apply food-grade specifications to hydraulic systems adjacent to mixing and filling operations.
Procurement sophistication peaks with Food Manufacturers; compliance complexity drives fastest specification evolution among Pharmaceutical Producers.
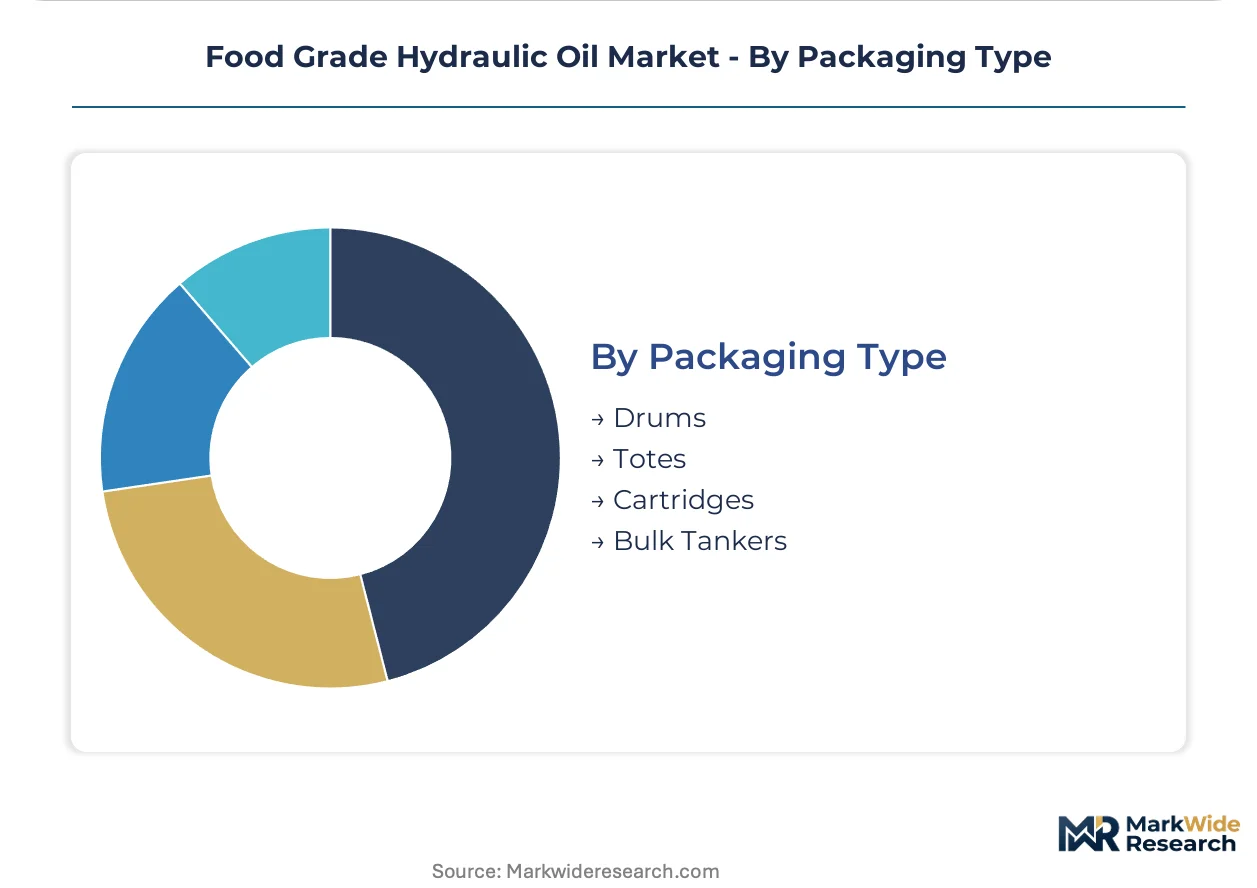
Packaging Type:
Packaging format selection correlates with consumption scale, storage infrastructure, and contamination control protocols.
- Bulk Tankers:Dedicated fleet delivery serves dairy processing cooperatives and multinational beverage bottlers with centralized bulk storage and automated transfer systems. Direct compounder relationships enable lot traceability and certificate of analysis integration with plant maintenance software.
- Drums:208-liter steel containers remain standard for mid-scale food manufacturers without bulk unloading infrastructure, offering flexibility across multiple equipment types.
- Totes:Intermediate bulk containers bridge drum and tanker volumes for regional processing facilities consolidating lubricant purchases.
- Cartridges:Pre-filled lubricant cartridges serve point-of-application needs in equipment with integrated automatic lubrication systems.
Shipment value concentrates in Bulk Tankers; format diversification accelerates among mid-scale processors upgrading from drum to tote configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for food grade hydraulic oil concentrates in Germany, where meat processing and dairy equipment upgrades drive replacement cycles for synthetic hydraulic fluids. Regulatory divergence between NSF H1 and emerging national standards forces compounders to maintain parallel certification investments across multiple jurisdictions.
Germany
Meat rendering systems and continuous fryer hydraulics impose severe thermal loads on lubricant formulations. ECHA is lowering acceptable limits for sulfur-phosphorus extreme pressure additives under REACH, compelling manufacturers to source ashless alternatives. Bavarian meat processors are eliminating mineral oil alternatives to prevent varnish contamination of product contact surfaces.
United States
Pharmaceutical cleanroom equipment operators specify PAO-based formulations to extend drain intervals beyond 8,000 operating hours. FDA compliance for incidental food contact under 21 CFR 178.3570 remains mandatory, pushing reformulation away from certain sulfur-phosphorus extreme pressure additives. New Jersey and Pennsylvania pharmaceutical clusters are accelerating qualification of calcium sulfonate grease alternatives ahead of anticipated regulatory shifts.
Netherlands
Dairy cooperatives with centralized technical departments negotiate volume contracts specifying base stock origin and additive package composition. EU chemicals strategy PFAS restrictions are forcing reformulation of fluorinated grease thickeners used in hydraulic adjacent equipment. Rotterdam-area processing facilities are consolidating lubricant purchases through direct compounder relationships.
India
Domestic dairy and edible oil processing capacity is scaling rapidly, creating first-mover positioning opportunities for NSF-registered suppliers. FSSAI is developing H1-equivalent certification frameworks to align with international standards. Maharashtra and Gujarat food processing corridors are attracting lubricant vendors establishing local blending capabilities.
Switzerland
Pharmaceutical equipment OEMs are accelerating qualification of calcium sulfonate and polyurea alternatives to maintain ISO 21469 compliance. Swissmedic oversight of pharmaceutical manufacturing equipment creates stringent particulate and bioburden control requirements. Basel-region pharmaceutical cleanroom operators are harmonizing formulations across manufacturing networks to simplify compliance documentation.
Food Grade Hydraulic Oil Market Competitive Landscape
Backward integration into base oil production dominates the current landscape as compounders seek supply resilience and margin control. The vendor base separates into three tiers: integrated majors with captive additive blending networks, regional specialists serving single-country dairy cooperatives, and distributor-dependent resellers. European compounders leverage in-house Group III production while North American players extend food-grade certifications across marine and industrial distribution arms. Portfolio diversification and geographic expansion represent the two dominant competitive moves as companies respond to tightening NSF H1 compliance timelines.
Among European integrated lubricant manufacturers, Fuchs Petrolub SE exemplifies the additive blending network archetype, while TotalEnergies SE anchors the backward integration position through captive Group III base oil production. Shell plc occupies the global distribution tier, extending certifications across multiple industrial segments. These three represent distinct strategic postures: formulation expertise concentration, upstream supply control, and geographic reach maximization.
| Leading Market Players |
|---|
| Fuchs Petrolub SE |
| TotalEnergies SE |
| Chevron Corporation |
| Exxon Mobil Corporation |
| Shell plc |
| BP p.l.c. |
| Petro-Canada Lubricants Inc. |
| AB SKF |
| Castrol Limited |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap compounders across Germany and the Netherlands anchor supply discipline through generational ownership structures that resist short-term margin compression, enabling sustained investment in NSF H1 certification pipelines while maintaining pricing power against distributor-dependent resellers.
Pricing Analysis
Volume pools in mineral oil formulations serving legacy beverage bottling lines, while margin concentrates in synthetic PAO and ester grades for pharmaceutical cleanrooms and clean-label food manufacturing. Price differentiation separates ISO 21469-certified premiums from standard H1 registrations, with certification tier and base stock origin as primary drivers. Cost compression in mineral oil tiers is intensifying because dairy cooperatives are consolidating purchasing power through direct compounder contracts. Beverage bottlers with aging equipment fleets remain most price-sensitive; pharmaceutical cleanroom operators prioritize drain interval economics over upfront fluid costs.
Supply Chain Analysis
Used fluid collection and re-refining networks are expanding across the Rhine-Ruhr industrial corridor, creating circular supply options that supplement virgin base stock procurement. High-purity Group III production concentrates in Germany, the Netherlands, and South Korea, with European compounders drawing from a limited refiner pool. Supply chain risk rests on single-source vulnerability for ashless additive packages sourced from specialty chemical producers. Distribution runs through direct compounder relationships for large dairy cooperatives, while regional distributors serve fragmented meat processing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NSF H1 registration timeline compression is forcing a consolidation play, as 14-18 month certification backlogs strand R&D investments for compounders without pipeline depth or capital reserves to survive launch delays.
For Market Incumbents: Anchor market position through backward integration into Group III base oil production or captive additive blending networks. Defend against emerging regional specialists in India by accelerating FSSAI-equivalent certification ahead of formal framework rollout. Prioritize talent retention programs targeting formulation chemists approaching retirement. For New Entrants and Emerging Players: Digital fluid monitoring platforms paired with predictive analytics subscriptions offer a direct-channel route to bypass established distributor relationships. White-space exists in India’s Maharashtra and Gujarat food processing corridors before local blending capacity saturates. Target mid-scale meat processors upgrading from mineral oil to synthetic ester formulations with condition-based replacement service bundles. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with established NSF registrations and stranded R&D pipelines in Germany and the Netherlands. Five-to-ten year viability hinges on navigating PFAS restriction implementation without formulation disruption. Monitor ECHA definitive rulings on fluorinated grease thickeners as inflection indicator for pharmaceutical equipment adjacent demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | TotalEnergies SE secures supply resilience against European refiner capacity constraints. |
| NSF H1 Registration Acceleration | Early-mover positioning captures India FSSAI framework alignment before domestic competitors qualify. |
| Digital Fluid Monitoring Platform Launch | IoT sensor subscriptions displace distributor intermediaries in beverage bottling accounts. |
| PFAS-Free Formulation Qualification | Calcium sulfonate grease alternatives maintain ISO 21469 compliance ahead of ECHA restrictions. |
| Direct Procurement Channel Expansion | Danish and Dutch dairy cooperatives consolidate volume contracts with specified base stock origins. |
Research Methodology
Trade data from Eurostat, U.S. Census Bureau import records, and ECHA substance registration databases formed the secondary backbone, cross-referenced with primary interviews involving lubricant formulation chemists, dairy cooperative procurement directors, pharmaceutical equipment OEM technical leads, and NSF International certification auditors. Bottom-up volume estimates triangulated against top-down market sizing from customs filings and industry association reports.
Historical trendline analysis of base stock pricing volatility and certification registration timelines informed projection modeling across the analysis window. Segmentation dimensions included base stock chemistry tier, equipment thermal load profile, end-user procurement sophistication, and regional regulatory framework cluster. CAGRs derived from equipment replacement cycle analysis and synthetic fluid penetration curves in pharmaceutical cleanroom expansions.
The model holds under stable REACH and FDA regulatory trajectories; deviation in PFAS restriction timing or FSSAI framework acceleration would shift synthetic formulation demand curves. Practitioners should monitor ECHA substance evaluation updates and India food processing capacity buildout rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Smart Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Global Low Voltage Motors Market