
 Synchronous Electric Motor Market | 2026-2036
Synchronous Electric Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Synchronous Electric Motor Market Analytics
China's motor manufacturing belt is rewriting supply dynamics for synchronous electric motors. Siemens AG leverages its digital twin platforms to sustain engineering intensity across European industrial accounts. ABB Ltd. anchors high-voltage synchronous motor production for mining and cement applications in Latin America and Africa. Nidec Corporation dominates compact permanent magnet synchronous motor supply for robotics and semiconductor equipment makers.
A synchronous electric motor rotates at a speed locked to the frequency of its AC power supply, with rotor construction employing either wound-field electromagnets or permanent magnet arrays to maintain exact synchronism between electrical and mechanical frequency. Industrial automation end users represent the deepest installed base, while electric vehicle traction applications are expanding fastest as automakers specify hairpin-wound permanent magnet synchronous motors for power density. Field oriented control technology leads motor drive architecture, though direct torque control is gaining ground in pump and fan applications where fast dynamic response matters less than structural simplicity.
The EU Ecodesign Directive and IEC 60034 efficiency standards shape product design thresholds, while China's GB 18613 motor efficiency grades control market access for imports. The US Department of Energy enforces minimum efficiency standards through NEMA MG-1 tables, compressing demand for legacy wound-field designs. Stakeholders must monitor rare earth supply chain concentration and permanent magnet recycling infrastructure as procurement criteria harden around lifecycle carbon intensity.
Market Dynamics
Permanent magnet synchronous motor architectures are displacing wound-field designs across industrial automation, driven by the EU Ecodesign Directive's tightening efficiency tiers and automaker demand for power-dense traction systems. Supply concentration in rare earth processing is amplifying procurement risk for motor manufacturers.
Growth Catalysts
- EU Ecodesign Directive:Efficiency mandates above IE4 grades are forcing industrial buyers to retire legacy induction motors, accelerating synchronous motor retrofits in German automotive plants.
- Hairpin winding technology:Automakers specify hairpin-wound permanent magnet synchronous motors for electric vehicle traction, achieving 30% higher slot fill factors than round-wire alternatives.
- Stuttgart-Munich industrial corridor:Precision motion control demand from automotive assembly and semiconductor equipment makers concentrates synchronous motor procurement in southern Germany.
Market Restraints
- Rare earth supply concentration:Neodymium and dysprosium processing capacity concentrates in China's Jiangxi and Inner Mongolia, exposing motor manufacturers to export quota volatility.
- Permanent magnet cost structure:Magnet materials constitute 35-45% of motor BOM costs, with dysprosium prices subject to speculative trading on Chinese spot markets.
- Wound-field technical limitation:Brushless excitation systems in large synchronous motors require slip rings and maintenance intervals incompatible with unmanned offshore platforms.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for textile and food processing machinery are creating first-time synchronous motor demand among small and medium enterprises.
- Magnet recycling infrastructure:Hydrometallurgical recovery of rare earth elements from end-of-life motors is hybridizing with virgin material supply chains, reducing lifecycle carbon intensity.
- Direct torque control convergence:Pump and fan OEMs are pairing simplified DTC drives with synchronous motors, bypassing field-oriented control complexity in cost-sensitive HVAC applications.
Industry Challenges
- Motor-drive integration complexity:Field-oriented control tuning for permanent magnet synchronous motors requires specialized power electronics expertise scarce in traditional mechanical engineering departments.
- IEC 60034 certification timelines:Efficiency testing protocols for IE5 ultra-premium grades extend product validation cycles by 4-6 months, delaying revenue recognition.
- Legacy system interoperability:Retrofitting synchronous motors into existing variable frequency drive infrastructure triggers harmonic resonance issues requiring site-specific filtering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synchronous Electric Motor Market |
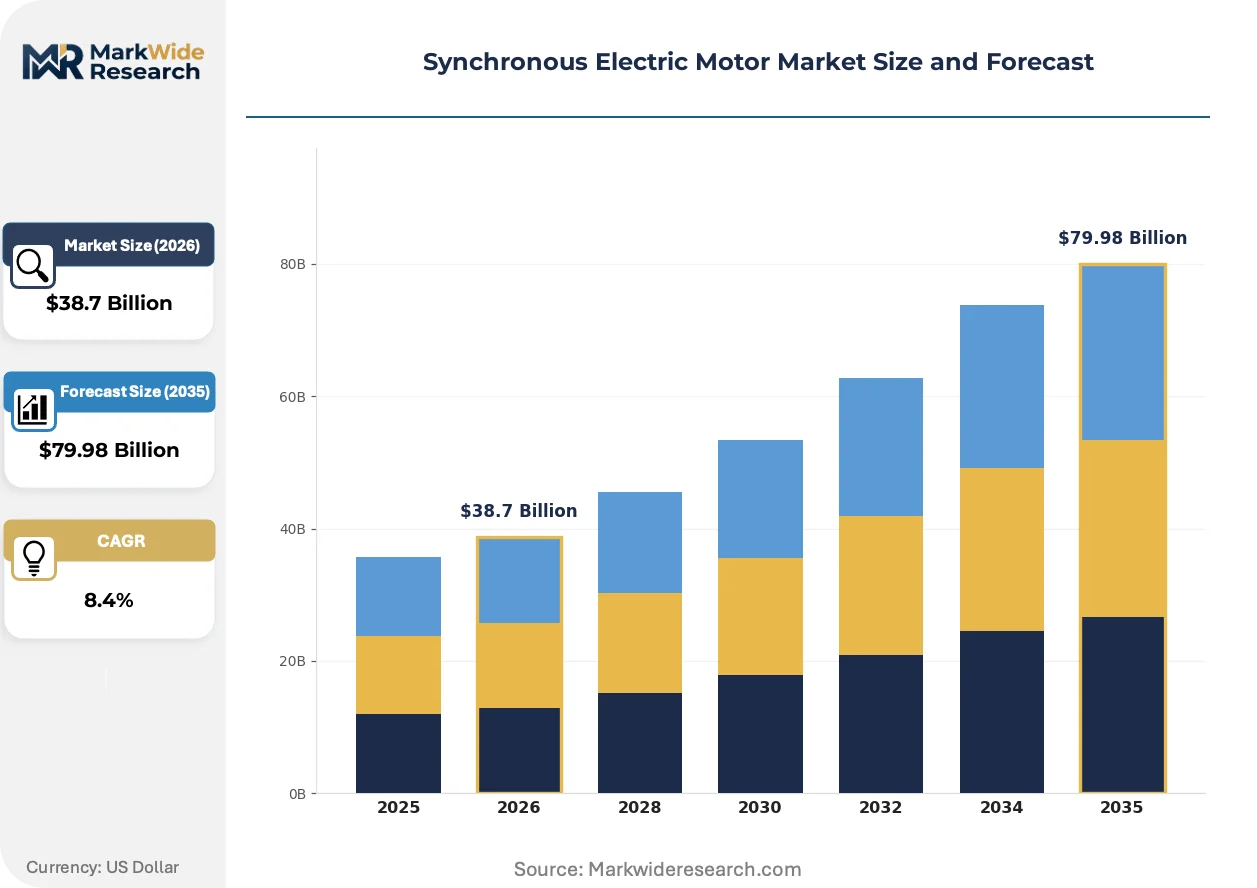
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless, Permanent Magnet, Synchronous Reluctance, Switched Reluctance End User: Industrial Automation, HVAC Systems, Electric Vehicles, Renewable Energy Application: Compressors, Pumps, Conveyors, Fans Technology: Field Oriented Control, Direct Torque Control, Vector Control, Active Front End |
| Companies Covered | ABB Ltd., Siemens AG, Nidec Corporation, WEG S.A., Rockwell Automation, Emerson Electric, Toshiba Corporation, General Electric, Fuji Electric Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchronous Electric Motor Market Evolving Landscape
Permanent magnet material science and digital twin simulation are compressing motor development cycles while regulatory pressure on efficiency grades intensifies specification volatility.
Axial-flux permanent magnet synchronous motor topology is hybridizing radial-flux dominance in power-dense applications. Electric vehicle traction motor designers at European and Asian automakers are adopting axial-flux architectures for 15-20% torque density improvements. This topology shift is compressing axial length constraints in front-wheel-drive platforms.
The EU Ecodesign Directive's 2023 recast tightens minimum efficiency requirements for motors above 75 kW to IE4 levels. Industrial buyers in German and Italian manufacturing clusters face accelerated replacement schedules for installed induction motor bases. Mining and cement applications in Latin America and Africa encounter compliance barriers when sourcing European-specified high-voltage synchronous motors.
Condition-based maintenance contracts are displacing traditional time-based service agreements for critical synchronous motor installations. Oil and gas operators in the North Sea and Middle East are unbundling motor monitoring from OEM service packages, favoring third-party vibration analysis providers. This procurement model evolution concentrates most visibly in offshore platform applications where unplanned downtime costs exceed $500,000 per day.
Synchronous Electric Motor Market Segmentation
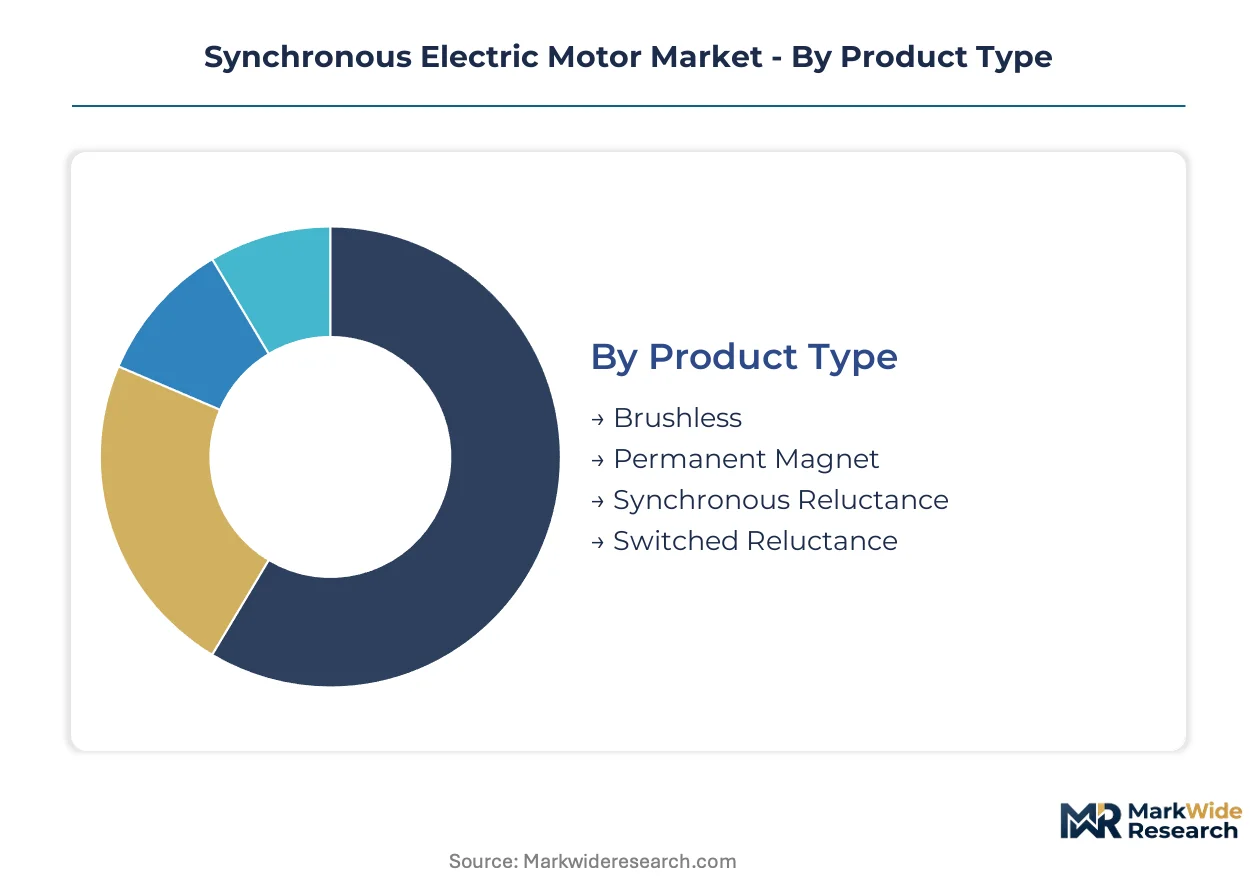
Synchronous motor architectures diverge sharply across power density requirements and control complexity. Segment boundaries reflect permanent magnet material choices, excitation methods, and drive electronics integration that determine suitability for precision motion versus bulk material handling.
Product Type:
Brushless and permanent magnet designs dominate power-dense applications, while reluctance variants serve cost-sensitive industrial loads where rare earth exposure is unacceptable.
- Brushless:Elimination of mechanical commutators through electronic switching enables maintenance-free operation in hermetically sealed compressor housings. Demand concentrates in HVAC refrigeration compressors for commercial buildings in Germany and Japan, driven by F-Gas Regulation phase-down schedules requiring higher efficiency cooling circuits.
- Permanent Magnet:Neodymium-iron-boron rotor arrays deliver the highest torque density among synchronous architectures, with hairpin winding techniques now standard in automotive traction specifications. Stuttgart-Munich automotive assembly plants specify these motors for robotic welding and paint shop conveyors, where precision positioning tolerances below 0.1 millimeters are mandatory.
- Synchronous Reluctance:Rotor saliency without permanent magnets eliminates supply chain exposure to dysprosium price volatility. Water treatment facilities in the US specify these motors for centrifugal pumps where IE4 efficiency grades suffice and capital cost sensitivity dominates.
- Switched Reluctance:Simple rotor construction withstands high-temperature environments in mining ventilation fans, though torque ripple requires application-specific vibration isolation.
Established volume favors Permanent Magnet; emerging adoption favors Synchronous Reluctance.
End User:
Customer segments separate by motion control precision requirements and duty cycle intensity, with electric vehicle traction representing the steepest expansion trajectory.
- Industrial Automation:Multi-axis servo systems in semiconductor equipment and automotive assembly require sub-millisecond torque response. German machine tool builders specify field-oriented control architectures for spindle applications where constant power speed ranges exceed 4:1 ratios.
- Electric Vehicles:Hairpin-wound permanent magnet synchronous motors achieve power densities above 4 kW per kilogram, enabling front-wheel-drive platform packaging constraints. European and Asian automakers are adopting axial-flux topologies for 15-20% torque density improvements over radial designs.
- HVAC Systems:Direct torque control paired with synchronous reluctance motors reduces drive complexity in commercial chiller plants. US Department of Energy NEMA MG-1 efficiency standards compress demand for legacy wound-field designs in this segment.
- Renewable Energy:Gearless direct-drive generators for wind turbines above 3 MW capacity employ electrically excited synchronous architectures to eliminate rare earth dependencies. Offshore installations in the North Sea favor brushless excitation systems with redundant cooling circuits.
Procurement scale favors Industrial Automation; specification volatility favors Electric Vehicles.
Application:
Load characteristics determine motor sizing methodology, with compressors and pumps representing continuous-duty applications where efficiency premiums justify synchronous motor cost premiums.
- Compressors:Hermetic refrigeration compressors in commercial HVAC systems specify brushless permanent magnet motors for partial-load efficiency optimization. EU Ecodesign Directive IE4 minimums for motors above 75 kW accelerate synchronous retrofits in industrial compressed air systems.
- Pumps:Centrifugal and positive displacement pump loads with quadratic torque curves suit direct torque control implementations. Water utilities in California specify premium efficiency synchronous motors for variable-flow municipal pumping stations under FERC demand response incentives.
- Conveyors:Belt and roller conveyor systems in distribution centers require precise speed synchronization across multiple drive points. E-commerce fulfillment facilities in the US Midwest specify distributed servo architectures with field-oriented control.
- Fans:Axial and centrifugal fan loads with low starting torque requirements accommodate simplified scalar control strategies. Mining ventilation applications in Latin America specify wound-field synchronous motors for explosive atmosphere compliance.
Retrofit urgency favors Compressors; greenfield specification favors Conveyors.
Technology:
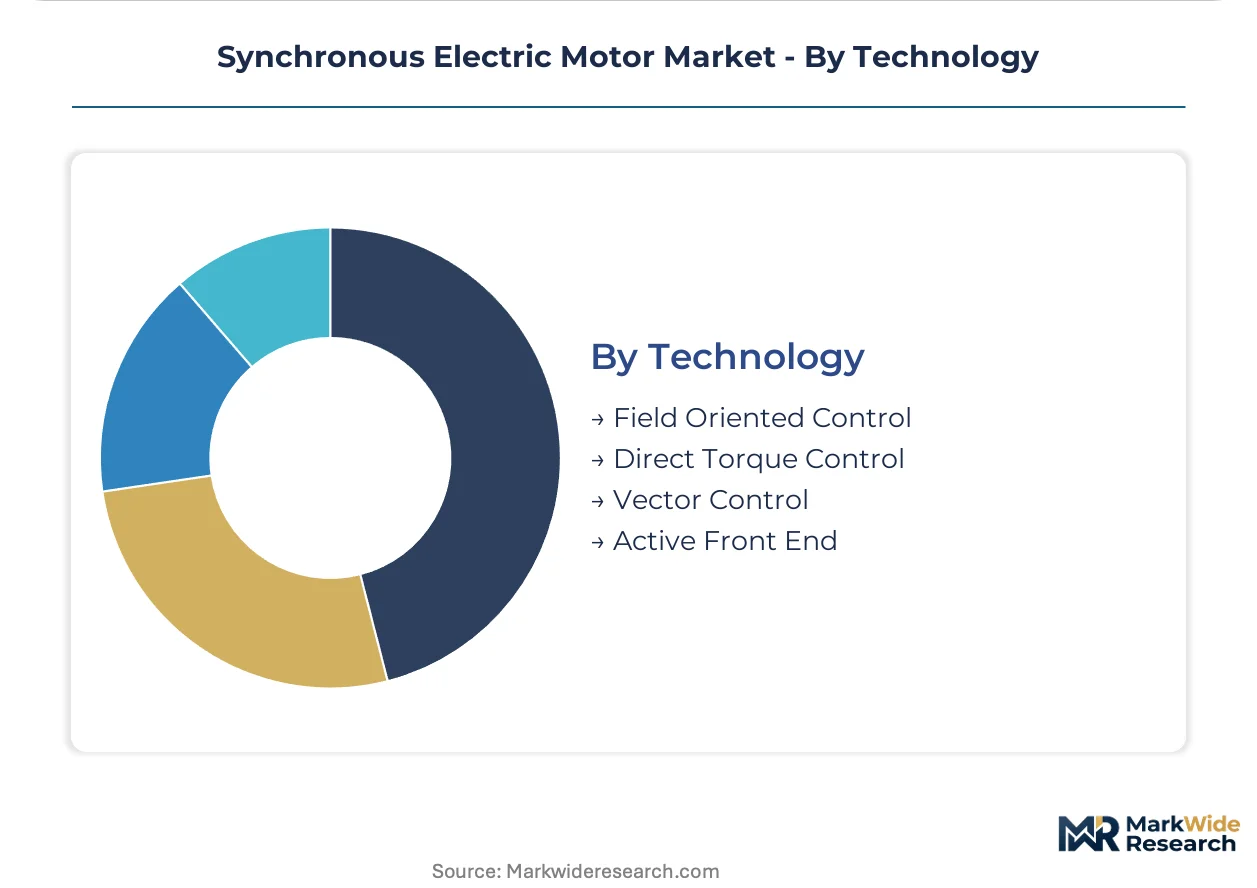
Control algorithm selection trades dynamic response performance against implementation complexity and sensor requirements.
- Field Oriented Control:Decoupled torque and flux control enables servo-grade dynamic response for multi-axis robotics. Semiconductor equipment makers in Japan and Taiwan specify FOC drives for wafer handling stages requiring nanometer positioning repeatability.
- Direct Torque Control:Hysteresis-based switching tables eliminate current loop regulators, reducing computational load for pump and fan applications. HVAC OEMs in Europe are pairing DTC drives with synchronous reluctance motors to bypass FOC tuning complexity.
- Vector Control:Indirect field orientation with current model observers provides intermediate performance for general-purpose industrial drives. Machine tool builders in Italy specify vector-controlled synchronous spindles for cost-sensitive turning centers.
- Active Front End:Regenerative rectifier topologies enable four-quadrant operation for crane and hoist applications with frequent deceleration cycles. Port container handling systems in Rotterdam and Hamburg specify AFE drives for energy recovery compliance.
Engineering intensity favors Field Oriented Control; cost optimization favors Direct Torque Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity concentrates in China's Jiangxi and Inner Mongolia provinces, creating supply chain exposure for motor manufacturers worldwide. This geographic clustering shapes procurement strategies across manufacturing regions.
China
Neodymium-iron-boron magnet production dominates global supply for permanent magnet synchronous motors. MIIT enforces GB 18613 motor efficiency grades controlling import market access. The Yangtze River Delta cluster around Shanghai anchors high-volume manufacturing for robotics and semiconductor equipment sectors.
Germany
Automotive assembly plants in the Stuttgart-Munich corridor scale precision motion control deployments. The EU Ecodesign Directive's IE4 minimums accelerate synchronous motor retrofits in industrial facilities. Siemens AG leverages digital twin platforms across European industrial accounts from Bavarian engineering centers.
United States
Water utilities specify premium efficiency synchronous motors for variable-flow municipal pumping stations. FERC demand response incentives compress payback periods for efficiency upgrades. The Midwest industrial belt around Michigan and Ohio concentrates automotive supplier demand for servo-grade motion systems.
Japan
Semiconductor equipment makers specify field-oriented control architectures for wafer handling stages. METI oversees JIS standards alignment with IEC 60034 efficiency protocols. The Chubu region around Nagoya anchors machine tool builder procurement for multi-axis spindle applications.
India
PLI scheme incentives for textile and food processing machinery create first-time synchronous motor demand among small enterprises. BIS certification requirements shape import specifications for industrial automation components. Gujarat and Maharashtra industrial corridors concentrate greenfield manufacturing investments.
Synchronous Electric Motor Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in magnet materials and power electronics. The vendor base structures around three tiers: diversified industrial conglomerates with full drive-motor integration capabilities, regional motor fabricators serving specific voltage classes, and rare earth material suppliers controlling upstream cost positions. Strategic moves concentrate on magnet recycling infrastructure partnerships and digital twin licensing arrangements.
Among diversified industrial conglomerates, ABB Ltd., Siemens AG, and Nidec Corporation occupy positions spanning drive electronics through motor manufacturing. ABB Ltd. represents the high-voltage heavy-industry archetype. Siemens AG exemplifies digital-integrated platform provision. Nidec Corporation anchors compact permanent magnet specialization for precision applications. These three entities collectively illustrate the competitive spectrum from bulk material handling through semiconductor-grade motion control.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Nidec Corporation |
| WEG S.A. |
| Rockwell Automation |
| Emerson Electric |
| Toshiba Corporation |
| General Electric |
| Fuji Electric Co., Ltd |
| Others |
Value Network & Pricing Analysis
Undercapacity in European magnet finishing facilities is amplifying supplier pricing power for permanent magnet synchronous motors. The EU Ecodesign Directive's IE4 efficiency mandates are compressing demand for legacy wound-field designs while concentrating procurement leverage among automotive OEMs in the Stuttgart-Munich corridor.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure for synchronous motors across European industrial accounts. Pricing stratifies across IE4 premium, IE5 ultra-premium, and legacy standard tiers, with efficiency certification grade and volume scale serving as primary differentiation drivers. Cost compression in standard-tier wound-field motors is intensifying because Chinese manufacturers are absorbing rare earth price volatility to maintain market share. Small and medium enterprises in India's textile sector exhibit highest price sensitivity, while German automotive assembly plants demonstrate lowest sensitivity due to precision motion control requirements.
Supply Chain Analysis
Contract manufacturing for permanent magnet synchronous motors concentrates among Yangtze River Delta facilities around Shanghai and Ningbo, with secondary capacity in Japan's Chubu region and South Korea's Gyeonggi-do cluster. Neodymium-iron-boron magnet arrays, hairpin copper windings, and silicon steel laminations constitute critical input dependencies. Single-source vulnerability in Jiangxi and Inner Mongolia rare earth processing exposes motor manufacturers to export quota volatility. Distribution runs through direct OEM supply agreements for automotive traction applications and industrial distributor networks for general-purpose automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synchronous electric motor market is entering a cyclical recovery phase driven by EU industrial efficiency retrofit mandates. Capital expenditure cycles in German automotive assembly are accelerating replacement demand for precision motion systems.
For Market Incumbents: Entrench digital twin platform differentiation to lock in European automotive accounts against emerging Asian competitors. Prioritize backward integration into magnet recycling infrastructure to reduce lifecycle carbon intensity exposure and secure supply chain resilience against Chinese export quota volatility. For New Entrants and Emerging Players: India's PLI-subsidized textile and food processing machinery sector offers the most penetrable geographic underpenetration for first-time synchronous motor adoption. Target synchronous reluctance motor specifications where rare earth supply chain exposure disqualifies permanent magnet competitors. Pursue channel partnerships with established industrial distributors rather than direct OEM engagement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among condition-based maintenance service providers for offshore oil and gas installations. Long-term viability over the next decade hinges on magnet recycling infrastructure positioning and digital twin software licensing capabilities. Monitor FERC demand response incentive expansion across US water utilities as an inflection indicator for premium efficiency motor procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Recycling Infrastructure Partnership | Hydrometallurgical recovery of dysprosium and neodymium reduces lifecycle carbon intensity for EU Ecodesign compliance. |
| Digital Twin Platform Licensing | Siemens AG leverages Bavarian engineering centers to sustain engineering intensity across European industrial accounts. |
| Hairpin Winding Technology Scale-Up | Automakers specify hairpin-wound permanent magnet synchronous motors for 30% higher slot fill factors in traction applications. |
| Direct Torque Control Drive Integration | HVAC OEMs pair simplified DTC drives with synchronous reluctance motors to bypass field-oriented control complexity. |
| Axial-Flux Topology Manufacturing Investment | European and Asian automakers adopt axial-flux architectures for 15-20% torque density improvements in front-wheel-drive platforms. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the synchronous electric motor value chain. Primary interviews engaged motor drive engineers at automotive OEMs, procurement leads at industrial automation distributors, maintenance directors at water utilities, and power electronics specialists at semiconductor equipment makers. Secondary validation drew from IEC 60034 efficiency testing protocols, SEC filings of listed motor manufacturers, EU Ecodesign Directive regulatory texts, and FERC demand response program databases. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Calibration against historical efficiency standard adoption curves and automotive platform electrification timelines anchored the projection framework. Segmentation dimensions modeled include motor architecture type, end-use industry, control technology, power density tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity expansion announcements. Rare earth price volatility indices and permanent magnet recycling capacity buildout schedules served as industry-specific forecast inputs throughout the modeling period.
Practitioners should monitor Chinese export quota announcements and EU Ecodesign Directive recast timelines for early signals of supply constraint or demand acceleration. Forecasts reflect assumptions around permanent magnet material substitution rates and field-oriented control adoption curves. Quarterly review of MIIT GB 18613 enforcement patterns and BIS certification backlog indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Smart Motors Market
Industrial Motors
Gear Motor Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Power Stacker Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Industrial Motor Brakes Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Global Low Voltage Motors Market