
 Electric Motors for Drones and Electric Vehicle Market | 2026-2036
Electric Motors for Drones and Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Motors for Drones and Electric Vehicle Market Analysis
China is rewriting supply dynamics for electric motors as Ningbo and Shenzhen expand dedicated production corridors for high-efficiency traction and propulsion units. Nidec anchors permanent magnet motor capacity through its Dalian and Pinghu facilities, leveraging integrated rotor-stator assembly lines. BorgWarner competes via its eAxle and motor portfolio, sustaining engineering presence in Shanghai and Wuhan. DeepDrive specializes in compact axial-flux architectures, differentiating on torque density for urban air mobility platforms.
Electric motors for drones and electric vehicles are electromechanical devices converting electrical energy into mechanical torque through electromagnetic interaction, typically operating at voltages from 48V to 800V with power densities exceeding 3 kW per kilogram for aerospace-grade brushless units. Their primary purpose is propulsion and traction across unmanned aerial systems and electrified ground transport. Brushless DC motors lead the product type landscape due to superior efficiency and thermal management in confined drone airframes, while permanent magnet technology captures the dominant technology share despite rare earth supply constraints. The autonomous driving application segment shows the fastest structural expansion as OEMs integrate wheel-hub and in-wheel motor configurations for precision torque vectoring.
The EPA tailpipe emission standards and NHTSA CAFE requirements in the United States are accelerating OEM motor electrification roadmaps, while the EU Green Deal and REACH chemical compliance reshape magnet composition and recyclability mandates across European supply chains. China's MIIT dual carbon goals and GB standards enforce domestic efficiency benchmarks that filter through export-oriented motor suppliers. Stakeholders must monitor rare earth processing concentration and alternative magnet formulations as the primary variables affecting cost trajectories and supply security.
Market Dynamics
Rare earth magnet supply concentration in China's processing corridor is forcing motor designers toward ferrite-assisted and induction alternatives, compressing permanent magnet dependence while tightening efficiency requirements from regulators.
Growth Catalysts
- Urban Air Mobility Deployment:Cargo drone fleets in Shenzhen and Dubai are scaling 800V axial-flux motor procurement for heavy-lift last-mile logistics, pulling torque density requirements above 5 kW/kg.
- EU F-Gas Efficiency Mandates:The regulation is tightening thermal management standards for traction motors, accelerating oil-cooled stator designs in European EV platforms.
- Silicon Carbide Inverter Pairing:Wide-bandgap power electronics are enabling 20 kHz+ switching frequencies, allowing motor designers to shed copper mass while maintaining output.
Market Restraints
- Dysprosium-Terbium Price Volatility:Heavy rare earth processing bottlenecks in southern China are inflating magnet costs for high-temperature traction applications.
- Single-Source Stator Lamination Supply:Electrical steel cold-rolling capacity concentrates in Nippon Steel and POSCO facilities, creating vulnerability for 0.2mm thin-gauge motor cores.
- Copper Winding Density Limits:Slot fill fractions above 65% require automated hairpin insertion that remains capital-intensive for sub-50k annual volumes.
Strategic Opportunities
- India PLI Scheme for Auto Components:The production-linked incentive is drawing motor assembly investments into Tamil Nadu and Gujarat for two-wheeler and three-wheeler traction units.
- Wheel-Hub Integration for Autonomous Shuttles:Torque vectoring demands from robotaxi platforms are opening design space for in-wheel motor architectures with integrated braking.
- Hydrogen Fuel Cell Auxiliary Motors:Balance-of-plant compressor and pump motors for FCV stacks represent unpenetrated demand as Hyundai and Toyota expand fuel cell truck pilots.
Industry Challenges
- Multiphysics Simulation Talent Scarcity:Electromagnetic-thermal-structural co-design for 20,000 RPM aerospace motors requires scarce expertise in ANSYS Maxwell and Motor-CAD platforms.
- DO-178C Aerospace Certification Timelines:Drone propulsion software qualification for beyond-visual-line-of-sight operation stretches 18-24 months, compressing product refresh cycles.
- Legacy Automotive Tooling Incompatibility:Round-wire stator winding equipment cannot be retrofitted for hairpin or continuous-waveform geometries without full line replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Motors for Drones and Electric Vehicle Market |
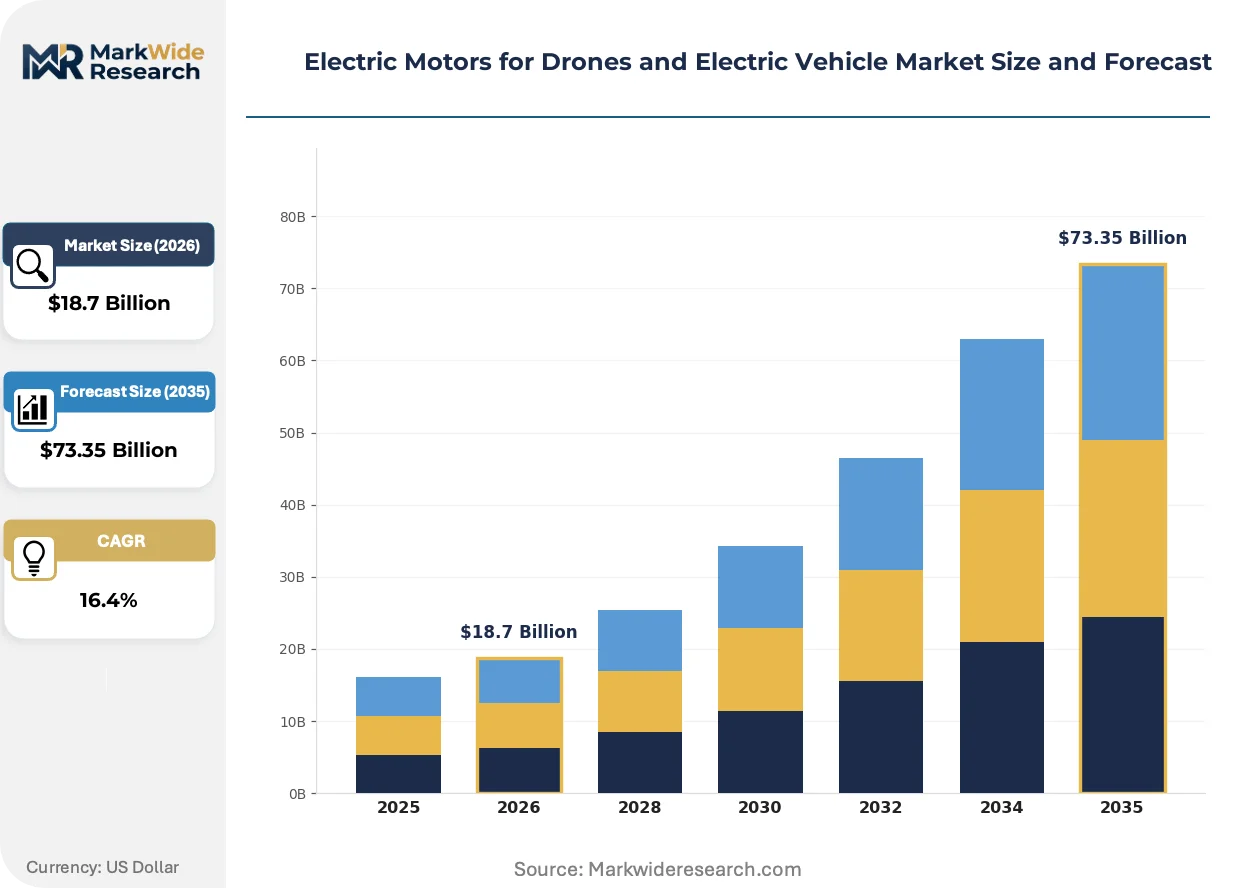
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless, Stepper, Induction, Synchronous End User: Aerospace, Automotive OEMs, Logistics, Agriculture Technology: Permanent Magnet, Switched Reluctance, Linear, Direct Drive Application: Payload Delivery, Recreational, Autonomous Driving, Military |
| Companies Covered | Hitachi, DeepDrive, BorgWarner, Allison Transmission, Danfoss Editron, Dana TM4, Elaphe, Detroit eAxles, Nidec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Motors for Drones and Electric Vehicle Market Emerging Trajectories
Axial-flux topologies and advanced thermal architectures are compressing motor mass while regulatory pressure on magnet supply chains accelerates material substitution roadmaps across aerospace and automotive programs.
Axial-flux permanent magnet motors with dual-rotor single-stator configurations are delivering 30% torque density improvements over radial equivalents for constrained drone airframes. Urban air mobility developers in Germany and the United Kingdom are qualifying these units for eVTOL transition phases above 150 kW peak. The topology is rendering obsolete conventional radial-flux designs in weight-critical applications where 50 grams of saved copper translates to payload capacity.
China's MIIT dual carbon enforcement and updated GB efficiency standards are mandating IE4-equivalent performance for domestically produced traction motors above 7.5 kW. Export-oriented suppliers in Ningbo and Changzhou are requalifying stator lamination grades and magnet compositions to maintain market access. The regulatory pressure is most acute for mid-power industrial motors repurposed for electric van drivetrains, where suppliers face 6-12 month redesign cycles.
Fleet operators are consolidating motor procurement through direct supplier contracts rather than Tier 1 system integrators, compressing margin capture for eAxle assemblers. Logistics operators in California and the Netherlands are establishing technical qualification teams to audit motor durability data directly. This disintermediation is most visible in last-mile electric van deployments above 500 units, where fleet-scale engineering resources justify bypassing traditional drivetrain suppliers.
Electric Motors for Drones and Electric Vehicle Market Segmentation
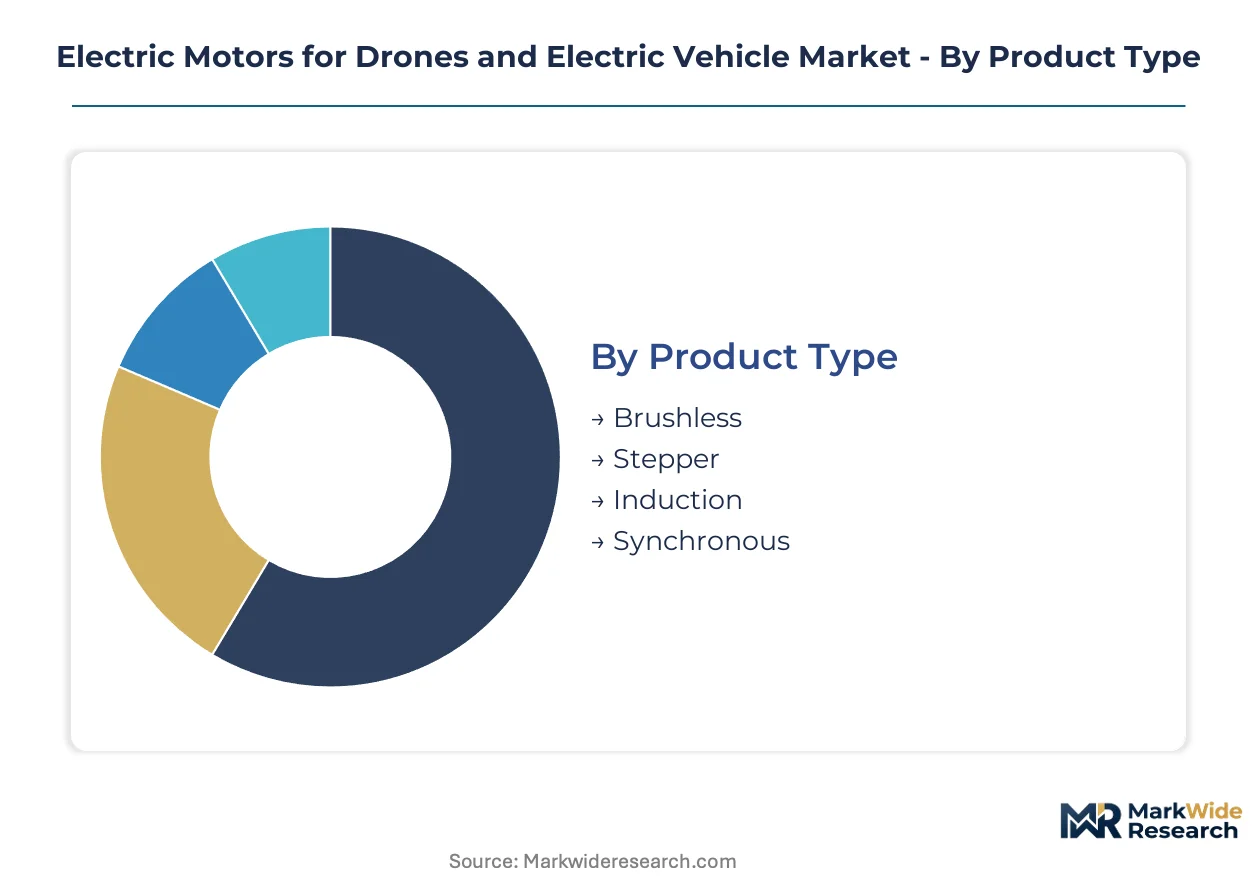
Motor architectures diverge sharply between aerospace weight constraints and automotive durability requirements. Procurement patterns across these segments reveal how torque density, thermal management, and certification complexity reshape supplier selection criteria.
Product Type:
Brushless configurations dominate where electromagnetic interference and maintenance intervals determine operational economics.
- Brushless:Permanent magnet rotors with electronic commutation deliver 90%+ efficiency at 10,000+ RPM for multirotor propulsion. Demand concentrates in Shenzhen's cargo drone manufacturing corridor, where 800V axial-flux variants are scaling for heavy-lift logistics above 50 kg payload.
- Induction:Squirrel-cage rotors eliminate rare earth dependencies while tolerating thermal overloads in commercial EV traction. European van fleets in the Netherlands and Germany are qualifying these units for last-mile delivery platforms seeking magnet supply security.
- Stepper:Discrete angular positioning suits gimbal stabilization and sensor alignment in surveying drones.
- Synchronous:Field-excited rotors enable precise speed control for autonomous shuttle traction systems.
Established volume favors Brushless; emerging adoption favors Induction.
End User:
Procurement authority sits with engineering teams whose durability specifications and certification burdens vary by operational environment.
- Automotive OEMs:Wheel-hub and eAxle integrations require 15-year corrosion resistance and ISO 26262 functional safety compliance. Ningbo's motor suppliers are requalifying stator lamination grades to meet MIIT dual carbon efficiency mandates for export qualification.
- Aerospace:eVTOL developers in Germany and the United Kingdom are sourcing dual-rotor axial-flux units for transition-phase power density above 5 kW/kg. DO-178C software certification timelines stretch 18-24 months for beyond-visual-line-of-sight propulsion systems.
- Logistics:Fleet operators in California are consolidating direct motor contracts, bypassing Tier 1 integrators for electric van deployments above 500 units.
- Agriculture:Spray drone operators in Brazil prioritize corrosion-resistant sealing for chemical exposure in tropical humidity.
Automotive OEMs anchor current procurement volume; Aerospace commands the steepest expansion trajectory.
Technology:
Magnet composition and flux path geometry determine cost structures and supply chain vulnerability profiles.
- Permanent Magnet:Neodymium-iron-boron rotors achieve highest torque density but face dysprosium-terbium price volatility from southern Chinese processing concentration. Designers are ferrite-assisting to reduce heavy rare earth dependence while maintaining efficiency.
- Switched Reluctance:Salient-pole rotors without windings or magnets tolerate extreme temperatures in mining and defense applications where maintenance access is limited.
- Linear:Direct electromagnetic thrust eliminates mechanical transmission for precision positioning in autonomous shuttle docking systems.
- Direct Drive:Elimination of gearboxes reduces maintenance in offshore wind turbine pitch control and marine propulsion derivatives repurposed for heavy-lift drones.
Permanent Magnet retains manufacturing scale; Switched Reluctance gains share fastest in high-temperature traction.
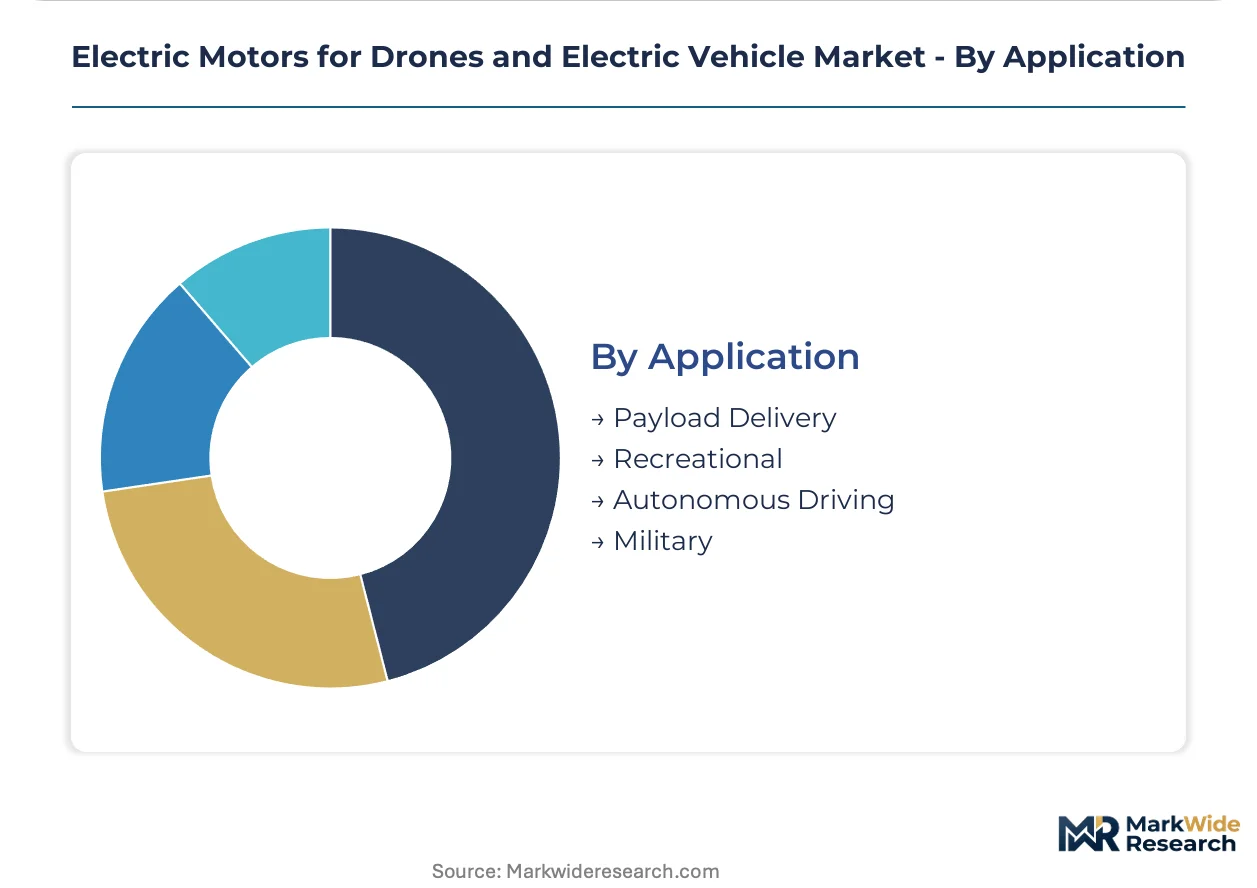
Application:
Operational profiles from recreational hobbyist use to military endurance missions dictate thermal management and redundancy architectures.
- Autonomous Driving:In-wheel motor configurations with integrated braking enable precision torque vectoring for robotaxi platforms. Silicon carbide inverter pairing at 20 kHz+ switching frequencies allows copper mass reduction while maintaining output.
- Payload Delivery:Last-mile cargo drones in Dubai and Shenzhen are scaling 800V systems for urban corridor operations above 150 kW peak. EU F-Gas Regulation is tightening thermal management standards, accelerating oil-cooled stator designs.
- Recreational:Consumer racing drones prioritize 3-5 minute burst power over thermal sustainability.
- Military:Surveillance platforms require EMI-hardened commutation and encrypted control links for contested electromagnetic environments.
Payload Delivery dominates current fleet procurement; Autonomous Driving represents the deepest engineering investment pipeline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT dual carbon enforcement and updated GB efficiency standards anchor supply-side dynamics, while the EU Green Deal and F-Gas Regulation reshape import requirements. Shenzhen's drone manufacturing cluster and Ningbo's EV supply base concentrate production scale for export-oriented suppliers.
China
Shenzhen's cargo drone corridor and Ningbo's EV motor base drive procurement scale for high-efficiency traction units. MIIT dual carbon goals and GB standards enforce IE4-equivalent performance for motors above 7.5 kW. Dalian and Pinghu facilities anchor permanent magnet rotor-stator assembly lines for regional export qualification.
Germany
eVTOL developers in Munich and Stuttgart source dual-rotor axial-flux units for transition-phase power density requirements. The EU F-Gas Regulation tightens thermal management standards for traction motors, accelerating oil-cooled stator designs. KBA oversight shapes type-approval timelines for autonomous shuttle motor integrations.
United States
EPA tailpipe emission standards and NHTSA CAFE requirements accelerate OEM motor electrification roadmaps for light-duty platforms. California fleet operators consolidate direct motor contracts for electric van deployments above 500 units. Detroit eAxles and Midwest manufacturing clusters sustain automotive-grade volume production.
India
The PLI scheme for auto components draws motor assembly investments into Tamil Nadu and Gujarat for two-wheeler and three-wheeler traction units. BIS efficiency mandates filter through domestic suppliers repurposing industrial motor designs. Engineering teams in Pune and Chennai requalify stator lamination grades for tropical humidity endurance.
Japan
METI industrial policy supports rare earth magnet recycling infrastructure to reduce import dependence for high-temperature traction applications. Automotive OEMs in Nagoya and Tokyo integrate silicon carbide inverter pairing at 20 kHz+ switching frequencies. JIS standards enforcement maintains quality benchmarks for export-oriented motor suppliers.
Electric Motors for Drones and Electric Vehicle Market Vendor Landscape
Capability concentration sits with specialized axial-flux designers; scale advantage sits with integrated rotor-stator assemblers. The market structures around three tiers: rare-earth-dependent permanent magnet specialists, rare-earth-free induction and switched reluctance developers, and system-integrated eAxle providers. Consolidation pressures favor M&A activity between stator lamination suppliers and winding equipment providers, while capacity expansion concentrates in Ningbo and Shenzhen corridors for export qualification.
Among integrated motor-assemblers, Nidec and BorgWarner occupy positions spanning permanent magnet traction and eAxle system integration. DeepDrive exemplifies the specialized tier, anchoring compact axial-flux architectures for weight-critical applications. Detroit eAxles represents the automotive-heritage segment, sustaining volume production through legacy OEM relationships and Midwest manufacturing infrastructure.
| Leading Market Players |
|---|
| Hitachi |
| DeepDrive |
| BorgWarner |
| Allison Transmission |
| Danfoss Editron |
| Dana TM4 |
| Elaphe |
| Detroit eAxles |
| Nidec |
| Others |
Supply Flow & Price Mechanics
Ningbo's EV motor manufacturing corridor anchors global permanent magnet rotor-stator assembly capacity, compressing pricing power for export-oriented suppliers while amplifying cost advantages for integrated producers serving Shenzhen's drone cluster. Downstream fleet operators in California and the Netherlands exploit this concentration through direct procurement contracts that bypass traditional Tier 1 margin capture.
Pricing Analysis
Price spreads between Shenzhen-sourced axial-flux units and European-assembled equivalents reflect magnet composition tiers and certification overhead. Three-tier pricing structure across aerospace-grade, automotive-qualified, and industrial-repurposed levels segments buyers by torque density requirements and thermal management specifications. Cost compression in mid-power traction applications intensifies as Ningbo suppliers requalify stator lamination grades for MIIT dual carbon compliance. Logistics fleet operators exhibit highest price sensitivity, while eVTOL developers prioritize power density over unit economics.
Supply Chain Analysis
Export control regimes restricting rare earth processing technology transfer limit non-Chinese magnet manufacturing scale, tethering high-temperature traction motor supply to southern Chinese dysprosium-terbium corridors. Raw material dependencies center on neodymium-iron-boron alloys, electrical steel cold-rolled to 0.2mm gauge, and copper winding stock. Single-source vulnerability concentrates in Nippon Steel and POSCO thin-gauge lamination capacity. Distribution runs through direct OEM contracts for volumes above 500 units, disintermediating traditional eAxle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against ferrite-assisted and induction motor architectures that threaten permanent magnet dominance. Incumbents must navigate rare earth supply security while maintaining efficiency leadership against rare-earth-free alternatives.
For Market Incumbents: Insulate magnet supply through captive processing partnerships in southern Chinese corridors or accelerated ferrite-assisted formulation R&D. Secure stator lamination offtake agreements with Nippon Steel and POSCO before capacity allocation tightens. Priority lever: backward integration into electrical steel slitting operations to control core material quality and delivery timelines. For New Entrants and Emerging Players: Tamil Nadu and Gujarat assembly corridors under India's PLI scheme offer white-space traction motor opportunities for two-wheeler and three-wheeler platforms. Target switched reluctance architectures for mining and defense applications where maintenance access constraints favor magnet-free durability. Go-to-market angle: direct fleet qualification teams in California and the Netherlands seeking bypass procurement relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized axial-flux designers over commodity radial-flux assemblers as urban air mobility scales. Long-term viability across the projection horizon rests on torque density leadership above 5 kW/kg and DO-178C certification completion. Acquisition target archetype: dual-rotor topology specialists with qualified aerospace production lines. Signal to watch: silicon carbide inverter pairing adoption rates enabling copper mass reduction without output sacrifice.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Recycling Infrastructure | METI-supported Japanese facilities reduce import dependence for high-temperature traction applications. |
| Axial-Flux Topology Qualification | eVTOL developers in Germany and the United Kingdom source dual-rotor units for transition-phase power density. |
| Direct Fleet Procurement Contracts | California logistics operators bypass Tier 1 integrators for electric van deployments above 500 units. |
| Silicon Carbide Inverter Pairing | Wide-bandgap electronics enable 20 kHz+ switching frequencies allowing motor copper mass reduction. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat draw assembly investment for two-wheeler and three-wheeler traction units. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, fleet operator technical qualification teams, and axial-flux motor design specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through MIIT efficiency standard filings, EPA tailpipe emission rulemakings, EU F-Gas Regulation implementation guidance, and customs trade data for electrical steel and rare earth oxide flows. Bottom-up motor shipment estimates by application and top-down OEM electrification roadmap analysis triangulated on volume figures.
Demand-supply-balance modeling across the analysis window incorporated urban air mobility deployment timelines, last-mile fleet electrification procurement schedules, and autonomous shuttle robotaxi platform motor integration roadmaps. Segmentation dimensions included product architecture, magnet composition technology, end-user procurement authority, and regional regulatory cluster. CAGRs derived from fitted adoption curves against OEM platform launch schedules and fleet operator contract announcements. Industry-specific inputs captured silicon carbide inverter pairing adoption rates and DO-178C certification completion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by rare earth processors or electrical steel producers would shift outcomes. Material shifts in dysprosium-terbium price volatility, export control regime expansion, or multiphysics simulation talent availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Tank Insulation Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Power Scraper Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Synchronous Electric Motor Market