
 Variable Speed Drive Market | 2026-2036
Variable Speed Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Speed Drive Market Analysis
Aftermarket service revenue is reshaping margin pools across the Variable Speed Drive landscape as hardware commoditization pressures OEM profitability. ABB Ltd. leverages its installed base of medium-voltage drives to capture recurring service contracts across pulp and paper facilities. Siemens AG anchors its position through digital twin integration that extends hardware lifecycles and locks in platform stickiness. Schneider Electric SE competes on energy management software layers that differentiate commodity drive hardware.
A variable speed drive modulates electric motor rotational speed by varying input frequency and voltage, typically operating across 0.4 kW to 100 MW power ranges with switching frequencies between 2 kHz and 16 kHz depending on insulated-gate bipolar transistor or silicon carbide architectures. Its primary purpose is to match motor output to mechanical load requirements, eliminating energy losses from throttling valves, dampers, or mechanical brakes in pumps, fans, and compressors. AC Drives dominate unit shipments due to their cost efficiency across standard induction motor applications, while Servo Drives command premium positioning in precision motion control for automotive assembly and semiconductor manufacturing where vector control algorithms enable sub-millisecond torque response. VFD technology leads retrofit installations given its compatibility with existing motor windings, whereas soft starter penetration remains concentrated in fixed-speed applications requiring only controlled acceleration.
The US Department of Energy enforces minimum energy performance standards under 10 CFR 431 that disqualify non-compliant motors from federal procurement channels, while the EU Ecodesign Directive mandates IE3 efficiency tiers for motors above 0.75 kW with variable speed drive pairings increasingly required for compliance. China's GB 18613 standard imposes analogous efficiency grades through SAMR enforcement, creating harmonized pressure for drive adoption across export-oriented manufacturing. Stakeholders must monitor silicon carbide MOSFET cost curves and embedded predictive maintenance capabilities as the primary axes of technology differentiation and procurement criteria.
Market Dynamics
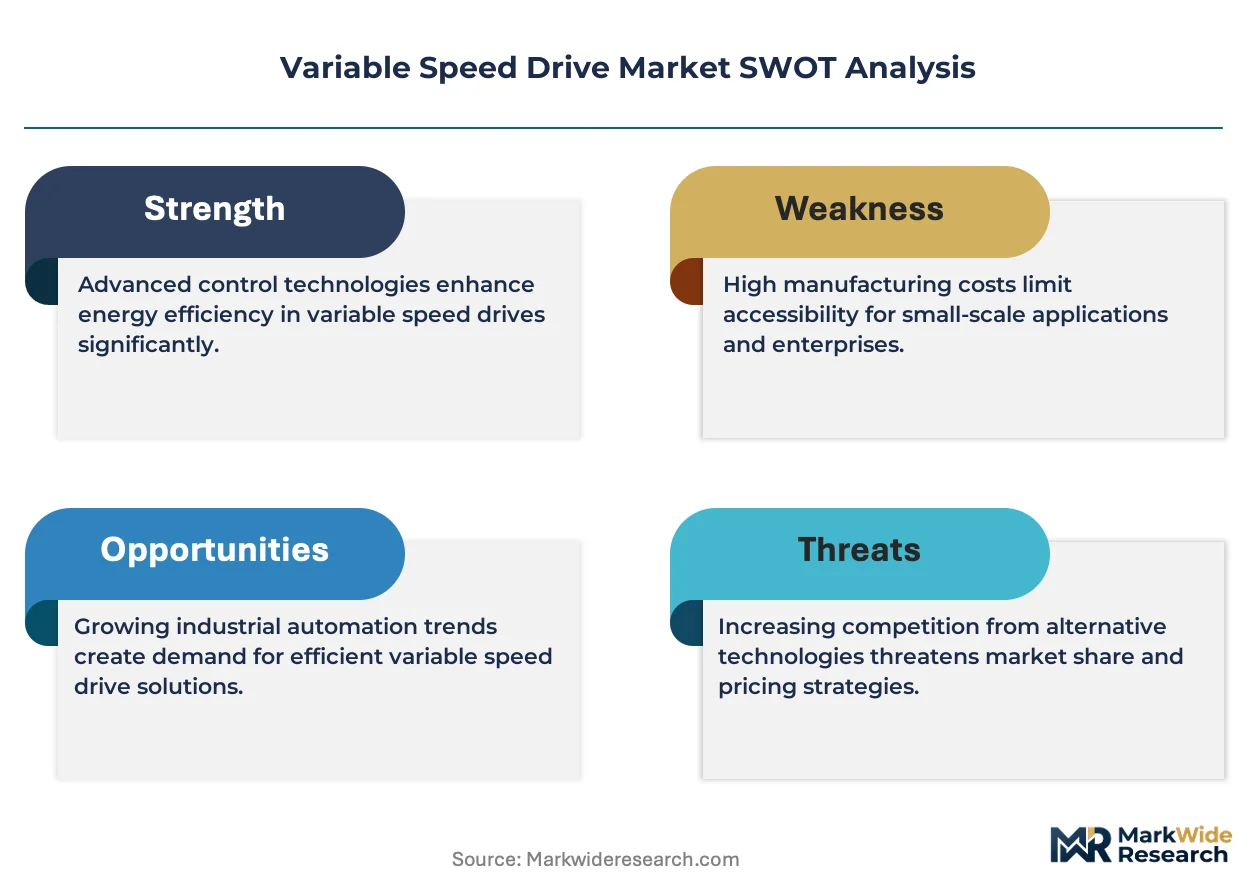
Silicon carbide MOSFET architectures are compressing switching losses and forcing incumbent IGBT suppliers into defensive R&D postures across the Variable Speed Drive landscape. The technology transition is redrawing component sourcing maps and rewiring procurement criteria toward thermal performance metrics rather than legacy cost-per-kilowatt benchmarks.
Growth Catalysts
- EU Ecodesign Directive:IE3 efficiency mandates for motors above 0.75 kW are compelling variable speed drive pairings across European manufacturing facilities.
- Water treatment infrastructure:Municipal retrofit programs are accelerating drive adoption in pumping stations and aeration systems.
- China's GB 18613 standard:SAMR enforcement of efficiency grades is triggering replacement cycles across export-oriented manufacturing clusters.
Market Restraints
- Silicon carbide substrate shortage:Limited wafer fabrication capacity is constraining MOSFET supply and inflating power module costs.
- Copper and rare earth volatility:Magnet material price swings are compressing margins for permanent magnet motor-drive combinations.
- Technical limitation in high-voltage integration:Insulation coordination challenges above 6.6 kV are slowing medium-voltage drive deployment in heavy industry.
Strategic Opportunities
- Predictive maintenance convergence:Embedded vibration analysis fused with edge computing is opening recurring revenue streams beyond hardware sales.
- India's industrial electrification:BIS efficiency labeling expansion is creating first-time drive demand in small and medium manufacturing enterprises.
- Energy-as-a-service models:Performance contracting is displacing capital expenditure procurement in commercial HVAC retrofits.
Industry Challenges
- Power electronics engineering scarcity:Shortage of designers proficient in wide-bandgap device gate drive circuits is extending product development timelines.
- Legacy motor compatibility:Retrofit installations face winding insulation stress assessment complexity when pairing modern drives with aged motor infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Speed Drive Market |
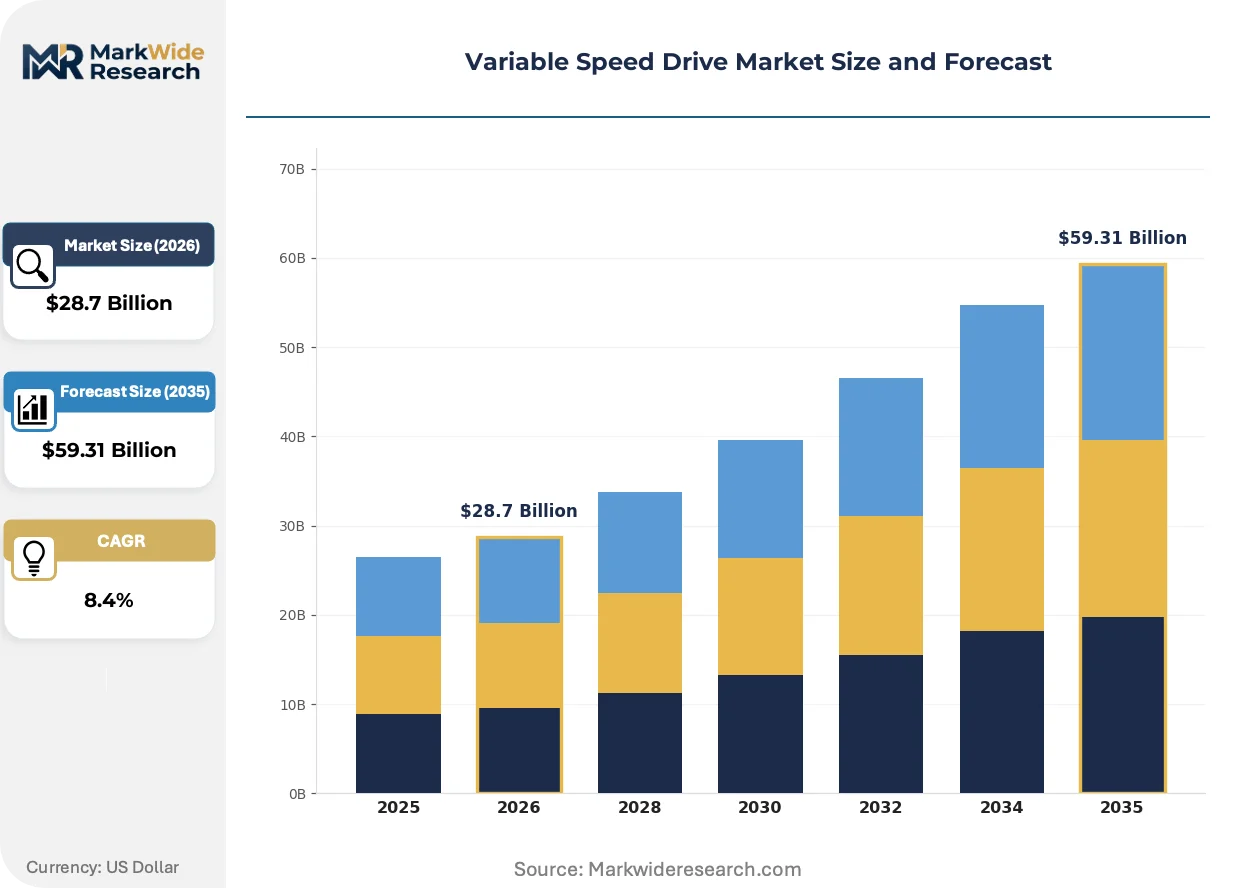
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Drives, DC Drives, Servo Drives, Adjustable Speed Drives Technology: VFD, Vector Control, Direct Online, Soft Starters End User: Manufacturing, Water Treatment, HVAC, Automotive Installation: Indoor, Outdoor, Portable, Fixed |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, Rockwell Automation, Inc., Danfoss A/S, Yaskawa Electric Corporation, Mitsubishi Electric Corporation, Eaton Corporation plc, Hitachi, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Speed Drive Market Emerging Trajectories
Digital twin integration is rewriting how drive performance is validated, commissioned, and maintained across industrial asset bases. The convergence of physics-based modeling with real-time operational data is collapsing traditional service boundaries.
Silicon carbide power semiconductors are enabling switching frequencies above 16 kHz with reduced thermal losses. Automotive battery manufacturing lines are adopting these drives for precision motor control in electrode coating operations. The technology is digitizing maintenance workflows by embedding thermal runaway prediction algorithms directly into drive firmware.
The US Department of Energy's 10 CFR 431 standards are disqualifying non-compliant motors from federal procurement channels. Industrial buyers are responding by specifying integrated motor-drive packages that guarantee efficiency compliance. Water treatment facilities in California and Texas are experiencing the most acute procurement pressure as federal infrastructure funding flows require certified equipment.
Service contract unbundling is fragmenting how buyers acquire drive capability. End-users in pulp and paper are separating hardware procurement from commissioning and long-term maintenance. China and Germany are exhibiting the sharpest divergence between transactional equipment sales and lifecycle performance agreements.
Variable Speed Drive Market Segmentation
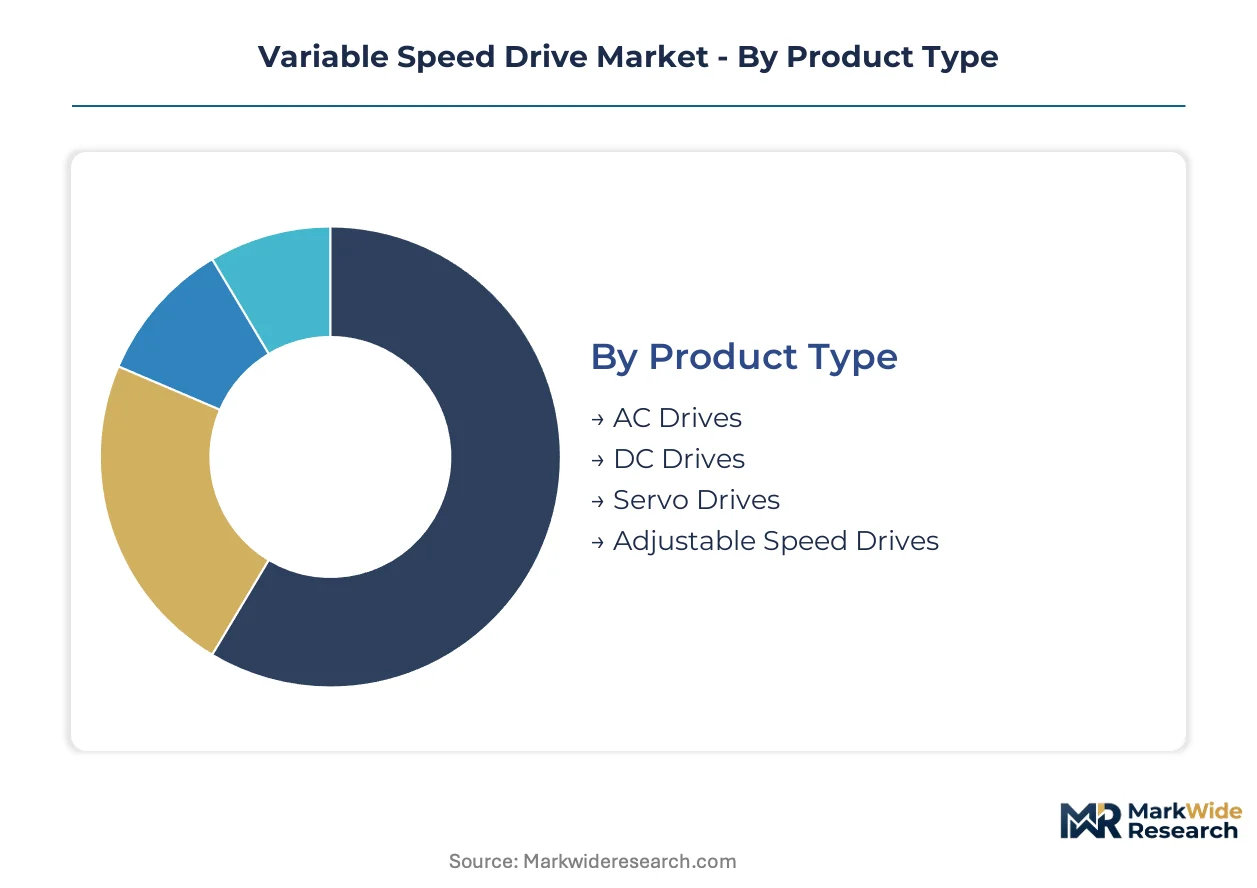
Variable speed drive segmentation reveals divergent service contract economics across hardware categories. Aftermarket revenue intensity varies sharply by product architecture and installation environment, reshaping how suppliers configure their commercial organizations.
Product Type:
After-sales service intensity peaks in segments where firmware complexity and thermal stress create recurring diagnostic needs.
- AC Drives:These units modulate frequency and voltage for standard induction motors across 0.4 kW to 2 MW ranges. Demand clusters in Chinese manufacturing clusters where GB 18613 efficiency mandates are forcing retrofit cycles in textile and food processing plants.
- Servo Drives:Precision motion control systems deploy vector control algorithms for sub-millisecond torque response in robotic assembly. German automotive suppliers and South Korean semiconductor fabs are driving specification intensity around embedded vibration monitoring.
- DC Drives:Legacy architectures persist in crane and hoist applications requiring sustained torque at zero speed.
- Adjustable Speed Drives:Mechanical configurations using eddy current clutches or hydraulic couplings retain niche positions in mining conveyors.
By volume, AC Drives leads. By growth pace, Servo Drives is expanding most quickly.
Technology:
Cost tier stratification separates premium wide-bandgap architectures from commodity IGBT platforms.
- VFD:Variable frequency drives dominate retrofit installations by interfacing with existing motor windings without mechanical modification. Water treatment facilities in California and Texas are specifying these units to meet federal infrastructure funding compliance requirements.
- Vector Control:Field-oriented control algorithms enable precise torque management in winding and extrusion operations. Japanese machine tool builders are embedding these drives directly into spindle assemblies.
- Direct Online:Across-the-line starting remains prevalent in low-duty-cycle applications where energy recovery does not justify drive investment.
- Soft Starters:Reduced-voltage starting limits mechanical stress in pumps and compressors without full variable speed capability.
By installed base, VFD dominates. By specification momentum, Vector Control is gaining share fastest.
End User:
Application-specific duty cycles determine warranty exposure and spare parts forecasting accuracy.
- Manufacturing:Continuous process industries generate the highest service contract attachment rates due to downtime cost sensitivity. EU Ecodesign Directive enforcement is mandating drive pairings for motors above 0.75 kW in packaging and material handling operations.
- HVAC:Commercial building automation creates seasonal load patterns that stress thermal management systems. Energy-as-a-service contracting is displacing capital procurement in US federal building retrofits.
- Water Treatment:Municipal pumping stations and aeration basins require corrosion-resistant enclosures and predictive maintenance integration.
- Automotive:Battery electrode coating lines demand silicon carbide switching for precision tension control in winding operations.
By revenue concentration, Manufacturing leads. By procurement model transformation, HVAC shows the steepest trajectory shift.
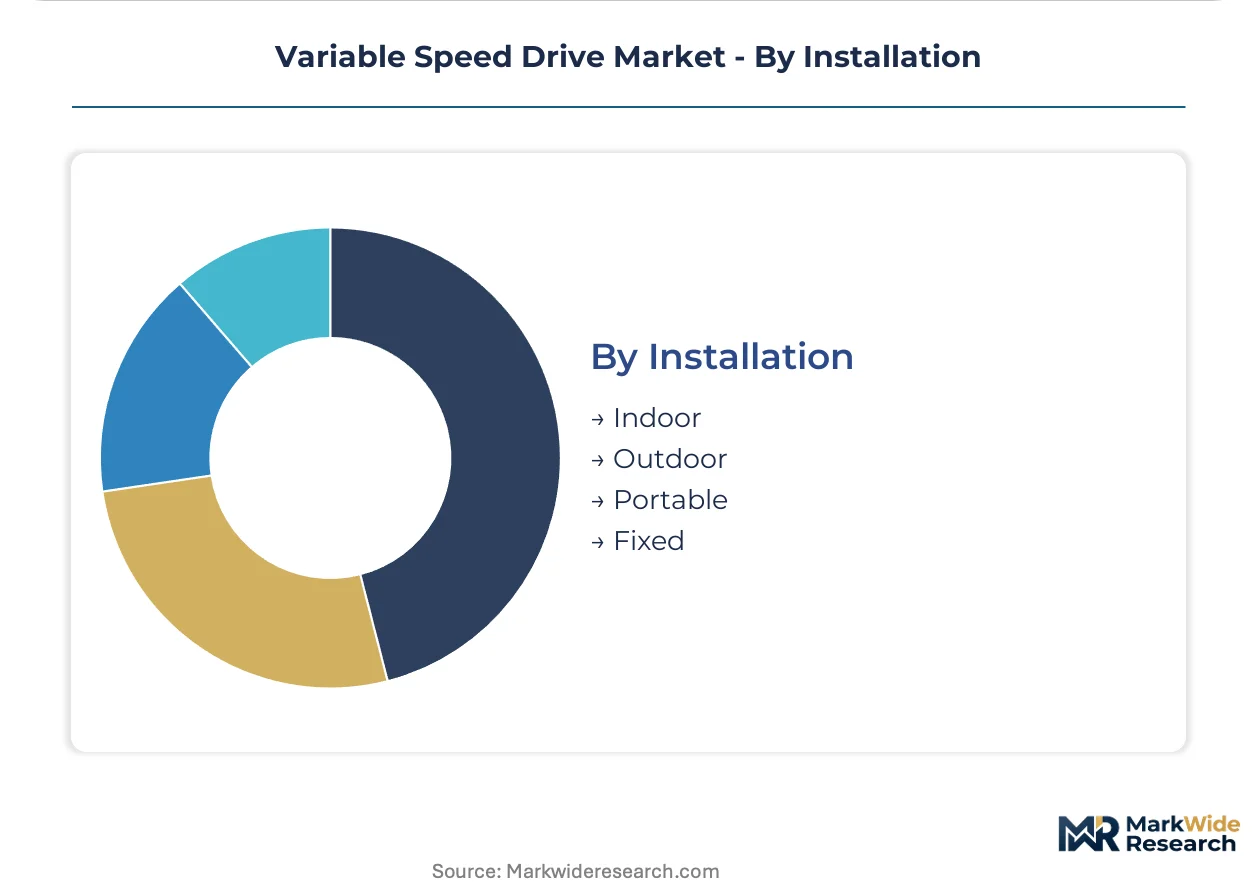
Installation:
Environmental exposure severity drives enclosure specification divergence and field service mobilization costs.
- Indoor:Climate-controlled electrical rooms enable standard IP20 enclosures with natural convection cooling. German automotive plants and Japanese electronics factories represent specification intensity centers.
- Outdoor:NEMA 4X and IP66 ratings protect against moisture ingress in wastewater treatment basins and offshore platforms. Coastal installations in Florida and the North Sea impose accelerated corrosion testing protocols.
- Portable:Mobile drive carts serve construction and mining applications requiring rapid redeployment between excavation sites.
- Fixed:Permanent mounting dominates industrial process integration where vibration isolation and conduit sealing are engineered to specification.
By shipment volume, Indoor leads. By specification premium expansion, Outdoor is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive suppliers prioritize precision motion control, while Chinese textile manufacturers optimize for retrofit cost efficiency. Municipal water utilities in Texas and California drive specification intensity around federal compliance.
China
Industrial electrification programs and state-mandated energy efficiency targets are accelerating replacement cycles. SAMR enforces GB 18613 efficiency grades that mandate drive pairings for motors above specified thresholds. Manufacturing clusters in Jiangsu and Zhejiang provinces are retrofitting textile and food processing facilities with variable frequency drives to meet export compliance requirements.
Germany
Automotive suppliers and machine tool builders demand sub-millisecond torque response for robotic assembly lines. The EU Ecodesign Directive mandates IE3 efficiency tiers for motors above 0.75 kW, compelling drive adoption across packaging operations. Industrial concentration in Baden-Württemberg and Bavaria anchors specification leadership for vector control systems in winding and extrusion applications.
United States
Federal infrastructure funding flows require certified equipment in water treatment facilities. The Department of Energy enforces 10 CFR 431 minimum energy performance standards that disqualify non-compliant motors from procurement channels. California and Texas municipalities are experiencing acute procurement pressure for pumping station retrofits.
Japan
Semiconductor fabrication and machine tool manufacturing drive demand for precision motion control. METI efficiency guidelines align with international standards while supporting domestic technology competitiveness. Nagoya and Osaka industrial corridors concentrate specification intensity for embedded vibration monitoring in spindle assemblies.
India
Small and medium manufacturing enterprises are creating first-time drive demand as BIS efficiency labeling expands. CEA regulations and state-level industrial electrification programs are triggering adoption in previously underserved sectors. Gujarat and Maharashtra manufacturing clusters are retrofitting pumping and material handling systems to reduce energy intensity.
Variable Speed Drive Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market exhibits tiered structure where premium technology developers compete separately from volume manufacturers serving retrofit applications. Strategic archetypes include integrated automation platform providers, power electronics specialists, and energy management software layers. Dominant competitive moves encompass digital twin integration for lifecycle extension and silicon carbide technology transitions for thermal performance differentiation.
Within the integrated automation tier, ABB Ltd. and Siemens AG exemplify platform-centric positioning that locks in recurring service revenue through installed base leverage. Schneider Electric SE occupies a distinct position anchoring energy management differentiation. Yaskawa Electric Corporation represents precision motion specialization serving robotic assembly and semiconductor fabrication requirements.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation, Inc. |
| Danfoss A/S |
| Yaskawa Electric Corporation |
| Mitsubishi Electric Corporation |
| Eaton Corporation plc |
| Hitachi, Ltd. |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam maritime corridor shapes cost dynamics across variable speed drive markets, compressing margins for European distributors while amplifying price differentiation between silicon carbide-enabled premium tiers and legacy IGBT platforms. Supply concentration in East Asian power module fabrication feeds directly into procurement cost structures for water treatment and automotive end-users.
Pricing Analysis
Long-term offtake contracts dominate procurement for municipal water infrastructure projects, insulating buyers from spot volatility in copper and rare earth magnet inputs. Price differentiation rests on efficiency certification tiers and embedded predictive maintenance capabilities, with EU Ecodesign IE3 compliance commanding substantial premiums. Cost compression in standard AC drive segments intensifies as Chinese manufacturers scale output for GB 18613 retrofit cycles. Small and medium manufacturing enterprises in India exhibit the highest price sensitivity, while German automotive suppliers prioritize torque response precision over unit economics.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk assessment for power electronics procurement. Silicon carbide substrate fabrication concentrates in Japan, the United States, and Germany, while IGBT module assembly draws heavily from Chinese and South Korean facilities. Raw material dependencies span copper busbars, rare earth permanent magnets, and epoxy molding compounds. Single-source vulnerability persists for 6-inch silicon carbide wafers. Distribution runs through authorized industrial automation distributors and direct OEM channels serving pulp and paper, automotive, and municipal utility verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering proficiency represents the critical capability gap constraining product development timelines and service contract profitability across the variable speed drive landscape.
For Market Incumbents: Insulate installed base revenue by embedding digital twin capabilities that extend hardware lifecycles and lock in platform stickiness against emerging silicon carbide specialists. Deepen backward integration into wide-bandgap semiconductor sourcing to mitigate substrate shortage exposure. Prioritize certification investment for EU Ecodesign IE4 readiness ahead of anticipated tier escalation. For New Entrants and Emerging Players: Establish a beachhead in India's small and medium manufacturing enterprise segment where BIS efficiency labeling creates first-time demand without entrenched incumbent relationships. Target portable drive configurations for construction and mining applications underserved by fixed-installation specialists. Pursue energy-as-a-service contracting models that displace capital expenditure procurement in commercial HVAC retrofits. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized drive divisions lacking predictive maintenance software layers. Long-term viability hinges on differentiation through embedded edge analytics rather than commodity hardware scale. Monitor silicon carbide MOSFET cost curve inflection as the signal for technology transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Transition | Enables switching frequencies above 16 kHz with reduced thermal losses for automotive battery manufacturing lines. |
| Digital Twin Integration | Extends hardware lifecycles through physics-based modeling fused with real-time operational data from pulp and paper facilities. |
| Predictive Maintenance Convergence | Opens recurring revenue streams beyond hardware sales via embedded vibration analysis and edge computing capabilities. |
| Energy-as-a-Service Models | Displaces capital expenditure procurement in US federal building retrofits through performance contracting structures. |
| Backward Integration into Power Semiconductors | Secures captive supply of wide-bandgap devices against silicon carbide substrate fabrication capacity constraints. |
Methodological Framework
The analysis maps AC drive, servo drive, and DC drive sub-sectors, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and municipal utility maintenance directors. Primary fieldwork combined with secondary validation from SEC filings, customs trade data, and EU Ecodesign regulatory databases supports bottom-up and top-down triangulation. Stakeholder interviews spanned maintenance directors at water treatment facilities, automation platform engineers, and power electronics procurement leads.
Assumptions around silicon carbide adoption velocity and efficiency regulation enforcement timelines were held fixed across baseline scenarios while varying replacement cycle intensity and municipal infrastructure funding flows. Segmentation dimensions modeled include product architecture, switching technology, end-use industry, and installation environment. CAGRs were derived from installed base turnover analysis and retrofit penetration curves. Forecast inputs incorporated SAMR enforcement patterns for GB 18613 and Federal infrastructure funding disbursement trajectories.
Sensitivities concentrate around silicon carbide substrate supply expansion and EU Ecodesign tier escalation schedules. Forecasts reflect documented assumptions regarding industrial electrification program continuity and rare earth magnet price stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
AC Motor Market
Industrial Motors
Power Stacker Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market