
 Submersible Pump Motor Market | 2026-2036
Submersible Pump Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Submersible Pump Motor Market Analytics
Municipal water management is decoupling from traditional agriculture-centric demand patterns across major economies. Grundfos Holding A/S leverages its integrated digital monitoring platforms to anchor premium positioning in smart water networks. Xylem Inc. competes through specialized dewatering solutions for mining and construction verticals, while KSB SE & Co. KGaA dominates large-scale flood control installations with its extended high-voltage motor range.
A submersible pump motor is a hermetically sealed electric drive unit designed to operate while fully immersed in fluid, typically constructed with corrosion-resistant stainless steel housings and oil-filled chambers to isolate windings from pumped media. Its primary industrial purpose is to convert electrical energy into mechanical rotation for fluid movement in borewells, sumps, and pressurized water systems where surface-mounted equipment proves impractical. Three-phase configurations lead the product type landscape due to superior thermal performance and continuous-duty ratings in deep-well extraction, while the above 10 HP power rating segment captures concentrated margin pools from heavy industrial dewatering and large-diameter irrigation projects. Direct current variants are gaining structural traction in off-grid solar pumping arrays across rural electrification corridors.
The U.S. Department of Energy enforces minimum efficiency standards under 10 CFR 431 that disqualify older single-phase designs from interstate commerce, while the EU Ecodesign Directive and associated CE marking requirements mandate IE3 premium efficiency classifications for motors above 0.75 kW. India's Bureau of Energy Efficiency Star Labeling program creates procurement gatekeeping for agricultural subsidy eligibility, directly shaping manufacturer product portfolios. Stakeholders must monitor evolving carbon border adjustment mechanisms and embedded energy disclosure rules that will soon determine competitive access across integrated water infrastructure supply chains.
Market Dynamics
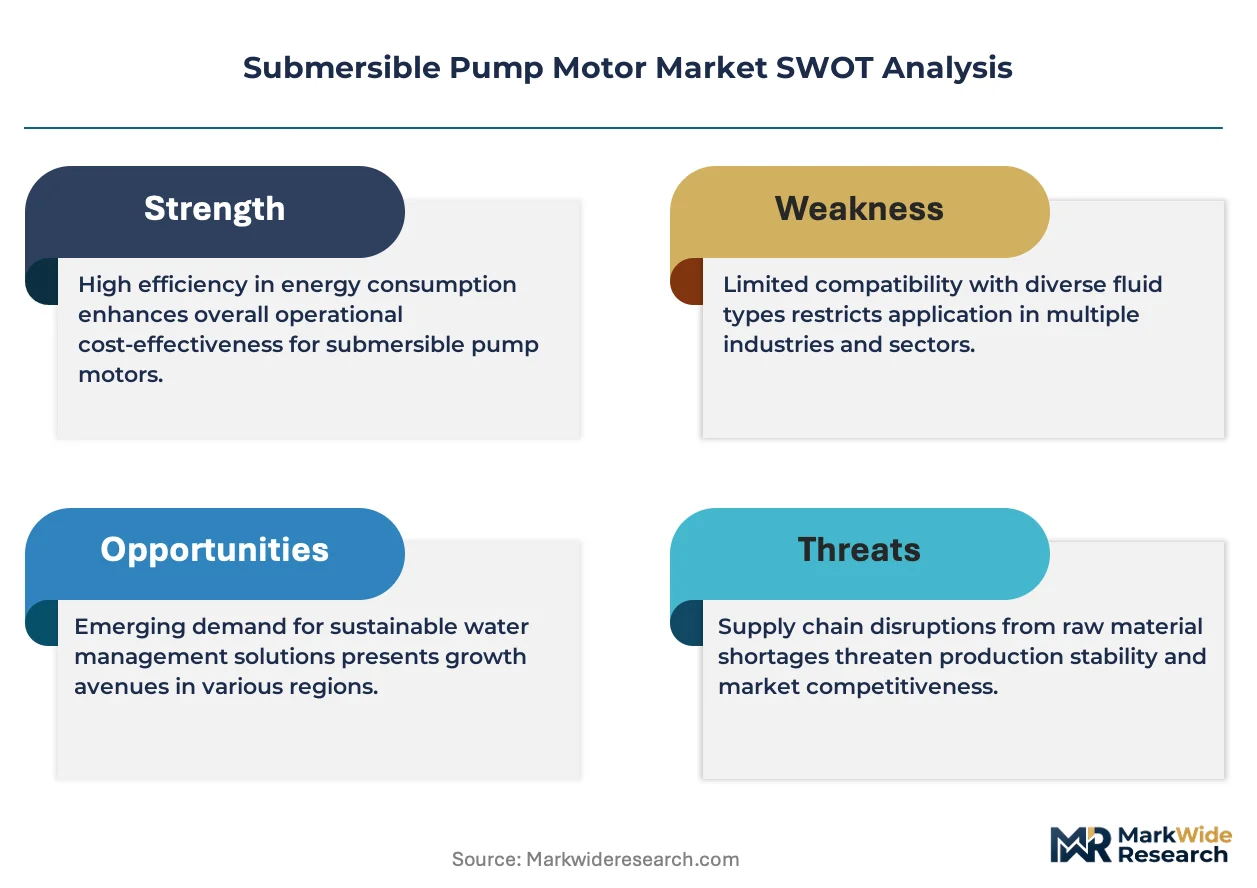
IE3 efficiency mandates under the EU Ecodesign Directive and comparable U.S. Department of Energy standards are compressing the addressable market for legacy single-phase designs while forcing manufacturers to absorb premium magnet costs and redesign thermal management systems.
Growth Catalysts
- Federal irrigation subsidies:India's Bureau of Energy Efficiency Star Labeling program ties agricultural equipment procurement to efficiency tiers, expanding the installed base of three-phase borewell units in water-stressed districts.
- EU Ecodesign Directive:Minimum efficiency performance standards above 0.75 kW are disqualifying older induction motor designs from CE-marked commerce, accelerating replacement cycles in municipal wastewater infrastructure.
- Permanent magnet synchronous motors:NdFeB magnet integration is enabling higher power density in sub-10 HP segments, reducing winding losses for continuous-duty deep-well extraction.
Market Restraints
- Rare earth price volatility:Neodymium and dysprosium supply concentration in Chinese processing facilities creates input cost instability for premium efficiency motor lines.
- Technical limitation — hermetic sealing:Oil-filled chamber integrity failures in high-sand-content groundwater environments limit service life warranties in Middle Eastern and North African installations.
- Substitution threat:Surface-mounted solar pumping systems with above-ground motor drives are capturing shallow-well agricultural applications below 50 meters depth.
Strategic Opportunities
- Off-grid solar corridors:Direct current submersible variants are penetrating rural electrification zones in sub-Saharan Africa and South Asia where grid extension remains uneconomical.
- Smart water networks:Integrated vibration and temperature sensors with IoT telemetry enable predictive maintenance contracts in Danish and Singaporean municipal utilities.
- Carbon border adjustment mechanisms:Embedded energy disclosure requirements under developing EU CBAM rules will reward manufacturers with low-carbon steel sourcing and regional assembly.
Industry Challenges
- Specialized winding expertise:Vacuum pressure impregnation technicians for high-voltage submersible coils are scarce in Southeast Asian manufacturing hubs, constraining capacity expansion.
- Certification timeline compression:Concurrent UL, CSA, and IECEx approval pathways for explosion-proof mining applications extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submersible Pump Motor Market |
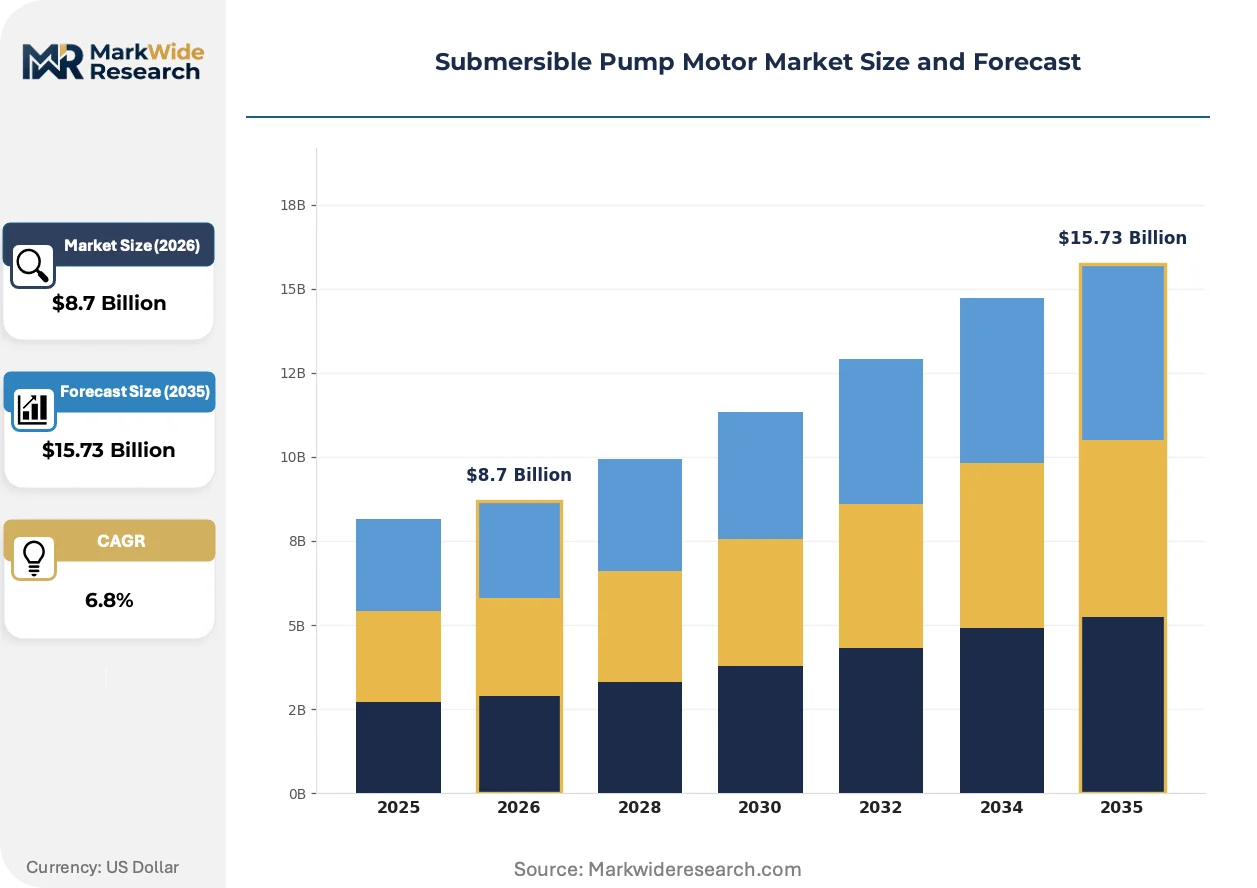
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-phase, Three-phase, Direct Current, Submersible Pumps End User: Agriculture, Industrial, Municipal, Construction Power Rating: Up to 1 HP, 1-5 HP, 5-10 HP, Above 10 HP Application: Groundwater Extraction, Flood Control, Wastewater Management, Irrigation |
| Companies Covered | Grundfos Holding A/S, Xylem Inc., KSB SE & Co. KGaA, Atlas Copco AB, Sulzer Ltd, EBARA Corporation, Franklin Electric, Kubota Corporation, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submersible Pump Motor Market Evolving Landscape
Digitalization of fluid management infrastructure is collapsing the distinction between hardware procurement and ongoing operational service, embedding connectivity as a standard feature rather than a premium upsell.
Permanent magnet synchronous motor technology is decentralizing power distribution architecture in deep-well extraction systems. These motors eliminate rotor slip losses through electronically commutated magnetic fields. Mining operators in Western Australia and Chilean copper districts are retrofitting existing boreholes with variable-frequency drive-matched PMSMs to cut energy intensity. The technology is decentralizing maintenance responsibility from centralized utility fleets toward equipment-integrated diagnostic platforms that flag bearing wear before catastrophic failure.
The EU Ecodesign Directive's 2023 expansion to motors below 0.75 kW is forcing redesign of fractional horsepower residential sump pumps. Manufacturers must now achieve IE2 minimums in single-phase designs previously exempt from efficiency tiers. Italian and Polish pump assemblers are responding by discontinuing shaded-pole motor platforms and transitioning to capacitor-run induction designs with copper rotor bars, compressing margins in the residential replacement market.
Lifecycle contracting is displacing transactional equipment sales in municipal water utilities. Danish and Dutch operators now specify total cost of ownership guarantees spanning 15-20 years, bundling energy performance bonds with hardware supply. Channel intermediaries in these markets are consolidating toward full-service water management integrators capable of underwriting operational risk, marginalizing traditional distributors without in-house hydraulic engineering capabilities.
Submersible Pump Motor Market Segmentation
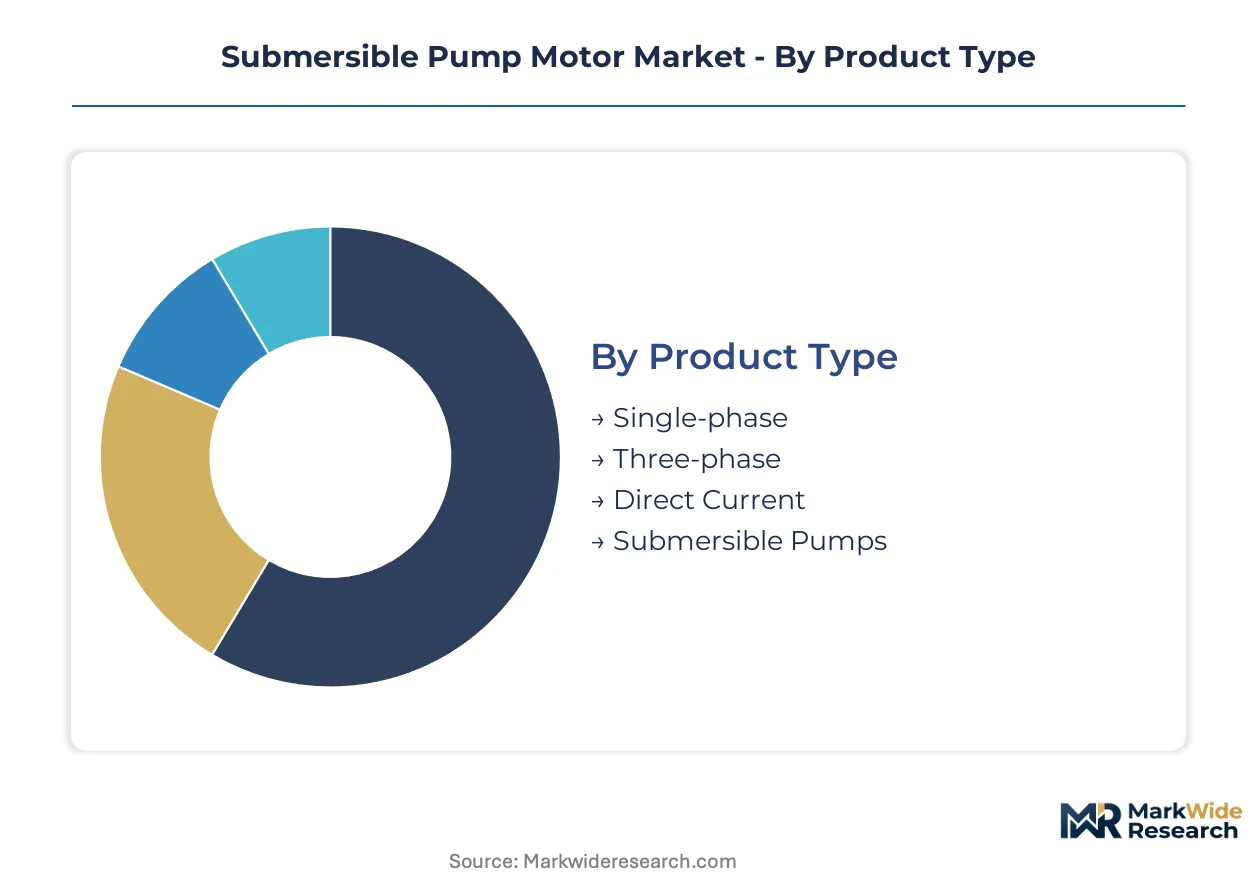
Submersible pump motor procurement hinges on matching electrical characteristics to duty cycles and immersion depth. Buyers weigh efficiency mandates against capital constraints while balancing thermal performance against grid availability.
Product Type:
Power delivery architecture determines thermal limits, starting torque, and compatibility with variable-frequency drives in deep-well installations.
- Three-phase:These motors deploy delta-wound stators with Class F insulation systems rated for continuous duty at depths exceeding 150 meters. Municipal utilities in Denmark and Singapore specify three-phase units for smart water network integration where predictive maintenance contracts require 20-year service life guarantees.
- Direct Current:Brushless permanent magnet designs with integrated MPPT controllers eliminate slip losses and enable direct solar array coupling. Rural electrification corridors in sub-Saharan Africa and South Asia favor DC variants where grid extension costs exceed distributed generation economics by factors of three to five.
- Single-phase:Capacitor-start induction designs dominate residential sump and light agricultural duty below 2 HP where three-phase infrastructure is unavailable.
- Submersible Pumps:Integrated motor-pump assemblies with canned stator construction reduce installation complexity for borewell retrofits in India's groundwater-depleted districts.
Volume sits with three-phase configurations; growth tilts toward direct current variants.
End User:
Capital intensity and operational risk tolerance separate buyer segments across the value chain.
- Municipal:Public utilities specify IE3 efficiency minimums and demand lifecycle cost guarantees spanning 15-20 years. Dutch water authorities bundle energy performance bonds with hardware procurement, displacing transactional distributors toward full-service integrators.
- Agriculture:India's Bureau of Energy Efficiency Star Labeling program ties federal irrigation subsidies to efficiency tiers, concentrating demand for three-phase borewell units in water-stressed Maharashtra and Gujarat districts where groundwater depletion exceeds recharge rates by 200%.
- Industrial:Mining operators in Western Australia and Chile retrofit existing boreholes with PMSMs to cut energy intensity in dewatering applications.
- Construction:Temporary dewatering projects favor rental fleets with rapid deployment specifications over capital purchases.
Revenue concentrates in municipal procurement; margin expansion tracks industrial retrofits.
Power Rating:
Horsepower thresholds align with impeller diameter, flow rate requirements, and cable sizing constraints in deep-well geometry.
- Above 10 HP:High-voltage wound stators with vacuum pressure impregnation withstand thermal cycling in flood control installations. KSB SE dominates large-diameter irrigation and drainage projects where NPSH requirements exceed 50 meters.
- 5-10 HP:Copper rotor bar designs with die-cast aluminum end rings balance efficiency against magnet cost volatility in mid-scale agricultural abstraction.
- 1-5 HP:Fractional horsepower segments face margin compression as EU Ecodesign Directive expansion to motors below 0.75 kW forces redesign of previously exempt single-phase platforms.
- Up to 1 HP:Shaded-pole motor discontinuation accelerates transition to capacitor-run induction designs in residential sump applications.
Unit volume clusters below 5 HP; value capture concentrates above 10 HP.
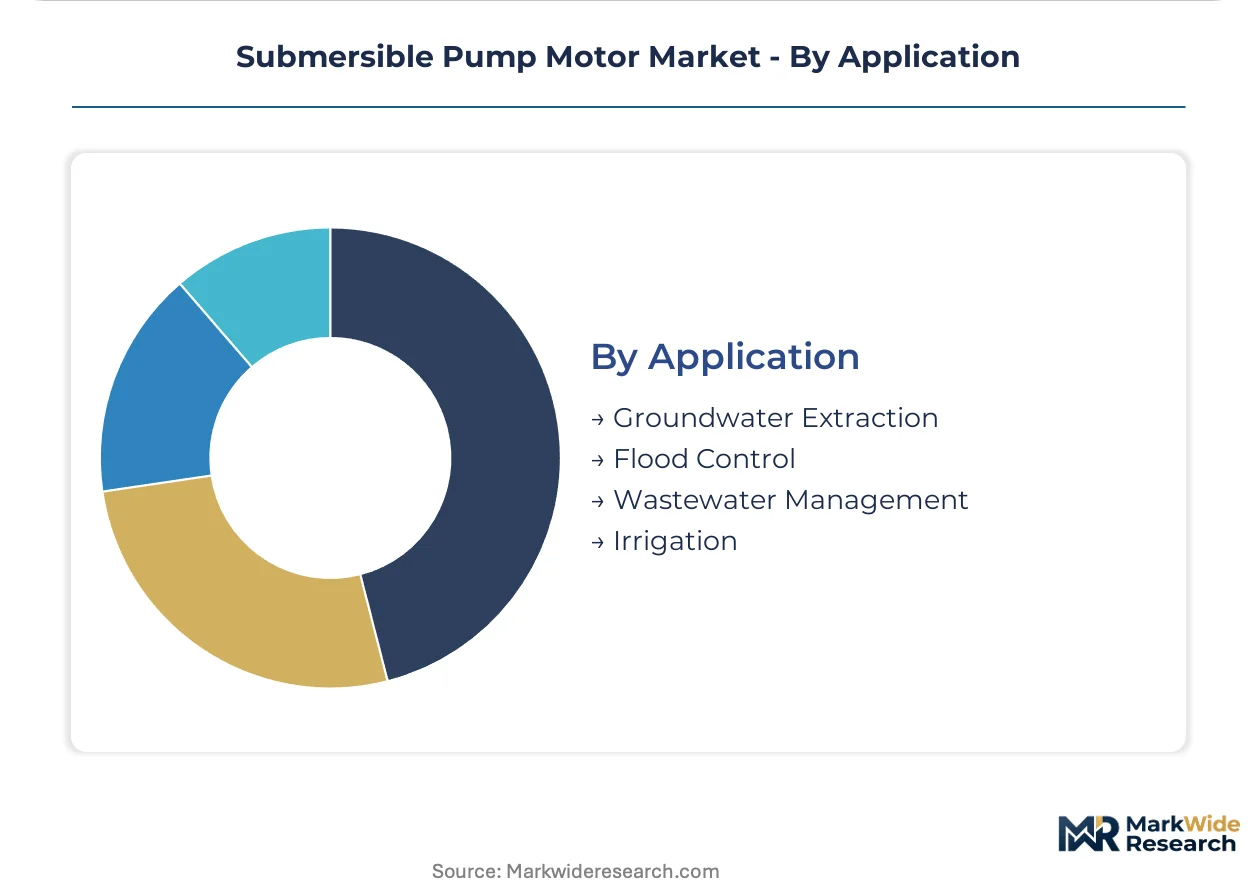
Application:
Hydraulic duty points and fluid characteristics dictate material selection and sealing architecture.
- Groundwater Extraction:Stainless steel 316L housings with tungsten carbide mechanical seals resist sand abrasion in Middle Eastern aquifers where suspended solids exceed 500 ppm. Hermetic sealing failures in high-sand environments limit warranty terms in Saudi and UAE installations.
- Wastewater Management:Vortex impeller designs with chopper mechanisms handle solids passage in municipal sewage networks. Southeast Asian infrastructure upgrades accelerate procurement of grinder pumps with integrated level controls.
- Irrigation:Center-pivot and drip system compatibility requires pressure-rated delivery at variable flow rates across undulating terrain.
- Flood Control:Portable submersible dewatering units with automatic thermal cutouts serve emergency deployment in coastal storm surge zones.
Installed base dominates groundwater extraction; technology refresh centers on wastewater management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Petroleum, Chemicals and Petrochemicals Investment Regions and China's coastal special economic zones concentrate submersible pump motor assembly capacity through tax-advantaged export processing. These zones attract winding equipment suppliers and magnet processors seeking duty-free component flows.
United States
Municipal wastewater infrastructure upgrades across the Great Lakes region and California's groundwater sustainability mandates drive three-phase unit procurement. The Department of Energy enforces 10 CFR 431 efficiency standards that disqualify legacy single-phase designs from interstate commerce. Chicago's metropolitan water reclamation district anchors smart network deployments with predictive maintenance specifications.
India
Federal irrigation subsidies through the Bureau of Energy Efficiency Star Labeling program expand three-phase borewell pump installations in water-stressed Maharashtra and Gujarat districts. Groundwater depletion exceeding recharge rates by 200% accelerates replacement cycles. Coimbatore's pump manufacturing cluster integrates permanent magnet synchronous motor production for agricultural duty.
Germany
The EU Ecodesign Directive's IE3 minimum efficiency standards above 0.75 kW force redesign of fractional horsepower residential platforms. Municipal utilities in North Rhine-Westphalia specify 15-20 year lifecycle cost guarantees with energy performance bonds. Dortmund's industrial automation corridor hosts winding equipment specialists serving mid-voltage submersible coil production.
China
Rare earth processing concentration in Jiangxi and Inner Mongolia supplies NdFeB magnet inputs for premium efficiency motor lines despite price volatility. The dual carbon goals policy framework tightens embedded energy disclosure requirements for export-bound equipment. Shanghai's Yangshan free-trade zone facilitates re-export assembly for Southeast Asian infrastructure projects.
Brazil
Center-pivot irrigation expansion in Mato Grosso and Goiás soybean belts drives demand for corrosion-resistant stainless steel housings. ANVISA-equivalent efficiency labeling for agricultural equipment creates procurement gatekeeping for subsidy eligibility. São Paulo state's industrial machinery district hosts distributors integrating Brazilian assembly with imported wound stators.
Submersible Pump Motor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated digital platform providers commanding premium positioning in municipal smart water networks while regional assemblers capture agricultural replacement cycles through price-competitive three-phase units. The vendor base organizes around three archetypes: full-service water management integrators bundling lifecycle contracts, component specialists controlling magnet and winding supply, and rental fleet operators serving temporary construction dewatering. Dominant competitive moves include backward integration into permanent magnet processing to offset rare earth cost volatility, and strategic partnerships with solar array installers to anchor off-grid DC variant distribution.
Within the full-service integrator tier, Grundfos Holding A/S and Xylem Inc. exemplify platform-centric positioning through digitally-enabled predictive maintenance offerings. KSB SE & Co. KGaA anchors the high-voltage industrial segment with specialized flood control and mining dewatering expertise. Among Japanese precision manufacturers, EBARA Corporation occupies a position emphasizing corrosion-resistant material science for aggressive fluid environments. These named entities represent strategic archetypes rather than exhaustive market coverage, with each exemplifying distinct competitive vectors in efficiency compliance, connectivity integration, or application-specific durability.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Xylem Inc. |
| KSB SE & Co. KGaA |
| Atlas Copco AB |
| Sulzer Ltd |
| EBARA Corporation |
| Franklin Electric |
| Kubota Corporation |
| Flowserve Corporation |
| Others |
Value Network & Pricing Analysis
Captive magnet processing in Chinese rare earth facilities anchors both cost structures and pricing power for premium efficiency motor lines, forcing Western assemblers to absorb NdFeB price volatility or surrender margin to integrated competitors.
Pricing Analysis
Short lead-time premiums command substantial markups in municipal procurement cycles where infrastructure deadlines override capital constraints. Three-tier pricing structure across premium, standard, and economy levels separates IE3-certified three-phase units from legacy single-phase designs and unbranded agricultural replacements. Price differentiation hinges on certification tier and after-sales service bundling. Cost compression in fractional horsepower segments is intensifying because EU Ecodesign Directive expansion forces redesign of previously exempt residential platforms. Agricultural buyers in India exhibit highest price sensitivity, while Dutch municipal utilities prioritize lifecycle cost guarantees over unit economics.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai to Rotterdam and Los Angeles destabilizes landed costs for wound stator assemblies and canned motor housings. Manufacturing concentrates in China, India, and Germany, with Jiangxi rare earth processing and Coimbatore winding clusters feeding global assembly. Supply chains draw from NdFeB magnets, copper rotor bars, and 316L stainless steel castings. Single-source vulnerability in Chinese magnet processing creates input cost instability. Distribution runs through full-service water management integrators in Northern Europe and regional distributors in South Asian agricultural corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive control over permanent magnet supply chains separates margin leaders from price-takers in efficiency-mandated procurement.
For Market Incumbents: Acquire NdFeB magnet processing capacity to offset Chinese supply concentration and rare earth price volatility. Secure vacuum pressure impregnation technicians in Southeast Asian hubs to constrain competitor capacity expansion. Surface-mounted solar pumping systems threaten shallow-well agricultural share below 50 meters depth. For New Entrants and Emerging Players: Launch via solar installer partnerships to anchor off-grid DC variant distribution in sub-Saharan African rural electrification corridors. Target Brazilian center-pivot irrigation retrofit cycles where ANVISA-equivalent efficiency labeling creates subsidy-gated procurement windows. White-space sits in predictive maintenance platform integration for mid-sized municipal utilities lacking in-house hydraulic engineering. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-centric water management integrators bundling 15-20 year lifecycle contracts. Long-term viability favors full-service operators with embedded IoT telemetry and energy performance bond underwriting capabilities. Watch carbon border adjustment mechanism implementation timing as inflection indicator for low-carbon steel sourcing advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Captive NdFeB supply insulates against Chinese processing concentration and price volatility. |
| Predictive Maintenance Platform Launch | Danish and Singaporean municipal utilities now specify IoT-enabled service contracts. |
| Solar Installer Partnership Network | Direct coupling with off-grid arrays penetrates sub-Saharan African rural electrification corridors. |
| Vacuum Pressure Impregnation Capacity Buildout | Scarce technician pools in Southeast Asia constrain competitor expansion. |
| Low-Carbon Steel Sourcing Certification | EU CBAM embedded energy disclosure rules will reward regional assembly advantages. |
Research Methodology
Multi-period observation of municipal procurement cycles, rare earth price indices, and agricultural subsidy disbursement rates anchored the trend analysis, supplemented by interviews with plant engineers at water reclamation districts, OEM procurement teams at pump manufacturers, aftermarket service heads, and distribution channel partners. Secondary validation drew from Bureau of Energy Efficiency Star Labeling databases, EU Ecodesign Directive compliance registries, SEC 10-K filings, and customs trade data. Bottom-up unit shipment estimates triangulated against top-down value projections.
Input-output matrices mapped power rating segments to end-use applications and regional regulatory clusters across the analysis window. Segmentation dimensions modeled include product type, power rating tier, end-use vertical, and geographic efficiency mandate compliance. CAGRs derived from regression analysis of historical replacement cycles and subsidy program scaling. Forecast inputs incorporated groundwater depletion rates in Indian agricultural districts and EU carbon border adjustment mechanism development trajectories.
Rare earth supply disruptions, municipal budget austerity cycles, and solar pumping substitution acceleration are the dominant revision risks to installed base projections. Forecasts reflect documented assumptions about subsidy continuity and efficiency mandate enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Nuclear Polar Crane Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Asia-Pacific Induction Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
China AC Motor Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
North America Induction Motor Market