
 Global Explosion-Proof Motor Casting Market | 2026-2036
Global Explosion-Proof Motor Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Explosion-Proof Motor Casting Market Analysis
IECEx equipment certification is collapsing from a twelve-month cycle to under six months for qualified foundries, tightening the vendor pool for explosion-proof motor castings. ABB Ltd leverages integrated foundry-to-assembly operations across European hazardous-duty hubs. Siemens AG anchors its casting supply through captive facilities in Germany and China. WEG competes on cost-optimized aluminum enclosure production for Latin American oilfield operators.
Explosion-proof motor casting refers to the production of metal housings engineered to contain internal ignition and withstand specified hydrostatic pressure tests, typically cast from aluminum alloys or ductile iron with minimum wall thicknesses governed by flame-path geometry. These enclosures isolate electrical components from explosive atmospheres in Zone 1 and Zone 2 environments. AC motor castings dominate volume demand across oil and gas installations where continuous-duty ratings prevail. Aluminum material grades are capturing share from cast iron in offshore and chemical processing applications where weight reduction drives total installed cost. Fixed installation castings generate the steadiest replacement demand, while portable configurations serve turnaround and maintenance cycles in refineries.
ATEX Directive 2014/34/EU and IECEx 02 certification govern market access across European and international hazardous-duty procurement channels, with OSHA 29 CFR 1910.146 confined space rules shaping US demand patterns for certified equipment. China's GB 3836 series aligns domestic explosion-protection standards with IEC frameworks, enabling local foundries to serve multinational EPC contractors. Stakeholders must monitor divergence between regional certification reciprocity agreements and emerging carbon-border adjustments affecting aluminum casting supply chains.
Market Dynamics
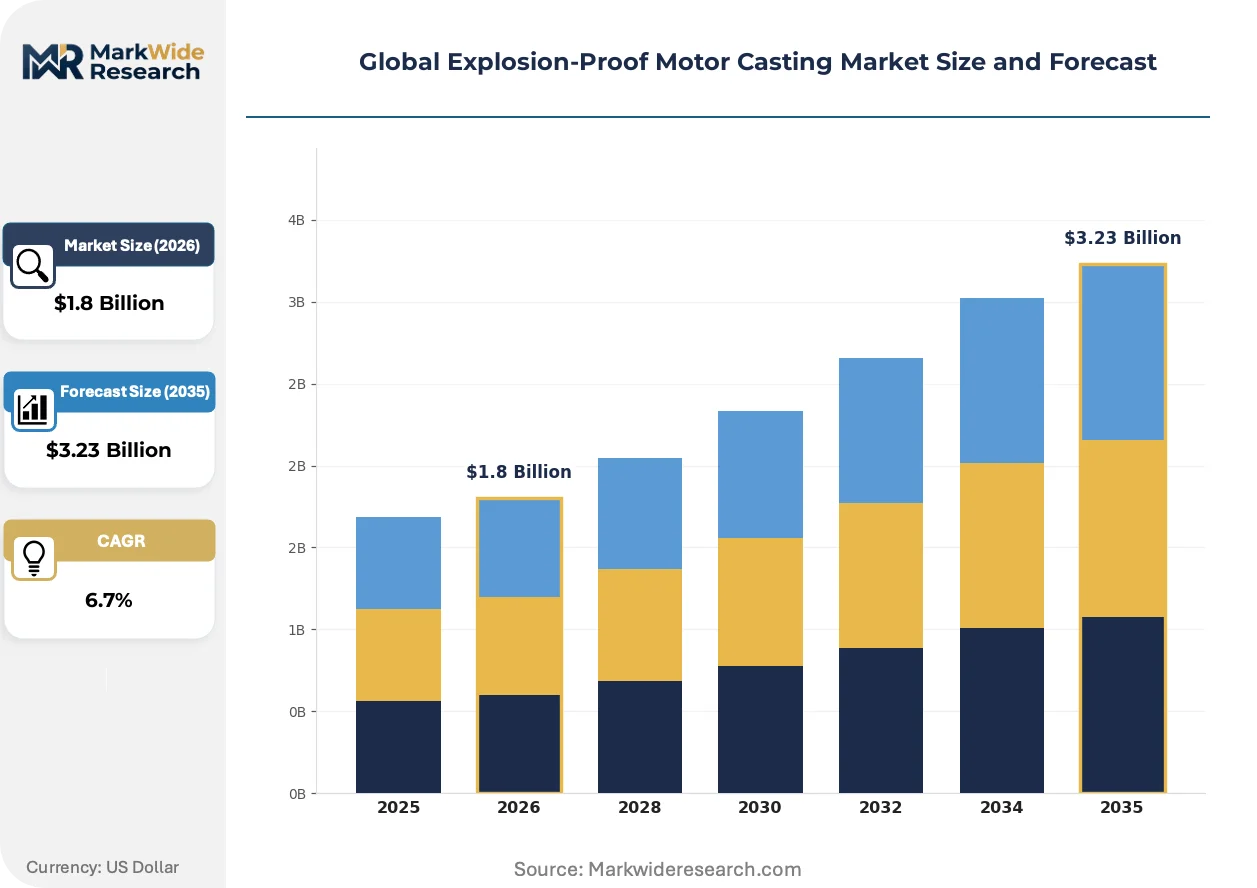
Certification timeline compression is the dominant structural force reshaping competitive access in explosion-proof motor castings, as IECEx scheme acceleration eliminates half-year qualification buffers and concentrates procurement among pre-qualified foundry networks.
Growth Catalysts
- ATEX Directive 2014/34/EU:European petrochemical operators face mandatory equipment recertification cycles that accelerate replacement demand for flame-path-compliant cast enclosures.
- Aluminum alloy substitution:Offshore platform operators in the North Sea and Gulf of Mexico specify aluminum motor housings to reduce topside weight and installation crane requirements.
- China petrochemical buildouts:Domestic foundries in Ningbo and Wuxi upgrade GB 3836 series compliance to capture multinational EPC contractor sourcing.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings compress foundry margin buffers and complicate long-term enclosure pricing agreements.
- European foundry concentration:IECEx-qualified casting capacity clusters in Germany and Italy, creating single-source vulnerability for ATEX-certified procurement.
- Cast iron residual demand:Heavy-duty mining operators in Australia and South Africa continue specifying ductile iron housings for impact resistance, limiting aluminum penetration in underground applications.
Strategic Opportunities
- India refining expansion:Reliance Industries and Indian Oil Corporation greenfield projects create first-mover advantage for IECEx-certified suppliers establishing local foundry partnerships.
- Hydrogen electrolyzer integration:Zone 1-rated cast enclosures for electrolyzer balance-of-plant motors represent emerging demand from green hydrogen projects in Saudi Arabia and the UAE.
- Carbon border adjustment mechanism:EU CBAM implementation incentivizes low-carbon aluminum casting sourcing, rewarding foundries with renewable energy supply.
Industry Challenges
- IECEx 02 audit compression:Six-month certification cycles strain foundry quality documentation systems and accelerate auditor resource scarcity.
- Flame-path machining precision:Tighter tolerance requirements for IEC/EN 60079-1 gap dimensions demand capital investment in CNC finishing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Explosion-Proof Motor Casting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Motor, DC Motor, Servo Motor, Stepper Motor Material: Aluminum, Stainless Steel, Cast Iron, Composite Industry Vertical: Oil & Gas, Chemical Processing, Mining, Wastewater Treatment Installation Type: Fixed, Portable, Mounted, Temporary |
| Companies Covered | ABB Ltd, Siemens AG, Eaton Corporation, Rockwell Automation, Honeywell International, Toshiba Corporation, WEG, Emerson Electric, Pepperl+Fuchs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Explosion-Proof Motor Casting Market Emerging Trajectories
Digital foundry process control and additive manufacturing integration are compressing prototype-to-production cycles for complex flame-path geometries, while regulatory carbon accounting penetrates casting supply chain qualification criteria.
Additive-manufactured sand printing for explosion-proof motor casting cores is fragmenting traditional pattern-making economics. Siemens AG and ABB Ltd pilot suppliers now iterate flame-path geometries in weeks rather than months. This capability is fragmenting the historical advantage of high-volume foundries with dedicated pattern libraries, enabling smaller qualified shops to compete on custom enclosure designs.
EU Carbon Border Adjustment Mechanism transitional reporting requirements are reshaping aluminum casting procurement specifications. Importers must document embedded emissions from 2026, pressuring foundries to secure renewable electricity contracts. German automotive and chemical OEMs now pre-qualify casting suppliers based on Scope 1 and 2 carbon intensity thresholds ahead of full CBAM implementation.
Buyer consolidation among international oil companies is compressing vendor approval cycles and unbundling aftermarket service contracts. BP and Shell now mandate single-source accountability for motor-assembly-to-casting traceability. This pattern concentrates procurement leverage with integrated foundry-to-finish suppliers capable of IECEx quality documentation across the full manufacturing chain.
Global Explosion-Proof Motor Casting Market Segmentation
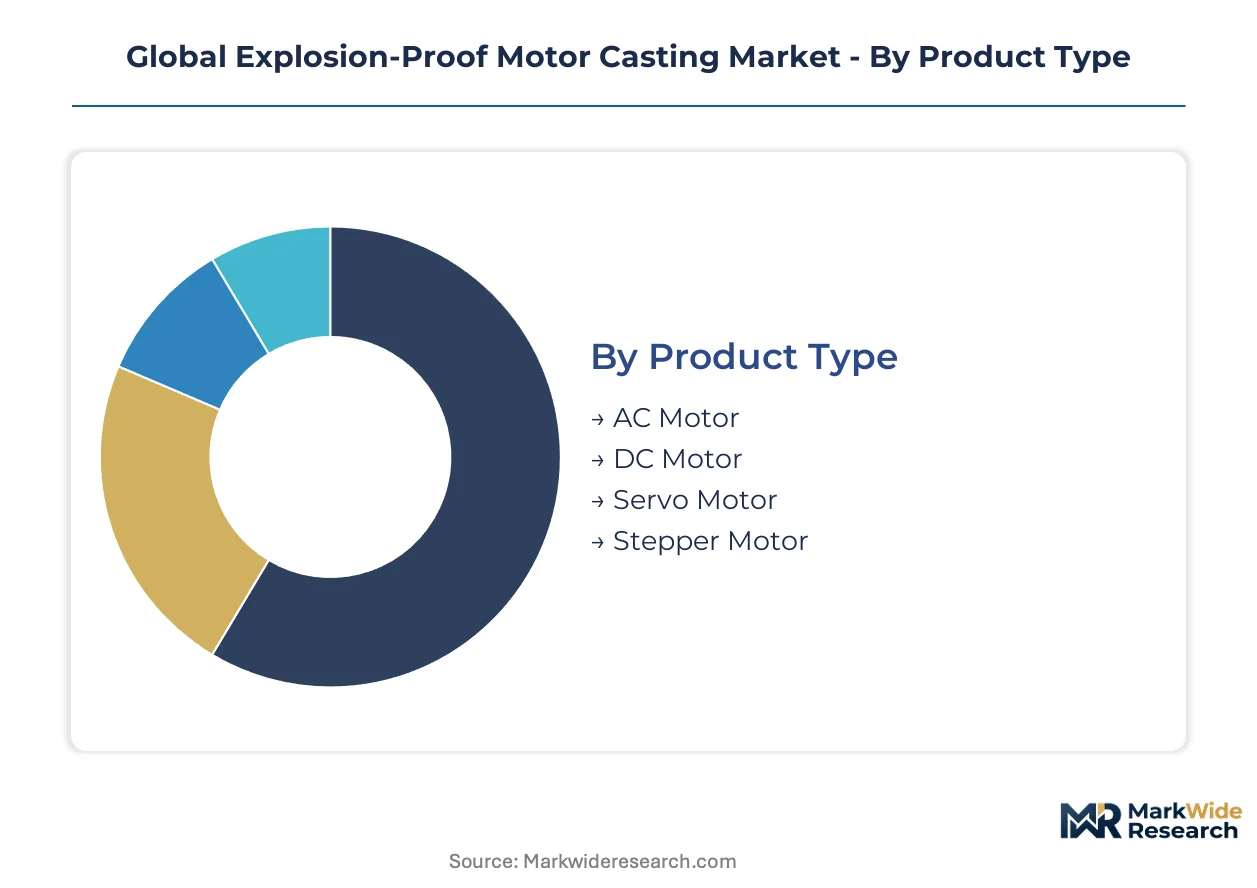
Explosion-proof motor casting procurement channels diverge sharply by product complexity and certification burden. Material selection and installation configuration determine whether castings flow through integrated OEM supply chains or independent foundry networks serving maintenance channels.
Product Type:
Channel mix splits between integrated motor OEM captive supply for high-volume AC and DC platforms versus independent foundry sourcing for specialized motion control applications.
- AC Motor:Three-phase induction motor castings constitute the highest-volume production category with standardized IEC frame sizes from 63 to 355. Oil and gas operators in the Permian Basin and North Sea specify these for continuous-duty pump and compressor drives where ATEX Zone 1 certification is mandatory.
- DC Motor:Commutator motor enclosures require more complex terminal box geometries and brush-gear isolation chambers. Mining haulage systems in South Africa and Australia specify DC castings for trolley locomotive traction where variable speed control dominates.
- Servo Motor:Precision-positioning castings with integrated encoder mounting interfaces serve chemical processing batch control systems.
- Stepper Motor:Fractional-horsepower enclosures for valve automation and conveyor indexing in refineries.
AC motor castings dominate installed base. Servo motor configurations are where expansion concentrates as process automation intensifies.
Material:
Cost tier stratification separates premium aluminum solutions from economy cast iron alternatives, with stainless steel commanding niche corrosion-resistant positioning.
- Aluminum:LM6 and LM25 alloy grades deliver the strength-to-weight ratio critical for offshore platform crane-limited installations. Gulf of Mexico operators specify aluminum motor housings to reduce topside structural loading and simplify maintenance handling.
- Cast Iron:EN-GJS-400-15 ductile iron retains dominance in underground mining where impact resistance and electromagnetic shielding outweigh weight penalties. Australian longwall operations continue specifying iron castings for shearer loader motors.
- Stainless Steel:CF8M austenitic grades for coastal petrochemical exposure and aggressive chemical washdown environments.
- Composite:Glass-reinforced polymer enclosures emerging for temporary Zone 2 portable applications where weight minimization is paramount.
Cast iron retains volume leadership in heavy-duty extraction. Aluminum is climbing the fastest as offshore and chemical processing operators prioritize installation economics.
Industry Vertical:
Customer type concentration varies by capital cycle timing and safety regulation enforcement intensity across hazardous-duty sectors.
- Oil & Gas:Upstream exploration and downstream refining generate the most stringent flame-path requirements with IECEx 02 certification mandatory for subsea and Arctic applications. Saudi Aramco and ADNOC procurement specifications now require foundry-level carbon disclosure.
- Chemical Processing:Batch pharmaceutical and specialty chemical operations drive demand for servo-compatible castings with CIP/SIP washdown resistance.
- Mining:Underground coal and hard-rock extraction specify reinforced ductile iron housings for continuous miner and longwall systems.
- Wastewater Treatment:Biogas recovery and anaerobic digester applications represent emerging Zone 1 specification territory for blower and pump motors.
Oil and gas commands premium pricing tiers. Wastewater treatment is gaining share fastest as biogas infrastructure expands.
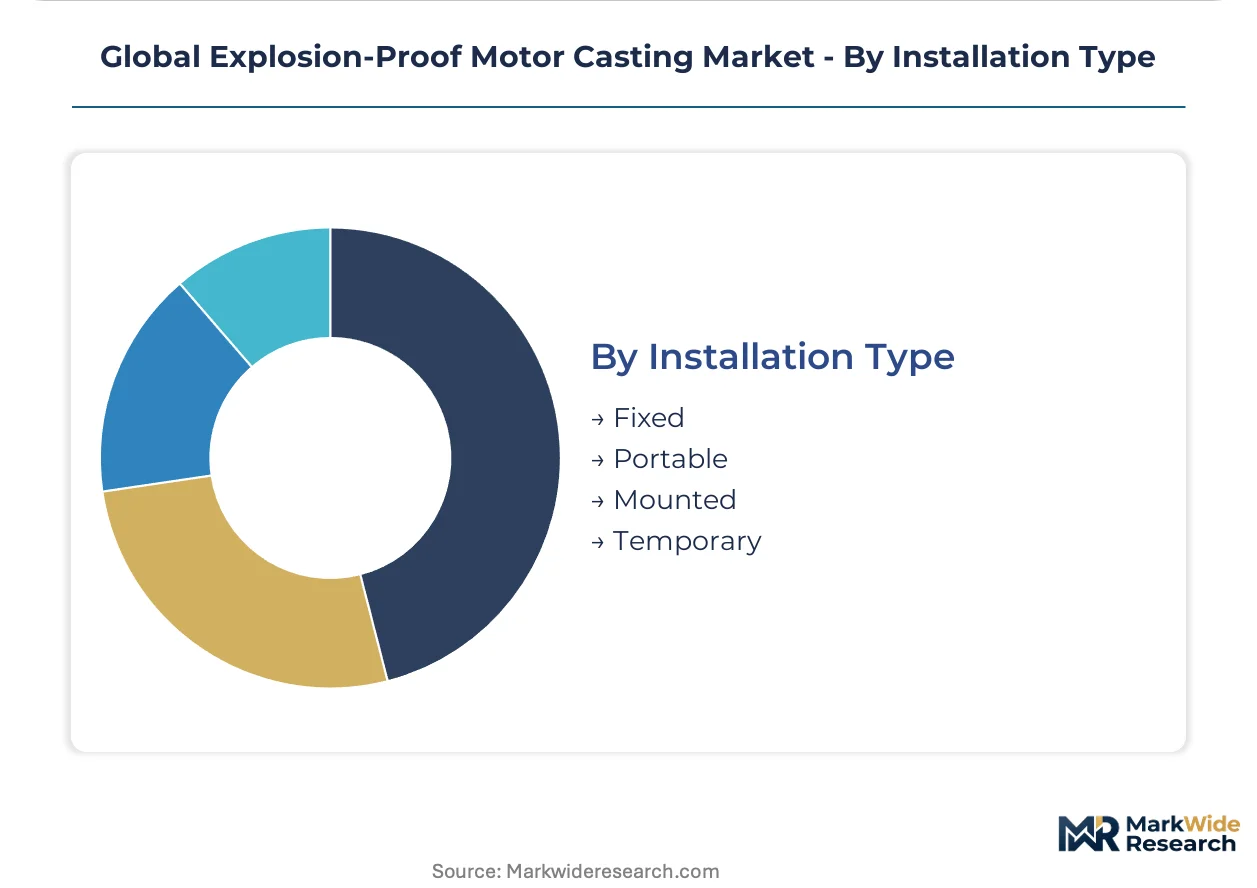
Installation Type:
Supply concentration patterns separate long-lead fixed infrastructure from spot-market temporary and portable replacement demand.
- Fixed:Permanent foundation-mounted castings for process-critical pumps, compressors, and fans generate predictable replacement cycles tied to turnaround schedules. European refineries in Rotterdam and Antwerp maintain ATEX-certified spare casting inventories.
- Portable:Skid-mounted and dolly-configured enclosures serve maintenance turnarounds and emergency replacement in refineries.
- Mounted:Flange and foot-mounted standardized frames for OEM motor assembly lines.
- Temporary:Rental fleet castings for construction and commissioning phases with reduced certification documentation.
Fixed installation castings anchor revenue stability. Portable configurations are expanding most quickly as turnaround intensity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Carbon Border Adjustment Mechanism transitional rules are redirecting aluminum casting procurement toward low-carbon foundries in Germany and renewable-energy-backed suppliers in China. IECEx certification acceleration is compressing vendor qualification timelines across hazardous-duty procurement channels.
China
Domestic petrochemical buildouts in Ningbo and Wuxi are driving foundry upgrades to GB 3836 series compliance. MIIT dual carbon goals pressure aluminum smelters to secure renewable power purchase agreements. Yangtze River Delta foundry clusters now supply multinational EPC contractors with IECEx-certified enclosures for Middle East refinery projects.
Germany
ATEX Directive 2014/34/EU mandatory recertification cycles accelerate replacement demand for flame-path-compliant castings. KBA and federal environmental regulators enforce strict emissions documentation for aluminum casting supply chains. North Rhine-Westphalia and Bavaria host the densest concentration of IECEx-qualified foundry capacity in Europe.
United States
OSHA 29 CFR 1910.146 confined space rules shape demand patterns for certified equipment in Gulf Coast refineries. Permian Basin operators specify Zone 1-rated motor housings for continuous-duty pump drives. Houston and Beaumont industrial corridors maintain spare casting inventories tied to turnaround schedules.
Saudi Arabia
Green hydrogen electrolyzer projects in NEOM and Jubail Industrial City generate emerging demand for Zone 1-rated cast enclosures. SFDA and SASO alignment with IECEx frameworks streamlines import qualification for balance-of-plant motors. Eastern Province smelter expansions target low-carbon aluminum output for European CBAM compliance.
India
Reliance Industries and Indian Oil Corporation greenfield refining projects create first-mover opportunities for IECEx-certified suppliers. CEA electrical safety mandates tighten equipment specifications for hazardous-area installations. Gujarat and Maharashtra industrial zones attract foundry joint ventures to serve domestic petrochemical capacity expansion.
Global Explosion-Proof Motor Casting Market Vendor Landscape
Player mix skews toward integrated electrical OEMs with captive foundry operations and independent specialized casting houses serving aftermarket channels. Market structure concentrates procurement leverage among pre-qualified suppliers capable of end-to-end IECEx quality documentation. Two strategic archetypes dominate: vertically integrated motor manufacturers controlling enclosure supply chains, and certification-focused foundries competing on flame-path machining precision. Competitive moves center on foundry-to-assembly traceability investments and renewable energy sourcing for aluminum casting carbon disclosure.
Within the integrated OEM tier, ABB Ltd and Siemens AG exemplify archetypes with European hazardous-duty hub networks and captive casting supply in Germany and China. WEG occupies a position among cost-optimized aluminum enclosure specialists serving Latin American oilfield procurement. These anchors represent the spectrum from premium certified supply to volume-driven regional competition.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| Eaton Corporation |
| Rockwell Automation |
| Honeywell International |
| Toshiba Corporation |
| WEG |
| Emerson Electric |
| Pepperl+Fuchs |
| Others |
Supply Flow & Price Mechanics
Aluminum alloy substitution for ductile iron in offshore motor housings redraws procurement geography toward Chinese and German foundries while compressing margin structures for legacy cast iron suppliers locked into long-term fixed-price contracts.
Pricing Analysis
Cost-plus contracts indexed to LME aluminum spot prices dominate enclosure procurement, with three-tier pricing structure across premium, standard, and economy levels differentiated by IECEx certification grade and flame-path machining precision. Pricing pressure stems from primary aluminum volatility that erodes foundry margin buffers on fixed-price legacy agreements. Large EPC contractors exhibit lowest price sensitivity due to total installed cost focus, while independent maintenance distributors face acute margin compression.
Supply Chain Analysis
Strategic stockpiling of ATEX-certified castings prevails among European refineries, contrasting with just-in-time aluminum procurement favored by Gulf of Mexico operators with crane-limited platforms. Supply concentrates in Germany, Italy, and China's Yangtze River Delta. Raw material flows draw from primary aluminum smelters in Saudi Arabia's Eastern Province and hydro-powered Chinese producers. Single-source vulnerability clusters around IECEx-qualified machining capacity in Bavaria. Distribution runs through integrated OEM captive networks and independent foundry aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Explosion-Proof Motor Casting Market sits at an inflection where IECEx certification acceleration and EU Carbon Border Adjustment Mechanism reporting converge to reward pre-qualified, low-carbon suppliers.
For Market Incumbents: Secure captive renewable energy contracts for aluminum smelting to meet EU CBAM embedded emissions documentation requirements. Deepen backward integration into flame-path CNC machining capacity to compress six-month IECEx audit cycles and defend against emerging Chinese foundries with GB 3836 compliance upgrades.
For New Entrants and Emerging Players: Lead with hydrogen electrolyzer balance-of-plant motor castings in Saudi Arabia and UAE green hydrogen projects, where Zone 1 certification demand outpaces established supply. Target India's Gujarat refining corridor through joint ventures with domestic foundries serving Reliance Industries and Indian Oil Corporation greenfield expansions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with end-to-end IECEx traceability. Five-to-ten year viability hinges on carbon-disclosure capabilities and renewable energy sourcing. Watch for CBAM full implementation as the inflection signal that separates compliant from stranded casting assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CNC Machining | Captive flame-path finishing capacity compresses IECEx audit timelines below six months. |
| Renewable Energy Supply Contracting | Low-carbon aluminum sourcing satisfies EU CBAM embedded emissions documentation requirements. |
| Joint Venture with Indian Foundry | Local IECEx-certified production captures Reliance and Indian Oil Corporation refining expansion demand. |
| Hydrogen Electrolyzer Casting Development | Zone 1-rated enclosures for NEOM and Jubail projects open green hydrogen equipment channel. |
| Additive Manufacturing Core Printing | Sand printing capability fragments pattern-library economics and accelerates custom enclosure prototyping. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with foundry operations managers, EPC contractor procurement leads, OEM motor assembly engineers, and aftermarket distribution specialists; and secondary validation through IECEx certification registry data, ATEX notified body filings, customs aluminum trade records, and SEC filings from listed electrical equipment manufacturers. Bottom-up casting volume estimates triangulated against top-down petrochemical and mining capital expenditure projections.
Across the modeling period, the analytical framework segmented demand by motor type, material grade, industry vertical, and installation configuration, with CAGRs derived from regression against hazardous-duty equipment procurement cycles and regulatory recertification timelines. Forecast inputs incorporated aluminum price elasticity coefficients and IECEx audit capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained petrochemical investment in China and the Middle East, or accelerated CBAM implementation, would require recalibration. Forecasts reflect assumptions about certification reciprocity stability and primary aluminum supply continuity. Revision becomes warranted when LME aluminum volatility or IECEx auditor scarcity crosses thresholds that disrupt foundry qualification pipelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Induction Motors Market
Industrial Motors
Hydraulic Motors Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Oil Mist Collector Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
Food Grade Hydraulic Oil Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Global Switched Reluctance Motor Market