
 Oil and Gas Hose Assemblies Market | 2026-2036
Oil and Gas Hose Assemblies Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Hose Assemblies Market Analytics
Composite-to-thermoplastic material substitution is fragmenting the traditional rubber-dominated supply base for high-pressure service. Parker Hannifin Corporation leverages its integrated motion and control portfolio to anchor positions in subsea umbilical systems. Gates Corporation competes through specialized elastomer compounding capabilities that sustain temperature ratings above 150°C in sour gas environments. Continental AG differentiates via captive polymer research and vertical control over aramid reinforcement supply.
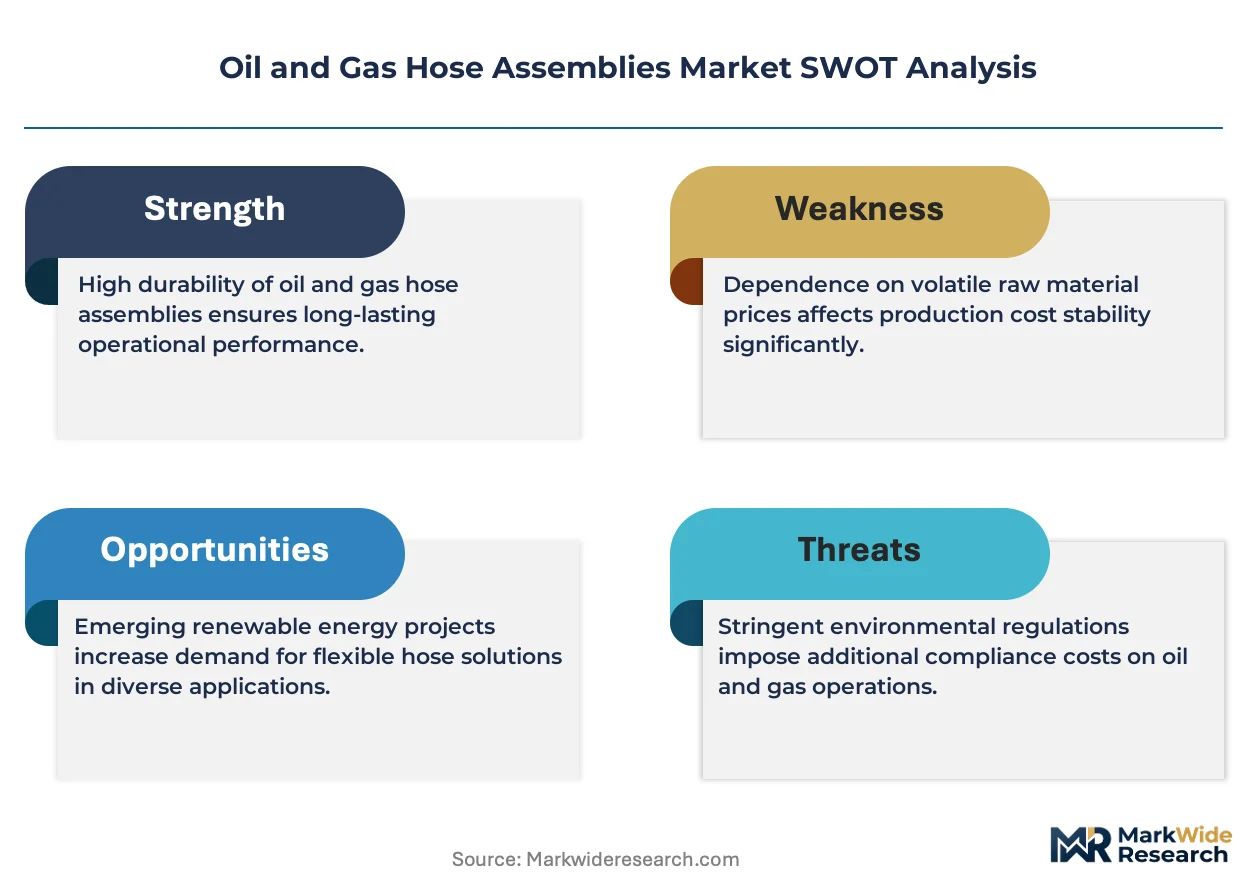
Oil and gas hose assemblies are engineered flexible pressure vessels, typically constructed from alternating layers of elastomeric barriers, textile or metallic reinforcement braids, and extruded thermoplastic jackets, designed to convey hydrocarbons, drilling muds, and production chemicals across pressure ratings from 5,000 to 15,000 psi in upstream and midstream operations. Fluid transfer hoses lead product type demand due to their ubiquity in hydraulic fracturing and well intervention, while composite materials represent the fastest-expanding material category as operators seek weight reduction and corrosion immunity for deepwater deployment. Downstream refining applications command premium margin pools because of stringent fire resistance and API certification requirements that limit supplier qualification.
API standards, ISO 13628-5 for subsea production systems, and OSHA Process Safety Management rules collectively dictate pressure testing protocols, material traceability, and replacement intervals that directly shape procurement budgets and vendor qualification timelines. The US Bureau of Safety and Environmental Enforcement enforces incident reporting that accelerates hose retirement cycles in offshore jurisdictions. Stakeholders must monitor the divergence between API qualification costs and operator willingness to specify uncertified alternatives in cost-constrained onshore shale plays.
Market Dynamics
Deepwater exploration economics are compressing replacement cycles for high-pressure hose assemblies as operators push equipment deeper and longer without dry-dock windows. API 7K certification timelines now gate project schedules more than material availability.
Growth Catalysts
- US Gulf Coast shale redevelopment:Hydraulic fracturing intensity drives continuous replacement of 10,000-15,000 psi fluid transfer hoses in Permian and Eagle Ford basins.
- ISO 13628-5 subsea qualification:Offshore operators in Brazil's pre-salt fields mandate certified composite umbilicals, expanding addressable market for qualified suppliers.
- Aramid reinforcement adoption:Weight reduction targets on floating production platforms accelerate specification of synthetic braid systems over traditional steel wire.
Market Restraints
- Specialty elastomer supply concentration:Hydrogenated nitrile butadiene rubber feedstock for sour gas service concentrates among three European compounders.
- API qualification cost escalation:Full 7K/16C certification cycles now exceed eighteen months, freezing new supplier entry.
- Thermoplastic substitution threat:Spoolable reinforced thermoplastic pipes capture land-based gathering line applications above 2,000 meters.
Strategic Opportunities
- West African offshore expansion:Senegal-Mauritania gas developments lack established local hose service infrastructure, creating first-mover positioning.
- OSHA Process Safety Management alignment:US refineries face mandated mechanical integrity program upgrades, expanding aftermarket inspection and replacement contracts.
- Digital twin integration:Sensor-embedded hose assemblies enabling predictive retirement scheduling command 40-60% service contract premiums.
Industry Challenges
- Composite NDT technician scarcity:Ultrasonic and radiographic inspection of filament-wound structures requires certifications held by fewer than 200 specialists globally.
- Legacy steel-braid inventory stranding:Operators holding pre-2018 API 7K certified stock face premature obsolescence as 2024 edition test protocols take effect.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Hose Assemblies Market |
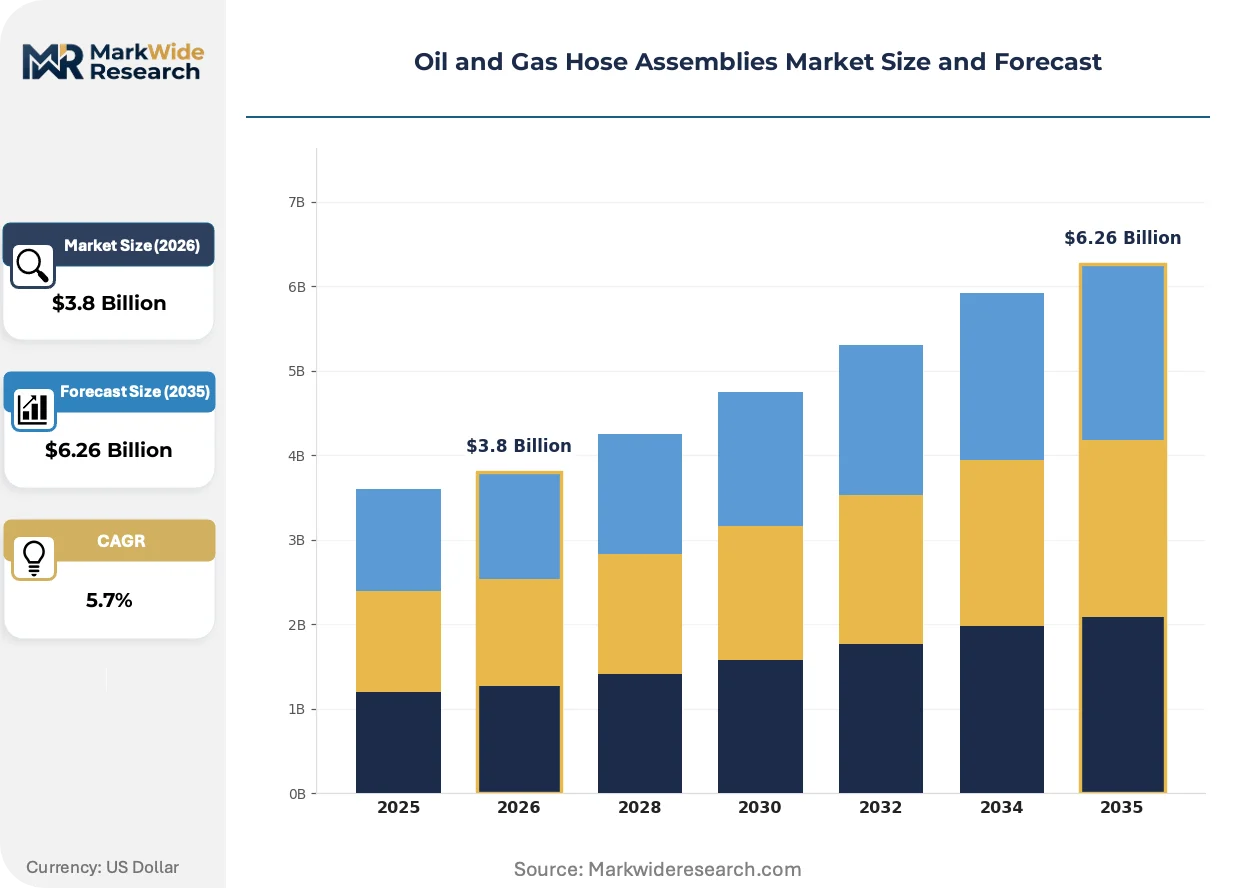
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid Transfer Hoses, Suction Hoses, Discharge Hoses, Industrial Hoses Application: Upstream Operations, Midstream Transportation, Downstream Refining, Exploration End User: Oilfield Services, Refining Companies, Distribution Firms, Energy Producers Material: Rubber, Composite, Thermoplastic, Steel |
| Companies Covered | Parker Hannifin Corporation, Gates Corporation, Continental AG, Eaton Corporation plc, ContiTech AG, TechnipFMC plc, Kuriyama of America, Inc., Alfa Gomma S.p.A., Gall Thomson Environmental Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Hose Assemblies Market Evolving Landscape
Material science advances and regulatory stringency are converging to redefine qualification benchmarks and procurement patterns across upstream and midstream operations.
Digital twin platforms are virtualizing condition monitoring for subsea production systems. Offshore operators in Norway's North Sea fields deploy fiber-optic strain sensing within composite hose walls to track fatigue accumulation in real time. This capability is virtualizing scheduled replacement with predictive retirement, compressing maintenance windows and reducing unplanned downtime exposure.
REACH substance restrictions on persistent organic pollutants are forcing reformulation of legacy fluoroelastomer barrier compounds. European compounders must phase out perfluorooctanoic acid-processed materials by 2025, triggering qualification runs for alternative barrier chemistries. Subsea umbilical manufacturers serving North Sea projects face the tightest compliance deadlines and highest retesting costs.
Integrated service contracting is displacing component-only procurement in US onshore shale plays. Pressure pumping contractors now bundle hose assemblies with inspection, recertification, and field repair under multi-year agreements. This shift concentrates purchasing authority among five national pressure pumping fleets and compresses margins for standalone hose distributors in Texas and Oklahoma.
Oil and Gas Hose Assemblies Market Segmentation
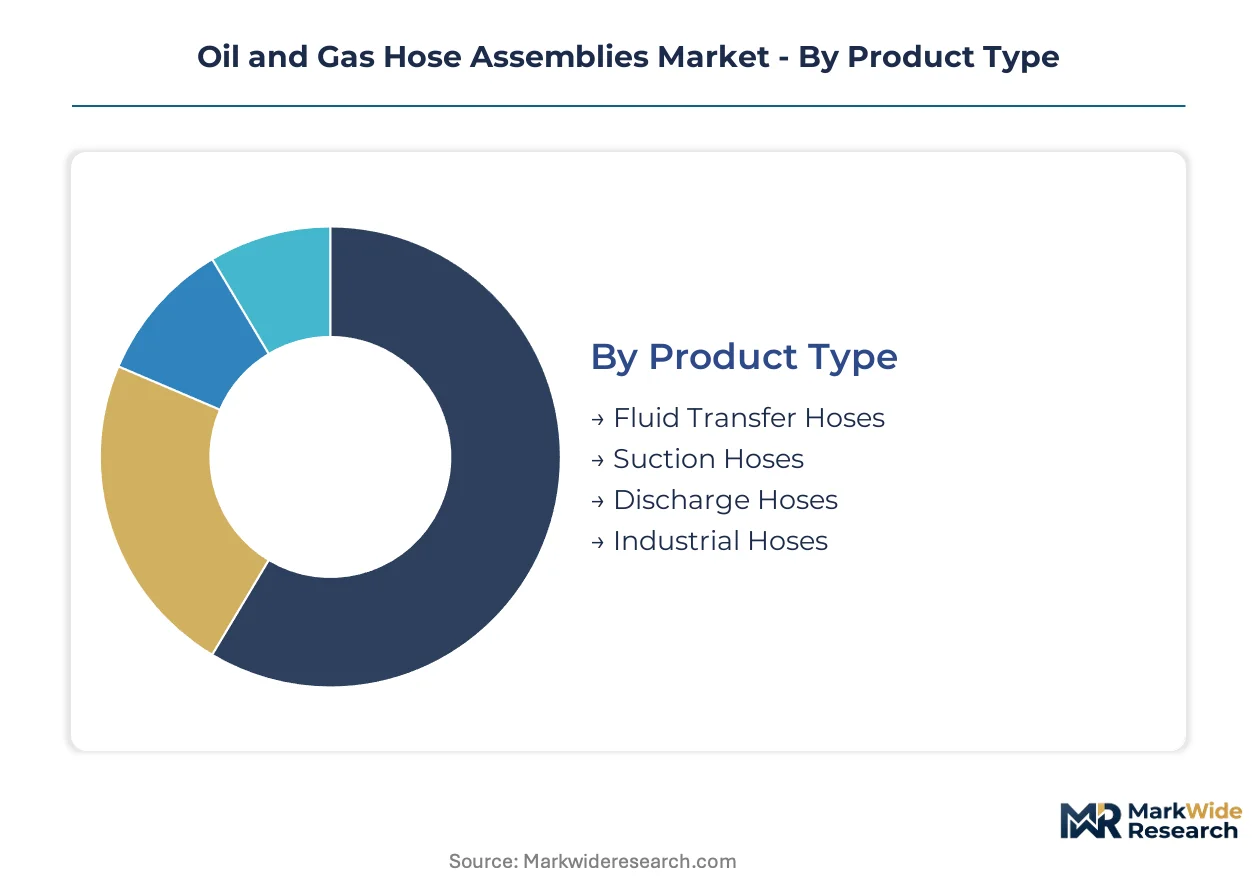
Segmentation in oil and gas hose assemblies determines aftermarket service intensity, replacement cycle predictability, and supplier qualification barriers. Each dimension—product construction, operational deployment, buyer type, and material composition—creates distinct margin pools and technical compliance requirements.
Product Type:
After-sales-service intensity varies sharply across product categories, with high-pressure rated assemblies demanding continuous inspection protocols and recertification scheduling.
- Fluid Transfer Hoses:Multi-layer elastomeric tubes reinforced with steel wire or aramid braids, rated for 10,000-15,000 psi in hydraulic fracturing operations. Demand concentrates in Permian Basin pressure pumping fleets where continuous duty cycles drive 90-day replacement intervals.
- Suction Hoses:Helix-wire reinforced constructions designed for negative pressure service in crude oil loading and tanker offloading. Brazilian pre-salt FPSO operators specify API 7K certified variants for dynamic riser connections, tightening vendor qualification timelines.
- Discharge Hoses:Heavy-wall constructions for positive pressure discharge in drilling mud circulation systems.
- Industrial Hoses:General-purpose configurations for auxiliary services including compressed air and water transfer in onshore facilities.
Fluid Transfer Hoses holds the largest share; momentum sits with Suction Hoses as deepwater suction riser specifications proliferate.
Application:
Cost tier stratification separates premium-certified offshore systems from commoditized onshore replacements, with certification overhead driving 3-4x price multiples.
- Upstream Operations:Exploration drilling, well completion, and production gathering systems requiring API 7K and 16C certification. US Gulf Coast shale redevelopment accelerates specification of 15,000 psi rated assemblies for extended-reach laterals.
- Midstream Transportation:Pipeline terminal loading, tanker transfer, and storage facility connectivity. Senegal-Mauritania gas export projects lack established hose service infrastructure, creating first-mover positioning for qualified suppliers.
- Downstream Refining:Process unit connectivity, tank farm transfer, and product loading operations.
- Exploration:Seismic vessel streamer deployment and subsea survey equipment umbilicals.
Upstream Operations commands the highest service contract attach rates; Downstream Refining generates the steadiest replacement revenue through OSHA-mandated mechanical integrity programs.
End User:
Customer type determines procurement centralization, with national pressure pumping fleets consolidating purchasing authority through integrated service contracting.
- Oilfield Services:Pressure pumping, well intervention, and drilling contractors operating on day-rate or per-stage contracts. Five national fleets in Texas and Oklahoma now bundle hose assemblies with inspection and field repair under multi-year agreements.
- Refining Companies:Integrated operators and independent refiners subject to OSHA Process Safety Management mechanical integrity mandates.
- Distribution Firms:Midstream logistics providers managing crude and product terminal networks.
- Energy Producers:E&P companies operating proprietary production infrastructure.
Oilfield Services concentrates the highest volume throughput; Refining Companies offers the most predictable aftermarket annuity streams.
Material:
Supply concentration in reinforcement fibers and specialty elastomers creates qualification bottlenecks that favor vertically integrated compounders.
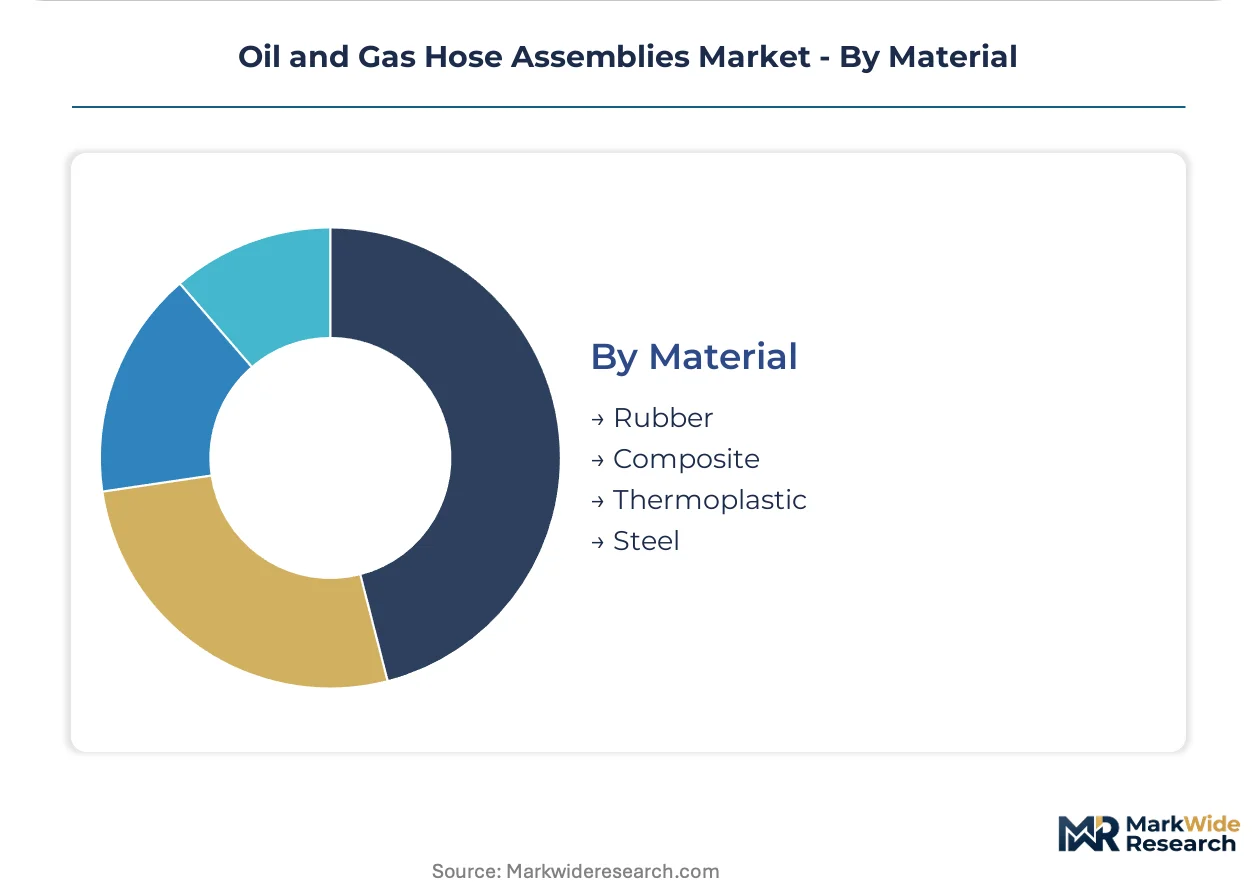
- Composite:Filament-wound aramid or carbon fiber reinforced thermoset constructions offering weight reduction and corrosion immunity. Floating production platform operators in Norway's North Sea fields specify composite umbilicals with embedded fiber-optic strain sensing.
- Rubber:Traditional nitrile, HNBR, and fluoroelastomer barrier compounds dominating legacy onshore applications. REACH substance restrictions on PFOA-processed materials force European compounders into costly reformulation cycles.
- Thermoplastic:Extruded nylon or PVDF jackets with textile reinforcement for chemical transfer service.
- Steel:Corrugated or interlocked metal hose constructions for extreme temperature and fire-resistant applications.
Rubber retains the largest installed base; Composite gains share fastest as deepwater weight reduction targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hose assembly fabricators supply pressure-rated systems to Brazil's pre-salt operators and West African LNG projects, establishing trans-Atlantic trade corridors for API-certified offshore equipment. This export flow concentrates manufacturing investment along the Gulf Coast while driving qualification standard harmonization across destination markets.
United States
Hydraulic fracturing intensity in the Permian Basin and Eagle Ford shale fields drives 90-day replacement cycles for 15,000 psi fluid transfer hoses. OSHA Process Safety Management rules mandate mechanical integrity programs that accelerate aftermarket service contracts in Texas and Oklahoma refining clusters. Houston anchors the nation's largest concentration of hose fabrication facilities serving both domestic pressure pumping fleets and export markets.
Brazil
Pre-salt field development off the Santos Basin coast mandates ISO 13628-5 certified composite umbilicals for floating production systems. The national petroleum regulator enforces local content requirements that pressure foreign suppliers to establish Brazilian assembly partnerships. Rio de Janeiro hosts the primary subsea equipment service hub supporting Petrobras-operated deepwater platforms.
Norway
North Sea platform operators specify aramid-reinforced composite hoses with embedded fiber-optic strain sensing for weight-critical floating installations. REACH substance restrictions on PFOA-processed fluoroelastomers force compound reformulation ahead of 2025 deadlines. Stavanger concentrates subsea umbilical engineering expertise serving Equinor and independent E&P operators.
Senegal and Mauritania
Greater Tortue Ahmeyim gas field development lacks established hose service infrastructure, creating positioning opportunities for qualified suppliers entering West African offshore markets. The national oil companies of both countries prioritize API-certified contractors for first-phase production systems. Dakar and Nouakchott serve as logistics coordination points for equipment staging.
Germany
Specialty elastomer compounding for sour gas service concentrates among Baden-Württemberg chemical suppliers serving global oilfield demand. ECHA enforcement of REACH persistent organic pollutant restrictions drives qualification costs for barrier material reformulation. Stuttgart anchors the European center for hydrogenated nitrile butadiene rubber production used in high-temperature hydrocarbon service.
Oil and Gas Hose Assemblies Market Competitive Landscape
On the supply side, the industry is consolidating around integrated motion-control conglomerates and specialized elastomer compounders with captive reinforcement supply. Three strategic archetypes dominate: diversified industrial conglomerates leveraging cross-divisional technology transfer, focused hose specialists defending positions through material science differentiation, and energy service contractors integrating hose procurement into bundled field service agreements. Competitive moves concentrate on vertical control over aramid fiber supply and API qualification capacity expansion to capture subsea project timelines.
Within the diversified industrial tier, Parker Hannifin Corporation and Eaton Corporation plc exemplify conglomerate-scale fabricators whose motion and control portfolios span multiple energy service applications. Gates Corporation occupies a position among specialized elastomer compounders with demonstrated high-temperature hydrocarbon service capabilities. Continental AG through its ContiTech AG division represents backward-integrated manufacturers controlling captive polymer research and reinforcement supply chains. These three anchors illustrate how qualification barriers and material concentration favor players with upstream control over critical feedstocks and certification infrastructure.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Gates Corporation |
| Continental AG |
| Eaton Corporation plc |
| ContiTech AG |
| TechnipFMC plc |
| Kuriyama of America, Inc. |
| Alfa Gomma S.p.A. |
| Gall Thomson Environmental Ltd. |
| Others |
Value Network & Pricing Analysis
Specialty elastomer compounding capacity in Germany and France concentrates upstream control over hydrogenated nitrile butadiene rubber feedstock, anchoring margin pools in sour gas service tiers where temperature ratings above 150°C command certification premiums. This geographic concentration of barrier material production directly shapes downstream pricing power for offshore umbilical assemblies.
Pricing Analysis
Next-generation composite hose systems with embedded fiber-optic strain sensing command substantial premiums over current-generation aramid-reinforced constructions and prior-generation steel-wire braid assemblies. Pricing stratifies across API 7K certified premium tiers, ISO 13628-5 qualified standard tiers, and uncertified economy tiers for onshore shale applications. Cost compression in economy tiers is intensifying because pressure pumping contractors consolidate purchasing authority through bundled service contracts. National pressure pumping fleets exhibit lowest price sensitivity due to uptime guarantees, while independent operators in Texas and Oklahoma remain most price-sensitive.
Supply Chain Analysis
Extended payment terms from 90 to 120 days now characterize supplier financing arrangements for aramid fiber and specialty elastomer procurement. Manufacturing concentrates in the United States, Germany, and Brazil, with raw material dependencies on aramid fiber from domestic sources, HNBR compound from European suppliers, and steel wire reinforcement from East Asian mills. Single-source vulnerability in HNBR feedstock creates structural risk for sour gas service production. Distribution runs through integrated service contractors in North American shale plays and direct OEM supply agreements for offshore projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against spoolable reinforced thermoplastic pipes capturing land-based gathering line applications above 2,000 meters. Incumbents must navigate this material transition while preserving certification-intensive offshore positions.
For Market Incumbents: Entrench API 7K and ISO 13628-5 certification capacity as the primary defensive moat against thermoplastic substitution threats. Deepen backward integration into aramid fiber supply through captive reinforcement partnerships. Expand qualification infrastructure in Brazil to capture pre-salt field development timelines before local content requirements harden. For New Entrants and Emerging Players: Establish a beachhead in West African offshore markets where Senegal-Mauritania gas development lacks established hose service infrastructure. Target inspection and recertification services as the most penetrable segment, bypassing eighteen-month API qualification barriers. Pursue digital twin integration partnerships with sensor manufacturers as the primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pressure pumping service contractors consolidating purchasing authority through multi-year bundled agreements. Long-term viability hinges on exposure to offshore certification premiums rather than commoditized onshore replacement cycles. Watch API qualification backlog duration as the signal for pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| API Qualification Capacity Expansion | Reduces eighteen-month certification bottlenecks gating subsea project schedules for Petrobras-operated platforms. |
| Aramid Fiber Supply Partnership | Secures captive reinforcement access for weight-critical floating production systems in Norway's North Sea fields. |
| Digital Twin Platform Integration | Enables predictive retirement scheduling commanding 40-60% service contract premiums from offshore operators. |
| West African Service Infrastructure Buildout | Captures first-mover positioning in Senegal-Mauritania gas export projects lacking established maintenance networks. |
| REACH Compliance Reformulation Investment | Accelerates alternative barrier chemistry qualification ahead of PFOA-processed material phase-out deadlines. |
Research Methodology
A spread of perspectives from hose assembly fabricators, pressure pumping fleet procurement directors, subsea equipment engineers, and refinery mechanical integrity managers converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from API certification records, BSEE incident reporting databases, OSHA enforcement data, and customs trade statistics. Bottom-up triangulation across product type demand and top-down validation against regional exploration capital expenditure patterns anchored the market sizing.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling across product construction, operational deployment, buyer type, and material composition. Deployment depth, pressure rating tier, and certification status formed additional industry-specific dimensions. CAGRs derived from replacement cycle compression rates and qualification timeline extensions rather than extrapolated historical trends. Forecast inputs incorporated hydraulic fracturing stage intensity in Permian Basin operations and pre-salt field development schedules off Brazil's coast.
Sensitivities concentrate around thermoplastic pipe substitution velocity, API qualification timeline fluctuations, and REACH enforcement stringency in European barrier material supply. Forecasts reflect documented assumptions regarding replacement cycle compression and offshore local content requirement evolution. Macroeconomic deviation in exploration capital allocation, regulatory acceleration in persistent organic pollutant restrictions, or breakthrough advances in non-metallic reinforcement chemistry would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
China Oil and Gas Midstream Market
Oil & Gas
Oil Hose Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Colombia Oil and Gas Midstream Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Global Carbon Steel Tubing in Oil and Gas Lift Applications Market
Oil & Gas
North America Proppants Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
North America Oil Storage Market
Oil & Gas
Global Deep-Well Disposal Services Market
Oil & Gas
Canada LNG Market
Oil & Gas
Wellhead System Market
Oil & Gas
Canada Oil and Gas Market
Oil & Gas
LNG Storage Tank Market