
 Wind Turbine Automation Market | 2026-2036
Wind Turbine Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Wind Turbine Automation Market Analytics
Buyer concentration among offshore wind developers is decoupling from traditional onshore utility procurement patterns as independent power producers and hybrid project financiers multiply. GE Vernova leverages its digital twin platform to anchor long-term service contracts across European offshore zones. Vestas Wind Systems A/S differentiates through predictive maintenance algorithms that sustain turbine availability rates above industry benchmarks. Siemens Gamesa Renewable Energy competes on integrated nacelle-control architectures that dominate the 8 MW-plus segment.
Wind turbine automation encompasses the sensor networks, programmable controllers, and supervisory systems that govern blade pitch, yaw orientation, generator output, and grid synchronization in variable wind conditions. These systems typically operate within IEC 61400-25 communication frameworks, processing sub-second telemetry from hundreds of IoT sensors per turbine to maximize energy capture and structural longevity. SCADA platforms command the largest installed base across deployment types, while IoT Sensors represent the fastest-expanding technology layer as edge-computing capabilities migrate into nacelle electronics. Control Systems capture the dominant share of component-level value, though Software Solutions are reshaping margin pools through subscription-based analytics and remote diagnostics.
The EU F-Gas Regulation and REACH directives constrain refrigerant and lubricant choices in turbine drivetrains, while China's GB standards and NMPA-equivalent equipment certifications govern domestic automation procurement. Germany's KBA and the US FAA coordinate offshore zoning and aviation lighting standards that dictate sensor placement and control-system redundancy. Stakeholders must monitor how divergent cybersecurity mandates between IEC 62351 and NERC CIP frameworks will fragment software certification pathways and reshape vendor qualification timelines.
Market Dynamics
Offshore wind farm operators are consolidating procurement of automated control systems around integrated nacelle architectures, compressing vendor qualification timelines and reshaping competitive entry barriers across the value chain.
Growth Catalysts
- EU F-Gas Regulation:Tightening refrigerant constraints in turbine drivetrains are accelerating replacement cycles for legacy control systems across European offshore zones.
- Edge computing migration:IoT sensor networks with onboard processing capabilities are expanding addressable automation scope beyond traditional SCADA platforms.
- China:GB standards enforcement and NMPA-equivalent equipment certifications are mandating domestic automation upgrades across turbine fleets exceeding 15 years of service.
Market Restraints
- Semiconductor supply concentration:Programmable logic controllers and power electronics depend on concentrated Asian foundry capacity, exposing lead time volatility for nacelle control systems.
- IEC 62351 cybersecurity mandates:Divergent certification pathways between European and North American cybersecurity frameworks are fragmenting software qualification timelines and raising compliance costs.
- Copper and rare earth magnet pricing:Yaw drive motors and generator control systems face input cost pressure from commodity volatility in permanent magnet supply chains.
Strategic Opportunities
- United States:FAA offshore zoning coordination and aviation lighting standards are creating specification windows for redundant sensor placement in coastal wind developments.
- Predictive maintenance algorithms:Machine learning convergence with vibration telemetry is opening subscription revenue pools beyond traditional hardware sales.
- Germany:KBA maritime certification requirements for offshore installations are accelerating demand for integrated control-validation services.
Industry Challenges
- SCADA-IoT integration complexity:Legacy turbine fleets require costly retrofit engineering to harmonize decades-old supervisory systems with modern edge-computing sensor layers.
- IEC 61400-25 certification timelines:Communication framework compliance for multi-vendor turbine arrays extends project commissioning schedules and strains working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wind Turbine Automation Market |
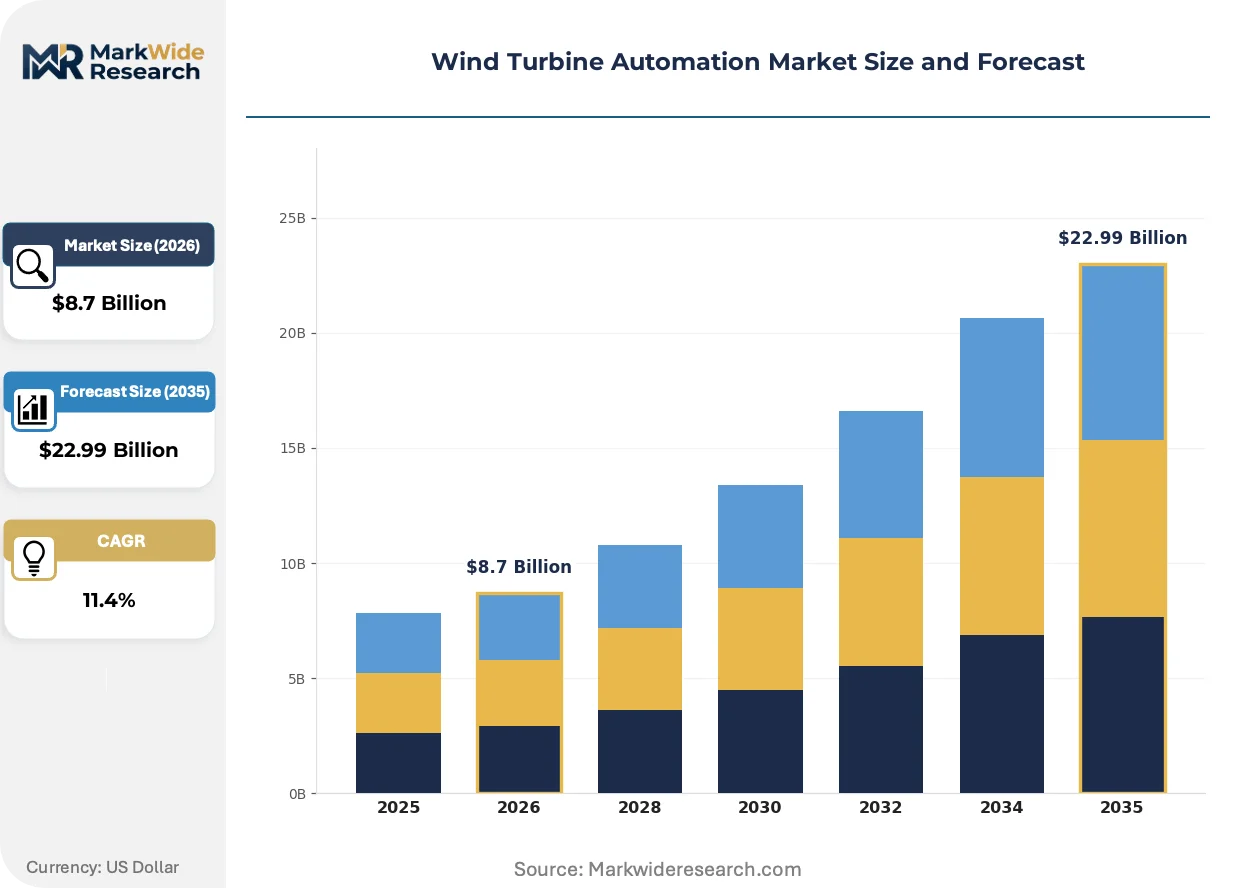
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: SCADA, PLC, DCS, IoT Sensors End User: Utility, Independent Power Producer, OEM, Consultancy Component: Control Systems, Sensors, Actuators, Software Solutions Deployment: Onshore, Offshore, Hybrid, Remote |
| Companies Covered | GE Vernova, Nordex SE, Vestas Wind Systems A/S, Mingyang Smart Energy, Envision Energy, Siemens Gamesa Renewable Energy, ENERCON GmbH, Shanghai Electric Wind Power Group Co., Ltd., Goldwind Science & Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wind Turbine Automation Market Evolving Landscape
Digital twin architectures and edge-computing sensor networks are compressing the traditional divide between hardware control systems and software analytics, enabling real-time turbine optimization that was previously confined to post-processing diagnostics.
Edge-computing nacelle electronics are consolidating turbine automation functions that previously required separate SCADA, condition monitoring, and power converter control cabinets. Offshore developers in the North Sea and Baltic Sea are deploying these integrated systems to reduce nacelle weight and cabling complexity. The technology is consolidating vendor tiers by enabling single-source responsibility for control, monitoring, and grid synchronization functions.
REACH directives and EU F-Gas Regulation amendments are constraining lubricant and coolant formulations in turbine drivetrains, forcing automation suppliers to recalibrate thermal management algorithms and sensor thresholds. Equipment manufacturers must revalidate control system performance under alternative fluid specifications. European OEMs are responding fastest, embedding compliance documentation into automated certification workflows.
Independent power producers and hybrid project financiers are fragmenting traditional utility procurement patterns, unbundling long-term service contracts from initial equipment supply. Developer consortiums in Chinese and German offshore zones now separate automation hardware sourcing from predictive analytics subscriptions. This shift is most visible in markets where tax equity structures incentivize operational expenditure optimization over capital expenditure minimization.
Wind Turbine Automation Market Segmentation
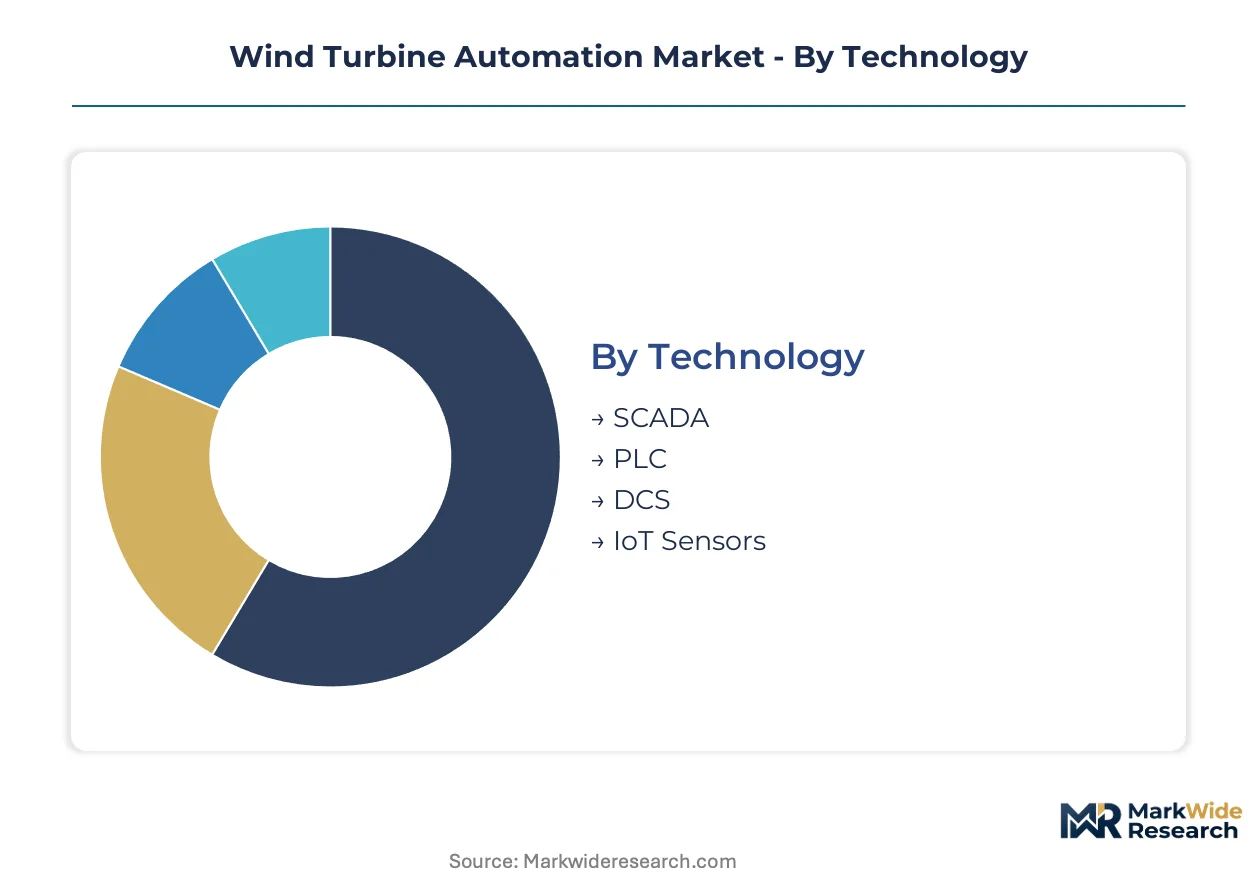
Wind turbine automation vendors configure product portfolios across four intersecting dimensions. Technology choices determine data architecture, while deployment type dictates environmental hardening requirements and certification pathways.
Technology:
Supply concentration among Asian semiconductor foundries shapes procurement risk profiles for each automation layer differently.
- SCADA:Supervisory control platforms aggregate turbine-level telemetry into centralized operator dashboards using IEC 61400-25 communication protocols. European offshore developers in the North Sea and Baltic Sea specify these systems for multi-array fleet coordination under KBA maritime certification requirements. The installed base remains largest across all deployment types.
- IoT Sensors:Edge-computing sensor networks process vibration, temperature, and aerodynamic data within nacelle-mounted electronics rather than transmitting raw signals to ground stations. Demand concentrates in Chinese offshore zones where GB standards mandate real-time structural monitoring for turbines exceeding 8 MW capacity. These devices are expanding addressable automation scope fastest.
- PLC:Programmable logic controllers execute millisecond-scale blade pitch and yaw adjustments using ladder logic routines. German turbine OEMs specify these for onshore retrofit projects where legacy SCADA systems require deterministic control supplementation.
- DCS:Distributed control systems coordinate multi-turbine arrays as unified generation assets for grid synchronization. US independent power producers deploy these in hybrid wind-storage configurations under FERC interconnection standards.
Today's leader: SCADA. Tomorrow's challenger: IoT Sensors.
End User:
Procurement authority fragmentation is accelerating as capital structures shift from utility balance sheets toward project finance vehicles.
- Utility:Vertically integrated electric utilities specify automation systems through decade-long framework agreements that bundle hardware supply with predictive maintenance subscriptions. These buyers dominate German and US onshore procurement under rate-base cost recovery mechanisms.
- Independent Power Producer:Non-utility developers unbundle equipment sourcing from service contracts to optimize tax equity structures. Chinese and German offshore consortiums now separate automation hardware procurement from analytics subscriptions, concentrating demand among financial sponsors rather than strategic buyers.
- OEM:Turbine manufacturers integrate automation as captive subsystems within nacelle assemblies. Vestas and Siemens Gamesa maintain in-house control system production for 8 MW-plus offshore platforms.
- Consultancy:Engineering firms specify third-party automation for owner-operated fleet modernization projects. These buyers concentrate in markets with aging turbine populations exceeding 15 years of service.
Utilities retain volume leadership. Independent power producers are gaining share fastest in offshore development.
Component:
Margin pools are migrating from electromechanical hardware toward software-intensive layers as subscription revenue models displace one-time equipment sales.
- Control Systems:Programmable controllers, power converters, and grid synchronization electronics constitute the dominant value share within nacelle automation architectures. These systems face input cost pressure from copper and rare earth magnet volatility in yaw drive motors.
- Software Solutions:Predictive analytics platforms and digital twin environments generate recurring revenue through remote diagnostics subscriptions. Machine learning convergence with vibration telemetry is opening revenue pools beyond traditional hardware sales.
- Sensors:Accelerometers, temperature probes, and blade pitch encoders provide raw telemetry for control algorithms. REACH and EU F-Gas Regulation constraints are forcing recalibration of thermal management sensor thresholds.
- Actuators:Electromechanical and hydraulic drives execute blade pitch and yaw positioning commands. These components require redundant certification under IEC 61400 standards for offshore aviation lighting coordination.
Control Systems anchor current revenue. Software Solutions are climbing the fastest.
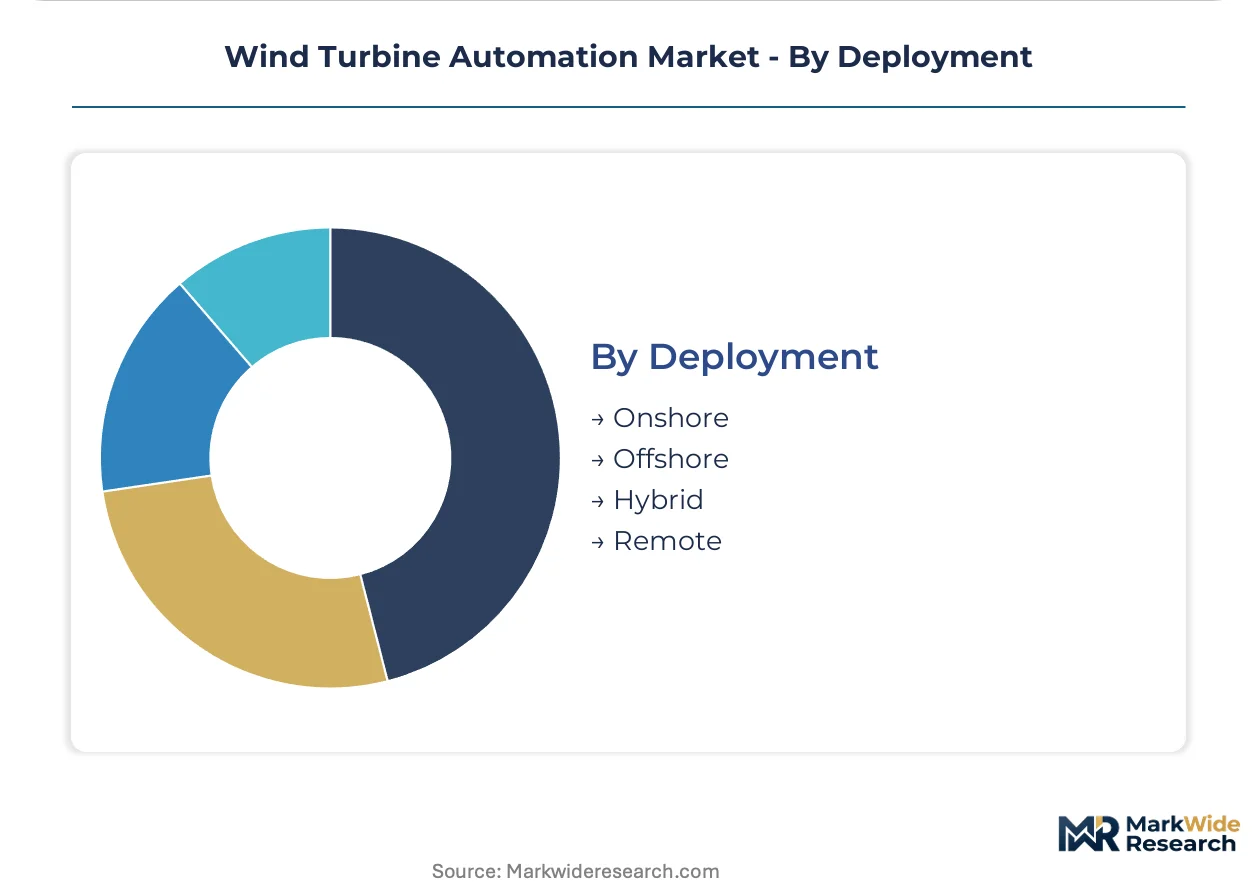
Deployment:
Environmental severity and accessibility constraints dictate automation architecture choices across installation types.
- Offshore:Salt corrosion, vibration, and limited maintenance access demand hardened control systems with redundant communication pathways. KBA maritime certification and FAA aviation lighting standards specify sensor placement and control-system redundancy for North Sea and US Atlantic developments.
- Onshore:Established turbine populations require retrofit engineering to harmonize legacy SCADA with modern edge-computing layers. China's GB standards enforcement is mandating domestic automation upgrades across fleets exceeding 15 years of service.
- Hybrid:Co-located wind and storage assets require integrated control architectures that coordinate generation with battery dispatch. US developers under FERC Order 841 specify these systems for wholesale market participation.
- Remote:Grid-isolated installations depend on satellite or mesh-network telemetry with autonomous fault-response capabilities. These configurations concentrate in frontier markets with limited transmission infrastructure.
Onshore retains installed base dominance. Offshore is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed turbine base while Germany enforces the most stringent automation certification standards, creating divergent procurement patterns across major markets. The United States and India are accelerating offshore development timelines. Sub-regional clusters concentrate engineering expertise and manufacturing capacity.
China
GB standards enforcement and NMPA-equivalent equipment certifications mandate automation upgrades across aging onshore fleets exceeding 15 years of service. The MIIT drives domestic semiconductor substitution in programmable controllers to reduce import dependency. Yangtze River Delta clusters around Shanghai host integrated nacelle assembly facilities serving both domestic and export markets.
Germany
KBA maritime certification requirements accelerate demand for redundant control-validation services in North Sea and Baltic Sea developments. The EU F-Gas Regulation tightens refrigerant constraints in turbine drivetrains, forcing thermal management algorithm recalibration. North Rhine-Westphalia industrial corridors concentrate drivetrain automation engineering and certification laboratory capacity.
United States
FAA offshore zoning coordination with FERC interconnection standards creates specification windows for redundant sensor placement in Atlantic coastal developments. The IRA production tax credit structures incentivize operational expenditure optimization over capital expenditure minimization. Northeast corridor project finance consortiums unbundle hardware procurement from predictive analytics subscriptions.
India
CEA grid code amendments mandate enhanced grid synchronization capabilities for multi-megawatt turbine arrays connecting to weak transmission networks. BIS certification timelines for IEC 61400-25 compliance extend project commissioning schedules for imported control systems. Gujarat and Tamil Nadu coastal zones concentrate early-stage offshore wind automation pilot deployments.
United Kingdom
Ofshore wind lease rounds under the Crown Estate drive procurement of integrated nacelle architectures for North Sea floating platform developments. The UK Health and Safety Executive enforces aviation lighting and marine coordination standards dictating sensor placement redundancy. Scottish waters host deep-water automation trials requiring autonomous fault-response capabilities beyond conventional SCADA reach.
Wind Turbine Automation Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered automation supply tiers, with offshore scale requirements favoring integrated platform vendors over component suppliers. The vendor base clusters around three strategic archetypes: full-system OEMs with captive control production, independent automation specialists licensing across turbine brands, and software-centric analytics platforms unbundling from hardware supply. Dominant competitive moves include backward integration into sensor manufacturing and strategic partnerships securing semiconductor foundry allocation.
Among diversified industrial conglomerates, GE Vernova and Siemens Gamesa Renewable Energy occupy positions anchoring integrated nacelle-control architectures for 8 MW-plus offshore segments. Vestas Wind Systems A/S exemplifies the focused pure-play archetype with in-house predictive maintenance algorithm development. These three entities represent distinct strategic postures: conglomerate platform breadth versus specialist operational depth versus hybrid hardware-software convergence.
| Leading Market Players |
|---|
| GE Vernova |
| Nordex SE |
| Vestas Wind Systems A/S |
| Mingyang Smart Energy |
| Envision Energy |
| Siemens Gamesa Renewable Energy |
| ENERCON GmbH |
| Shanghai Electric Wind Power Group Co., Ltd. |
| Goldwind Science & Technology Co., Ltd. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation amendments are gating qualified supply and premium-tier pricing access by forcing automation vendors to revalidate thermal management algorithms under alternative refrigerant specifications before securing maritime certification for North Sea deployments.
Pricing Analysis
Capacity additions in Chinese semiconductor foundries are reshaping price floors for programmable logic controllers and power electronics, compressing margins for European automation specialists. Three-tier pricing structure across premium, standard, and economy levels stratifies by IEC 61400-25 certification grade and after-sales service bundling. Cost compression in standard-tier SCADA hardware is intensifying because Yangtze River Delta manufacturing clusters are scaling nacelle electronics output. Independent power producers exhibit highest price sensitivity due to tax equity structure constraints, while German utilities under rate-base recovery show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundry capacity for industrial-grade semiconductors powering blade pitch controllers and yaw drive systems. The supply chain draws from China for rare earth magnets in permanent magnet generators, Germany for precision drivetrain components, and South Korea for power electronics modules. Copper and neodymium price volatility in permanent magnet supply chains creates commodity exposure for nacelle control architectures. Distribution runs through turbine OEM captive channels and third-party engineering procurement firms serving fleet modernization projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
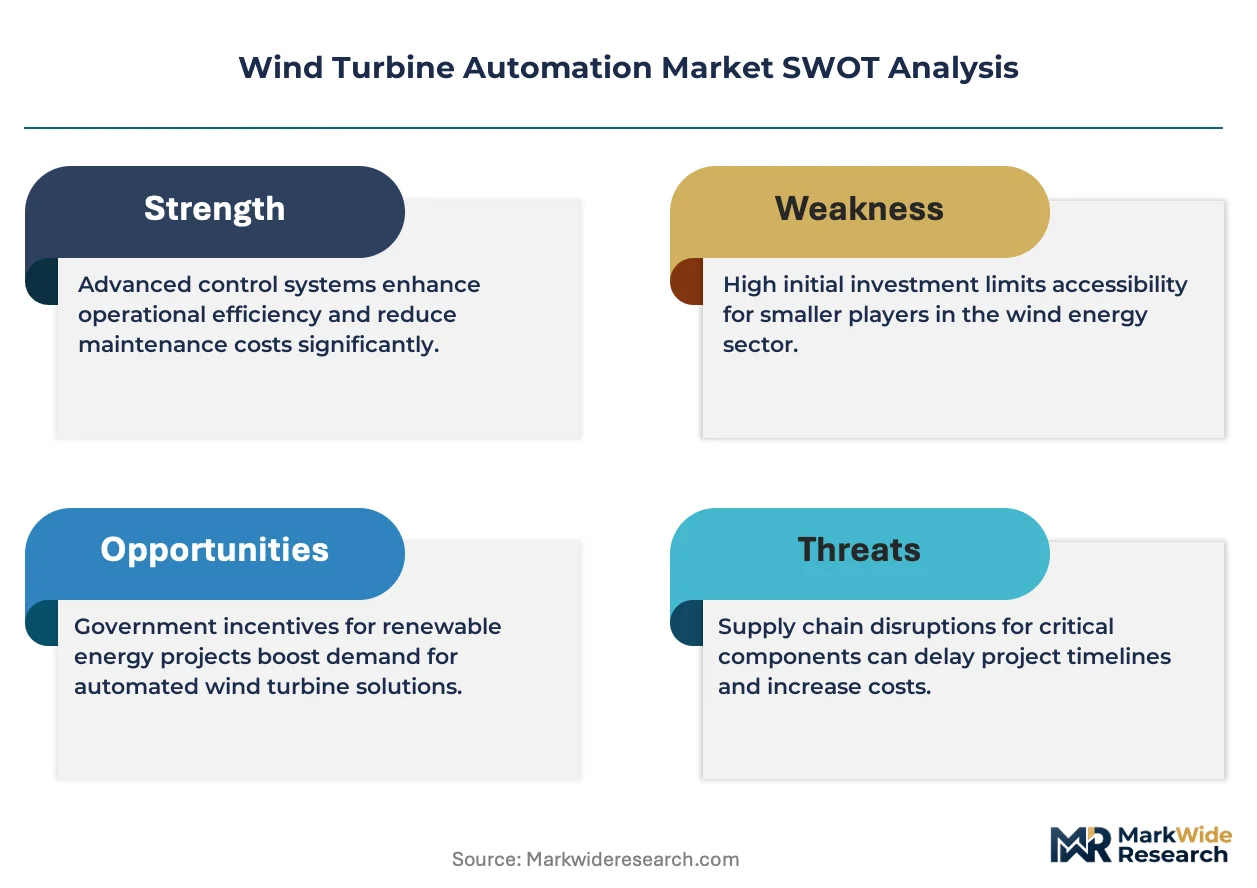
Margin expansion in wind turbine automation rests on software subscription revenue displacing one-time hardware sales, with predictive analytics platforms capturing recurring value from operational expenditure optimization.
For Market Incumbents: Hedge against semiconductor supply volatility by securing long-term foundry allocation agreements for industrial-grade PLCs and power electronics. Consolidate backward integration into sensor manufacturing to reduce import dependency exposure under China's MIIT domestic substitution mandates. Prioritize IEC 62351 cybersecurity certification investment to preempt fragmentation between European and North American compliance pathways. For New Entrants and Emerging Players: Engineering procurement firms represent the most accessible channel partner type for penetrating aging onshore fleet modernization markets in China and Germany. Target consultancy-specified automation retrofits for turbines exceeding 15 years of service where incumbent OEMs maintain weaker service lock-in. Pursue white-label edge-computing sensor partnerships with Yangtze River Delta nacelle assemblers to bypass direct utility sales cycles. For Investors and Strategic Acquirers: Roll-up economics work for independent automation specialists licensing across turbine brands because procurement authority fragmentation among IPPs and hybrid project financiers is unbundling long-term service contracts from hardware supply. Five-to-ten year viability favors software-centric analytics platforms with established vibration telemetry machine learning pipelines over pure hardware vendors. Monitor divergence between IEC 62351 and NERC CIP cybersecurity mandate harmonization as inflection indicator for vendor qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces import exposure under China's MIIT domestic substitution mandates for nacelle electronics. |
| Digital Twin Platform Development | Captures subscription revenue from GE Vernova-style long-term service contracts in European offshore zones. |
| IEC 61400-25 Certification Investment | Accelerates project commissioning timelines for multi-vendor turbine arrays under KBA maritime requirements. |
| Predictive Maintenance Algorithm Licensing | Opens recurring revenue pools beyond hardware sales through Vestas-style availability rate guarantees. |
| Edge-Computing Nacelle Consolidation | Reduces cabling complexity and weight for 8 MW-plus offshore platforms in North Sea developments. |
Research Methodology
Multiple input streams — executive interviews with turbine OEM control system architects, primary discussions with offshore project developers, and technical consultations with maritime certification engineers — were reconciled against customs trade data for automation component imports, FERC interconnection filings, and EIA project development databases. Bottom-up unit economics for nacelle control systems were triangulated with top-down market sizing from turbine deployment pipelines.
Historical installation trajectories were cross-referenced against expert panel assessments of edge-computing adoption velocity across the projection horizon. Segmentation modeling incorporated technology layer, deployment type, end-user procurement authority, and regional regulatory framework dimensions. CAGRs were derived from capacity expansion schedules and replacement cycle dynamics for aging fleets, with semiconductor supply constraints and cybersecurity certification timelines as key sensitivity inputs.
Revisions become necessary when F-Gas Regulation amendments accelerate thermal management system recertification, or when cybersecurity mandate divergence fragments software qualification pathways beyond current modeling assumptions. Forecasts reflect documented assumptions about offshore development timelines and domestic content requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Renewable Energy Inverters Market
Renewable Energy
Philippines Renewable Energy Market
Renewable Energy
Net-Zero Energy Buildings Market
Renewable Energy
Europe Single-Axis Solar Tracker Market
Renewable Energy
North America Renewable Energy Market
Renewable Energy
Europe Ocean Power Market
Renewable Energy
India Renewable Energy Market
Renewable Energy
Hungary Renewable Energy Market
Renewable Energy
Offshore Wind Energy Infrastructure Market
Renewable Energy
Africa Renewable Energy Market
Renewable Energy
Renewable Energy Cable Market
Renewable Energy
Solar Cooker Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Germany Renewable Energy Market
Renewable Energy
Solar Farm Market