
 Global Refrigeration Oil Market | 2026-2036
Global Refrigeration Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigeration Oil Market Foresight
The EU F-Gas Regulation is decoupling refrigeration oil demand from traditional mineral-based formulations, forcing cold chain operators and OEMs to qualify synthetic lubricants compatible with hydrofluoroolefin blends. ExxonMobil Corporation leverages its integrated polyol ester supply chain to capture premium positions in compressor OEM fill markets. Shell plc anchors European demand through backward integration into base-stock refining and direct technical service ties with supermarket retrofit programs. BASF SE differentiates via specialty additive packages that extend drain intervals in ammonia and CO2 systems.
Refrigeration oil comprises refined base stocks—mineral, synthetic, or semi-synthetic—formulated with antioxidant, antiwear, and foam suppressant additives to lubricate compressor bearings, seal clearances, and transfer heat in vapor-compression cycles; typical viscosity grades span ISO 32 to ISO 68 with pour points below minus forty degrees Celsius for low-temperature evaporator duty. Synthetic oil commands the highest margin pool as OEMs mandate compatibility with R-32, R-1234yf, and R-513A refrigerant chemistries. Commercial refrigeration generates the largest volume footprint, while transport refrigeration represents the fastest-growing application segment due to refrigerated trucking fleet expansion in Asia and Latin America.
The U.S. EPA SNAP program, Japan's METI refrigerant transition roadmap, and China's GB standards for low-GWP equipment collectively shape product registration requirements and reformulation timelines across major manufacturing bases. Compliance with REACH substance restrictions and evolving F-Gas phase-down quotas in Europe limits market access for lubricant suppliers lacking certified synthetic portfolios. Stakeholders must monitor refrigerant-chemistry migration paths and pre-qualify next-generation lubricants against compressor OEM test protocols before regulatory deadlines compress switching windows.
Market Dynamics
Refrigerant chemistry migration paths are fragmenting lubricant formulation requirements as compressor OEMs pre-qualify polyol ester portfolios against hydrofluoroolefin compatibility mandates before regulatory deadlines compress switching windows.
Growth Catalysts
- EU F-Gas Regulation phase-down quotas:Cold chain operators in Germany and France accelerate retrofit cycles to maintain compliance, pulling forward synthetic lubricant demand for lower-GWP refrigerant systems.
- E-commerce grocery fulfillment networks:Domestic cold storage expansion in China drives fleet lubrication program upgrades to protect compressor efficiency under stricter food safety protocols.
- Transport refrigeration fleet expansion:Refrigerated trucking growth across Brazil and India generates aftermarket volume for high-viscosity synthetic formulations in mobile compressor applications.
Market Restraints
- Base-stock supply concentration:Captive polyol ester production capacity concentrates among integrated petrochemical majors, limiting formulation flexibility for independent blenders.
- REACH substance restriction compliance costs:European additive package requalification expenses compress margins for specialty lubricant suppliers serving ammonia and CO2 refrigeration systems.
- Mineral oil substitution lag:Legacy R-22 equipment in Southeast Asian cold storage facilities extends drain intervals, delaying synthetic conversion timelines.
Strategic Opportunities
- India cold chain infrastructure buildout:FSSAI-mandated food safety upgrades drive first-time synthetic lubricant adoption in domestic dairy and pharmaceutical storage networks.
- Carbon dioxide transcritical system proliferation:Supermarket retrofit programs in Scandinavia create demand for polar additive packages that manage miscibility in high-pressure compressor architectures.
- Digital fleet monitoring integration:Cold chain operators combine lubricant condition sensors with predictive maintenance platforms to optimize drain intervals across distributed transport assets.
Industry Challenges
- Refrigerant-lubricant miscibility testing capacity:Compressor OEM qualification protocols require extended thermal stability trials that strain laboratory throughput at independent testing facilities.
- Cross-border formulation registration:Divergent GB standards in China, METI refrigerant roadmaps in Japan, and EPA SNAP program requirements in the US multiply compliance documentation burdens for multinational lubricant suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigeration Oil Market |
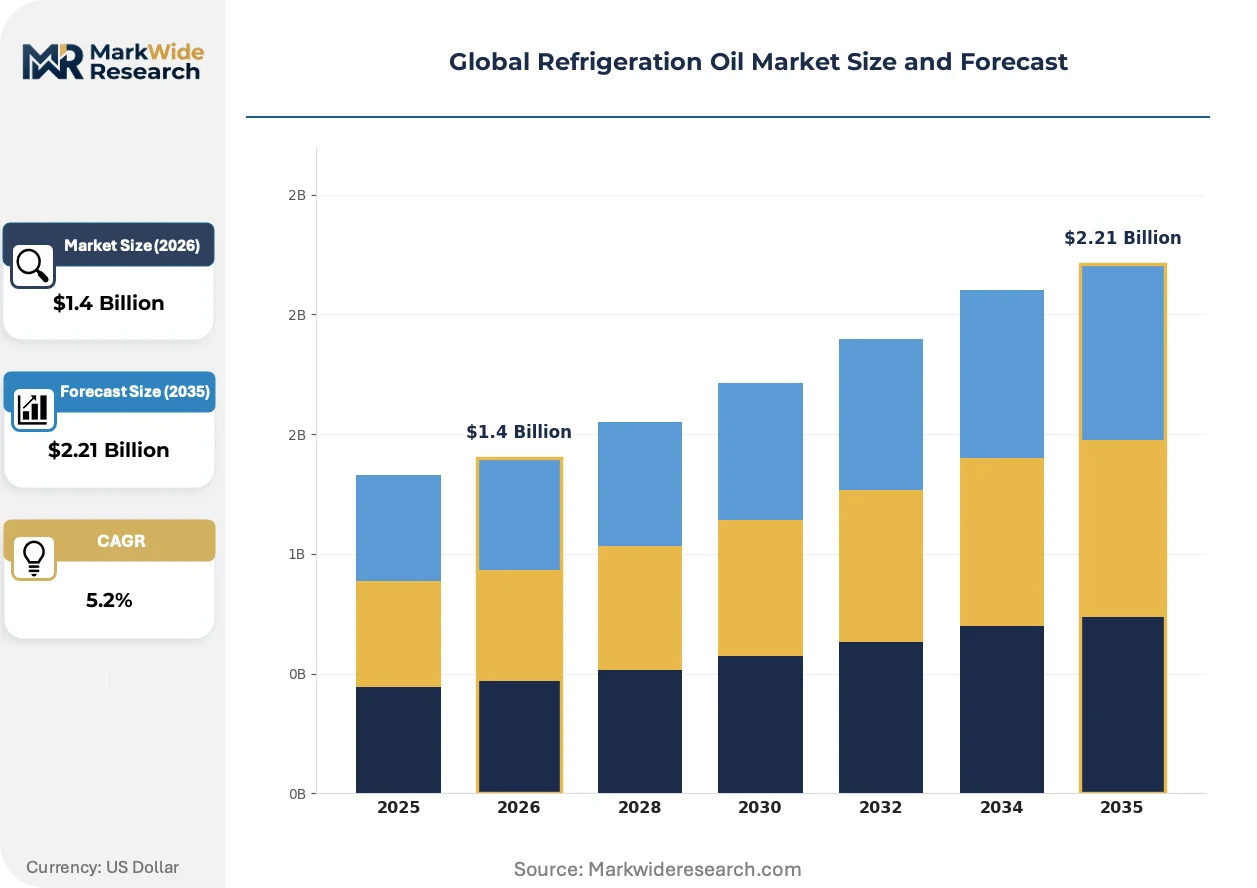
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oil, Mineral Oil, Polyol Ester Oil, Alkylbenzene Oil, Silicone Oil Technology: Compressor Lubrication, Heat Transfer, Insulation, Vapor Compression, Absorption Systems Application: Commercial Refrigeration, Industrial Cooling, Transport Refrigeration, Cold Storage, HVAC Systems End User: Manufacturers, Cold Chain Operators, Food Processing, Refrigeration Contractors, Chemical Plants |
| Companies Covered | ExxonMobil Corporation, Shell plc, BASF SE, Idemitsu Kosan Co. Ltd, TotalEnergies, PETRONAS Lubricants International, China Petroleum & Chemical Corporation, FUCHS, ENEOS Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigeration Oil Market Shifts & Advancements
Formulation science is converging with compressor engineering specifications as OEMs tighten lubricant qualification windows ahead of refrigerant transition deadlines.
Polyol ester chemistry is consolidating technical leadership in synthetic refrigeration oil portfolios. Cold storage operators in the Netherlands and Denmark specify these formulations for R-1234yf and R-513A systems to maintain thermal stability under low-temperature evaporator duty. The technology is consolidating supplier relationships around integrated base-stock producers capable of backward integration into additive package development.
Japan's METI refrigerant transition roadmap mandates equipment phase-out schedules that cascade into lubricant pre-qualification requirements. Domestic compressor manufacturers accelerate test protocols to certify miscibility with next-generation hydrofluoroolefin blends before installation deadlines. Transport refrigeration OEMs face compressed switching windows that favor lubricant suppliers with established Asian technical service infrastructure.
Service contract unbundling is fragmenting procurement authority in European supermarket chains. Facility managers now source lubricants separately from compressor maintenance agreements, creating direct purchasing relationships with specialty blenders. This pattern concentrates in Germany and the UK where energy efficiency auditing requirements elevate lubricant selection to a standalone compliance decision.
Global Refrigeration Oil Market Segmentation
Refrigeration oil procurement patterns diverge sharply between integrated compressor OEM fill programs and fragmented aftermarket service contracts. Understanding these segment boundaries clarifies where formulation premiums concentrate versus where price competition dominates.
Product Type:
Mineral oil formulations function as standalone drop-in lubricants for legacy R-22 and R-134a systems, while synthetic chemistries require tight integration with compressor OEM qualification protocols and refrigerant compatibility testing.
- Synthetic Oil:Polyol ester and polyalkylene glycol base stocks deliver thermal stability above 150°C for R-32 and hydrofluoroolefin refrigerant blends. Cold chain operators in Germany and France specify these formulations for supermarket retrofit programs under EU F-Gas Regulation mandates.
- Mineral Oil:Refined naphthenic and paraffinic base stocks serve legacy ammonia systems and R-22 equipment in Southeast Asian cold storage facilities. Extended drain intervals in Vietnam and Indonesia delay conversion timelines despite refrigerant phase-down pressures.
- Polyol Ester Oil:Polar ester structures optimize miscibility with lower-GWP refrigerants in transcritical CO2 architectures.
- Alkylbenzene Oil:Synthetic hydrocarbon chemistry bridges mineral and full-synthetic performance tiers for retrofit applications.
- Silicone Oil:Siloxane-based formulations address extreme low-temperature evaporator duty in specialized industrial applications.
Synthetic oil leads volumes today; polyol ester oil is gaining share fastest.
Technology:
Cost tiers separate mature vapor-compression lubrication from emerging absorption system chemistries that command formulation premiums.
- Compressor Lubrication:Bearing and seal lubrication accounts for the largest formulation volume across reciprocating, scroll, and screw compressor architectures. Transport refrigeration OEMs in Brazil specify high-viscosity synthetics for mobile duty cycles.
- Heat Transfer:Thermal conductivity-optimized oils double as working fluids in specialized refrigeration cycles. Industrial cooling networks in Texas and Alberta deploy these formulations for geothermal heat pump integration.
- Insulation:Dielectric-grade refrigeration oils protect hermetic compressor motor windings from electrical breakdown.
- Vapor Compression:Traditional lubrication for reciprocating and centrifugal systems dominates installed base maintenance.
- Absorption Systems:Lithium bromide and ammonia-water absorption chillers require specialized lubricant chemistries with distinct additive packages.
Compressor lubrication anchors revenue today; heat transfer technology is climbing the fastest.
Application:
Customer type fragmentation separates capital-intensive industrial cooling projects from recurring aftermarket service in commercial refrigeration.
- Commercial Refrigeration:Supermarket display cases and convenience store systems generate the largest installed base for lubricant aftermarket sales. Service contract unbundling in the UK and Germany redirects procurement toward direct specialty blender relationships.
- Transport Refrigeration:Mobile compressor applications in refrigerated trucking face severe thermal cycling and contamination exposure. Fleet expansion across India and Brazil drives synthetic formulation demand for extended drain intervals.
- Industrial Cooling:Petrochemical and pharmaceutical process cooling requires fire-resistant formulations for ammonia systems.
- Cold Storage:Warehouse refrigeration for e-commerce grocery fulfillment concentrates demand in China's eastern provinces.
- HVAC Systems:Building climate control applications overlap with refrigeration oil specifications in heat pump configurations.
Commercial refrigeration leads volumes today; transport refrigeration is expanding most quickly.
End User:
Supply concentration distinguishes captive OEM fill programs from fragmented contractor purchasing authority.
- Manufacturers:Compressor OEMs specify factory-fill lubricants through qualified supplier programs with multi-year technical service agreements. ExxonMobil and Shell anchor these relationships through integrated base-stock supply.
- Cold Chain Operators:Third-party logistics providers manage fleet lubrication programs across distributed assets. Digital condition monitoring integration in the Netherlands enables predictive drain interval optimization.
- Food Processing:Dairy and meat processing plants require food-grade incidental contact lubricants for compressor systems.
- Refrigeration Contractors:Independent service technicians source lubricants through wholesale distribution channels with limited brand loyalty.
- Chemical Plants:Process refrigeration for specialty chemicals demands fire-resistant and corrosion-inhibited formulations.
Manufacturers lead volumes today; cold chain operators are gaining procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refrigeration oil formulation science crystallized in early twentieth-century Germany, where compressor OEMs pioneered synthetic lubricant chemistry for industrial ammonia systems. Today, demand disperses across manufacturing clusters in Asia, Europe, and North America, each shaped by distinct refrigerant transition timelines and cold chain infrastructure investment cycles.
Germany
Supermarket retrofit programs in Bavaria and North Rhine-Westphalia accelerate synthetic lubricant adoption for R-1234yf and R-513A systems. The EU F-Gas Regulation phase-down quotas compress switching windows, forcing cold chain operators to pre-qualify polyol ester formulations before 2025 equipment deadlines. Berlin-based technical service networks anchor aftermarket distribution across Central European markets.
China
E-commerce grocery fulfillment expansion in the Yangtze River Delta and Pearl River Delta drives cold storage capacity additions requiring fleet lubrication upgrades. GB standards for low-GWP equipment mandate refrigerant-chemistry migration paths that cascade into lubricant requalification requirements. Shanghai and Shenzhen cluster compressor OEM fill programs alongside domestic base-stock refining investments.
United States
Industrial cooling networks in Texas and California deploy thermal conductivity-optimized oils for geothermal heat pump integration. The EPA SNAP program shapes product registration requirements for hydrofluoroolefin-compatible formulations. Houston and Los Angeles anchor petrochemical and pharmaceutical process cooling demand for fire-resistant ammonia system lubricants.
Japan
Domestic compressor manufacturers in the Chubu region accelerate test protocols to certify miscibility with next-generation hydrofluoroolefin blends. METI refrigerant transition roadmaps cascade into lubricant pre-qualification deadlines that favor suppliers with established Asian technical service infrastructure. Nagoya-based OEMs tighten qualification windows ahead of equipment phase-out schedules.
India
FSSAI-mandated food safety upgrades drive first-time synthetic lubricant adoption in Maharashtra and Gujarat dairy and pharmaceutical storage networks. Cold chain infrastructure buildout concentrates procurement authority among third-party logistics providers managing distributed assets. Mumbai and Ahmedabad anchor fleet lubrication program expansions for refrigerated trucking corridors.
Global Refrigeration Oil Market Competitive Landscape
Premium-margin players sit above commodity-margin players across base-stock integration depth and OEM qualification protocol access. Integrated petrochemical majors capture factory-fill positions through captive polyol ester production, while independent blenders compete on aftermarket service responsiveness and specialty additive formulation. The market structures around three archetypes: backward-integrated majors with refining-to-blending control, regional specialists with technical service density, and independent blenders with formulation flexibility. Competitive moves concentrate on capacity expansion in synthetic base stocks and strategic partnerships for refrigerant-lubricant miscibility testing access.
Within the integrated majors tier, ExxonMobil Corporation and Shell plc exemplify archetypes built on refining integration and direct OEM technical service relationships. BASF SE occupies a position as a specialty additive supplier extending drain intervals in alternative refrigeration systems. These three anchors demonstrate how market positioning derives from supply chain configuration rather than product differentiation alone.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Shell plc |
| BASF SE |
| Idemitsu Kosan Co. Ltd |
| TotalEnergies |
| PETRONAS Lubricants International |
| China Petroleum & Chemical Corporation |
| FUCHS |
| ENEOS Corporation |
| Others |
Supply & Pricing Matrix
Compressor OEM factory-fill programs concentrate procurement authority among integrated petrochemical majors, anchoring a contract-based pricing structure where multi-year technical service agreements lock in premium synthetic formulations and lock out price competition from independent blenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-qualified polyol ester formulations from semi-synthetic alkylbenzene retrofits and commodity mineral oil drops. Price differentiation hinges on refrigerant compatibility certification tier and captive base-stock integration depth. Cost compression in mineral oil segments is intensifying because Southeast Asian cold storage operators extend drain intervals on legacy R-22 equipment. Aftermarket service contractors exhibit highest price sensitivity, while supermarket chains under EU F-Gas mandates show lowest sensitivity due to compliance-driven specification requirements.
Supply Chain Analysis
Single-source vulnerability sits with China, Germany, and the United States for polyol ester base-stock production and additive package formulation. Raw material dependencies draw from palm oil derivatives for ester synthesis, phosphate esters for antiwear additives, and Group IV/V synthetic base oils from ethylene crackers. Tariff exposure on Chinese additive imports strains European blender margins. Distribution runs through compressor OEM qualified-supplier programs and regional technical service depots rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic lubricant premiums are expanding as cold chain operators absorb reformulation costs to meet lower-GWP refrigerant mandates, with polyol ester conversion timelines compressing faster than supply response.
For Market Incumbents: Acquire captive miscibility testing laboratory capacity to pre-qualify formulations ahead of Japan METI and China GB standard deadlines. Compressor OEMs are tightening qualification windows to 18-month cycles, squeezing independent blenders without in-house thermal stability protocols. Backward integration into Group V base-stock refining secures margin control against feedstock volatility. For New Entrants and Emerging Players: Digital fleet monitoring integration offers a technology-first wedge into transport refrigeration aftermarket contracts. Cold chain operators in India and Brazil lack predictive maintenance platforms for distributed trucking assets. White-space concentration sits with FSSAI-mandated dairy storage networks in Maharashtra and Gujarat, where first-time synthetic adoption creates specification voids. Partner with telematics providers to bundle lubricant condition sensors with drain interval optimization software. For Investors and Strategic Acquirers: Integrated petrochemical majors are the most active acquirer in this space, targeting regional blenders with established OEM technical service relationships. Long-term viability rests on synthetic base-stock capacity positions and refrigerant-chemistry migration alignment. Acquisition target archetype: mid-cap specialists with polar additive expertise for CO2 transcritical systems. Watch for EU F-Gas quota auction price spikes as inflection signal for accelerated retrofit pull-forward demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyol Ester Base Stocks | Captive supply of Group V synthetics locks in OEM fill positions against feedstock cost volatility. |
| Refrigerant-Lubricant Miscibility Testing Partnership | Joint laboratory access with compressor OEMs accelerates pre-qualification for R-1234yf and R-513A systems. |
| Digital Fleet Monitoring Platform Integration | Sensor-enabled predictive maintenance contracts in Indian refrigerated trucking secure recurring aftermarket revenue. |
| Polar Additive Package Development for CO2 Systems | Specialty formulations for transcritical supermarket retrofits in Scandinavia command formulation premiums. |
| Regional Technical Service Network Expansion | Distributed engineering support in China and Brazil captures transport refrigeration fleet lubrication programs. |
Research Methodology
Direct dialogue with compressor OEM procurement directors, cold chain operator fleet managers, lubricant blend plant engineers, and refrigerant transition consultants grounded qualitative findings. Secondary validation drew from EPA SNAP program filings, ECHA REACH substance restriction updates, Japan METI equipment phase-out schedules, and China GB standard draft releases. Bottom-up triangulation against customs trade data for polyol ester base-stock flows and top-down reconciliation with compressor production statistics established volume anchors.
Bottom-up modeling built from refrigerant chemistry migration paths and lubricant specification shifts across the analysis window. Segmentation dimensions included product type tier, compressor architecture, application duty cycle, and regional regulatory cluster. CAGRs derived from equipment installation forecasts and drain interval assumptions, with synthetic conversion rates calibrated to F-Gas quota phase-down trajectories and METI roadmap deadlines.
The model holds under steady regulatory enforcement timelines; deviation in EU F-Gas quota allocation or China GB standard implementation pace would shift volume trajectories. Forecasts reflect assumptions on refrigerant-lubricant miscibility test capacity expansion and cold storage capacity buildout rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Air Heater Tubes Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Middle East and Africa Variable Frequency Drive (VFD) Market
Industrial Motors
Synchronous Electric Motor Market
Industrial Motors
Global Linear Motors Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Vertical Gear Motor Market