
 Safety Drives and Motors Market | 2026-2036
Safety Drives and Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Drives and Motors Market Analytics
German industrial automation suppliers is rebalancing capacity toward integrated safety motion platforms. ABB Ltd leverages its servo drive portfolio to anchor premium positioning in process automation. Siemens AG dominates safety-certified drive architectures through its SIMOTION platform. Schneider Electric SE extends its machine safety footprint with PacDrive-compatible servo systems.
Safety drives and motors are electromechanical motion control devices engineered with redundant feedback channels, safe torque-off circuitry, and SIL-rated architectures to prevent hazardous energy release during human-machine interaction. These systems incorporate dual-channel encoders, STO (Safe Torque Off) interfaces, and Category 3 PLd safety architectures to satisfy IEC 61800-5-2 functional safety requirements for industrial machinery. Servo drives and AC motors command the largest installed base due to mature supply chains and broad applicability across automated production lines, while digital technology interfaces are displacing analog control in new installations as Industry 4.0 architectures demand real-time safety diagnostics over EtherCAT and PROFIsafe networks.
IEC 61508, ISO 13849, and the EU Machinery Directive shape product certification pathways and market access for safety motion equipment sold into European industrial end-use. OSHA lockout/tagout enforcement and NHTSA functional safety expectations for automated guided vehicles in US manufacturing facilities are extending compliance obligations beyond traditional machinery boundaries. Stakeholders must monitor evolving harmonization gaps between regional safety standards as export-oriented manufacturers face divergent certification costs across destination markets.
Market Dynamics
Automotive electrification is compressing development cycles for integrated safety motion systems as OEMs mandate SIL-rated architectures for autonomous assembly lines and battery production facilities.
Growth Catalysts
- EU Machinery Directive enforcement:European manufacturers must retrofit existing production lines with Category 3 PLd safety architectures, generating replacement demand for certified drive systems.
- Battery gigafactory construction:Cell assembly and module integration lines require STO-capable servo systems to protect workers from high-voltage hazards during human-robot collaboration.
- EtherCAT Safety proliferation:Real-time safety diagnostics over industrial Ethernet networks is reducing wiring complexity and enabling centralized safety monitoring across distributed motion axes.
Market Restraints
- Rare earth magnet dependency:Neodymium and dysprosium supply concentration in Chinese processing facilities creates input cost volatility for high-performance servo motors.
- Certification timeline friction:IEC 61508 SIL 3 validation cycles extend 18-24 months, delaying product launches and freezing development roadmaps.
- Integrated drive-motor substitution:Compact mechatronic units with embedded safety logic are displacing discrete drive-motor pairings in space-constrained robotic applications.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives for automotive and electronics production are creating first-mover advantage for safety motion suppliers establishing local certification support.
- AGV safety standardization:NHTSA functional safety expectations for automated guided vehicles extend addressable demand beyond traditional fixed machinery into mobile robotics.
- Digital twin convergence:Integration of safety drive diagnostics with virtual commissioning platforms is compressing validation cycles and reducing physical prototype requirements.
Industry Challenges
- Functional safety engineering scarcity:SIL certification expertise and TÜV qualification pathways remain concentrated among a limited pool of specialized engineers, constraining R&D throughput.
- Legacy fieldbus integration:Brownfield facilities running PROFIBUS DP networks face complex gateway architectures to bridge STO safety signals into modern EtherCAT infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Drives and Motors Market |
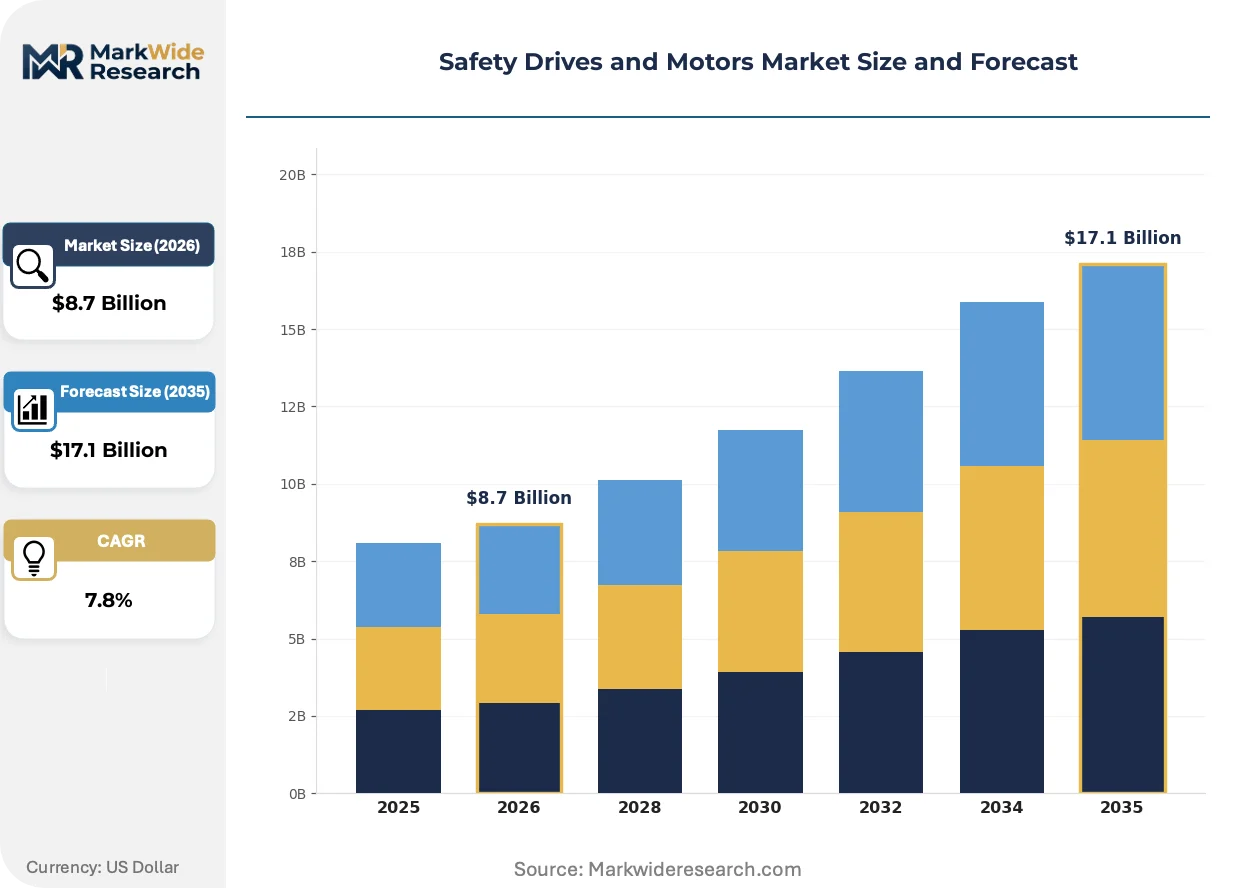
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Servo Drives, AC Motors, DC Motors, Stepper Motors Technology: Digital, Analog, Hybrid, Wireless End User: Automotive OEMs, Industrial Machinery, Robotics, HVAC Systems Application: Process Automation, Conveyor Systems, Material Handling, Safety Systems |
| Companies Covered | Rockwell Automation Inc., ABB Ltd, Siemens AG, Schneider Electric SE, Mitsubishi Electric Corporation, Beckhoff Automation GmbH, KOLLMORGEN Corporation, Emerson Electric Co., Bosch Rexroth AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Drives and Motors Market Evolving Landscape
Real-time safety diagnostics and predictive maintenance capabilities are redefining how motion systems protect personnel while sustaining production uptime in continuous manufacturing environments.
Single-chip safety drive architectures with integrated STO circuitry and dual-channel encoder interfaces are electrifying the cost structure of SIL-rated motion control. Packaging machinery OEMs in Germany and Japan are adopting these compact designs to reduce panel space and wiring labor. The technology is electrifying competitive positioning by enabling mid-tier suppliers to offer certified safety performance previously reserved for premium platforms.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of insulation materials and bearing lubricants in safety motors sold into European industrial end-use. Motor manufacturers must validate alternative dielectric systems without compromising thermal performance or bearing life. The regulation most affects food and beverage processing equipment where washdown duty ratings intersect with material compliance requirements.
Certification-driven procurement is consolidating supplier relationships as automotive and pharmaceutical buyers mandate pre-qualified safety component vendors to accelerate their own machinery validation. Distributors with in-house functional safety support capabilities are displacing traditional component resellers in specification-intensive segments. This pattern is most visible in German automotive supply chains where OEM safety audits cascade tier-by-tier through equipment suppliers.
Safety Drives and Motors Market Segmentation
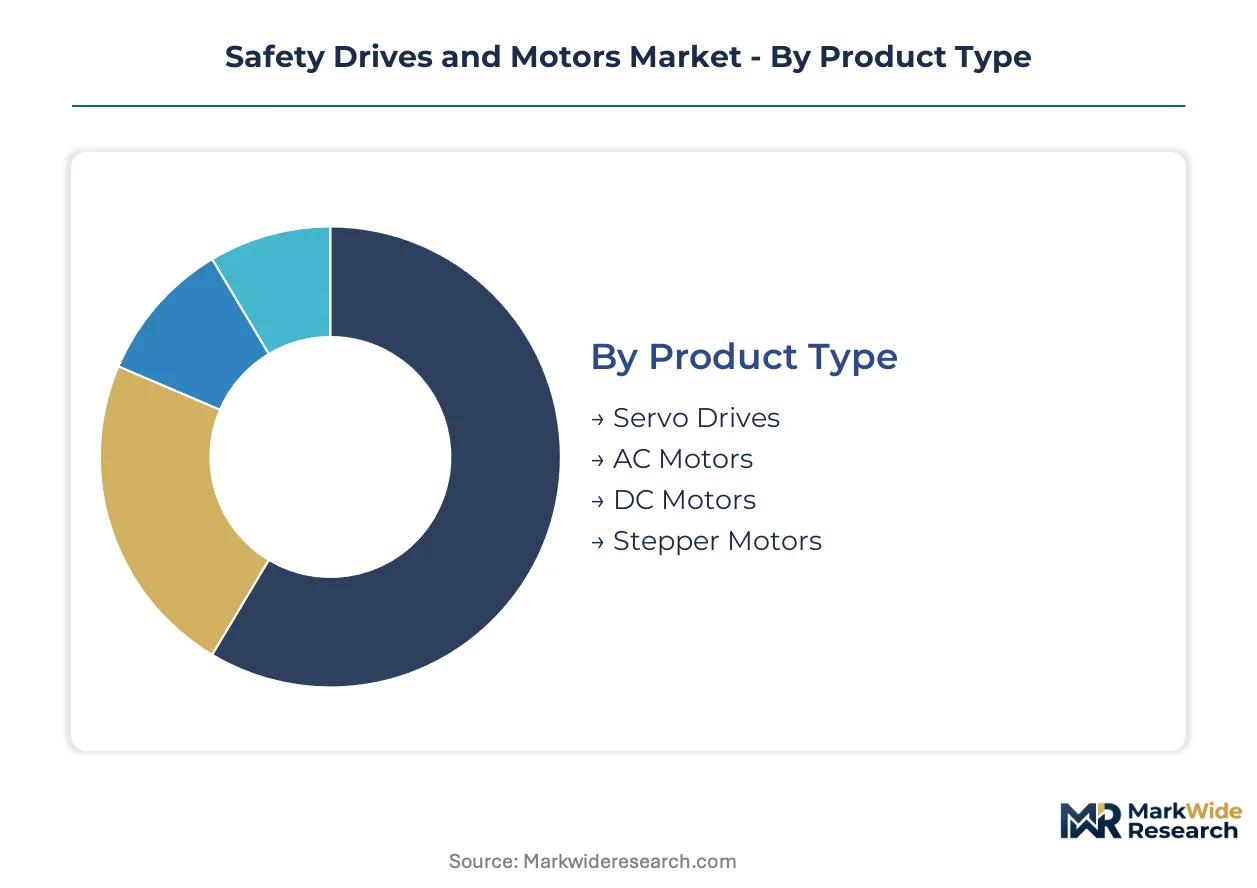
Segmentation in safety drives and motors reflects divergent technical requirements across motion control architectures. Certification tiers, communication protocols, and end-use hazard profiles create distinct procurement pathways that reshape supplier positioning.
Product Type:
Buyers prioritize torque density and STO integration density when selecting motor-drive pairings for hazardous machinery zones.
- Servo Drives:Closed-loop systems with embedded safe torque-off circuitry and dual-channel encoder feedback dominate battery gigafactory automation. German automotive OEMs specify these for human-robot collaboration cells where SIL 3 architectures prevent uncontrolled energy release.
- AC Motors:Induction and synchronous designs with integrated STO terminals command the broadest installed base across process industries. Mature supply chains and IEC 61800-5-2 compatibility sustain specification dominance in brownfield retrofit projects.
- DC Motors:Brushed and brushless configurations serve legacy material handling equipment requiring simple safe-stop functionality.
- Stepper Motors:Open-loop positioning systems with external safety monitoring suit low-cost packaging machinery.
AC Motors lead on scale; Servo Drives lead on momentum.
Technology:
Control interface selection determines wiring complexity, diagnostic granularity, and integration cost for distributed safety architectures.
- Digital:EtherCAT Safety and PROFIsafe protocols enable real-time diagnostic streaming over single-cable architectures. Industry 4.0 deployments in German precision engineering clusters favor these interfaces for centralized safety monitoring across multi-axis systems.
- Analog:Hardwired STO circuits and discrete safety I/O persist in cost-sensitive retrofit installations where legacy controllers resist digital migration.
- Hybrid:Mixed-signal architectures bridge analog position feedback with digital safety buses.
- Wireless:Safety-rated wireless I/O modules eliminate slip-ring maintenance in rotating machinery applications.
Digital interfaces are climbing the fastest; Analog retains residual share in mature industrial estates.
End User:
End-use safety audit intensity and liability exposure create tiered procurement specifications across industrial sectors.
- Automotive OEMs:Electrification and autonomous assembly mandates drive SIL-rated architecture demand. Battery cell assembly lines require STO-capable servo systems to protect technicians from high-voltage arc flash during collaborative robot operations.
- Industrial Machinery:General automation OEMs face EU Machinery Directive retrofit obligations. Metalworking and plastics processing equipment suppliers source Category 3 PLd certified drives to satisfy downstream automotive customer audits.
- Robotics:Collaborative robot manufacturers integrate safety drives at joint-level to achieve force-limiting compliance.
- HVAC Systems:Commercial building automation specifies safe torque-off for fan and damper actuators in occupied spaces.
Automotive OEMs anchor premium tier demand; Industrial Machinery spans the widest volume base.
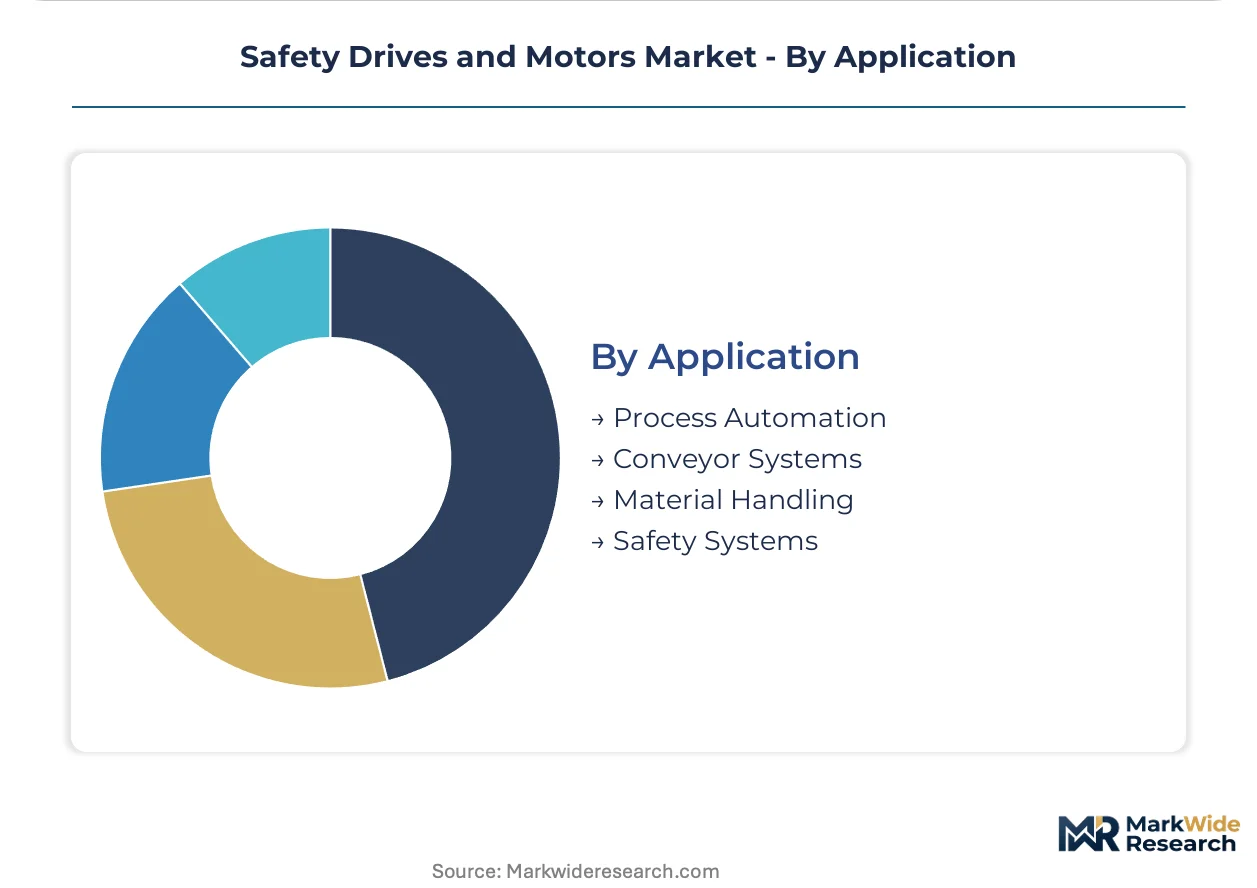
Application:
Motion safety requirements vary with personnel exposure duration and kinetic energy stored in moving masses.
- Process Automation:Continuous manufacturing lines demand predictive safety diagnostics to sustain uptime. Pharmaceutical batch processing in Germany specifies drives with integrated safe speed monitoring to prevent contamination during operator intervention.
- Conveyor Systems:Bulk material handling requires safe stop categories aligned with access frequency. Airport baggage systems and parcel sorting hubs deploy STO-capable distributed drives to isolate zones without full line shutdown.
- Material Handling:Automated guided vehicles extend safety motion requirements into mobile robotics with NHTSA functional safety expectations.
- Safety Systems:Dedicated emergency stop actuators and protective door drives serve as final control elements in safety instrumented functions.
Process Automation commands the steepest expansion trajectory; Conveyor Systems represent the most mature replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specification intensity for integrated safety motion systems while the United States extends compliance obligations through OSHA enforcement and NHTSA functional safety mandates for mobile robotics.
United States
Automotive electrification and battery gigafactory construction drive STO-capable servo demand across Michigan and Ohio manufacturing corridors. OSHA lockout/tagout enforcement tightens retrofit requirements for brownfield process automation. Detroit-area automotive OEMs mandate SIL-rated architectures for autonomous assembly lines.
Germany
Precision engineering clusters and automotive supply chains anchor European demand for Category 3 PLd certified drives. EU Machinery Directive enforcement compels retrofit investments across metalworking and plastics processing equipment. Bavarian automation suppliers concentrate R&D resources toward single-chip safety drive architectures.
China
Battery cell assembly and module integration lines require high-voltage hazard protection for collaborative robot operations. MIIT industrial upgrading programs accelerate domestic safety motion component certification. Yangtze River Delta manufacturing hubs source SIL-rated servo systems for export-oriented automotive production.
Japan
Collaborative robot manufacturers integrate joint-level safety drives to achieve force-limiting compliance for human-machine interaction. METI technology roadmaps prioritize predictive safety diagnostics integration. Nagoya-area automotive equipment suppliers specify compact mechatronic units with embedded safety logic.
India
PLI scheme incentives for automotive and electronics production create first-mover positioning for safety motion suppliers establishing local certification support. BIS machinery safety standards harmonize with IEC 61508 frameworks. Tamil Nadu and Maharashtra industrial corridors attract specification-intensive investments from German automation vendors.
Safety Drives and Motors Market Competitive Landscape
German producers anchor the premium-tier certification segment; Japanese specialists hold collaborative robotics integration expertise. The supplier base concentrates around three strategic archetypes: diversified industrial conglomerates with safety-certified drive portfolios, pure-play motion control specialists with deep SIL certification expertise, and emerging single-chip architecture disruptors. Competitive positioning hardens through certification-driven procurement consolidation and distributor capability differentiation.
Within the diversified industrial tier, ABB Ltd and Siemens AG occupy positions as archetypal full-range safety motion providers. Schneider Electric SE exemplifies the machine safety expansion specialist archetype. These three anchors represent the concentration of TÜV-qualified engineering resources and pre-qualified vendor status that automotive OEMs mandate for tier-by-tier supply chain audits.
| Leading Market Players |
|---|
| Rockwell Automation Inc. |
| ABB Ltd |
| Siemens AG |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Beckhoff Automation GmbH |
| KOLLMORGEN Corporation |
| Emerson Electric Co. |
| Bosch Rexroth AG |
| Others |
Value Network & Pricing Analysis
Neodymium and dysprosium price volatility from Chinese processing facilities cascades through servo motor manufacturing into three-tier pricing stratification across premium SIL 3 architectures, standard PLd-certified systems, and economy-grade STO-capable units. Tier 1 automotive OEMs absorb rare earth cost pass-throughs through long-term offtake agreements, while mid-tier industrial machinery buyers face spot-market exposure.
Pricing Analysis
Distributor margins compress as certification-driven procurement consolidates specification authority among TÜV-qualified distributors with in-house functional safety engineering. Three-tier pricing structure across premium, standard, and economy levels separates SIL 3 servo systems from PLd-certified AC motors and basic STO-capable stepper units. Price differentiation hinges on certification grade and volume scale, with automotive OEMs least sensitive and packaging machinery OEMs most responsive to cost compression. Pricing pressure stems from single-chip safety drive architectures electrifying competitive positioning at mid-tier price points.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German automotive clusters and Yangtze River Delta battery gigafactories, while authorized distributors serve specification-intensive mid-market segments. Manufacturing concentrates in Germany, China, and Japan for safety drive assembly, with rare earth magnet processing anchored in Chinese facilities. The supply chain draws from neodymium magnets, silicon steel laminations, and dual-channel encoder components. Single-source vulnerability in rare earth processing creates tariff exposure and input cost volatility. Distribution runs through certified system integrators with TÜV-qualified engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Safety Drives and Motors Market operates as a stable compounder anchored by mandatory EU Machinery Directive retrofit cycles and automotive electrification CAPEX that sustain replacement demand through economic cycles.
For Market Incumbents: Hedge rare earth cost volatility through backward integration into magnet recycling or long-term offtake agreements with Australian and Vietnamese rare earth projects. Defend certification moats by accelerating single-chip safety drive R&D to match emerging fabless competitors. Prioritize TÜV qualification capacity expansion as functional safety engineering scarcity constrains R&D throughput across the supplier base. For New Entrants and Emerging Players: Distributors with in-house SIL certification support represent the fastest path to specification authority in German automotive supply chains. Target India's PLI scheme corridors in Tamil Nadu and Maharashtra where first-mover certification infrastructure remains underdeveloped. White-space exists in AGV safety standardization for mobile robotics extending beyond traditional fixed machinery boundaries. For Investors and Strategic Acquirers: Consolidation pressure builds where TÜV-qualified engineering talent concentrates among a limited pool of specialized suppliers. The market supports long-term viability through embedded regulatory compliance mandates that sustain replacement demand. Acquisition targets should display deep SIL certification expertise and pre-qualified vendor status with automotive OEMs. Monitor harmonization gaps between regional safety standards as the signal for divergent certification cost impacts on export-oriented manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Chip Safety Architecture Development | Enables mid-tier suppliers to offer SIL-rated performance previously reserved for premium platforms from Siemens and ABB. |
| India Certification Infrastructure Buildout | Captures PLI scheme-driven demand from Tamil Nadu automotive corridors before German incumbents establish local TÜV support. |
| Rare Earth Magnet Recycling Investment | Reduces dependency on Chinese neodymium processing facilities facing export restriction risks. |
| AGV Safety Standardization Partnership | Extends addressable demand into mobile robotics as NHTSA functional safety expectations tighten. |
| Digital Twin Integration Platform | Compresses IEC 61508 validation cycles through virtual commissioning with predictive safety diagnostics. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, TÜV certification specialists, and aftermarket service heads grounded qualitative insights in operational realities across German automotive clusters and Yangtze River Delta manufacturing hubs. Secondary validation drew from IEC 61508 certification databases, EU Machinery Directive enforcement records, SEC filings of listed automation suppliers, and customs trade data for rare earth magnet flows. Bottom-up demand modeling from end-use CAPEX plans converged with top-down supply-side capacity assessments.
Segment-level outputs across servo drive, AC motor, DC motor, and stepper motor categories combined with technology interface splits and end-use industry allocations to generate consistent volume and value trajectories. CAGRs derived from regression analysis against automotive production forecasts, battery gigafactory construction pipelines, and regulatory retrofit obligation schedules. Rare earth price indices and certification timeline assumptions fed sensitivity testing across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to harmonization gaps between OSHA, EU Machinery Directive, and MIIT safety standards that could fragment certification requirements. Automotive electrification CAPEX cycles and rare earth supply concentration represent primary assumption risks that could revise trajectory. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
China AC Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
AC Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Cryogenic Air Separation Units (Asus) Market