
 Industrial Personnel and Burden Carriers [Electric] Market | 2026-2036
Industrial Personnel and Burden Carriers [Electric] Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Personnel and Burden Carriers [Electric] Market Foresight
OSHA workplace emissions guidelines and the EU F-Gas Regulation is decoupling electric burden carriers from diesel-equipment cost parity. Toyota Industries Corporation leverages captive battery supply chains to dominate Asian manufacturing corridors. Jungheinrich AG anchors European warehousing demand through dense service networks. Crown Equipment Corporation differentiates via automation-ready chassis architectures for assembly-line integration.
Industrial personnel and burden carriers (electric) are battery-powered, ride-on or walk-behind vehicles engineered to transport personnel, tow trailers, or move palletized loads at speeds typically below 25 km/h, with load capacities ranging from 500 kg to over 10,000 kg depending on configuration. These machines serve manufacturing floors, distribution centers, and airport tarmacs where zero-emission operation, compact turning radii, and operator visibility take priority over highway speed. Tugs and stand-up vehicles command the largest installed base across warehousing and logistics applications, while fuel cell variants represent the fastest-growing technology subset as hydrogen infrastructure matures in heavy-duty material handling environments. Li-ion battery configurations now capture the dominant share of new orders as thermal runaway protection standards and opportunity-charging protocols displace legacy lead-acid systems.
The EPA enforces Tier 4 Final emissions thresholds that effectively bar new diesel-powered burden carriers from indoor industrial use, while OSHA mandates operator training and equipment inspection regimens that favor electric platforms with simpler drivetrain maintenance profiles. BIS certification requirements in India and CE marking obligations under the EU Machinery Directive further fragment market access for non-compliant manufacturers. Stakeholders must monitor hydrogen fuel cell total-cost-of-ownership trajectories against advancing solid-state battery energy densities to time fleet transition strategies.
Market Dynamics
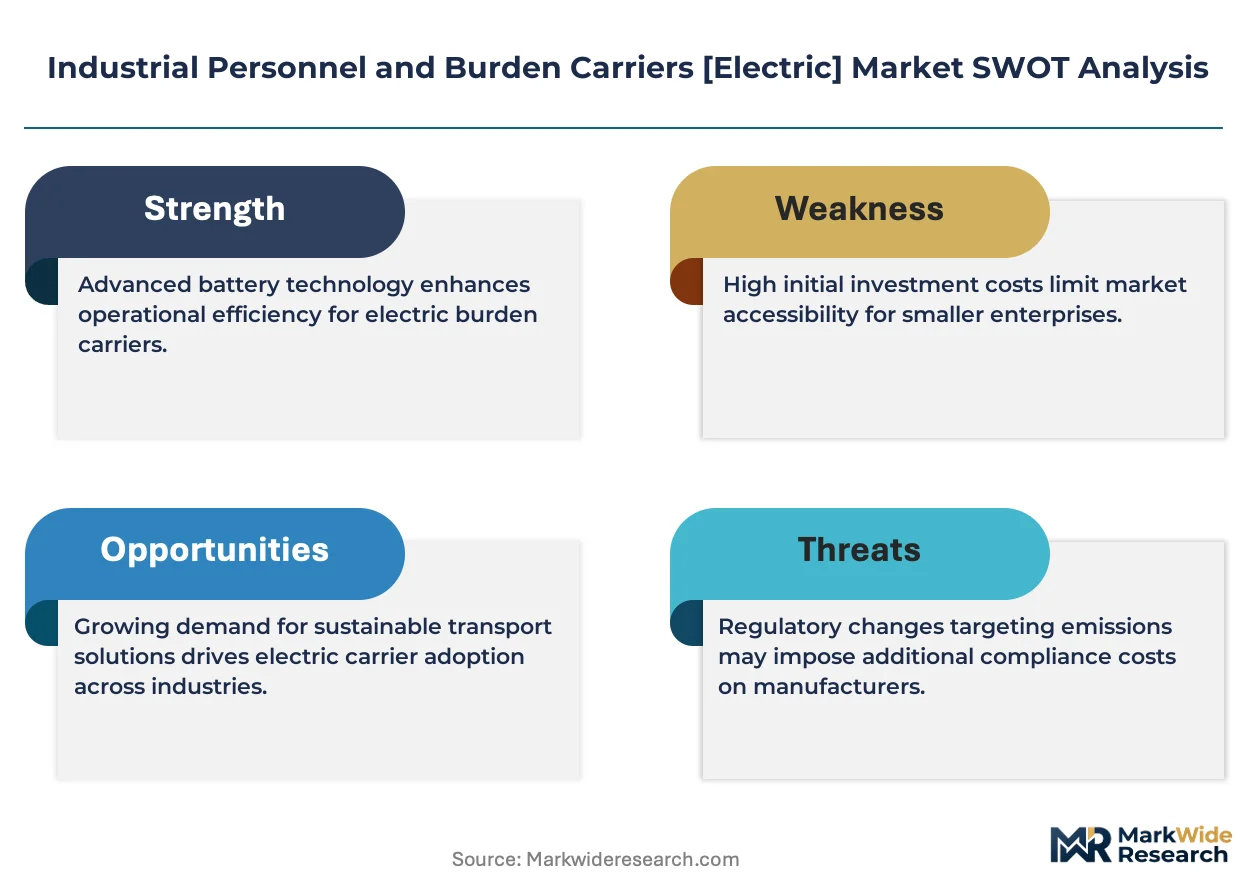
Li-ion battery chemistry is electrifying intralogistics fleets faster than hydrogen infrastructure can scale, compressing the competitive window for fuel cell variants while OSHA indoor air quality enforcement eliminates diesel alternatives from warehouse environments.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based cooling systems in material handling equipment accelerates electric platform adoption across German and French distribution hubs.
- Opportunity charging infrastructure:Warehouse operators in the United States deploy 350 kW DC fast-charging stations at dock doors, eliminating battery swap labor and extending fleet uptime.
- Airport ground support electrification:FAA emissions guidelines for tarmac equipment drive carrier replacements at Dallas-Fort Worth, Denver International, and Hartsfield-Jackson Atlanta.
Market Restraints
- Cobalt and lithium carbonate volatility:Cathode material spot price swings above forty percent annually destabilize OEM pricing models and fleet leasing contracts.
- Charging infrastructure capex concentration:Grid upgrade requirements for high-amperage depot installations concentrate deployment feasibility among large-scale 3PL operators with balance sheet capacity.
- Thermal runaway containment standards:UL 2580 certification complexity extends product development cycles and fragments supplier qualification across North American and European markets.
Strategic Opportunities
- India warehousing modernization:BIS certification alignment with IEC 61508 functional safety standards opens access to Mumbai-Pune and Bengaluru-Chennai industrial corridors.
- Autonomous towing convergence:Integration of LiDAR-based navigation with electric tug platforms enables lights-out manufacturing lines in automotive assembly plants.
- US Inflation Reduction Act credits:Commercial clean vehicle tax incentives offset thirty percent of acquisition costs for qualified battery-electric burden carriers deployed in qualified census tracts.
Industry Challenges
- High-voltage technician scarcity:OEM service networks struggle to recruit certified electricians capable of diagnosing 800-volt architectures outside major metropolitan maintenance hubs.
- Legacy fleet integration friction:Mixed-voltage charging protocols and incompatible telematics APIs complicate phased transitions from lead-acid to lithium-ion platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Personnel and Burden Carriers [Electric] Market |
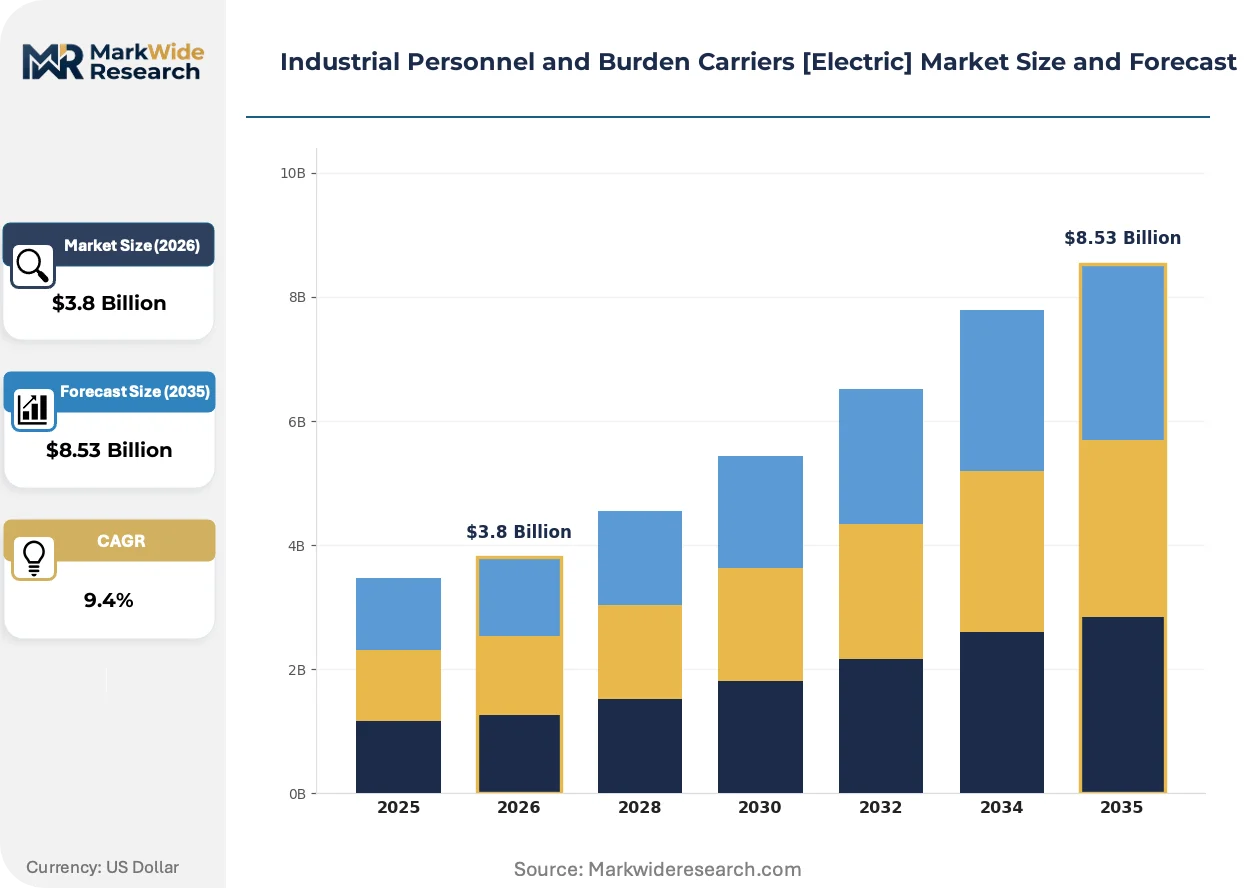
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Vehicles, Tugs, Carts, Stackers Technology: Electric Motors, Li-ion Batteries, Fuel Cells, Automation End User: Manufacturing, Warehousing, Retail, Logistics Application: Material Handling, Assembly Lines, Inventory Management, Transportation |
| Companies Covered | Toyota Industries Corporation, Kion Group AG, Jungheinrich AG, Crown Equipment Corporation, Hyster-Yale Group, Inc., Clark Material Handling Company, Club Car LLC, Motrec International Inc., Bradshaw Electric Vehicles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Personnel and Burden Carriers [Electric] Market Shifts & Advancements
Electrification is compressing equipment lifecycles and rewiring supplier relationships as battery chemistry becomes the primary value determinant in procurement decisions.
Solid-state battery prototypes with silicon-anode architectures are electrifying next-generation carrier designs by eliminating liquid electrolyte fire risks. German automotive suppliers pilot these cells in automated guided tug fleets operating twenty-four-hour shifts. The technology is compressing insurance premiums and enabling denser battery packaging within existing chassis footprints.
EPA Tier 4 Final emissions thresholds functionally prohibit new diesel burden carrier sales for indoor industrial use across the United States. The regulation forces rental fleet operators to accelerate electric unit procurement and retrain field service technicians on inverter diagnostics. California's CARB amendments extend these restrictions to off-road equipment under twenty-five horsepower, tightening compliance timelines for small-format carriers.
Power purchase agreement structures for depot charging are displacing capital-intensive on-site solar-plus-storage installations. Third-party energy service companies in the Netherlands and Belgium now bundle electricity supply with managed charging optimization for electric carrier fleets. This model concentrates procurement authority among sustainability-focused logistics directors at European grocery and pharmaceutical distributors.
Industrial Personnel and Burden Carriers [Electric] Market Segmentation
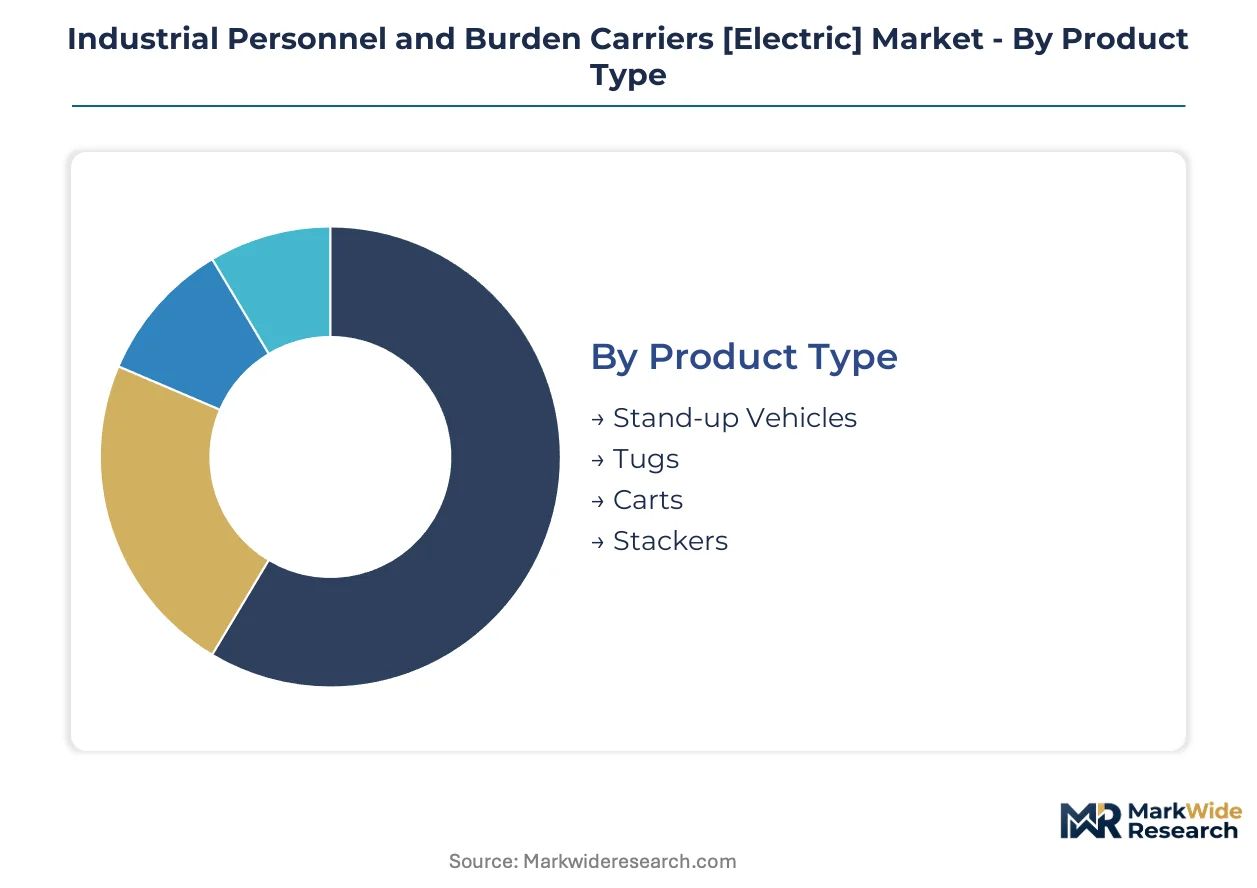
Segmentation in electric burden carriers separates volume-driven warehousing configurations from premium automation-ready platforms. Procurement patterns diverge sharply across battery chemistry, chassis architecture, and integration depth with facility management systems.
Product Type:
Volume concentration clusters in stand-up configurations for high-density warehousing, while premium pricing attaches to specialized tugs engineered for manufacturing line integration.
- Stand-up Vehicles:These ride-on platforms feature operator platforms elevated above battery packs, enabling rapid dock-to-rack transit in distribution centers exceeding 500,000 square feet. Demand concentrates among third-party logistics operators in Germany's Ruhr industrial corridor, where EU F-Gas Regulation compliance deadlines accelerate fleet replacement cycles.
- Tugs:Tow tractors with fifth-wheel couplings pull trailer trains up to 10,000 kg across automotive assembly plants and airport tarmacs. German automotive suppliers at Wolfsburg and Stuttgart facilities specify 800-volt architectures for continuous 24-hour production schedules.
- Carts:Platform carriers with flat decks transport palletized loads or custom fixtures through narrow manufacturing aisles. Japanese electronics assemblers favor compact turning radii under 1.5 meters for cleanroom material flows.
- Stackers:Counterbalanced units combine horizontal transport with vertical lifting to 6 meters, eliminating separate forklift requirements in retail backrooms. French grocery distributors deploy these for store replenishment from urban micro-fulfillment centers.
Today's leader: Stand-up Vehicles. Tomorrow's challenger: Tugs.
Technology:
Cost tier separation runs deepest here—lead-acid legacy systems anchor rental fleet economics while solid-state prototypes command prototype premiums from early adopters.
- Electric Motors:AC induction and permanent magnet synchronous drives deliver 5-15 kW continuous output with regenerative braking. Permanent magnet designs from German suppliers dominate European manufacturing corridors due to efficiency mandates under EU Green Deal industrial benchmarks.
- Li-ion Batteries:NMC and LFP cathode chemistries have displaced lead-acid across new orders, with opportunity-charging protocols eliminating shift-change battery swaps. OSHA indoor air quality enforcement in US distribution centers removed diesel alternatives from consideration.
- Fuel Cells:Proton exchange membrane systems with 350-bar hydrogen storage extend range beyond 200 km for airport ground support and heavy manufacturing. FAA emissions guidelines at Dallas-Fort Worth and Denver International drive pilot deployments despite infrastructure gaps.
- Automation:LiDAR-equipped autonomous navigation modules integrate with warehouse management systems for lights-out operations. Automotive assembly plants in Stuttgart and Munich specify these for just-in-sequence component delivery.
Li-ion Batteries capture procurement volume. Fuel Cells claim the steepest expansion trajectory as hydrogen infrastructure matures.
End User:
Application maturity separates established warehousing demand from emerging retail micro-fulfillment requirements.
- Manufacturing:Assembly-line tugs with AGV compatibility serve automotive, aerospace, and electronics producers requiring synchronized material delivery. German industrial clusters specify CE-marked platforms with IEC 61508 functional safety certification.
- Warehousing:High-velocity distribution centers deploy stand-up vehicles with 350 kW opportunity charging at dock doors. US Inflation Reduction Act credits offset acquisition costs for qualified battery-electric units in designated census tracts.
- Retail:Compact stackers and carts enable store-backroom inventory positioning without aisle width expansion. French and Belgian grocery chains prioritize units under 1 meter width for urban store footprints.
- Logistics:Third-party operators with multi-client contracts demand telematics interoperability across mixed-voltage fleets. BIS certification requirements in India filter supplier qualification for Mumbai-Pune corridor modernization.
Warehousing commands installed base dominance. Retail logistics emerges as the fastest-climbing demand category.
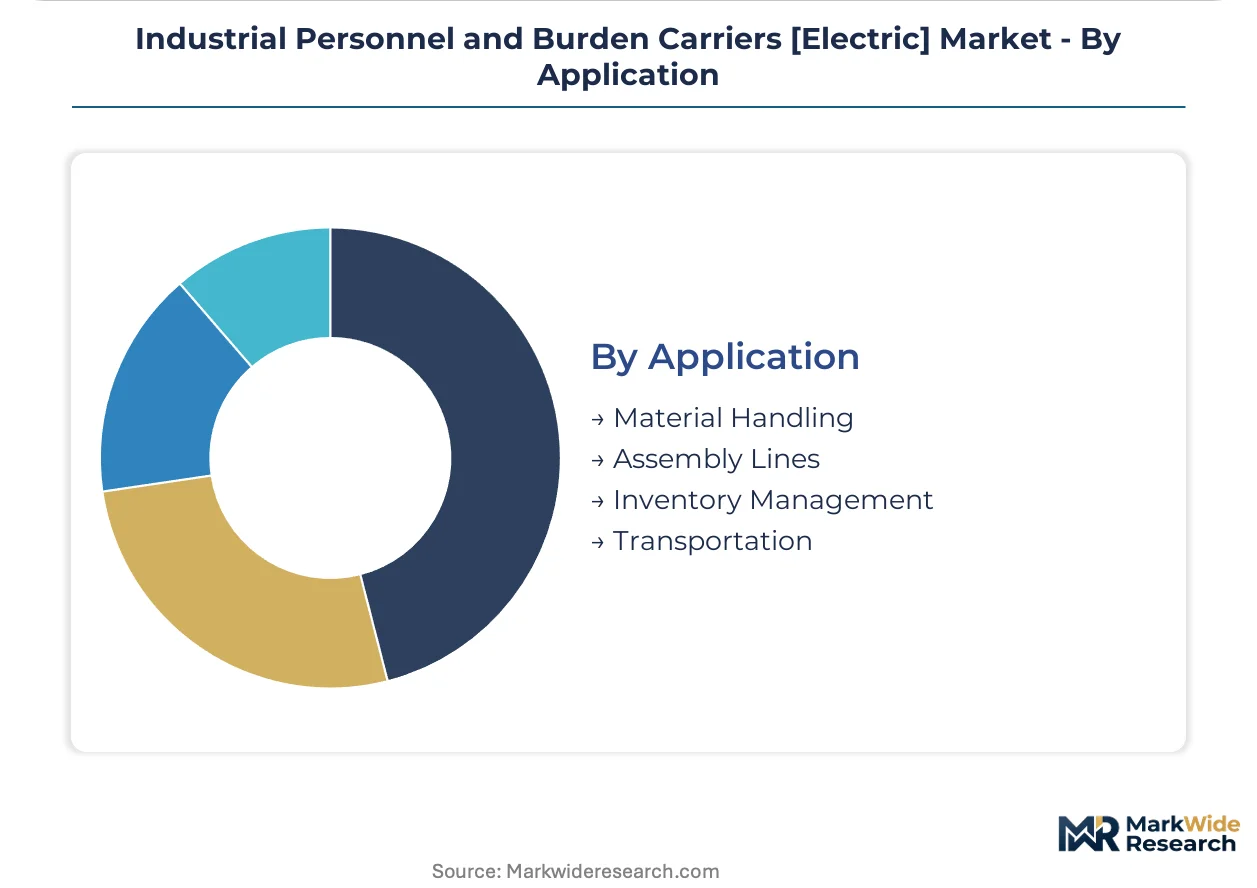
Application:
Margin structure inverts between commoditized horizontal transport and premium vertical-lifting integration.
- Material Handling:Pallet movement, trailer towing, and bulk container transport constitute the core revenue pool. German and French distribution hubs specify IP54-rated enclosures for cold-chain pharmaceutical handling.
- Assembly Lines:Synchronized tug fleets deliver components to production stations at 5-8 km/h with millimeter positioning accuracy. Stuttgart automotive suppliers require ISO 26262-aligned control systems for safety-critical operations.
- Inventory Management:Stackers and order pickers enable high-density storage with 6-meter vertical reach. Dutch pharmaceutical distributors deploy these for temperature-controlled vault access.
- Transportation:Airport ground support equipment moves baggage carts and catering trucks across tarmac environments. FAA guidelines at Hartsfield-Jackson Atlanta mandate zero-emission replacements for diesel units under 25 horsepower.
Material Handling anchors revenue concentration. Assembly Lines present the premium expansion path.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial electrification in intralogistics during the 1980s, establishing the regulatory and engineering foundations that shaped modern electric burden carrier design. The industry's geographic footprint now spans manufacturing clusters where zero-emission mandates and dense warehousing infrastructure converge.
Germany
Automotive assembly plants at Wolfsburg and Stuttgart drive demand for 800-volt tug architectures capable of continuous 24-hour operation. The EU F-Gas Regulation accelerates phase-outs of hydrofluorocarbon-dependent equipment across Ruhr industrial corridor distribution centers. North Rhine-Westphalia hosts Europe's densest concentration of third-party logistics operators modernizing fleets ahead of 2030 compliance deadlines.
United States
Airport ground support electrification at Dallas-Fort Worth, Denver International, and Hartsfield-Jackson Atlanta creates concentrated replacement demand under FAA emissions guidelines. OSHA indoor air quality enforcement removes diesel alternatives from warehouse environments nationwide. California's CARB amendments extend Tier 4 Final restrictions to off-road equipment under twenty-five horsepower, tightening timelines for small-format carrier procurement in the Inland Empire logistics cluster.
China
Battery supply chain concentration in the Yangtze River Delta enables cost-competitive domestic production of lithium-ion platforms. The country's national industrial regulator enforces dual carbon goals that pressure manufacturing facilities toward electrified material handling. Shenzhen and Dongguan electronics assemblers specify compact turning radii under 1.5 meters for cleanroom material flows.
India
BIS certification alignment with IEC 61508 functional safety standards filters supplier qualification for Mumbai-Pune corridor warehouse modernization. The country's national industrial infrastructure incentive program subsidizes domestic manufacturing of electric material handling equipment. Bengaluru-Chennai automotive suppliers pilot automated guided tug fleets for just-in-sequence component delivery.
Japan
Permanent magnet synchronous drive suppliers dominate efficiency mandates under national industrial benchmarks administered by METI. Electronics manufacturers in the Chubu region favor platform carriers with IP54-rated enclosures for semiconductor cleanroom operations. Toyota City anchors captive battery supply chain integration for regional manufacturing corridor deployment.
Industrial Personnel and Burden Carriers [Electric] Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive battery supply chains. Market concentration clusters among three to five integrated manufacturers capable of vertical control over cell chemistry and chassis fabrication. Strategic archetypes separate conglomerate-backed platform suppliers, specialized automation-ready chassis architects, and regional rental fleet operators. Dominant competitive moves include backward integration into lithium cell production and geographic expansion through energy-service partnership models.
Among diversified industrial manufacturers, Toyota Industries Corporation exemplifies the conglomerate-backed archetype with integrated battery supply chain control. Jungheinrich AG anchors the European service-network-dependent tier through dense aftermarket presence. Crown Equipment Corporation occupies a position representing automation-ready chassis specialization for assembly-line integration. These three entities collectively illustrate the strategic segmentation between supply chain-integrated, service-intensive, and technology-differentiated competitive positions.
| Leading Market Players |
|---|
| Toyota Industries Corporation |
| Kion Group AG |
| Jungheinrich AG |
| Crown Equipment Corporation |
| Hyster-Yale Group, Inc. |
| Clark Material Handling Company |
| Club Car LLC |
| Motrec International Inc. |
| Bradshaw Electric Vehicles |
| Others |
Supply & Pricing Matrix
Cobalt and lithium carbonate spot price swings above forty percent annually cascade through NMC and LFP cathode chemistries into three-tier pricing structures across premium, standard, and economy equipment tiers. OEMs serving German automotive assembly plants at Wolfsburg absorb volatility through long-term offtake contracts, while rental fleet operators in the United States face compressed margins on spot-market battery procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automation-ready chassis with LiDAR integration from basic stand-up configurations. Certification grade under UL 2580 thermal runaway standards and ISO 26262 functional safety alignment command fifteen to twenty percent premiums over CE-marked baseline units. Pricing pressure stems from cobalt spot market volatility destabilizing OEM pricing models. Third-party logistics operators with multi-client contracts exhibit highest price sensitivity, while German automotive suppliers prioritize specification compliance over acquisition cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Wolfsburg and Stuttgart assembly plants, while distributor networks serve fragmented warehousing operators across the Ruhr corridor. Cell production concentrates in China, South Korea, and Japan, with cathode active material processing anchored in the Democratic Republic of Congo and Indonesia. The supply chain draws from permanent magnet rare earth elements and high-purity electrolyte solvents. Single-source vulnerability in cobalt hydroxide refining creates exposure to export restriction shocks. Distribution runs through captive battery supply chains at Toyota Industries Corporation and third-party logistics partnerships at Jungheinrich AG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as warehousing operators shift procurement criteria from capital cost minimization toward total-cost-of-ownership optimization including opportunity-charging infrastructure and telematics integration depth.
For Market Incumbents: Extend service network density into secondary industrial corridors before emerging automation specialists capture aftermarket revenue pools. Threats from fuel cell variants with 350-bar hydrogen storage architectures intensify as Denver International and Dallas-Fort Worth airport infrastructure matures. Priority levers include backward integration into solid-state battery prototyping and certification pre-alignment with IEC 61508 functional safety standards for Indian market access. For New Entrants and Emerging Players: Digital-channel routes through energy-service companies bundling electricity supply with managed charging optimization offer rapid European grocery and pharmaceutical distributor penetration. White-space targets concentrate in Indian Mumbai-Pune corridor warehouse modernization and US retail micro-fulfillment center compact stacker deployment. The most penetrable segment is mid-size third-party logistics operators with fifty to two hundred unit fleet scales lacking in-house electrification expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where captive battery supply chain control determines margin sustainability against spot-market cathode material exposure. Long-term viability favors conglomerate-backed platform suppliers with vertical integration depth over pure-play chassis architects vulnerable to cell chemistry transition costs. Acquisition target archetype: regional rental fleet operators with dense installed bases and retrofit-ready maintenance networks. Signal to watch: hydrogen fuel cell total-cost-of-ownership breakeven against solid-state lithium-ion energy density improvements in airport ground support applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Chemistry | Captive lithium supply chains insulate Toyota Industries Corporation from cobalt spot volatility. |
| Opportunity Charging Infrastructure Deployment | 350 kW DC fast-charging at dock doors eliminates battery swap labor for US distribution hubs. |
| Automation-Ready Chassis Certification | LiDAR-equipped platforms capture Stuttgart automotive assembly plant just-in-sequence contracts. |
| Regional Service Network Expansion | Dense aftermarket presence anchors Jungheinrich AG's Ruhr corridor fleet replacement cycles. |
| Hydrogen Fuel Cell Pilot Programs | FAA emissions guidelines at Hartsfield-Jackson Atlanta validate zero-emission tarmac equipment viability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at German automotive plants, warehouse operations managers at Ruhr corridor third-party logistics operators, OEM procurement teams specifying 800-volt architectures, and aftermarket service heads managing mixed-voltage fleet transitions. Secondary validation drew from EPA Tier 4 Final enforcement documentation, EU F-Gas Regulation compliance timelines, FAA emissions guidelines for ground support equipment, and BIS certification alignment with IEC 61508 standards. Bottom-up unit deployment estimates and top-down industrial electrification spending trajectories were cross-referenced for triangulation.
Segment-weighting approaches distributed volume and value projections across product type, battery chemistry, end-use industry, and application depth with facility management systems. The analytical framework modeled stand-up vehicle, tug, cart, and stacker configurations separately against manufacturing, warehousing, retail, and logistics demand verticals. CAGRs were derived from fleet replacement cycle compression under regulatory deadlines and opportunity-charging infrastructure penetration curves. Industry-specific inputs included OSHA indoor air quality enforcement intensity and EU Green Deal industrial benchmark adoption rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization or hydrogen fuel cell infrastructure acceleration would alter the outlook. Forecasts reflect base-case assumptions regarding cobalt price stabilization, charging infrastructure capex availability among large-scale operators, and thermal runaway containment standard harmonization across North American and European markets. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Safety Drives and Motors Market
Industrial Motors
High Voltage Motor Sleeve Bearing Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Permanent Magnet Synchronous Motors Market
Industrial Motors
Global Switched Reluctance Motor Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Vietnam Air Compressor Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Spargers Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Global Sliding Vane Air Motor Market