
 Global Switched Capacitor Filter Market | 2026-2036
Global Switched Capacitor Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Switched Capacitor Filter Market Intelligence
The premium commodity split in switched capacitor filters is consolidating around precision versus cost-optimized die footprints. Analog Devices leverages monolithic integration to sustain leadership in instrumentation-grade filters. Texas Instruments anchors its position through dense CMOS libraries for audio processing codecs. Maxim Integrated differentiates via low-power architectures that compete directly with discrete RC alternatives in portable equipment.
A switched capacitor filter employs clocked MOS switches and capacitors to emulate resistive elements, achieving programmable corner frequencies from hertz to megahertz ranges without precision passive components. The architecture eliminates laser-trimming steps, reducing wafer processing cost for band-pass and low-pass variants in signal conditioning front ends. Low-pass filters dominate volume shipments for anti-aliasing duties in data acquisition chains, while band-pass configurations capture margin in radar IF strips where Q-factor stability determines detection thresholds. CMOS technology leads fabrication economics, though silicon-germanium variants extend frequency reach for microwave communications modules.
FCC emission limits and EU RoHS substance restrictions shape substrate material choices and package metallurgy for filters entering North American and European telecom infrastructure. ETSI harmonized standards for 5G NR equipment in Europe and FDA electromagnetic compatibility rules for medical instrumentation in the United States create parallel certification pathways that vendors must navigate. Stakeholders should monitor foundry capacity allocation for specialty analog processes, as switched capacitor designs compete for 180nm and 130nm CMOS line space against power management and sensor interface products.
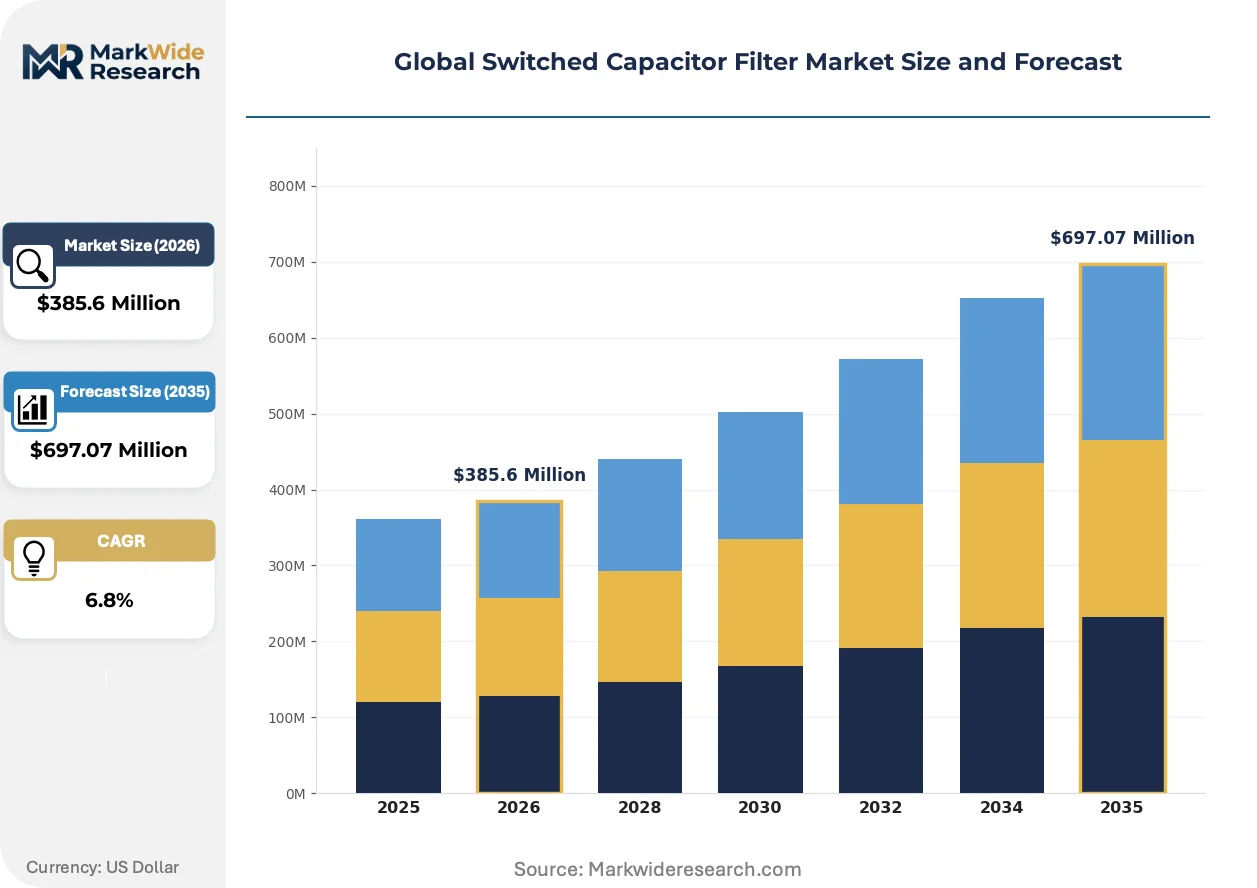
Market Dynamics
CMOS process shrinks below 180nm are compressing die footprints while silicon-germanium integration extends frequency reach, forcing foundries to allocate scarce analog line capacity among competing precision analog products.
Growth Catalysts
- 5G NR infrastructure deployment:FCC emission limits and ETSI harmonized standards for baseband processing are mandating precision filtering in macro and small-cell installations across the United States and Europe.
- EU RoHS substance restrictions:Lead-free package metallurgy requirements are accelerating migration from discrete RC networks to monolithic switched capacitor alternatives in medical instrumentation bound for European markets.
- Defense electronics procurement:Radar IF strip modernization programs in China, Germany, and the United States are specifying band-pass configurations with stable Q-factors for detection threshold reliability.
Market Restraints
- Foundry capacity scarcity:180nm and 130nm CMOS lines face allocation competition from power management ICs and sensor interfaces, extending lead times for specialty analog processes.
- Discrete RC substitution economics:Cost-optimized consumer audio applications continue selecting passive resistor-capacitor networks below certain price thresholds, capping penetration in portable equipment segments.
- Silicon-germanium process complexity:Heterojunction bipolar transistor integration demands specialized epitaxial growth equipment, limiting supplier base for microwave communications variants.
Strategic Opportunities
- India telecom infrastructure:TRAI spectrum allocation policies and domestic manufacturing incentives under the PLI scheme are creating demand for integrated filter banks in base station equipment.
- Automotive radar module convergence:Fusion of 77GHz front-ends with switched capacitor IF processing is enabling single-chip solutions for adaptive cruise control systems.
- Japan medical device certification:PMDA electromagnetic compatibility rules for diagnostic imaging equipment are specifying programmable corner frequencies that favor clocked MOS architectures over laser-trimmed alternatives.
Industry Challenges
- Analog-mixed signal design expertise:Scarcity of engineers proficient in switched capacitor noise analysis and clock feedthrough mitigation is constraining product development velocity at fabless specialists.
- FDA electromagnetic compatibility certification:Extended timeline for medical instrumentation approval in the United States is compressing product launch windows relative to consumer electronics cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Switched Capacitor Filter Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Pass Filter, High-Pass Filter, Band-Pass Filter, Band-Stop Filter, Notch Filter Technology: CMOS, BiCMOS, Bipolar Junction Transistor, GaAs, Silicon-Germanium Application: Wireless Communications, Radar Systems, Audio Processing, Signal Conditioning, Instrumentation End User: Telecommunication Equipment Manufacturers, Aerospace & Defense, Consumer Electronics, Test & Measurement, Semiconductor Fabricators |
| Companies Covered | Analog Devices, Texas Instruments, Siemens AG, Maxim Integrated, NXP Semiconductors, Eaton Corporation, Skyworks Solutions, TE Connectivity, Encore Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Switched Capacitor Filter Market Strategic Shifts & Innovations
Precision analog integration is compressing traditional component hierarchies, with programmable corner frequency architectures displacing fixed-function alternatives across instrumentation and communications verticals.
Silicon-germanium BiCMOS processes are consolidating microwave-frequency switched capacitor designs into single-die solutions for 5G millimeter-wave baseband processing. Defense contractors in Germany and the United States are qualifying these variants for radar IF strips where thermal stability determines operational margins. The technology is consolidating previously discrete amplifier-filter chains into monolithic signal conditioning front ends.
ETSI harmonized standards for 5G NR equipment in Europe are mandating stricter out-of-band emission controls that programmable switched capacitor architectures satisfy more readily than fixed passive networks. Base station OEMs are redesigning RF signal chains to incorporate clock-tunable filtering that adapts to regional spectrum allocations. Medical instrumentation vendors serving European markets are parallel-tracking CE marking and FDA submissions to maintain synchronized product release schedules.
Defense procurement offices in China, Germany, and the United States are consolidating vendor lists for integrated filter banks, awarding multi-year contracts to suppliers with captive analog process development capabilities. This concentration is compressing qualification timelines for second-source alternatives and elevating importance of foundry relationships with demonstrated radiation-hardened process expertise. Telecom infrastructure procurement in India and Japan is following similar consolidation patterns, though with greater emphasis on domestic content requirements.
Global Switched Capacitor Filter Market Segmentation
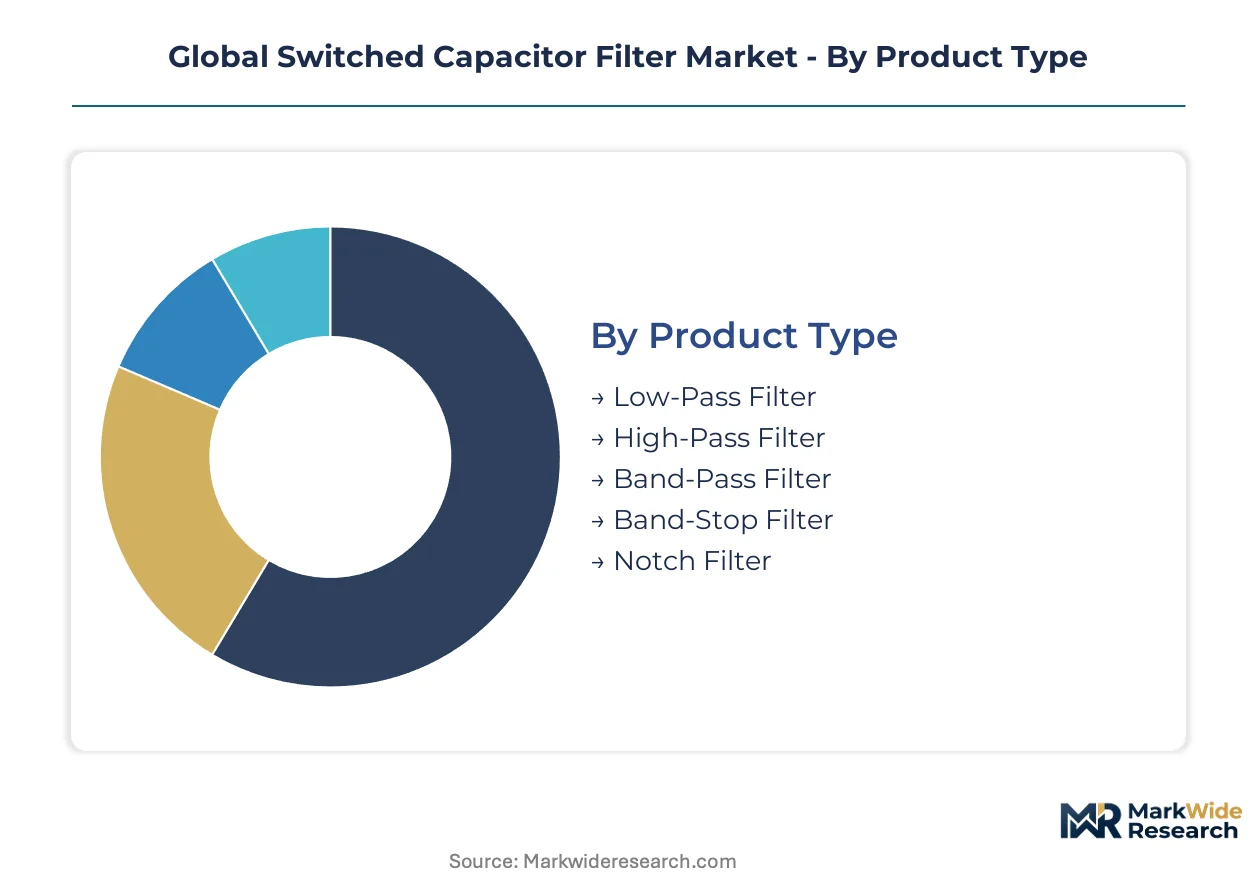
Switched capacitor filter architectures fragment across multiple technical and commercial dimensions. Each segmentation layer reveals distinct procurement patterns, process dependencies, and margin structures that shape competitive positioning.
Product Type:
Supply concentration in precision analog foundries favors architectures with established design libraries and characterized noise models.
- Low-Pass Filter:Anti-aliasing front ends in data acquisition chains employ clocked MOS switches to eliminate precision passive components. Telecommunication Equipment Manufacturers in China and Germany source these for 5G baseband processing where FCC emission limits and ETSI harmonized standards mandate sharp roll-off characteristics.
- Band-Pass Filter:Radar IF strips require stable Q-factor performance across temperature extremes. Aerospace & Defense procurement offices in the United States specify these for detection threshold reliability in modernized surveillance systems.
- High-Pass Filter:DC offset removal in instrumentation amplifiers leverages switched capacitor architectures for programmable corner frequencies.
- Band-Stop Filter:Narrow interference rejection in wireless communications modules employs clock-tunable notching for regional spectrum compliance.
- Notch Filter:Medical instrumentation for diagnostic imaging uses these to suppress power line harmonics under FDA electromagnetic compatibility rules.
Low-Pass Filter absorbs the bulk of installed capacity; Band-Pass Filter is expanding most quickly.
Technology:
Process maturity curves determine which technologies capture volume versus premium positioning.
- CMOS:Dominant fabrication economics for 180nm and 130nm nodes with dense digital integration capability. Foundry capacity allocation competition from power management ICs extends lead times for specialty analog processes.
- Silicon-Germanium:Heterojunction bipolar transistor integration extends frequency reach into microwave communications. Defense contractors in Germany and the United States qualify these for radar IF strips where thermal stability determines operational margins.
- BiCMOS:Combines CMOS density with bipolar precision for mixed-signal instrumentation front ends.
- Bipolar Junction Transistor:Legacy processes sustain niche demand for ultra-low noise audio applications.
- GaAs:Millimeter-wave communications modules employ these for front-end filtering prior to baseband conversion.
CMOS commands the dominant share of wafer starts; Silicon-Germanium is climbing the fastest as 5G millimeter-wave deployments accelerate.
Application:
End-use requirements for programmable corner frequencies versus fixed specifications drive architecture selection.
- Wireless Communications:5G NR infrastructure demands precision filtering for macro and small-cell installations. Base station OEMs in India under TRAI spectrum policies and PLI scheme incentives are redesigning RF signal chains for clock-tunable adaptation.
- Radar Systems:Modernization programs in China, Germany, and the United States specify integrated filter banks with stable Q-factors.
- Audio Processing:Portable equipment segments face substitution pressure from discrete RC networks below certain price thresholds.
- Signal Conditioning:Industrial automation and medical instrumentation require programmable architectures that eliminate laser-trimming steps.
- Instrumentation:Test & Measurement equipment vendors parallel-track CE marking and FDA submissions for synchronized product releases.
Wireless Communications accounts for the largest revenue pool; Radar Systems is gaining share fastest on defense procurement concentration.
End User:
Procurement consolidation patterns favor suppliers with captive analog process development and radiation-hardened expertise.
- Telecommunication Equipment Manufacturers:Multi-year contracts for integrated filter banks concentrate on vendors with demonstrated foundry relationships. India's domestic manufacturing incentives and Japan's PMDA electromagnetic compatibility rules create parallel certification requirements.
- Aerospace & Defense:Vendor list consolidation in China, Germany, and the United States compresses qualification timelines for second-source alternatives.
- Consumer Electronics:Cost-optimized audio codecs select discrete RC networks where price thresholds permit.
- Test & Measurement:Programmable corner frequency requirements favor clocked MOS architectures over laser-trimmed alternatives.
- Semiconductor Fabricators:Captive production of specialty analog processes competes for 180nm and 130nm CMOS line space.
Telecommunication Equipment Manufacturers represent the primary demand anchor; Aerospace & Defense is expanding most quickly on modernization program funding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's electronics corridor anchors CMOS foundry capacity for switched capacitor filter production serving 5G baseband processing demand.
United States
Defense electronics procurement and FDA electromagnetic compatibility rules for medical instrumentation drive precision filter demand. FCC emission limits for 5G NR infrastructure mandate sharp roll-off characteristics in macro and small-cell installations. Greater Boston's defense contractor cluster qualifies integrated filter banks for radar IF strip modernization programs.
China
MIIT spectrum policies and domestic manufacturing scale support 5G base station deployment across multiple provincial markets. NMPA medical device regulations and dual carbon goals shape substrate material selections for instrumentation-grade filters. Yangtze River Delta foundries allocate 180nm and 130nm CMOS line space for specialty analog processes competing with power management ICs.
Germany
ETSI harmonized standards for 5G NR equipment and EU RoHS substance restrictions create parallel certification requirements for telecom and medical filter applications. KBA automotive safety regulations intersect with radar module convergence for adaptive cruise control systems. Bavaria's precision analog design houses supply integrated filter banks to defense and industrial automation OEMs.
India
TRAI spectrum allocation policies and PLI scheme domestic manufacturing incentives drive base station equipment demand. CEA power sector regulations and BIS standards shape procurement specifications for grid-connected instrumentation. Bengaluru's telecom hardware cluster redesigns RF signal chains for clock-tunable filtering adaptation to regional spectrum allocations.
Japan
METI industrial policy and PMDA electromagnetic compatibility rules for diagnostic imaging equipment specify programmable corner frequencies. JIS standards harmonization with ETSI frameworks enables synchronized CE marking submissions for European market access. Tokyo-Osaka industrial corridor vendors parallel-track medical device certifications to compress product launch windows.
Global Switched Capacitor Filter Market Key Industry Players
Premium-margin players sit above commodity-margin players across process technology and application specialization dimensions. The vendor base concentrates around captive analog foundry relationships and radiation-hardened process expertise, with defense procurement offices compressing qualification timelines for second-source alternatives. Three archetypes dominate: integrated device manufacturers with monolithic CMOS libraries, fabless specialists leveraging silicon-germanium BiCMOS processes, and diversified component suppliers serving cost-optimized consumer audio segments. Competitive moves center on foundry capacity reservations for 180nm and 130nm nodes and strategic partnerships with telecom infrastructure OEMs for multi-year integrated filter bank contracts.
Within the integrated device manufacturer tier, Analog Devices and Texas Instruments exemplify contrasting positioning strategies for instrumentation-grade versus audio processing codec applications. Maxim Integrated occupies a distinct position in low-power architecture development competing with discrete RC alternatives. Among European-based diversified technology groups, Siemens AG anchors industrial automation and medical instrumentation filter demand through captive system integration capabilities.
| Leading Market Players |
|---|
| Analog Devices |
| Texas Instruments |
| Siemens AG |
| Maxim Integrated |
| NXP Semiconductors |
| Eaton Corporation |
| Skyworks Solutions |
| TE Connectivity |
| Encore Electronics |
| Others |
Cost & Logistics Intelligence
Defense electronics procurement offices in China, Germany, and the United States anchor demand for instrumentation-grade switched capacitor filters, concentrating purchasing power around multi-year integrated filter bank contracts that favor value-based pricing tied to detection threshold reliability and radiation-hardened process guarantees.
Pricing Analysis
Value-based pricing anchored to yield performance in radar IF strips and 5G baseband processing dominates premium tiers. Three-tier pricing structure across instrumentation-grade, industrial-standard, and cost-optimized consumer levels separates vendors by certification grade and captive foundry access. Cost compression in portable audio codecs is intensifying because discrete RC networks undercut monolithic alternatives below specific die-size thresholds. Telecommunication Equipment Manufacturers exhibit lowest price sensitivity due to multi-year procurement horizons, while Consumer Electronics OEMs drive hardest bargain on per-unit costs.
Supply Chain Analysis
Single-source vulnerability sits with 180nm and 130nm CMOS specialty analog capacity concentrated in Taiwan, China, and South Korea. Heterojunction bipolar transistor epitaxial equipment for silicon-germanium variants draws from a limited installed base of foundry partners. Tariff exposure on packaged filters entering North American telecom infrastructure creates margin pressure for non-captive suppliers. Distribution runs through authorized distributors serving defense contractors and direct OEM relationships for high-volume base station equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry capacity scarcity for 180nm and 130nm CMOS specialty analog processes props pricing power for incumbents with captive wafer supply, constraining volume expansion for second-source alternatives.
For Market Incumbents: Hedge against silicon-germanium BiCMOS supply constraints by securing multi-year epitaxial growth equipment contracts with foundry partners in Taiwan and South Korea. Reinforce position in radar IF strips through radiation-hardened process qualification with defense procurement offices in Germany and the United States, while monitoring discrete RC substitution pressure in portable audio segments.
For New Entrants and Emerging Players: A price-point gap between precision instrumentation-grade filters and economy consumer codecs creates entry space for mid-tier industrial automation suppliers. Target India's PLI scheme beneficiaries with clock-tunable filter banks for base station RF signal chains. Pursue fabless partnership models with Yangtze River Delta foundries to bypass captive capacity constraints.
For Investors and Strategic Acquirers: The window for entry favors fabless specialists with silicon-germanium BiCMOS design libraries and demonstrated ETSI certification track records. Long-term viability rests on consolidation of analog-mixed signal engineering talent pools and foundry relationship depth. Watch for TRAI spectrum policy shifts in India as inflection indicator for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Reservation | 180nm and 130nm CMOS line commitments with Taiwan-based specialty analog foundries secure wafer supply against power management IC competition. |
| Radiation-Hardened Process Qualification | Defense contractor certification in Germany and the United States opens multi-year integrated filter bank procurement channels. |
| Silicon-Germanium BiCMOS Migration | Single-die consolidation of amplifier-filter chains addresses 5G millimeter-wave baseband processing frequency requirements. |
| India PLI Scheme Alignment | Domestic manufacturing incentives under TRAI spectrum policies position suppliers for base station OEM redesign cycles. |
| Discrete RC Substitution Defense | Low-power architecture development competes directly with passive networks in portable equipment price-sensitive segments. |
Research Approach
Independent corroboration across primary interviews with analog-mixed signal design engineers, defense procurement officers, telecom infrastructure OEM procurement teams, and foundry process development leads underwrites the qualitative findings. Secondary validation draws from SEC 10-K filings of precision analog semiconductor suppliers, ETSI harmonized standards documentation, FCC emission limit rulings, and customs trade data for packaged filter imports. Bottom-up unit demand estimates triangulate against top-down wafer start allocations for specialty analog processes.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by filter architecture, process technology node, end-use vertical, and geographic regulatory cluster. CAGRs derive from fitted growth curves incorporating defense modernization program funding cycles, 5G NR infrastructure deployment schedules, and foundry capacity expansion timelines. Industry-specific forecast inputs include MIIT spectrum policy announcements in China and NMPA medical device regulation updates.
Inputs from defense contractor qualification databases and foundry utilization reports were available through the study window; gaps in real-time wafer pricing for specialty analog processes introduce uncertainty bands around cost projections. Forecasts reflect documented assumptions regarding CMOS node migration timelines and silicon-germanium BiCMOS yield maturation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Layer Pads Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Pcie Switches Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Silicon Epitaxial Wafer Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
N-Topcon Solar Cells Market