
 Global Layer Pads Market | 2026-2036
Global Layer Pads Market Size, Share, and Industry Trends Forecast 2026-2036
Global Layer Pads Market Outlook
Market Context
Electronics logistics is realigning layer pad procurement toward anti-static and vibration-damping specifications. Smurfit Kappa Group leverages its European corrugated network to supply custom layer pads for automotive tier-one suppliers. DS Smith Plc anchors its position through closed-loop recycling programs that reduce per-trip packaging costs for industrial end users. International Paper Company competes on FSC-certified fiber sourcing that meets sustainability mandates from multinational electronics brands.
Technical Definition and Segment Structure
Layer pads are flat separators, typically manufactured from corrugated fiberboard, foam, or composite substrates, designed to stabilize palletized goods by distributing load and preventing vertical compression damage during transit and storage. The product serves essential protective functions across supply chains where unitized loads require interlayer cushioning or surface protection against abrasion. Anti-slip layer pads command premium positioning due to specialized coating requirements that reduce load shift in high-vibration transport modes. Composite material formulations represent the fastest-growing segment as manufacturers substitute multi-ply structures for single-material pads to achieve weight reduction without sacrificing compressive strength. Soft layer pads retain mature volume share in food and beverage applications where conformability to irregular crate bases remains critical.
Regulatory Environment
REACH in Europe restricts certain chemical treatments used in anti-slip coatings, while EPA guidelines in the United States govern recycled fiber content claims in packaging materials. China's SAMR enforces GB standards for reusable packaging performance that directly affect layer pad thickness and compression test protocols. Stakeholders must monitor regulatory divergence between jurisdictions to avoid specification mismatches that disqualify products from cross-border supply contracts.
Market Dynamics
Semiconductor logistics is forcing layer pad specifications toward anti-static and vibration-damping performance thresholds that corrugated fiberboard alone cannot satisfy. Electronics OEMs now reject single-material pads for high-value wafer shipments, compressing margins for converters lacking composite substrate capabilities.
Growth Catalysts
- REACH chemical restrictions:European regulations on anti-slip coating formulations are accelerating substitution toward water-based alternatives that composite layer pads accommodate more readily than traditional corrugated.
- Automotive inbound logistics:German OEMs specify high-performance composite separators for just-in-time parts delivery, creating specification pull-through across tier-one supplier networks.
- Closed-loop rental systems:Industrial packaging pooling operators in the Netherlands and Belgium are expanding layer pad fleets to capture reusable packaging mandates from multinational food processors.
Market Restraints
- OCC price volatility:Old corrugated containerboard input costs swing with Chinese import quota adjustments, destabilizing converter margin structures for fiber-based pads.
- Polypropylene supply concentration:Foam layer pad manufacturers depend on Gulf Coast petrochemical complexes where hurricane disruptions compress availability windows.
- Compression test protocol divergence:China's SAMR GB standards and EU EN testing methods specify incompatible load-deflection curves, forcing dual-sku strategies that inflate inventory carrying costs.
Strategic Opportunities
- India pharmaceutical cold chain:Temperature-stable composite layer pads remain underpenetrated in vaccine distribution networks where pallet stability during refrigerated transport commands premium positioning.
- Japan METI circular economy incentives:Subsidies for reusable packaging adoption in electronics assembly are redirecting procurement toward rental-based layer pad programs.
- RFID-embedded trackability:Convergence of passive sensor tags with composite substrates enables location-aware pooling systems that reduce per-trip asset loss rates.
Industry Challenges
- Anti-static formulation expertise:Converter technical staffs lack proficiency in carbon-black loading ratios and surface resistivity testing required for semiconductor-grade pad certification.
- Multi-material recycling infrastructure:Composite pads combining fiberboard, foam, and polymer films face limited post-consumer processing capacity in most municipal waste systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Layer Pads Market |
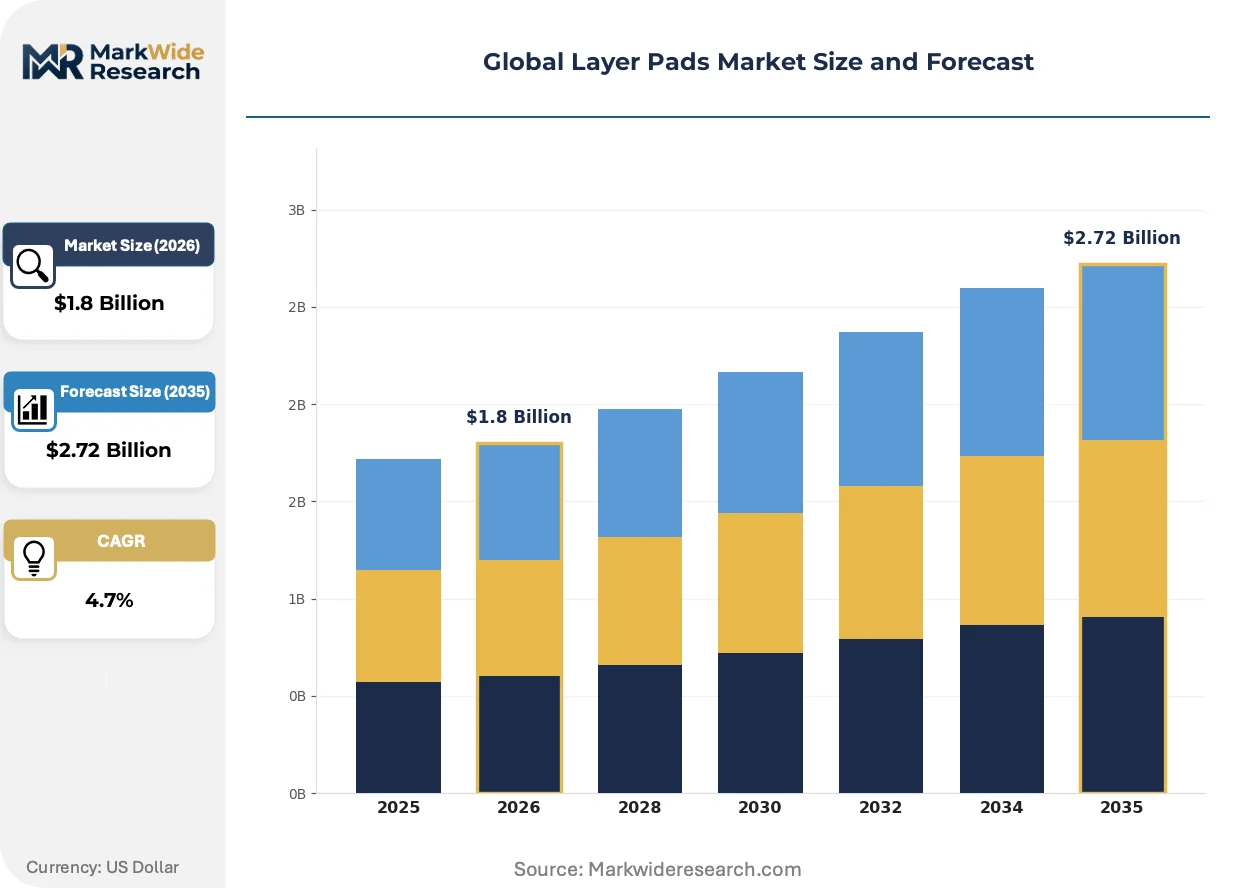
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Layer Pads, Hard Layer Pads, Anti-slip Layer Pads, Custom Layer Pads Material: Foam, Rubber, Silicone, Composite End User: Automotive, Aerospace, Electronics, Industrial Application: Packing, Cushioning, Vibration Damping, Surface Protection |
| Companies Covered | Smurfit Kappa Group, DS Smith Plc, International Paper Company, WestRock Company, KARTON SpA, Corex Plastics Pty Ltd., GWP Group Limited, Shish Industries Limited, ER&GE Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Layer Pads Market Strategic Shifts
Active coating technologies and embedded sensing capabilities are redefining layer pad functional specifications beyond passive load distribution. Electronics and automotive logistics buyers now evaluate separators as data-capture nodes and contamination-control barriers.
Bio-based barrier coatings are converging with nanocellulose reinforcement to create moisture-resistant fiberboard pads that match synthetic foam performance. Food exporters in Scandinavia are piloting these formulations for seafood containerization where condensation protection previously required plastic interlayers. The technology is converging with existing corrugated production lines, lowering retrofit capital barriers for mid-scale converters.
ECHA's expanding SVHC candidate list now captures several siloxane compounds common in anti-slip treatments, forcing reformulation cycles across European pad manufacturers. Industrial laundries operating pooling systems face compliance verification costs that favor larger operators with dedicated analytical laboratories. German automotive suppliers are responding by consolidating vendor bases toward converters with in-house coating development capabilities.
Specification consolidation among electronics contract manufacturers is compressing approved vendor lists from regional fragmentation toward global framework agreements. Foxconn and Pegatron procurement teams now mandate ISO 9001 and FSC chain-of-custody certification as baseline qualifiers, disqualifying smaller regional converters. This concentration is most visible in Vietnam and Mexico where new assembly capacity is activating without established local pad supply bases.
Global Layer Pads Market Segmentation
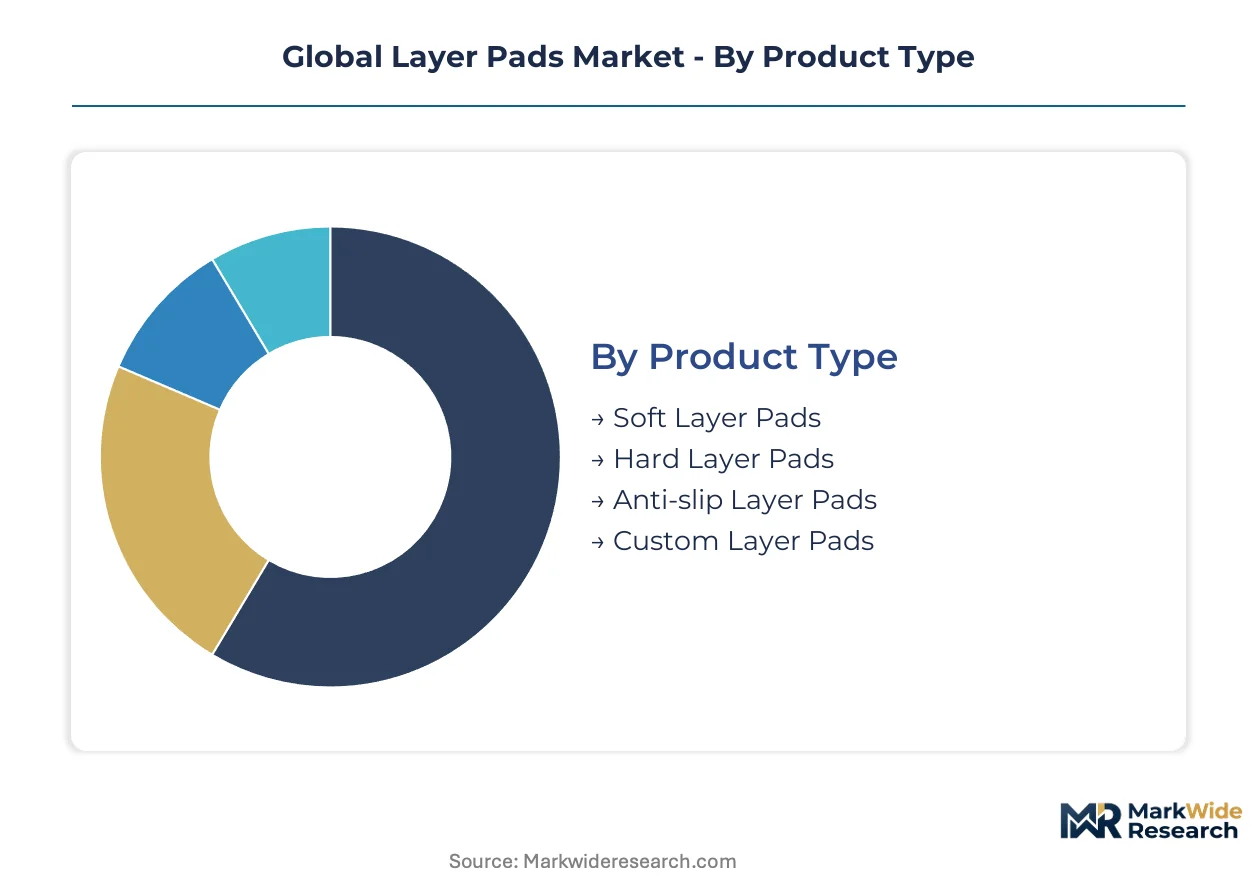
Layer pad procurement diverges sharply across end-use requirements, with semiconductor logistics demanding anti-static composite formulations while automotive inbound operations prioritize load stability under vibration. Material selection and product construction type determine converter margin structures and recycling compliance burdens.
Product Type:
Buyers differentiate primarily by load stability requirements and surface friction needs, with premium specifications commanding multi-material construction.
- Soft Layer Pads:Manufactured from conformable foam or low-density fiberboard substrates that adapt to irregular crate bases and uneven pallet surfaces. Food and beverage distributors in Germany specify these for inbound produce logistics where base irregularity is common, though compression set limits restrict reuse cycles.
- Anti-slip Layer Pads:Engineered with specialized coatings—siloxane-based or water-borne alternatives under REACH transition—that increase surface friction coefficients to prevent load shift during high-vibration transport. German automotive OEMs mandate these for just-in-time parts delivery, with coating chemistry compliance now filtering supplier qualification lists.
- Hard Layer Pads:Rigid corrugated or solid fiberboard constructions delivering maximum compressive strength for dense, uniform loads. Electronics contract manufacturers in Vietnam deploy these for standardized component totes where surface regularity permits.
- Custom Layer Pads:Engineered-to-order dimensions and material stacks for non-standard pallet footprints or specialized handling equipment. Aerospace suppliers in Toulouse and Hamburg specify these for irregular airframe component geometries.
Soft layer pads lead volumes today; anti-slip variants are gaining share fastest.
Material:
Raw material selection determines regulatory compliance pathways and end-of-life processing options, with multi-material laminates creating recycling complexity.
- Composite:Multi-ply structures combining fiberboard, foam layers, and polymer films to achieve weight reduction without sacrificing compressive strength. Semiconductor logistics buyers in Japan and South Korea specify these for wafer shipments where vibration damping and anti-static performance must coexist.
- Foam:Polypropylene or polyethylene extrusions delivering conformability and cushioning recovery across multiple use cycles. Pooling operators in the Netherlands favor foam for closed-loop rental systems where washability and durability justify higher acquisition costs.
- Rubber:Natural or synthetic elastomer sheets providing extreme grip and chemical resistance for industrial chemical transport. Limited adoption due to weight penalties and higher per-unit costs.
- Silicone:High-performance elastomer formulations for temperature-extreme applications, notably pharmaceutical cold chain in India where vaccine distribution requires stability across refrigerated transport ranges.
Foam dominates installed base; composite materials are expanding most quickly.
End User:
Sector-specific certification requirements and supply chain power structures shape procurement concentration and vendor consolidation patterns.
- Automotive:Tier-one suppliers specify REACH-compliant anti-slip and high-compression variants for inbound logistics to assembly plants. German OEM procurement frameworks are pulling specification standardization across European supplier networks.
- Electronics:Contract manufacturers mandate ISO 9001 and FSC chain-of-custody certification as baseline qualifiers, with anti-static and vibration-damping performance now non-negotiable for high-value component shipments.
- Industrial:General manufacturing applications spanning machinery parts, raw materials, and processed goods. Price-sensitive procurement with lower specification barriers permits regional converter competition.
- Aerospace:Low-volume, high-specification requirements for airframe and engine component protection. Custom dimensions and fire-retardant properties dominate procurement criteria.
Automotive anchors current demand; electronics is climbing the fastest.
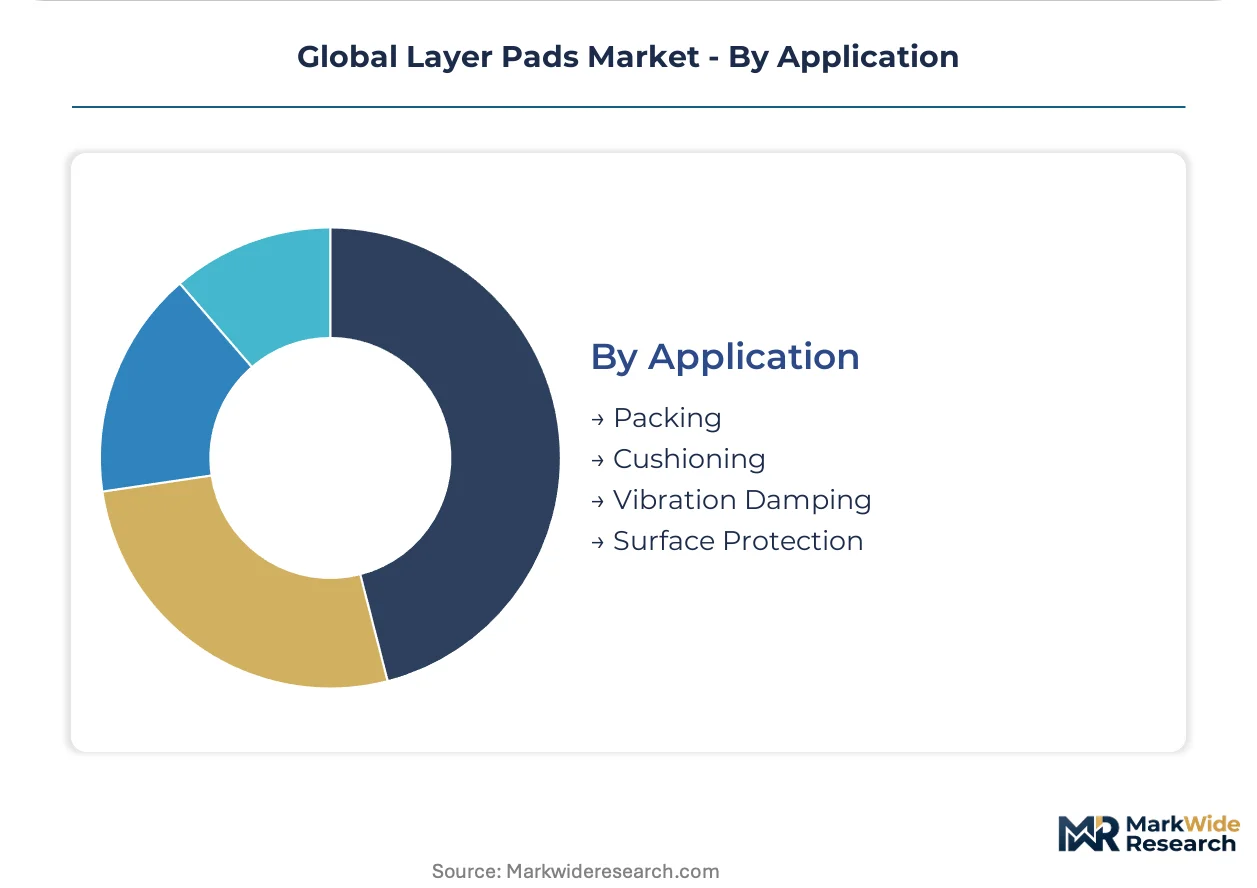
Application:
Functional performance requirements determine material stack complexity and coating specifications, with multi-function pads commanding premium positioning.
- Vibration Damping:Engineered to absorb mechanical energy from transport modes, protecting sensitive electronics and precision components. Composite substrates with tuned foam densities serve semiconductor and automotive electronics logistics.
- Surface Protection:Prevents abrasion and contamination between stacked layers, critical for finished goods with cosmetic requirements. Electronics OEMs in Mexico specify these for display panel shipments.
- Packing:General unitization and load stabilization across standard pallet configurations. Mature volume segment with commodity pricing pressure.
- Cushioning:Impact absorption for irregular or fragile goods, common in food and beverage distribution where product geometry varies.
Packing leads volumes today; vibration damping is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEM procurement frameworks are pulling specification standardization across European supplier networks, while semiconductor logistics in East Asia and pharmaceutical cold chains in South Asia reshape material requirements.
Germany
Automotive tier-one suppliers specify REACH-compliant anti-slip and high-compression variants for inbound logistics to assembly plants. KBA vehicle safety regulations intersect with packaging performance standards for just-in-time delivery systems. The Stuttgart-Munich corridor concentrates converter capacity serving BMW, Mercedes-Benz, and Volkswagen supplier networks.
United States
Electronics contract manufacturers mandate EPA-compliant recycled fiber content claims for packaging materials serving domestic semiconductor assembly. EPA guidelines govern environmental marketing claims that affect converter qualification. Austin and Phoenix metro areas host expanding wafer fabrication facilities driving anti-static pad specification.
China
SAMR enforces GB standards for reusable packaging performance that directly affect layer pad thickness and compression test protocols. MIIT industrial standards for electronics logistics create certification requirements for semiconductor-grade separators. The Yangtze River Delta clustering around Shanghai and Suzhou concentrates contract manufacturing demand.
Japan
METI circular economy incentives subsidize reusable packaging adoption in electronics assembly, redirecting procurement toward rental-based layer pad programs. JIS standards specify performance testing methods for industrial packaging materials. The Nagoya-Toyota industrial corridor anchors automotive electronics logistics demand.
India
Temperature-stable composite layer pads remain underpenetrated in vaccine distribution networks where pallet stability during refrigerated transport commands premium positioning. CDSCO pharmaceutical regulations create cold chain validation requirements affecting packaging selection. Maharashtra and Gujarat host expanding pharmaceutical manufacturing clusters driving specification development.
Global Layer Pads Market Competitive Environment
Capacity expansion dominates the current landscape as converters retrofit lines for composite substrate production. The vendor base organizes around three tiers: integrated paperboard multinationals with captive fiber supply, regional specialists in anti-slip coating technologies, and pooling operators managing closed-loop rental fleets. Strategic archetypes include sustainability-certified suppliers capturing electronics OEM procurement and composite technology specialists serving semiconductor logistics. M&A activity and geographic expansion into Vietnam and Mexico represent the dominant competitive moves.
Among European-integrated packaging groups, Smurfit Kappa Group and DS Smith Plc exemplify the sustainability-certified archetype, while International Paper Company occupies a position representing North American fiber-based supply. These three entities anchor the tier of converters with FSC chain-of-custody certification that meets multinational electronics brand procurement mandates.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| DS Smith Plc |
| International Paper Company |
| WestRock Company |
| KARTON SpA |
| Corex Plastics Pty Ltd. |
| GWP Group Limited |
| Shish Industries Limited |
| ER&GE Limited |
| Others |
Value Chain & Pricing Dynamics
FSC chain-of-custody certification gates both qualified supply and premium-tier pricing access for converters serving multinational electronics brands, compressing margins for uncertified competitors while rewarding integrated paperboard groups with direct fiber sourcing.
Pricing Analysis
Distributor margins of 12-18 percent separate direct-to-OEM contract pricing from spot-market transactions, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and volume scale. Anti-static composite pads command premium positioning due to carbon-black loading expertise and surface resistivity testing capabilities that few converters possess. Cost compression in fiber-based tiers is intensifying because OCC price volatility transfers directly to converter margin structures. Regional automotive suppliers exhibit highest price sensitivity due to just-in-time inventory pressures, while semiconductor logistics buyers prioritize performance compliance over unit cost.
Supply Chain Analysis
China's evolving GB standards for reusable packaging performance are reshaping sourcing decisions for converters supplying Yangtze River Delta contract manufacturers, forcing dual-sku strategies that inflate working capital requirements. Raw material supply draws from German automotive corridor converter capacity, US Gulf Coast petrochemical complexes for polypropylene foam feedstock, and Scandinavian pulp mills for FSC-certified fiber. Single-source vulnerability concentrates in anti-slip coating formulations where REACH-compliant water-based alternatives face limited qualified suppliers. Distribution runs through tier-one automotive supplier networks and closed-loop pooling operators in the Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through composite substrate substitution that displaces single-material pads in semiconductor logistics, capturing value from technical specification premiums.
For Market Incumbents: Anchor market position through backward integration into captive fiber supply and anti-slip coating formulation capabilities, defending against specialty composite entrants from East Asia. Invest in RFID-embedded trackability R&D to capture pooling operator procurement consolidation. Prioritize certification maintenance for FSC chain-of-custody and ISO 9001 as baseline qualifiers for electronics OEM frameworks. For New Entrants and Emerging Players: Enter via India's pharmaceutical cold chain segment where temperature-stable composite layer pads remain underpenetrated in vaccine distribution networks. Target Maharashtra and Gujarat manufacturing clusters with CDSCO-compliant validation support. Pursue technical partnership routes with established coating developers rather than greenfield formulation investment. For Investors and Strategic Acquirers: Roll-up economics work for regional anti-slip coating specialists because specification consolidation among electronics contract manufacturers is compressing approved vendor lists toward converters with in-house technical capabilities. Five-to-ten year viability rests on composite substrate expertise displacing commodity fiberboard. Monitor Japan METI circular economy subsidy disbursement rates as inflection signal for rental-based program adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Substrate Capacity Expansion | Captures semiconductor logistics demand for anti-static and vibration-damping performance specifications. |
| REACH-Compliant Coating Development | Secures European automotive OEM qualification as ECHA SVHC restrictions tighten. |
| Closed-Loop Pooling Fleet Investment | Aligns with Netherlands and Belgium reusable packaging mandates from multinational food processors. |
| RFID-Enabled Trackability Integration | Reduces per-trip asset loss rates for industrial packaging operators. |
| India Pharmaceutical Cold Chain Entry | Addresses underpenetrated vaccine distribution networks requiring refrigerated transport stability. |
Study Parameters
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each market gathered through converter plant managers, automotive tier-one procurement leads, electronics contract manufacturer supply chain directors, and pooling system operators. Secondary validation drew from SAMR GB standard filings, ECHA SVHC candidate list updates, METI circular economy program disclosures, and customs trade data for corrugated fiberboard and polymer foam inputs. Bottom-up demand modeling triangulated against top-down supply capacity estimates.
Granularity-level modeling operated at product type, material substrate, end-user sector, and application function dimensions across the analysis window. CAGRs were derived from segment-level volume trajectories weighted by regional demand concentration. Forecast inputs incorporated semiconductor fabrication capacity expansion timelines, automotive OEM just-in-time logistics restructuring, and pharmaceutical cold chain infrastructure investment patterns.
Inputs from regulatory filing databases and primary stakeholder interviews were available through the study window; gaps in real-time OCC price volatility data and proprietary converter margin structures introduce uncertainty bands around fiber-based segment projections. Forecasts reflect assumptions regarding REACH transition timelines and GB standard enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Semiconductor Diode Market
Semiconductor Devices
Transistor Arrays Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
ATX Motherboards Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Japan MLCC Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
Printed Circuit Board (PCB) Laminate Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
AIN DBC Ceramic Substrate Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
Gan on Diamond Technology Market