
 Metal-Semiconductor-Metal Photodetector Market | 2026-2036
Metal-Semiconductor-Metal Photodetector Market Size, Share, and Industry Trends Forecast 2026-2036
Metal-Semiconductor-Metal Photodetector Market Foresight
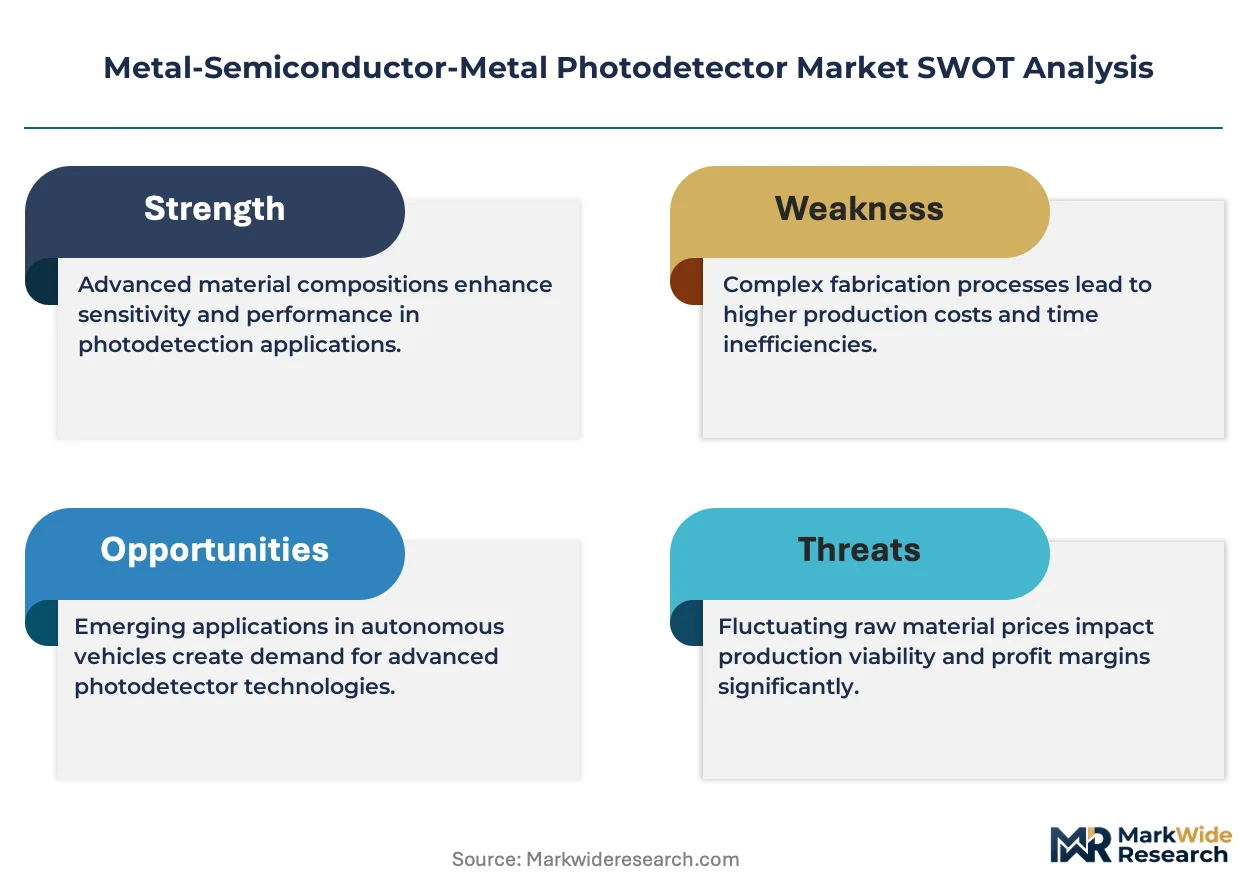
Asset-light foundry partnerships is narrowing the capital barrier for photodetector specialists seeking commercial scale. Hamamatsu Photonics leverages its captive crystal growth and epitaxy capabilities to sustain margin control across ultraviolet and infrared variants. Broadcom competes through vertical integration into optical transceiver modules that embed MSM devices directly. VIGO Photonics S.A. anchors its position in mercury-cadmium-telluride alternatives for defense spectroscopy applications.
A metal-semiconductor-metal photodetector employs interdigitated metal electrodes deposited onto a semiconductor surface to generate photocurrent through internal photoemission or band-to-band absorption, with finger spacing typically ranging from sub-micron to several microns depending on target wavelength and speed requirements. These devices serve primarily in high-speed optical communication receivers, thermal imaging focal planes, and precision spectroscopy where picosecond response times matter. Infrared product types lead value contribution due to defense and industrial automation budgets, while ultraviolet variants show the fastest expansion driven by sterilization and flame detection applications. Quantum technology segments capture premium pricing through single-photon sensitivity, whereas thermal technology occupies mature volume pools in non-critical sensing.
FDA device classification rules influence healthcare imaging system approvals incorporating MSM arrays for diagnostic spectroscopy. EPA hazardous substance limits affect semiconductor fab chemistry choices in domestic manufacturing. FCC spectral allocation decisions shape lidar and optical communication application roadmaps by determining permitted transmitter bands. Stakeholders must monitor how export control revisions on compound semiconductor substrates redirect supply chain geography regardless of end-market demand strength.
Market Dynamics
Optical communication infrastructure buildouts are compressing device qualification cycles while REACH and RoHS substance restrictions force material substitutions in electrode metallization and compound semiconductor substrates.
Growth Catalysts
- Telecom fiber densification:5G backhaul and data center interconnects require picosecond-response photodetectors for 400G/800G transceivers, pulling MSM device volumes into optical receiver modules.
- REACH substance restrictions:European chemical compliance mandates eliminate lead-bearing solders and cadmium-containing buffer layers, accelerating adoption of gold-free electrode architectures and indium-phosphide substrate alternatives.
- Defense spectroscopy budgets:Mercury-cadmium-telluride focal plane arrays for infrared threat detection drive demand for cryogenic-compatible MSM readout circuits in Germany, France, and the United States.
Market Restraints
- III-V substrate concentration:Gallium arsenide and indium phosphide wafer supply concentrates among Japanese and Chinese crystal growers, exposing device fabricators to export control disruptions and price volatility.
- Gold electrode cost exposure:Interdigitated finger metallization relies on high-purity gold for ohmic contact stability, tying production economics to precious metal commodity swings.
- Silicon photonics substitution:Integrated germanium-on-silicon photodetectors in CMOS foundries threaten discrete MSM devices in cost-sensitive datacom applications below 100 Gbps.
Strategic Opportunities
- Quantum sensing instrumentation:Single-photon-sensitive MSM variants capture premium positioning in quantum key distribution systems and lidar-based autonomous navigation under development in the United Kingdom and Canada.
- UV sterilization equipment:Mercury-free ultraviolet-C sources for hospital and water treatment systems create demand for solar-blind aluminum-gallium-nitride photodetectors with nanosecond gating capability.
- India PLI scheme:Production-linked incentives for semiconductor packaging and testing attract MSM module assembly investments serving domestic telecom and space research demand.
Industry Challenges
- Compound semiconductor process talent:MOCVD epitaxy and electron-beam lithography for sub-micron finger patterning require specialized technicians concentrated in legacy optoelectronics clusters around Munich and Tokyo.
- Dual-use export licensing:Infrared-sensitive devices with military spectroscopy applications face International Traffic in Arms Regulations and Wassenaar Arrangement classification delays, extending customer qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal-Semiconductor-Metal Photodetector Market |
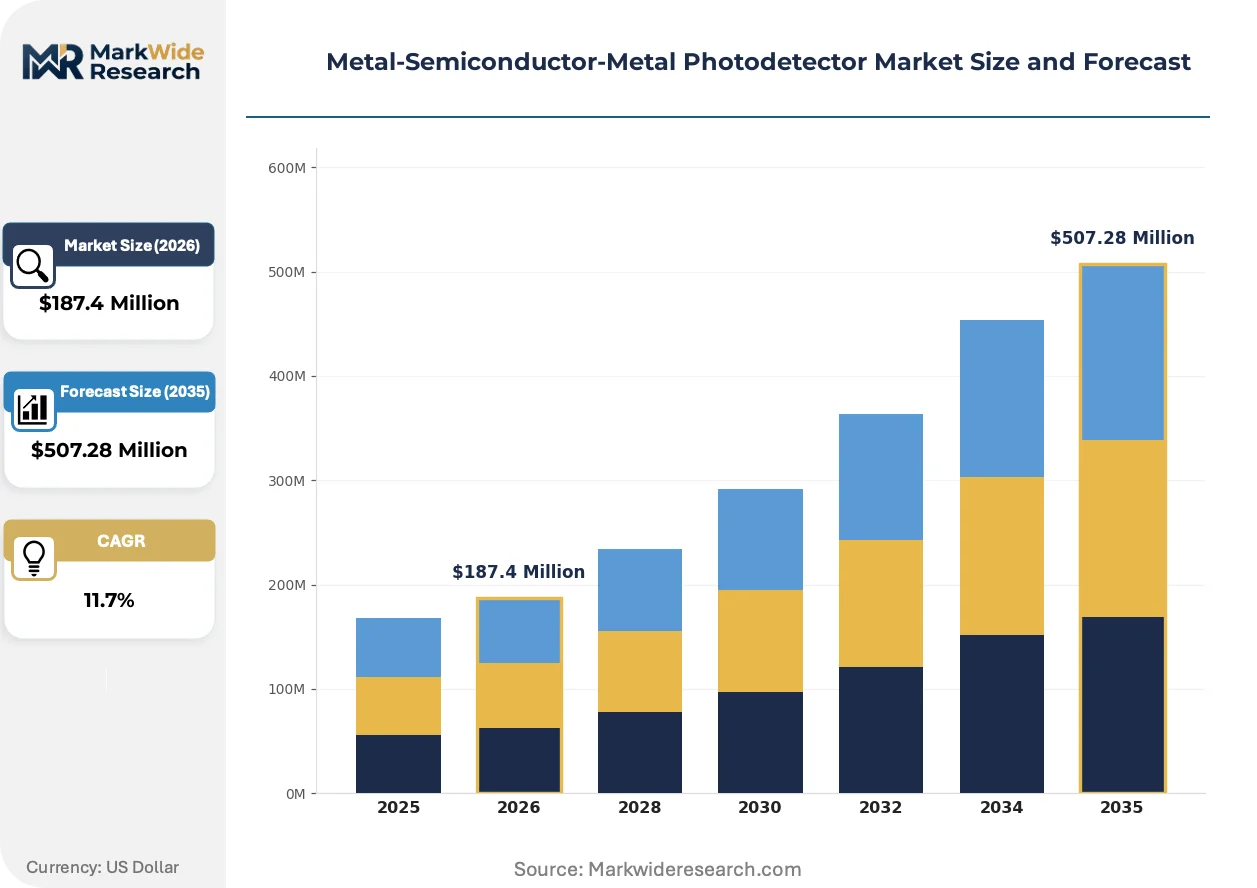
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
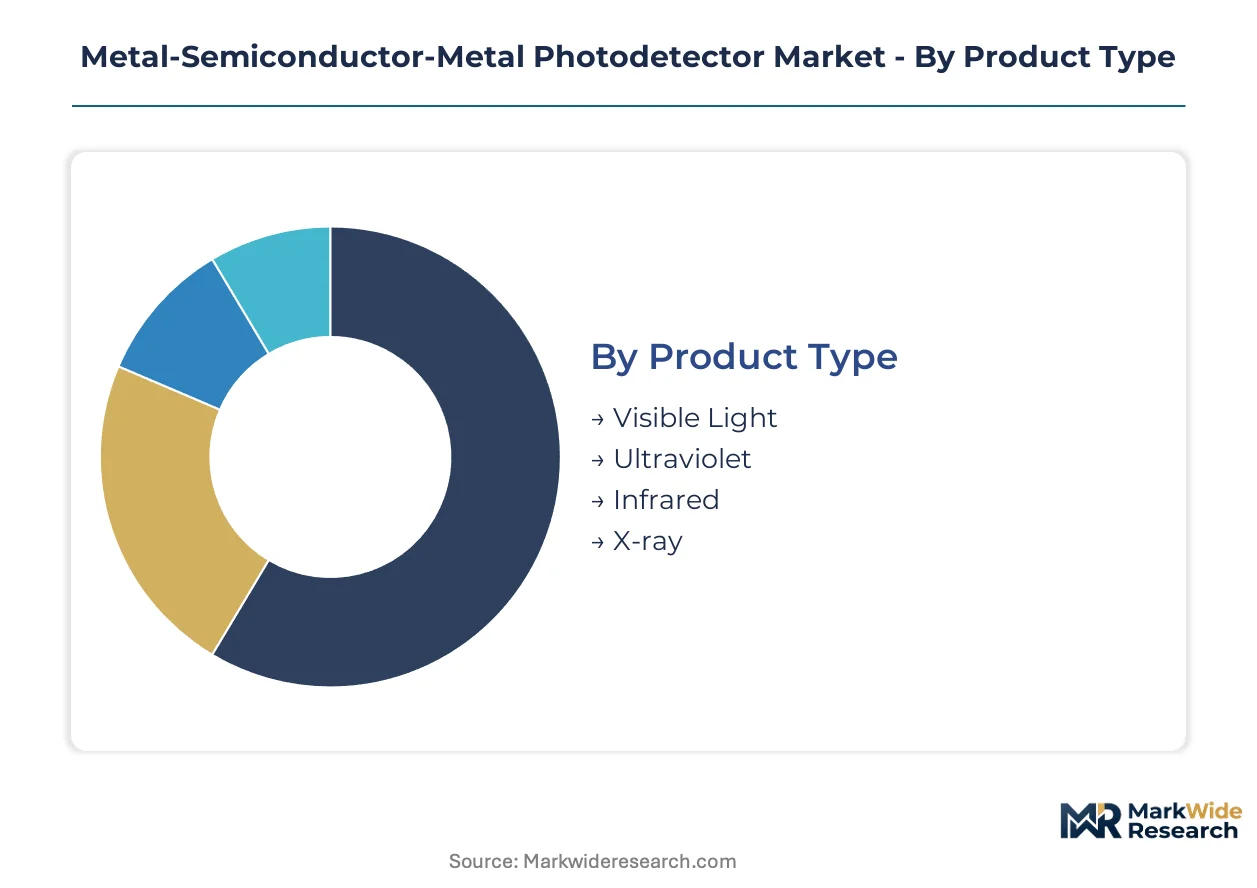
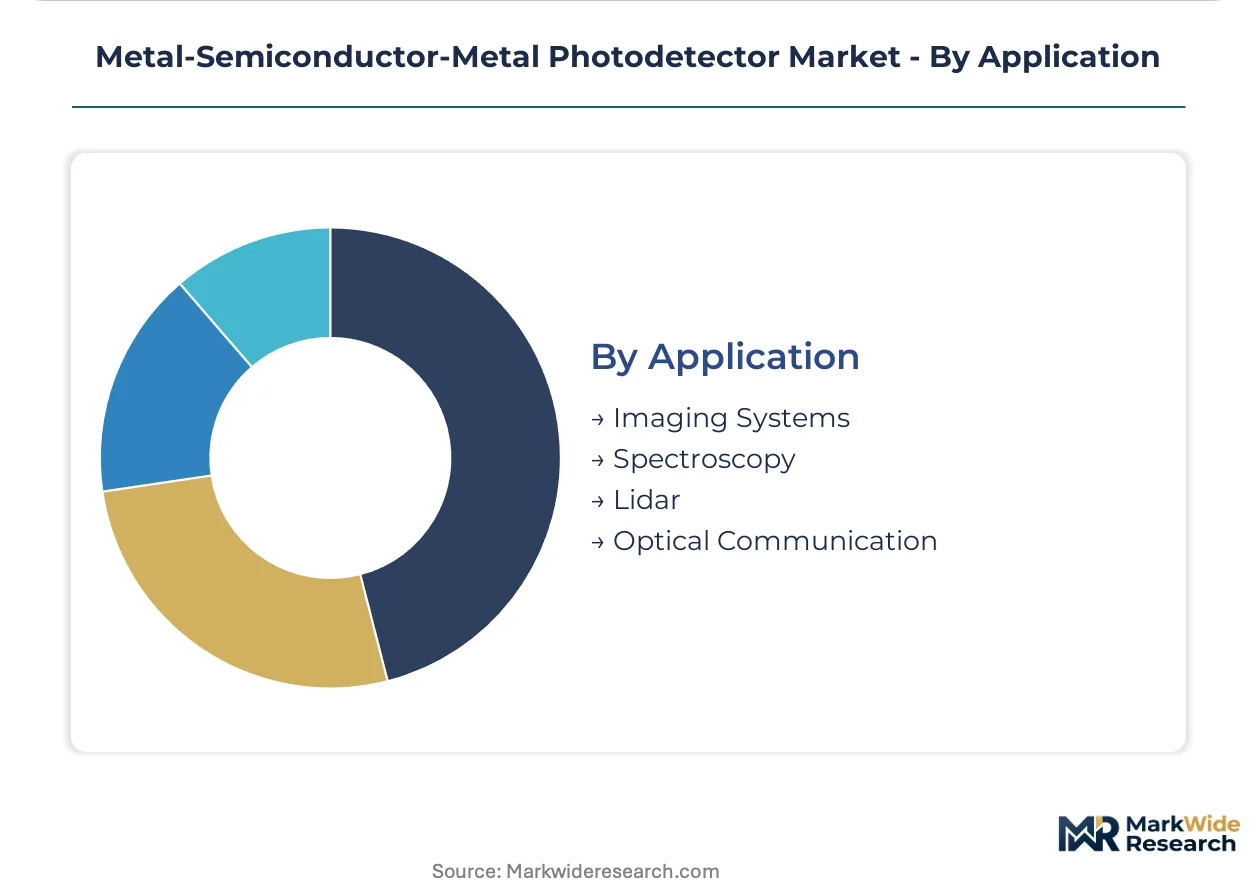
| Segmentation | Product Type: Visible Light, Ultraviolet, Infrared, X-ray Technology: Thermal, Quantum, Avalanche, Barrier End User: Telecommunications, Defense, Industrial Automation, Healthcare Application: Imaging Systems, Spectroscopy, Lidar, Optical Communication |
| Companies Covered | Hamamatsu Photonics, ON Semiconductor, Broadcom, STMicroelectronics, ams-OSRAM AG, Excelitas Technologies Corp, First Sensor, VIGO Photonics S.A., NTT Innovative Devices Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal-Semiconductor-Metal Photodetector Market Shifts & Advancements
Device architectures are converging with heterogeneous integration platforms while regulatory chemical restrictions reshape fabrication chemistries and procurement patterns favor qualified second-source suppliers.
Plasmonic nanostructure integration is digitizing MSM photodetector performance by concentrating optical fields into sub-wavelength volumes. Defense lidar developers in the United States and Israel are adopting gold nanopatterned electrodes for enhanced responsivity at 1550 nm. This nanophotonic approach is digitizing the speed-sensitivity tradeoff that previously forced binary device selection.
EU F-Gas Regulation phase-down schedules are eliminating sulfur hexafluoride etching chemistries used in gallium arsenide mesa isolation. German foundries near Jena are transitioning to inductively coupled plasma etching with alternative fluorinated precursors. Infrared focal plane manufacturers face process revalidation costs that disadvantage smaller compound semiconductor houses against integrated silicon photonics competitors.
After-sales technical support unbundling is fragmenting traditional component distributor relationships. Optical transceiver OEMs in California's Bay Area and China's Yangtze River Delta now procure bare MSM die through specialized compound semiconductor brokers while retaining in-house packaging and testing. This channel restructuring concentrates volume with foundries offering certified design kits and application engineering, compressing margins for undifferentiated merchant suppliers.
Metal-Semiconductor-Metal Photodetector Market Segmentation
MSM photodetector purchasing patterns diverge sharply across wavelength regimes and integration complexity, with after-sales calibration support becoming a decisive vendor selection criterion in defense and healthcare deployments. Device specification sheets rarely capture the full cost of ownership, driving procurement teams toward suppliers with field application engineering presence.
Product Type:
After-sales service intensity peaks in cryogenic infrared arrays and deep-ultraviolet sterilization systems, where electrode degradation and hermetic seal failures demand rapid technical response.
- Infrared:Mercury-cadmium-telluride and indium-gallium-arsenide compositions dominate thermal imaging focal planes. Defense spectroscopy budgets in Germany and the United States concentrate demand for cryogenic-compatible devices with sub-nanosecond response, though gold electrode costs expose fabricators to precious metal volatility.
- Ultraviolet:Aluminum-gallium-nitride heterostructures enable solar-blind detection below 280 nm for flame sensing and water sterilization. Hospital systems in France and Japan are retrofitting mercury-free UV-C disinfection chambers, pulling nanosecond-gated MSM devices into volume production.
- Visible Light:Silicon-based interdigitated electrodes serve precision colorimetry and machine vision inspection lines.
- X-ray:Direct-conversion cadmium-zinc-telluride crystals support dental and industrial CT scanners with high stopping power.
Infrared holds the largest share; momentum sits with ultraviolet as sterilization regulations tighten across healthcare infrastructure.
Technology:
Cost tier separation runs deepest between mature thermal devices and quantum-enabled single-photon variants, with price multiples exceeding 50x at equivalent active areas.
- Quantum:Superconducting nanowire and avalanche quenching architectures achieve single-photon sensitivity for quantum key distribution. Research consortia in the United Kingdom and Canada are integrating these devices into autonomous navigation lidar, though dilution refrigeration requirements limit field deployment.
- Thermal:Bolometric and pyroelectric mechanisms serve uncooled motion detection and industrial temperature monitoring. Warehouse automation projects in Bavaria and Michigan specify these devices for conveyor belt hot-spot detection, prioritizing reliability over speed.
- Avalanche:Internal gain multiplication enables low-light imaging without external amplification.
- Barrier:Unipolar nBn and pBp heterostructures suppress dark current in high-temperature operation.
Thermal technology commands volume leadership; quantum variants are climbing the fastest on defense and quantum communication investment.
End User:
Application-driven procurement patterns concentrate volume in telecommunications, where transceiver OEMs specify MSM die for 400G/800G receiver modules.
- Telecommunications:Data center interconnect and 5G backhaul infrastructure in California's Bay Area and China's Yangtze River Delta pull picosecond-response devices into optical receiver assemblies. Foundry partnerships with compound semiconductor houses are narrowing the capital barrier for merchant suppliers.
- Defense:Infrared threat detection and hyperspectral reconnaissance systems drive demand for cryogenic focal plane readout circuits. Export licensing under ITAR and Wassenaar Arrangement protocols extends qualification timelines for non-domestic suppliers.
- Industrial Automation:Process control spectroscopy and precision gauging specify visible and near-infrared variants.
- Healthcare:Diagnostic spectroscopy arrays face FDA device classification scrutiny for clinical deployment.
Telecommunications generates the highest unit volumes; defense captures premium pricing through performance specifications.
Application:
Customer type fragmentation separates integrated module buyers from bare-die procurement, with optical transceiver OEMs increasingly unbundling packaging and testing.
- Optical Communication:Receiver front-ends for coherent and direct-detection transceivers require sub-picosecond jitter performance. Foundries near Jena and Tokyo are qualifying gold-free electrode architectures to satisfy REACH substance restrictions.
- Spectroscopy:Laboratory and field-portable instruments demand broadband responsivity from ultraviolet through mid-infrared. German precision optics clusters anchor European supply for research-grade devices.
- Imaging Systems:Thermal cameras and medical radiography arrays specify large-format focal planes.
- Lidar:Automotive and aerial mapping systems drive 1550 nm eye-safe transmitter development.
Optical communication dominates current procurement; spectroscopy applications are expanding most quickly on environmental monitoring and pharmaceutical quality control budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in compound semiconductor substrates are redrawing procurement geography for MSM photodetector fabricators. Foundries in Japan and China control gallium arsenide and indium phosphide wafer supply, while European device houses concentrate on precision electrode patterning and hermetic packaging.
United States
Defense spectroscopy budgets and datacenter interconnect demand pull cryogenic-compatible MSM devices into infrared focal planes and 400G transceivers. FDA device classification rules govern diagnostic spectroscopy arrays for clinical deployment. California's Bay Area anchors optical transceiver OEM procurement, with foundry partnerships narrowing capital barriers for merchant suppliers.
Germany
Precision optics clusters in Jena and Munich concentrate mercury-cadmium-telluride readout circuit fabrication for thermal imaging. EU F-Gas Regulation phase-downs are eliminating sulfur hexafluoride etching chemistries, forcing process revalidation at compound semiconductor houses near Jena. REACH substance restrictions accelerate gold-free electrode architecture adoption across Bavarian foundries.
Japan
METI industrial technology roadmaps prioritize picosecond-response photodetectors for 5G backhaul and quantum communication. Domestic crystal growers supply high-purity gallium arsenide substrates, reducing import dependency for device fabricators. Tokyo and Nagoya house concentrated MOCVD epitaxy and electron-beam lithography talent pools for sub-micron finger patterning.
China
Yangtze River Delta optical transceiver OEMs unbundle packaging and testing from bare-die procurement, restructuring traditional distributor relationships. MIIT spectral allocation decisions shape lidar and optical communication roadmaps by determining permitted transmitter bands. Dual carbon goals are pressuring semiconductor fab chemistry choices toward lower-emission processing.
India
Domestic telecom infrastructure and space research demand attract MSM module assembly investments under PLI scheme incentives for semiconductor packaging and testing. CDSCO medical device regulations influence diagnostic spectroscopy system approvals incorporating MSM arrays. Karnataka and Telangana are emerging as compound semiconductor testing hubs serving regional optical communication markets.
Metal-Semiconductor-Metal Photodetector Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: captive crystal growth specialists, vertically integrated transceiver module houses, and fabless design firms relying on foundry partnerships. Strategic archetypes include precision optics heritage players with in-house epitaxy, semiconductor conglomerates with broad optoelectronics portfolios, and defense-focused specialists in infrared materials. Competitive moves concentrate on backward integration into substrate supply and geographic expansion through qualified second-source arrangements.
Within the precision optics tier, Hamamatsu Photonics and VIGO Photonics S.A. exemplify divergent specialization paths—Hamamatsu representing Japanese vertical integration from crystal growth through device packaging, VIGO Photonics occupying Polish expertise in mercury-cadmium-telluride alternatives. Broadcom sits within the semiconductor conglomerate archetype, leveraging scale advantages in optical transceiver module integration.
| Leading Market Players |
|---|
| Hamamatsu Photonics |
| ON Semiconductor |
| Broadcom |
| STMicroelectronics |
| ams-OSRAM AG |
| Excelitas Technologies Corp |
| First Sensor |
| VIGO Photonics S.A. |
| NTT Innovative Devices Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in III-V substrate crystal growth across Japanese and Chinese suppliers is tightening feedstock allocation for device fabricators, compressing margins on gallium arsenide and indium phosphide wafers while amplifying pricing power at the substrate tier. This utilization squeeze cascades downstream, forcing photodetector manufacturers to absorb cost pass-throughs or renegotiate long-term offtake terms with optical transceiver OEMs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with cryogenic infrared arrays commanding substantial premiums over uncooled visible-light variants. Price differentiation hinges on certification grade for defense ITAR compliance and volume scale in datacenter interconnect procurement. Cost compression in standard-tier devices is intensifying because silicon photonics substitution threatens discrete MSM volumes below 100 Gbps. Telecommunications transceiver manufacturers exhibit highest price sensitivity, while defense spectroscopy integrators prioritize performance specifications over unit economics.
Supply Chain Analysis
High-purity gallium arsenide and indium phosphide wafer supply concentrates in Japan, China, and select European crystal growth houses, with MOCVD epitaxy services clustering around Munich and Tokyo. Raw material dependencies include gold bullion for interdigitated electrode metallization, mercury-cadmium-telluride crystals for infrared focal planes, and aluminum-gallium-nitride heterostructures for ultraviolet variants. Single-source vulnerability in Japanese substrate supply exposes fabricators to export control disruptions. Distribution runs through specialized compound semiconductor brokers serving bare-die procurement by optical transceiver OEMs in California and the Yangtze River Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across wavelength regimes and integration complexity creates niche formation opportunities, with unbundling of packaging and testing services fragmenting traditional distributor relationships and opening entry points for specialized foundry partners.
For Market Incumbents: Harden supply chain resilience through backward integration into indium phosphide substrate supply or qualified second-source arrangements with European crystal growers. Defend margin position by accelerating gold-free electrode architecture certification to satisfy REACH substance restrictions before regulatory deadlines tighten. Prioritize captive MOCVD epitaxy capacity in Munich and Tokyo clusters to retain sub-micron finger patterning talent. For New Entrants and Emerging Players: India's underpenetrated compound semiconductor testing infrastructure offers white-space opportunity under PLI scheme incentives for packaging and testing investments. Target ultraviolet sterilization equipment manufacturers in France and Japan retrofitting mercury-free UV-C disinfection chambers. Pursue foundry partnership models with certified design kit offerings to bypass capital-intensive crystal growth barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision optics heritage players with in-house epitaxy and field application engineering presence. Long-term viability centers on defensible positioning in quantum sensing instrumentation and defense spectroscopy where single-photon sensitivity commands premium pricing. Monitor export control revisions on compound semiconductor substrates as inflection indicator for supply chain geography redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Supply | Crystal growth captive supply insulates margin control against Japanese and Chinese wafer price volatility. |
| Gold-Free Electrode Architecture Certification | REACH compliance investment opens European defense and healthcare procurement channels closed to lead-bearing competitors. |
| Foundry Partnership with Design Kit Offering | Certified application engineering support concentrates volume with fabless specialists seeking commercial scale. |
| Quantum Sensing Instrumentation Development | Single-photon sensitivity captures premium positioning in United Kingdom and Canada quantum key distribution systems. |
| Geographic Expansion through Second-Source Arrangements | Qualified European substrate alternatives reduce ITAR and Wassenaar Arrangement licensing exposure for defense exports. |
Research Methodology
The analysis maps infrared, ultraviolet, visible-light, and X-ray photodetector sub-sectors, each validated through compound semiconductor foundry executives, optical transceiver OEM procurement leads, defense spectroscopy system integrators, and precision optics cluster managers in Jena and Munich. Primary interview insights triangulate against customs trade data for III-V substrate imports, SEC filings from vertically integrated device manufacturers, ECHA REACH substance restriction databases, and ITAR export licensing records. Bottom-up unit economics from wafer processing through module assembly reconcile with top-down market sizing across telecommunications, defense, and healthcare end-use segments.
Assumptions held fixed include sustained defense spectroscopy budget allocation in Germany and the United States, continued REACH and RoHS chemical compliance enforcement across European fabrication, and stable gallium arsenide substrate pricing over the projection horizon. Variables modeled encompass silicon photonics substitution rates in datacom below 100 Gbps, quantum communication infrastructure deployment timelines, and India PLI scheme incentive continuity. CAGRs derive from segment-level volume trajectories weighted by price tier mix across quantum, thermal, avalanche, and barrier technology architectures. Forecast inputs include MOCVD reactor capacity expansion announcements and FCC spectral allocation decisions shaping lidar transmitter band availability.
Macroeconomic conditions sit as an overlay; deviation in defense procurement cycles, precious metal commodity swings, or compound semiconductor export control stringency would shift the trajectory. Cross-checking against optical transceiver OEM capex disclosures and foundry utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Global Probe Card Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Programmable Logic Device (PLD) Market
Semiconductor Devices
Superconductor Wire Market